

Autonomy-Ready eVTOL Cabin HMI Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomy-Ready eVTOL Cabin HMI Systems Market Insights
A shortage of certified systems integrators is redrawing competitive boundaries across the autonomy-ready eVTOL cabin HMI landscape. Honeywell leverages its avionics heritage to anchor positions in pilot-assistance architectures, while Thales competes through specialized haptic-feedback engineering for reduced-crew operations. Garmin sustains channel control over touchscreen display supply chains serving urban air mobility operators in North America and Europe.
Autonomy-ready eVTOL cabin HMI systems encompass multimodal human-machine interfaces engineered for pilotless or reduced-crew vertical flight operations, integrating touchscreens, gesture sensors, and voice-recognition modules with sub-100-millisecond latency requirements for safety-critical commands. These systems serve the primary commercial purpose of maintaining passenger situational awareness and enabling remote operator override during autonomous flight segments. Touchscreen displays currently dominate installed value across early eVTOL programs, while augmented reality interfaces represent the fastest-growing technology segment as manufacturers seek to reduce physical control density in compact cabins. AI-based voice assistants command premium margin pools where natural-language processing supports multi-passenger command arbitration in shared urban air mobility configurations.
FAA Part 23 reform and EASA SC-VTOL special conditions are tightening software-assurance requirements for HMI systems, compelling suppliers to demonstrate fail-operational behavior under single-fault conditions. ISO 26262 functional-safety adaptation for aviation and EU AI Act risk-classification rules for autonomous decision-support interfaces will further shape product-development roadmaps and market-access timelines. Stakeholders must monitor which certification body first publishes definitive HMI human-factors guidance for fully autonomous passenger operations, as this will trigger rapid realignment of engineering investment and partnership strategies across the supplier base.
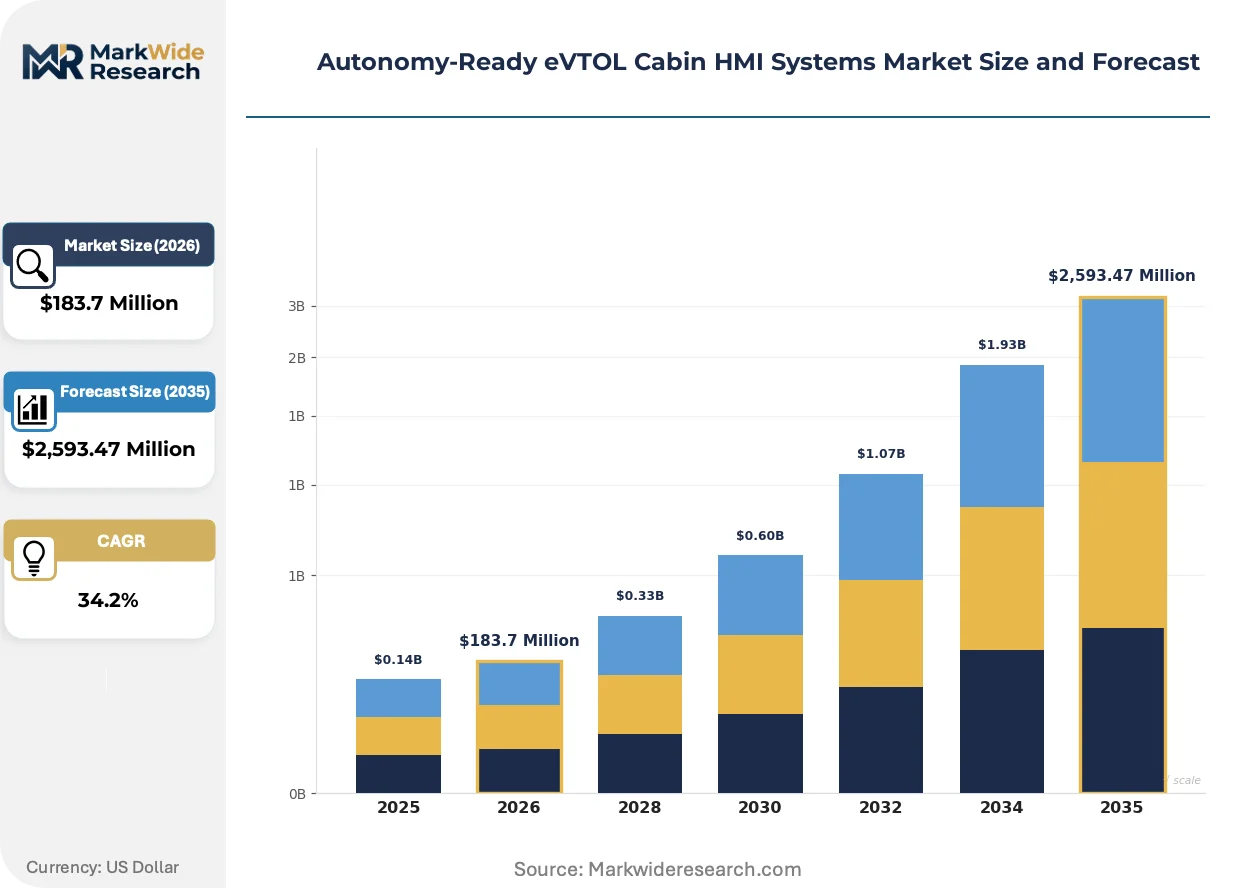
Market Dynamics
Certification timelines for autonomous flight software are compressing engineering cycles across the supplier base, forcing HMI developers to front-load human-factors validation before airframe partners freeze cabin architectures.
Growth Catalysts
- FAA Part 23 Reform:Modernized certification standards for small aircraft are streamlining type-approval pathways for touchscreen-based flight controls, reducing validation cycles for new entrants.
- Gesture Recognition:Non-contact cabin interfaces are gaining traction among German and Japanese urban air mobility operators seeking to minimize physical surface contamination in high-turnover passenger configurations.
- Urban Air Mobility Corridors:California's advanced air mobility infrastructure investments are creating concentrated demand for augmented reality pilot displays capable of operating under degraded visual conditions.
Market Restraints
- Silicon Supply Concentration:Advanced gesture-processing chipsets depend on fabrication capacity concentrated in East Asian foundries, exposing HMI suppliers to geopolitical disruption risks.
- EASA SC-VTOL Compliance Costs:Special conditions for vertical take-off and landing aircraft impose extensive software-assurance documentation requirements that inflate development budgets for multimodal interface systems.
- Latency Engineering Constraints:Sub-100-millisecond command-response specifications for safety-critical functions demand specialized real-time operating systems with limited vendor alternatives.
Strategic Opportunities
- UAE Regulatory Sandbox:Dubai's autonomous aviation test corridors offer accelerated deployment pathways for voice-assistant interfaces before equivalent FAA frameworks mature.
- AI-Voice Convergence:Natural-language processing integration with haptic feedback systems opens premium positioning for shared-ride configurations requiring multi-passenger command arbitration.
- Remote Operator Centers:Ground-based supervision infrastructure creates aftermarket demand for mirrored cabin displays enabling seamless human takeover during autonomous flight anomalies.
Industry Challenges
- Human-Factors Engineering Talent:Aviation-certified interface designers with autonomous systems experience command scarcity premiums that strain development team scaling.
- ISO 26262 Adaptation:Automotive functional-safety standards require substantial reinterpretation for aviation software assurance, creating interpretation friction with certification authorities.
- Legacy Avionics Integration:Backward compatibility demands from established airframe programs constrain architectural freedom for next-generation multimodal HMI architectures.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomy-Ready eVTOL Cabin HMI Systems Market Trends and Innovations
Interface modality preferences are diverging sharply between piloted transition aircraft and fully autonomous configurations, fragmenting R&D investment across competing human-factors philosophies. This divergence is accelerating specialization among subsystem suppliers.
Optical waveguide-based augmented reality displays are supplanting conventional LCD panels in compact eVTOL cabins. Joby Aviation and Archer Aviation have committed to holographic pilot guidance systems for their production airframes. This shift is compressing supply chains for traditional avionics display manufacturers while opening specialist opportunities in photonics integration.
EASA's SC-VTOL special conditions are mandating fail-operational behavior for all safety-critical HMI functions under single-fault scenarios. The regulation forces suppliers to implement redundant sensor fusion architectures for gesture and voice inputs. European urban air mobility programs are responding by pre-certifying dual-modal backup systems before primary interfaces enter service.
Air taxi operators are unbundling hardware procurement from software maintenance, favoring subscription-based interface updates over perpetual licensing. This reconfiguration concentrates purchasing authority with fleet management platforms rather than individual aircraft lessors. The model is most advanced in California's advanced air mobility corridor, where Volocopter and Lilium have structured multi-year service agreements covering continuous HMI refinement.
Autonomy-Ready eVTOL Cabin HMI Systems Market Segmentation
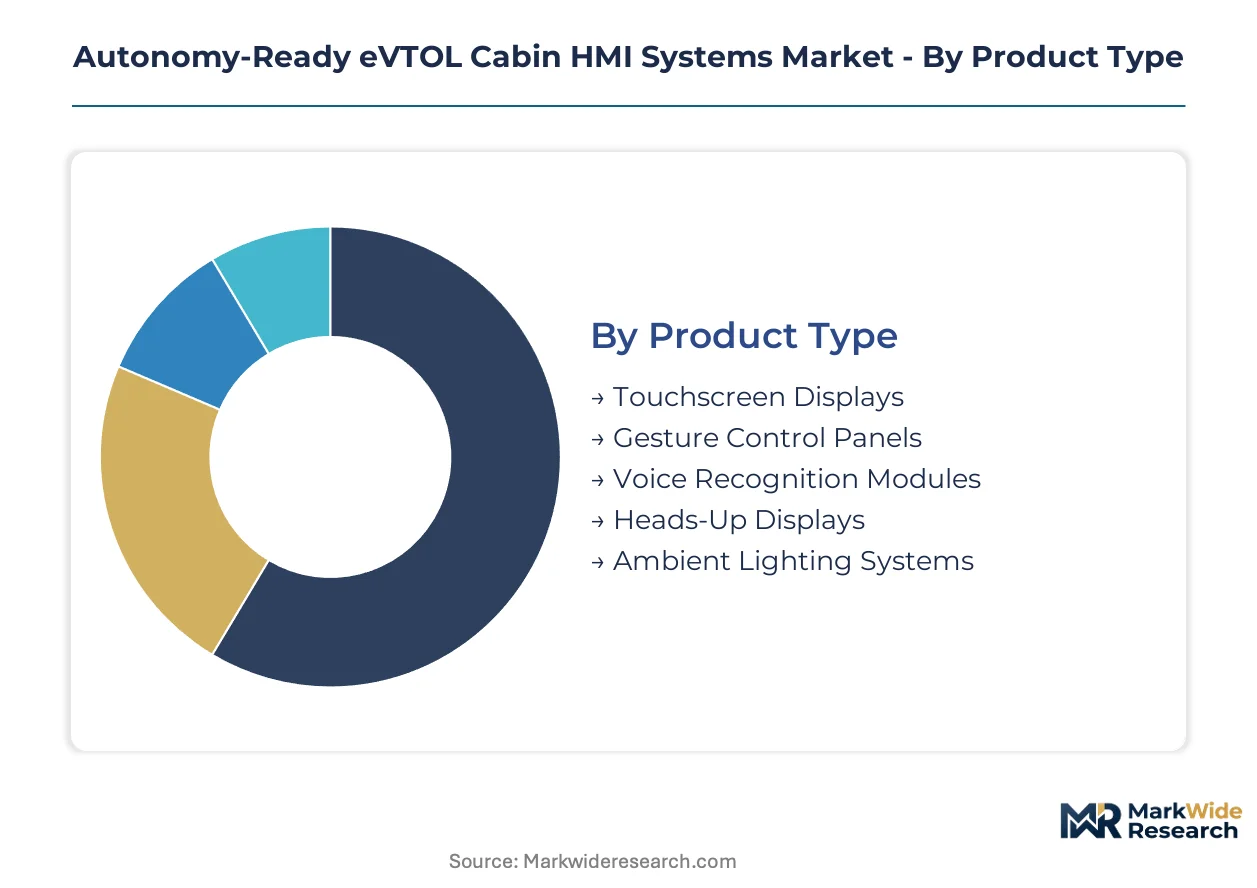
eVTOL cabin HMI segmentation fragments across four dimensions: product hardware, enabling technology, functional application, and buyer archetype. Each dimension carries distinct margin profiles and certification burdens that reshape supplier positioning.
Product Type:
Margin pools concentrate in interfaces commanding FAA and EASA software-assurance premiums.
- Touchscreen Displays:LCD and OLED panels with aviation-grade bonding and anti-reflective coatings dominate early production programs. Demand clusters with California's advanced air mobility corridor operators seeking Part 23-compliant flight control surfaces.
- Gesture Control Panels:Optical and radar-based non-contact interfaces eliminate physical contamination risks in high-turnover urban configurations. German and Japanese operators are expanding procurement as cabin hygiene protocols tighten.
- Voice Recognition Modules:Far-field microphone arrays with noise cancellation for rotorcraft acoustic environments.
- Heads-Up Displays:Combiner glass and waveguide projection systems for degraded-visibility operations.
- Ambient Lighting Systems:Programmable LED matrices supporting passenger anxiety reduction during autonomous segments.
Touchscreen displays hold installed capacity. Gesture control panels are rotating up the share rankings.
Technology:
Cost tiering separates safety-critical sensor fusion from discretionary passenger-facing features.
- Advanced Sensor Fusion:Multi-modal input arbitration combining touch, voice, and gesture with deterministic latency guarantees. EASA SC-VTOL fail-operational mandates are driving dual-redundant architectures into European programs.
- AI-Based Voice Assistants:Natural-language processing engines supporting multi-passenger command arbitration in shared-ride configurations. Premium positioning concentrates where fleet management platforms bundle subscription software updates.
- Haptic Feedback:Tactile confirmation systems for reduced-crew operations requiring eyes-out posture.
- Augmented Reality Interfaces:Optical see-through overlays projecting flight path and hazard symbology.
- Eye-Tracking Systems:Gaze monitoring for pilot attention verification and passenger experience personalization.
Sensor fusion commands the highest certification premiums. Voice assistants are climbing the fastest as operators unbundle hardware from software subscriptions.
Application:
Volume concentrates in safety-mandated functions versus discretionary cabin amenities.
- Passenger Interaction:Multimodal interfaces enabling ride-hailing, destination input, and emergency communication without crew intervention. Urban air mobility operators in the United Arab Emirates are deploying these in Dubai's autonomous aviation test corridors ahead of FAA framework maturity.
- Pilot Assistance:Augmented reality guidance and synthetic vision for transition-phase flight. California infrastructure investments are creating concentrated demand for degraded-visual-condition capability.
- In-Flight Entertainment:Passenger-facing content delivery with minimal certification burden.
- Security Monitoring:Cabin camera and sensor feeds for remote operator centers.
- Environmental Controls:Climate and lighting adjustment interfaces with low safety-criticality classification.
Pilot assistance holds installed capacity. Passenger interaction is rotating up the share rankings.
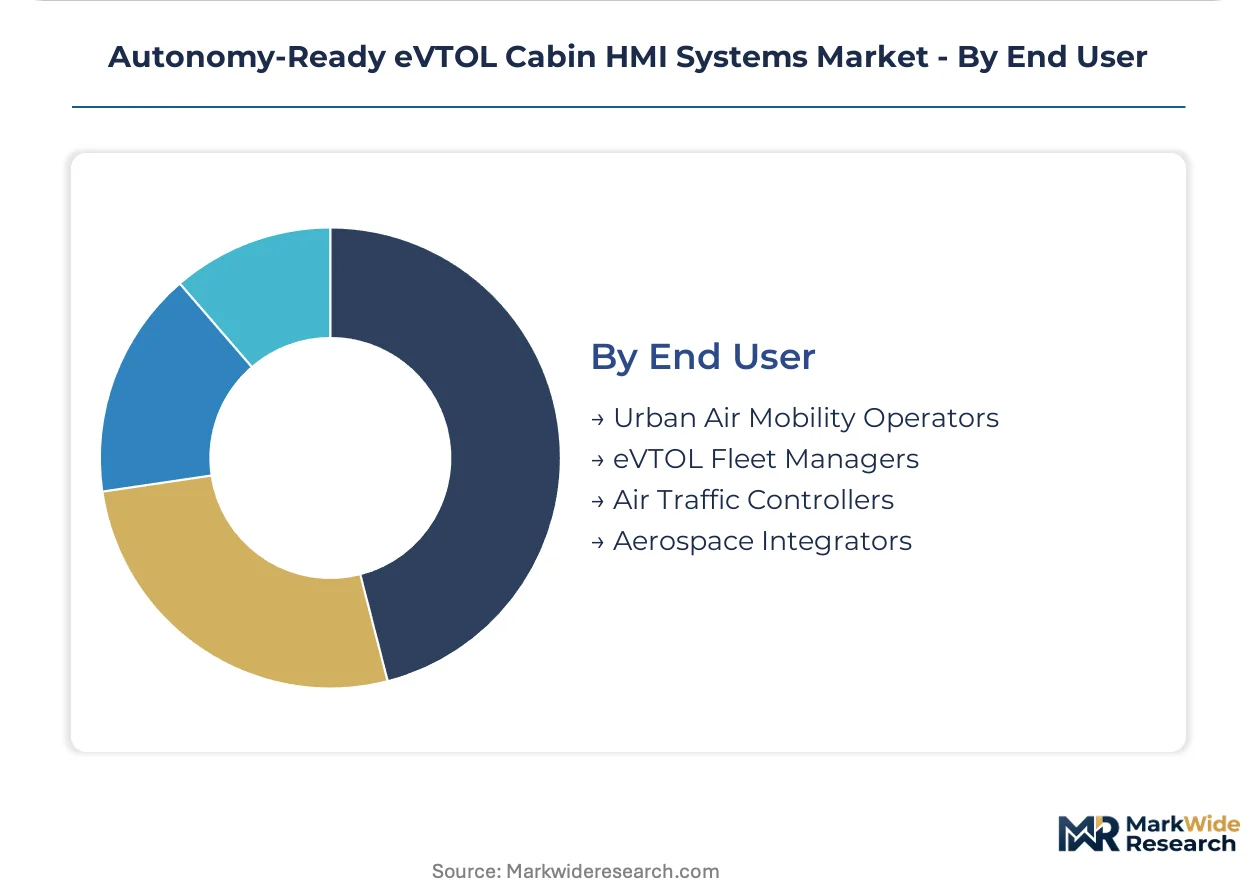
End User:
Procurement authority is shifting from aircraft lessors to fleet management platforms.
- Urban Air Mobility Operators:Direct purchasers specifying HMI configurations for passenger-facing service models. Volocopter and Lilium have structured multi-year service agreements covering continuous interface refinement in California's corridor.
- eVTOL Fleet Managers:Aggregators controlling purchasing decisions for multiple operating certificates. These buyers favor subscription-based software maintenance over perpetual licensing.
- Air Traffic Controllers:Ground-based supervision infrastructure requiring mirrored cabin displays for remote takeover.
- Aerospace Integrators:Tier-1 suppliers bundling HMI subsystems into complete avionics packages.
Urban air mobility operators hold installed capacity. Fleet managers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German operators prioritize gesture-controlled hygiene interfaces, while California's corridor concentrates demand for augmented reality pilot assistance. Japanese programs emphasize fail-operational redundancy, and UAE regulators accelerate deployment ahead of Western certification timelines.
United States
California's advanced air mobility corridor drives concentrated procurement of AR pilot displays for degraded-visual-condition operations. FAA Part 23 reform streamlines touchscreen flight control certification, reducing validation cycles for new entrants. Los Angeles and San Francisco Bay Area clusters host Volocopter and Lilium service agreements covering continuous HMI refinement.
Germany
Urban air mobility operators in Munich and Stuttgart expand gesture-controlled cabin interface procurement as cabin hygiene protocols tighten. EASA SC-VTOL special conditions mandate fail-operational behavior under single-fault scenarios, forcing redundant sensor fusion architectures. Baden-Württemberg's aerospace engineering base anchors haptic-feedback engineering for reduced-crew operations.
Japan
Tokyo and Osaka metropolitan operators prioritize non-contact interfaces to minimize physical surface contamination in high-turnover passenger configurations. METI aviation technology programs support multimodal HMI development with deterministic latency guarantees. Kansai region manufacturing clusters integrate optical waveguide AR displays into compact eVTOL cabin designs.
United Arab Emirates
Dubai's autonomous aviation test corridors offer accelerated deployment pathways for voice-assistant interfaces before equivalent FAA frameworks mature. MOHAP and civil aviation authority sandbox programs enable pre-certification operational data collection. Abu Dhabi investment vehicles fund fleet management platforms bundling subscription-based HMI software maintenance.
United Kingdom
London's urban air mobility planning integrates remote operator center infrastructure requiring mirrored cabin displays for seamless human takeover. CAA engagement with EASA SC-VTOL alignment creates transitional certification pathways for gesture and voice input systems. Thames Valley aerospace clusters concentrate on pilot-assistance augmented reality for transition-phase flight operations.
Autonomy-Ready eVTOL Cabin HMI Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-tier competitive structure. Tier-1 suppliers bundle complete avionics packages with captive HMI subsystems, while specialists concentrate on single-modality excellence in gesture, voice, or haptic domains. Three archetypes dominate: legacy avionics integrators leveraging certification heritage, automotive electronics crossovers adapting ISO 26262 standards, and photonics specialists capturing AR display transitions. Competitive moves concentrate on strategic partnerships with airframe programs and technology licensing for fail-operational sensor fusion.
Within the legacy avionics tier, Honeywell and Thales exemplify contrasting strategic positions. Honeywell occupies a position anchored in pilot-assistance architectures, while Thales represents specialized haptic-feedback engineering for reduced-crew operations. Garmin sits within the channel-control archetype, sustaining touchscreen display supply chain positions across North American and European urban air mobility operators.
| Leading Market Players |
|---|
| Honeywell |
| Garmin |
| Thales |
| Astronics |
| Diehl Aviation |
| Collins Aerospace |
| Safran |
| FACC AG |
| Recaro Aircraft Seating |
| Others |
Pricing and Supply Chain Analysis
Forty-five-week lead times for aviation-grade OLED display bonding equipment concentrate pricing power with East Asian foundries capable of multi-layer ceramic substrate fabrication, while EASA SC-VTOL documentation requirements inflate software-assurance premiums that compress margins for European integrators.
Pricing Analysis
Long-term service agreements dominate procurement as fleet management platforms unbundle hardware from subscription-based software maintenance. Price differentiation separates fail-operational sensor fusion architectures from discretionary passenger-facing features, with certification-grade latency guarantees commanding substantial premiums. Pricing pressure stems from silicon supply concentration in Taiwanese and South Korean fabrication facilities. Urban air mobility operators exhibit highest price sensitivity, while aerospace integrators prioritize performance guarantees over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for advanced gesture-processing chipsets, while German precision optics manufacturers supply holographic waveguide components for augmented reality displays. Raw material dependencies center on indium tin oxide coatings, gallium arsenide photonic substrates, and aviation-grade aluminum bonding adhesives. Single-source vulnerability in East Asian foundry capacity exposes HMI suppliers to geopolitical disruption. Distribution runs through Tier-1 avionics integrators bundling complete cabin systems for airframe programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified human-factors engineering talent with autonomous aviation experience commands scarcity premiums that constrain development team scaling across the supplier base.
For Market Incumbents: Fortify certification heritage advantages by accelerating FAA Part 23 and EASA SC-VTOL pre-qualification investments before airframe partners freeze cabin architectures. Deepen channel control over touchscreen display supply chains serving California's advanced air mobility corridor operators. Counter automotive electronics crossovers by emphasizing aviation-specific software-assurance documentation capabilities that ISO 26262 adaptation alone cannot satisfy. For New Entrants and Emerging Players: Dubai's autonomous aviation test corridors offer accelerated deployment pathways for voice-assistant interfaces before equivalent FAA frameworks mature. Target gesture control panel procurement expansion among German and Japanese operators prioritizing cabin hygiene protocols. Pursue white-label haptic-feedback engineering partnerships with established avionics integrators seeking reduced-crew operational capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy avionics divisions with dormant photonics integration capabilities applicable to holographic waveguide displays. Long-term viability hinges on positioning ahead of definitive HMI human-factors guidance publication by major certification bodies. Monitor which regulator first issues fully autonomous passenger operation standards as the inflection trigger for rapid engineering investment realignment.| Strategic Initiative | Industry Significance |
|---|---|
| Fail-Operational Sensor Fusion Certification | EASA SC-VTOL mandates dual-redundant architectures for gesture and voice inputs in European programs. |
| Photonics Integration Partnership | Optical waveguide specialists capture AR display transitions as Joby and Archer commit to holographic systems. |
| Subscription Software Unbundling | Volocopter and Lilium structure multi-year service agreements covering continuous HMI refinement in California. |
| UAE Regulatory Sandbox Deployment | Dubai's test corridors enable pre-certification operational data collection for voice-assistant interfaces. |
| Remote Operator Center Infrastructure | Ground-based supervision creates aftermarket demand for mirrored cabin displays enabling seamless human takeover. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with avionics systems integrators, certification specialists at FAA and EASA, urban air mobility fleet managers, and human-factors engineering directors; and secondary validation against airframe program announcements, regulatory docket filings, and semiconductor trade flow databases. Bottom-up triangulation across component-level procurement patterns and top-down reconciliation against fleet deployment projections anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning interface modality, functional safety classification, buyer archetype procurement authority, and regional regulatory maturity. CAGRs were derived from weighted scenario analysis incorporating airframe production ramp schedules and certification pathway probability assessments. Deterministic latency specifications and fail-operational redundancy requirements shaped technology adoption curve assumptions.
Underlying assumptions cover EASA SC-VTOL special condition finalization timelines and FAA Part 23 reform implementation pace, with deviation risk concentrated in certification body human-factors guidance publication sequencing. Forecasts reflect these assumptions pending material shifts in autonomous aviation regulatory frameworks. Recalibration cycles align with definitive HMI standards issuance and airframe partner cabin architecture freeze dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.