
 Aircraft Interior Lighting Market | 2026-2036
Aircraft Interior Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Interior Lighting Market Insights
The split between premium programmable cabin environments and commodity overhead illumination is repositioning procurement strategies across the aviation supply chain. Collins Aerospace leverages its integrated avionics heritage to bundle lighting with flight-deck and cabin management systems. Diehl Aviation anchors European narrow-body programs through deep OEM relationships on Airbus platforms. Safran competes by extending its electrical systems portfolio into smart cabin architectures that merge lighting with passenger connectivity.
Aircraft interior lighting comprises engineered luminaires, control modules, and distribution systems designed to provide regulated illumination across passenger compartments, crew workstations, and service areas, typically operating within 28V DC aircraft electrical architectures and meeting stringent flammability standards under FAR 25.853. LED lights now dominate retrofit programs due to weight reduction and lifecycle cost advantages over legacy fluorescent and halogen technologies. Smart integration systems command premium positioning as airlines seek programmable color-temperature control for circadian rhythm management on long-haul routes. Fiber optic lights retain niche applications where electromagnetic interference immunity matters, though their share remains constrained by higher installation complexity.
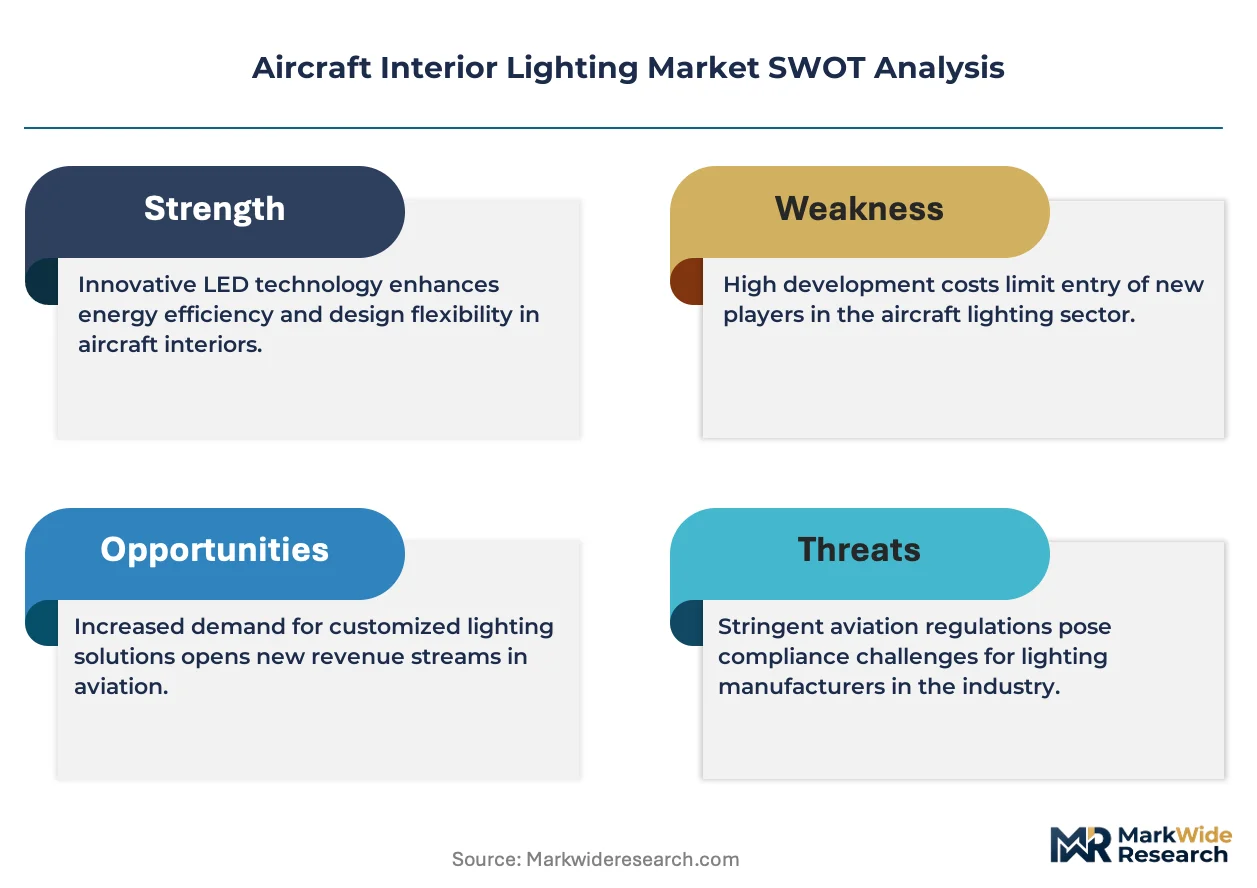
FAA certification requirements under Part 25 govern airworthiness standards for U.S.-registered aircraft lighting systems, while EASA CS-25 provides parallel regulatory architecture for European operators, with both agencies intensifying focus on energy efficiency metrics and hazardous material restrictions. The EU Green Deal and emerging CSRD disclosure obligations are pressuring European carriers to document lifecycle environmental impacts of cabin upgrades, indirectly shaping supplier selection criteria. Stakeholders must monitor divergence between FAA and EASA test protocols for next-generation OLED panel certification, as harmonization gaps could fragment product development roadmaps and delay cross-fleet deployments.
Market Dynamics
Retrofit cycles for narrow-body fleets are compressing as airlines compete on passenger experience differentiation, forcing lighting suppliers to accelerate certification timelines while managing legacy platform compatibility. This tension between innovation velocity and airworthiness rigor defines current competitive positioning.
Growth Catalysts
- FAA Part 25 energy efficiency amendments:Tightening illumination power-density standards are mandating LED conversions across aging fleets, creating replacement pull-through for control module and distribution system suppliers.
- Circadian rhythm programming:Long-haul carriers are specifying tunable white-light systems for crew rest compartments and premium cabins, expanding addressable content per aircraft.
- Chinese narrow-body production ramps:COMAC C919 manufacturing milestones are opening specification windows for domestic and joint-venture lighting suppliers previously locked out of Boeing-Airbus supply chains.
Market Restraints
- OLED panel fragility:Flexure tolerance limitations in thin-film organic emitters restrict deployment to static ceiling panels, excluding high-vibration sidewall and reading-light applications.
- Aluminum heat-sink cost volatility:LED thermal management hardware faces input price swings that compress margin on fixed-price retrofit contracts.
- EASA-FAA harmonization gaps:Divergent flammability test protocols for photoluminescent exit path markings force dual-certification investments that deter mid-tier suppliers from cross-Atlantic programs.
Strategic Opportunities
- India MRO network expansion:IndiGo and Air India's fleet growth is concentrating third-party maintenance capacity in Delhi-Mumbai corridors, creating localized specification influence points for lighting vendors.
- EU CSRD lifecycle disclosure mandates:European carriers must document cabin upgrade environmental footprints, advantaging suppliers with verified carbon accounting for LED retrofit programs.
- Power-over-Ethernet convergence:Cabin management networks are adopting IEEE 802.3bt standards, enabling single-cable lighting-control integration that reduces harness weight and installation labor.
Industry Challenges
- EMC certification specialist scarcity:Aircraft electromagnetic compatibility testing for wireless-enabled smart luminaires faces bottlenecked laboratory capacity, extending program timelines.
- Legacy 28V DC integration complexity:New solid-state lighting architectures must interface with aging distribution buses designed for incandescent loads, requiring custom power-conditioning hardware per platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Interior Lighting Market |
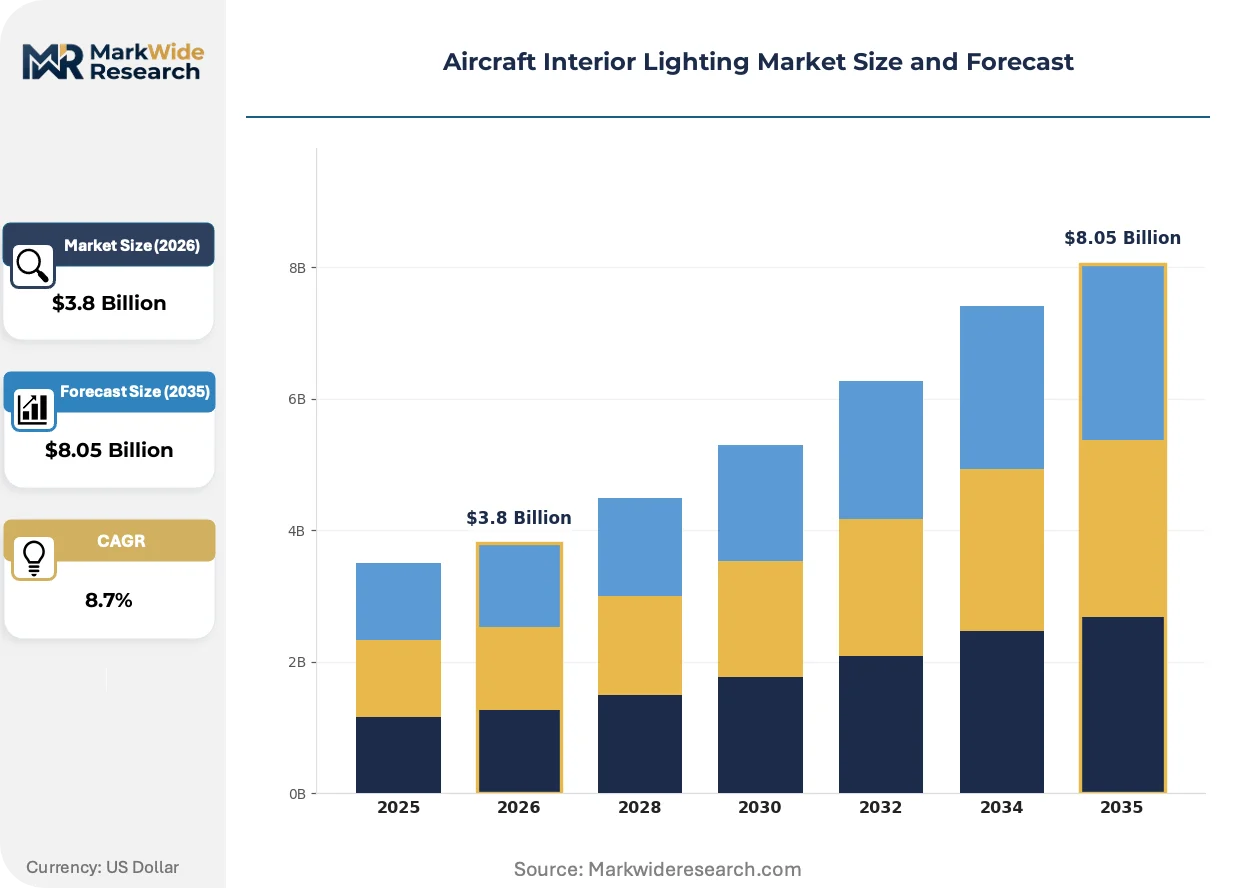
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lights, Halogen Lights, OLED Panels, Fluorescent Lights, Fiber Optic Lights Technology: Intensity Control, Color Changing, Energy Efficient, Smart Integration, Wireless Connectivity Application: Passenger Cabins, Cockpit Displays, Cargo Hold, Lavatories, Galley Areas End User: Commercial Airlines, Business Jet Operators, Military Aviation, Charter Services, Maintenance Providers |
| Companies Covered | Collins Aerospace, Diehl Aviation, Astronics Corporation, Safran, SCHOTT, Luminator Technology Group, STG Aerospace, Honeywell International, Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Interior Lighting Market Trends and Innovations
Active cabin environment programming is displacing static illumination as the baseline specification, with airlines treating lighting as a configurable service layer rather than fixed infrastructure. This reclassification is redrawing supplier relationships and value capture models.
Human-centric lighting is converging with biometric passenger monitoring systems, enabling real-time circadian adjustment based on actual sleep-wake detection rather than pre-programmed schedules. Full-service carriers on trans-Pacific routes are piloting these integrated suites. The technology is converging with predictive maintenance analytics, compressing the traditional separation between passenger experience hardware and aircraft health monitoring.
EASA's intensified focus on hazardous substance restrictions under REACH Annex XVII is phasing out legacy phosphor coatings in fluorescent tube replacements. Manufacturers serving European-registered fleets must reformulate emitter chemistries or surrender retrofit market access. Narrow-body operators with mixed FAA-EASA registrations face specification fragmentation that favors dual-certified product families.
Airline technical procurement teams are consolidating vendor relationships around integrated cabin system providers rather than standalone lighting specialists. This concentration is displacing component-level sourcing for new-build programs. Aftermarket channels retain fragmentation, though lessors are increasingly mandating approved supplier lists that mirror OEM preferences. The shift is most visible in Southeast Asia, where lessor-influenced fleet decisions dominate narrow-body configurations.
Aircraft Interior Lighting Market Segmentation
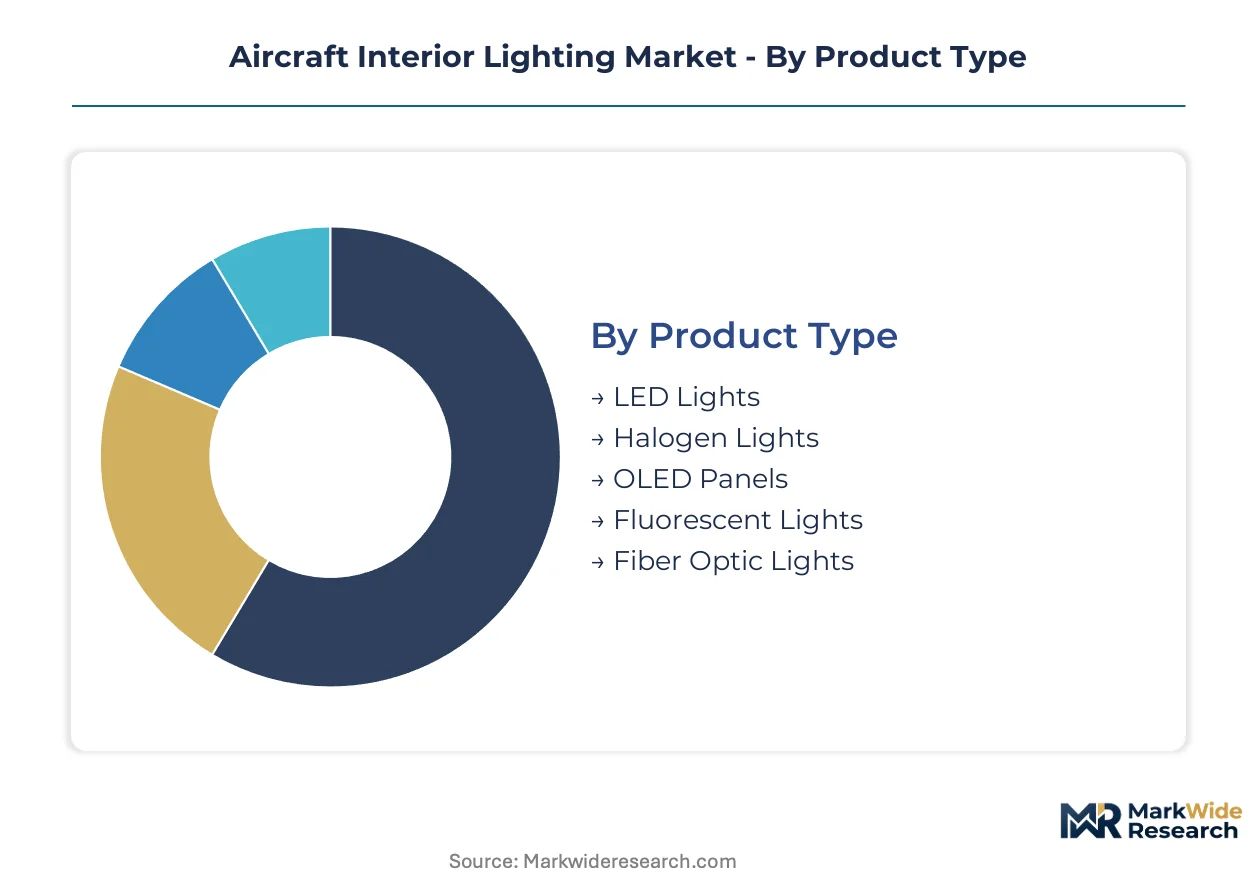
Interior lighting procurement splits sharply between commodity retrofits and experience-driven new-build specifications. Understanding where each segment sits on this spectrum reveals which suppliers capture margin versus volume.
Product Type:
Customization intensity varies from plug-compatible LED replacements to fully bespoke OLED cabin architectures requiring airframe-specific integration.
- LED Lights:Solid-state emitters operating at 28V DC with aluminum heat-sink thermal management. Narrow-body retrofit demand concentrates at US MRO facilities in Dallas-Fort Worth and Miami corridors as FAA Part 25 energy amendments force fluorescent phase-outs.
- OLED Panels:Thin-film organic emitters enabling seamless ceiling illumination without fixture depth. Long-haul carriers in the United Arab Emirates and Singapore specify these for first-class suites where weight and profile constraints override fragility concerns.
- Halogen Lights:Tungsten-halogen incandescents persisting in legacy cockpit applications where color-rendering fidelity outweighs efficiency mandates.
- Fluorescent Lights:Cold-cathode and tri-phosphor tubes facing accelerated replacement cycles under REACH Annex XVII hazardous substance restrictions.
- Fiber Optic Lights:Polymer and glass fiber bundles delivering interference-immune illumination for avionics bays and fuel-proximate zones.
Leading the category by volume: LED Lights. Expanding most quickly: OLED Panels.
Technology:
Technology tiering follows a hardware-to-software progression, with premium value capture shifting from luminaire manufacture to control algorithm licensing.
- Smart Integration:Programmable cabin management systems linking lighting to flight-phase automation and passenger service units. Full-service carriers on trans-Pacific routes deploy these for circadian rhythm programming in crew rest compartments.
- Color Changing:Multi-channel LED drivers enabling tunable white and saturated color washes. Narrow-body operators in India specify these for mood-lighting differentiation on competitive domestic trunk routes.
- Intensity Control:Analog and PWM dimming circuits for basic illumination regulation.
- Energy Efficient:Optimized driver electronics and emitter efficacy meeting tightening power-density standards.
- Wireless Connectivity:Bluetooth and proprietary RF protocols for maintenance diagnostics, constrained by FAA EMC certification bottlenecks.
Highest margin concentration: Smart Integration. Steepest adoption curve: Color Changing.
Application:
Application segmentation maps directly to passenger-facing versus operational zones, with certification rigor scaling inversely with occupant exposure.
- Passenger Cabins:Mood-lighting systems for economy through first-class seating zones, including reading lights, sidewall washes, and ceiling cove illumination. Retrofit demand clusters at German and French MRO hubs serving mixed EASA-FAA registered fleets.
- Cockpit Displays:NVIS-compatible panel and flood lighting for flight deck operations. Military aviation procurement through the US Defense Logistics Agency sustains specialized supplier relationships.
- Cargo Hold:Explosion-proof and moisture-resistant fixtures for Class E compartments.
- Lavatories:Compact, vandal-resistant luminaires with occupancy sensor integration.
- Galley Areas:Task-optimized illumination meeting food safety visibility requirements.
Largest installed base: Passenger Cabins. Fastest specification upgrade cycle: Cockpit Displays.
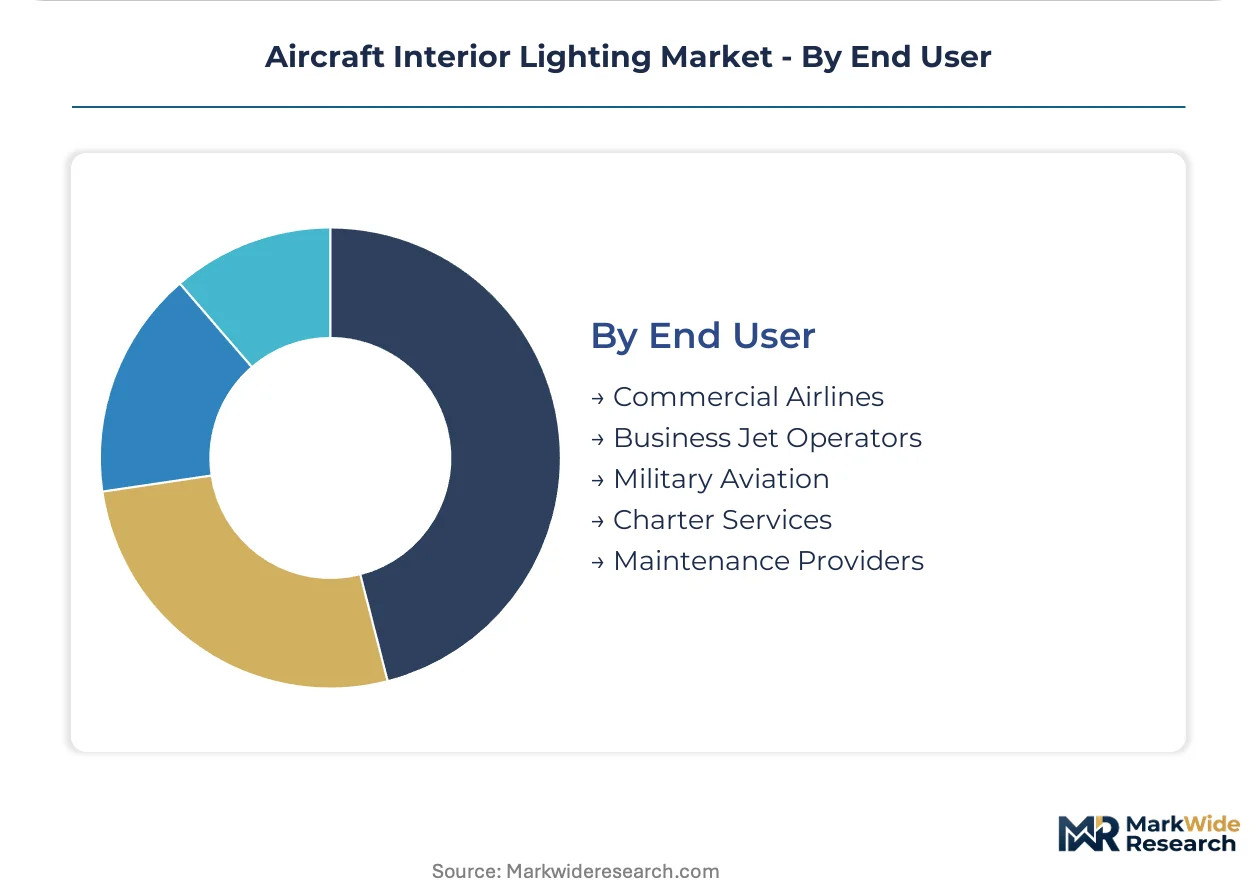
End User:
End-user segmentation reflects divergent procurement authority structures, from centralized airline fleet management to fragmented third-party maintenance decision-making.
- Commercial Airlines:Network carriers and low-cost operators specifying lighting as part of cabin brand identity programs. US legacy carriers drive narrow-body retrofit volume through accelerated fleet harmonization initiatives.
- Maintenance Providers:Independent MROs and OEM-affiliated service centers executing airworthiness directive compliance and discretionary upgrades. Indian MRO network expansion around Delhi and Mumbai creates localized specification influence points.
- Business Jet Operators:Fractional ownership and charter fleets prioritizing rapid turnaround customization.
- Military Aviation:Defense procurement agencies with MIL-STD-3009 night vision compatibility requirements.
- Charter Services:Seasonal and ad-hoc operators with deferred maintenance tendencies.
Dominant procurement volume: Commercial Airlines. Gaining share fastest: Maintenance Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth and Miami corridors anchor North American retrofit demand as FAA Part 25 energy amendments force accelerated LED conversions across aging narrow-body fleets. German and French MRO hubs concentrate European specification influence for mixed EASA-FAA registered aircraft. Delhi-Mumbai corridors in India concentrate emerging third-party maintenance capacity as fleet growth accelerates.
United States
Legacy carriers drive narrow-body retrofit volume through accelerated fleet harmonization initiatives. FAA airworthiness directives on flammability tighten certification pathways for new lighting technologies. Dallas-Fort Worth and Miami MRO corridors concentrate specification decision-making for domestic retrofit programs.
Germany
Diehl Aviation anchors European narrow-body programs through deep OEM relationships on Airbus platforms. EASA CS-25 provides parallel regulatory architecture with intensifying focus on energy efficiency metrics. Hamburg and Munich industrial clusters concentrate avionics integration expertise for next-generation cabin systems.
France
Safran extends its electrical systems portfolio into smart cabin architectures merging lighting with passenger connectivity. EU Green Deal and CSRD disclosure obligations pressure carriers to document lifecycle environmental impacts. Toulouse aerospace corridor concentrates integrated systems engineering for long-haul carrier specifications.
India
IndiGo and Air India fleet growth concentrates third-party maintenance capacity in Delhi-Mumbai corridors. BIS standards and PLI scheme incentives shape domestic supplier qualification pathways. Bangalore and Hyderabad technology zones concentrate engineering talent for control module localization.
United Arab Emirates
Long-haul carriers in Dubai and Abu Dhabi specify OLED panels for first-class suites where weight constraints override fragility concerns. GCAA harmonization with EASA standards streamlines dual-certification pathways. Dubai South aerospace cluster concentrates VIP completion center specification influence.
Aircraft Interior Lighting Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the aircraft interior lighting supply chain. The market structure tilts toward consolidation as airlines consolidate vendor relationships around integrated cabin system providers. Three archetypes dominate: avionics-heritage conglomerates bundling lighting with flight-deck systems, European OEM-captive specialists, and electrical-systems diversifiers extending into smart architectures. Dominant competitive moves include strategic partnerships for control algorithm licensing and geographic expansion into Indian MRO corridors.
Among North American avionics conglomerates, Collins Aerospace and Honeywell International exemplify the bundled-systems archetype leveraging integrated heritage. Diehl Aviation GmbH and Safran S.A. anchor European positioning through OEM-captive relationships and electrical portfolio extension. Astronics Corporation occupies a mid-tier specialist position focused on control module engineering for retrofit applications.
| Leading Market Players |
|---|
| Collins Aerospace |
| Diehl Aviation |
| Astronics Corporation |
| Safran |
| SCHOTT |
| Luminator Technology Group |
| STG Aerospace |
| Honeywell International |
| Thales |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up LED component specialists have consolidated thermal management and driver electronics manufacturing, concentrating supply leverage with three dominant distributors while compressing margin pools for retrofit contractors locked into fixed-price airline contracts.
Pricing Analysis
Value-based pricing anchored to aircraft downtime reduction and fuel burn savings from LED weight advantages commands premium positioning against commodity retrofit quotes. Pricing stratifies across FAA-EASA dual-certified systems, single-jurisdiction products, and uncertified aftermarket alternatives, with certification grade as the primary price differentiation driver. Cost compression in narrow-body retrofit tiers is intensifying because aluminum heat-sink input volatility and fixed-price MRO contracts squeeze installer margins. Low-cost carriers in India exhibit highest price sensitivity, while Emirates and Singapore Airlines premium cabin specifications show least elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese gallium nitride wafer foundries supplying LED driver substrates, creating exposure to export licensing disruptions. Manufacturing concentrates in the United States, Germany, and China, with German facilities specializing in OLED panel fabrication and US corridors dominating avionics-integrated control modules. The supply chain draws from rare-earth phosphor deposits, aluminum extrusion capacity, and specialized EMC testing laboratory availability. Tariff exposure on Chinese-sourced driver electronics threatens margin stability for mid-tier retrofit specialists. Distribution runs through OEM-affiliated service networks and independent MRO procurement desks with divergent approved supplier list requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft interior lighting market is becoming a vertical-integration race, with Collins Aerospace and Honeywell leveraging captive avionics platforms to bundle lighting with flight-deck systems while locking out component specialists from new-build specifications.
For Market Incumbents: Acquire EMC certification laboratory capacity to eliminate program timeline bottlenecks for wireless-enabled smart luminaires. Secure backward integration into aluminum heat-sink extrusion to buffer margin compression from commodity price swings. The emergence of Power-over-Ethernet cabin networks threatens standalone lighting suppliers without data infrastructure heritage. For New Entrants and Emerging Players: Begin with Indian MRO corridor penetration, where IndiGo and Air India fleet growth concentrates specification influence points previously controlled by legacy US and European vendors. Target COMAC C919 domestic supply chain qualification as the most penetrable entry vector. Pursue joint-venture structures with established avionics integrators to bypass standalone certification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap control module specialists with FAA Part 25 certification portfolios and stranded OEM relationships in German industrial clusters. Long-term viability hinges on software-defined cabin architecture positioning rather than luminaire manufacturing scale. Watch for EASA-FAA harmonization protocol convergence as the signal indicating cross-Atlantic specification consolidation and winner-take-most dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| EMC Laboratory Acquisition | Eliminates certification bottlenecks for FAA wireless-enabled smart luminaire programs. |
| Heat-Sink Backward Integration | Buffers margin compression from aluminum commodity volatility on fixed-price retrofit contracts. |
| Power-over-Ethernet Platform Development | Positions suppliers for IEEE 802.3bt cabin network convergence reducing harness weight. |
| Indian MRO Corridor Partnership | Captures specification influence points from IndiGo and Air India fleet expansion. |
| COMAC C919 Supply Qualification | Opens specification windows previously locked by Boeing-Airbus supply chain dominance. |
Research Methodology
FAA airworthiness directive filings, EASA certification databases, and airline fleet planning disclosures formed the secondary backbone, cross-referenced against primary interviews with avionics integration engineers, MRO procurement managers, airline technical specification leads, and lighting control module designers. Bottom-up and top-down triangulation validated segment-level volume estimates against OEM delivery schedules and retrofit cycle documentation.
Bottom-up modeling built from individual platform content per aircraft, fleet size by registration jurisdiction, and retrofit penetration assumptions, while top-down analysis cross-checked aggregate market evolution against aerospace electronics spending patterns. Segmentation dimensions included product type, technology tier, application zone, and end-user procurement authority. CAGR derivation incorporated LED conversion cycle acceleration from FAA Part 25 energy amendments and OLED panel adoption curves in premium cabin specifications.
Regulatory protocol divergence, raw material price volatility, and OEM supply chain consolidation are the dominant revision risks to projection assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Aircraft Cabin Interiors Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Premium Air Taxi Cabin Interior Systems Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Aerospace Galley Trolley Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market