
 Europe Commercial Aircraft Cabin Seating Market | 2026-2036
Europe Commercial Aircraft Cabin Seating Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Aircraft Cabin Seating Market Foresight
Consolidation among European full-service carriers is realigning procurement volumes toward fewer but larger fleet retrofit contracts. Safran Seats leverages its vertical integration from raw materials to final assembly to secure long-term agreements with Airbus and airline operators. Recaro Aircraft Seating anchors its position through intensive R&D spending on lightweight kinematic mechanisms that reduce per-seat weight below ten kilograms. Collins Aerospace competes by extending its avionics and interiors portfolio into connected seating platforms with integrated power and data distribution.
Europe commercial aircraft cabin seating comprises fixed and convertible passenger seating structures engineered to meet 16g crashworthiness, HIC head injury criteria, and CS 25.853 flammability standards, primarily serving airline operators seeking to maximize certified passenger capacity within type-specific cabin envelopes. Single aisle configurations dominate current delivery volumes due to narrowbody fleet renewal cycles across European low-cost carriers, while business class segments capture disproportionate margin pools through lie-flat mechanisms and direct aisle access arrangements. Fabric upholstery materials lead in unit shipments for economy cabins, though leather and advanced synthetic covers concentrate in premium tiers where replacement cycles run shorter and brand differentiation carries higher value.
EASA maintains primary regulatory authority through CS-25 certification requirements, while REACH chemical regulations and the EU Green Deal framework constrain material selection and end-of-life disposal pathways for seating components. The EU AI Act introduces emerging compliance dimensions for smart seats with passenger monitoring sensors, though implementation timelines remain under industry consultation. Stakeholders must monitor evolving EASA rulemaking on occupant safety during extended-range single aisle operations, as longer flight durations intensify ergonomic and durability requirements for narrowbody seating platforms.
Market Dynamics
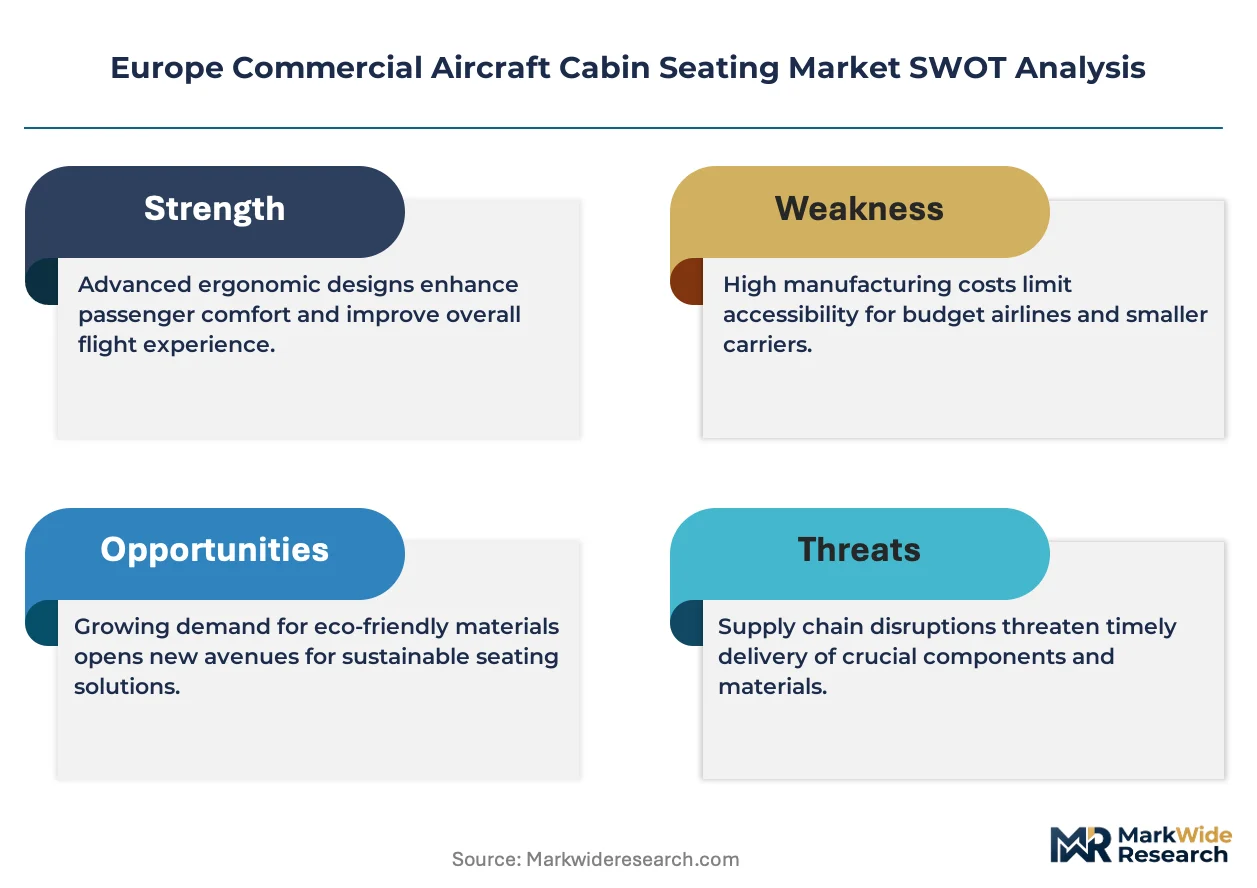
EASA's 16g dynamic seat testing mandates and REACH chemical restrictions are compressing supplier margins while forcing accelerated material transitions toward fire-resistant composites across European manufacturing networks.
Growth Catalysts
- Narrowbody fleet renewal cycles:European low-cost carriers are replacing aging A320ceo and 737-800 fleets with neo and MAX variants, triggering bulk seating procurement contracts for higher-density configurations.
- EU Green Deal framework:Carbon-neutral aviation targets are pressuring airlines to specify lighter seat structures that reduce fuel burn per passenger-kilometer across short-haul networks.
- Premium cabin retrofit investments:Full-service carriers in France, Germany, and the Netherlands are reconfiguring widebody cabins to capture yield premiums on transatlantic and Middle Eastern routes.
Market Restraints
- Raw material cost volatility:Aramid fiber and advanced thermoplastic prices fluctuate with aerospace composite demand cycles, squeezing margin predictability for seat frame manufacturers.
- Supplier concentration risk:Three integrated seating groups control final assembly capacity for EASA-certified 16g platforms, limiting airline negotiation leverage on large fleet orders.
- REACH compliance friction:Chemical substance restrictions on flame retardants and adhesives are forcing reformulation of proven upholstery bonding systems, extending qualification timelines.
Strategic Opportunities
- Extended-range single-aisle operations:Longer narrowbody flights to secondary cities in Eastern Europe and Central Asia create demand for enhanced ergonomic seating with improved recline kinematics and power distribution.
- Smart seat sensor integration:The EU AI Act's emerging passenger monitoring provisions open pathways for occupancy detection and predictive maintenance data services.
- Aftermarket refurbishment services:Compressed replacement cycles for premium cabin upholstery in business and first-class segments enable recurring revenue streams independent of new aircraft deliveries.
Industry Challenges
- Certification timeline compression:EASA's evolving rulemaking on head injury criteria and extended-range occupant safety demands simultaneous requalification of seat structures across multiple aircraft types.
- Composite repair technician scarcity:Advanced carbon fiber frame damage assessment and bonded repair capabilities remain concentrated among specialized MRO facilities in France and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Aircraft Cabin Seating Market |
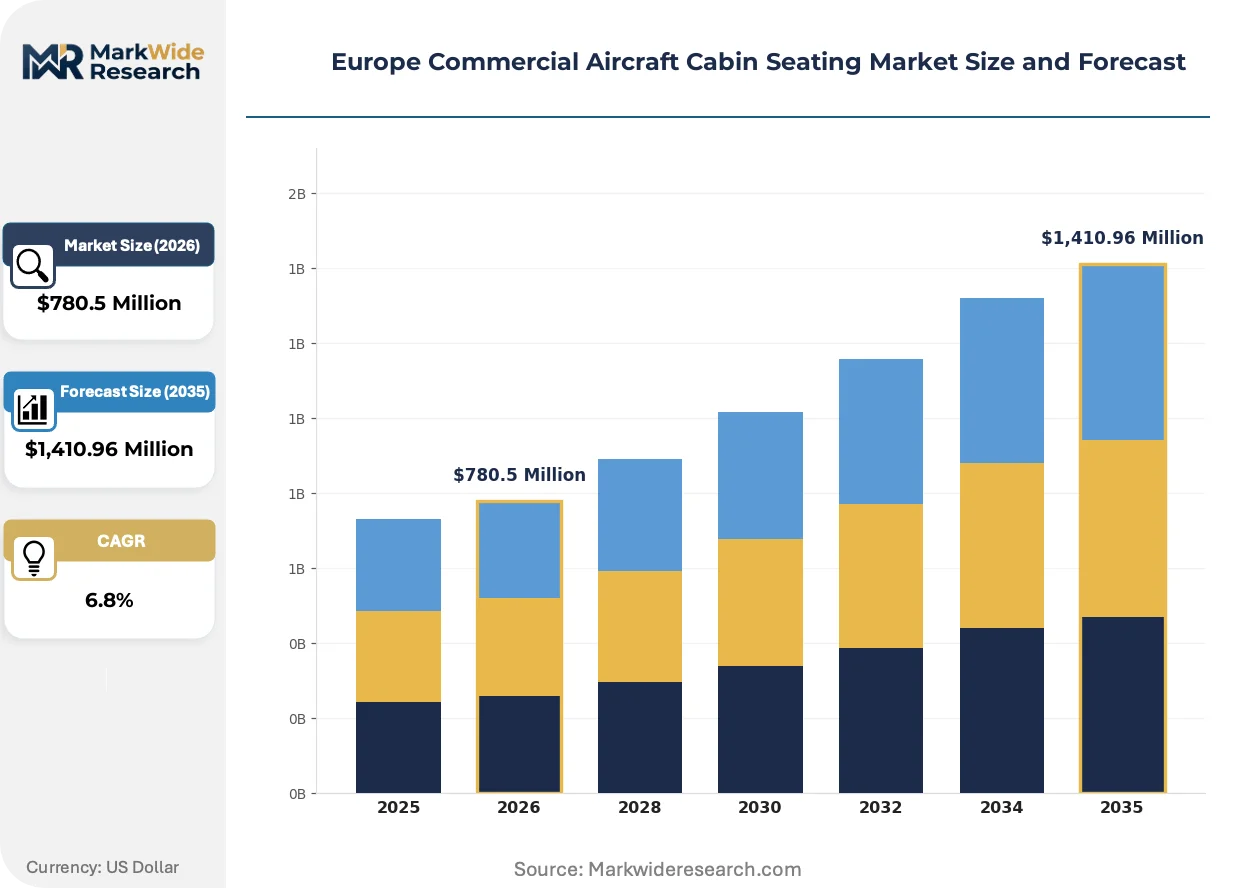
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,410.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Aisle, Twin Aisle, Business Class, First Class Material: Leather, Fabric, Foam, Plastic Configuration: 2-2, 3-3, 2-4-2, 1-1-1 End User: Airlines, Charter Services, Private Operators, Government |
| Companies Covered | Safran Seats, Recaro Aircraft Seating, Collins Aerospace, Thompson Aero Seating, Aviointeriors, Geven S.p.A., ZIM Aircraft Seating, Acro Aircraft Seating, STELIA Aerospace, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Aircraft Cabin Seating Market Shifts & Advancements
Active materials substitution and connected cabin architectures are restructuring competitive differentiation in European aircraft seating, with regulatory chemistry constraints and procurement model evolution operating as parallel forcing mechanisms.
Kinematic mechanisms employing titanium and carbon fiber hybrid structures are decentralizing weight concentration away from traditional aluminum seat frames. Lufthansa Group and Air France-KLM specification teams are embedding sub-nine-kilogram economy seat targets into narrowbody request-for-proposal documents. This materials transition is decentralizing manufacturing geography toward specialized composite processing clusters in southern Germany and southwestern France.
REACH Annex XVII restrictions on halogenated flame retardants are compelling upholstery suppliers to validate phosphorus-based and intumescent coating alternatives. The regulatory pressure is eliminating legacy vinyl formulations from premium cabin specifications and accelerating bio-based leather substitute adoption. Business class seating programs in the United Kingdom and Scandinavian markets are experiencing the most compressed reformulation schedules.
Airline technical procurement teams are consolidating seating decisions into fleet-level framework agreements spanning ten to fifteen year horizons. Traditional transaction-by-transaction purchasing for individual aircraft deliveries is contracting in favor of lifecycle cost models incorporating guaranteed weight, reliability, and refurbishment terms. This behavioral shift concentrates supplier selection authority within technical departments at International Airlines Group and Air France-KLM.
Europe Commercial Aircraft Cabin Seating Market Segmentation
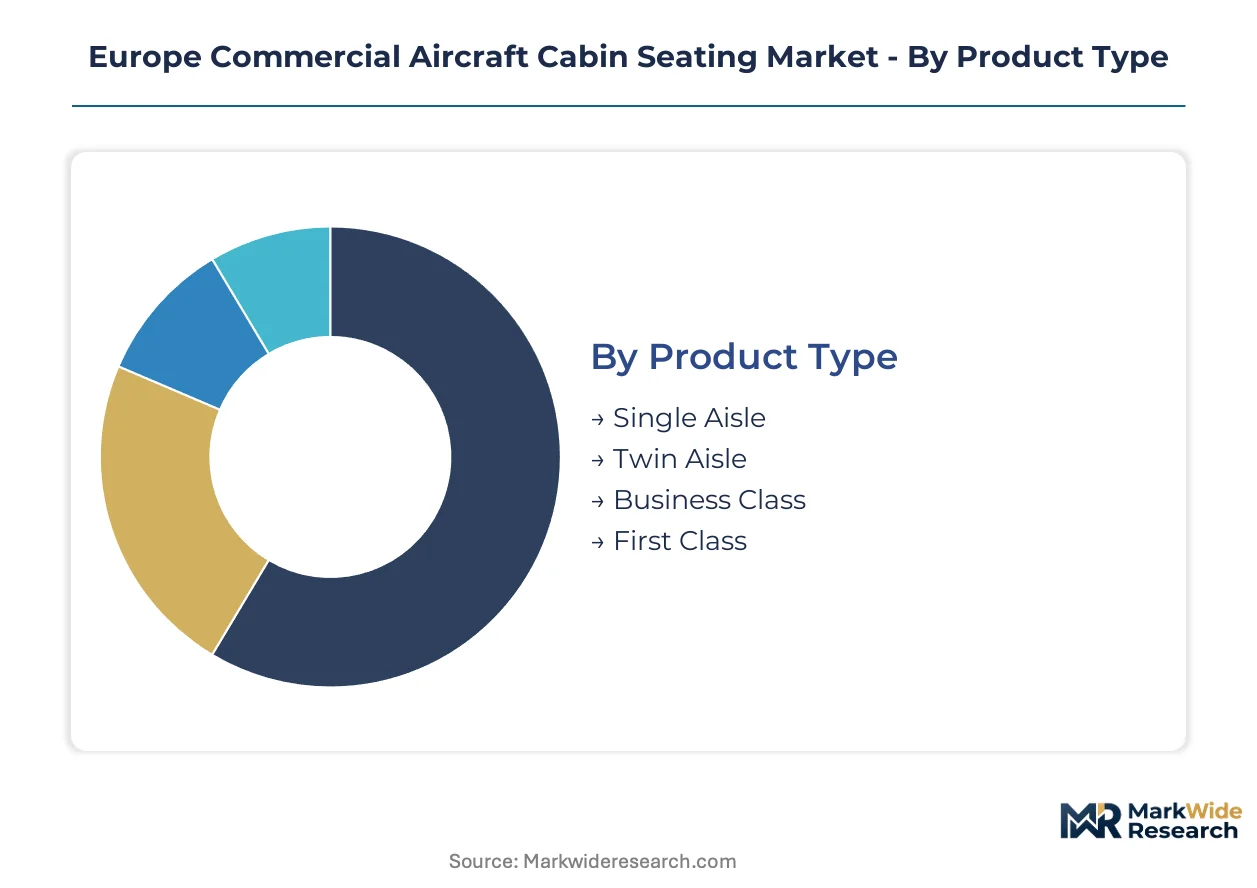
European airlines configure seating procurement around aircraft type economics, regulatory certification tiers, and yield management strategies. Segmentation reveals how material choices and cabin density specifications align with fleet renewal priorities and EASA safety mandates.
Product Type:
Airline procurement teams differentiate spending by fuselage width and revenue cabin tier, with narrowbody renewals dominating volume and widebody retrofits commanding premium unit economics.
- Single Aisle:High-density economy configurations engineered for A320neo and 737 MAX fleets serve Ryanair, easyJet, and Wizz Air renewal programs. Demand concentrates in Ireland and Hungary where low-cost carriers optimize passenger-kilometer costs through 28-inch pitch specifications.
- Twin Aisle:Lie-flat business class mechanisms and premium economy recline systems for A350 and 787 cabins capture disproportionate margin pools. Lufthansa and Air France-KLM drive specification authority through transatlantic route yield optimization.
- Business Class:Direct aisle access arrangements with staggered or reverse herringbone kinematics address extended-range single-aisle operations to Eastern Europe and Central Asia.
- First Class:Enclosed suite configurations with independent air circulation and privacy doors retain limited deployment on flagship A380 and 777-300ER services.
Single Aisle leads volumes today; Business Class is gaining share fastest.
Material:
REACH chemical restrictions and EU Green Deal carbon intensity targets are forcing upholstery specification shifts away from legacy formulations toward bio-based alternatives.
- Leather:Premium hide and advanced synthetic substitutes dominate business and first-class cabins where replacement cycles run shorter and brand differentiation carries higher value. Scandinavian carriers and British Airways specification teams are accelerating bio-based leather adoption under compressed reformulation schedules.
- Fabric:Woven synthetic upholstery engineered for 16g dynamic testing compliance and flammability resistance serves economy cabins across European low-cost networks. France and Germany concentrate manufacturing of REACH-compliant fabric treatments.
- Foam:Fire-resistant cushioning materials meeting CS 25.853 standards provide impact absorption and ergonomic support in seat back and bottom assemblies.
- Plastic:Advanced thermoplastic components reduce per-seat weight in structural frames and decorative trim elements.
Fabric leads volumes today; Leather is expanding most quickly.
Configuration:
Cabin density specifications directly determine certified passenger capacity and per-aircraft revenue potential within type-specific fuselage envelopes.
- 2-2:Regional jet and narrowbody business class arrangements providing direct aisle access without middle seats. Specifications from Air France and KLM Cityhopper prioritize passenger throughput on short-haul feeder routes.
- 3-3:Standard single-aisle economy density maximizing seats per row on A320 and 737 families. European low-cost carriers specify this configuration exclusively for fleet commonality.
- 2-4-2:Widebody economy arrangements balancing passenger capacity with emergency evacuation compliance on A330 and 787 cabins.
- 1-1-1:Ultra-premium first-class suites with enclosed compartments and independent seat kinematics deployed on select long-haul flagship services.
3-3 leads volumes today; 2-2 is climbing the fastest.
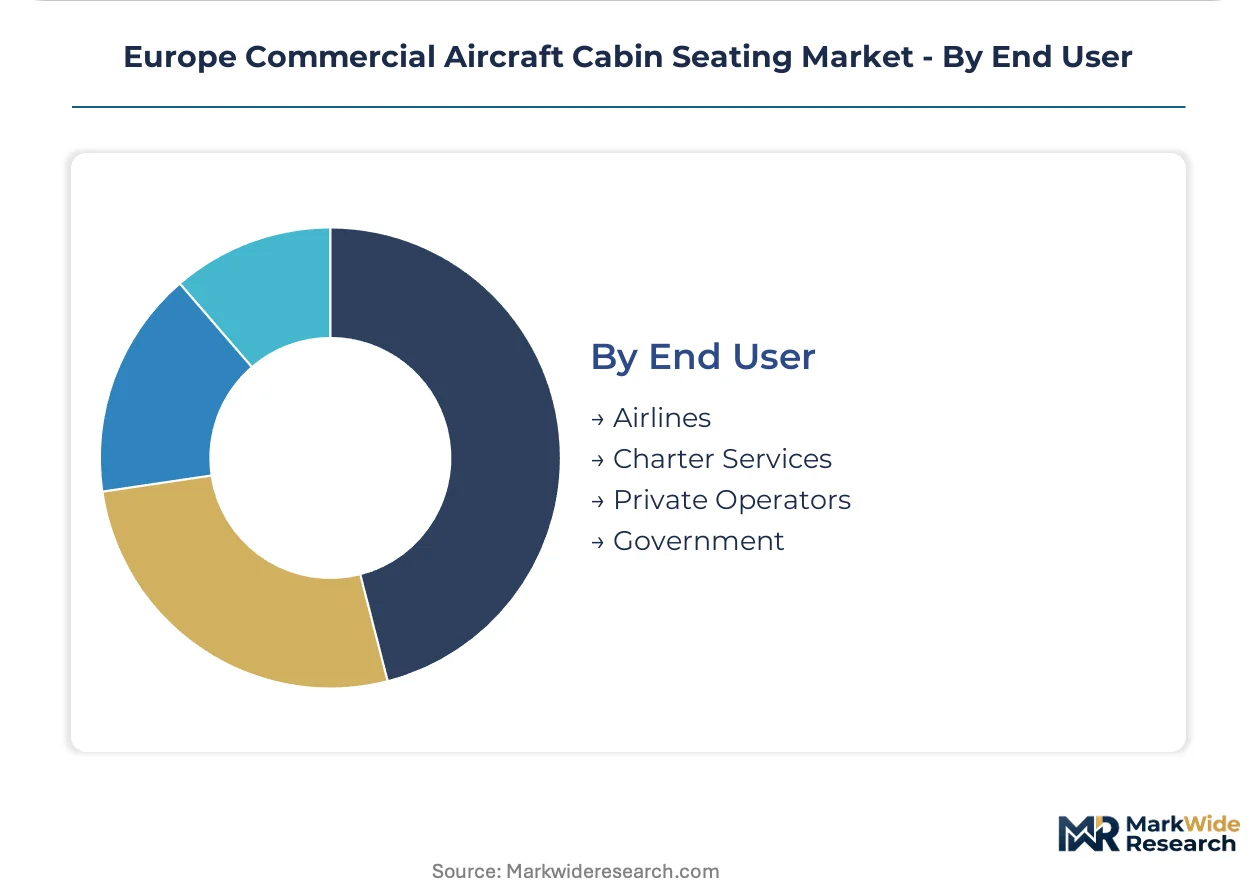
End User:
Procurement authority concentrates with scheduled network carriers, though charter and government segments impose distinct certification and durability requirements.
- Airlines:Full-service and low-cost scheduled carriers account for dominant procurement volume through fleet-level framework agreements spanning ten to fifteen year horizons. International Airlines Group and Air France-KLM technical departments consolidate supplier selection authority.
- Charter Services:Seasonal leisure operators and ACMI providers specify quick-change cabin configurations for mixed passenger-cargo operations. Demand clusters in Mediterranean markets serving holiday destinations.
- Private Operators:Corporate shuttle and VIP completion centers customize seating for head-of-state and ultra-high-net-worth aircraft modifications.
- Government:Military transport and state aircraft programs require enhanced crashworthiness and ballistic protection specifications beyond commercial CS-25 standards.
Airlines leads volumes today; Charter Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European aerospace engineering talent clusters around Toulouse, Hamburg, and Munich, anchoring procurement decisions for EASA-certified seating platforms. This workforce concentration shapes where airlines negotiate fleet-level agreements and where suppliers locate final assembly capacity.
France
Air France-KLM technical teams in Paris specify business class lie-flat mechanisms for transatlantic A350 and 787 cabins. EASA CS-25 certification requirements drive seat suppliers toward Toulouse-area engineering partnerships with Airbus final assembly lines. The Occitanie region concentrates composite frame manufacturing for 16g dynamic testing compliance.
Germany
Lufthansa Group procurement in Frankfurt and Munich embeds sub-nine-kilogram economy seat targets into A320neo RFP documents. REACH Annex XVII chemical restrictions force upholstery reformulation at Baden-Württemberg textile clusters. Hamburg anchors narrowbody retrofit engineering for extended-range single-aisle operations to Eastern Europe.
United Kingdom
British Airways specification teams in London prioritize bio-based leather substitutes for premium cabin refurbishment cycles. The UK Civil Aviation Authority enforces EASA-equivalent 16g standards while monitoring EU AI Act provisions for smart seat sensor integration. Southeast England clusters MRO facilities handling composite frame damage assessment.
Italy
ITA Airways procurement in Rome concentrates on quick-change configurations for mixed passenger-cargo charter operations. The Italian National Civil Aviation Authority aligns with EASA flammability standards while Mediterranean leisure operators drive seasonal seating demand. Lombardy suppliers focus on regional jet 2-2 business class arrangements.
Netherlands
KLM Cityhopper in Amsterdam specifies high-density economy platforms for short-haul feeder routes into Schiphol hub operations. The Human Environment and Transport Inspectorate enforces REACH compliance on flame retardant adhesives used in upholstery bonding. Eindhoven-region thermoplastic processors supply lightweight structural components.
Europe Commercial Aircraft Cabin Seating Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across EASA-certified seating procurement. Three integrated groups control final assembly capacity for 16g platforms, compressing airline negotiation leverage on large fleet orders. Market structure reveals two archetypes: aerospace conglomerates extending avionics and interiors portfolios, and dedicated seating manufacturers emphasizing kinematic R&D. Dominant competitive moves include long-term framework agreements spanning ten to fifteen years and backward integration into raw material processing.
Within the dedicated seating tier, Safran Seats and Recaro Aircraft Seating exemplify contrasting strategic positions. Safran represents the conglomerate-anchored archetype with aerospace and defense diversification. Recaro occupies a position as a focused family-owned specialist. Collins Aerospace sits within the diversified industrial group category, extending broader aviation systems capabilities into connected cabin platforms. Thompson Aero Seating anchors the mid-tier specialist segment serving retrofit and modification centers.
| Leading Market Players |
|---|
| Safran Seats |
| Recaro Aircraft Seating |
| Collins Aerospace |
| Thompson Aero Seating |
| Aviointeriors |
| Geven S.p.A. |
| ZIM Aircraft Seating |
| Acro Aircraft Seating |
| STELIA Aerospace |
| Others |
Supply & Pricing Matrix
Composite frame engineering talent clustering in southern Germany and southwestern France creates labor-cost differentials that widen pricing-tier spreads between premium kinematic mechanisms and commodity economy platforms. EASA CS-25 certification requirements concentrate high-value assembly in these regions, compressing margins on standardized narrowbody seating sourced from lower-cost upholstery processing zones.
Pricing Analysis
Bundled lifecycle service agreements covering maintenance, refurbishment, and recertification compete against unbundled per-seat transactional procurement for spot fleet retrofits. Three-tier pricing structure across premium lie-flat, standard recline, and high-density economy levels tracks certification complexity and kinematic mechanism sophistication. Pricing pressure stems from REACH compliance costs forcing upholstery reformulation at Baden-Württemberg textile clusters. Low-cost carriers exhibit highest price sensitivity through bulk narrowbody fleet orders, while full-service network carriers prioritize weight guarantees and reliability terms over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle Airbus final assembly line demand from Toulouse and Hamburg, while retrofit modification centers source through specialized distributor networks. Manufacturing concentrates in France, Germany, and Italy for EASA-certified 16g frame assembly. Aramid fiber, carbon fiber prepreg, and fire-resistant foam cushioning constitute critical input dependencies. Single-source vulnerability runs through specialized composite repair technician pools concentrated in Occitanie and Bavaria. Distribution runs through tier-one seating integrators holding long-term framework agreements with airline technical procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EASA's evolving extended-range single-aisle occupant safety rulemaking creates sustained demand for requalification services and next-generation kinematic platforms.
For Market Incumbents: Hedge against raw material cost volatility through captive supply of aramid fiber and advanced thermoplastic processing in southwestern France. Secure long-term framework agreements spanning ten to fifteen years with International Airlines Group and Air France-KLM technical departments to lock in retrofit volumes. Invest in REACH-compliant phosphorus-based flame retardant bonding systems ahead of Annex XVII enforcement timelines to defend margin position against reformulation delays. For New Entrants and Emerging Players: Enter via aftermarket refurbishment services for premium cabin upholstery replacement cycles, where business and first-class segments offer recurring revenue independent of new aircraft delivery volatility. Target Mediterranean charter operators requiring quick-change configurations for seasonal mixed passenger-cargo operations. Pursue EASA certification partnerships with established composite frame manufacturers to bypass multi-year qualification barriers. For Investors and Strategic Acquirers: Aerospace conglomerates with avionics and interiors portfolios are the most active acquirers in this space, seeking connected cabin platform integration capabilities. Mid-tier specialists with kinematic R&D depth and existing EASA 16g certifications represent prime acquisition targets over a five-to-ten year consolidation window. Monitor EASA rulemaking publication timelines as the critical signal for inflection in retrofit demand and requalification service pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Term Framework Agreement | Air France-KLM technical departments consolidate supplier selection authority through fleet-level procurement spanning multiple renewal cycles. |
| REACH-Compliant Material Transition | Phosphorus-based flame retardant validation at Baden-Württemberg textile clusters eliminates legacy vinyl from premium cabin specifications. |
| Smart Seat Sensor Integration | EU AI Act passenger monitoring provisions open predictive maintenance data services for connected cabin platform providers. |
| Extended-Range Single-Aisle Certification | EASA evolving rulemaking on occupant safety during longer narrowbody flights intensifies ergonomic and durability requirements. |
| Aftermarket Refurbishment Capacity | Compressed replacement cycles for business class upholstery enable recurring revenue streams independent of new aircraft deliveries. |
Research Methodology
Bottom-up airline fleet renewal modeling reconciled against top-down seat manufacturer order book tracking forms the analytical core of this study. Primary interviews with airline technical procurement managers, EASA certification engineers, composite frame manufacturing directors, and MRO facility operations heads were combined with secondary validation from EASA CS-25 regulatory filings, REACH Annex XVII chemical restriction updates, EU Green Deal aviation framework documents, and airline fleet plan disclosures. Triangulation across these sources ensures demand-side and supply-side estimates converge within acceptable variance bands.
Input-output matrix framing connects narrowbody and widebody delivery schedules to seat configuration densities and material specification tiers across the projection horizon. Segmentation dimensions modeled include aircraft type, cabin class tier, upholstery material grade, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical EASA certification timelines and airline retrofit program pacing. Forecast inputs incorporate composite material substitution rates and REACH compliance cost pass-through assumptions.
Inputs from airline fleet planning departments and seat manufacturer order disclosures were available through the study window; gaps in long-term narrowbody utilization assumptions for extended-range operations introduce uncertainty bands around ergonomic seating demand estimates. Forecasts reflect documented assumptions regarding EASA rulemaking implementation pacing and EU Green Deal carbon intensity target enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Aircraft Cabin Management System Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Seat Upholstery Market