
 Aircraft Galley Market | 2026-2036
Aircraft Galley Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Galley Market Analysis
The EU Green Deal and associated aviation decarbonization targets are repositioning galley procurement criteria toward lighter, recyclable configurations. Collins Aerospace leverages its integrated aerostructures portfolio to supply thermoplastic composite galleys that reduce per-unit mass. Jamco Corporation anchors its position through dedicated aerospace manufacturing facilities in Japan and sustained R&D partnerships with Asian carriers. Safran Cabin differentiates via smart galley architectures that integrate IoT-enabled inventory tracking for commercial airline clients.
An aircraft galley constitutes the onboard food preparation and service station, typically fabricated from aluminum alloys, carbon-fiber-reinforced polymers, or hybrid sandwich panels rated for flame, smoke, and toxicity (FST) compliance under FAR 25.853. The assembly houses ovens, chillers, beverage makers, and waste compaction units within a constrained fuselage envelope optimized for weight and spatial efficiency. Galley inserts and beverage equipment dominate current revenue as fleet operators prioritize retrofit compatibility over full-system replacement. Smart galleys and energy-efficient designs represent the fastest-expanding technology cluster, though modular systems retain the broadest installed base across narrow-body platforms.
FAA airworthiness directives and EASA certification standards (CS-25) govern flammability, electrical safety, and electromagnetic interference for galley installations, creating compliance barriers that favor established OEM partnerships. The EPA and REACH frameworks increasingly restrict halogenated flame retardants in polymer matrices, pushing suppliers toward phosphorus-based alternatives. Stakeholders must monitor evolving MEE environmental standards in China and dual carbon policy implementation timelines, as these will reshape material qualification pathways and supplier qualification costs for galley manufacturers serving international programs.
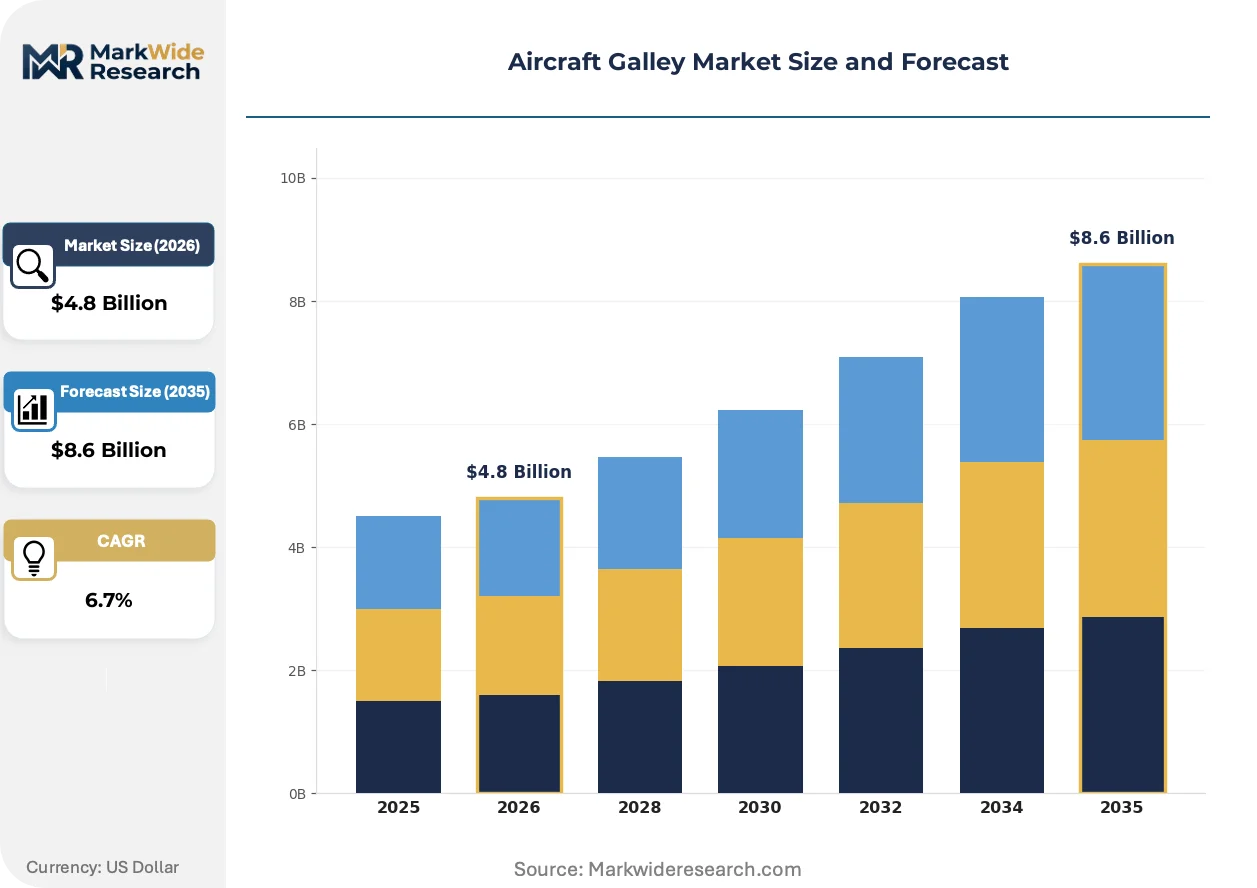
Market Dynamics
Fleet renewal cycles across narrow-body commercial airlines are compressing procurement timelines for lightweight galley systems, forcing suppliers to accelerate composite material qualification while maintaining FAA and EASA airworthiness compliance.
Growth Catalysts
- Weight-reduction mandates:FAA and EASA certification standards under FAR 25.853 and CS-25 are compelling fleet operators to replace aluminum galley structures with carbon-fiber-reinforced polymer alternatives to achieve fuel efficiency targets.
- IoT integration:Smart galley architectures with inventory tracking capabilities are gaining traction among full-service carriers seeking operational visibility across narrow-body and wide-body platforms.
- Asian fleet expansion:China and Japan are experiencing concentrated demand for galley retrofits as domestic carriers accelerate narrow-body procurement to serve regional route networks.
Market Restraints
- Composite material costs:Thermoplastic polymer feedstock prices exhibit volatility tied to petrochemical supply chains, compressing margin structures for galley OEMs serving price-sensitive retrofit segments.
- Certification timeline friction:EASA CS-25 and FAA flame-smoke-toxicity testing protocols for new polymer matrices extend product development cycles by 18-24 months versus legacy aluminum configurations.
- Substitution pressure from galley-less configurations:Ultra-low-cost carriers are piloting buy-on-board models that eliminate full galleys in favor of compact service stations, threatening addressable volume in the budget airline segment.
Strategic Opportunities
- India's aviation infrastructure buildout:The country's PLI scheme for aerospace manufacturing is creating localized assembly opportunities for galley suppliers targeting IndiGo and Air India's narrow-body fleet requirements.
- Phosphorus-based flame retardant transition:REACH restrictions on halogenated compounds are opening qualification pathways for European chemical suppliers specializing in sustainable polymer additives.
- Modular retrofit kits:Standardized insert compatibility across Boeing 737 MAX and Airbus A320neo platforms is enabling aftermarket revenue streams independent of full galley system replacement cycles.
Industry Challenges
- Electromagnetic interference certification:Integrating IoT-enabled galley systems with existing aircraft avionics requires extensive FAA STC (Supplemental Type Certificate) validation, creating deployment bottlenecks for smart galley rollouts.
- Cross-program material qualification:Suppliers must maintain parallel certification tracks for thermoplastic composites under both EASA and FAA frameworks, duplicating testing expenditure without guarantee of reciprocal acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Galley Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Galley Inserts, Food Storage Systems, Beverage Equipment, Waste Management Solutions Technology: Smart Galleys, Modular Systems, Automated Dispensing, Energy-Efficient Designs End User: Commercial Airlines, Private Jets, Military Aviation, Cargo Planes Distribution Channel: Direct Sales, Distributors, Online Platforms, OEM Partnerships |
| Companies Covered | Jamco Corporation, AIM Altitude, Collins Aerospace, Korita Aviation, Aerolux Ltd., Safran Cabin, Bucher Leichtbau AG, Dynamo Aviation, Diehl Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Galley Market Emerging Trajectories
Thermoplastic composite manufacturing is displacing thermoset processes across galley structural components, driven by recyclability requirements under the EU Green Deal and compressed production cycle demands from narrow-body OEMs.
Thermoplastic composite sandwich panels are expanding into primary galley structural elements previously dominated by aluminum honeycomb constructions. Narrow-body fleet operators in Germany and the United States are adopting these configurations at accelerating pace to meet 2030 weight-reduction targets. The technology is expanding into secondary galley components including stowage bins and meal-cart retention systems, creating downstream qualification requirements for insert manufacturers.
REACH Phase 2 restrictions on halogenated flame retardants are forcing polymer matrix reformulations across European galley supply chains. The regulation is compressing incumbent chemical supplier relationships while elevating phosphorus-based additive specialists. Narrow-body platforms serving intra-European routes face the most acute compliance pressure, with retrofit timelines accelerating to avoid fleet grounding risks.
Airline procurement teams are consolidating galley and cabin interior contracts under single-source aerostructures agreements, displacing standalone galley vendor relationships. Full-service carriers in China and Japan are leading this consolidation, bundling smart galley systems with overhead bin and lavatory packages. The pattern concentrates negotiation leverage with integrated cabin system providers while fragmenting standalone galley OEM access to new-build programs.
Aircraft Galley Market Segmentation
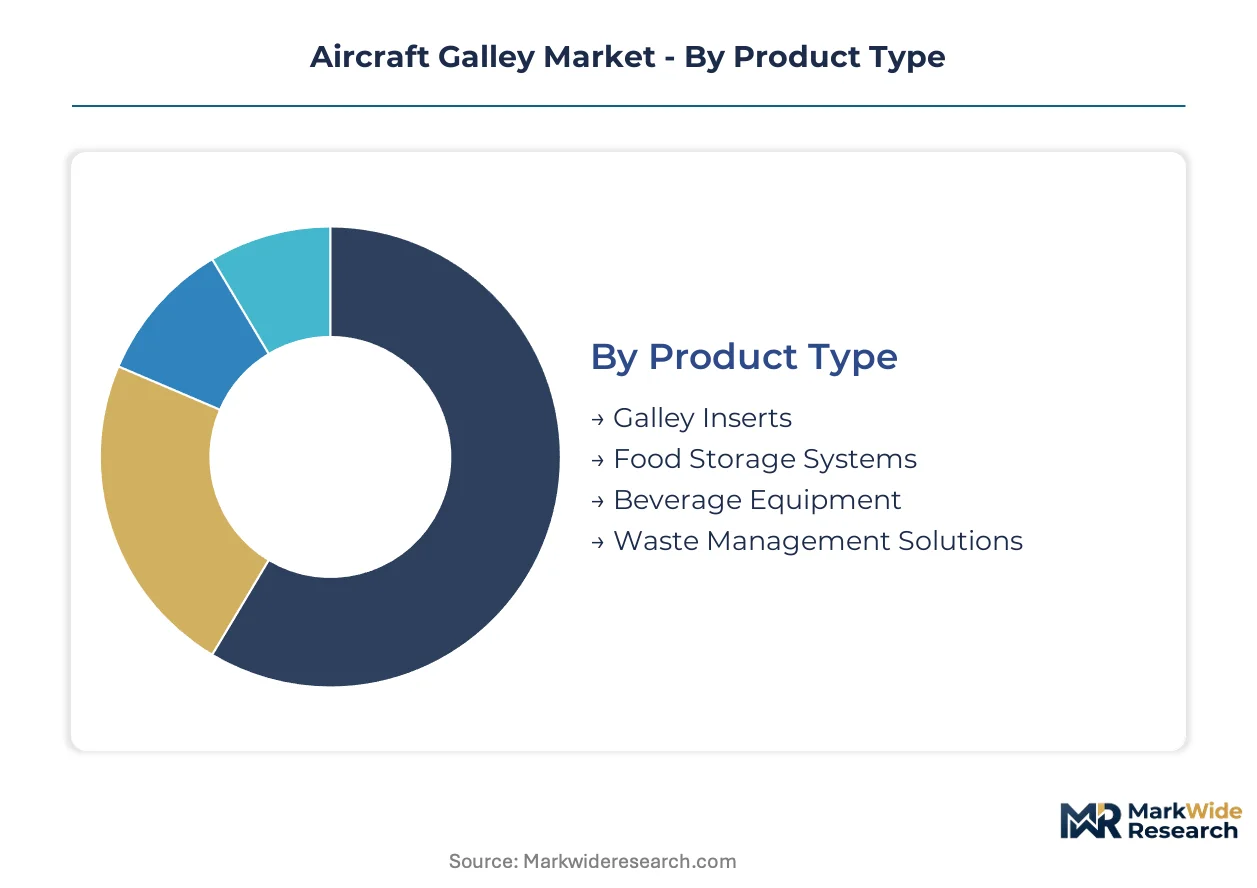
Aircraft galley procurement splits across multiple dimensions that determine certification pathways, margin structures, and supplier access. Fleet operators balance retrofit compatibility against new-build specifications, while regulatory compliance requirements vary sharply by installation type and carrier category.
Product Type:
Customization intensity spans from standardized beverage dispensers to fully bespoke food storage architectures, with cost and certification complexity rising along this spectrum.
- Galley Inserts:Self-contained units including ovens, chillers, and coffee makers designed for standardized rail mounting systems. Demand concentrates among narrow-body retrofit programs in the United States and Germany, where FAA STC timelines pressure operators toward plug-and-play solutions that minimize aircraft downtime.
- Food Storage Systems:Refrigerated compartments and ambient stowage rated for meal-cart containment and thermal retention. Asian carriers in China and Japan are prioritizing these configurations for regional route networks, driven by expanded in-flight catering requirements on single-aisle platforms.
- Beverage Equipment:Hot and cold drink dispensers with FST-rated housings.
- Waste Management Solutions:Compactors and collection units for post-service cleanup.
Most installed capacity flows through Galley Inserts. Expansion is steepest in Food Storage Systems.
Technology:
Cost tier separation distinguishes premium smart architectures from baseline modular configurations, with energy efficiency emerging as a mid-market differentiator.
- Smart Galleys:IoT-enabled systems integrating inventory sensors, predictive maintenance modules, and crew workflow optimization software. Full-service carriers in Japan and Germany are deploying these platforms to reduce catering waste and accelerate turnarounds, though FAA electromagnetic interference certification creates deployment friction.
- Modular Systems:Interchangeable structural and insert components enabling rapid reconfiguration between service cycles. Narrow-body operators across China and the United States favor these for fleet commonality, as standardized rail interfaces reduce spare parts complexity across Boeing 737 MAX and Airbus A320neo mixed fleets.
- Automated Dispensing:Crew-reduction equipment for self-service beverage and snack distribution.
- Energy-Efficient Designs:Low-draw electrical systems optimized for next-generation aircraft power architectures.
Modular Systems retain the broadest installed base. Smart Galleys are climbing the fastest as IoT integration matures.
End User:
Application severity separates commercial aviation's volume-driven procurement from specialized military and private aviation requirements with divergent certification and performance specifications.
- Commercial Airlines:Full-service and low-cost carriers operating narrow-body and wide-body fleets under EASA CS-25 and FAA Part 25 airworthiness frameworks. Fleet renewal cycles in China, Germany, and the United States are compressing procurement timelines, with weight-reduction mandates accelerating composite material adoption.
- Private Jets:Business aviation operators specifying bespoke galley configurations for VIP cabin layouts. Demand clusters in the United States and Switzerland, where completion centers prioritize aesthetic customization and reduced certification burden versus commercial platforms.
- Military Aviation:Transport and tanker aircraft with mission-specific catering requirements.
- Cargo Planes:Converted freighter configurations with minimal or eliminated galley systems.
Commercial Airlines absorb the dominant volume share. Private Jets deliver the steepest margin expansion trajectory.
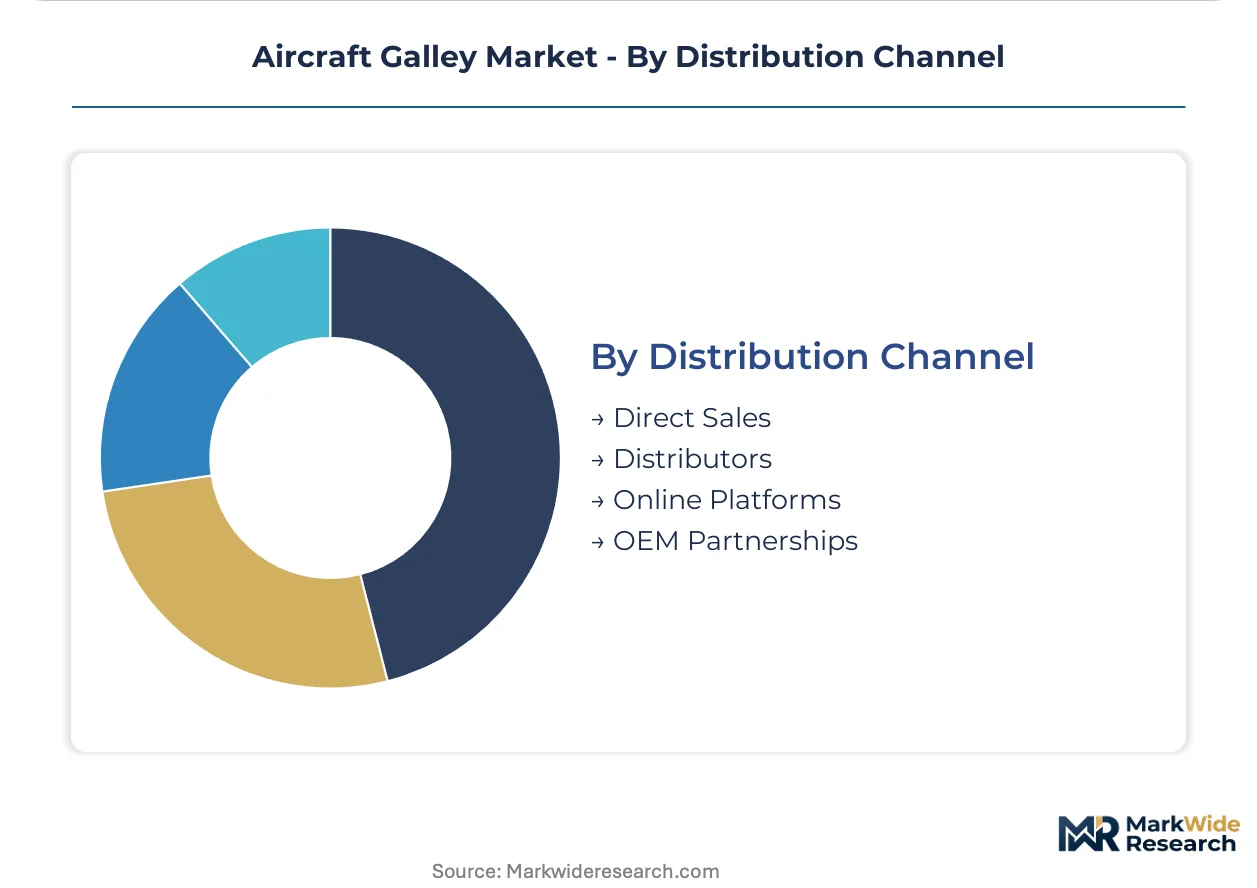
Distribution Channel:
Customer type and contract scale determine channel selection, with direct relationships dominating fleet-wide programs and intermediaries serving fragmented retrofit demand.
- Direct Sales:OEM-to-airline contracts covering new-build fleet commitments and multi-aircraft retrofit campaigns. Airbus and Boeing supply chain integration in Germany and the United States favors this channel, as airframers consolidate galley procurement within broader cabin interior packages.
- OEM Partnerships:Tier-1 aerostructures suppliers embedding galley systems within integrated lavatory, stowage, and monument assemblies. Collins Aerospace and Safran Cabin leverage these arrangements to secure sole-source positions on narrow-body programs in China and Japan.
- Distributors:Regional stocking intermediaries for aftermarket spare parts and emergency replacements.
- Online Platforms:Digital procurement portals for standardized inserts and consumables.
OEM Partnerships capture the largest new-build volume. Direct Sales channels are gaining share fastest as airlines consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aircraft galley industry traces its modern origins to post-war American aerospace manufacturing, with Boeing's commercial aviation dominance establishing Seattle as the first major galley procurement hub. European airframers subsequently built parallel supply chains around Toulouse and Hamburg, while Japan's METI-driven aerospace industrialization in the 1970s created a third concentration.
United States
Fleet renewal cycles at American Airlines, Delta, and United are compressing procurement timelines for Boeing 737 MAX galley retrofits. FAA airworthiness directives under FAR 25.853 are accelerating composite material transitions across domestic narrow-body fleets. The Pacific Northwest aerospace cluster around Seattle and Everett hosts integrated cabin system providers serving both new-build and aftermarket segments.
Germany
Airbus's Hamburg final assembly lines are driving concentrated demand for A320neo galley configurations among Lufthansa Group and Eurowings. EASA CS-25 certification standards and REACH Phase 2 restrictions on halogenated flame retardants are reshaping polymer matrix specifications. The Bavarian aerospace corridor around Munich anchors specialist thermoplastic composite suppliers qualifying for next-generation galley platforms.
China
COMAC's C919 production ramp and Air China's narrow-body fleet expansion are generating procurement volume for domestically assembled galley systems. MEE environmental standards and dual carbon policy implementation timelines are accelerating local material qualification pathways. The Yangtze River Delta manufacturing belt around Shanghai hosts joint-venture cabin interior facilities serving both indigenous and Western airframe programs.
Japan
ANA and JAL's regional fleet modernization is concentrating demand for weight-optimized galley retrofits on domestic route networks. METI's aerospace industrial policy supports dedicated manufacturing facilities for thermoplastic composite components. The Chubu region around Nagoya maintains precision fabrication capabilities for galley structural elements serving Asian carrier retrofit programs.
India
IndiGo and Air India's narrow-body procurement campaigns are opening localized assembly opportunities under the PLI scheme for aerospace manufacturing. BIS certification requirements and DGFT import substitution policies are reshaping supplier qualification pathways. The Karnataka-Telangana aerospace corridor around Bangalore and Hyderabad is attracting tier-1 galley component manufacturers seeking proximity to emerging fleet operators.
Aircraft Galley Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification complexity and integration depth. The vendor base organizes into three tiers: integrated aerostructures conglomerates controlling full cabin system portfolios, standalone galley specialists competing on retrofit responsiveness, and regional fabricators serving aftermarket spare parts demand. Consolidation pressure is intensifying as airlines bundle galley procurement within single-source monument contracts. Strategic partnerships between composite material suppliers and tier-1 aerostructures providers represent the dominant competitive move, followed by geographic expansion into Asian manufacturing hubs.
Among integrated aerostructures providers, Collins Aerospace and Safran Cabin exemplify the full-cabin-system archetype, anchoring positions through OEM partnerships on narrow-body programs. Jamco Corporation occupies a distinct position as a Japan-based specialist with dedicated aerospace manufacturing facilities. These three represent contrasting strategic postures: American and French conglomerates leveraging portfolio breadth against Japanese precision fabrication focused on regional carrier relationships.
| Leading Market Players |
|---|
| Jamco Corporation |
| AIM Altitude |
| Collins Aerospace |
| Korita Aviation |
| Aerolux Ltd. |
| Safran Cabin |
| Bucher Leichtbau AG |
| Dynamo Aviation |
| Diehl Aviation |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of thermoplastic composite structures anchors both supply security and pricing power for tier-1 galley OEMs serving narrow-body programs in Germany, the United States, and China. Backward integration into carbon-fiber-reinforced polymer feedstock processing shields these suppliers from petrochemical volatility while compressing qualification timelines under EASA CS-25 and FAA FAR 25.853 frameworks.
Pricing Analysis
Three-tier pricing structure across premium smart-galley, standard modular, and economy retrofit tiers governs procurement negotiations between OEMs and fleet operators. Price differentiation rests on certification grade—FAA STC versus full airframe OEM qualification—and volume scale across single-aircraft versus fleet-wide commitments. Cost compression in the economy retrofit tier is intensifying because REACH Phase 2 compliance is forcing polymer matrix reformulations without corresponding value capture. Ultra-low-cost carriers exhibit the sharpest price sensitivity, while full-service carriers in Japan and Germany absorb premium tiers for IoT-enabled inventory tracking capabilities.
Supply Chain Analysis
Refurbishment flows for galley inserts and beverage equipment are creating secondary supply channels that compete with new-build OEM shipments, particularly for Boeing 737 MAX and Airbus A320neo retrofit programs. Manufacturing concentration centers on Germany, the United States, and Japan, with emerging assembly capacity in China's Yangtze River Delta and India's Karnataka-Telangana corridor. Raw material dependencies draw from carbon-fiber prepreg suppliers in Japan, thermoplastic resin specialists in Germany, and phosphorus-based flame-retardant additive producers in Switzerland. Single-source vulnerability around FAA-certified composite qualification labs concentrates risk in the Pacific Northwest and Bavarian aerospace clusters. Distribution runs through OEM-embedded partnerships for new-build programs and regional distributors for aftermarket spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
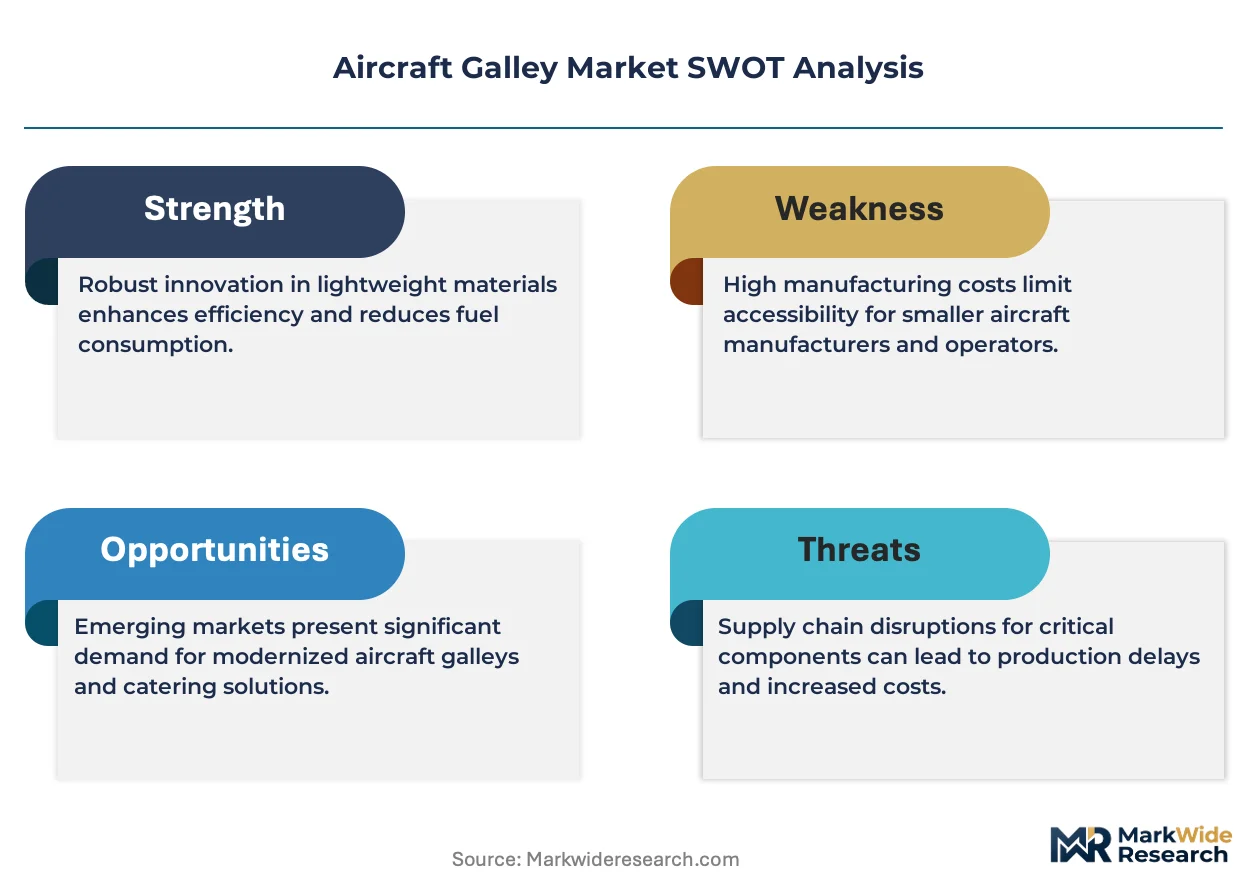
Margin expansion in this market is anchored in composite material cost-down curves as thermoplastic manufacturing scales, alongside premium-tier capture from smart-galley IoT deployments among full-service carriers in Germany and Japan.
For Market Incumbents: Anchor positions through exclusive thermoplastic composite qualification partnerships with EASA and FAA certification labs, compressing rival access to 18-24 month approval pathways. Deepen backward integration into carbon-fiber prepreg processing to offset petrochemical feedstock volatility threatening margin structures in the retrofit segment. Prioritize smart-galley software development to defend against standalone IoT vendors fragmenting the premium tier. For New Entrants and Emerging Players: Thermoplastic composite recycling technology offers a wedge into European supply chains facing EU Green Deal recyclability mandates. Target India's PLI scheme aerospace manufacturing incentives for localized assembly partnerships with IndiGo and Air India's narrow-body fleet requirements. Pursue modular retrofit kit standardization across Boeing 737 MAX and Airbus A320neo platforms as the primary go-to-market angle, bypassing full-system certification barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where airlines bundle galley procurement within single-source monument contracts, concentrating negotiation leverage with integrated cabin system providers. Long-term viability favors tier-1 aerostructures conglomerates with full-cabin-system portfolios spanning lavatories, stowage, and monuments alongside galley capabilities. Watch for FAA electromagnetic interference certification bottlenecks in smart-galley deployments as an inflection signal—resolution would accelerate premium-tier adoption and reshape competitive positioning toward software-integrated hardware providers.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Composite Qualification Partnership | Secures 18-24 month EASA and FAA certification timelines against rival access. |
| Smart-Galley IoT Platform Development | Captures premium tier from ANA and Lufthansa Group operational visibility requirements. |
| Modular Retrofit Kit Standardization | Enables aftermarket revenue independent of full galley replacement cycles. |
| India PLI Scheme Manufacturing Localization | Positions assembly capacity adjacent to IndiGo and Air India fleet expansion. |
| Phosphorus-Based Flame Retardant Transition | Aligns polymer matrices with REACH Phase 2 restrictions ahead of competitor reformulation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airline procurement directors, cabin interior engineering leads, EASA certification specialists, and thermoplastic composite R&D directors at tier-1 suppliers with secondary validation. Secondary sources included FAA airworthiness directive filings, EASA CS-25 certification databases, REACH Phase 2 regulatory updates, and airline fleet renewal announcements. Bottom-up segment sizing across product type, technology, and end-user categories was triangulated against top-down aerospace manufacturing output estimates.
Comparable-period anchoring to historical fleet renewal cycles and retrofit penetration rates established the forecast window baseline. The analytical framework modeled segmentation across product type, technology tier, end-user category, and distribution channel, with regional production cluster as an industry-specific dimension. CAGRs were derived from fitted growth curves applied to validated base-year estimates. Industry-specific forecast inputs included narrow-body delivery schedules from Boeing and Airbus, and EASA flame-smoke-toxicity testing protocol timelines for new polymer matrices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH regulatory expansion timelines and COMAC C919 production ramp execution. Forecasts reflect documented assumptions around fleet renewal cycle intensity and composite material qualification reciprocity between EASA and FAA frameworks. Practitioners should monitor FAA STC backlog durations and thermoplastic resin price indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Commercial Aircraft Floor Panels Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Aircraft Cabin Interiors Market
Aircraft Cabin Interior
Aircraft Cabin Management System Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Cabin Interior Composites Market