
 Fixed Wing Aircraft Rivets Market | 2026-2036
Fixed Wing Aircraft Rivets Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Wing Aircraft Rivets Market Analysis
The fixed wing aircraft rivets market is restructuring around a widening gap between aerospace-grade titanium and nickel alloy fasteners and commodity aluminum rivets used in general aviation. Precision Castparts Corp. leverages captive metallurgy capabilities to dominate premium engine-adjacent fastening, while LISI Aerospace anchors European supply chains through specialized blind rivet production for Airbus programs. Cherry Aerospace differentiates via proprietary locking technologies that sustain higher shear-load ratings in military airframe applications.
Fixed wing aircraft rivets are permanent mechanical fasteners installed in drilled or pre-punched holes, typically cold-worked through bucking or pull-stem installation to create a shop head that clamps structural sheets together under controlled preload. Solid rivets remain the mature backbone of primary fuselage assembly, but blind rivets are capturing faster growth in automated wing panel lines where rear-side tool access is restricted. Titanium material grades command the deepest margin pools as OEMs substitute heavier stainless steel in next-generation weight-reduction programs, while aluminum persists in high-volume secondary structures where cost sensitivity outweighs performance premiums.
FAA airworthiness standards and EASA CS-25 certification frameworks mandate traceable lot control, tensile testing documentation, and anti-corrosion surface treatments that filter out non-aerospace suppliers. Military Contractors face supplemental DFARS sourcing constraints and ITAR-controlled alloy specifications that further narrow qualified vendor pools. Stakeholders must monitor how OEM consolidation of fastener specifications into platform-wide master agreements reshapes pricing leverage and volume allocation across tier-two distributors.
Market Dynamics
Fixed wing aircraft rivets procurement is restructuring around OEM consolidation of fastener specifications into platform-wide master agreements, concentrating pricing leverage among Boeing and Airbus supply chains while squeezing tier-two distributors.
Growth Catalysts
- FAA Airworthiness Directives:Fatigue-resistant fastening mandates tighten material specifications, filtering non-aerospace suppliers and expanding qualified vendor pools for titanium-grade producers.
- Commercial Fleet Renewal:Narrowbody replacement cycles at Boeing and Airbus drive OEM procurement volumes for solid and blind rivet configurations across fuselage and wing assemblies.
- Titanium Substitution:Weight-reduction programs displace stainless steel with aerospace-grade titanium alloys in engine-adjacent structures, deepening margin pools for metallurgy-capable manufacturers.
Market Restraints
- DFARS Sourcing Constraints:Military contractors face ITAR-controlled alloy specifications and domestic content requirements that narrow qualified supplier pools for defense airframe programs.
- Raw Material Volatility:Sponge titanium and nickel alloy input costs fluctuate with aerospace demand cycles, compressing margins for distributors without long-term OEM contracts.
- Automated Fastening Systems:Electromagnetic riveting and friction stir welding technologies threaten blind rivet growth in wing panel assembly lines with rear-access automation.
Strategic Opportunities
- Urban Air Mobility Airframes:Electric vertical takeoff platforms require lightweight fastening systems certified to modified CS-23 standards, opening design-in opportunities for specialized blind rivet configurations.
- Indian MRO Expansion:IndiGo and Air India fleet growth drives aftermarket rivet demand through Bangalore and Hyderabad maintenance clusters, bypassing traditional European distribution channels.
- EU Green Deal Alignment:EASA emissions reduction frameworks incentivize weight-optimized titanium fasteners in retrofitted narrowbody fuel efficiency programs.
Industry Challenges
- NDT Certification Bottlenecks:Eddy current and ultrasonic inspection qualifications for automated rivet installation require 18-24 month technician training programs, constraining workforce scaling.
- Lot Traceability Systems:FAA and EASA mandate serialized documentation across forging, heat treatment, and surface coating stages, forcing legacy ERP upgrades at mid-tier distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Wing Aircraft Rivets Market |
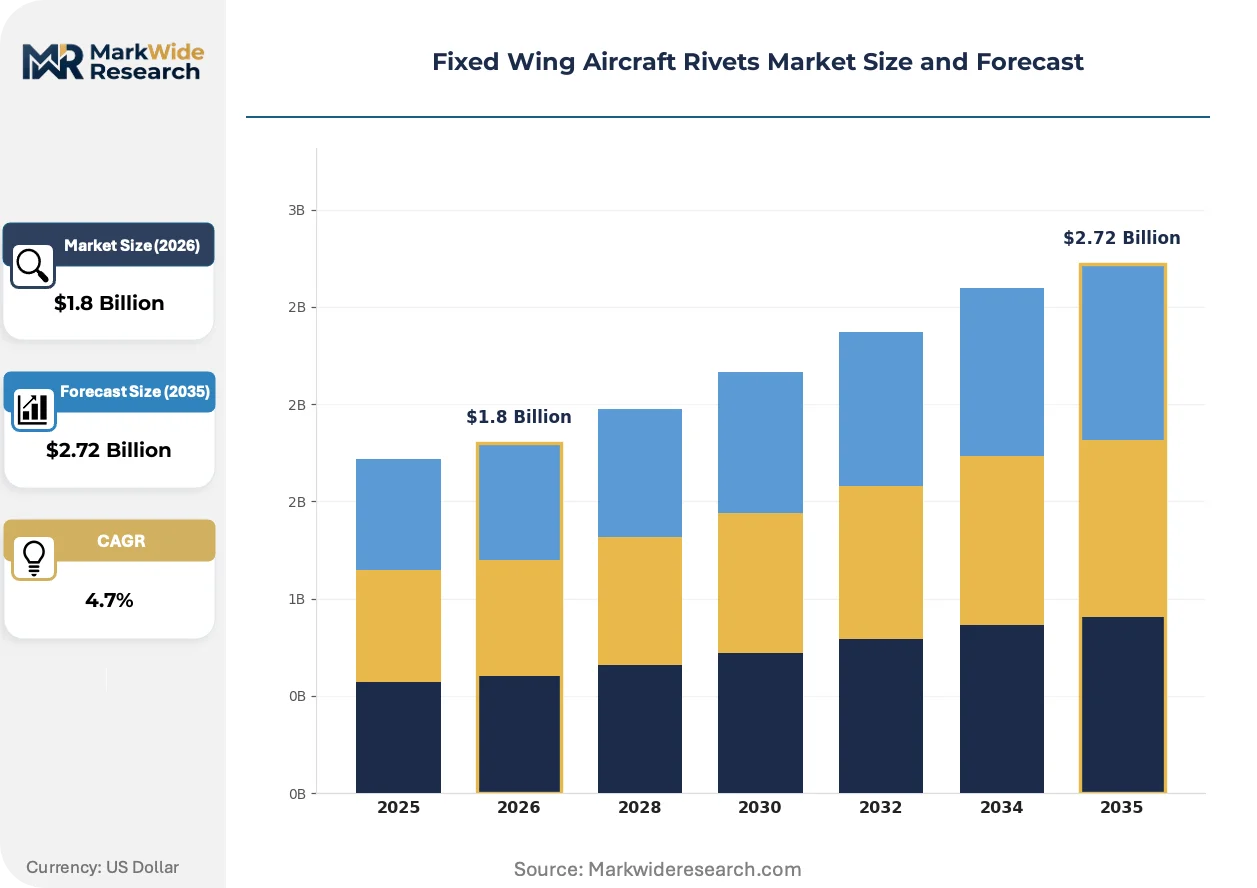
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Rivets, Blind Rivets, Semi-tubular Rivets, Grip Rivets Material: Aluminum, Stainless Steel, Titanium, Nickel Alloys Application: Fuselage, Wings, Control Surfaces, Landing Gear End User: OEMs, Maintenance Providers, Aftermarket Suppliers, Military Contractors |
| Companies Covered | Stanley Black & Decker, Inc., Alcoa Fastening Systems & Rings, Precision Castparts Corp., LISI Aerospace, Cherry Aerospace, Arconic Inc., Monogram Aerospace Fasteners, Allfast Fastening Systems, TriMas Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Wing Aircraft Rivets Market Emerging Trajectories
Fixed wing rivet technology is absorbing automation pressures and regulatory tightening through material substitution and installation method evolution. Three developments dominate supplier R&D allocation.
Titanium-beta alloys with enhanced cold-workability are absorbing shear-load requirements previously assigned to heavier stainless steel configurations. Airbus A320neo and Boeing 737 MAX wing programs specify these grades for fuel efficiency gains. The technology is absorbing margin compression from commodity aluminum rivets by concentrating premium pricing in engine-adjacent applications.
EASA CS-25 certification amendments now mandate documented fatigue life testing for all primary structural fasteners, extending approval timelines by 8-14 months. European OEMs respond by consolidating supplier qualifications into multi-year platform agreements. Tier-one distributors in France and Germany absorb compliance costs through captive metallurgy laboratories.
Airline procurement teams now specify outcome-based fastener performance contracts tied to airframe longevity metrics rather than unit pricing. MRO channels in the United States and United Kingdom face disintermediation as OEMs enforce direct vendor-managed inventory at airline technical operations centers. The shift compresses distributor margins while locking in volume commitments.
Fixed Wing Aircraft Rivets Market Segmentation
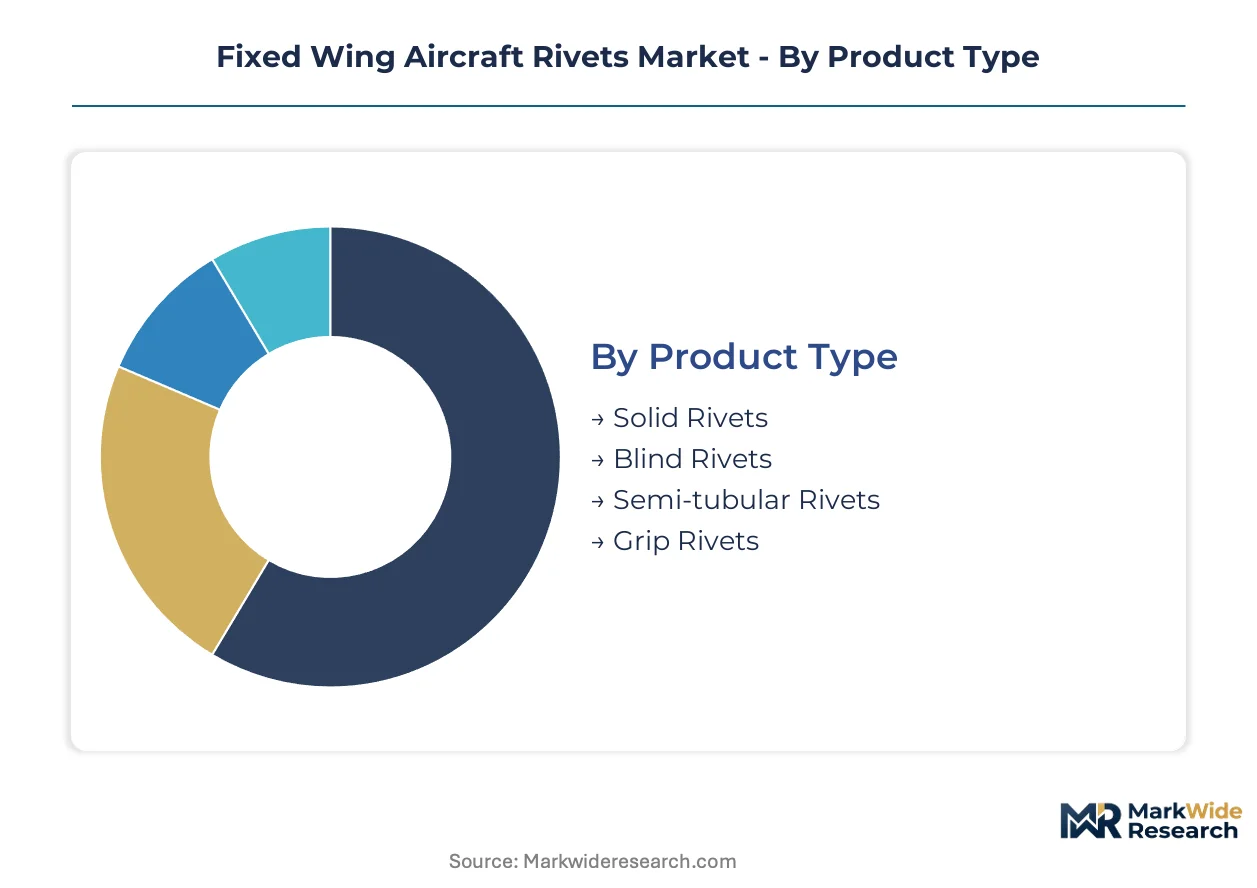
Fixed wing aircraft rivet procurement splits across four distinct dimensions, each governing different margin structures and qualification barriers. Product type determines installation automation compatibility, while material selection locks suppliers into specific metallurgy certifications.
Product Type:
Upgrade cycles in narrowbody assembly lines are reconfiguring demand toward blind rivet configurations that accommodate rear-access automation.
- Solid Rivets:Cold-worked aluminum and titanium alloys installed through bucking bar techniques remain the structural backbone of primary fuselage joints. Boeing 737 MAX and Airbus A320neo programs in the United States and France anchor procurement volumes for these configurations, though manual installation requirements constrain throughput in automated wing panel lines.
- Blind Rivets:Pull-stem fasteners with self-forming shop heads capture expanding share in wing assembly where rear-side tool access is restricted. Airbus wing plants in Germany and Boeing facilities in Washington state specify these grades for automated drilling and fastening cells, driving supplier qualification investments at European distributors.
- Semi-tubular Rivets:Partial-hollow configurations serve secondary structural applications in general aviation airframes manufactured in Wichita and Savannah clusters.
- Grip Rivets:Specialized clamping designs accommodate variable material thicknesses in retrofit and repair scenarios across United States MRO networks.
Volume placements concentrate in solid rivets; the faster expansion belongs to blind rivets.
Material:
Cost tier stratification separates aerospace-grade titanium from commodity aluminum, with nickel alloys occupying a narrow defense-specialist niche.
- Aluminum:2024-T4 and 2117-T4 grades dominate high-volume secondary structures where cost sensitivity outweighs performance premiums. General aviation manufacturers in the United States and Brazil specify these alloys for non-critical fuselage skins and interior attachments.
- Titanium:Ti-6Al-4V and beta-alloy formulations command the deepest margin pools as OEMs substitute heavier stainless steel in next-generation weight-reduction programs. Airbus and Boeing engine-adjacent structures in France, Germany, and Washington state specify these grades for fuel efficiency gains.
- Stainless Steel:A-286 and 17-4 PH grades persist in high-temperature exhaust fairings and landing gear attachments where corrosion resistance exceeds titanium cost justification.
- Nickel Alloys:Inconel and Monel specifications serve military turbine exhaust structures subject to ITAR-controlled sourcing constraints.
Aluminum retains the largest installed base; titanium alloys are climbing the fastest.
Application:
Structural criticality governs material specification intensity, with primary load-bearing assemblies demanding full metallurgical traceability.
- Fuselage:Circumferential lap joints and longitudinal stringer attachments require solid rivet configurations with documented fatigue life certification. Boeing and Airbus final assembly lines in Washington state, South Carolina, France, and Germany concentrate procurement for these applications.
- Wings:Spar-to-skin connections and rib assemblies specify blind rivets for automated panel lines. Airbus wing plants in Broughton, UK and Bremen, Germany anchor European demand.
- Control Surfaces:Aileron, elevator, and rudder hinge fittings utilize semi-tubular configurations in secondary structural roles.
- Landing Gear:High-shear stainless steel and titanium grades withstand cyclic loading in strut and door attachments.
Fuselage applications absorb the greatest procurement volume; wing assemblies are gaining share fastest.
End User:
Customer type determines contract structure, with OEMs consolidating specifications into platform-wide master agreements that reshape distributor economics.
- OEMs:Boeing and Airbus anchor production schedules through multi-year fastener agreements that concentrate pricing leverage. Direct vendor-managed inventory programs at final assembly sites in the United States, France, and Germany disintermediate traditional distribution channels.
- Maintenance Providers:United Airlines, Delta, and Lufthansa Technik operations in Houston, Atlanta, and Hamburg drive aftermarket demand through airframe longevity programs and D-check intervals.
- Aftermarket Suppliers:Tier-two distributors in the United States and United Kingdom face margin compression as OEMs enforce direct supply relationships with airline technical operations centers.
- Military Contractors:Lockheed Martin and Northrop Grumman programs operate under DFARS sourcing constraints and ITAR-controlled alloy specifications that narrow qualified vendor pools.
Procurement volume concentrates with OEMs; maintenance providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors global fixed wing aircraft rivets procurement through Boeing's final assembly lines and its captive supplier base, with precision fastener demand radiating across Washington state's aerospace corridor.
United States
Boeing 737 MAX and 777X production schedules in Everett and Renton drive solid rivet volumes for fuselage assembly. FAA airworthiness directives on fatigue-resistant fastening tighten material specifications for titanium-grade suppliers. Wichita's general aviation cluster sustains aluminum rivet demand for secondary structures at Textron Aviation and Bombardier facilities.
France
Airbus final assembly in Toulouse and wing production in Broughton anchor European procurement for blind rivet configurations. EASA CS-25 certification amendments extend approval timelines, consolidating supplier qualifications into multi-year platform agreements. Saint-Étienne's metallurgy laboratories absorb compliance costs for tier-one distributors serving A320neo programs.
Germany
Airbus wing plants in Bremen and Hamburg specify automated blind rivet installations for A350 and A330neo panels. REACH regulations govern surface treatment chemistries for anti-corrosion coatings. Bavaria's precision engineering cluster hosts specialized fastener distributors qualified to EASA traceability mandates.
United Kingdom
Broughton's wing assembly operations for Airbus anchor titanium rivet demand through GKN Aerospace supply chains. UK Export Finance programs support fastener procurement for defense airframe programs at BAE Systems. Southwest England's MRO clusters in Bristol and Gloucester face OEM disintermediation through direct vendor-managed inventory.
India
IndiGo and Air India fleet expansion drives aftermarket rivet demand through Bangalore and Hyderabad maintenance hubs. DGFT import regulations on aerospace-grade alloys filter qualified supplier pools for domestic distributors. Tata Advanced Systems' aerostructures plant in Hyderabad opens design-in opportunities for blind rivet specifications on regional aircraft programs.
Fixed Wing Aircraft Rivets Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material certification tiers, with titanium-grade specialists commanding pricing leverage over aluminum-rivet distributors. The market structures around three strategic archetypes: metallurgy-integrated manufacturers with captive forging capabilities, specialized blind-rivet producers serving automated assembly lines, and tier-two distributors facing margin compression from OEM consolidation. Competitive moves concentrate on backward integration into heat-treatment operations and multi-year platform agreements that lock in volume commitments.
Among North American fabricators, Precision Castparts Corp. and Cherry Aerospace exemplify the metallurgy-integrated archetype, while LISI Aerospace anchors European supply chains from its French base. Stanley Black & Decker, Inc. occupies a position spanning industrial tool adjacencies into aerospace fastening distribution. These three represent distinct competitive vectors: captive titanium capabilities, specialized blind-rivet automation, and scale-driven portfolio breadth.
| Leading Market Players |
|---|
| Stanley Black & Decker, Inc. |
| Alcoa Fastening Systems & Rings |
| Precision Castparts Corp. |
| LISI Aerospace |
| Cherry Aerospace |
| Arconic Inc. |
| Monogram Aerospace Fasteners |
| Allfast Fastening Systems |
| TriMas Corporation |
| Others |
Supply Flow & Price Mechanics
Automated riveting systems adoption in wing panel assembly lines simultaneously compresses unit economics for blind rivet configurations and concentrates procurement leverage among Boeing and Airbus supply chains. This technology shift feeds back into supplier consolidation as tier-two distributors absorb margin compression from long-term OEM master agreements.
Pricing Analysis
Outcome-based performance contracts tied to airframe longevity metrics now anchor pricing negotiations between OEMs and qualified suppliers. Three-tier pricing structure across premium titanium grades, standard aluminum alloys, and economy general aviation specifications separates margin pools by certification intensity. Cost compression in commodity aluminum segments is intensifying because general aviation manufacturers in Brazil and the United States prioritize unit cost over traceability documentation. Military contractors exhibit the lowest price sensitivity due to DFARS sourcing constraints, while aftermarket distributors face the highest sensitivity from OEM disintermediation.
Supply Chain Analysis
Freight costs for aerospace-grade titanium sponge from Russia and Kazakhstan feed into margin structures at forging operations in the United States, France, and Germany. Raw material dependencies center on sponge titanium, nickel alloy feedstock, and specialized anti-corrosion surface treatment chemistries. Single-source vulnerability runs through qualified heat-treatment facilities certified to FAA and EASA lot traceability mandates. Distribution runs through direct vendor-managed inventory programs at Boeing and Airbus final assembly sites, bypassing traditional tier-two channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FAA airworthiness directives and EASA CS-25 certification requirements create a regulatory moat that filters out non-aerospace suppliers and protects qualified incumbents.
For Market Incumbents: Lock in multi-year platform agreements with Boeing and Airbus before automated fastening systems displace blind rivet growth in wing panel lines. Backward integration into captive heat-treatment operations absorbs compliance costs for EASA lot traceability mandates. Precision Castparts Corp. and LISI Aerospace demonstrate how metallurgy-integrated manufacturers defend margin pools against commodity aluminum distributors.
For New Entrants and Emerging Players: Electromagnetic riveting compatibility for urban air mobility airframes offers a technology-first wedge into modified CS-23 certification pathways for electric vertical takeoff platforms. Indian MRO expansion through Bangalore and Hyderabad maintenance clusters presents the most penetrable geography, bypassing entrenched European distribution channels. Design-in partnerships with Tata Advanced Systems' aerostructures operations provide a direct go-to-market angle for blind rivet specifications on regional aircraft programs.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by tier-one aerospace conglomerates seeking captive titanium metallurgy capabilities. Long-term viability hinges on qualification barriers that extend 18-24 months for NDT technician training programs. Watch for inflection signals in EASA emissions reduction frameworks that accelerate titanium substitution in retrofitted narrowbody fuel efficiency programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive metallurgy operations absorb EASA lot traceability compliance costs at tier-one distributors. |
| Multi-Year Platform Agreement | OEM master contracts with Boeing and Airbus lock in volume commitments and pricing leverage. |
| Automated Installation Certification | NDT technician qualifications for eddy current inspection constrain workforce scaling. |
| Urban Air Mobility Design-In | Modified CS-23 certification pathways open specialized blind rivet opportunities for electric vertical takeoff platforms. |
| Indian MRO Channel Development | Bangalore and Hyderabad maintenance hubs bypass traditional European distribution for aftermarket rivet demand. |
Methodological Framework
Multi-period observation of Boeing and Airbus production schedules, FAA airworthiness directive issuance patterns, and titanium sponge price indices anchored the trend analysis, supplemented by interviews with procurement directors at tier-one distributors, quality assurance managers at heat-treatment facilities, and program managers at military contractors. Secondary validation drew from FAA certification databases, EASA CS-25 amendment filings, SEC 10-K disclosures from publicly traded fastener manufacturers, and customs trade data for aerospace-grade alloy imports. Bottom-up segment sizing triangulated against top-down OEM procurement estimates.
Segment-weighting across product type, material grade, application structural criticality, and end-user contract structure informed the analytical framework across the analysis window. CAGRs were derived from production forecast trajectories for 737 MAX and A320neo programs, alloy substitution rates in engine-adjacent structures, and MRO demand modeling for fleet renewal cycles. Forecast inputs included Boeing and Airbus order backlogs, DGFT import regulation changes in India, and REACH surface treatment compliance timelines in Germany.
Several conditions sit outside the modeled scope, including unannounced platform cancellations, geopolitical disruptions to titanium sponge supply, and breakthrough friction stir welding adoption that eliminates riveted joints entirely. Forecasts reflect documented assumptions about OEM production rate stability and certification timeline continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Search and Rescue Helicopter Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
GCC Business Jet Market
Aircraft
Active Air Deflector Market
Aircraft
Light and Very Light Jets Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Commercial Aerospace Market
Aircraft
Global Ultralight and Light Aircraft Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Aircraft Leasing Market
Aircraft
Airship Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Aircraft Sequencing System Market