
 Airplane Ailerons Market | 2026-2036
Airplane Ailerons Market Size, Share, and Industry Trends Forecast 2026-2036
Airplane Ailerons Market Insights
Fly-by-wire actuation is tilting aileron design toward electromechanical systems with embedded sensors. Boeing leverages vertical integration across its control surface supply chain to secure proprietary actuation architectures. Spirit AeroSystems anchors high-volume composite aileron fabrication for narrowbody platforms. Saab AB specializes in military-grade flight control surfaces with enhanced survivability specifications.
An airplane aileron is a hinged flight control surface mounted on the trailing edge of each wing, typically spanning 15 to 25 percent of the wing chord, that generates differential roll moments through asymmetric deflection to bank the aircraft. Carbon fiber composite ailerons now dominate new commercial programs because the material's specific stiffness reduces hinge moment loads and enables thinner aerodynamic profiles. Frise ailerons occupy the retrofit segment for turboprop fleets where adverse yaw compensation remains critical. Maintenance Repair Organizations represent a growing customer type as aging aircraft inspections drive recurring replacement demand for corroded aluminum alloy surfaces.
FAA airworthiness standards under Part 25 govern aileron structural integrity and flutter margins for transport category aircraft, while EASA CS-25 certification imposes equivalent fatigue life requirements across European-registered fleets. Both regulators now mandate damage tolerance assessments for composite control surfaces, forcing suppliers to maintain extensive test databases. Stakeholders must monitor evolving electromechanical actuation reliability standards as hybrid hydraulic-electric architectures proliferate across next-generation platforms.
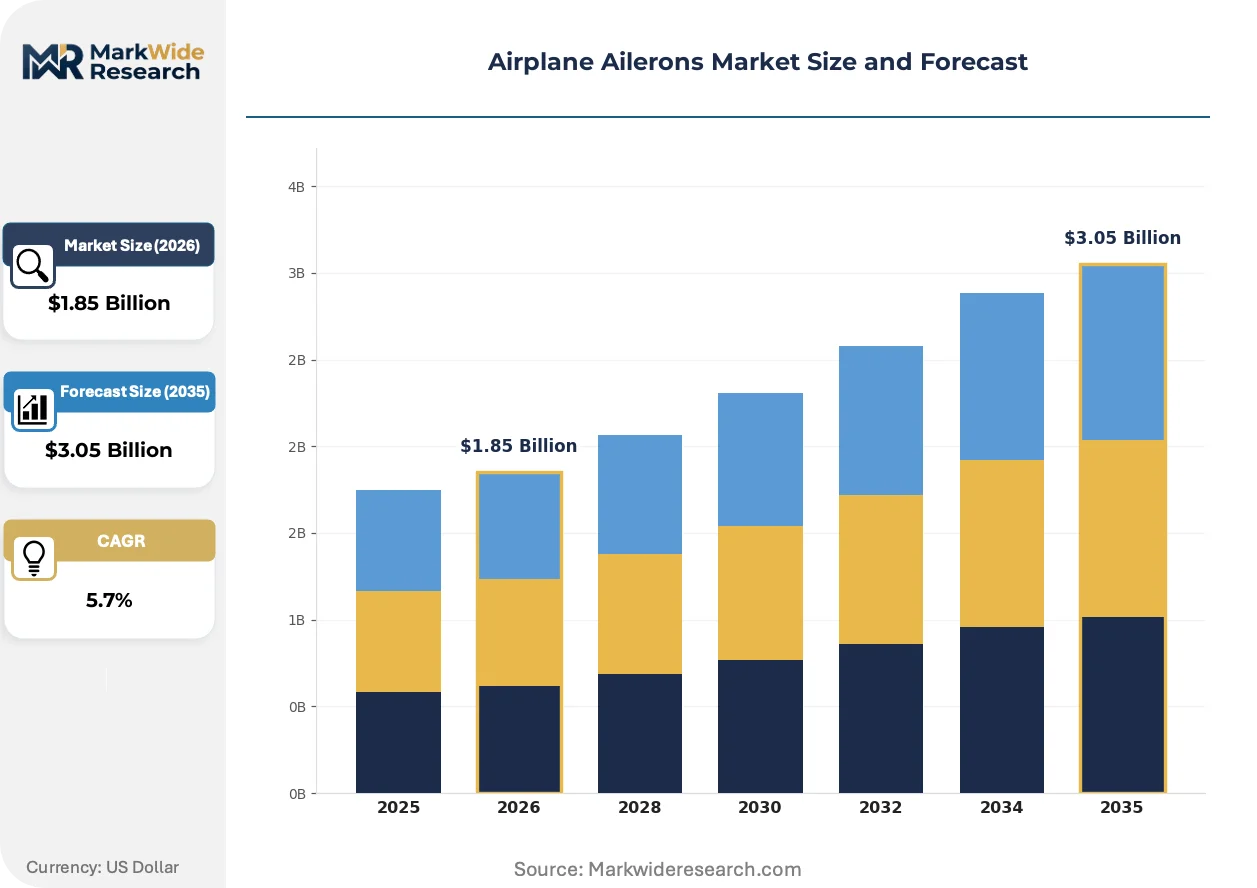
Market Dynamics
Electromechanical actuation architectures are displacing hydraulic systems across narrowbody and widebody platforms, compressing supplier margins while forcing tier-one fabricators to absorb sensor integration costs.
Growth Catalysts
- CS-25 Amendment 25:EASA's updated damage tolerance mandates for composite control surfaces compel fleet operators to accelerate replacement schedules for aging aluminum ailerons.
- Fly-by-wire proliferation:Next-generation aircraft programs embed electromechanical actuation with real-time load monitoring, expanding addressable content per shipset.
- India:IndiGo and Air India's fleet expansion orders drive localized MRO capacity buildup for flight control surface overhaul.
Market Restraints
- Carbon fiber prepreg volatility:Aerospace-grade Toray T800S and Hexcel IM7 supply concentrates among Japanese and US chemical processors, exposing fabricators to resin system price swings.
- Single-source forging risk:Titanium hinge fittings for high-load aileron attachments depend on a narrow supplier base in the United States and Russia.
- Hydraulic legacy lock-in:Retrofit platforms face integration barriers where existing hydraulic routing cannot accommodate electromechanical torque tubes without wing box modification.
Strategic Opportunities
- Brazil:Embraer's E2 program supplier localization requirements create openings for composite aileron fabrication within Mercosur trade zones.
- Digital thread certification:Model-based systems engineering shortcuts FAA Part 21 compliance timelines for derivative aileron designs.
- Urban air mobility:eVTOL developers specify morphing aileron concepts that blend roll control with drag modulation, diverging from conventional hinged architectures.
Industry Challenges
- Electromechanical reliability database gaps:Mean-time-between-failure data for hybrid actuation remains thin, forcing suppliers to fund extended accelerated life testing.
- Composite repair technician scarcity:Boeing and Airbus-approved scarf repair certification requires specialized fiber placement training that outpaces vocational pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airplane Ailerons Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Ailerons, Frise Ailerons, Differential Ailerons, Slotted Ailerons, Others Material: Aluminum Alloy, Carbon Fiber Composite, Titanium, Thermoplastic, Kevlar Application: Commercial Aircraft, Military Aircraft, Business Jets, Agricultural Planes, Experimental Aircraft Customer Type: Aircraft Manufacturers, Maintenance Repair Organizations, Aerospace Suppliers, Aviation Training Centers |
| Companies Covered | Saab AB, Sealand Aviation Ltd, ShinMaywa Industries, Strata Manufacturing, Turkish Aerospace Industries, Asian Composites Manufacturing, LAM Aviation, Boeing, Spirit AeroSystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airplane Ailerons Market Trends and Innovations
Sensor fusion and additive manufacturing are converging to reshape how flight control surfaces are designed, certified, and maintained across the commercial and defense sectors.
Shape-memory alloy actuation is digitizing aileron trim response through embedded nickel-titanium wire arrays that replace conventional servo tabs. Business jet OEMs are piloting these systems on super-midsize platforms where weight reduction justifies development cost. The technology is digitizing feedback loops between pilot input and surface deflection, compressing latency margins previously reserved for fly-by-wire architectures.
REACH Annex XVII restrictions on hexavalent chromium surface treatments are forcing suppliers to transition toward plasma electrolytic oxidation for aluminum alloy corrosion protection. This regulatory shift elevates processing costs but eliminates hazardous waste liabilities for European MRO facilities. Suppliers serving EASA-registered fleets are consolidating finishing operations to capture economies of scale.
Airline technical procurement teams are unbundling flight control surface contracts from full airframe purchase agreements, creating direct relationships with tier-two fabricators. This disintermediation bypasses traditional airframe OEM markup structures while transferring certification liability downstream. The pattern is most pronounced among low-cost carriers in Southeast Asia negotiating component-level spare provisioning.
Airplane Ailerons Market Segmentation
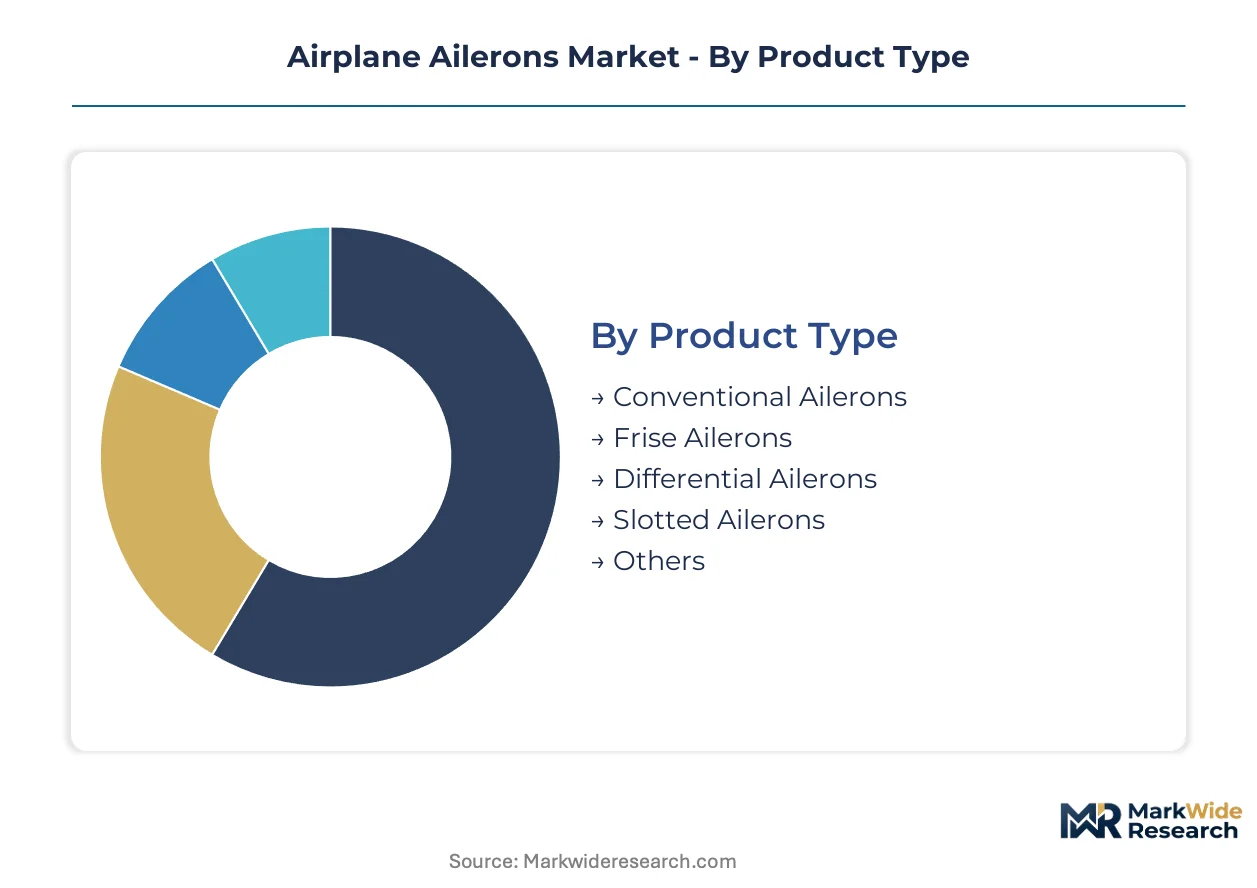
Aileron procurement patterns diverge sharply across platform types and operational cycles. Fleet operators prioritize retrofit compatibility, while OEMs drive specifications toward integrated electromechanical architectures.
Product Type:
Mature architectures dominate installed bases, yet emerging configurations are capturing new program awards through aerodynamic efficiency gains.
- Conventional Ailerons:Hinged trailing-edge surfaces with simple up-down deflection mechanics constitute the bulk of legacy fleet installations. Boeing 737 NG and Airbus A320ceo operators in the United States and China sustain replacement demand through scheduled heavy maintenance intervals.
- Frise Ailerons:Offset hinge geometry creates differential drag to counter adverse yaw without requiring coordinated rudder input. Turboprop operators in Canada and Scandinavia specify these for short-field operations where pilot workload reduction justifies modest weight penalties.
- Differential Ailerons:Asymmetric travel limits generate self-correcting yaw moments through purely mechanical means.
- Slotted Ailerons:Deployed gap seals maintain boundary layer attachment at high deflection angles.
- Others:Morphing and segmented architectures remain experimental.
Conventional ailerons retain volume leadership; slotted configurations hold the steepest expansion curve.
Material:
Cost tiers separate legacy metal fabrications from advanced composite systems with embedded sensor pathways.
- Carbon Fiber Composite:Toray T800S and Hexcel IM7 prepreg layups deliver specific stiffness ratios that enable thinner wing sections. Boeing 787 and Airbus A350 production lines in the United States, France, and Japan anchor demand concentration for primary flight control surfaces.
- Aluminum Alloy:7075-T6 and 2024-T3 sheet metal fabrications persist in retrofit markets where damage tolerance certification databases are mature. FAA-mandated corrosion inspections on aging narrowbodies drive recurring replacement schedules for US-based MRO networks.
- Titanium:Ti-6Al-4V hinge fittings and attachment lugs manage concentrated bearing loads.
- Thermoplastic:PEEK and PPS resin systems enable rapid thermoforming for low-rate production.
- Kevlar:Aramid fiber hybrids provide impact resistance for leading-edge applications.
Aluminum alloy retains volume leadership; carbon fiber composite holds the steepest expansion curve.
Application:
Customer type dictates specification rigor, from Part 25 transport category certification to experimental amateur-built exemptions.
- Commercial Aircraft:Transport category platforms subject to FAA Part 25 and EASA CS-25 damage tolerance mandates require extensive fatigue test databases. Airbus A320neo and Boeing 737 MAX production rates in Toulouse and Renton determine aggregate volume for tier-one suppliers.
- Military Aircraft:Survivability specifications include ballistic tolerance and redundant actuation channels. Saab Gripen and Lockheed Martin F-35 programs in Sweden and the United States drive demand for hardened flight control surfaces with enhanced electromagnetic protection.
- Business Jets:Gulfstream and Dassault platforms prioritize weight reduction for range extension.
- Agricultural Planes:Air Tractor and Thrush aircraft operate in corrosive environments requiring frequent replacement.
- Experimental Aircraft:Amateur-built kit planes utilize simplified certification pathways.
Commercial aircraft retain volume leadership; military applications hold the steepest expansion curve.
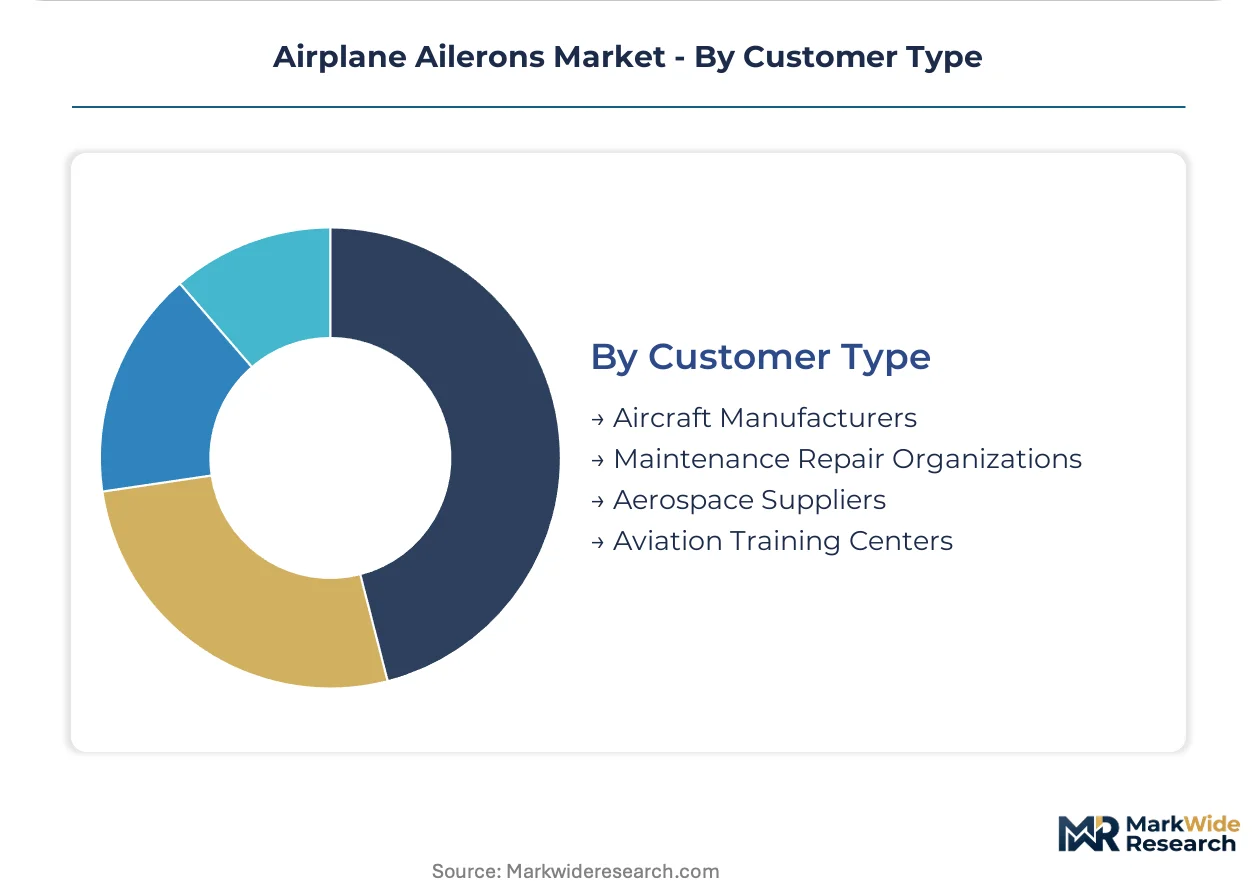
Customer Type:
Procurement patterns concentrate among vertically integrated OEMs, with disintermediation creating direct relationships with specialized fabricators.
- Aircraft Manufacturers:Boeing and Airbus exercise design authority over proprietary actuation interfaces, sourcing ailerons as shipsets through long-term supply agreements. Final assembly lines in Everett, Charleston, Toulouse, and Hamburg determine regional demand distribution for tier-one fabricators.
- Maintenance Repair Organizations:Third-party overhaul facilities in Singapore, Dubai, and Miami hold stock for aging fleet support where airframe OEM lead times exceed operational tolerance. EASA and FAA repair station certifications govern parts acceptance for European and US-registered aircraft.
- Aerospace Suppliers:Tier-two fabricators serve as overflow capacity during production rate surges.
- Aviation Training Centers:Flight schools require replacement surfaces for training aircraft with high cycle accumulation.
Aircraft manufacturers retain volume leadership; MRO channels hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The airplane ailerons market exhibits pronounced trade asymmetry, with the United States running substantial surpluses in finished flight control surfaces while importing specialized carbon fiber prepreg from Japan and titanium forgings from Russia. European and Asian manufacturing clusters consume American-designed shipsets while building indigenous MRO capabilities.
United States
Boeing's final assembly lines in Everett and Charleston anchor North American demand for composite aileron shipsets. FAA Part 25 certification requirements under recent amendments tighten damage tolerance documentation for primary control surfaces. Wichita's aerostructure cluster hosts Spirit AeroSystems fabrication facilities serving narrowbody programs.
Japan
Toray Industries and Mitsubishi Chemical supply aerospace-grade carbon fiber prepreg to global aileron fabricators under METI industrial guidance. JIS standards govern material qualification for flight control surfaces on domestically registered aircraft. Nagoya's aerospace corridor concentrates ShinMaywa Industries production for regional jet platforms.
France
Airbus final assembly in Toulouse drives procurement of electromechanically actuated ailerons for A320neo and A350 programs. EASA CS-25 Amendment 25 mandates accelerated replacement schedules for aging aluminum control surfaces. The Occitanie region hosts specialized composite repair stations serving European MRO networks.
Sweden
Saab AB's Gripen fighter program sustains demand for military-grade flight control surfaces with enhanced survivability specifications. The Swedish Defence Materiel Administration imposes redundant actuation channel requirements for combat aircraft. Linköping's aerospace cluster concentrates hardened aileron development and electromagnetic protection testing.
United Arab Emirates
Dubai and Abu Dhabi MRO facilities build capacity for flight control surface overhaul serving Middle Eastern carrier fleets. GCAA regulations align with EASA standards for composite repair station certification. Jebel Ali's aviation free zone attracts tier-two fabricators establishing regional distribution hubs.
Airplane Ailerons Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated airframe OEMs and specialized tier-one fabricators serving overflow capacity. Boeing exercises design authority through captive supply arrangements while Spirit AeroSystems anchors high-volume composite production. Three archetypes dominate: proprietary actuation specialists, composite fabrication scale players, and military survivability engineers. Competitive moves concentrate on strategic partnerships for electromechanical integration and geographic expansion into Mercosur trade zones.
Among defense-oriented specialists, Saab AB exemplifies the hardened flight control surface archetype through its Gripen program heritage. Boeing and Spirit AeroSystems occupy positions on the commercial OEM-integrated tier, with the latter representing outsourced composite fabrication at production scale. Turkish Aerospace Industries and Strata Manufacturing sit within emerging regional supply base development, reflecting geographic diversification beyond traditional aerospace clusters.
| Leading Market Players |
|---|
| Saab AB |
| Sealand Aviation Ltd |
| ShinMaywa Industries |
| Strata Manufacturing |
| Turkish Aerospace Industries |
| Asian Composites Manufacturing |
| LAM Aviation |
| Boeing |
| Spirit AeroSystems |
| Others |
Pricing and Supply Chain Analysis
Wichita's aerostructure cluster anchors North American composite aileron fabrication capacity, concentrating supply-side leverage among tier-one fabricators serving Boeing's narrowbody programs. This geographic concentration amplifies pricing power for carbon fiber shipsets while forcing downstream MRO channels to absorb premium markups on FAA-certified replacement surfaces.
Pricing Analysis
Current-generation electromechanical actuation systems command substantial premiums over legacy hydraulic architectures, with next-generation morphing concepts still in pre-certification pricing. Three-tier pricing structure across premium composite shipsets, standard aluminum retrofits, and economy-grade training aircraft surfaces separates OEM procurement from aftermarket channels. Cost compression in standard-tier aluminum fabrications is intensifying because IndiGo and Air India fleet expansion programs are squeezing MRO margin structures. Low-cost carriers in Southeast Asia exhibit highest price sensitivity through component-level unbundling, while defense integrators remain least sensitive due to survivability specification mandates.
Supply Chain Analysis
ITAR and EAR export controls restrict electromechanical actuation technology flows to non-allied aerospace programs, fragmenting supplier access across geopolitical boundaries. Manufacturing gravity centers on the United States, Japan, and France for carbon fiber prepreg and finished flight control surfaces. Raw material dependencies draw from Toray T800S and Hexcel IM7 carbon fiber systems, titanium Ti-6Al-4V hinge forgings, and aerospace-grade resin matrices. Single-source vulnerability concentrates in Russian titanium forging supply for high-load attachment fittings. Distribution runs through tier-one fabricator shipset agreements with Boeing and Airbus, supplemented by MRO channel stock positions in Singapore, Dubai, and Miami.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airplane aileron procurement sits in early-cycle expansion as fly-by-wire proliferation across next-generation narrowbody and widebody platforms accelerates electromechanical actuation penetration. Fleet modernization mandates from EASA CS-25 Amendment 25 compound replacement demand for aging aluminum surfaces.
For Market Incumbents: Insulate proprietary actuation architectures through backward integration into sensor fusion electronics and embedded software stacks. Captive supply of electromechanical torque tubes mitigates margin erosion from tier-two fabricator disintermediation. Expand FAA Part 21 certification capacity in Wichita and Charleston to capture derivative design volume from Boeing rate increases. For New Entrants and Emerging Players: Pursue Mercosur trade zone localization requirements for Embraer E2 program supplier qualification, where composite fabrication capacity gaps create white-space openings. Urban air mobility eVTOL developers represent the most penetrable segment given morphing aileron specification fluidity and absence of entrenched incumbents. Lead with digital thread certification capabilities to compress FAA compliance timelines for derivative designs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among MRO-focused fabricators with EASA and FAA repair station certifications, where aging fleet inspections generate predictable replacement schedules. Long-term viability favors suppliers with demonstrated damage tolerance databases for composite control surfaces and established relationships with airline technical procurement teams. Watch for inflection signals in electromechanical reliability database maturation as hybrid actuation mean-time-between-failure data reaches certification thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Actuation Integration | Embedded sensor architectures expand addressable content per shipset for Boeing 737 MAX and Airbus A320neo programs. |
| Digital Thread Certification Investment | Model-based systems engineering accelerates FAA Part 21 compliance for derivative aileron designs. |
| MRO Channel Capacity Expansion | Singapore and Dubai facilities capture recurring replacement demand from corrosion inspections on aging narrowbodies. |
| Morphing Aileron R&D Partnership | eVTOL developer collaborations establish intellectual property positions in boundary-layer modulation architectures. |
| Composite Repair Technician Pipeline | Boeing and Airbus-approved scarf repair certification addresses technician scarcity constraining European MRO throughput. |
Research Methodology
The analysis maps conventional, Frise, differential, and slotted aileron architectures, each validated through procurement directors at tier-one fabricators, airline technical fleet managers, MRO facility operations heads, and regulatory certification specialists. Primary interviews with Spirit AeroSystems production planners and Saab AB survivability engineers combined with secondary validation from FAA airworthiness directives, EASA CS-25 amendment filings, Toray Industries carbon fiber supply disclosures, and Boeing supplier conference presentations. Bottom-up shipset volume estimates triangulated against top-down fleet projection models from aviation lessor databases.
Assumption sets held constant include Boeing and Airbus narrowbody production rate trajectories, EASA damage tolerance mandate enforcement timelines, and carbon fiber prepreg supply elasticity from Japanese chemical processors. Segmentation dimensions modeled span product type, material grade, application category, and customer channel across the projection horizon. CAGRs derived from production rate forecasts, fleet age distributions, and regulatory replacement schedule accelerations. Industry-specific inputs incorporated electromechanical actuation reliability maturation curves and composite repair technician training pipeline capacity.
Macroeconomic conditions sit as an overlay; deviation in jet fuel price volatility, airline bankruptcy frequencies, or trade tariff regimes would shift the trajectory. Forecasts reflect documented assumptions on certification timeline adherence and supply chain disruption frequency. Material shifts in FAA or EASA regulatory stringency for composite damage tolerance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Sailplane Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Australia Aviation Market
Aircraft
Global Helicopter Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
Aircraft Jack Market
Aircraft
North America Aviation Market
Aircraft
Aircraft Ailerons Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Aircraft Sequencing System Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
Aircraft Window Frame Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Global Aircraft Towbars Market