
 Aero Wing Market | 2026-2036
Aero Wing Market Size, Share, and Industry Trends Forecast 2026-2036
Aero Wing Market Analysis
Carbon fiber reinforced polymer is hardening its cost-position against aluminum alloys in next-generation wing programs. Spirit AeroSystems leverages its position as a tier-one aerostructures supplier with dedicated composite wing facilities in multiple geographies. Airbus sustains vertical integration through proprietary wing design centers that feed its final assembly lines. Mitsubishi Heavy Industries anchors regional jet wing production with advanced automated fiber placement capabilities.
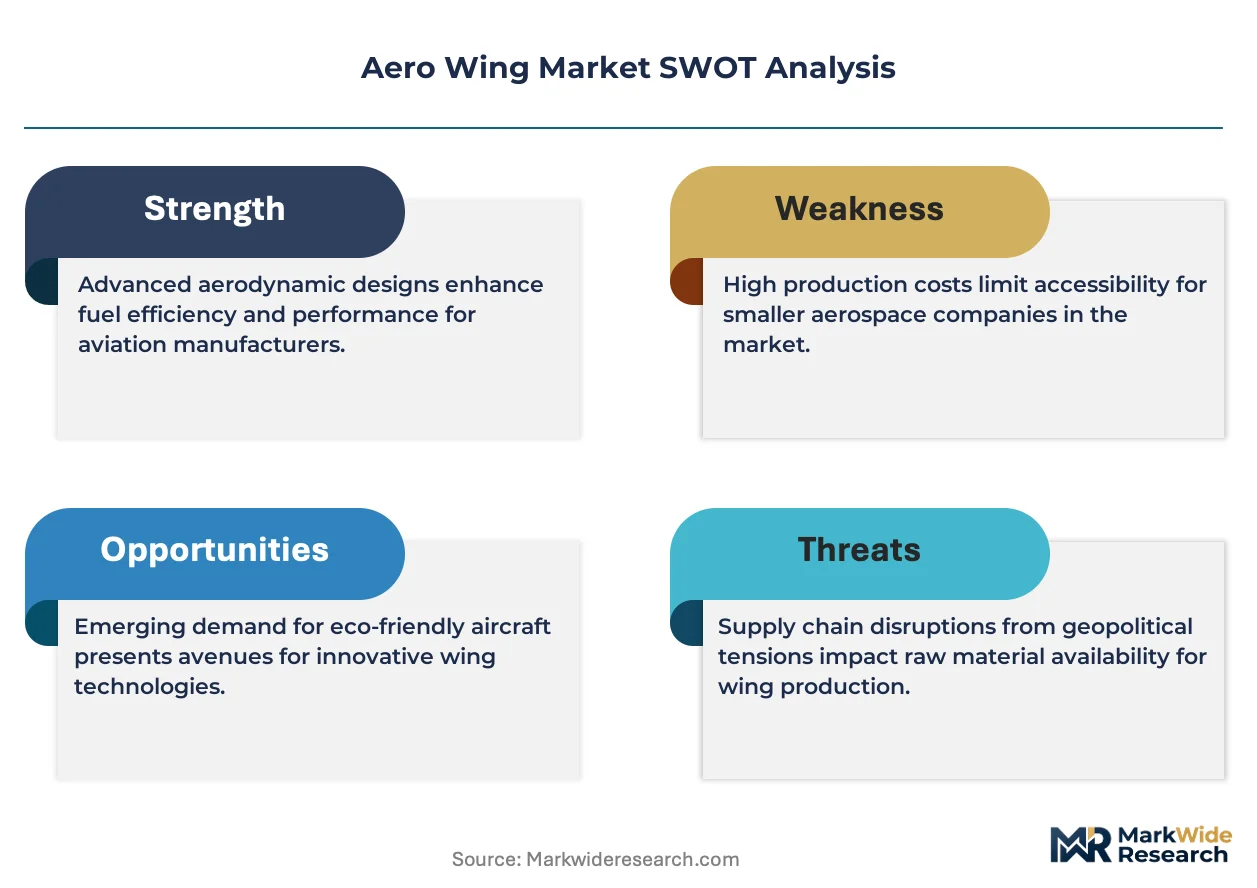
An aero wing is a primary lifting surface comprising spars, ribs, skins, and control surfaces engineered to generate aerodynamic force while managing bending, torsional, and fatigue loads across flight envelopes; modern examples span 35-40 meter semi-span lengths on single-aisle platforms and integrate morphing trailing-edge devices for load alleviation. Fixed wings dominate commercial value pools given their scale in narrowbody and widebody programs, while composite materials capture expanding share as out-of-autoclave processing matures and recurring cost curves flatten. Civil aviation applications command the largest absolute volume, though military aviation segments sustain premium pricing through low-rate initial production and stealth-compatible surface treatments.
FAA damage tolerance requirements under Part 25 and EASA CS-25 airworthiness codes mandate full-scale fatigue testing and discrete source damage assessments that extend development timelines and certification costs. The EU Green Deal emissions trading framework and ICAO carbon offsetting standards are reshaping wing design priorities toward laminar flow and induced drag reduction. Stakeholders must weigh composite recycling obligations against performance gains as regulatory pressure on end-of-life aerostructures intensifies.
Market Dynamics
Composite material substitution is compressing design cycles and redrawing supplier power maps across commercial aviation wing programs. Automated fiber placement and out-of-autoclave curing are collapsing recurring cost premiums against aluminum, forcing tier-one aerostructures suppliers to reposition capital toward resin transfer molding and robotic assembly lines.
Growth Catalysts
- FAA Part 25 Damage Tolerance Mandates:Fatigue testing requirements are accelerating wing platform refreshes as airlines retire older narrowbody fleets. New certification standards create replacement demand for modern damage-tolerant designs.
- Asia-Pacific Fleet Expansion:Chinese, Vietnamese, and Indonesian carriers are placing multi-year orders for next-generation single-aisle aircraft. Domestic route density growth requires expanded wing production capacity.
- Thermoplastic Resin Maturation:Welding-compatible thermoplastic composites enable faster assembly sequences and reduced fastener counts. Wing manufacturers are qualifying these materials for primary load-bearing structures.
Market Restraints
- Carbon Fiber Supply Concentration:Precursor and tow production clusters in Japan and the United States create geographic vulnerability for European wing fabricators. Single-source dependencies amplify price volatility risk.
- EASA CS-25 Certification Burden:Full-scale fatigue test protocols and discrete source damage assessments extend development timelines. Small-tier suppliers lack capital reserves to sustain multi-year certification programs.
- Aluminum-Lithium Alloy Competition:Third-generation Al-Li alloys retain cost advantages for lower-wing applications and repair scenarios. Composite penetration faces substitution pressure in cost-sensitive program variants.
Strategic Opportunities
- Urban Air Mobility Wing Architectures:Distributed electric propulsion requires novel high-aspect-ratio wing designs with integrated motor mounts. Startups in Germany and California are soliciting custom composite wing development partnerships.
- EU Green Deal Emissions Trading:Carbon pricing mechanisms reward laminar flow wing designs that reduce induced drag. European OEMs are prioritizing natural laminar flow research for next-generation platforms.
- Sustainable Aviation Fuel Compatibility:Wing-integrated fuel systems must accommodate higher aromatic content and thermal properties of SAF blends. Retrofit and new-build fuel system engineering services are expanding.
Industry Challenges
- Composite Repair Technician Scarcity:Airlines and MRO providers face shortages of inspectors qualified to EASA and FAA composite damage assessment standards. Training pipeline capacity lags fleet composite content growth.
- Tooling Capital Intensity:Wing mandrels and automated fiber placement heads require eight-figure capital commitments with decade-long depreciation horizons. Mid-tier suppliers struggle to finance program-dedicated equipment.
- End-of-Life Recycling Obligations:Thermoset composite wing structures lack economically viable reclamation pathways. Regulatory pressure on aerostructure landfill diversion is intensifying across European jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aero Wing Market |
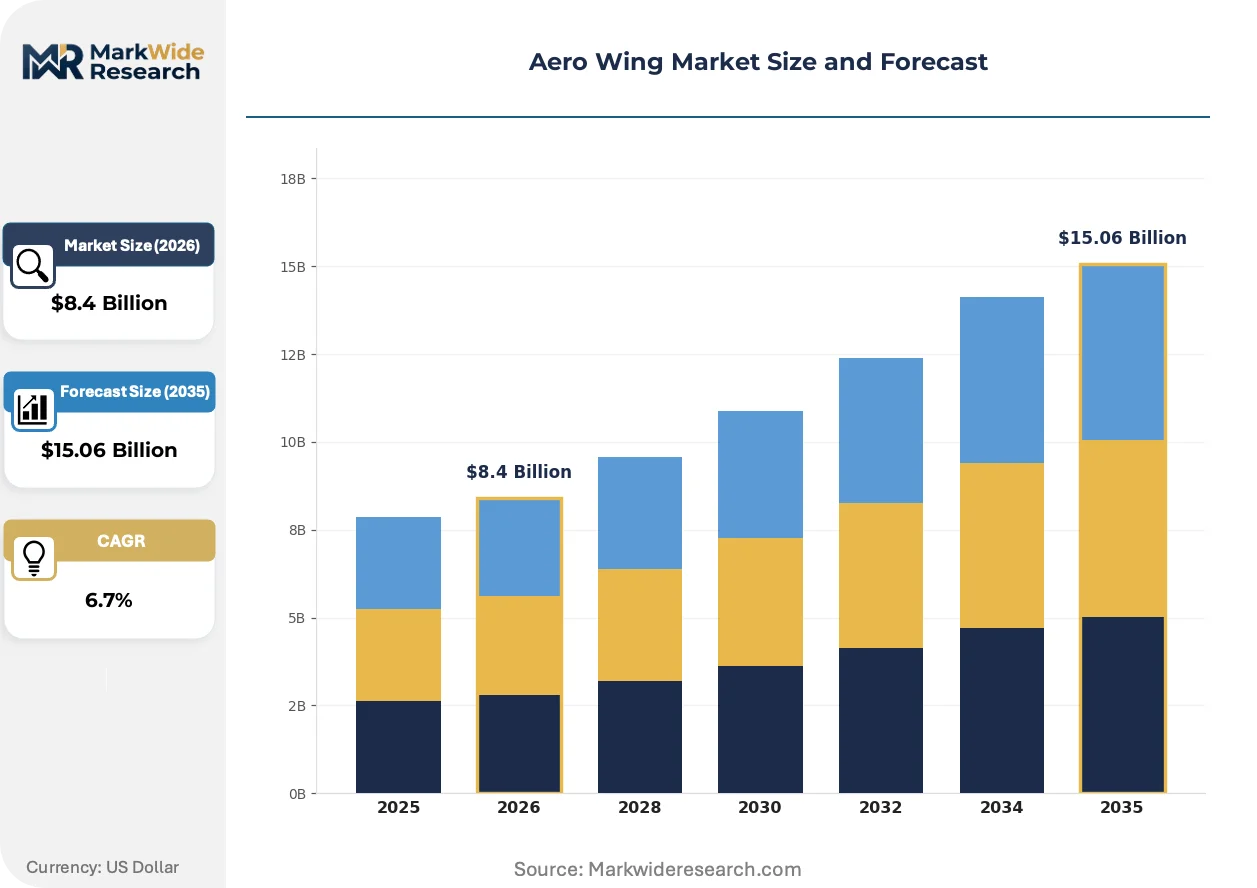
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Wings, Rotary Wings, Ultralight Wings, Gliders Material: Composite Materials, Aluminum Alloys, Steel Alloys, Carbon Fiber Application: Civil Aviation, Military Aviation, Research and Development, Recreational Use End User: Government Agencies, Private Corporations, Research Institutions, Hobbyists |
| Companies Covered | Spirit AeroSystems, GKN Aerospace Services Limited, Airbus, The Boeing Company, Lockheed Martin, Mitsubishi Heavy Industries, Northrop Grumman, RUAG Group, FACC AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aero Wing Market Emerging Trajectories
Digital thread integration and generative design algorithms are collapsing the traditional handoff between aerodynamic optimization and structural manufacturability. Wing engineering workflows now iterate across physics-based simulation and automated production constraints in unified platforms.
Out-of-autoclave thermoset prepregs are rewriting the capital efficiency calculus for large composite wing structures. Airbus and Boeing derivative programs are adopting these materials for trailing-edge components and control surfaces. The technology is compressing autoclave bottlenecks and enabling distributed manufacturing footprints closer to final assembly lines.
EASA's evolving CS-25 guidance on composite damage tolerance and repair is tightening documentation requirements for bonded joints and bolted repairs. European wing suppliers are investing in non-destructive inspection automation to sustain certification compliance. The regulation is most acutely affecting legacy platform life-extension programs where original design data archives are incomplete.
Airline technical procurement teams are consolidating supplier relationships around full-wing-system integrators rather than discrete component vendors. Long-term performance-based contracts with availability guarantees are displacing traditional unit-price purchase agreements. This consolidation is most visible among low-cost carriers in Southeast Asia seeking to minimize spare part complexity across narrowbody fleets.
Aero Wing Market Segmentation
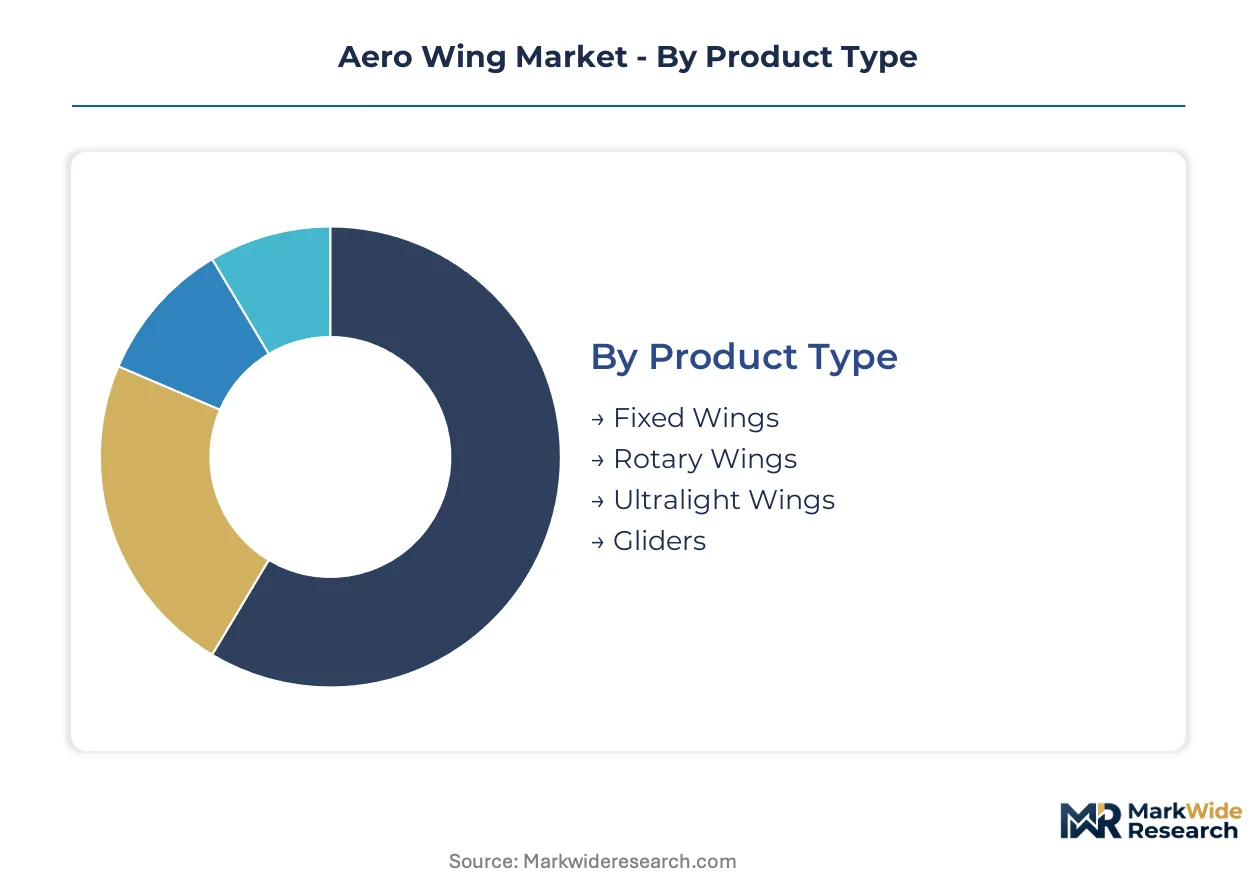
Wing architecture varies dramatically across flight regimes, from high-aspect-ratio fixed platforms to autorotating rotary systems. Material selection and end-use certification requirements create distinct procurement channels with diverging margin structures and technical standards.
Product Type:
Integration depth spans standalone lifting surfaces through fully embedded propulsion-wing systems across aviation platforms.
- Fixed Wings:Semi-monocoque structures with integral fuel tanks and control surfaces dominate commercial narrowbody and widebody programs. Airlines in China and Vietnam are expanding fleet orders for next-generation single-aisle aircraft with advanced laminar flow profiles.
- Rotary Wings:Main and tail rotor blade systems with composite spar construction serve military and civil vertical lift applications. Demand concentrates in defense procurement programs requiring damage-tolerant designs under FAA Part 27 and EASA CS-27 certification.
- Ultralight Wings:Fabric-covered aluminum tube structures prioritize weight minimization over aerodynamic efficiency.
- Gliders:High-aspect-ratio composite wings optimized for thermal soaring performance in recreational and competition segments.
Volume placements concentrate in Fixed Wings; the faster expansion belongs to Rotary Wings.
Material:
Cost tier stratification separates premium composite systems from commodity metal alternatives with diverging capital intensity.
- Composite Materials:Carbon fiber reinforced polymer systems with thermoset or thermoplastic matrices enable weight reduction and corrosion immunity. Automated fiber placement adoption in Japan and the United States is flattening recurring cost curves against aluminum.
- Aluminum Alloys:Third-generation aluminum-lithium sheet and extrusion products retain cost advantages for lower-wing applications and repair scenarios. Boeing and Airbus derivative programs specify Al-Li for cost-sensitive trailing-edge components.
- Steel Alloys:High-strength precipitation-hardened grades serve landing gear attachment fittings and hinge brackets.
- Carbon Fiber:PAN-based and pitch-based fiber tows with tailored modulus properties anchor primary structural applications.
Revenue concentration sits with Composite Materials; Aluminum Alloys maintain the broadest installed base.
Application:
Customer maturity separates regulated commercial aviation from discretionary recreational procurement with fundamentally different sales cycles.
- Civil Aviation:Transport category aircraft under FAA Part 25 and EASA CS-25 drive the largest absolute wing production volumes. Chinese carriers are scaling COMAC C919 integration into domestic route networks.
- Military Aviation:Stealth-compatible surface treatments and low-rate initial production sustain premium pricing for fighter and transport wing programs. Defense procurement in Germany and France prioritizes European supply chain sourcing.
- Research and Development:Experimental platforms for laminar flow and morphing structure validation.
- Recreational Use:Light sport and experimental amateur-built aircraft with simplified certification pathways.
Production scale favors Civil Aviation; Military Aviation commands the highest unit margins.
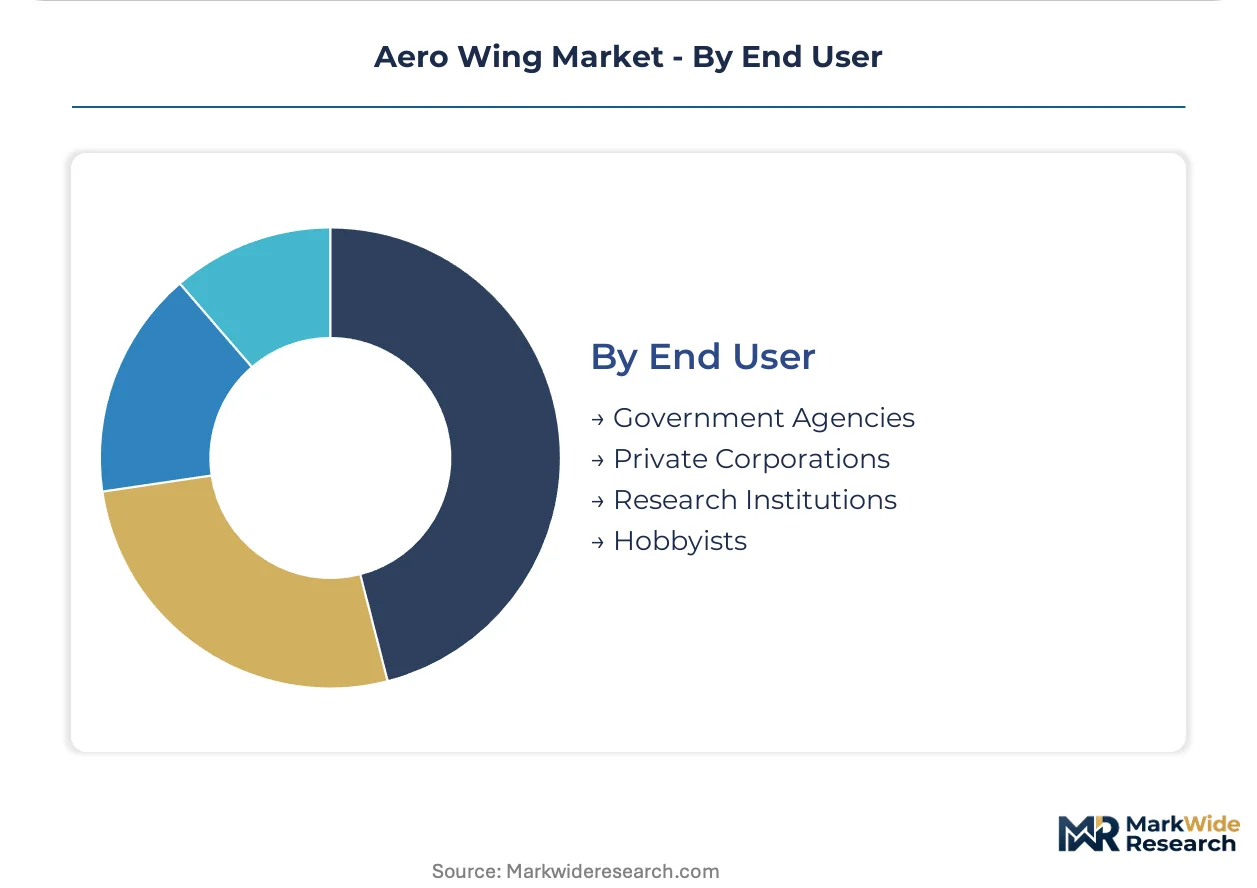
End User:
Procurement authority separates sovereign defense acquisition from decentralized private fleet management with diverging contract structures.
- Government Agencies:Military and coast guard operators specify damage-tolerant designs with multi-decade support obligations. FAA and EASA certification mandates for full-scale fatigue testing extend development timelines for agency-funded programs.
- Private Corporations:Airlines and cargo operators negotiate performance-based contracts with availability guarantees. Low-cost carriers in Indonesia consolidate supplier relationships around full-wing-system integrators.
- Research Institutions:Universities and national laboratories commission custom wing geometries for aerodynamic studies.
- Hobbyists:Individual builders and flying clubs source kit components and raw materials for amateur construction.
Contract value aggregates with Government Agencies; Private Corporations drive recurring aftermarket demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese carriers are scaling COMAC C919 integration into domestic route networks, concentrating procurement demand for narrowbody wing systems. Airlines in Vietnam and Indonesia are expanding order books for next-generation single-aisle programs. Certification mandates from FAA and EASA are reshaping supplier qualification requirements across manufacturing geographies.
United States
Spirit AeroSystems operates dedicated composite wing facilities serving Boeing commercial programs. FAA Part 25 damage tolerance mandates accelerate design refresh cycles for aging narrowbody fleets. Wichita, Kansas anchors tier-one aerostructures production with automated fiber placement capabilities.
China
COMAC scales C919 production to meet domestic airline fleet expansion targets. MIIT industrial policy prioritizes composite materials substitution in civil aviation programs. Shanghai and Xi'an concentrate wing manufacturing infrastructure within the Yangtze River Delta cluster.
Germany
Airbus sustains proprietary wing design centers feeding European final assembly lines. EU Green Deal emissions trading frameworks reward laminar flow wing configurations. Hamburg and Bremen host advanced aerostructures engineering for A320 family programs.
Japan
Mitsubishi Heavy Industries anchors regional jet wing production with automated fiber placement systems. METI supports carbon fiber precursor supply chain resilience for aerospace applications. Nagoya concentrates composite manufacturing infrastructure serving domestic and export programs.
United Kingdom
GKN Aerospace Services operates wing component fabrication for Airbus and Boeing platforms. EASA CS-25 certification requirements extend development timelines for new wing architectures. Bristol and Filton sustain heritage aerostructures engineering clusters with composite repair capabilities.
Aero Wing Market Vendor Landscape
Capacity expansion dominates the current landscape as tier-one suppliers reposition capital toward resin transfer molding and robotic assembly lines. The vendor base concentrates around full-wing-system integrators rather than discrete component vendors. Three archetypes define competitive positioning: OEM-captive fabricators, independent tier-one aerostructures suppliers, and composite materials specialists. Strategic partnerships and geographic expansion represent the dominant competitive moves as suppliers establish distributed manufacturing footprints closer to final assembly lines.
Among independent tier-one suppliers, Spirit AeroSystems exemplifies the scale-driven archetype with multi-site composite wing facilities. GKN Aerospace Services Limited and Mitsubishi Heavy Industries occupy positions within the technology-specialist tier, anchoring regional production clusters in Europe and Asia respectively. These fabricators represent the consolidation trajectory as airlines consolidate supplier relationships around full-system integrators with availability guarantees.
| Leading Market Players |
|---|
| Spirit AeroSystems |
| GKN Aerospace Services Limited |
| Airbus |
| The Boeing Company |
| Lockheed Martin |
| Mitsubishi Heavy Industries |
| Northrop Grumman |
| RUAG Group |
| FACC AG |
| Others |
Supply Flow & Price Mechanics
Carbon fiber precursor costs cascade through three pricing tiers as PAN-based tow moves from Japanese and U.S. chemical plants to wing fabricators in China and Germany. Raw material concentration at the precursor stage amplifies pricing power for upstream suppliers while compressing margins for tier-two composite processors serving regional jet programs.
Pricing Analysis
Volume placements concentrate in fixed-wing narrowbody programs with thin margins, while military rotary-wing systems sustain premium pricing through stealth-compatible surface treatments and low-rate production economics. Three-tier pricing structure separates FAA-certified primary structures from EASA-compliant derivatives and uncertified aftermarket components. Pricing pressure stems from COMAC's domestic supplier qualification mandates in China, which force Western tier-one suppliers to absorb certification costs. Low-cost carriers in Southeast Asia exhibit the highest price sensitivity, bundling wing system procurement with long-term maintenance contracts.
Supply Chain Analysis
Single-source vulnerability sits with Toray and Hexcel precursor production clustered in Japan and the United States, exposing European wing fabricators to logistics disruption and currency fluctuation. Automated fiber placement heads and out-of-autoclave curing systems draw from German and Japanese precision equipment suppliers. Carbon fiber tow, epoxy resin systems, and titanium fasteners constitute the critical input trinity. Tariff exposure on aerospace-grade materials between major trading blocs threatens cost predictability for multi-site wing programs. Distribution runs through OEM-captive fabrication facilities and independent tier-one aerostructures suppliers with dedicated final assembly line proximity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autoclave capacity scarcity at tier-one composite facilities props pricing for qualified wing fabricators, creating a supply-constrained environment where certification backlog determines market access.
For Market Incumbents: Extend backward integration into carbon fiber precursor supply through offtake agreements with Japanese chemical producers. Secure dedicated autoclave capacity in the Yangtze River Delta to defend position against COMAC's domestic supplier consolidation. Lock in multi-year performance-based contracts with Indonesian low-cost carriers before second-tier competitors qualify alternative wing system integrators. For New Entrants and Emerging Players: Enter via urban air mobility wing architectures where distributed electric propulsion creates demand for novel high-aspect-ratio composite designs. Target German and California startups seeking custom development partnerships for motor-integrated wing structures. Pursue EASA CS-27 certification pathway for light-sport and experimental platforms as the most penetrable regulatory entry point. For Investors and Strategic Acquirers: COMAC C919 production rate acceleration is the leading indicator that Chinese domestic supply chain substitution will displace Western tier-one market share within the narrowbody segment. Position acquisition strategy around composite materials specialists with thermoplastic welding capabilities and established FAA repair station certifications. Watch for Spirit AeroSystems facility utilization rates as the signal of capacity tightness enabling pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Out-of-Autoclave Capacity Expansion | Reduces autoclave bottlenecks at Airbus and Boeing supplier facilities. |
| Thermoplastic Composite Qualification | Enables faster assembly sequences for next-generation wing programs. |
| Regional Repair Station Certification | Captures aftermarket revenue from Asia-Pacific narrowbody fleet expansion. |
| Natural Laminar Flow R&D Partnership | Positions European suppliers for EU Green Deal emissions trading compliance. |
| End-of-Life Recycling Infrastructure | Addresses EASA pressure on thermoset composite landfill diversion mandates. |
Methodological Framework
Trade data from U.S. Census Bureau aerospace exports, MIIT civil aviation production statistics, and EASA certification databases formed the secondary backbone. Primary interviews with tier-one aerostructures procurement directors, composite materials R&D leads, airline fleet planning executives, and FAA certification engineers validated demand assumptions. Bottom-up triangulation across wing program production rates and top-down cross-check against OEM delivery forecasts ensured segmentation consistency.
Bottom-up modeling aggregated individual program volumes across fixed-wing, rotary-wing, and emerging ultralight categories. Segmentation dimensions included material system type, certification tier, end-use application, and geographic production cluster. CAGRs were derived from production ramp schedules and fleet replacement cycles. Forecast inputs incorporated COMAC C919 delivery trajectories, thermoplastic composite qualification timelines, and EASA damage tolerance guidance evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon fiber supply disruption or accelerated SAF blend mandates. Forecasts reflect documented assumptions on fleet retirement rates and certification backlog clearance. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
North America Light and Very Light Jets Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market
Aircraft
Freighter Aircraft Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Air Deflector Market
Aircraft
UK Military Aviation Market
Aircraft
Search and Rescue Aircraft Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
North America Helicopters Market
Aircraft
US Aviation Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Supersonic Jet Market