
 EAS Antennas Market | 2026-2036
EAS Antennas Market Size, Share, and Industry Trends Forecast 2026-2036
EAS Antennas Market Intelligence
China is reconfiguring EAS antenna component supply chains through expanded ferrite and copper coil manufacturing capacity. Checkpoint Systems leverages backward integration into RF subsystem production to sustain margin control across North American retail deployments. Sensormatic Solutions anchors its position through software-integrated antenna platforms that dominate high-frequency EM installations in apparel chains. Nedap N.V. differentiates through RFID-native antenna architectures that compete directly with legacy acousto-magnetic infrastructure.
EAS antennas are electromagnetic detection systems operating at specific radio frequencies, typically incorporating ferrite cores, copper coils, and resonant circuits tuned to detect security tags passing through defined gate zones. These systems generate controlled electromagnetic fields to identify tagged merchandise, with RF systems operating near 8.2 MHz and acousto-magnetic systems utilizing 58 kHz resonant frequencies for detection accuracy. Hard tags retain structural dominance in high-value apparel and electronics due to reusability and mechanical durability, while RFID technology represents the fastest-expanding segment as retailers merge loss prevention with inventory visibility. Soft tags and labels capture volume in grocery and pharmacy settings where disposable attachment suits lower-margin merchandise.
FCC Part 15 regulations govern RF emissions from EAS installations in the United States, while CE marking under the EU Radio Equipment Directive mandates electromagnetic compatibility compliance for European deployments. Retailers in both jurisdictions face escalating compliance obligations as regulators tighten limits on interference with adjacent wireless systems. Stakeholders must monitor convergence between EAS and RFID standards as inventory-automation requirements reshape antenna procurement specifications.
Market Dynamics
RFID-antenna convergence is compressing procurement cycles as retailers demand unified loss-prevention and inventory-automation infrastructure from single vendors. This technology shift is collapsing the historical separation between EAS detection and supply-chain visibility systems.
Growth Catalysts
- FCC Part 15 tightening:Stricter electromagnetic emission limits in the United States are forcing antenna replacement cycles, accelerating hardware refresh demand among big-box retailers.
- Organized retail crime surge:Loss-prevention departments in apparel and electronics chains are expanding gate deployments to protect high-shrink categories.
- Ferrite core manufacturing:Expanded production capacity in China is stabilizing input costs for resonant circuit components.
Market Restraints
- Copper coil volatility:Electromagnetic component pricing fluctuates with commodity markets, squeezing margin predictability for antenna assemblers.
- Single-source ferrite dependence:Concentrated supply of high-permeability cores in East Asian foundries creates vulnerability to trade policy shifts.
- Acousto-magnetic obsolescence pressure:Legacy 58 kHz infrastructure faces substitution risk as RFID-native platforms capture new installations.
Strategic Opportunities
- Pharmacy and grocery penetration:Disposable soft-tag applications remain underdeployed in food and drug retail relative to apparel.
- EU Radio Equipment Directive alignment:CE marking harmonization is creating cross-border procurement efficiencies for European retail chains.
- RFID-EAS hybrid architectures:Convergence between ultra-high-frequency inventory tracking and traditional detection gates opens unified platform sales.
Industry Challenges
- Electromagnetic compatibility certification:FCC and CE testing timelines extend product launch schedules by six to twelve months.
- Legacy system integration:Retrofitting RFID-native antennas into existing acousto-magnetic gate footprints requires site-specific engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EAS Antennas Market |
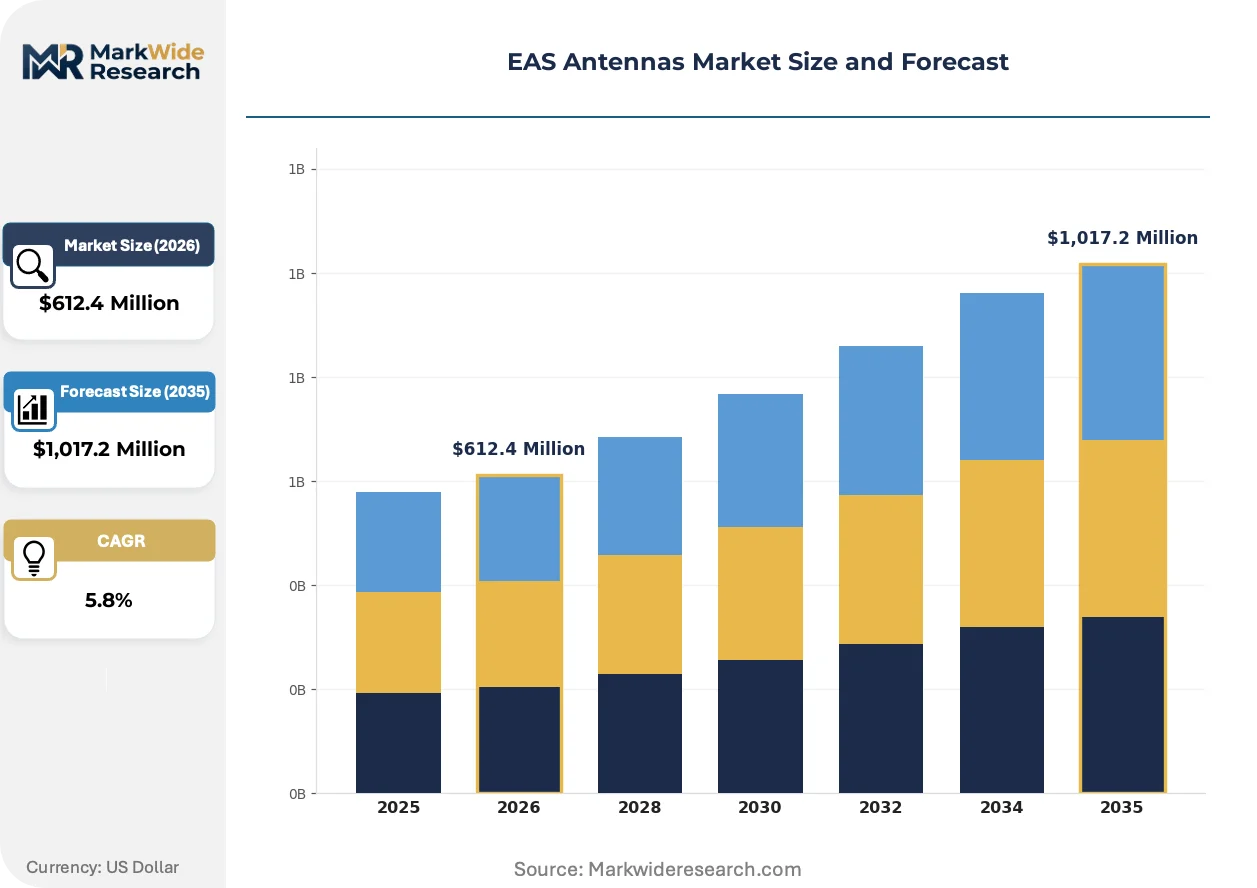
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Tags, Soft Tags, Labels, Cards Technology: RF, EM, RFID, Acousto-Magnetic End User: Retail, Library, Warehouse, Healthcare Installation: In-Store, Mobile, Remote, Industrial |
| Companies Covered | Checkpoint Systems, Sensormatic Solutions, Nedap N.V., Johnson Controls International, Avery Dennison Corporation, CCL Industries, Gunnebo AB, TAG Worldwide Group Limited, Ketec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EAS Antennas Market Strategic Shifts & Innovations
Antenna platforms are evolving from standalone detection hardware into software-defined systems that merge loss prevention with real-time inventory intelligence. This shift is redefining vendor value propositions and procurement evaluation criteria.
RFID-native antenna systems is migrating from pilot deployments in high-frequency apparel chains toward mainstream adoption across mid-market retail. Department stores and specialty chains are accelerating replacement of standalone EAS gates with hybrid platforms. This technology convergence is compressing the addressable market for pure-play acousto-magnetic hardware while expanding total solution contract values.
CE marking under the EU Radio Equipment Directive is tightening electromagnetic compatibility thresholds for gate installations in European retail environments. Manufacturers must redesign coil configurations and shielding to meet revised emission limits. Apparel chains in Germany and France are prioritizing pre-certified antenna platforms to accelerate store rollout schedules.
Buyer consolidation among North American big-box retailers is shifting procurement toward multi-year framework agreements with integrated solution providers. Single-vendor accountability for hardware, software, and maintenance is displacing fragmented component sourcing. This concentration is most visible in United States supercenter chains modernizing loss-prevention infrastructure at scale.
EAS Antennas Market Segmentation
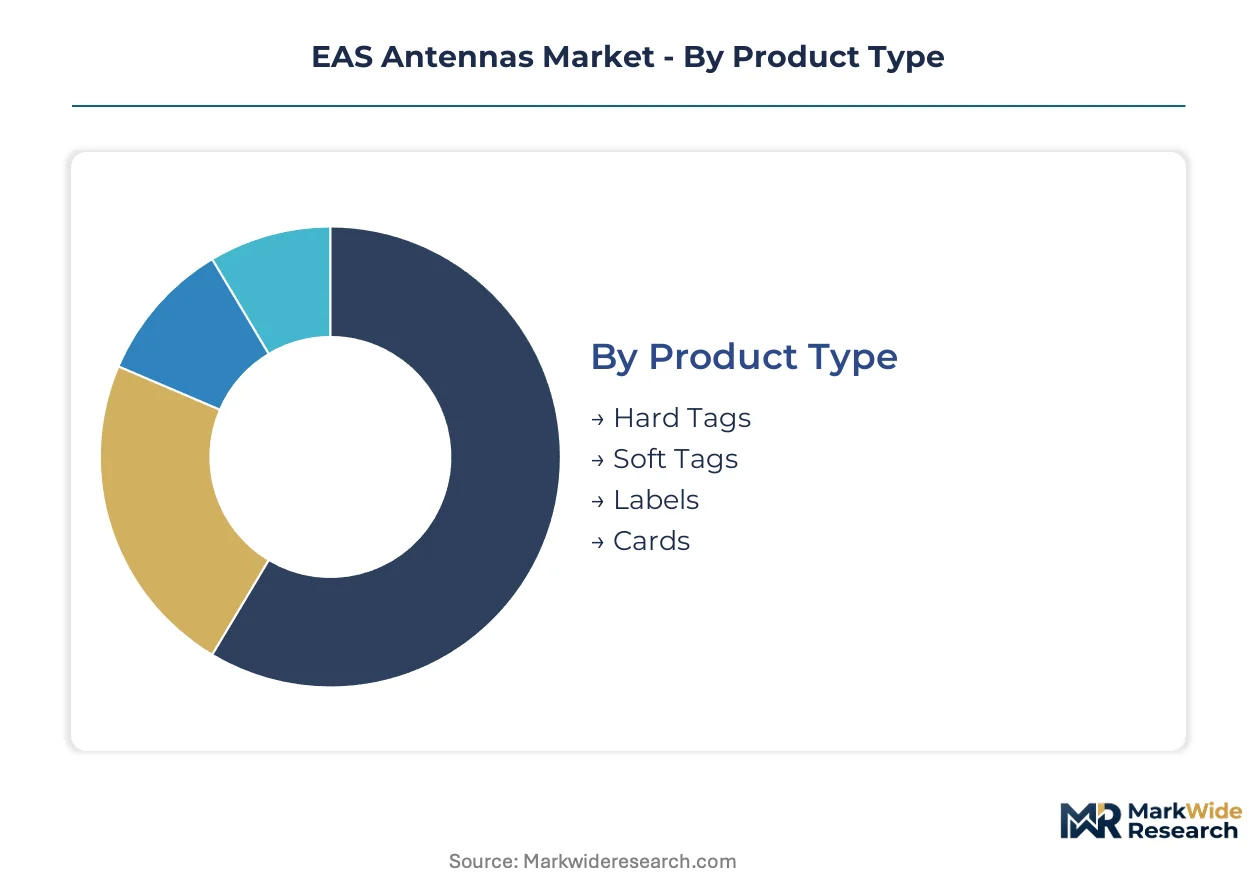
EAS antenna procurement varies sharply across product formats, detection technologies, and deployment environments. Retailers select configurations based on merchandise value, shrink rates, and integration requirements for inventory systems.
Product Type:
Cost tier differentiation separates reusable security hardware from disposable attachment formats across retail categories.
- Hard Tags:Molded plastic housings with ferrite-cored locking mechanisms attach to high-value apparel and electronics through mechanical pins. United States big-box retailers deploy these across denim, outerwear, and consumer electronics departments where organized retail crime concentrates.
- Soft Tags:Flexible disposable labels with embedded resonant circuits suit grocery and pharmacy merchandise where per-unit security cost must stay minimal. German drugstore chains are expanding soft-tag deployments to cosmetics and over-the-counter medications.
- Labels:Adhesive-backed disposable formats integrate EAS functionality into standard product labeling for books, media, and packaged goods.
- Cards:Rigid credential formats serve library and corporate access control applications requiring repeated credential presentation.
Hard tags command the established base. The steepest expansion runs through soft tags.
Technology:
Detection methodology determines field range, interference susceptibility, and compatibility with emerging inventory-automation infrastructure.
- RF:8.2 MHz radio frequency systems generate electromagnetic fields through copper-coil antenna arrays for gate-based detection. United States apparel chains favor RF for its balance of detection range and hardware cost in high-traffic store formats.
- RFID:Ultra-high-frequency platforms merge loss prevention with real-time inventory tracking through unified antenna infrastructure. French department stores are accelerating RFID-native gate replacements to satisfy CSRD supply-chain visibility mandates.
- EM:Electromagnetic strip detection operates at lower frequencies for library and document security applications.
- Acousto-Magnetic:58 kHz resonant frequency systems offer superior detection in metallic environments but face substitution pressure from RFID convergence.
RF installations represent the largest installed base. RFID platforms are climbing the fastest as retailers consolidate vendors.
End User:
Customer type dictates antenna specification, deployment density, and integration complexity with existing operational systems.
- Retail:Apparel, electronics, and general merchandise chains deploy gate arrays at store entrances with centralized monitoring. United States supercenters are modernizing thousands of locations under multi-year framework agreements.
- Warehouse:Distribution centers require wide-field detection for pallet-level monitoring and loading-dock security.
- Library:Public and academic institutions utilize EM-based systems for media and document circulation control.
- Healthcare:Hospitals and pharmacies apply EAS to pharmaceutical inventory and equipment tracking.
Retail absorbs the dominant procurement volume. Healthcare is gaining share fastest as pharmaceutical chains automate dispensing security.
Installation:
Deployment architecture determines power requirements, network connectivity, and maintenance accessibility for antenna systems.
- In-Store:Fixed gate installations at retail entrances require precise electromagnetic field calibration for adjacent wireless coexistence. FCC Part 15 compliance testing extends deployment timelines for United States locations.
- Industrial:Heavy-duty antenna arrays withstand manufacturing and logistics environments with elevated interference and physical stress.
- Mobile:Portable detection units serve temporary retail formats and event-based merchandise protection.
- Remote:Network-connected standalone antennas monitor distributed locations without on-site security staffing.
In-store deployments command the established base. Industrial installations are expanding most quickly through warehouse automation projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 regulations in the United States are tightening electromagnetic emission standards for EAS antenna systems, forcing hardware refresh cycles among big-box retailers and accelerating procurement demand across North America and Europe.
United States
Organized retail crime is driving gate deployment expansion across supercenter and apparel chains. FCC Part 15 compliance testing extends product launch timelines by six to twelve months. Chicago and Dallas retail clusters are modernizing loss-prevention infrastructure under multi-year framework agreements.
Germany
Apparel chains are prioritizing pre-certified antenna platforms to accelerate store rollout schedules. CE marking under the EU Radio Equipment Directive mandates stricter electromagnetic compatibility thresholds for gate installations. The Rhine-Ruhr industrial corridor is consolidating procurement for cross-border retail efficiency.
France
Department stores are accelerating RFID-native gate replacements to satisfy CSRD supply-chain visibility mandates. ANSM and CNIL oversight intersects with retail data governance for inventory-automation systems. Paris retail clusters dominate high-frequency EM installations in luxury apparel.
China
Ferrite and copper coil manufacturing capacity expansion is reconfiguring component supply chains for global antenna assemblers. GB standards and MIIT oversight govern electromagnetic compatibility for domestic deployments. The Yangtze River Delta anchors resonant circuit production for export markets.
United Kingdom
Retail chains are navigating post-Brexit regulatory divergence while maintaining CE marking alignment for EU market access. The Medicines and Healthcare products Regulatory Agency intersects with pharmaceutical retail security applications. London and Southeast England concentrate demand for software-integrated antenna platforms.
EAS Antennas Market Key Industry Players
Integrated solution providers and component specialists split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: hardware-integrated platforms, RFID-native specialists, and legacy acousto-magnetic defenders. Multi-year framework agreements with big-box retailers are displacing fragmented component sourcing. Backward integration into RF subsystem production and software-defined antenna architectures represent the dominant competitive vectors.
Among Netherlands-based specialists, Nedap N.V. exemplifies RFID-native antenna architectures competing with legacy infrastructure. Checkpoint Systems and Sensormatic Solutions anchor the integrated platform tier, representing divergent approaches to loss-prevention and inventory-automation convergence. These three occupy positions across the technology transition from standalone detection to unified visibility systems.
| Leading Market Players |
|---|
| Checkpoint Systems |
| Sensormatic Solutions |
| Nedap N.V. |
| Johnson Controls International |
| Avery Dennison Corporation |
| CCL Industries |
| Gunnebo AB |
| TAG Worldwide Group Limited |
| Ketec Inc. |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta freight corridor channels ferrite core and copper coil shipments from Chinese foundries to antenna assemblers worldwide, with transport cost volatility amplifying price spreads between premium certified systems and standard hardware tiers.
Pricing Analysis
Price differentiation between United States and European deployments runs 15-25 percent, driven by FCC Part 15 compliance testing costs and CE marking certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates software-integrated hybrid platforms from standalone RF gates and legacy acousto-magnetic units. Cost compression in the economy tier is intensifying because of Chinese ferrite oversupply, while big-box retailers show lowest price sensitivity due to multi-year framework contracting.
Supply Chain Analysis
Upstream feedstock concentration in China, South Korea, and Japan anchors global ferrite core and copper coil availability for resonant circuit production. Antenna assembly draws from high-permeability ferrite, oxygen-free copper wire, and epoxy shielding compounds as critical inputs. Single-source vulnerability in East Asian foundries creates exposure to trade policy shifts. Distribution runs through integrated solution providers serving retail chains directly, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
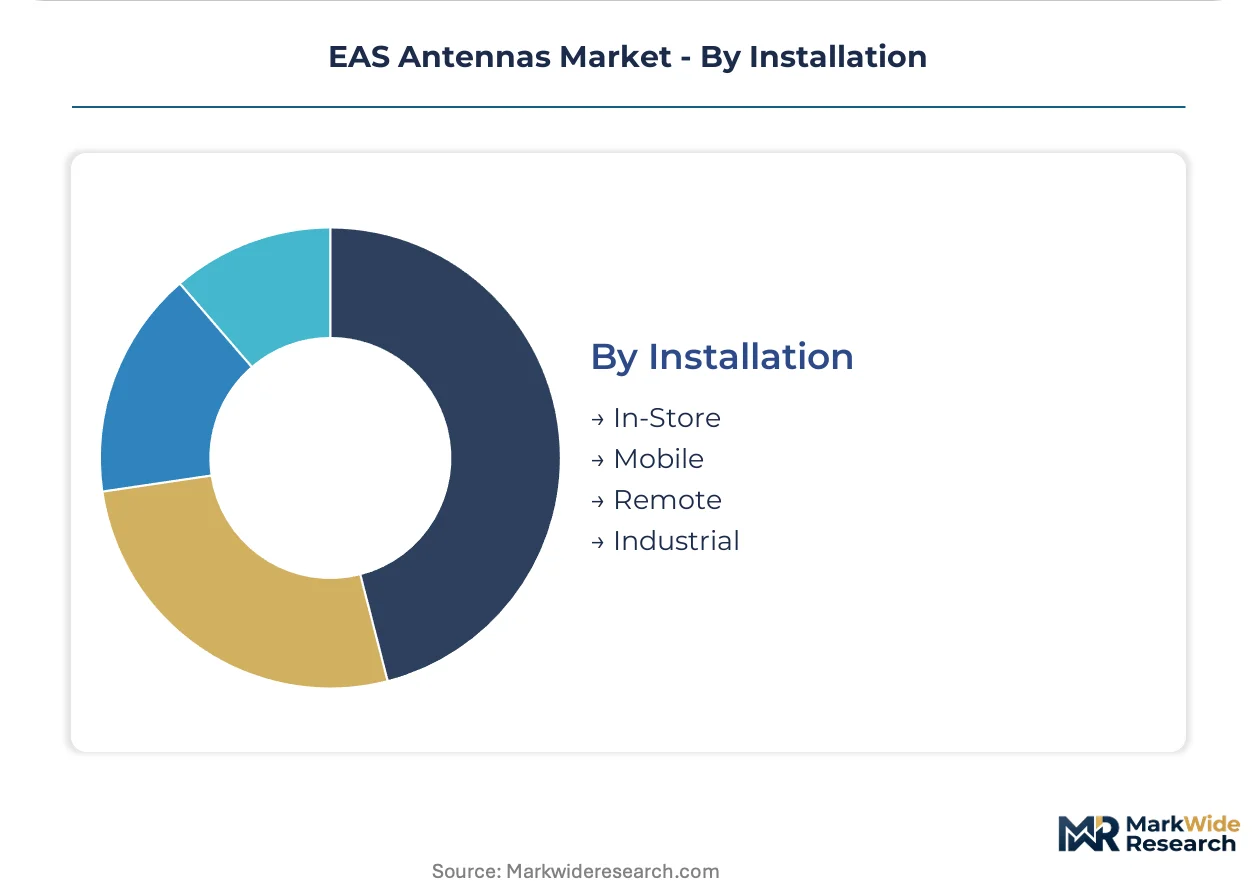
EAS antenna procurement operates as a defensive-moat market where regulatory entrenchment through FCC Part 15 and CE marking certification timelines locks in incumbent positions against rapid substitution.
For Market Incumbents: Build switching-cost moats by embedding software-defined inventory-automation modules into antenna platforms, deepening captive supply of RF subsystems through backward integration into ferrite-cored coil manufacturing, and securing multi-year framework agreements with United States supercenter chains before RFID-native specialists gain procurement traction.
For New Entrants and Emerging Players: German pharmacy and grocery soft-tag deployments represent underpenetrated whitespace where disposable label demand outpaces dedicated vendor coverage. French department stores under CSRD supply-chain visibility mandates offer second entry point through RFID-native hybrid architectures. Lead with pre-certified CE marking packages to compress deployment timelines against entrenched competitors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component-integrated platform providers over pure-play hardware assemblers. Long-term viability hinges on software-recurring revenue attachment rates rather than gate hardware margins. Watch RFID-antenna convergence penetration in mid-market apparel chains as inflection signal for technology substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Core Production | Captive supply of high-permeability components insulates margin from Chinese commodity volatility. |
| RFID-Native Hybrid Platform Launch | Unified loss-prevention and inventory-tracking architecture satisfies CSRD visibility mandates in French retail. |
| Pre-Certified CE Marking Investment | Accelerated European store rollout schedules reduce competitive friction in German apparel procurement. |
| Multi-Year Framework Agreement Expansion | Single-vendor accountability displaces fragmented sourcing in United States big-box modernization programs. |
| Software-Defined Antenna Development | Real-time inventory intelligence modules create recurring revenue streams beyond hardware installation. |
Research Approach
A spread of perspectives from loss-prevention executives at apparel chains, RF subsystem procurement managers, antenna platform engineers, and FCC compliance consultants converged on the working assumptions. Primary fieldwork combined structured interviews with retail technology directors and secondary validation through SEC filings of integrated solution providers, customs records tracking ferrite core trade flows, and FCC equipment authorization databases. Bottom-up antenna deployment counts triangulated against top-down retail capital expenditure disclosures.
Demand-supply balance modeling tracked gate replacement cycles against ferrite foundry capacity expansion across the projection horizon. Segmentation dimensions included detection technology type, product format tier, end-user vertical, and installation architecture. CAGRs derived from hardware refresh velocity curves and RFID convergence adoption rates. Forecast inputs incorporated FCC Part 15 compliance timeline data and CE marking harmonization progress under EU Radio Equipment Directive revisions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by Chinese ferrite specialists or accelerated RFID substitution by apparel chains would shift outcomes. Cross-checking against retail capital expenditure surveys and antenna equipment authorization filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
Aircraft Control Surface Market
Aerospace & Defense
Identification Friend or Foe Systems Market
Aerospace & Defense
ASEAN Satellite-Based Earth Observation Market
Aerospace & Defense
Space Radar Market
Aerospace & Defense
Aircraft Tow Tractors Market
Aerospace & Defense
Sea-Based Remote Weapon Systems Market
Aerospace & Defense
Drone Lens Market
Aerospace & Defense
Digital Glass Military Aircraft Cockpit Systems Market
Aerospace & Defense
Commercial Aircraft Cabin Lighting Market
Aerospace & Defense
Unmanned Systems Market
Aerospace & Defense
Europe Freighter Aircraft Market
Aerospace & Defense
Airship Market
Aerospace & Defense
Europe Military Aircraft Communication Avionics Market
Aerospace & Defense
Vetronics Market
Aerospace & Defense
Military Test Equipment Market
Aerospace & Defense
Asia-Pacific Aerospace Composites Market