
 Europe Inertial Systems Market | 2026-2036
Europe Inertial Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Inertial Systems Market Foresight
The performance gap between fiber-optic inertial measurement units and commodity MEMS accelerometers is broadening. Safran Group leverages its Sagem subsidiary to dominate high-end aerospace and defense gyroscopes with deep French supply chain integration. Bosch Sensortec GmbH competes at volume scale in automotive-grade MEMS, anchoring its position through captive wafer fabrication in Germany. STMicroelectronics differentiates by spanning both tiers with dual-use IMU platforms that serve industrial and consumer crossover applications.
Inertial systems comprise gyroscopes, accelerometers, and magnetometers integrated into IMUs that measure angular rate, linear acceleration, and magnetic field orientation with precision ranging from tactical-grade to navigation-grade specifications. These instruments enable dead-reckoning navigation where GPS signals degrade or jam, serving as the positional backbone for missiles, drones, autonomous vehicles, and offshore platforms. Fiber-optic gyroscopes command the highest precision tier and margin pools in defense and marine navigation, while MEMS technology captures the fastest expansion through automotive ADAS and drone stabilization demand. Ring-laser systems retain niche dominance in strategic-grade ballistic missile guidance where drift tolerances below 0.001 degrees per hour are mandatory.
EU Green Deal decarbonization targets and the EU AI Act are reshaping product certification requirements for autonomous marine and aerial platforms deploying inertial guidance. EASA airworthiness standards and CE marking under the Machinery Directive govern market access for commercial drone and uncrewed surface vehicle manufacturers. The EU Chips Act and national security screening mechanisms under the EU Foreign Subsidies Regulation are tightening control over semiconductor supply chains that feed inertial sensor production. Stakeholders must track how ESA funding allocations and national defense procurement frameworks in France, Germany, and Italy redirect demand toward qualified domestic suppliers versus non-European component sources.
Market Dynamics
Defense procurement frameworks across NATO member states are accelerating adoption of navigation-grade inertial systems for autonomous platforms, while the EU Chips Act simultaneously redirects semiconductor supply chains toward domestic MEMS fabrication capacity.
Growth Catalysts
- EU Chips Act subsidies:Domestic MEMS foundry investments in France and Germany reduce import dependency for inertial sensor wafers. French aerospace clusters leverage these incentives to secure captive supply chains.
- Autonomous marine platforms:Uncrewed surface vessels for offshore energy inspection require navigation-grade IMUs immune to GPS jamming. North Sea wind farm operators drive specification tightening.
- EASA airworthiness certification:Commercial drone manufacturers must integrate dual-redundant inertial systems for beyond-visual-line-of-sight operations. This mandates hardware upgrades across the European uncrewed aerial vehicle fleet.
Market Restraints
- Strategic-grade component concentration:Ring-laser gyroscope production for ballistic missile guidance concentrates in a handful of qualified European defense suppliers. Entry barriers include decade-long qualification timelines.
- Raw material volatility:High-purity silica fiber for fiber-optic gyroscopes faces price instability tied to telecom infrastructure demand cycles. This squeezes margin pools at the precision tier.
- REACH compliance burden:Substance restrictions on piezoelectric materials complicate accelerometer manufacturing. Reformulation costs disproportionately impact mid-tier industrial IMU producers.
Strategic Opportunities
- Poland and Baltic states:NATO eastern flank defense modernization programs lack qualified domestic inertial suppliers. Joint ventures with established French or German manufacturers capture this procurement gap.
- EU AI Act certification pathways:Autonomous vehicle type-approval now requires traceable sensor fusion architectures. Inertial system vendors can bundle IMU hardware with algorithmic compliance documentation.
- MEMS-industrial convergence:Automotive-grade inertial sensors migrate into predictive maintenance for rotating machinery. Bosch Sensortec and STMicroelectronics already serve this crossover with repurposed platforms.
Industry Challenges
- Navigation-grade calibration expertise:Temperature compensation and bias stability testing require specialized technicians. European defense primes poach talent from university photonics programs faster than replacement pipelines fill.
- Dual-use export control complexity:ITAR and EU dual-use regulations create licensing friction for IMU sales to non-NATO customers. Compliance teams must navigate divergent national implementation of harmonized codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Inertial Systems Market |
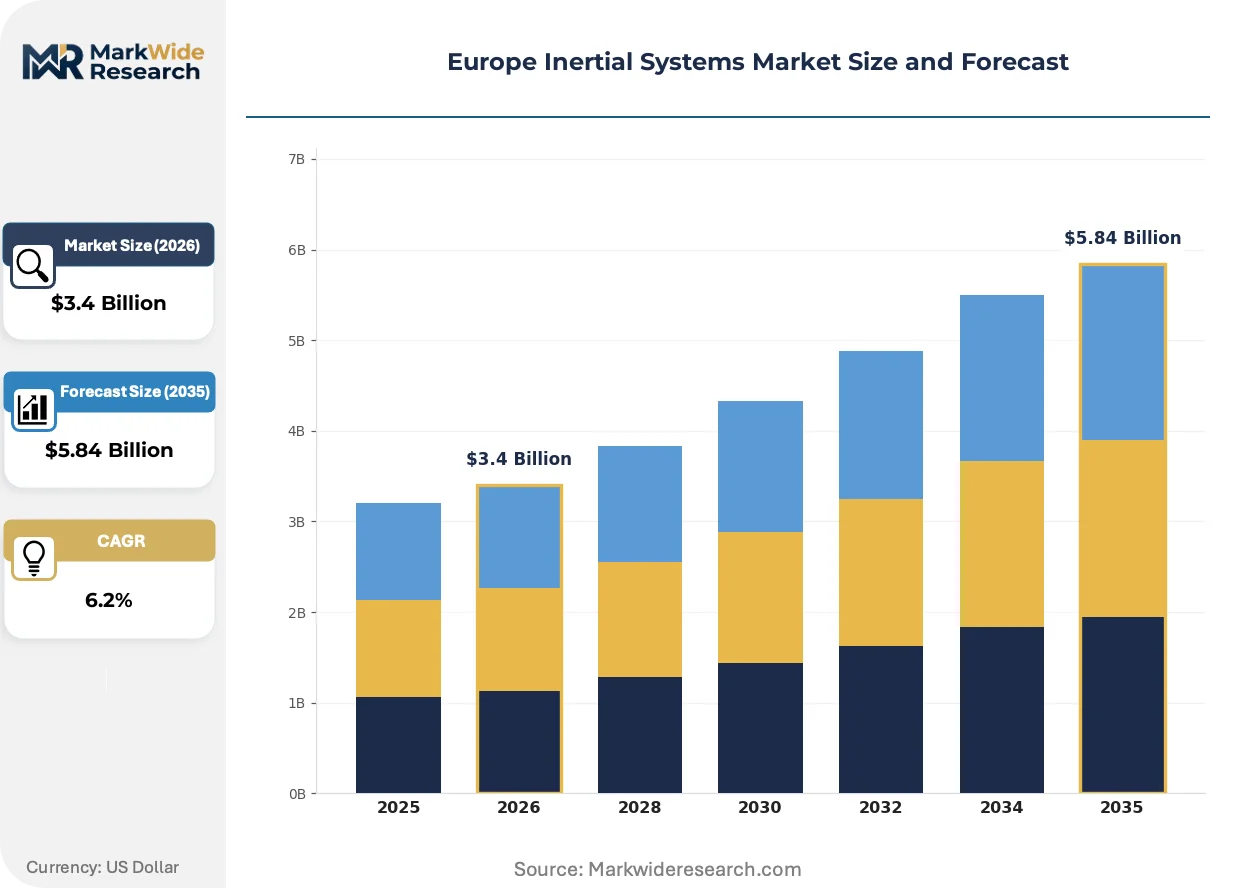
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gyroscopes, Accelerometers, Magnetometers, IMUs Technology: MEMS, Fiber Optic, Ring Laser, Quartz End User: Aerospace, Automotive, Defense, Marine Application: Navigation, Guidance, Stabilization, Motion Tracking |
| Companies Covered | Analog Devices Inc., Safran Group, Honeywell Aerospace Inc., STMicroelectronics, L3Harris Technologies Inc., Northrop Grumman Corporation, Thales Group, Trimble Inc., Bosch Sensortec GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Inertial Systems Market Shifts & Advancements
Silicon photonics integration and AI-driven sensor fusion are compressing the performance gap between tactical-grade MEMS and legacy fiber-optic systems, while regulatory mandates for autonomous platform safety reshape hardware specifications.
Photonic inertial sensors are modularizing around chip-scale integration architectures. Defense contractors in Germany and France now specify IMUs with interchangeable optical subassemblies rather than monolithic designs. This enables field-upgradeable performance tiers without platform recertification, compressing procurement cycles for multi-decade weapon programs.
EU AI Act algorithmic transparency requirements are forcing IMU manufacturers to document sensor fusion decision pathways. EASA certification for commercial drones now mandates interpretable error propagation models. Vendors serving the uncrewed aerial vehicle segment must rebuild software stacks around explainable Kalman filter architectures.
Buyer concentration in European defense procurement is consolidating specification-setting power. France's Direction Générale de l'Armement and Germany's BAAINBw now coordinate IMU requirements through the Permanent Structured Cooperation framework. This reduces vendor fragmentation but extends qualification timelines as dual-national approval gates multiply.
Europe Inertial Systems Market Segmentation
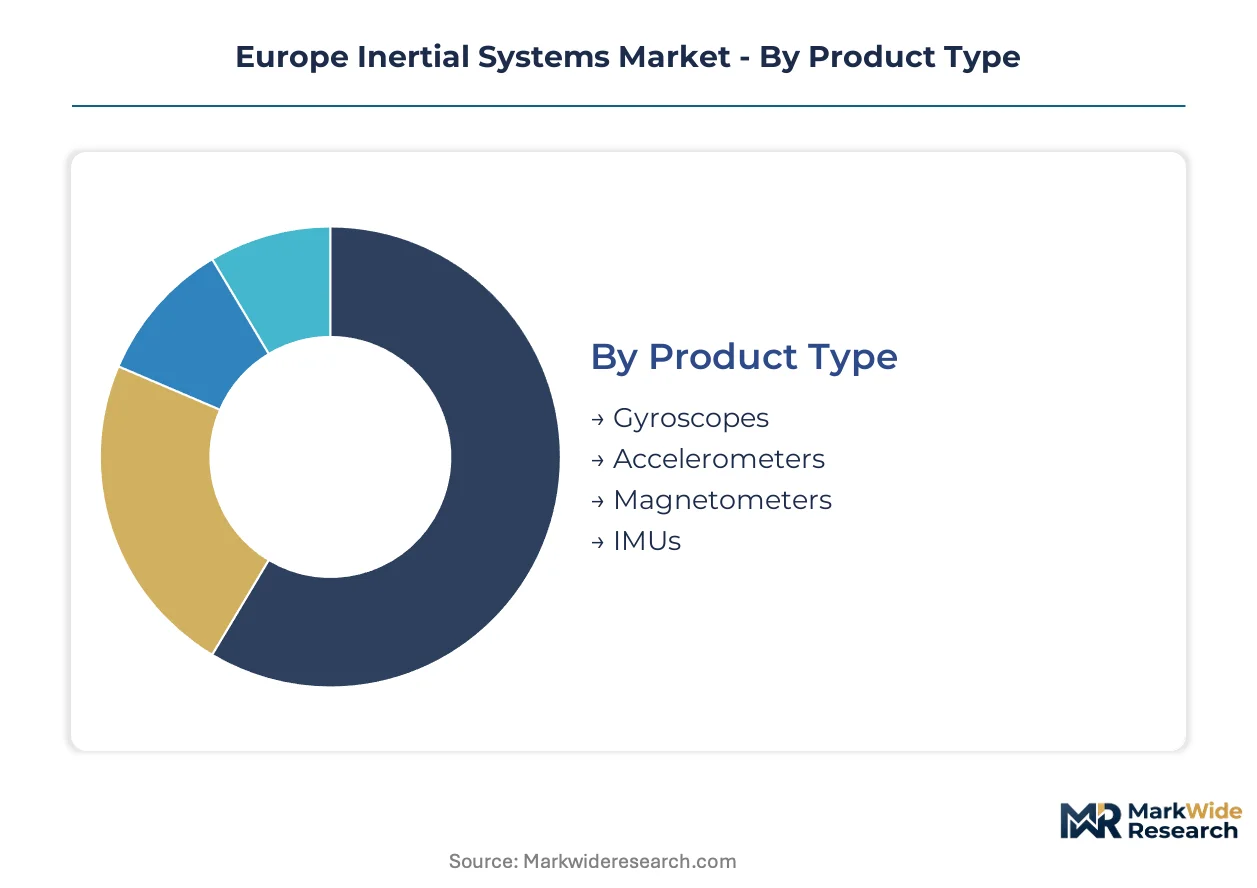
European inertial systems procurement fragments across performance tiers and integration depths, with standalone navigation-grade units commanding defense budgets while embedded MEMS sensors penetrate automotive and consumer volumes. Segmentation reveals how technology choices cascade through supply chain qualification requirements and end-use certification pathways.
Product Type:
Standalone gyroscopes and accelerometers serve calibration-intensive defense applications, while complete IMU modules dominate embedded integration in vehicles and drones.
- Gyroscopes:Fiber-optic and ring-laser variants measure angular rotation with drift tolerances spanning tactical-grade to navigation-grade precision. French defense procurement concentrates demand for Sagem-supplied units in missile guidance and submarine navigation.
- Accelerometers:MEMS capacitive and piezoelectric designs detect linear acceleration across ±2g to ±200g ranges depending on shock survivability requirements. Bosch Sensortec's captive German fabrication anchors automotive ADAS volumes.
- Magnetometers:Anisotropic magnetoresistive and fluxgate sensors provide magnetic heading reference for compass-aided dead reckoning.
- IMUs:Multi-axis integrated modules combine gyroscopic and accelerometric sensing with onboard sensor fusion processing.
IMUs lead volumes today; gyroscopes are gaining share fastest in NATO autonomous platform programs.
Technology:
Cost tier stratification separates precision-defense applications from high-volume automotive and consumer deployments, with mid-tier industrial bridging the gap.
- MEMS:Silicon micromachined structures enable batch fabrication at wafer scale, collapsing unit costs for automotive stability control and consumer drone stabilization. STMicroelectronics' Italian and French fabs supply crossover industrial-automotive platforms.
- Fiber Optic:Sagnac interferometry through coiled optical fiber achieves navigation-grade precision without moving parts. North Sea offshore energy inspection drives specification tightening for GPS-denied marine navigation.
- Ring Laser:Helium-neon gas laser cavities in triangular configurations deliver strategic-grade drift performance below 0.001 degrees per hour for ballistic missile guidance.
- Quartz:Piezoelectric crystal resonators provide tactical-grade performance in temperature-stable packages for aviation attitude reference.
MEMS dominates unit volumes; fiber-optic systems are expanding most quickly in defense and marine navigation.
End User:
Customer type determines certification burden and procurement cycle length, with defense primes demanding decade-long qualification timelines absent in commercial segments.
- Aerospace:Commercial aviation and satellite platforms require DO-178C software certification and EASA airworthiness validation for flight-critical inertial reference.
- Automotive:OEM tier-one suppliers integrate IMUs for electronic stability control, rollover detection, and emerging autonomous driving stacks under UN ECE regulation.
- Defense:National procurement frameworks in France, Germany, and Italy mandate ITAR and EU dual-use compliance for weapon system integration.
- Marine:Offshore energy and autonomous surface vessel operators specify navigation-grade immunity to GPS jamming in North Sea and Mediterranean deployments.
Automotive leads volumes today; marine is climbing the fastest on uncrewed platform proliferation.
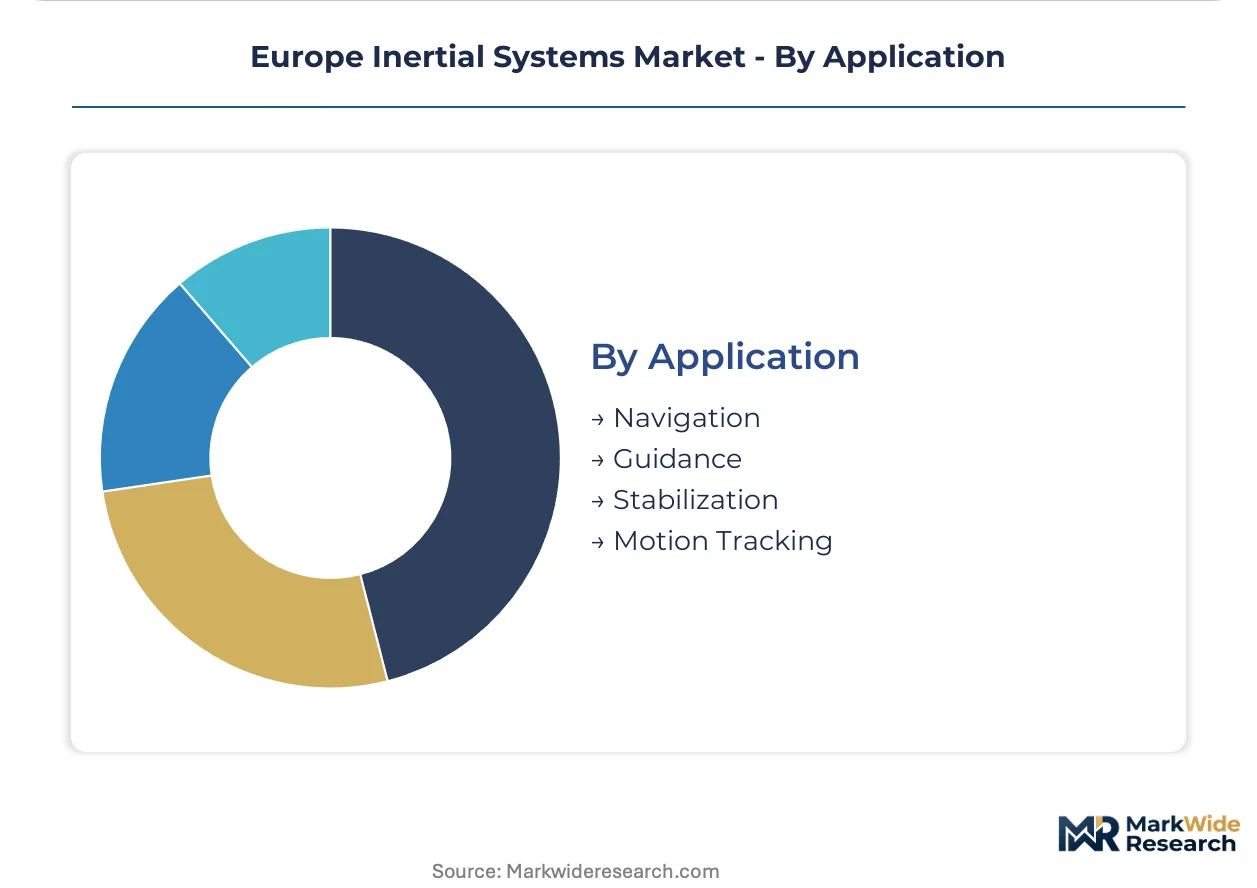
Application:
Functional use case dictates sensor fusion complexity and redundancy requirements, with safety-critical navigation demanding dual or triple modular redundancy absent in motion tracking.
- Navigation:Dead-reckoning position calculation during GPS denial requires bias stability below 0.01 degrees per hour and continuous calibration updates.
- Guidance:Missile and drone flight control loops demand microsecond-latency angular rate data with shock survivability exceeding 10,000g.
- Stabilization:Camera gimbals and antenna pointing systems reject platform vibration through high-bandwidth rate feedback.
- Motion Tracking:Virtual reality controllers and sports analytics capture orientation and acceleration with relaxed drift tolerances.
Navigation leads volumes today; guidance is expanding most quickly on NATO munitions modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photonics engineers and MEMS process specialists concentrate in French aerospace clusters and German automotive corridors, anchoring Europe's inertial systems talent base. Defense procurement frameworks in NATO member states redirect demand toward qualified domestic suppliers. The EU Chips Act accelerates foundry investments that reshape component sourcing patterns.
France
Direction Générale de l'Armement procurement drives navigation-grade gyroscope demand for missile and submarine programs. EU Chips Act subsidies support MEMS foundry expansion near Grenoble. The Paris-Saclay aerospace cluster hosts Sagem and Thales integration facilities for defense IMU production.
Germany
BAAINBw coordinates NATO munitions requirements through Permanent Structured Cooperation frameworks. REACH compliance mandates reformulation of piezoelectric accelerometer materials. Stuttgart's automotive corridor anchors Bosch Sensortec captive wafer fabrication for ADAS-grade sensors.
United Kingdom
North Sea offshore wind operators specify GPS-denied navigation for uncrewed surface vessel inspection fleets. EASA airworthiness standards govern commercial drone certification for beyond-visual-line-of-sight operations. Cambridge photonics clusters supply fiber-optic gyroscope subassemblies to defense primes.
Italy
Leonardo's defense electronics division sources tactical-grade IMUs for helicopter flight control systems. CE marking under the Machinery Directive regulates autonomous marine platform market access. Milan-Turin industrial corridors host STMicroelectronics fabs serving crossover automotive-industrial sensor demand.
Poland
NATO eastern flank modernization programs lack qualified domestic inertial suppliers, creating procurement gaps for navigation-grade systems. EU Foreign Subsidies Regulation screening tightens control over semiconductor supply chain investments. Wrocław emerging as a MEMS packaging hub through German-Polish joint ventures.
Europe Inertial Systems Market Competitive Landscape
Top-tier vendors anchor navigation-grade defense contracts, while mid-tier specialists serve automotive and industrial crossover segments. The vendor base stratifies across performance tiers rather than consolidating around volume scale. Two strategic archetypes dominate: captive foundry operators with backward integration into wafer fabrication, and modular subsystem integrators sourcing optical subassemblies from qualified supplier networks. Competitive moves center on dual-use certification acceleration and photonics-MEMS hybrid platform development.
Within the defense-prime tier, Safran Group and Thales Group exemplify European anchoring through deep supply chain integration. STMicroelectronics occupies a position spanning automotive volume and industrial precision segments through dual-use IMU platforms. Bosch Sensortec GmbH represents the captive-fabrication archetype with in-house German wafer production securing automotive ADAS supply security.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| Safran Group |
| Honeywell Aerospace Inc. |
| STMicroelectronics |
| L3Harris Technologies Inc. |
| Northrop Grumman Corporation |
| Thales Group |
| Trimble Inc. |
| Bosch Sensortec GmbH |
| Others |
Supply & Pricing Matrix
French Direction Générale de l'Armement and Germany's BAAINBw procurement concentration shapes a contract-based pricing model where navigation-grade fiber-optic gyroscopes command substantial premiums over automotive MEMS volumes. Long-term qualification timelines and dual-use compliance burdens insulate established vendors from spot-price competition.
Pricing Analysis
Hardware-software bundling separates pricing architectures in this market. Navigation-grade IMUs for defense applications incorporate calibration services and field-upgradeable optical subassemblies, while automotive MEMS ships as commodity components. Certification tier under EASA airworthiness standards and ITAR compliance levels differentiate price bands substantially. Cost compression in automotive-grade MEMS intensifies as Bosch Sensortec and STMicroelectronics expand wafer-scale fabrication capacity. Commercial drone manufacturers exhibit highest price sensitivity, whereas ballistic missile program offices prioritize drift performance over unit cost.
Supply Chain Analysis
Refurbishment flows for ring-laser gyroscope helium-neon cavities create secondary supply channels for legacy defense platforms. German and French foundries anchor MEMS wafer production under EU Chips Act subsidies. High-purity silica fiber for Sagnac interferometry draws from telecom infrastructure suppliers, creating cross-industry demand tension. Single-source vulnerability concentrates in strategic-grade ring-laser production where decade-long qualification timelines lock out alternative suppliers. Distribution runs through defense prime integration facilities and Tier 1 automotive supplier networks rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
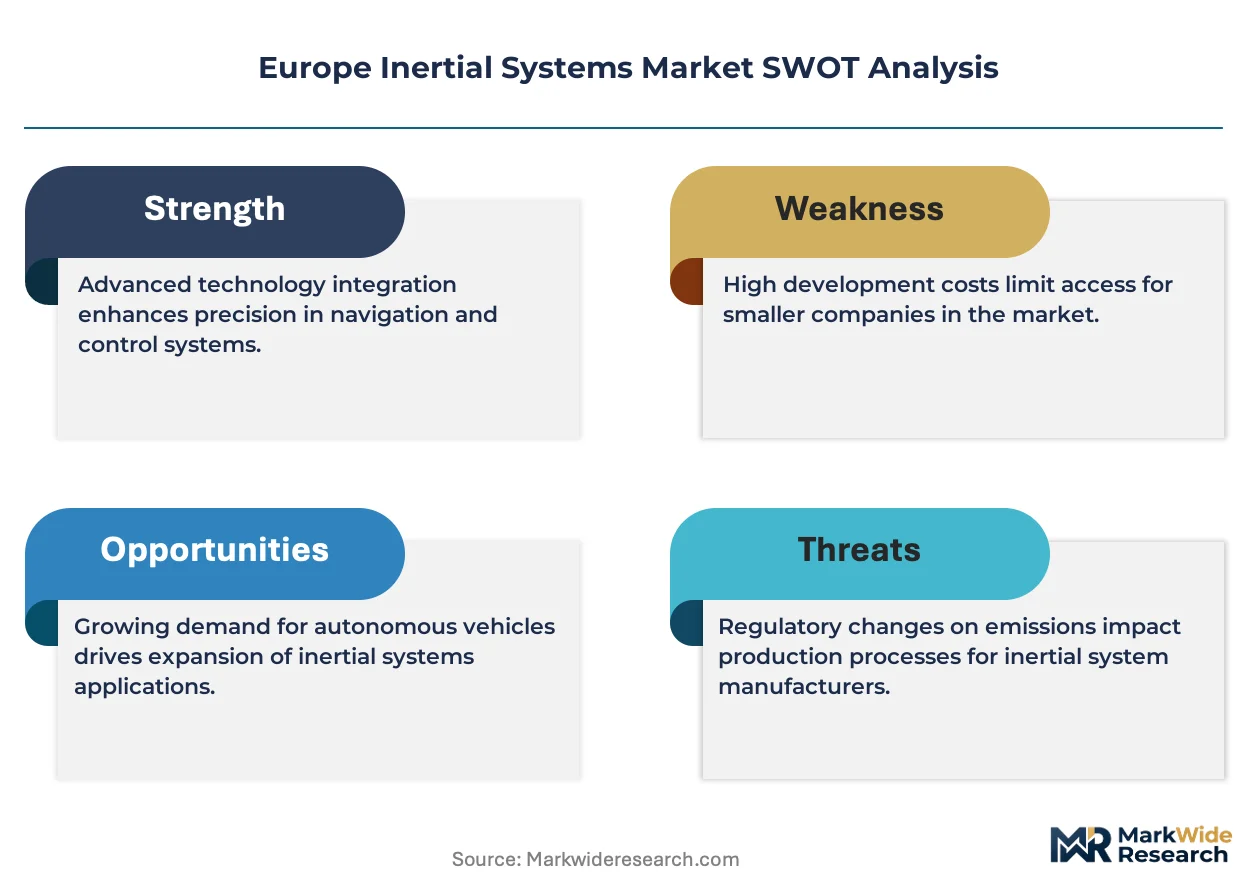
Margin expansion in European inertial systems rests on silicon photonics cost-down trajectories compressing tactical-grade MEMS production economics while navigation-grade fiber-optic platforms capture premium positioning in NATO munitions modernization.
For Market Incumbents: Acquire photonics packaging capabilities to secure chip-scale integration architectures that EASA now mandates for commercial drone certification. Defense primes like Safran Group and Thales Group should deepen backward integration into MEMS foundry capacity near Grenoble and Stuttgart to reduce import exposure. Threat from silicon photonics startups demands accelerated R&D in modular optical subassemblies that enable field-upgradeable performance tiers without platform recertification. For New Entrants and Emerging Players: The mid-tier industrial-automotive crossover gap between Bosch Sensortec's volume MEMS and Safran's navigation-grade systems offers viable entry terrain. Poland and Baltic states present the most penetrable geography where NATO eastern flank procurement lacks qualified domestic suppliers. Target predictive maintenance applications for rotating machinery where repurposed automotive IMU platforms require less stringent certification than aerospace or defense deployments. For Investors and Strategic Acquirers: Defense electronics divisions of European aerospace conglomerates are the most active acquirers in this space, seeking dual-use certification assets that accelerate ITAR and EU dual-use compliance timelines. Long-term viability favors vendors with captive photonics fabrication and established BAAINBw or Direction Générale de l'Armement qualification records. Monitor EU Foreign Subsidies Regulation screening decisions on semiconductor supply chain investments as an inflection indicator for domestic MEMS capacity expansion pace.| Strategic Initiative | Industry Significance |
|---|---|
| Photonics-MEMS Hybrid Platform Development | Silicon photonics integration narrows performance gaps between tactical and navigation-grade tiers. |
| Dual-Use Certification Acceleration | Expedited ITAR and EU dual-use compliance unlocks NATO munitions procurement pipelines. |
| Modular Optical Subassembly Standardization | Interchangeable components reduce multi-decade weapon program recertification burdens. |
| Captive MEMS Foundry Expansion | EU Chips Act subsidies in France and Germany reduce import dependency for sensor wafers. |
| AI-Driven Sensor Fusion Documentation | Explainable Kalman filter architectures satisfy EU AI Act algorithmic transparency mandates. |
Research Methodology
Direct dialogue with defense procurement officers at France's Direction Générale de l'Armement and Germany's BAAINBw, MEMS process engineers at STMicroelectronics and Bosch Sensortec facilities, EASA certification specialists, and North Sea offshore wind farm operators grounded qualitative insights. Secondary validation drew from EU Chips Act subsidy disclosures, EASA airworthiness directive filings, REACH compliance documentation, NATO Permanent Structured Cooperation procurement frameworks, and trade data on high-purity silica fiber imports. Bottom-up unit economics triangulated against top-down defense budget allocation patterns.
Bottom-up modeling tracked IMU shipments by performance tier, integration depth, and end-use qualification requirements across the projection horizon. Segmentation dimensions included gyroscope technology type, accelerometer fabrication method, defense versus commercial certification pathway, and autonomous platform application. CAGRs derived from defense procurement cycle analysis and automotive ADAS penetration curves. Industry-specific inputs incorporated ESA funding allocations and national security screening timelines under the EU Foreign Subsidies Regulation.
Caveats apply where REACH substance restriction reforms on piezoelectric materials or raw material volatility in silica fiber markets could materially shift the outlook. Forecasts reflect assumptions on NATO munitions modernization pace and EU Chips Act foundry construction timelines. Practitioners should monitor BAAINBw-Direction Générale de l'Armement coordination intensity and EASA algorithmic transparency rulemaking for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
Connected Aircraft Market