
 Air Brake Reservoirs Market | 2026-2036
Air Brake Reservoirs Market Size, Share, and Industry Trends Forecast 2026-2036
Air Brake Reservoirs Market Analytics
Fleet operators is bifurcating demand away from owner-operator buyers toward large-scale logistics consolidators with centralized procurement protocols. Knorr-Bremse AG dominates European OEM supply through captive forging operations and reservoir-to-actuator system integration. Wabtec Corporation anchors North American rail applications with pressure-rated reservoir designs certified for commuter and freight train braking architectures. Bendix CVS LLC leverages its aftermarket channel density to sustain replacement part turnover across independent repair networks.
Air brake reservoirs are pressure vessels, typically fabricated from steel or aluminum alloy, designed to store compressed air at operating pressures between 8.3 and 10.3 bar for pneumatic braking systems in commercial vehicles and rail equipment. The reservoir's primary function is to ensure instantaneous air volume availability for brake application, with corrosion-resistant interior coatings and drain valve configurations preventing moisture accumulation that would compromise braking performance. Aluminum reservoirs command expanding share in on-road commercial vehicles where weight reduction translates directly to fuel economy compliance under EPA Phase 2 greenhouse gas standards. Composite and plastic reservoir variants represent the fastest-growing material category, though penetration remains constrained by temperature tolerance limitations and OEM qualification timelines. Steel reservoirs retain dominance in off-road and railway installations where impact resistance and extreme thermal cycling durability override mass considerations.
FMVSS 121 governs air brake system performance thresholds for commercial vehicles operating in the United States, mandating specific reservoir capacity-to-brake-chamber ratios and pressure decay limits that directly influence product sizing and validation protocols. EPA emission regulations and NHTSA fuel economy standards indirectly shape reservoir demand by pressuring vehicle weight reduction, accelerating aluminum and composite substitution in certified configurations. Stakeholders must monitor proposed amendments to FMVSS 121 reservoir testing protocols and track state-level commercial vehicle inspection enforcement intensity as determinants of aftermarket replacement velocity.
Market Dynamics
Fleet consolidation across North American logistics networks is compressing procurement cycles and forcing reservoir manufacturers to reconfigure volume pricing structures around enterprise-scale contracts rather than fragmented owner-operator orders.
Growth Catalysts
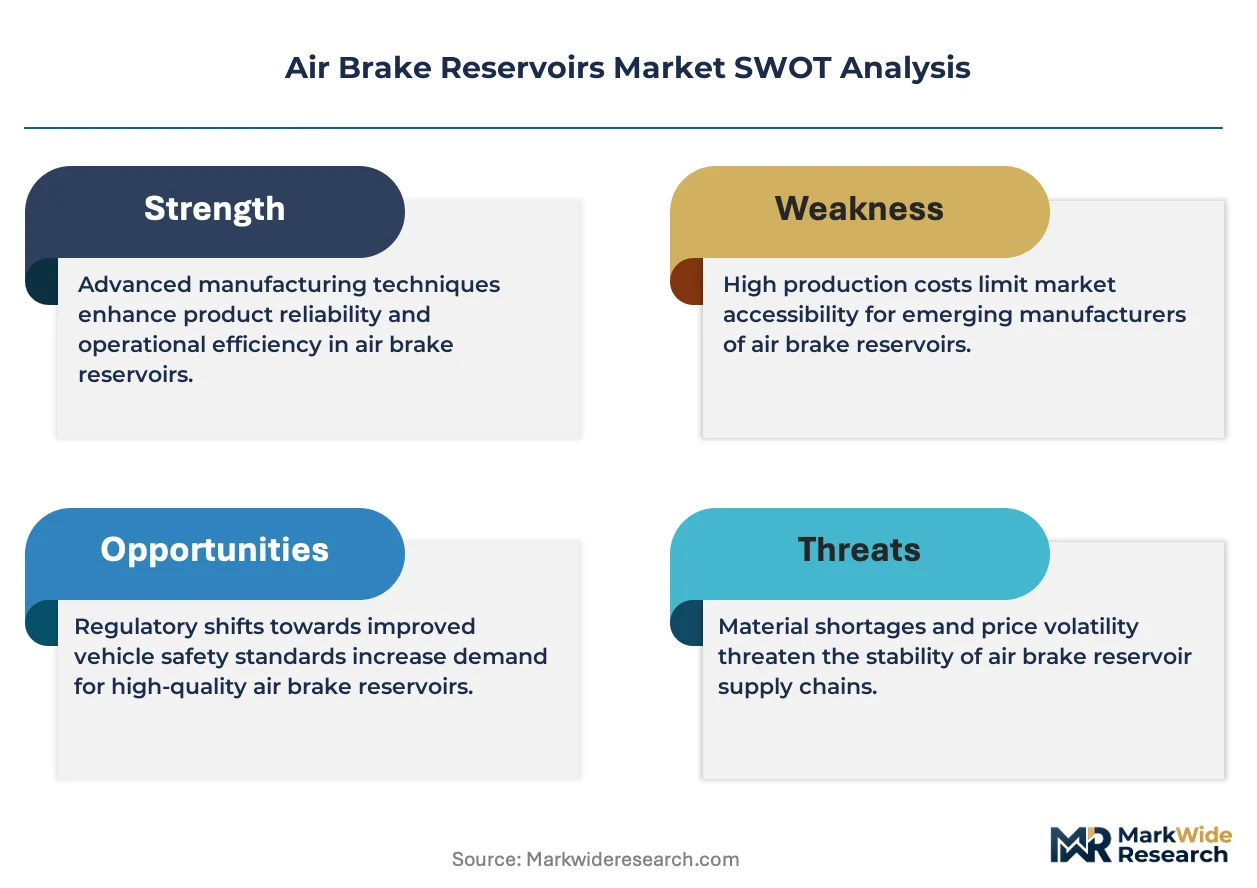
- EPA Phase 2 greenhouse gas standards:Fuel economy mandates are accelerating aluminum reservoir adoption in heavy-duty trucking as fleets pursue measurable weight reduction for compliance credits.
- Railway infrastructure modernization:Freight and commuter rail operators in the United States are expanding brake system refurbishment programs to meet FRA safety inspection protocols.
- Moisture management coatings:Advanced interior surface treatments are extending service intervals and driving aftermarket replacement demand among preventive maintenance programs.
Market Restraints
- Steel price volatility:Raw material cost swings for carbon steel sheet directly pressure margins on legacy reservoir production lines serving off-road equipment.
- Composite temperature limitations:Glass-reinforced polymer reservoirs face qualification barriers in engine-bay installations where sustained thermal exposure exceeds material ratings.
- Forging capacity concentration:Captive aluminum forging operations at dominant European suppliers limit third-party access to pressure-rated seamless reservoir blanks.
Strategic Opportunities
- Electric commercial vehicle platforms:Battery-electric truck architectures require redesigned pneumatic systems with space-optimized reservoir configurations absent traditional engine-driven compressors.
- FMVSS 121 testing protocol amendments:Proposed reservoir pressure decay validation changes would force premature replacement of pre-2020 installed bases.
- Independent repair network digitization:E-commerce parts platforms are capturing aftermarket volume from traditional jobber distribution in the United States.
Industry Challenges
- Pressure vessel certification timelines:DOT-SP and UN ISO 9809 qualification protocols extend new product introduction cycles by 18-24 months.
- Welding automation skill gaps:Reservoir seam welding for aluminum alloys requires specialized robotic programming expertise scarce in regional manufacturing labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Brake Reservoirs Market |
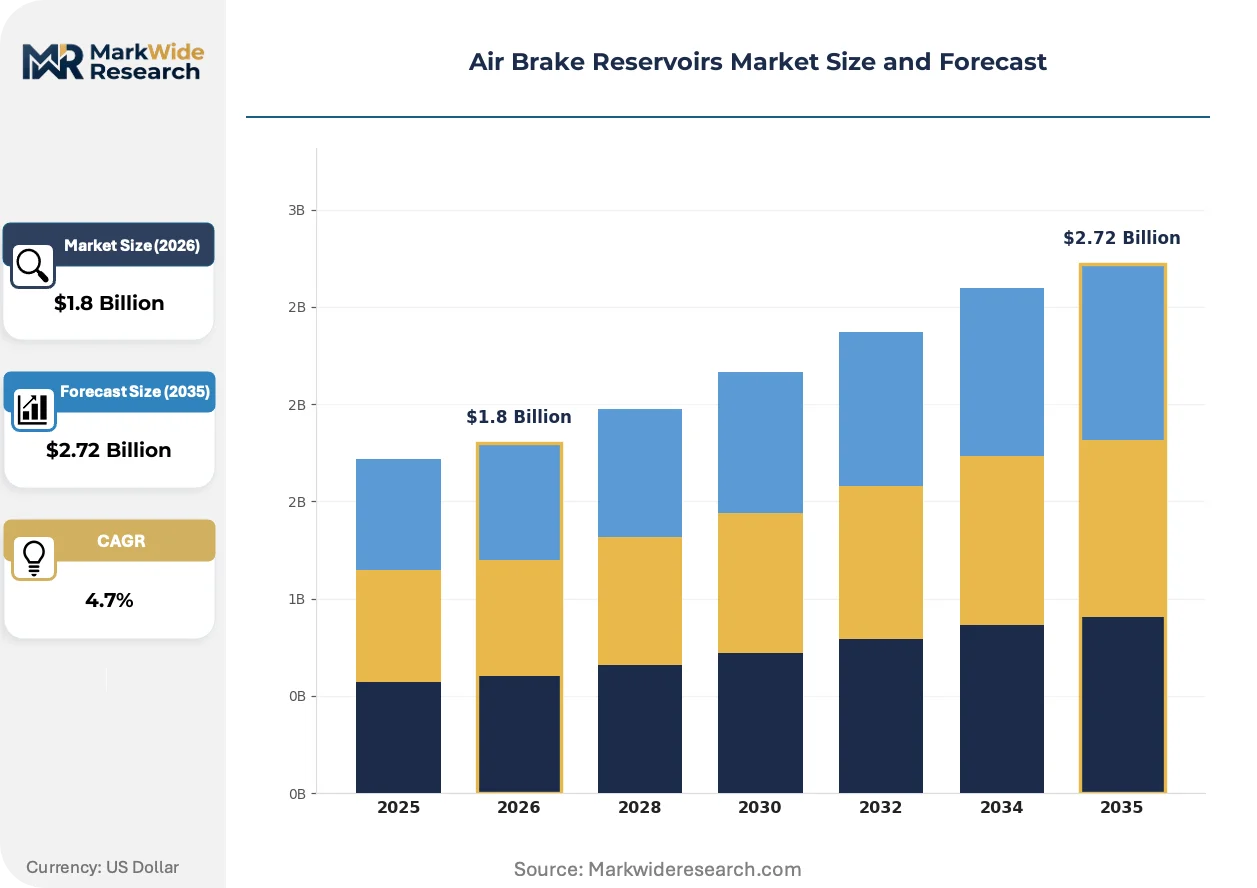
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Composite, Plastic End User: Commercial Vehicles, Heavy Machinery, Trains, Buses Installation Type: On-road, Off-road, Railway, Marine Capacity: 5-10 Liters, 10-20 Liters, 20-30 Liters, Others |
| Companies Covered | Haldex AB, Nabtesco Corp., Knorr-Bremse AG, TSE Brakes Inc., Bendix CVS LLC, ZF Friedrichshafen AG, Cummins Inc., SORL Auto Parts Inc., Wabtec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Brake Reservoirs Market Evolving Landscape
Material science advances and regulatory calibration requirements are redefining reservoir design priorities, with weight reduction and corrosion resistance now competing against legacy durability metrics as primary specification drivers.
Composite overwrap pressure vessels are miniaturizing storage footprints while maintaining burst pressure ratings through filament-wound carbon fiber reinforcement. Class 8 truck OEMs are qualifying these designs for frame-rail mounting in aerodynamic tractor configurations. The technology is miniaturizing traditional cylindrical steel geometries into conformable shapes that integrate with battery pack enclosures.
NHTSA has proposed updated reservoir capacity verification procedures under FMVSS 121 that would mandate dynamic pressure testing rather than static certification. Brake system suppliers must revalidate existing product lines against transient load profiles simulating emergency stop sequences. Heavy-duty truck manufacturers in the United States are pre-emptively redesigning reservoir volumes to exceed draft thresholds by 15 percent.
Large fleet operators are consolidating brake component procurement through integrated maintenance contracts bundling reservoirs with actuator and compressor replacements. Independent service dealers are losing share to OEM-affiliated service networks offering guaranteed uptime commitments. This concentration is most visible among 500-plus unit trucking fleets operating dedicated lanes between the Midwest and Southeast United States.
Air Brake Reservoirs Market Segmentation
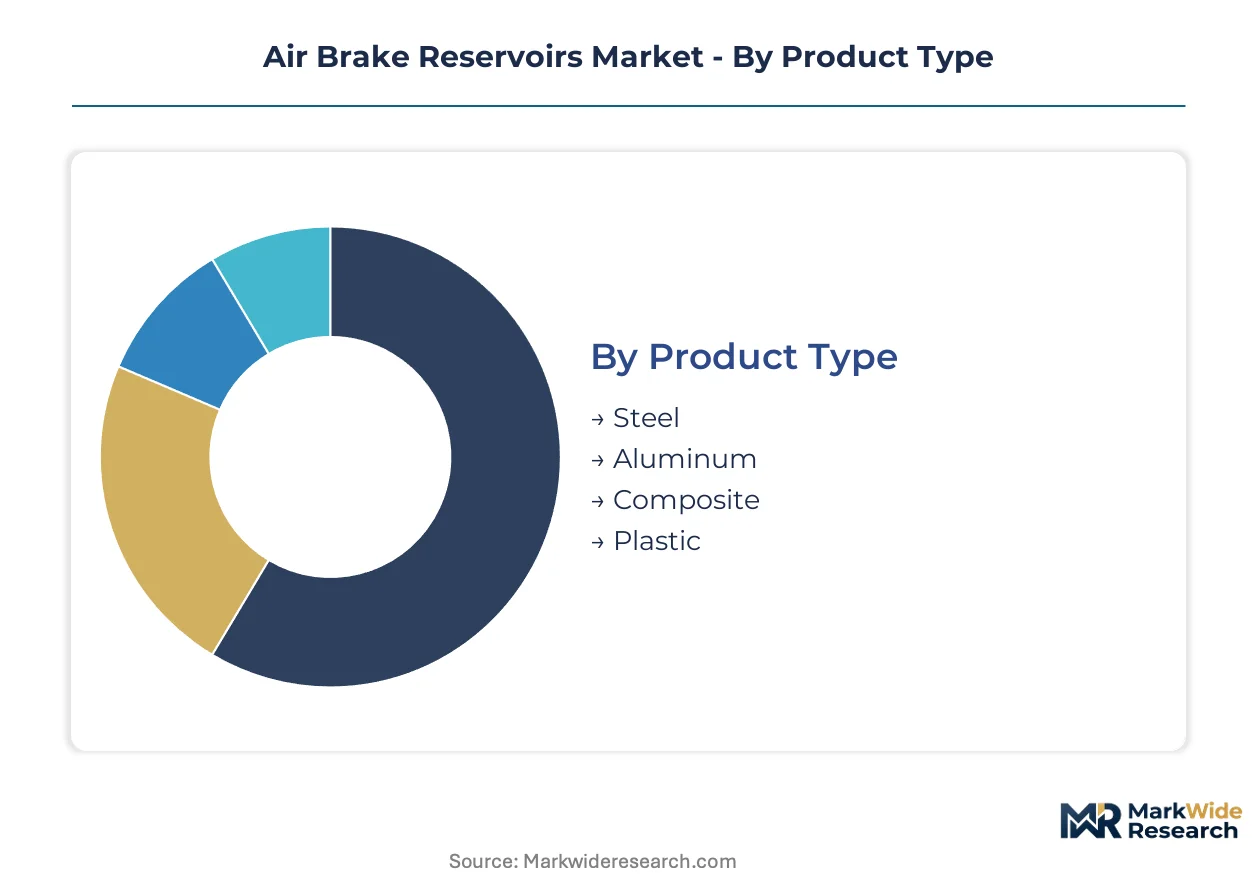
Air brake reservoir segmentation reveals divergent margin structures across material grades and installation environments. Procurement patterns differ sharply between fleet operators optimizing for total cost of ownership and OEMs prioritizing weight-driven fuel economy compliance.
Product Type:
Margin pools concentrate in aluminum and composite categories where EPA Phase 2 compliance premiums support pricing power above commodity steel benchmarks.
- Steel:Fabricated from carbon steel sheet with corrosion-resistant interior coatings, steel reservoirs dominate off-road equipment and railway applications where impact resistance outweighs mass considerations. Demand concentrates in mining trucks and freight locomotives operating across the United States and Canada, with procurement cycles tied to FRA safety inspection protocols and mine fleet replacement schedules.
- Aluminum:Seamless forged aluminum alloy construction delivers 40-60 percent weight reduction versus steel equivalents, qualifying heavy-duty trucking fleets for greenhouse gas compliance credits under EPA regulations. Fleet operators in the United States are consolidating procurement around aluminum specifications for Class 8 tractors, with volume pricing structures compressing margins for non-captive suppliers lacking in-house forging capacity.
- Composite:Filament-wound carbon fiber overwrap enables conformable geometries for battery-electric truck platforms. Temperature tolerance limitations constrain engine-bay placement.
- Plastic:Glass-reinforced polymer variants serve auxiliary pneumatic systems in light commercial vehicles. Qualification timelines lag metallic alternatives.
Steel holds installed capacity across legacy fleets. Aluminum is rotating up the share rankings in on-road commercial vehicle procurement.
End User:
Application-specific certification requirements fragment demand across mobility modes with distinct regulator relationships and safety-critical performance thresholds.
- Commercial Vehicles:Class 6-8 trucks and tractors constitute the dominant demand pool, with FMVSS 121 mandating reservoir capacity-to-brake-chamber ratios that directly influence product sizing. Fleet consolidation in the United States is shifting procurement toward enterprise-scale contracts bundling reservoirs with compressor and actuator replacements.
- Trains:Commuter and freight rail operators require pressure-rated designs certified under FRA protocols, with refurbishment cycles accelerating across Amtrak and Class I railroad networks. Wabtec Corporation anchors supply through captive qualification relationships with major United States rail operators.
- Heavy Machinery:Construction and mining equipment prioritizes impact resistance over weight, sustaining steel reservoir dominance in Caterpillar and Komatsu supply chains.
- Buses:Transit agencies specify aluminum reservoirs for urban duty cycles where stop-and-go braking frequency demands rapid air volume recovery.
Commercial vehicles command the volume base. Trains are climbing the fastest in aftermarket refurbishment intensity.
Installation Type:
Environmental exposure severity determines material selection and coating specifications across operating environments.
- On-road:Highway trucking applications prioritize aerodynamic integration and weight reduction, with frame-rail mounting configurations standardizing around aluminum and emerging composite designs. EPA fuel economy standards are disqualifying steel specifications from new Class 8 tractor platforms in the United States.
- Railway:Under-carriage mounting subjects reservoirs to debris impact and thermal cycling extremes, favoring steel construction with reinforced weld seams certified for 25-year service lives.
- Off-road:Mining and construction equipment operates in abrasive environments where structural integrity overrides mass considerations, sustaining premium pricing for thick-walled steel variants.
- Marine:Saltwater exposure demands specialized corrosion protection systems, with limited penetration outside coastal commercial fishing fleets.
On-road installations anchor aluminum growth. Railway specifications are gaining share in refurbishment procurement.
Capacity:
Brake system architecture and vehicle gross weight ratings dictate reservoir volume requirements with direct implications for forging equipment scale and material throughput.
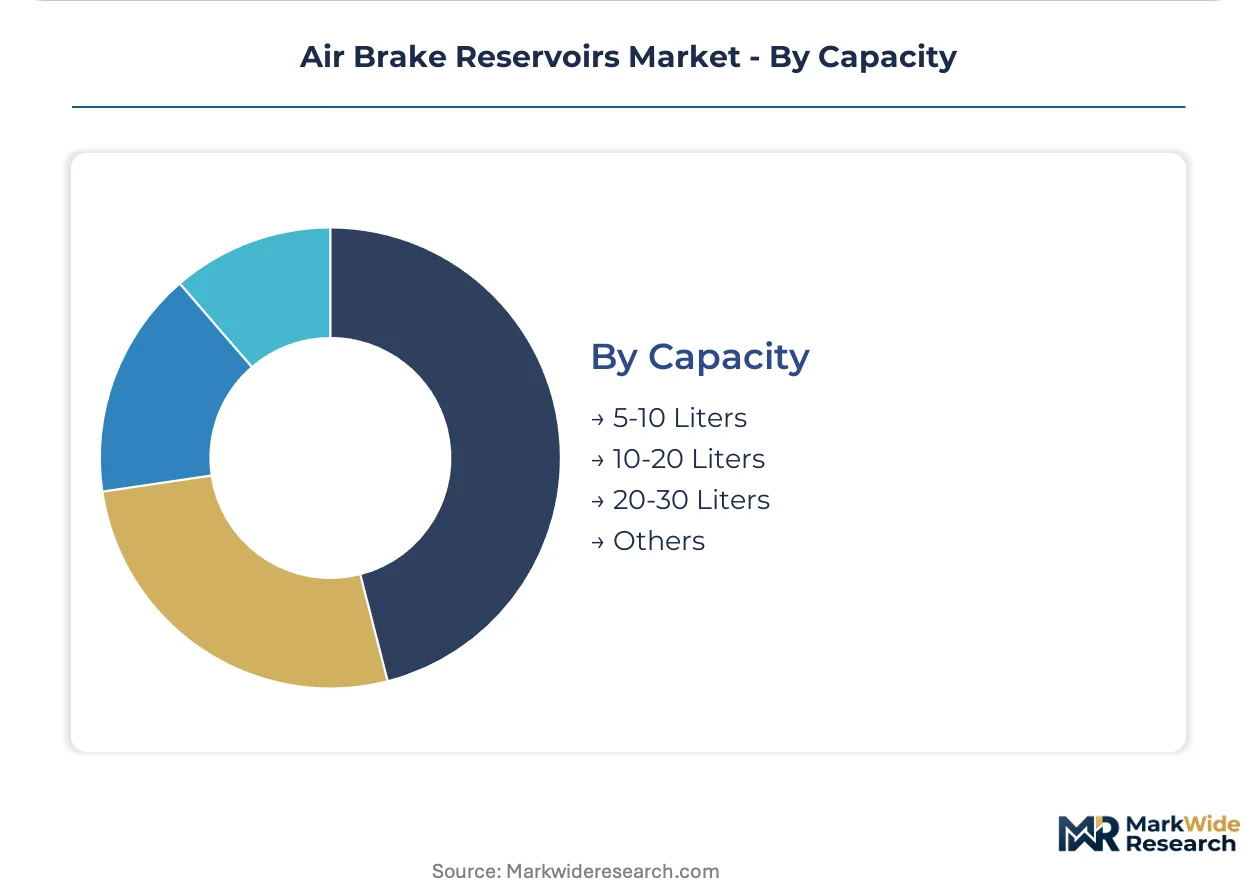
- 10-20 Liters:The standard configuration for Class 8 tractors and heavy-duty trucks, this capacity band balances emergency reserve air volume against packaging constraints. United States fleet operators are preemptively upsizing to 20-liter specifications in anticipation of FMVSS 121 testing protocol amendments.
- 20-30 Liters:Triple-axle configurations and specialized haulage applications require expanded capacity for distributed brake chamber networks. Demand concentrates in logging and heavy-haul segments across the Pacific Northwest and Appalachian regions.
- 5-10 Liters:Light and medium-duty commercial vehicles utilize compact designs with integrated dryer cartridges.
- Others:Custom volumes serve rail multiple-unit trains and off-road equipment with non-standard axle configurations.
10-20 liter specifications hold installed fleet dominance. 20-30 liter variants are expanding most quickly in heavy-haul procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-forged aluminum reservoirs to North American heavy-duty truck OEMs, while Chinese fabricators supply steel variants to Southeast Asian mining equipment assemblers. Trade corridors reflect divergent material specialization across forging capacity centers.
United States
Class 8 truck production volumes at Detroit Three manufacturers drive reservoir procurement, with EPA Phase 2 fuel economy standards accelerating aluminum adoption. NHTSA enforces FMVSS 121 pressure decay protocols that dictate reservoir sizing. Manufacturing concentrates in Michigan and Ohio, where Tier 1 brake system suppliers operate captive forging operations for seamless aluminum blanks.
Germany
Commercial vehicle OEMs in Baden-Württemberg and Bavaria specify integrated reservoir-actuator systems for export tractors. KBA administers type approval for pressure vessels under EU Directive 2014/29/EU. Industrial clusters around Stuttgart and Munich host captive aluminum forging operations that supply reservoir blanks across European OEM networks.
China
Domestic heavy-duty truck manufacturers source steel reservoirs for cost-sensitive fleet segments, with aluminum penetration lagging Western benchmarks. MIIT enforces GB/T 13077 standards for seamless steel gas cylinders that cover brake reservoir applications. Yangtze River Delta fabricators in Jiangsu and Zhejiang provinces export commodity steel reservoirs to Southeast Asian mining markets.
Japan
Isuzu and Hino integrate compact aluminum reservoirs into medium-duty platforms for ASEAN export markets. METI oversees JIS B 8265 pressure vessel standards that align with global brake system certifications. Manufacturing concentrates in Gunma and Tochigi prefectures, where precision forging houses supply seamless reservoir cylinders to domestic brake system integrators.
India
Tata Motors and Ashok Leyland specify steel reservoirs for domestic heavy commercial vehicles, with aluminum adoption constrained by fleet cost sensitivity. BIS mandates IS 2825 certification for unfired pressure vessels including brake reservoirs. Industrial corridors in Maharashtra and Tamil Nadu host reservoir fabricators serving OEM assembly plants in Pune and Chennai.
Air Brake Reservoirs Market Competitive Landscape
Listed leaders compete with private specialists across forging capacity and aftermarket channel density. The vendor base stratifies into three tiers: multinational brake system integrators with captive reservoir production, independent metalformers supplying Tier 2 contracts, and regional aftermarket distributors. Strategic moves center on backward integration into aluminum forging and e-commerce platform development for replacement part sales.
Among European-based brake system houses, Knorr-Bremse AG and ZF Friedrichshafen AG exemplify the integrated OEM supply archetype through captive forging operations and system-level bundling. Wabtec Corporation represents the rail-specialist position with pressure-rated designs certified for commuter and freight applications. These three entities anchor distinct competitive vectors—on-road commercial vehicle integration, rail system certification, and multi-modal pressure vessel expertise—without overlapping core account bases.
| Leading Market Players |
|---|
| Haldex AB |
| Nabtesco Corp. |
| Knorr-Bremse AG |
| TSE Brakes Inc. |
| Bendix CVS LLC |
| ZF Friedrichshafen AG |
| Cummins Inc. |
| SORL Auto Parts Inc. |
| Wabtec Corporation |
| Others |
Value Network & Pricing Analysis
Aluminum-forged reservoir blanks displacing steel sheet fabrications simultaneously redraw supply geography toward Germany and the United States while compressing margin structures for non-captive suppliers lacking in-house forging capacity. Fleet procurement consolidation amplifies this shift by concentrating volume pricing power with Tier 1 brake system integrators.
Pricing Analysis
Technology-generation pricing gaps separate legacy steel reservoirs from EPA Phase 2-compliant aluminum specifications and emerging composite prototypes. Three-tier pricing structure across premium forged aluminum, standard welded steel, and economy-grade plastic variants reflects certification grade and volume scale differentials. Cost compression in steel tiers is intensifying because carbon sheet price volatility pressures legacy production lines. Owner-operator buyers exhibit highest price sensitivity, while 500-plus unit fleets prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Germany and the United States anchor precision aluminum forging for seamless reservoir blanks, while China and India supply commodity steel fabrications for cost-sensitive markets. Raw material flows draw from bauxite refining corridors, carbon steel sheet mills, and carbon fiber precursor suppliers. Single-source vulnerability concentrates in captive forging operations at dominant European suppliers. Distribution runs through OEM-affiliated service networks capturing fleet maintenance contracts and independent repair channels serving fragmented aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite reservoir technologies threaten incumbent metal positions by enabling conformable geometries for electric commercial vehicle platforms, forcing traditional suppliers to defend material relevance through accelerated qualification investments.
For Market Incumbents: Secure captive aluminum forging capacity in Michigan or Ohio to maintain supply leverage against Knorr-Bremse and ZF captive operations. Defend aftermarket channel density through e-commerce platform investments that preempt independent repair network digitization. Composite temperature limitations provide temporary shelter for metallic specifications in engine-bay installations. For New Entrants and Emerging Players: Lead with filament-wound carbon fiber overwrap designs targeting battery-electric truck OEMs seeking space-optimized pneumatic configurations. White-space concentrates in Class 8 tractor frame-rail mounting applications where conformable geometries enable aerodynamic integration. Partner with emerging electric commercial vehicle platforms lacking established brake system supply relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed metalformers supplying Tier 2 contracts without backward integration into forging. Long-term viability hinges on aluminum conversion exposure and FMVSS 121 amendment readiness. Monitor NHTSA testing protocol finalization timing as inflection indicator for premature replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Forging Expansion | Secures seamless reservoir blank supply for EPA Phase 2 compliance in United States heavy-duty trucking. |
| Composite Qualification Investment | Enables temperature-tolerant carbon fiber designs for electric commercial vehicle battery pack integration. |
| Aftermarket E-Commerce Platform | Captures independent repair network volume from traditional jobber distribution channels. |
| FMVSS 121 Pre-Compliance Redesign | Preempts dynamic pressure testing mandates with 15 percent volume buffer specifications. |
| Electric Vehicle Platform Partnership | Establishes pneumatic system design relationships absent traditional engine-driven compressor architectures. |
Research Methodology
A standing panel of fleet maintenance directors, Tier 1 brake system procurement managers, aftermarket distributor operations heads, and NHTSA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FMVSS 121 docket filings, EPA Phase 2 compliance documentation, FRA safety inspection protocols, heavy-duty truck production databases, and SEC filings from listed brake system suppliers. Bottom-up volume modeling triangulated against top-down market sizing across material grade and installation environment segments.
Consistency checks validated volume and value outputs against external benchmarks including vehicle registration data, aftermarket parts shipment records, and OEM production schedules across the analysis window. Segmentation dimensions encompassed material type, end-use application, installation environment, and capacity tier alongside geographic production cluster and regulatory compliance status. CAGRs were derived from fitted growth curves incorporating fleet replacement cycle acceleration, material substitution elasticity, and refurbishment intensity patterns in railway and commercial vehicle installed bases.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity, stable aluminum forging capacity expansion, or unamended FMVSS 121 protocols would require recalibration. Forecasts reflect assumptions regarding fleet consolidation velocity, composite temperature tolerance advancement, and railway infrastructure refurbishment commitment levels. Recalibration cycles align with material shifts in NHTSA regulatory finalization, electric commercial vehicle platform launch schedules, and primary aluminum price trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Spark Plug Accessories Market
Vehicle Components
Rear Axle Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
2 Wheeler Fuel Tank Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Throttle Cable Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
Towing Ropes Market
Vehicle Components
Steering Stabilizers Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Suction Road Sweeper Market