
 Aerospace Consulting Services Market | 2026-2036
Aerospace Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Consulting Services Market Insights
Advisory procurement channels for defense contractors and satellite operators are reshaping how expertise reaches aerospace decision-makers. Bain & Company leverages its defense practice to anchor long-term engagements with Pentagon program offices. Accenture competes through technology advisory tied to digital thread implementations across OEM engineering departments. McKinsey & Company dominates board-level strategy mandates for commercial aviation restructuring and fleet renewal planning.
Aerospace consulting services encompass technical advisory, regulatory navigation, and operational optimization delivered to aviation and space organizations managing complex certification, supply chain, and mission-critical systems. Consultants apply systems engineering frameworks, earned value management protocols, and risk-adjusted scheduling algorithms to compress development cycles and reduce program overruns. Strategy Consulting leads revenue contribution as OEMs confront fleet transition decisions and defense primes restructure for multi-domain operations. Sustainability Consulting represents the fastest-expanding segment as airlines respond to CORSIA obligations and manufacturers pursue scope-three emissions accounting.
FAA certification standards, EASA CS-25 airworthiness requirements, and ITAR export control frameworks govern market access and shape consultant competency demands across jurisdictions. Compliance complexity escalates as dual-use technologies blur civilian-military boundaries and space launch licensing fragments across national regulators. Stakeholders must monitor how emerging AI-assisted design validation triggers novel liability frameworks and reshapes advisory scope in certification support.
Market Dynamics
Fleet transition timelines for next-generation narrow-body aircraft are compressing advisory cycles as airlines confront simultaneous engine procurement, pilot retraining, and route network reconfiguration demands. This structural pressure forces consulting engagements toward integrated program management rather than discrete technical studies.
Growth Catalysts
- CORSIA carbon offset mandates:Airlines in the United States, Germany, and Singapore are procuring emissions accounting advisory to meet ICAO compliance deadlines and avoid penalty exposure.
- Digital thread architectures:OEM engineering departments in France and Japan are embedding model-based systems engineering consultants into development programs to compress design validation cycles.
- Urban air mobility certification:FAA's Special Federal Aviation Regulation framework for eVTOL aircraft is generating specialized advisory demand from California and Texas-based operators seeking type certification.
Market Restraints
- ITAR export control friction:Dual-use technology classifications restrict consultant mobility and data sharing between United States and European defense clients.
- Specialized talent scarcity:Systems engineers with combined FAA certification and software safety expertise command premium rates that inflate project budgets.
- Concentrated OEM buyer power:Boeing and Airbus procurement offices dictate fixed-fee structures that compress margins for tier-two advisory firms.
Strategic Opportunities
- India defense modernization:Ministry of Defence offset obligations and indigenization targets create openings for foreign consultants to partner with domestic engineering houses.
- AI-assisted design validation:Convergence of machine learning algorithms with traditional airworthiness engineering is collapsing certification documentation timelines for advanced composites.
- Space launch licensing fragmentation:National regulators in Australia, New Zealand, and the United Kingdom are building licensing frameworks that require specialized regulatory navigation support.
Industry Challenges
- Legacy system integration complexity:Airlines operating mixed fleets of 737 MAX and 737 NG variants require consultants to reconcile incompatible maintenance planning systems.
- Security clearance bottlenecks:Pentagon program offices impose personnel vetting delays that stretch advisory team mobilization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Consulting Services Market |
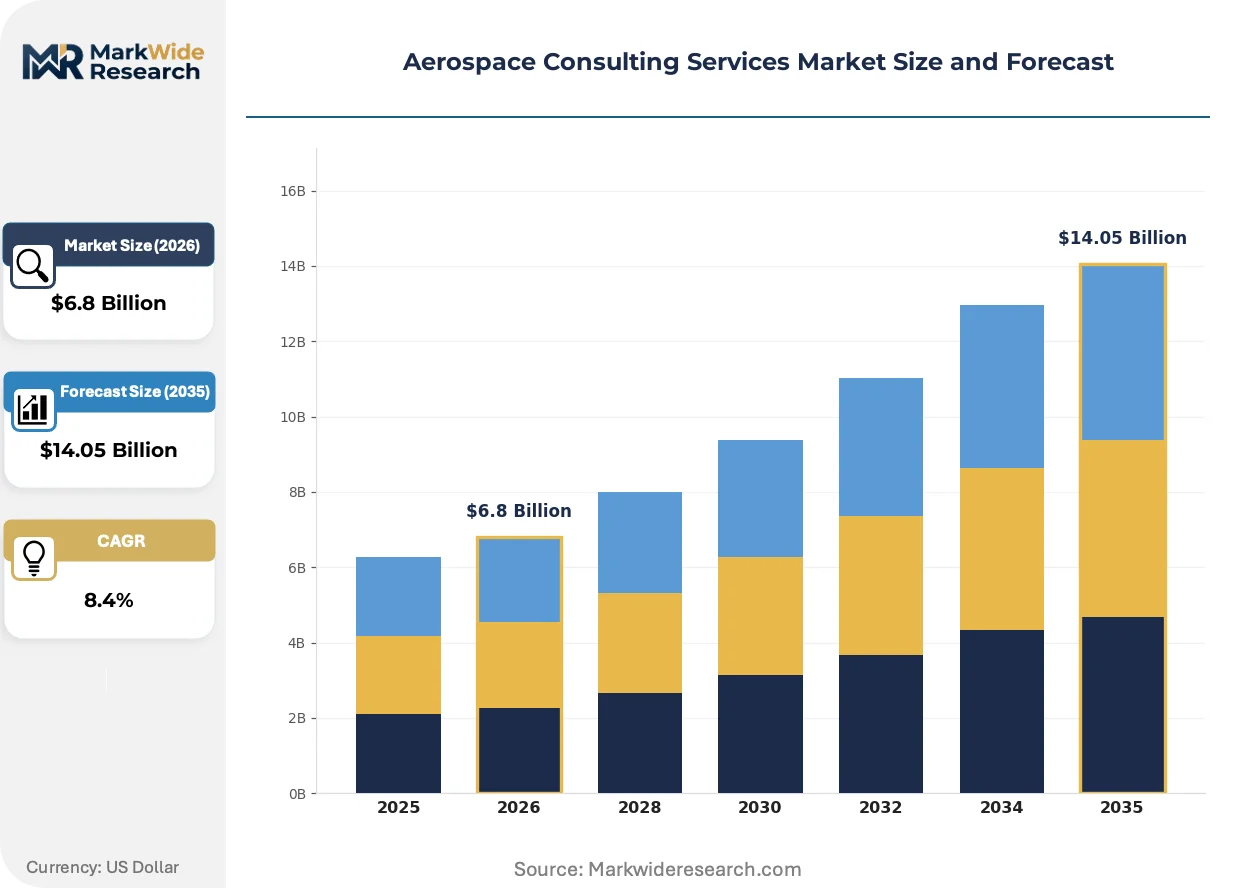
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Consulting, Technology Advisory, Regulatory Compliance, Risk Management, Sustainability Consulting Application: Aircraft Design, Space Missions, Defense Programs, Maintenance Planning, Supply Chain Optimization End User: OEMs, Satellite Operators, Defense Contractors, Maintenance Providers, Research Institutions Delivery Model: Onsite Consulting, Remote Advisory, Project-Based, Retainer Agreements, Custom Workshops |
| Companies Covered | Bain & Company, Accenture, McKinsey & Company, BCG, Deloitte, Booz Allen Hamilton, Vertex Professional Services, Avascent, Renaissance Strategic Advisors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Consulting Services Market Trends and Innovations
Advisory delivery models are pivoting from episodic studies toward continuous engineering partnerships embedded within OEM development programs. This shift reflects the compression of aircraft development cycles and the integration of software-defined systems into hardware platforms.
Model-based systems engineering is collapsing traditional document-centric certification processes by enabling real-time design verification against FAA and EASA airworthiness criteria. Airbus and Lockheed Martin engineering departments are adopting these digital threads to synchronize supplier data and reduce rework during validation phases. The structural consequence is a halving of advisory hours previously consumed by manual traceability documentation.
EASA's CS-25 airworthiness requirement updates for hydrogen propulsion systems are forcing consultancies to build specialized competency in cryogenic fuel storage safety cases. German and French regulators are coordinating certification criteria that exceed existing FAA guidance, creating advisory demand from European OEMs seeking first-mover advantage. Affected segments include regional aircraft manufacturers targeting 2035 service entry dates.
Airline procurement departments are unbundling advisory contracts into discrete work packages awarded through competitive mini-tenders rather than sole-source relationships. United States network carriers now segment strategy, technical, and regulatory advisory into separate vendor pools to benchmark pricing. This pattern is most visible among legacy carriers undergoing Chapter 11 restructuring, where creditor committees demand transparent fee justification.
Aerospace Consulting Services Market Segmentation
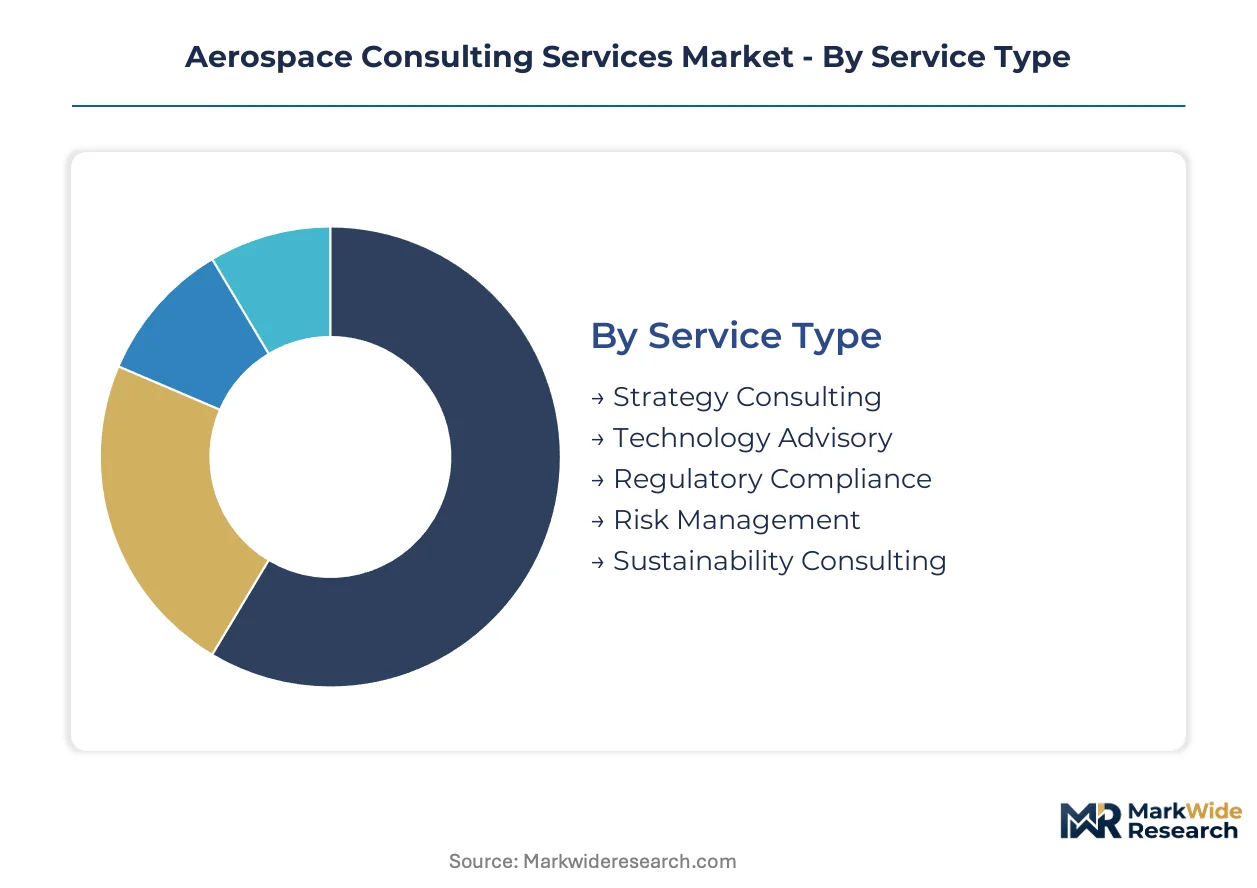
Aerospace consulting engagements vary dramatically in duration and renewal patterns across service lines. Procurement officers structure vendor portfolios around these cycle-time differences to balance strategic continuity with tactical flexibility.
Service Type:
Strategy Consulting turns over slowest with multi-year retainer structures, while Sustainability Consulting contracts refresh fastest as regulatory deadlines shift.
- Strategy Consulting:Board-level mandates covering fleet renewal planning and multi-domain defense restructuring. Airlines in the United States and Germany procure these services through 24-36 month engagements tied to creditor committee oversight.
- Sustainability Consulting:Emissions accounting and CORSIA compliance advisory with compressed 6-12 month cycles. Singapore carriers and French OEMs drive procurement as EASA environmental mandates tighten faster than FAA guidance.
- Technology Advisory:Digital thread implementation and model-based systems engineering support for Airbus and Lockheed Martin engineering departments.
- Regulatory Compliance:FAA certification navigation and EASA CS-25 airworthiness documentation for eVTOL developers in California and Texas.
- Risk Management:Earned value management protocols and program overrun prevention for Pentagon satellite acquisition offices.
Strategy Consulting anchors the volume base while Sustainability Consulting gains share at the steepest rate.
Application:
Cost tier separation runs deepest between mission-critical defense programs and commoditized maintenance planning.
- Defense Programs:Multi-domain operations restructuring and ITAR-compliant advisory for Pentagon program offices. Security clearance bottlenecks inflate mobilization costs and stretch timelines.
- Space Missions:Launch licensing navigation across fragmented national regulators in Australia, New Zealand, and the United Kingdom. Specialized competency demands command premium pricing.
- Aircraft Design:Hydrogen propulsion safety cases and cryogenic fuel storage certification for German and French regional aircraft manufacturers.
- Supply Chain Optimization:Boeing supplier network restructuring and NASA contracting pipeline alignment.
- Maintenance Planning:Legacy system integration for mixed 737 MAX and 737 NG fleets requiring incompatible planning system reconciliation.
Defense Programs absorb the highest per-engagement spend while Space Missions expand most quickly.
End User:
Customer type determines contract structure more than any other segmentation dimension.
- OEMs:Integrated program management partnerships replacing discrete technical studies. Airbus and Boeing procurement offices dictate fixed-fee structures that compress advisor margins.
- Defense Contractors:Long-term Pentagon program office engagements anchored by Bain defense practice relationships. ITAR restrictions limit consultant mobility between United States and European clients.
- Satellite Operators:Regulatory navigation for national launch licensing frameworks and spectrum coordination.
- Maintenance Providers:Route network reconfiguration and pilot retraining program design for United States network carriers.
- Research Institutions:NASA contracting pipeline alignment and technology transfer advisory.
OEMs dominate absolute contract value while Defense Contractors deliver the most predictable renewal rates.
Delivery Model:
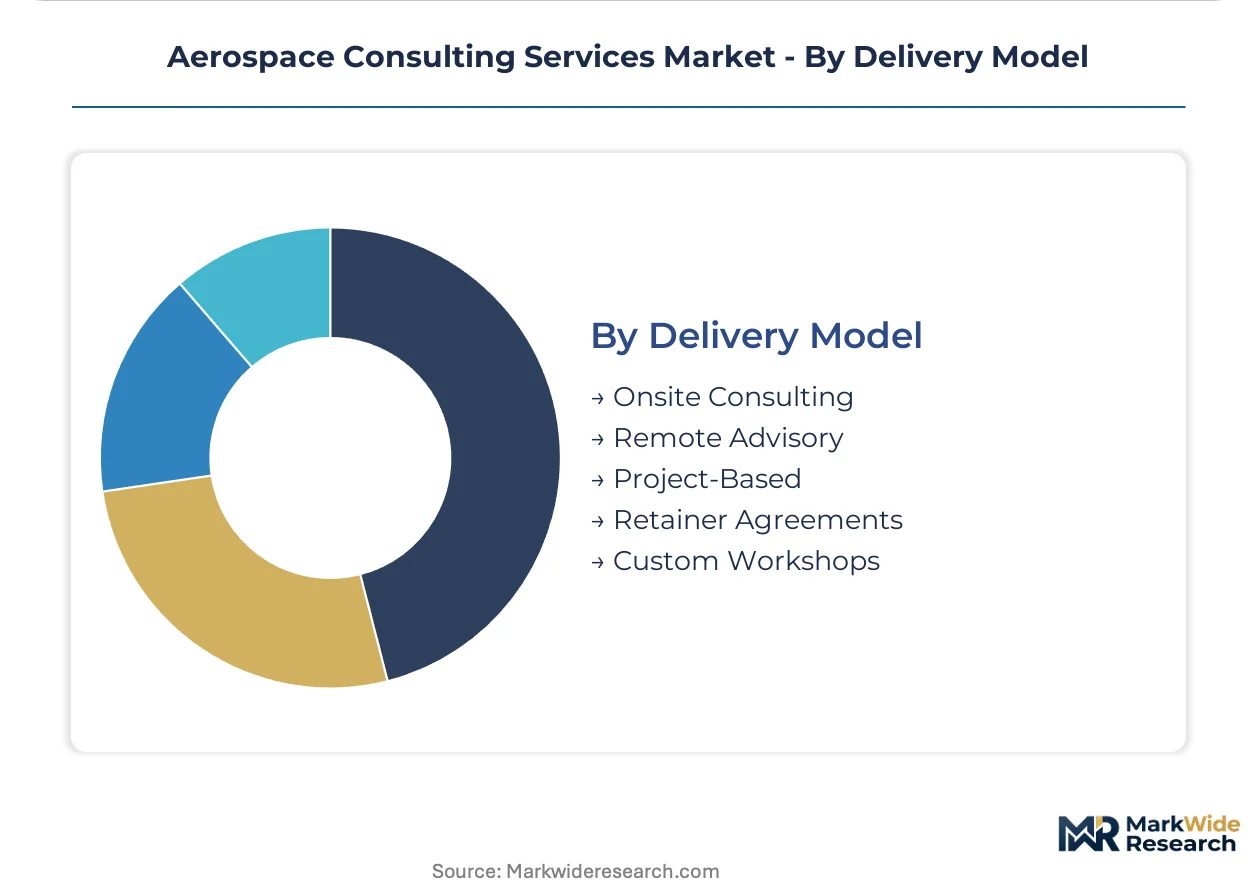
Volume concentration sits with project-based structures, though margin accrues to retainer relationships.
- Project-Based:Discrete certification studies and compliance documentation with defined deliverables. United States legacy carriers undergoing Chapter 11 restructuring unbundle these into competitive mini-tenders.
- Retainer Agreements:Continuous engineering partnerships embedded within OEM development programs. These reflect compressed aircraft development cycles and software-defined system integration.
- Onsite Consulting:FAA and EASA airworthiness criteria verification through real-time design collaboration.
- Remote Advisory:Emissions accounting and CORSIA offset calculation for distributed airline operations.
- Custom Workshops:Intensive certification preparation for eVTOL operators seeking type certification under FAA Special Federal Aviation Regulation frameworks.
Project-Based structures generate the highest absolute hours while Retainer Agreements climb the fastest as advisory delivery pivots toward continuous partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification timelines and Pentagon contracting pipelines anchor United States demand, while EASA environmental mandates and hydrogen propulsion safety cases concentrate activity in Germany and France. Advisory procurement patterns diverge sharply between defense-heavy North American markets and sustainability-driven European jurisdictions.
United States
Boeing supplier networks and NASA contracting pipelines sustain dense consulting ecosystems across Washington State, Kansas, and Texas. FAA Special Federal Aviation Regulation frameworks for eVTOL certification generate specialized advisory demand from California and Texas-based operators. Security clearance bottlenecks at Pentagon program offices stretch advisory team mobilization timelines and inflate costs.
Germany
EASA CS-25 airworthiness requirement updates for hydrogen propulsion systems force consultancies to build cryogenic fuel storage safety case competency. Regional aircraft manufacturers targeting 2035 service entry dates drive procurement of specialized certification support. Munich and Hamburg engineering clusters concentrate model-based systems engineering advisory for Airbus development programs.
France
Airbus procurement offices dictate fixed-fee structures that compress margins for tier-two advisory firms while embedding consultants into digital thread implementations. EASA environmental mandates tighten faster than FAA guidance, accelerating sustainability consulting contract refresh cycles. Toulouse and Paris engineering departments anchor integrated program management partnerships replacing discrete technical studies.
United Kingdom
Space launch licensing fragmentation across national regulators generates regulatory navigation demand from satellite operators and launch vehicle developers. London-based advisory practices serve Commonwealth defense modernization programs and commercial aviation restructuring mandates. Scottish and Southwest England clusters concentrate launch site licensing expertise for emerging spaceports.
India
Ministry of Defence offset obligations and indigenization targets create openings for foreign consultants to partner with domestic engineering houses in Bangalore and Hyderabad. BIS standards alignment and DGFT export control navigation shape advisory scope for aerospace component manufacturers. Bengaluru and Hyderabad defense clusters concentrate systems engineering talent for fighter aircraft and unmanned aerial vehicle programs.
Aerospace Consulting Services Market Competitive Landscape
Strategy-heavy generalists and defense-specialized boutiques split the market into distinct advisory tiers. Tier-one management consultancies capture board-level mandates through multi-year retainer structures, while specialized defense advisors secure Pentagon program office relationships through security-cleared talent pools. Boutique regulatory specialists and technology implementation firms occupy intermediate positions. Competitive moves center on embedding consultants into OEM engineering departments and building hydrogen propulsion safety case competency ahead of EASA mandate deadlines.
Within the strategy consulting tier, Bain & Company and McKinsey & Company exemplify divergent approaches to aerospace advisory. Bain anchors long-term Pentagon program office engagements through its defense practice relationships, while McKinsey dominates commercial aviation restructuring mandates for creditor committee oversight. Accenture occupies a distinct position at the technology advisory intersection, embedding model-based systems engineering support into Airbus and Lockheed Martin digital thread implementations.
| Leading Market Players |
|---|
| Bain & Company |
| Accenture |
| McKinsey & Company |
| BCG |
| Deloitte |
| Booz Allen Hamilton |
| Vertex Professional Services |
| Avascent |
| Renaissance Strategic Advisors |
| Others |
Pricing and Supply Chain Analysis
Washington State engineering clusters and Pentagon program office corridors concentrate cleared talent pools that feed margin capture downstream into defense contractor advisory tiers. Boeing and Airbus procurement offices exploit this supply concentration to dictate fixed-fee structures that compress advisor margins while embedding consultants into continuous engineering partnerships.
Pricing Analysis
United States advisory rates command significant premiums over European and Indian counterparts due to ITAR clearance requirements and FAA certification expertise scarcity. Project-based structures dominate commercial aviation while retainer agreements anchor defense mandates, with price differentiation resting on security clearance tier and model-based systems engineering competency. Cost compression in tier-two advisory tiers is intensifying because concentrated OEM buyer power forces competitive mini-tender unbundling. Maintenance providers and regional carriers exhibit highest price sensitivity, whereas Pentagon program offices demonstrate lowest sensitivity due to mission-critical program overrun exposure.
Supply Chain Analysis
ITAR export control frameworks fragment consultant mobility between United States and European defense clients, creating artificial supply scarcity that inflates cleared talent premiums. Talent supply concentrates in the United States, Germany, and India, with raw inputs drawing from systems engineering programs, FAA certification pipelines, and security clearance vetting queues. Single-source vulnerability sits with specialized practitioners holding combined airworthiness and software safety credentials. Distribution runs through direct Pentagon program office relationships, OEM procurement panels, and competitive mini-tender platforms for commercial aviation restructuring mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace consulting is approaching a platform-economics inflection as digital thread architectures and model-based systems engineering create interoperability standards that reshape how expertise integrates into OEM development programs.
For Market Incumbents: Pre-empt margin erosion from boutique regulatory specialists by acquiring hydrogen propulsion safety case competency ahead of EASA mandate deadlines. Embed consultants deeper into Airbus and Lockheed Martin engineering departments through continuous engineering partnerships that displace discrete technical study vendors. Vertical integration into model-based systems engineering tooling creates defensive moats against Accenture's technology advisory expansion.
For New Entrants and Emerging Players: Pursue white-space opportunities in space launch licensing navigation across Australia's, New Zealand's, and the United Kingdom's fragmented national regulators. Target sustainability consulting for Singapore carriers and French OEMs facing faster-tightening EASA environmental mandates than FAA guidance. A regulatory-specialist positioning with cryogenic fuel storage certification competency offers the cleanest go-to-market angle for European regional aircraft manufacturers.
For Investors and Strategic Acquirers: Capital is best deployed toward boutique defense advisors with cleared talent pools and established Pentagon program office relationships, given multi-year visibility from offset-driven India defense modernization. Long-term viability across the projection horizon hinges on advisory firms capturing digital thread implementation mandates as OEMs compress development cycles. The signal to watch as inflection indicator is FAA Special Federal Aviation Regulation framework expansion beyond eVTOL into additional advanced air mobility categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Propulsion Safety Case Buildout | EASA CS-25 updates for cryogenic fuel storage create first-mover certification advantage for German and French advisory practices. |
| Digital Thread Partnership Embedding | Continuous engineering integration into Airbus and Lockheed Martin development programs displaces episodic study competitors. |
| Space Launch Licensing Specialization | Fragmented national regulators in Australia, New Zealand, and the United Kingdom generate premium regulatory navigation demand. |
| Cleared Talent Pool Expansion | Security clearance bottlenecks at Pentagon program offices stretch mobilization timelines and inflate advisory premiums. |
| Sustainability Consulting Capability | CORSIA compliance deadlines for United States, Germany, and Singapore carriers accelerate contract refresh cycles fastest. |
Research Methodology
A spread of perspectives from Pentagon program office directors, Airbus procurement executives, FAA certification leads, and sustainability officers at Singapore carriers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with these stakeholders alongside secondary validation from FAA Special Federal Aviation Regulation filings, EASA airworthiness documentation, NASA contracting pipeline disclosures, and customs data on aerospace services trade flows. Bottom-up engagement sizing and top-down market triangulation anchored volume and value estimates across the analysis window.
Demand-supply-balance dynamics across advisory talent pools, certification backlog queues, and OEM procurement cycles structured the analytical framework throughout the modeling period. Segmentation dimensions included service type, application, end user, and delivery model, with CAGRs derived from regression analysis against fleet transition timelines and regulatory deadline clustering. Forecast inputs incorporated digital thread adoption curves and hydrogen propulsion certification pathway announcements from EASA and FAA.
Sensitivities concentrate around ITAR policy shifts, EASA environmental mandate acceleration, and AI-assisted design validation liability framework emergence. Forecasts reflect documented assumptions regarding clearance processing timelines and OEM procurement centralization trends. Material shifts in dual-use technology classification boundaries or space launch licensing harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
Artificial Intelligence in Space Market
Aerospace & Defense AI
AI in Aviation Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market