
 Tilt Rotor Aircraft Market | 2026-2036
Tilt Rotor Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Tilt Rotor Aircraft Market Intelligence
Defense contractors is reorganizing tilt rotor procurement priorities around long-range assault and distributed maritime operations. Bell Textron Inc. leverages decades of V-22 Osprey production experience to sustain its position in heavy-lift military variants. Boeing anchors the segment through its partnership in the V-22 program and ongoing next-generation development. Leonardo S.p.A. competes with its AW609 civil tilt rotor program, targeting executive transport and offshore energy missions.
A tilt rotor aircraft combines helicopter vertical takeoff and landing capability with fixed-wing cruise efficiency through rotors that pivot from horizontal to vertical orientation, typically achieving cruise speeds exceeding 250 knots and service altitudes above 25,000 feet. The primary purpose spans military assault transport, search and rescue, and emerging urban air mobility where runway independence creates operational flexibility. Military applications dominate current procurement volumes given established defense budgets and proven combat utility, while commercial segments face longer certification timelines. Turbine technology leads installed propulsion systems, though hybrid and electric architectures attract development investment for noise reduction and fuel efficiency gains.
FAA powered-lift certification standards govern US market entry, while EASA maintains parallel requirements under its tilt rotor specific airworthiness code. Military procurement flows through NAVAIR and the Joint Program Office, creating dual regulatory exposure for suppliers serving both civil and defense channels. Stakeholders must monitor FAA final rulemaking on powered-lift pilot training and operational requirements, as these standards will determine commercial viability timelines and fleet economics for new entrants.
Market Dynamics
The tilt rotor aircraft market pivots on FAA powered-lift certification pathways that compress development timelines for hybrid-electric architectures while extending validation periods for conventional turbine platforms. This regulatory bifurcation is redistributing R&D budgets toward noise-reduction technologies and urban air mobility configurations.
Growth Catalysts
- EU Green Deal aviation emissions standards:Stringent carbon intensity thresholds for powered-lift aircraft are accelerating investment in hybrid propulsion architectures. Operators in European offshore energy sectors are pre-ordering compliant platforms to secure fleet renewal slots.
- Expeditionary logistics missions:Military procurement for distributed maritime operations is expanding tilt rotor deployment beyond traditional assault transport. The US Marine Corps is prioritizing long-range payload capacity for Pacific theater requirements.
- Urban air mobility infrastructure:NASA research programs and vertiport development in Texas and California are creating certified operational corridors. Municipal transit authorities are evaluating tilt rotor configurations for inter-city passenger services.
Market Restraints
- Turbine engine supply concentration:Propulsion system manufacturing clusters in the United States and United Kingdom create single-source vulnerability for international programs. Geopolitical friction is extending lead times for critical components.
- FAA powered-lift pilot training requirements:Pending final rulemaking on type certification and operational qualifications is freezing commercial investment decisions. Insurers are withholding coverage pending regulatory clarity.
- Helicopter substitution economics:Mature rotary-wing platforms with established maintenance networks and lower acquisition costs retain market share in search and rescue and executive transport segments.
Strategic Opportunities
- Offshore energy logistics:North Sea and Gulf of Mexico oil platform operators are evaluating civil tilt rotor configurations to replace aging helicopter fleets for crew rotation missions. Range and speed advantages reduce personnel transit time.
- Hybrid-electric convergence:Battery density improvements and turbine-electric hybrid architectures are converging to enable 50% noise reduction in terminal areas. Urban air mobility developers are prioritizing this configuration for community acceptance.
- Japan urban air mobility corridors:METI funding for Osaka-Kobe vertiport networks and regulatory sandbox exemptions are creating early-mover advantages for powered-lift certification. Domestic aerospace suppliers are seeking foreign platform partnerships.
Industry Challenges
- Powered-lift flight control engineering:The transition envelope between helicopter and fixed-wing modes demands specialized aerodynamic modeling expertise. Workforce pipelines for this hybrid skill set remain underdeveloped.
- Dual-use certification complexity:Suppliers serving both NAVAIR military channels and FAA civil pathways face conflicting documentation standards and audit protocols. Compliance costs are compressing margins for mid-tier component manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tilt Rotor Aircraft Market |
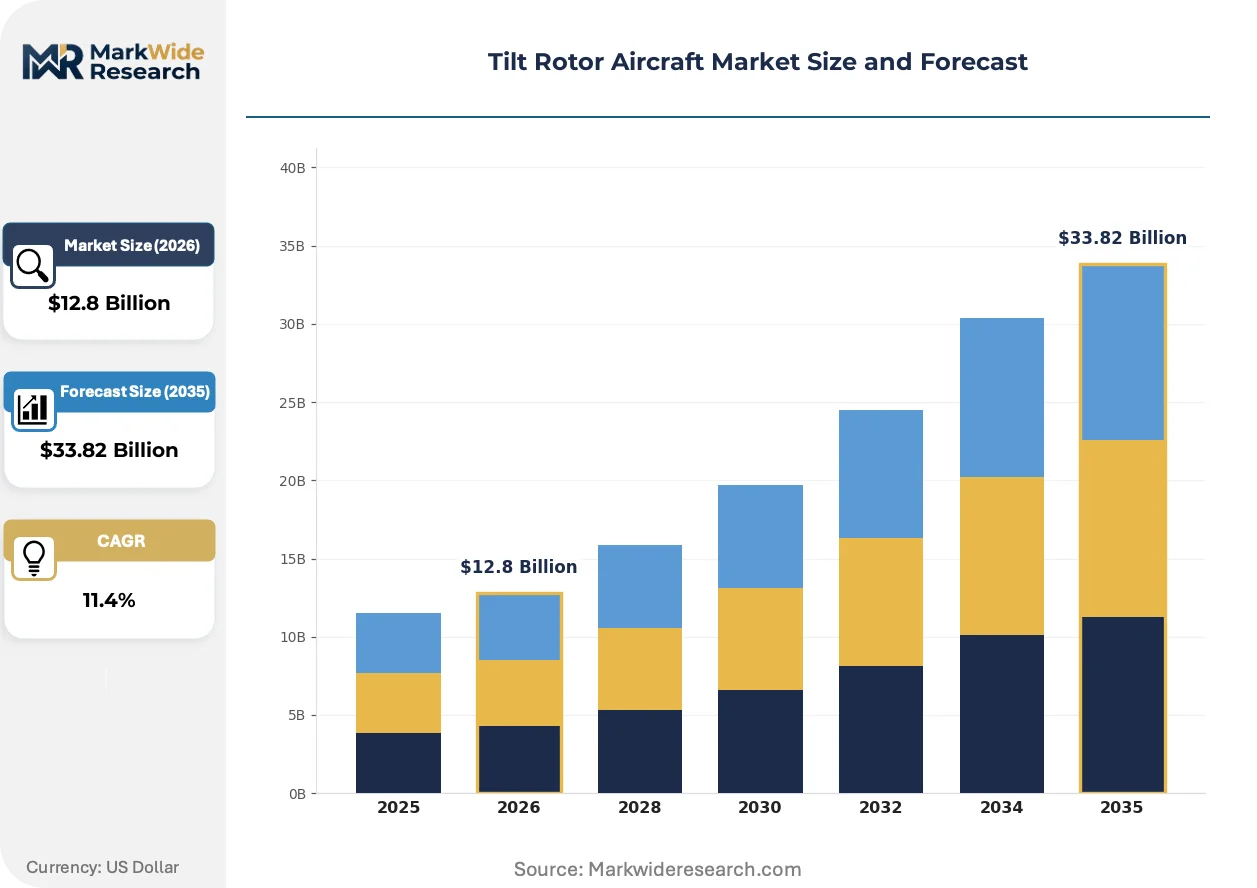
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Military, Commercial, Civil, Search and Rescue Technology: Hybrid, Electric, Turbine, Turbo-shaft End User: Government, Private Operators, Emergency Services, Defense Contractors Application: Aerial Surveillance, Logistics, Transport, Medical Evacuation |
| Companies Covered | Bell Textron Inc., Boeing, Leonardo S.p.A., Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems, GE Aviation Systems, AgustaWestland, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tilt Rotor Aircraft Market Strategic Shifts & Innovations
Propulsion architecture miniaturization is converging with digital flight control advances to reshape platform economics. Certification frameworks are adapting to accommodate hybrid systems while preserving safety margins established through decades of military operations.
Integrated motor-rotor units are miniaturizing. These compact electromechanical systems replace mechanical linkages with distributed electric actuation, reducing maintenance intervals and part counts. Urban air mobility developers in California and Texas are flight-testing these configurations for 2027 service entry. The technology is miniaturizing powertrain footprints, enabling four-rotor layouts previously impractical for manned aircraft.
REACH chemical substance restrictions are extending to aerospace manufacturing supply chains. EASA alignment with these protocols is mandating alternative materials for rotor blade composites and hydraulic fluids. European tilt rotor programs are reformulating resin systems and lubricants to maintain airworthiness certification. Suppliers in Germany and France are accelerating qualification timelines for compliant substitutes.
Defense procurement is consolidating requirements around multi-mission modularity. The US Marine Corps and UK Royal Navy are specifying reconfigurable cabin architectures for assault, medical evacuation, and cargo missions within single airframes. Platform economics now favor versatility over specialized variants. This pattern concentrates in Anglo-American procurement channels where joint operational requirements dominate fleet planning.
Tilt Rotor Aircraft Market Segmentation
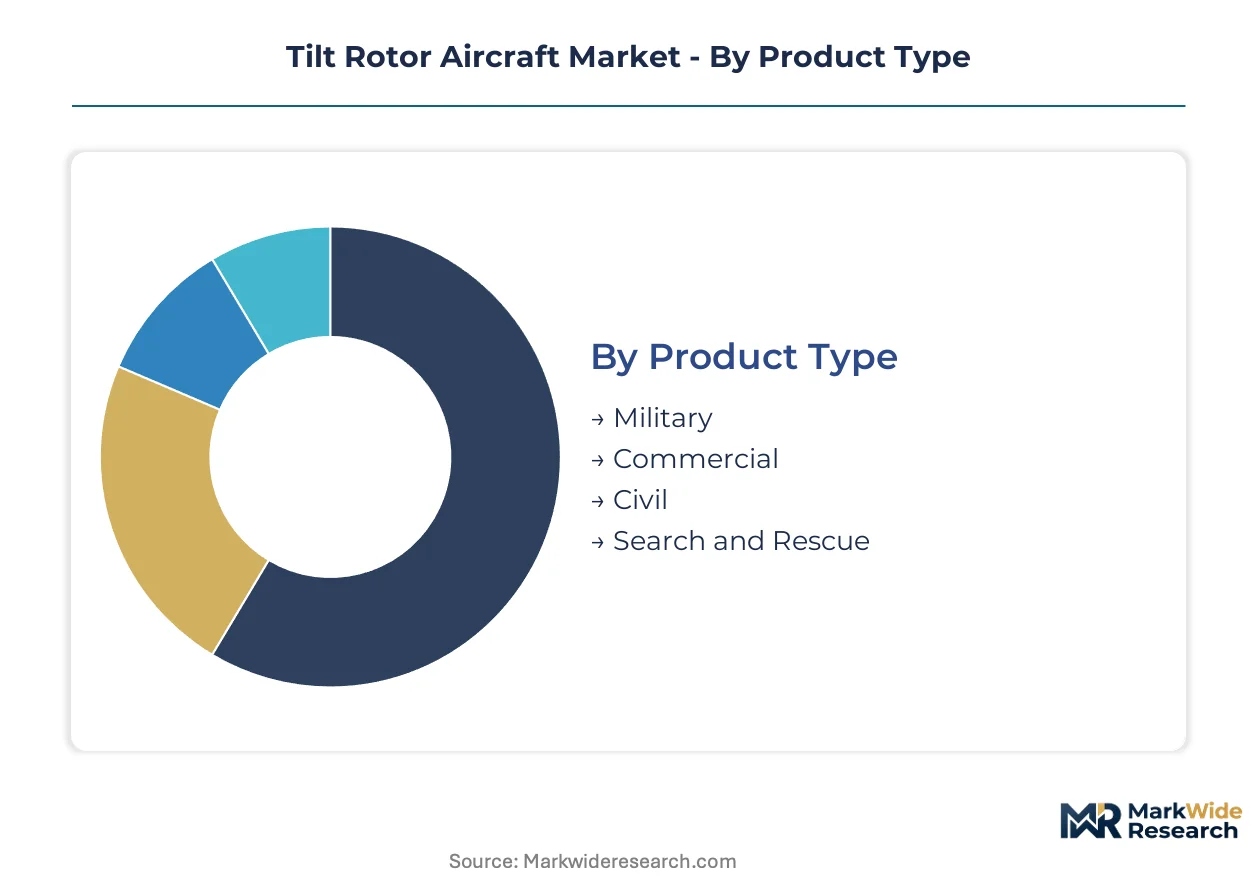
Tilt rotor aircraft segmentation reveals divergent certification burdens and operational economics across mission profiles. Military platforms leverage established NAVAIR procurement channels, while commercial categories navigate unresolved FAA powered-lift standards.
Product Type:
Military configurations face limited substitution pressure from conventional helicopters due to payload-range requirements in Pacific theater operations, whereas commercial segments confront aggressive competition from mature rotary-wing platforms with lower acquisition costs.
- Military:Heavy-lift variants integrate reconfigurable cabin architectures for assault, medical evacuation, and cargo missions. US Marine Corps procurement anchors demand through distributed maritime operations requirements, with long-range payload capacity prioritized for expeditionary logistics.
- Commercial:Executive transport configurations target offshore energy crew rotation missions in the North Sea and Gulf of Mexico. FAA powered-lift certification delays and insurer coverage freezes constrain fleet investment decisions pending final rulemaking.
- Civil:Leonardo's AW609 program dominates this segment with twin-engine executive layouts.
- Search and Rescue:Mature helicopter fleets with established maintenance networks retain market share in this application.
Military retains volume leadership; commercial holds the steepest expansion curve once certification pathways clarify.
Technology:
Cost tier stratification separates proven turbine architectures from developmental electric systems, with hybrid configurations occupying a transitional price-performance position attracting urban air mobility investment.
- Hybrid:Turbine-electric architectures converge battery density improvements with conventional propulsion for 50% noise reduction in terminal areas. California and Texas developers prioritize this configuration for community acceptance and vertiport corridor access.
- Turbine:Established turbo-shaft systems power current military fleets through concentrated US and UK manufacturing clusters. Geopolitical friction extends lead times for critical components, creating supply vulnerability for international programs.
- Electric:Battery density limitations restrict pure-electric configurations to short-range urban demonstrations.
- Turbo-shaft:Mechanical simplicity sustains this architecture in heavy-lift military applications.
Turbine dominates current installed base; hybrid is climbing the fastest toward commercial service entry.
End User:
Customer type concentration varies sharply, with defense contractors capturing multi-airframe procurement volumes while private operators remain sidelined by certification uncertainty.
- Defense Contractors:Bell Textron and Boeing sustain production through V-22 program continuity and next-generation development. NAVAIR procurement flows and Joint Program Office specifications create stable demand visibility absent in civil channels.
- Government:NASA urban air mobility research programs and municipal transit authority evaluations in Texas and California generate experimental demand for powered-lift corridor development.
- Emergency Services:Helicopter substitution economics delay tilt rotor adoption in this segment.
- Private Operators:Insurer coverage withholding pending FAA clarity freezes investment decisions.
Defense contractors retain volume leadership; government holds the steepest expansion curve through research program scaling.
Application:
Mission maturity separates combat-proven transport roles from emerging surveillance configurations, with medical evacuation occupying an intermediate position shaped by modularity requirements.
- Transport:Long-range assault and logistics missions dominate current fleet utilization. US Marine Corps Pacific theater requirements prioritize payload capacity and runway independence for distributed maritime operations.
- Medical Evacuation:Reconfigurable cabin specifications from Anglo-American procurement channels favor multi-mission airframes. UK Royal Navy requirements integrate medical modules with assault and cargo capabilities within single platforms.
- Logistics:Offshore energy crew rotation drives civil evaluation in the Gulf of Mexico.
- Aerial Surveillance:Sensor integration complexity limits deployment in current procurement cycles.
Transport retains volume leadership; medical evacuation gains share fastest through multi-mission modularity specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense procurement anchors global tilt rotor demand, with NAVAIR contracts flowing to domestic manufacturers who export subsystems to allied militaries in Japan and the United Kingdom. FAA powered-lift certification pathways determine commercial market entry timelines across all importer geographies.
United States
US Marine Corps Pacific theater requirements drive heavy-lift procurement through distributed maritime operations specifications. FAA final rulemaking on powered-lift pilot training standards shapes commercial investment decisions nationwide. Texas and California vertiport development clusters anchor NASA urban air mobility research programs.
Japan
METI funding for Osaka-Kobe urban air mobility corridors creates early-mover regulatory sandbox opportunities. The country's civil aviation regulator coordinates powered-lift certification exemptions with foreign platform developers. Domestic aerospace suppliers in the Kansai region seek international partnerships for tilt rotor component manufacturing.
United Kingdom
UK Royal Navy multi-mission modularity specifications integrate medical evacuation with assault transport requirements. EASA alignment with REACH chemical restrictions mandates alternative materials for rotor blade composites. Aerospace manufacturing clusters in the Southwest concentrate on reconfigurable cabin architectures.
Italy
Leonardo's AW609 civil program targets executive transport and offshore energy missions from Italian manufacturing bases. EU Green Deal aviation emissions standards accelerate hybrid propulsion investment timelines. The Campania aerospace corridor concentrates tilt rotor development expertise for European certification pathways.
Germany
Offshore energy operators in the North Sea evaluate civil tilt rotor configurations for crew rotation missions. EASA powered-lift airworthiness codes govern platform approval timelines for domestic energy sector procurement. Bavarian aerospace suppliers reformulate resin systems to comply with REACH chemical substance restrictions.
Tilt Rotor Aircraft Market Key Industry Players
Player mix skews toward defense-anchored conglomerates with captive aerospace divisions. Market structure concentrates around three production programs serving military procurement channels. Strategic archetypes include turbine propulsion specialists, integrated airframe assemblers, and civil certification pioneers. Competitive moves center on multi-mission modularity specifications and hybrid-electric architecture licensing.
Among US-based defense contractors, Bell Textron Inc. and Boeing occupy positions exemplifying the integrated airframe assembler archetype through sustained V-22 program continuity. Leonardo S.p.A. represents the civil certification pioneer tier with its AW609 development program targeting executive transport applications. These three companies anchor the competitive landscape across divergent regulatory pathways.
| Leading Market Players |
|---|
| Bell Textron Inc. |
| Boeing |
| Leonardo S.p.A. |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| GE Aviation Systems |
| AgustaWestland |
| Kawasaki Heavy Industries |
| Others |
Cost & Logistics Intelligence
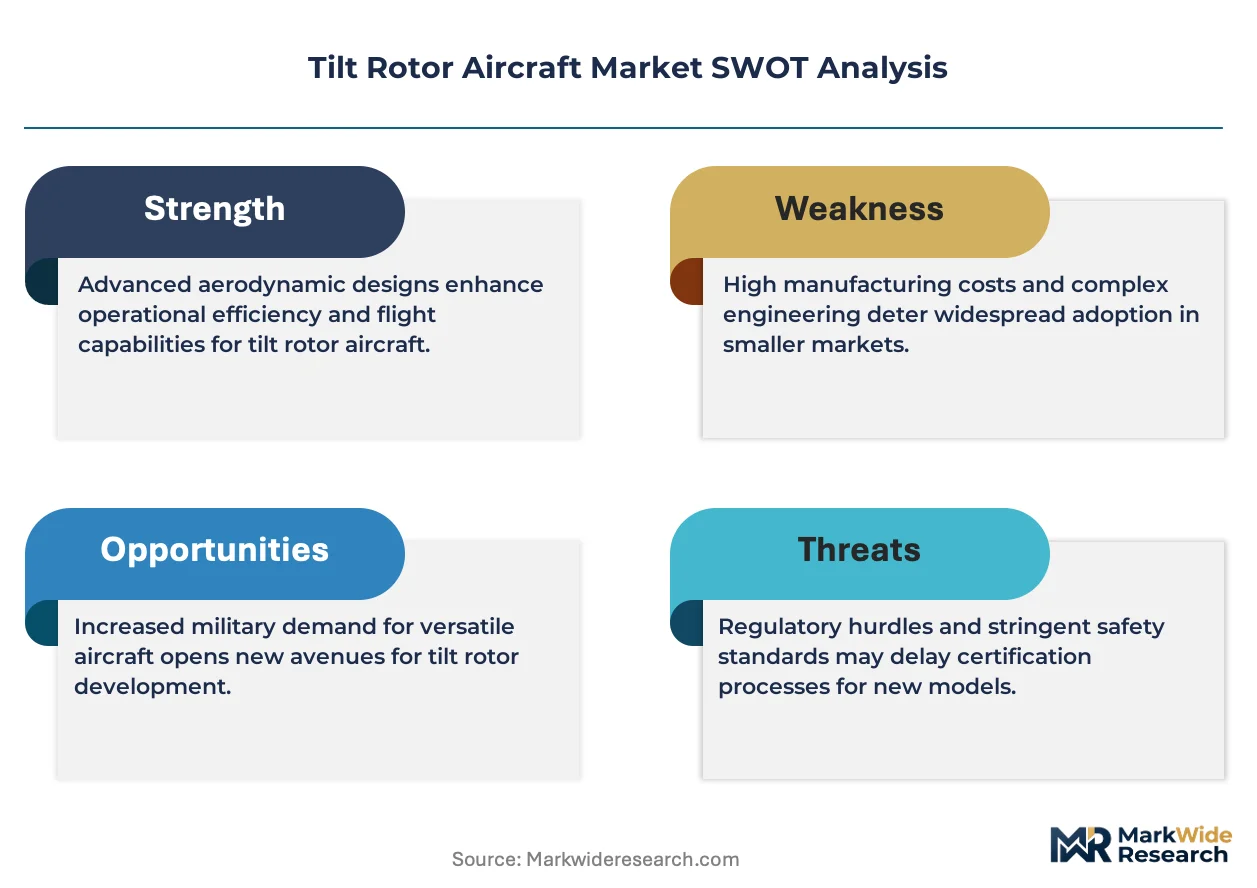
FAA powered-lift certification standards gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified vendors while awarding premium positioning to airframe assemblers with validated military production histories. This regulatory architecture concentrates pricing power among defense-anchored incumbents who can amortize compliance costs across multi-airframe procurement volumes.
Pricing Analysis
Turbine-to-hybrid technology-generation pricing gaps separate established military platforms from developmental electric architectures, with hybrid configurations occupying a transitional cost tier attracting urban air mobility investment. Three-tier pricing structure across certified-military, developmental-civil, and experimental-electric levels reflects certification burden and production scale differentials. Cost compression in developmental tiers intensifies because battery density improvements and distributed manufacturing erode first-mover hardware advantages. Defense contractors exhibit lowest price sensitivity given mission-critical requirements and NAVAIR procurement stability, while private operators and municipal transit authorities remain sidelined pending FAA clarity on operational qualifications.
Supply Chain Analysis
The United States and United Kingdom anchor turbine propulsion manufacturing, with concentrated turbo-shaft production clusters in Connecticut and Southwest England feeding military assembly lines. Rotor blade composites draw from German and French resin formulation specialists, while flight control avionics rest on semiconductor supply chains concentrated in Taiwan and South Korea. Single-source vulnerability runs through concentrated US engine manufacturing, where geopolitical friction extends component lead times for international programs. Distribution runs through NAVAIR military procurement channels and FAA-certified civil airworthiness pathways, creating dual-audit exposure for suppliers serving both segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around defense procurement offices with multi-airframe fleet authority, fragmenting price negotiation leverage among commercial operators awaiting certification clarity.
For Market Incumbents: Compound defensive positioning through captive control over powered-lift flight control engineering talent pools and NAVAIR relationship continuity. Vertical integration into rotor blade composite manufacturing mitigates REACH chemical restriction compliance costs. Certification investment in hybrid-electric architectures preserves optionality against pure-electric entrant disruption. For New Entrants and Emerging Players: FAA powered-lift pilot training rulemaking finalization creates a certification fast-track window for urban air mobility configurations in Texas and California vertiport corridors. Underpenetrated offshore energy crew rotation in the Gulf of Mexico offers lowest competitive density. Partnership with Japanese domestic aerospace suppliers in the Kansai region accelerates METI sandbox access for Osaka-Kobe corridor entry. For Investors and Strategic Acquirers: FAA final rulemaking on powered-lift operational requirements reshapes the acquisition landscape by clarifying commercial viability timelines and insurability thresholds. Long-term viability favors airframe assemblers with dual-use military-civil certification capabilities and hybrid propulsion optionality. The signal to watch is EASA alignment with EU Green Deal aviation emissions standards accelerating compliant platform pre-orders from North Sea energy operators.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Architecture Licensing | Turbine-electric convergence enables 50% noise reduction for community acceptance in urban corridors. |
| Multi-Mission Modularity Specification | Reconfigurable cabin architectures concentrate Anglo-American procurement around versatile single-airframe platforms. |
| Vertiport Infrastructure Partnership | Texas and California corridor development anchors NASA urban air mobility research program scaling. |
| REACH Chemical Compliance Acceleration | EASA-aligned resin reformulation preserves European airworthiness certification for rotor blade suppliers. |
| Powered-Lift Pilot Training Investment | FAA rulemaking clarity unlocks insurer coverage and commercial fleet investment decisions. |
Research Approach
Findings reconcile primary fieldwork against secondary review of NAVAIR procurement disclosures, FAA docket filings on powered-lift rulemaking, EASA airworthiness code documentation, and EU Green Deal aviation emissions implementation guidance. Primary interviews with V-22 program engineers, tilt rotor certification specialists at Leonardo, vertiport infrastructure planners in Texas and California, and offshore energy logistics procurement managers in the North Sea and Gulf of Mexico informed demand-side validation. Secondary sources include SEC 10-K aerospace segment disclosures, METI urban air mobility funding announcements, and REACH chemical substance restriction aerospace supply chain guidance. Bottom-up platform economics modeling triangulates against top-down defense budget appropriation analysis.
Segmentation dimensions modeled span product type (military, commercial, civil, search and rescue), technology architecture (turbine, hybrid, electric, turbo-shaft), end user category (defense contractors, government, emergency services, private operators), and application mission (transport, medical evacuation, logistics, aerial surveillance) across the analysis window. CAGRs derive from airframe delivery projections weighted by unit economics and aftermarket service attach rates. Industry-specific forecast inputs include battery density improvement curves for hybrid-electric configurations and NAVAIR distributed maritime operations procurement cycle timing.
The analysis sits within stated boundaries; outcomes outside FAA powered-lift certification finalization, EASA emissions standard enforcement timelines, or sustained defense appropriation levels would require recalibration. Forecasts reflect documented assumptions on technology maturation, regulatory pathway clarity, and military procurement continuity. Specific risk factors include turbine engine supply concentration vulnerability, REACH chemical restriction acceleration, and vertiport infrastructure deployment delays. Recalibration cycles align with material shifts in FAA rulemaking, EU Green Deal implementation, and USMC Pacific theater force structure announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Aeronautic Propeller Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Search and Rescue Aircraft Market
Aircraft
Global Aircraft Tugs Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
US Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
North America General Aviation Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
Aircraft Cargo Container Market