
 Naval ISR Market | 2026-2036
Naval ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Naval ISR Market Outlook
Buyer concentration among sovereign naval fleets is expanding as defense procurement consolidates under national security priorities and alliance-funded modernization pools. BAE Systems Plc leverages its underwater warfare heritage to sustain dominance in towed-array sonar and submarine ISR integration. General Dynamics Corporation anchors its position through the Electric Boat division's control over US Navy Virginia-class payload modules. Lockheed Martin Corporation differentiates via Aegis combat system architectures that embed multi-domain sensor fusion for surface fleet commanders.
Naval intelligence, surveillance, and reconnaissance encompasses the integrated collection, processing, and dissemination of tactical and strategic information from maritime platforms, employing sensor payloads operating across acoustic, electromagnetic, and electro-optical spectra with detection ranges extending from coastal littorals to open-ocean depths. Its primary purpose enables real-time battlespace awareness, threat identification, and precision targeting for naval task forces operating in contested environments. Radar Systems technology leads current platform retrofit cycles as navies prioritize multi-function phased arrays for anti-ship missile defense and air search. Unmanned Aerial Vehicles represent the fastest-expanding system type as drone mothership concepts aboard destroyers and amphibious vessels mature. Integrated Software captures concentrated margin pools where artificial intelligence-enabled sensor correlation and automated track management replace legacy manual fusion workflows.
The US Navy's Program Executive Office for Integrated Warfare Systems and the UK Ministry of Defence's Defence Equipment and Support directorate shape demand through mandated open-architecture standards and interoperability certification for allied fleet integration. NATO's Maritime Unmanned Systems Initiative establishes common data-link protocols that determine market access for non-compliant subsystem vendors. Stakeholders must monitor how AUKUS technology-sharing agreements and evolving undersea cable protection mandates redistribute procurement authority across national defense industrial bases.
Market Dynamics
Distributed maritime operations doctrine is compressing sensor procurement timelines as NATO navies mandate interoperable open-architecture suites for allied task force integration.
Growth Catalysts
- PESCO Maritime Surveillance Framework:EU defense ministers pool procurement budgets for shared ISR capabilities, creating consolidated demand for multi-national platform integration.
- Undersea Cable Protection Mandates:Critical infrastructure security directives from coastal states accelerate towed-array sonar and autonomous underwater vehicle procurement for seabed monitoring.
- Acoustic Sensor Fusion:Machine learning-enabled signal processing reduces operator workload while expanding detection ranges against quiet diesel-electric submarines.
Market Restraints
- Specialized Alloy Supply Concentration:High-performance nickel-titanium alloys for hydrophone arrays source from limited European and Japanese suppliers, creating input vulnerability.
- ITAR Classification Barriers:US State Department export controls restrict subsystem transfer to non-allied navies, fragmenting addressable demand pools.
- Platform Integration Complexity:Legacy combat management systems on mid-life frigates resist seamless sensor data ingestion without costly middleware development.
Strategic Opportunities
- Japan Defense Buildup:Tokyo's counter-strike capability investments open demand for next-generation submarine ISR and surface fleet distributed sensor networks.
- AI-Enabled Track Correlation:Convergence of edge computing architectures with synthetic aperture sonar is absorbing manual analyst functions into automated contact classification workflows.
- Drone Mothership Concepts:Amphibious assault ships and destroyers deploy as unmanned aerial vehicle carriers, creating new payload module specifications for ISR-optimized rotary-wing drones.
Industry Challenges
- Submarine Sonar Technician Shortage:Acoustic intelligence analysis requires specialized training pipelines that naval recruitment struggles to fill at fleet expansion rates.
- Open-Architecture Certification Delays:NATO's interoperability validation protocols extend subsystem qualification timelines, compressing prime contractor margin recovery windows.
- Legacy System Integration Friction:Aegis combat system baselines on older cruisers demand expensive hardware refresh cycles to host modern multi-function radar arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval ISR Market |
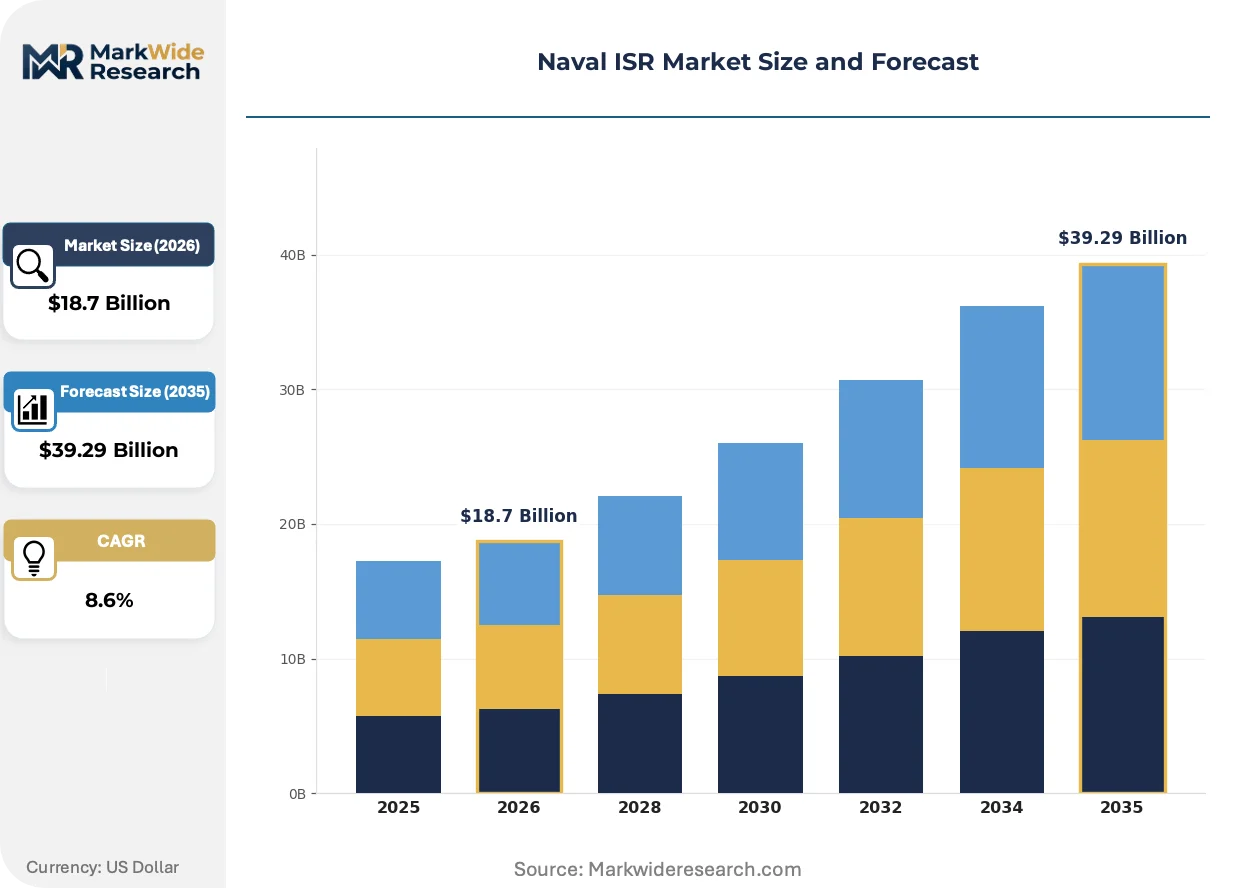
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Unmanned Aerial Vehicles, Surface Ships, Submarines, Ground Stations Technology: Electro-Optical Sensors, Radar Systems, Communication Systems, Integrated Software End User: Naval Forces, Coast Guard, Defense Contractors, Research Institutions Application: Surveillance, Intelligence Gathering, Reconnaissance, Target Tracking |
| Companies Covered | BAE Systems Plc, General Dynamics Corporation, Lockheed Martin Corporation, L3Harris Technologies Inc., Thales Group, Atlas Elektronik GmbH, Northrop Grumman Corporation, Leonardo DRS, Raytheon Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval ISR Market Strategic Shifts
Maritime ISR platforms are absorbing software-defined radio architectures that collapse multiple single-purpose sensors into reconfigurable payload suites, altering fleet upgrade economics.
Synthetic aperture sonar is absorbing high-resolution seabed mapping functions previously requiring dedicated survey vessels. Royal Australian Navy AUKUS submarine programs deploy these payloads for continuous bathymetric data collection. The technology is absorbing capital expenditure from standalone oceanographic ships into combatant hulls.
EU AI Act classification rules for high-risk autonomous systems impose algorithmic transparency requirements on unmanned maritime platforms. Naval procurement offices now mandate explainable AI documentation for track management software. European shipyards delay unmanned surface vessel deliveries to achieve compliance certification.
Fleet buyers consolidate sensor procurement under sovereign capability funds rather than individual platform line items. Australia's AUKUS submarine commitments and Britain's Dreadnought-class programs bundle ISR subsystem acquisition into decade-long industrial partnerships. Defense ministries in Tokyo and Seoul replicate this model for indigenous destroyer construction programs.
Naval ISR Market Segmentation
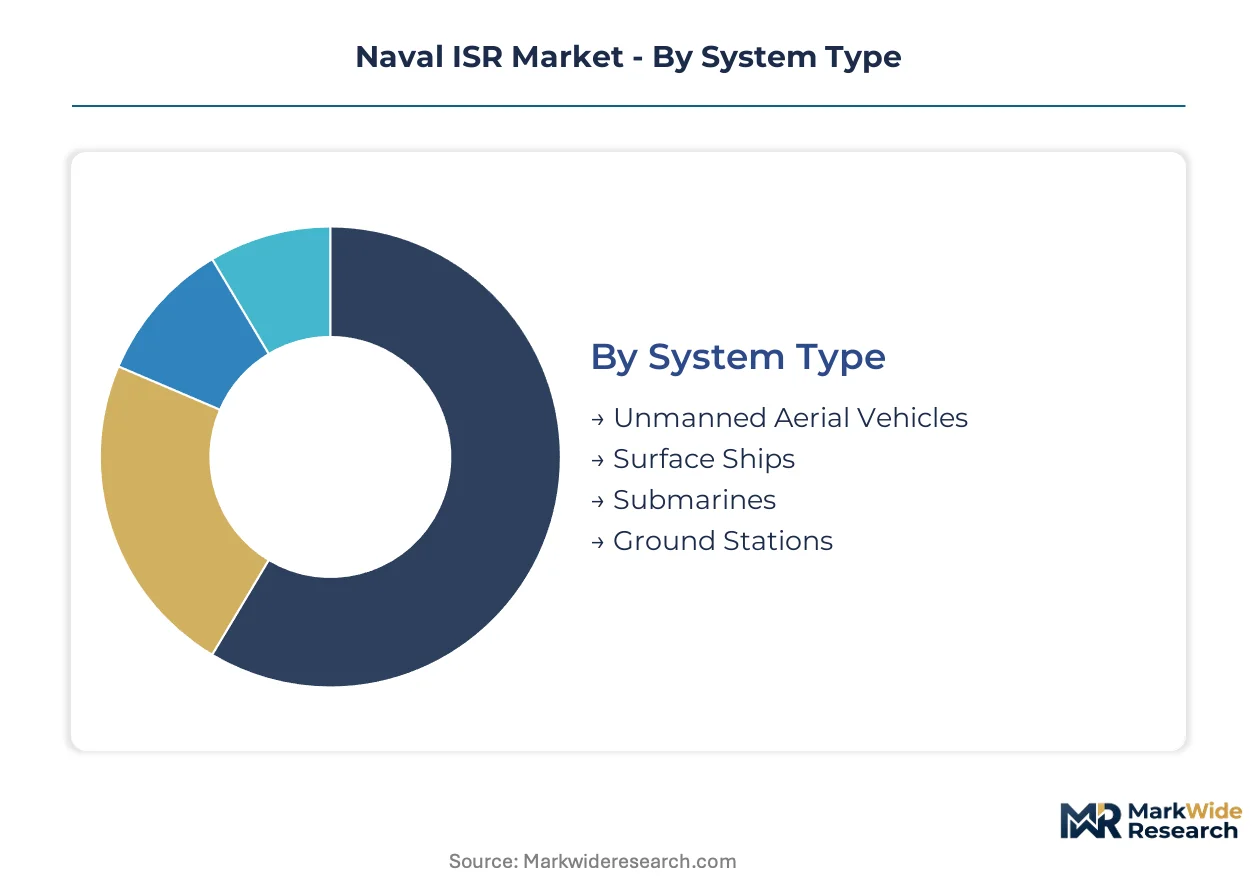
Naval ISR procurement patterns diverge sharply across operational domains, with platform constraints and mission profiles dictating sensor payload specifications. Buyers prioritize integration depth over standalone capability, compressing vendor selection criteria toward open-architecture compliance.
System Type:
Platform selection hinges on endurance requirements and threat environment, with unmanned systems displacing crewed assets in high-risk littoral zones.
- Unmanned Aerial Vehicles:Rotary-wing and fixed-wing drones operating from destroyer flight decks and amphibious assault ships provide over-the-horizon targeting data. Demand concentrates in the Indo-Pacific, where Japan's defense buildup funds carrier-based ISR drone procurement for distributed maritime operations.
- Surface Ships:Multi-function phased array radars and towed sonar arrays on frigates and destroyers form the backbone of allied task force situational awareness. NATO's Permanent Structured Cooperation framework pools procurement for interoperable sensor suites across European fleets.
- Submarines:Virginia-class payload modules and AUKUS submarine programs deploy synthetic aperture sonar for seabed warfare missions.
- Ground Stations:Shore-based fusion centers process acoustic intelligence from undersea sensor networks.
Volume sits with Surface Ships; growth tilts toward Unmanned Aerial Vehicles.
Technology:
Technology selection tracks mission-critical performance thresholds, with software architectures capturing disproportionate margin pools through recurring upgrade cycles.
- Radar Systems:Active electronically scanned arrays deliver simultaneous air search, surface tracking, and missile defense functions from common aperture hardware. US Navy Arleigh Burke-class modernization programs prioritize AN/SPY-6 radar backfits for extended detection ranges against hypersonic threats.
- Integrated Software:Artificial intelligence-enabled track correlation algorithms automate contact classification and reduce operator cognitive load. Australia's AUKUS commitments mandate explainable AI documentation for submarine combat system upgrades, extending procurement timelines for algorithm validation.
- Electro-Optical Sensors:Multi-spectral cameras and laser rangefinders provide passive identification at standoff distances.
- Communication Systems:Software-defined radio architectures collapse multiple waveforms into reconfigurable payload suites.
Revenue concentrates in Integrated Software; capability gaps persist in Communication Systems interoperability.
End User:
End user procurement authority reflects sovereign capability priorities, with national naval fleets retaining direct control over combat system integration.
- Naval Forces:Sovereign fleets specify sensor performance requirements and mandate open-architecture standards for allied interoperability. The US Navy's Program Executive Office for Integrated Warfare Systems enforces Common Data Link protocols that determine subsystem market access.
- Coast Guard:Maritime law enforcement agencies prioritize surface search radar and electro-optical packages for exclusive economic zone patrol. Undersea cable protection mandates accelerate towed-array procurement for seabed infrastructure monitoring.
- Defense Contractors:Prime integrators bundle ISR subsystems into platform-level deliverables under decade-long industrial partnerships.
- Research Institutions:Academic and government laboratories prototype acoustic signal processing algorithms for transition to operational systems.
Procurement volume aggregates under Naval Forces; Coast Guard requirements are expanding most quickly.
Application:
Application segmentation tracks the intelligence cycle, with real-time dissemination demands reshaping sensor-to-shooter latency requirements.
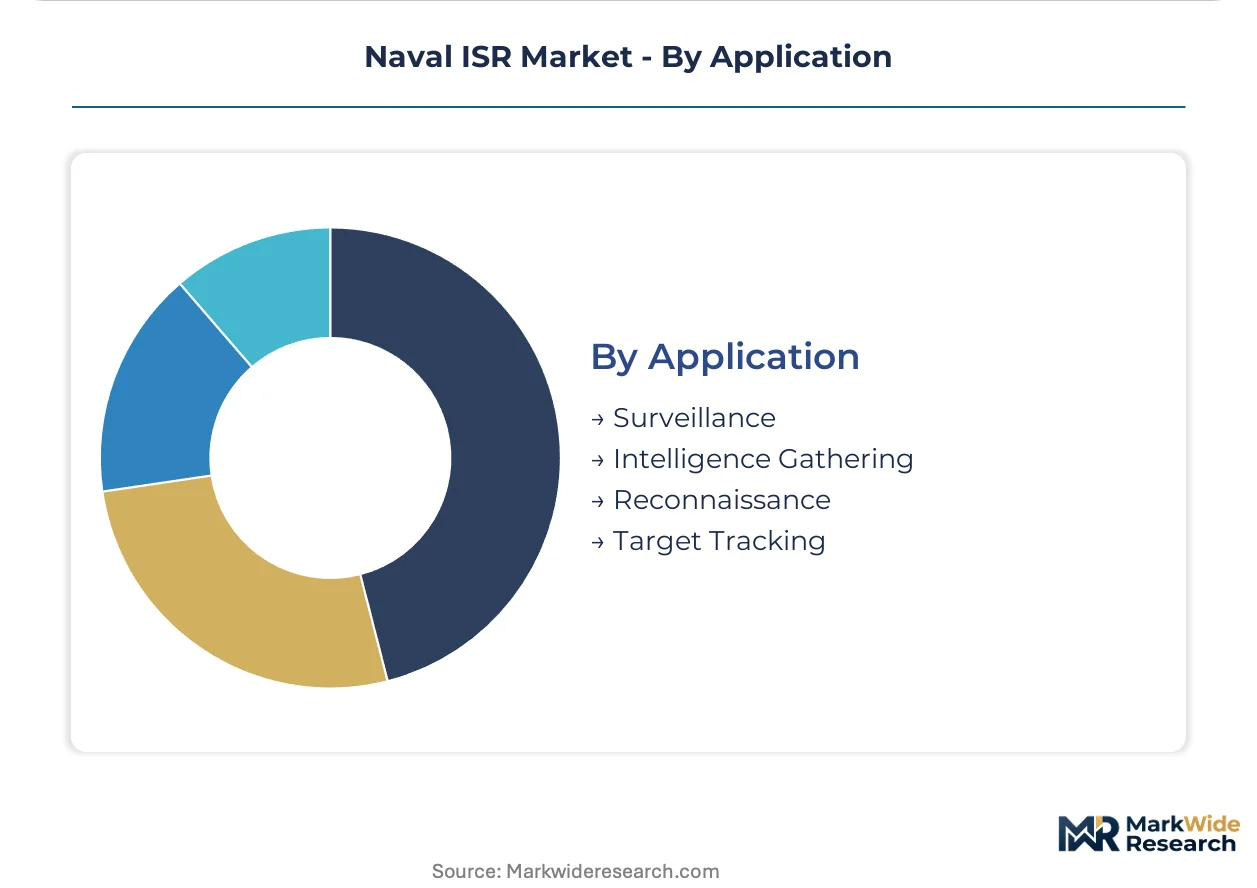
- Surveillance:Persistent area coverage missions employ unmanned surface vessels and aerostats for chokepoint monitoring. EU defense ministers pool PESCO funding for shared Mediterranean surveillance capabilities.
- Intelligence Gathering:Signals intelligence and electronic warfare payloads intercept adversary communications and radar emissions. AUKUS technology-sharing agreements redistribute signals intelligence procurement authority across US, UK, and Australian industrial bases.
- Reconnaissance:Time-sensitive targeting missions require rapid sensor tasking and cross-cueing between platforms.
- Target Tracking:Fire control quality solutions enable over-the-horizon missile engagements.
Operational tempo favors Surveillance; capability investment tilts toward Intelligence Gathering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Naval ISR procurement concentrates in sovereign defense budgets aligned with alliance commitments. The United States, United Kingdom, Japan, Australia, and France absorb dominant platform investment volumes through submarine modernization and surface fleet distributed sensor networks.
United States
Virginia-class payload modules and Arleigh Burke-class radar modernization programs drive multi-billion-dollar sensor procurement. The US Navy's Program Executive Office for Integrated Warfare Systems mandates open-architecture standards that determine subsystem vendor eligibility. Electric Boat facilities in Groton, Connecticut and Huntington Ingalls in Newport News, Virginia anchor submarine ISR integration capacity.
United Kingdom
Dreadnought-class ballistic missile submarine programs consolidate decade-long industrial partnerships for combat system delivery. The Ministry of Defence's Defence Equipment and Support directorate enforces interoperability certification for allied fleet integration. Barrow-in-Furness shipyards concentrate synthetic aperture sonar payload integration for AUKUS technology-sharing commitments.
Japan
Counter-strike capability investments accelerate demand for next-generation submarine ISR and surface fleet distributed sensor networks. METI defense production guidelines channel procurement toward indigenous shipyard capacity. Mitsubishi Heavy Industries in Yokohama and Kobe anchor domestic combat system integration for destroyer and submarine programs.
Australia
AUKUS submarine commitments bundle ISR subsystem acquisition into sovereign capability funds spanning multi-decade industrial partnerships. TGA-equivalent defense certification requirements extend algorithm validation timelines for AI-enabled track management software. Osborne Naval Shipyard in South Australia concentrates hull construction and combat system integration for nuclear-powered submarine delivery.
France
Suffren-class nuclear attack submarine programs sustain domestic sonar and electronic warfare payload production. ANSM-equivalent defense procurement regulations mandate algorithmic transparency for autonomous maritime systems under EU AI Act alignment. Naval Group facilities in Cherbourg and Lorient anchor submarine combat system integration for domestic and export programs.
Naval ISR Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue unmanned platform specialization and AI-enabled software modules. The vendor base stratifies across prime integrators controlling platform-level contracts and subsystem specialists delivering sensor payloads under open-architecture mandates. Three archetypes dominate: sovereign defense champions with state equity stakes, diversified aerospace-electronics conglomerates leveraging cross-domain technology transfer, and niche acoustic sensor houses with hydrophone array heritage. Competitive moves center on decade-long industrial partnerships bundling ISR procurement into sovereign capability funds, and strategic technology licensing to achieve NATO interoperability certification.
Among UK-based defense champions, BAE Systems Plc and Thales Group exemplify the sovereign-anchored archetype with multi-decade submarine and surface combatant integration legacies. Lockheed Martin Corporation occupies a position representing the US prime integrator tier, with Aegis combat system architectures embedding multi-domain sensor fusion. Atlas Elektronik GmbH anchors the specialized acoustic sensor house category, with German GmbH structure indicating focused undersea warfare payload development.
| Leading Market Players |
|---|
| BAE Systems Plc |
| General Dynamics Corporation |
| Lockheed Martin Corporation |
| L3Harris Technologies Inc. |
| Thales Group |
| Atlas Elektronik GmbH |
| Northrop Grumman Corporation |
| Leonardo DRS |
| Raytheon Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Allied fleet open-architecture mandates are compressing subsystem qualification timelines and forcing prime contractors to absorb middleware development costs that were previously passed through to naval procurement offices. This specification shift is redistributing pricing power toward sovereign defense champions with captive integration capacity, while fragmenting margins for component specialists facing NATO interoperability certification delays.
Pricing Analysis
Volume concentrates in surface ship multi-function radar retrofits where contract-based long-term offtake agreements dominate; margins pool in integrated software where AI-enabled track correlation commands recurring upgrade revenue. Price differentiation rests on certification grade—NATO Common Data Link compliance versus national-standard systems—and customization depth for legacy combat management system integration. Cost compression in hardware tiers is intensifying because software-defined radio architectures collapse multiple single-purpose sensors into reconfigurable suites, eroding standalone sensor premiums. Coast Guard maritime law enforcement agencies exhibit highest price sensitivity due to exclusive economic zone patrol budget constraints; nuclear submarine programs show lowest sensitivity given sovereign capability fund insulation.
Supply Chain Analysis
Domestic-content mandates from Australia's AUKUS industrial partnership requirements and Japan's METI defense production guidelines are reshaping sourcing patterns toward sovereign shipyard clusters. Geographic supply concentration centers on the United States, United Kingdom, and Japan for combat system integration; Germany and France anchor specialized acoustic sensor production. Raw material dependencies draw from limited European and Japanese suppliers for high-performance nickel-titanium hydrophone alloys, plus gallium nitride substrates for active electronically scanned arrays. Single-source vulnerability in specialized alloy feedstock creates input bottleneck risk. Distribution runs through prime integrator channels—Electric Boat, Naval Group, Mitsubishi Heavy Industries—controlling platform-level procurement authority and subsystem vendor selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Naval ISR procurement is transitioning from hardware-centric sensor suites to software-defined architectures where artificial intelligence-enabled track correlation replaces manual analyst workflows. Synthetic aperture sonar and unmanned aerial vehicle mothership concepts are displacing crewed survey vessels and dedicated ISR aircraft in littoral zone operations.
For Market Incumbents: Extend open-architecture certification pipelines to compress NATO interoperability validation timelines and recover margin compression from middleware development. Lock in decade-long industrial partnerships with Australia's AUKUS sovereign capability funds and Britain's Dreadnought-class programs to defend against emerging entrants pursuing unmanned platform specialization. Prioritize in-house production of AI-enabled sensor fusion software to capture recurring upgrade revenue pools.
For New Entrants and Emerging Players: The gap between premium-tier Aegis-integrated combat systems and economy-tier coast guard surface search packages offers entry leverage. Target Japan's defense buildup for indigenous destroyer ISR subsystem procurement, where METI guidelines favor domestic shipyard partnerships over foreign primes. Pursue drone mothership payload module specifications as the go-to-market angle, positioning rotary-wing ISR drones for amphibious assault ship deployment.
For Investors and Strategic Acquirers: The window for entry favors specialized acoustic sensor houses with hydrophone array heritage and explainable AI software modules achieving EU AI Act compliance. Long-term viability hinges on AUKUS technology-sharing agreement expansion and undersea cable protection mandate proliferation across coastal states. Monitor submarine sonar technician shortage severity as inflection signal—acute personnel gaps will accelerate automated contact classification software procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Track Correlation Development | Automated contact classification absorbs manual analyst functions into edge computing architectures for Virginia-class payload modules. |
| Synthetic Aperture Sonar Integration | High-resolution seabed mapping payloads displace dedicated survey vessels in Royal Australian Navy AUKUS submarine programs. |
| Drone Mothership Payload Certification | Rotary-wing ISR drone specifications for destroyer flight decks create new demand pools in Japan's defense buildup. |
| Open-Architecture Middleware Investment | NATO interoperability validation protocols extend qualification timelines, compressing prime contractor margin recovery windows. |
| Explainable AI Documentation Compliance | EU AI Act algorithmic transparency requirements delay unmanned surface vessel deliveries for European shipyards. |
Study Parameters
Defense procurement databases, NATO Maritime Unmanned Systems Initiative technical specifications, and national defense ministry budget disclosures formed the secondary backbone for market sizing and fleet modernization tracking. Primary interviews with submarine combat system program managers, naval sonar technician training pipeline officers, and prime integrator business development directors validated subsystem procurement timelines and open-architecture compliance requirements. Bottom-up and top-down triangulation cross-referenced platform-level contract awards against component supplier revenue disclosures.
Bottom-up modeling aggregated individual platform procurement—Virginia-class payload modules, Arleigh Burke-class radar backfits, AUKUS submarine commitments—across the projection horizon. Segmentation dimensions included system type, technology category, end user procurement authority, and application mission profile. CAGRs were derived from fleet modernization cycle analysis and sovereign defense budget trajectory assessment. Industry-specific forecast inputs incorporated PESCO maritime surveillance framework funding pools and undersea cable protection mandate proliferation rates.
Inputs from US Navy Program Executive Office for Integrated Warfare Systems and UK Ministry of Defence Defence Equipment and Support were available through the study window; gaps in classified submarine combat system specification details introduce uncertainty bands around synthetic aperture sonar payload adoption timelines. Forecasts reflect assumptions regarding AUKUS technology-sharing agreement implementation pace and EU AI Act enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Asia-Pacific C4ISR Market
ISR
Australia C4ISR Market
ISR
Low Altitude Radar Market
ISR
C5ISR Market
ISR
C4ISR Market
ISR
Europe C5ISR Market
ISR
C6ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
IFF System Market
ISR
United States C4ISR Market
ISR
Land Based C4ISR Market
ISR
Synthetic Aperture Radar (SAR) Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Intelligence Surveillance and Reconnaissance (ISR) Market
ISR
Eastern Europe C4ISR Market
ISR
Air Based C4ISR Market