
 Cloud Directory Services Software Market | 2026-2036
Cloud Directory Services Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Directory Services Software Market Analysis
Capital-intensity divergence between hyperscale platform operators and focused identity vendors is reorganizing competitive dynamics across the sector. Microsoft Corporation leverages its Azure Active Directory integration to anchor enterprise deployments through bundled cloud productivity suites. JumpCloud Inc. competes by specializing in mid-market multi-directory environments that unify on-premises and cloud identity stores without requiring full Microsoft ecosystem commitment.
Cloud directory services software constitutes a centralized identity repository delivered through cloud infrastructure, typically implementing LDAP schemas, REST APIs, and SCIM protocols to authenticate users and authorize resource access across distributed IT environments. The technology serves primarily to eliminate on-premises Active Directory dependencies while enabling single sign-on across SaaS applications, mobile devices, and remote work endpoints. Public cloud deployment models currently dominate volume, though hybrid cloud configurations capture disproportionate margin pools as enterprises maintain sensitive directory data on-premises while extending authentication to cloud workloads. Among service types, identity management functions lead absolute spending, while directory synchronization tools represent the fastest-expanding category as organizations confront fragmented identity sprawl across multiple cloud platforms.
NIST cybersecurity frameworks in the United States, the EU AI Act's governance requirements for automated access systems, and Japan's METI data sovereignty guidelines collectively elevate compliance-driven procurement standards for directory infrastructure. These regulatory pressures directly shape product roadmaps, mandating audit logging, encryption standards, and residency controls that vendors must certify before qualifying for government and regulated industry contracts. Stakeholders should monitor how forthcoming interoperability mandates between national digital identity schemes reshape vendor selection criteria and deployment architectures.
Market Dynamics
Zero-trust security mandates from NIST and comparable frameworks across the European Union and Japan are compelling wholesale replacement of legacy on-premises Active Directory infrastructure. This regulatory pressure is reorganizing procurement priorities toward cloud-native identity systems with built-in compliance certification.
Growth Catalysts
- NIST Cybersecurity Framework:Federal agencies and defense contractors must replace perimeter-based security models with continuous verification architectures. Cloud directory services provide the identity backbone for these zero-trust deployments.
- Healthcare workforce mobility:Hospital systems and clinical networks require unified authentication for distributed physicians, nurses, and temporary staff accessing patient records across multiple facilities and cloud applications.
- Hybrid cloud adoption:Enterprises maintaining sensitive directory data on-premises while extending authentication to cloud workloads create demand for synchronization tools that bridge identity stores without full migration.
Market Restraints
- Data residency requirements:EU AI Act governance rules and Japan's METI data sovereignty guidelines mandate local storage of identity attributes, fragmenting vendor architectures and inflating operational costs for multinational deployments.
- Skilled identity architect scarcity:Enterprise IT departments lack personnel fluent in SCIM protocol implementation, LDAP schema migration, and cross-cloud policy orchestration, slowing deployment timelines.
- Legacy integration complexity:Decades-old on-premises Active Directory customizations and third-party application dependencies resist clean cloud migration, forcing expensive parallel-system operation.
Strategic Opportunities
- Machine identity management:Internet of Things device authentication and service-to-service credential rotation represent underserved segments as operational technology networks converge with IT infrastructure.
- Mid-market unified platforms:Organizations between five hundred and five thousand employees seek multi-directory solutions without committing to full Microsoft ecosystem lock-in, creating openings for independent vendors.
- Cross-border digital identity interoperability:Emerging mandates for mutual recognition between national digital identity schemes in Germany, France, and the Netherlands will reshape vendor qualification criteria and deployment architectures.
Industry Challenges
- Certification timeline compression:Vendors must simultaneously achieve FedRAMP authorization, ISO 27001 certification, and SOC 2 Type II attestation to qualify for government and regulated industry contracts, straining engineering resources.
- Fragmented multi-cloud identity sprawl:Enterprises adopting AWS, Azure, and Google Cloud simultaneously face inconsistent policy enforcement and audit logging across disparate native identity services, demanding costly custom integration work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Directory Services Software Market |
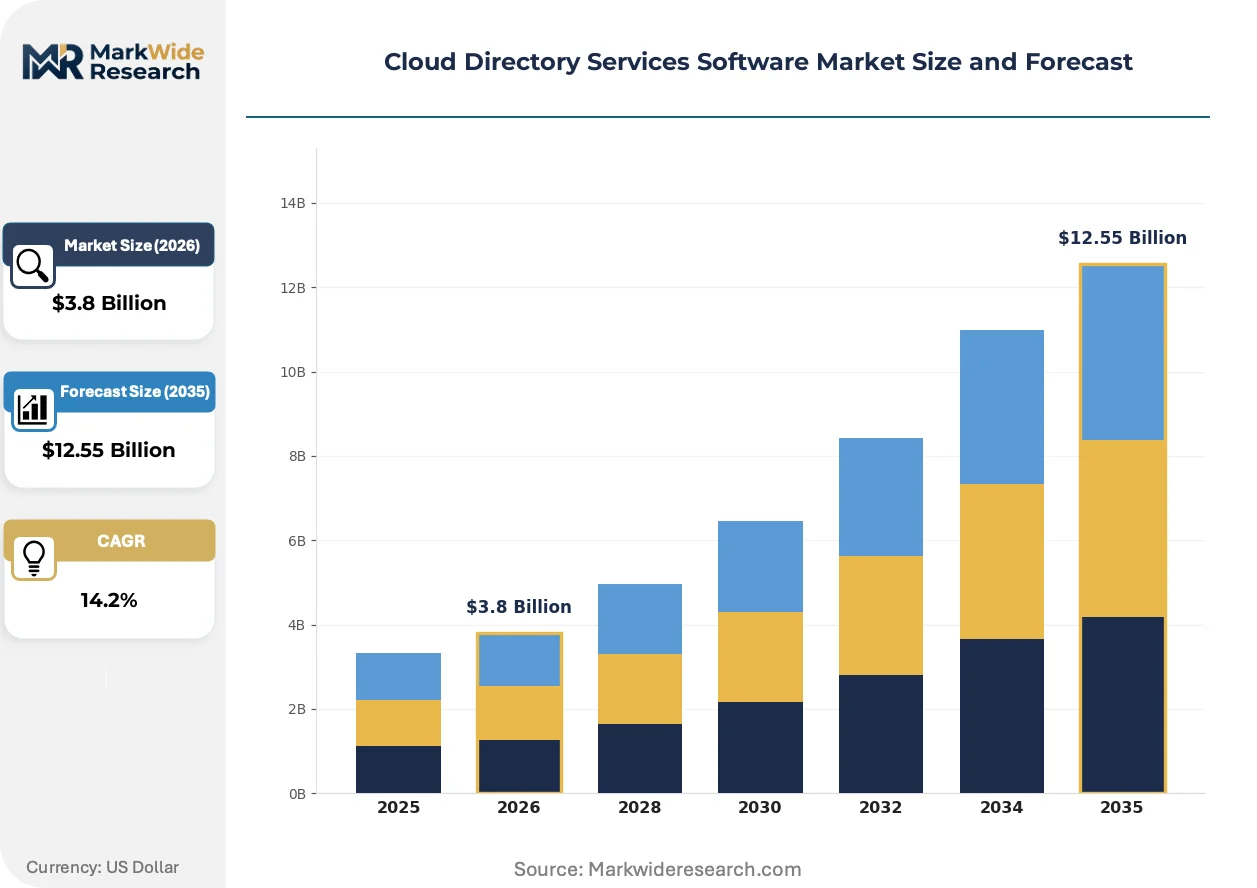
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Service Type: Identity Management, Access Management, Directory Synchronization, Authentication Services End User: Small Businesses, Enterprises, Government Agencies, Educational Institutions Technology: LDAP, SSO, API Integration, SaaS |
| Companies Covered | Microsoft Corporation, Amazon.com Inc., Google LLC, Oracle Corporation, IBM, Okta Inc., Ping Identity Corporation, JumpCloud Inc., OneLogin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Directory Services Software Market Emerging Trajectories
Passwordless authentication architectures are restructuring how enterprises approach identity verification, with biometric and cryptographic methods displacing credential-based access across sensitive applications. This shift is compressing the addressable market for traditional password management tools while elevating directory services that natively support FIDO2 and WebAuthn protocols.
Just-in-time access provisioning is supplanting standing administrative privileges in regulated environments. Financial services firms and healthcare systems now grant elevated permissions for limited time windows rather than permanent role assignments. Directory platforms supporting automated entitlement revocation and session recording command premium positioning. This capability is compressing sales cycles for vendors with native privileged access management integration.
The EU AI Act's governance requirements for automated access systems now mandate explainable decision trails for algorithmic authorization. Vendors must implement audit logging that captures not merely who accessed what, but the policy logic triggering each permission grant. German automotive manufacturers and French pharmaceutical groups are advancing procurement specifications that disqualify systems lacking this interpretability layer.
Consolidated security service edge platforms are absorbing standalone directory functions as enterprises seek to reduce vendor fragmentation. Buyers increasingly demand identity verification, access policy enforcement, and threat detection within unified perimeters rather than separate infrastructure components. This preference is most pronounced among United States technology sector adopters managing distributed software development teams.
Cloud Directory Services Software Market Segmentation
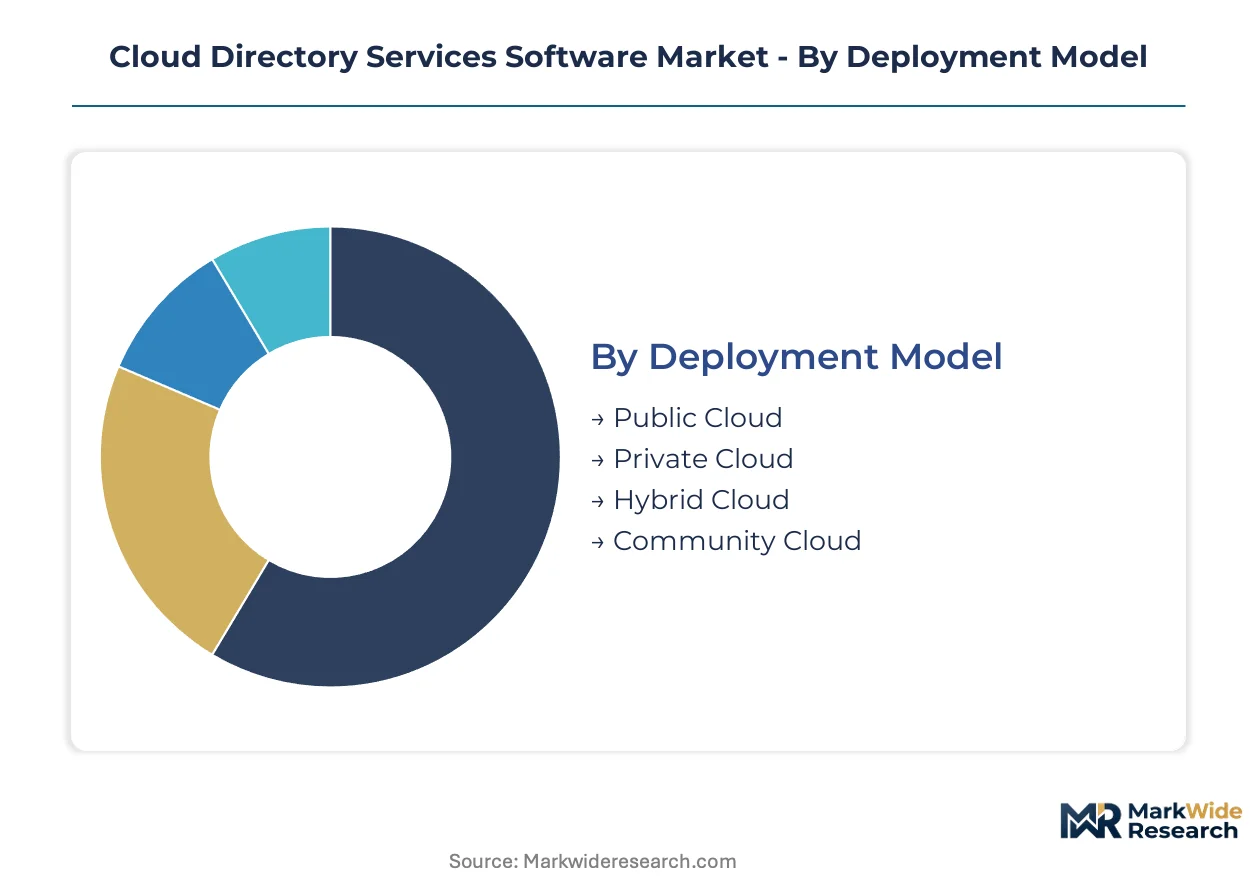
Cloud directory services software vendors pursue sharply divergent margin profiles depending on deployment architecture and service complexity. Procurement patterns reveal how regulatory pressure and legacy infrastructure constraints reshape segment priorities across customer organizations.
Deployment Model:
Margin pools concentrate most heavily in configurations that preserve customer flexibility while offloading operational burden.
- Public Cloud:Multi-tenant architectures deliver identity services through shared infrastructure with automatic scaling and zero hardware maintenance. Demand concentrates among United States technology startups and mid-market SaaS companies seeking rapid provisioning without capital expenditure.
- Hybrid Cloud:Split deployments maintain sensitive directory attributes on-premises while extending authentication to cloud workloads. German automotive manufacturers and Japanese financial institutions drive adoption as METI data sovereignty guidelines and EU AI Act residency mandates fragment storage requirements.
- Private Cloud:Single-tenant dedicated environments serve defense contractors and intelligence agencies requiring isolated infrastructure with custom encryption controls.
- Community Cloud:Shared infrastructure restricted to specific industry verticals enables cost pooling among healthcare networks and university systems with common compliance frameworks.
The dominant share belongs to Public Cloud, while Hybrid Cloud is closing the gap fastest.
Service Type:
Application complexity determines pricing power, with integration-heavy offerings commanding premium positioning.
- Directory Synchronization:Bridge technologies reconcile identity attributes across fragmented on-premises and cloud stores without forcing wholesale migration. United States enterprises with decades-old Active Directory customizations drive volume as NIST zero-trust mandates compel infrastructure modernization.
- Identity Management:Lifecycle automation for user provisioning, role assignment, and deprovisioning anchors enterprise deployments. Healthcare systems across Germany require these capabilities for managing distributed clinical staff accessing patient records across multiple facilities.
- Access Management:Policy enforcement engines govern resource authorization based on contextual risk signals and device posture.
- Authentication Services:Credential verification and token issuance provide foundational security primitives for application developers.
Identity Management captures the largest revenue pool, though Directory Synchronization is gaining share fastest.
End User:
Customer scale dictates sales motion economics, from self-service onboarding to eighteen-month enterprise procurement cycles.
- Enterprises:Organizations exceeding five thousand employees require multi-directory unification across geographic subsidiaries with centralized audit and compliance reporting. Japanese conglomerates and United States defense contractors represent core demand as FedRAMP authorization becomes mandatory for federal contracts.
- Government Agencies:Sovereign entities demand certified infrastructure with domestic data residency and cryptographic modules meeting national standards.
- Small Businesses:Organizations below five hundred employees prioritize turnkey solutions with minimal configuration overhead.
- Educational Institutions:Universities and K-12 districts seek volume pricing for transient student populations with seasonal enrollment patterns.
Enterprises dominate absolute spending, while Government Agencies are expanding most quickly.
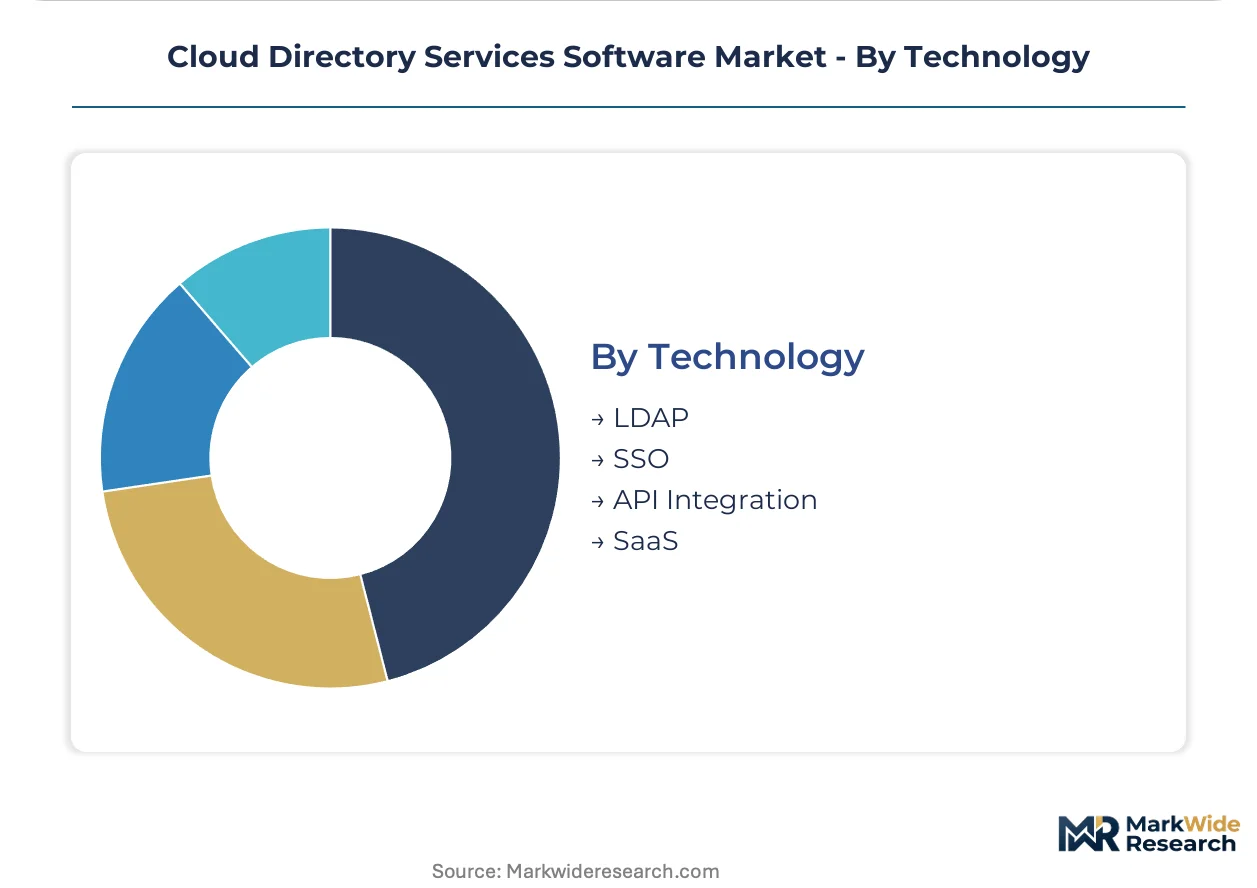
Technology:
Protocol maturity shapes implementation risk and integration cost for customer technical teams.
- LDAP:Lightweight Directory Access Protocol remains the foundational schema for hierarchical identity storage and query operations. German industrial manufacturers maintain substantial on-premises LDAP investments resisting full cloud migration.
- SSO:Single sign-on protocols eliminate credential re-entry across federated application environments. United States healthcare providers deploy SSO to streamline physician access across dozens of specialized clinical systems.
- API Integration:RESTful and SCIM endpoints enable programmatic identity operations for DevOps pipelines and custom application development.
- SaaS:Software-as-a-service delivery models abstract protocol complexity behind managed service interfaces.
LDAP retains the widest installed base, though SSO is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by jurisdiction. United States buyers prioritize zero-trust compliance velocity. German and Japanese procurement teams weight data residency above deployment speed.
United States
Federal agencies and defense contractors drive volume through NIST cybersecurity framework mandates. FedRAMP authorization has become a gatekeeper qualification for cloud directory contracts. Washington DC corridor and Virginia data center clusters concentrate deployment activity as contractors modernize legacy Active Directory infrastructure.
Germany
Automotive manufacturers and pharmaceutical groups anchor enterprise demand for hybrid cloud configurations. EU AI Act governance requirements for automated access systems mandate explainable audit trails. Bavarian industrial corridors and Frankfurt financial centers lead implementation as METI-aligned data sovereignty concerns reshape vendor selection.
Japan
Conglomerates and financial institutions confront METI data sovereignty guidelines requiring domestic identity attribute storage. Healthcare networks managing distributed clinical staff accelerate cloud migration. Tokyo and Osaka metropolitan areas concentrate deployment as regulators tighten cross-border data flow restrictions.
United Kingdom
Financial services firms and NHS trusts prioritize directory synchronization tools bridging on-premises legacy systems with cloud workloads. Post-Brexit regulatory divergence from EU frameworks creates procurement complexity. London fintech clusters and Manchester health technology hubs drive specialized demand for just-in-time access provisioning.
India
IT services exporters and domestic enterprises adopt cloud directory services to manage distributed development teams across multiple client environments. Data localization expectations under draft digital personal data protection frameworks influence vendor architecture decisions. Bangalore and Hyderabad technology corridors concentrate adoption as multinational back-office operations expand.
Cloud Directory Services Software Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier. Hyperscale platform operators leverage bundled cloud productivity suites to anchor enterprise deployments. Independent vendors compete through multi-directory unification without ecosystem lock-in. Specialists target mid-market segments with simplified onboarding. Competitive moves concentrate on strategic partnerships with systems integrators and portfolio expansion into machine identity management.
Within the integrated platform tier, Microsoft Corporation exemplifies the bundled-suite archetype through Azure Active Directory anchoring. JumpCloud Inc. occupies a distinct position among independent specialists serving mid-market multi-directory environments. Okta Inc. represents the cloud-native identity pure-play approach. These three companies illustrate the strategic segmentation between ecosystem-integrated, independent unified, and specialized cloud-native positioning.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon.com Inc. |
| Google LLC |
| Oracle Corporation |
| IBM |
| Okta Inc. |
| Ping Identity Corporation |
| JumpCloud Inc. |
| OneLogin |
| Others |
Supply Flow & Price Mechanics
Ninety-day implementation timelines for enterprise directory deployments concentrate pricing power with vendors possessing pre-certified FedRAMP and ISO 27001 attestations, while compressing margins for specialists lacking these qualifications. This lead-time pressure intersects with supply-chain concentration in cloud infrastructure provisioning, where hyperscale platform operators leverage captive compute and storage capacity to undercut independent software vendors on total cost of ownership.
Pricing Analysis
Annual subscription contracts with auto-renewal clauses dominate enterprise procurement, though project-based implementation fees for complex Active Directory migrations command premium positioning. Price differentiation rests on certification tier—FedRAMP High authorization separates defense-contractor-qualified vendors from commercial-only alternatives—and on vertical integration depth, where bundled identity and productivity suites extract economies of scope. Cost compression in the mid-market tier intensifies as JumpCloud and comparable independents introduce freemium onboarding to displace Microsoft ecosystem commitments. Small businesses below five hundred employees exhibit highest price sensitivity, while United States federal agencies demonstrate lowest elasticity due to mandate-driven procurement urgency.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for hardware security modules and specialized cryptographic appliances deployed in private cloud configurations. Software supply chains draw from United States hyperscale infrastructure, Irish and Singaporean data center clusters for EU and Asia-Pacific residency compliance, and domestic Japanese facilities for METI-aligned deployments. Single-source vulnerability concentrates in certificate authority dependencies and FIDO2 hardware token manufacturing. Distribution runs through direct enterprise sales teams for large deployments, supplemented by systems integrator channels for mid-market implementations requiring customization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States federal agencies and German automotive conglomerates, whose consolidated procurement volumes force vendors into certification-heavy competitive bidding that fragments margin pools.
For Market Incumbents: Compound defensive positioning through accelerated FedRAMP authorization timelines and in-house development of machine identity management capabilities to offset pure-play specialist encroachment. Deepen vertical integration into hardware security module provisioning to capture cryptographic appliance margins currently leaking to third-party suppliers. Threat substitution from consolidated security service edge platforms absorbing standalone directory functions demands preemptive platform bundling. For New Entrants and Emerging Players: Mid-market multi-directory unification without Microsoft ecosystem lock-in represents the most penetrable white-space segment, particularly among United States healthcare networks and Japanese conglomerates with hybrid cloud mandates. Target five-hundred-to-five-thousand-employee organizations seeking rapid provisioning without eighteen-month enterprise procurement cycles. A channel-first go-to-market through managed service providers offers lower customer acquisition cost than direct sales investment. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because regulatory certification timelines create durable moats around authorized vendors while zero-trust mandates compel sustained replacement demand. Acquisition target archetype: independent vendors possessing FedRAMP authorization and native SCIM protocol implementation expertise. The signal to watch is cross-border digital identity interoperability mandates between Germany, France, and the Netherlands reshaping vendor qualification criteria.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | United States federal contracts become accessible to vendors achieving High authorization tier. |
| Machine Identity Management Launch | IoT device authentication and service-to-service credential rotation capture underserved operational technology segments. |
| Strategic Partnership with Systems Integrators | Channel leverage penetrates mid-market healthcare and manufacturing verticals requiring customization. |
| Acquisition of SCIM Protocol Specialist | Technical talent scarcity in cross-cloud policy orchestration is addressed through specialized team integration. |
| Geographic Expansion to Japanese Domestic Cloud | METI data sovereignty guidelines require local identity attribute storage for financial institution contracts. |
Methodological Framework
A standing panel of chief information security officers, identity architects at Fortune 500 enterprises, FedRAMP authorization consultants, and healthcare IT procurement directors provided ongoing calibration against market developments. Primary interview findings were cross-validated with secondary sources including SEC 10-K filings from publicly traded vendors, hyperscaler capex disclosures revealing infrastructure investment patterns, NIST cybersecurity framework update documentation, and EU AI Act regulatory guidance publications. Bottom-up deployment volume estimates were reconciled with top-down market sizing derived from enterprise IT budget allocation surveys.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework modeled deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster as segmentation dimensions. CAGRs were derived from fitted growth curves anchored to documented procurement volumes and mandate implementation schedules. Industry-specific forecast inputs included NIST zero-trust compliance deadline acceleration and EU AI Act audit trail requirement enforcement timelines.
Material uncertainties—regulatory timeline delays, hyperscaler pricing warfare, and skilled identity architect scarcity—sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained federal mandate enforcement and cross-border digital identity scheme interoperability advancement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Retail Cloud Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
Healthcare Cloud Infrastructure Market
Cloud Computing
Cloudifier Market
Cloud Computing
Global Grid Computing Market
Cloud Computing
Public Finance Cloud Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
Europe AI Cloud Computing in Automotive Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Cloud Systems Management Software Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
North America Professional Cloud Services Market
Cloud Computing
North America Cloud Computing Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Cloud Migration Services Market
Cloud Computing
Cloud Data Warehouse Market