
 France Cloud Computing Market | 2026-2036
France Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
France Cloud Computing Market Insights
Modular service bundling is expanding buyer choice across the France cloud computing landscape. OVHcloud leverages its sovereign cloud certifications to anchor public-sector contracts. Microsoft Corporation sustains enterprise momentum through Azure's hybrid integration capabilities. Scaleway competes on price-performance for developer-centric workloads.
Cloud computing denotes on-demand delivery of compute, storage, and networking resources via internet-connected data centers with service-level agreements guaranteeing uptime above 99.9%. Its primary purpose is to replace capital-intensive on-premises infrastructure with elastic operational expenditure models. SaaS and IaaS command the largest revenue pools, while multi-cloud deployment architectures represent the fastest-growing configuration as organizations distribute workloads across providers to mitigate concentration risk. Government and education end users exhibit accelerating procurement velocity following France's cloud de confiance labeling program.
ANSSI, the EU AI Act, and France's SecNumCloud certification collectively shape vendor eligibility and data residency requirements for sensitive workloads. These frameworks restrict non-European providers from certain public contracts while creating compliance moats for certified domestic operators. Stakeholders must monitor evolving sovereignty criteria and their interaction with the EU Data Act's portability mandates.
Market Dynamics
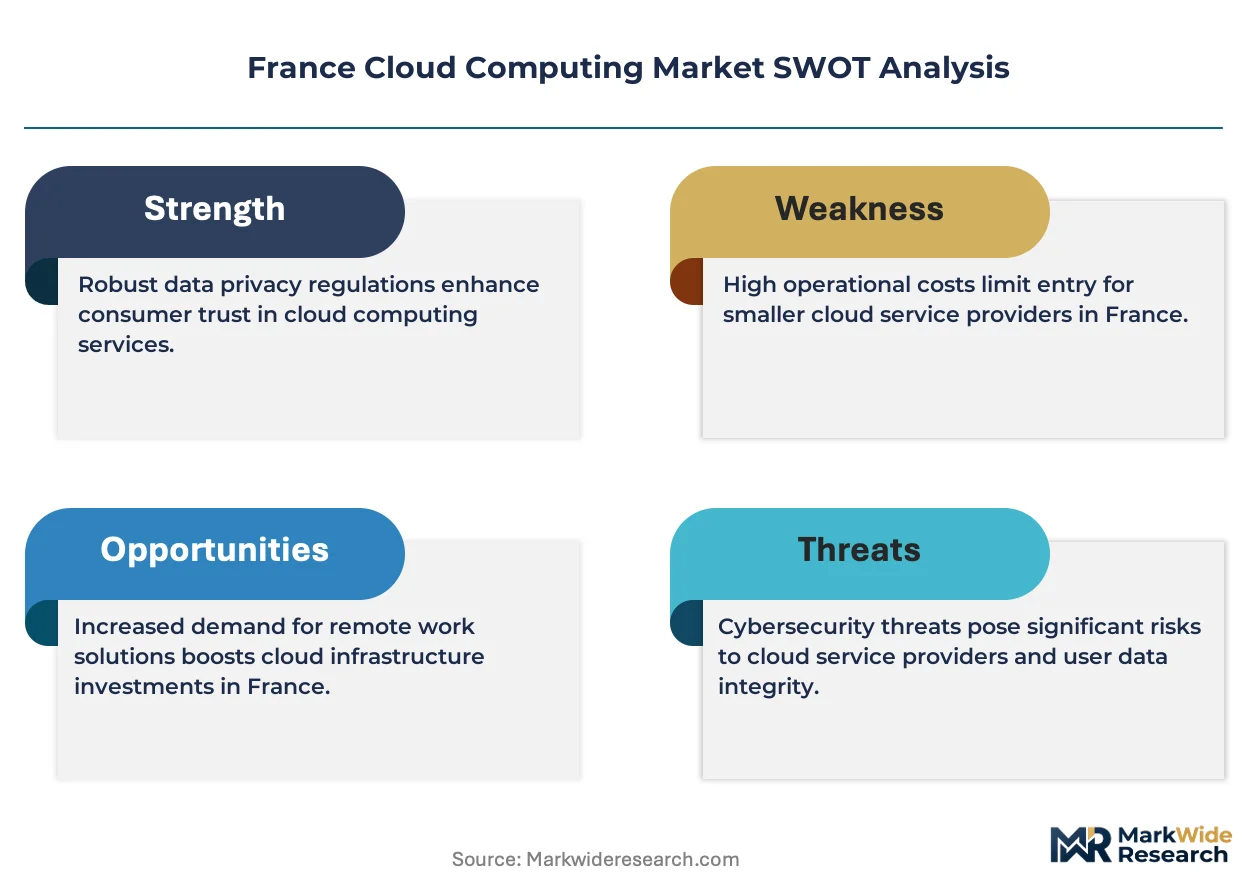
Sovereignty mandates from ANSSI and the EU AI Act are restructuring procurement eligibility, forcing hyperscale providers to localize infrastructure and domestic operators to scale certified capacity.
Growth Catalysts
- SecNumCloud Certification:France's national security agency labels create compliance moats for domestic operators bidding on defense and healthcare contracts.
- Paris-Saclay Data Center Corridor:Concentrated hyperscale and edge facility investments reduce latency for financial services workloads requiring sub-10ms response times.
- Core Banking Migration:French insurers and retail banks are replatforming legacy mainframe estates onto containerized sovereign environments to satisfy operational resilience directives.
Market Restraints
- Certification Timeline Friction:ANSSI evaluation cycles for cloud de confiance status extend 18-24 months, freezing vendor eligibility for sensitive public tenders.
- Energy Input Volatility:Nuclear and renewable power purchase agreements for Île-de-France data centers face repricing pressure from grid capacity constraints.
- Technical Skill Scarcity:Multi-cloud architecture and zero-trust security competencies remain concentrated among a limited pool of Paris-region systems integrators.
Strategic Opportunities
- Edge-AI Convergence:Manufacturing and autonomous vehicle developers in Lyon and Toulouse require localized inference capacity combining 5G MEC with GPU clusters.
- Public Sector Channel Expansion:France's cloud de confiance labeling program opens direct procurement pathways for certified operators previously excluded from state contracts.
- Healthcare Data Federation:Regional hospital groups seek compliant platforms for cross-institutional analytics under the EU Health Data Space preparatory framework.
Industry Challenges
- Interoperability Complexity:Multi-cloud deployments spanning hyperscale and sovereign environments demand specialized integration labor that French system integrators struggle to staff.
- Legacy Modernization Risk:COBOL-dependent financial institutions face extended parallel-run periods when migrating core banking ledgers, compressing project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Cloud Computing Market |
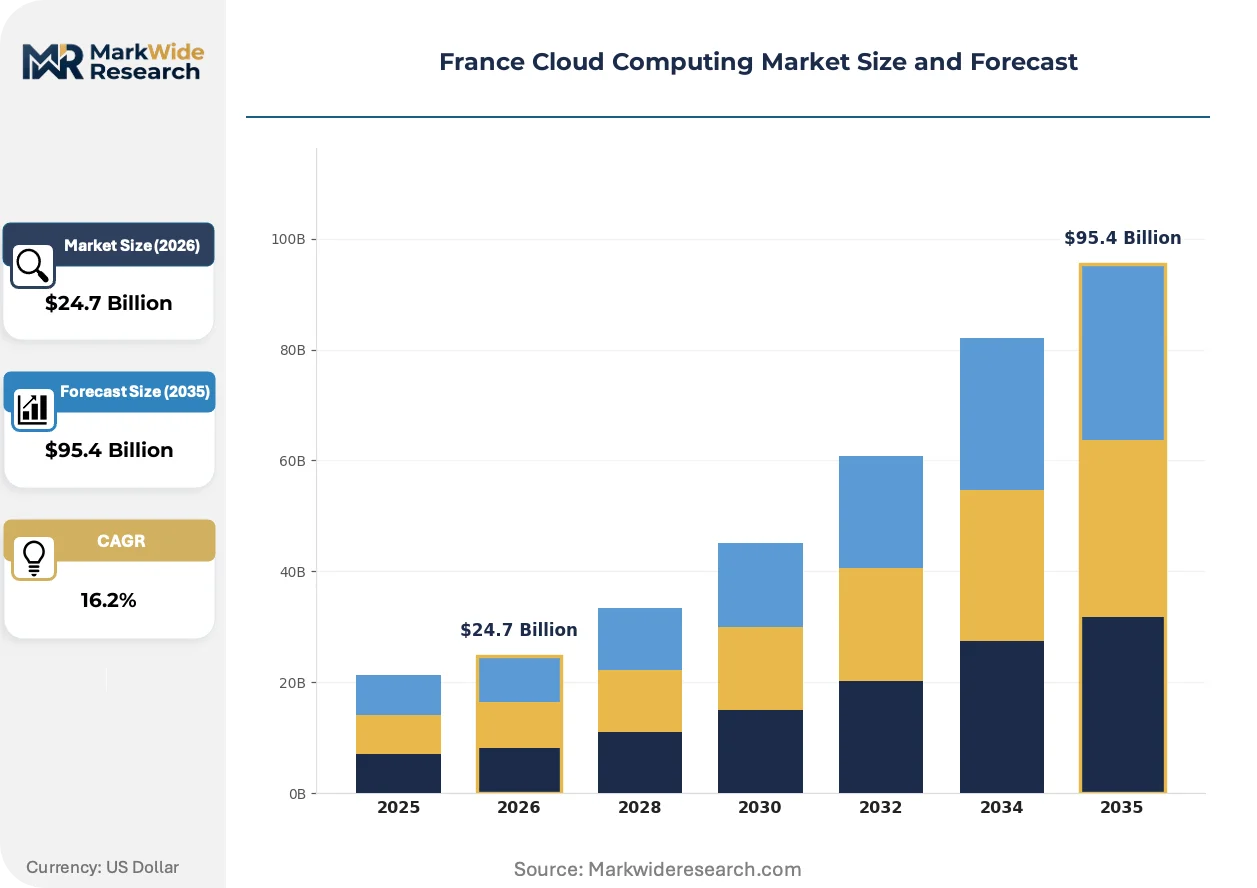
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $95.4 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, DaaS End User: SMBs, Enterprises, Government, Education Application: Data Storage, Backup Solutions, Disaster Recovery, Big Data Analytics |
| Companies Covered | OVHcloud, Microsoft Corporation, Amazon Web Services, Google LLC, Orange S.A., IBM Corporation, Scaleway, Capgemini, OUTSCALE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Cloud Computing Market Trends and Innovations
Workload portability and sovereignty compliance are converging to reshape how French organizations architect their infrastructure, with certification status now outweighing raw price-performance in procurement scoring.
Confidential computing is integrating hardware-based encryption for data-in-use protection. Defense contractors and pharmaceutical researchers in the Paris-Saclay cluster are adopting AMD SEV-SNP and Intel TDX instances to process classified datasets without trusting the cloud operator. This capability is integrating sovereign cloud offerings into markets previously reserved for air-gapped on-premises infrastructure.
France's cloud de confiance program and the EU AI Act are tightening data residency and algorithmic transparency requirements. Providers must document training data provenance and model architecture for high-risk AI deployments. Healthcare AI developers and public employment services face the steepest compliance burden, with several delaying product launches to complete conformity assessments.
Consumption-based commitment structures are displacing traditional reserved instance contracts. Mid-market enterprises in Lyon and Marseille prefer granular pay-per-query models for analytics workloads over three-year capacity blocks. This shift pressures providers to unbundle professional services and expose raw API pricing, compressing attach-rate revenue for implementation and support.
France Cloud Computing Market Segmentation
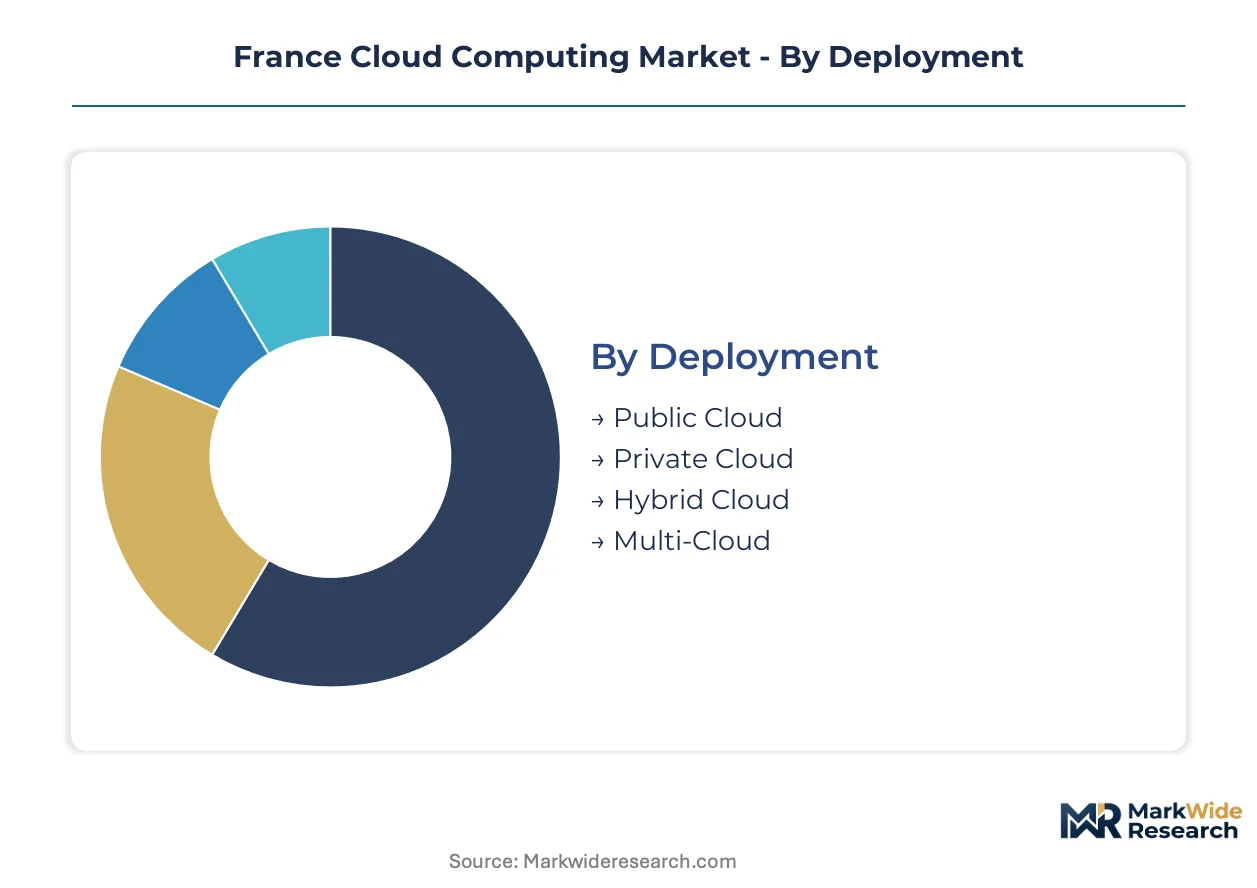
Cloud procurement decisions in France now hinge on sovereignty compliance and workload portability rather than unit economics alone. Segmentation reveals how certification requirements reshape vendor eligibility across deployment modes and service tiers.
Deployment:
Capital intensity peaks with private infrastructure builds requiring dedicated hardware and facility investments, while public deployments minimize upfront outlays through shared resource pools.
- Public Cloud:Shared infrastructure pools deliver compute and storage via standardized APIs with zero physical asset ownership. French mid-market enterprises in Lyon and Marseille favor this model for burst workloads, though ANSSI restrictions limit its use for sensitive public-sector data.
- Private Cloud:Dedicated single-tenant environments demand full hardware procurement and facility buildout, concentrating investment among defense contractors and pharmaceutical researchers in the Paris-Saclay corridor processing classified datasets.
- Hybrid Cloud:Interconnected on-premises and off-premises resources balance control with elasticity, attracting financial institutions running parallel legacy and containerized systems during core banking migrations.
- Multi-Cloud:Orchestrated workloads across two or more providers reduce concentration risk, gaining traction among insurers distributing analytics across sovereign and hyperscale environments.
Most installed capacity flows through Public Cloud. Expansion is steepest in Multi-Cloud.
Service Type:
Margin structures diverge sharply, with infrastructure services commoditizing while platform and software layers capture premium pricing through developer productivity gains.
- IaaS:Raw compute, storage, and networking resources provisioned as virtualized infrastructure. French manufacturers in Toulouse deploy GPU clusters via IaaS for simulation workloads, driving demand for localized bare-metal instances with sub-10ms latency.
- PaaS:Application development and deployment environments abstract infrastructure management. Developer teams at regional hospital groups select PaaS to accelerate healthcare AI prototyping under EU Health Data Space preparatory frameworks.
- SaaS:Fully managed application software delivered via subscription, dominating procurement volumes among SMBs seeking to replace on-premises productivity suites without internal IT expansion.
- DaaS:Desktop virtualization streams complete workstation environments to endpoint devices, attracting education sector buyers equipping distributed campuses with standardized software access.
Revenue concentrates in SaaS. IaaS climbs fastest as sovereign certification requirements drive dedicated infrastructure procurement.
End User:
Procurement sophistication varies by organizational scale, with large institutions operating formal vendor qualification programs that exclude uncertified operators.
- SMBs:Organizations with limited IT staff prioritize managed services and consumption-based billing, selecting bundled offerings that minimize architectural decision burden.
- Enterprises:Multinational corporations with French subsidiaries operate global cloud frameworks, adapting procurement to incorporate SecNumCloud requirements for local data residency.
- Government:Central and regional administrations mandate cloud de confiance certification, restricting eligible vendors to domestic operators with ANSSI evaluation.
- Education:Universities and research institutions combine public grant funding with commercial workloads, creating hybrid procurement profiles spanning sovereign and standard cloud tiers.
Enterprise accounts deploy the largest absolute capacity. Government segment expands most rapidly following labeling program expansion.
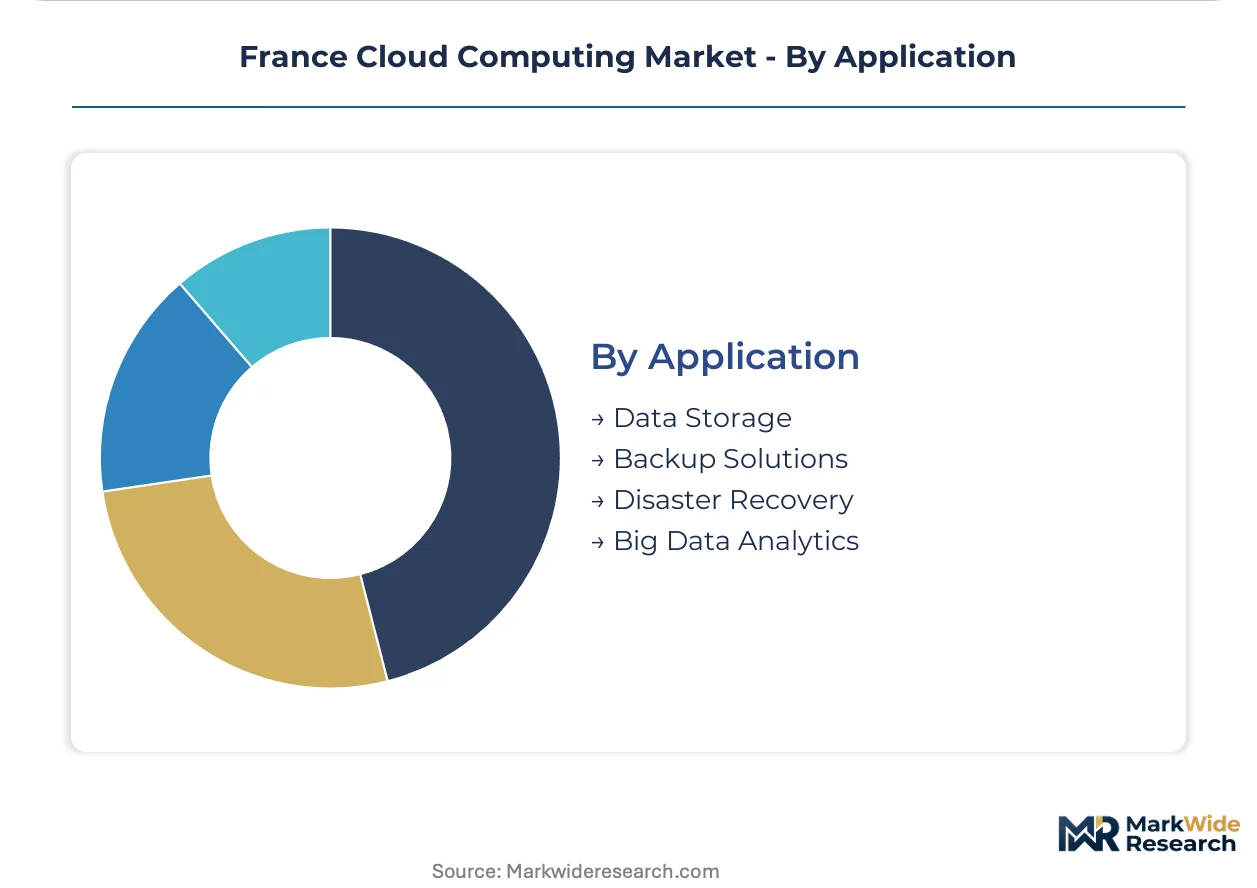
Application:
Workload criticality determines infrastructure redundancy requirements, with tier-one systems demanding geographically distributed failover capabilities.
- Data Storage:Object, block, and file repositories scaled to petabyte volumes. Genomics researchers at Paris-Saclay institutes drive demand for high-throughput archival tiers with retrieval SLAs under four hours.
- Backup Solutions:Point-in-time data protection with immutable retention policies. Financial services compliance teams specify air-gapped backup architectures satisfying operational resilience directives.
- Disaster Recovery:Automated failover systems maintaining business continuity during regional outages. Retail banks mandate RPOs under one minute for core ledger systems, requiring synchronous replication across availability zones.
- Big Data Analytics:Distributed processing frameworks for structured and unstructured datasets. Employment services agencies deploy analytics platforms to model benefit allocation, facing steep algorithmic transparency requirements under the EU AI Act.
Data Storage commands the largest footprint. Big Data Analytics scales fastest as AI training workloads proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud computing infrastructure first achieved commercial scale in the United States through hyperscale data center deployments, yet France has emerged as Europe's sovereign cloud laboratory where regulatory frameworks now shape procurement patterns ahead of other jurisdictions.
Île-de-France
Paris-Saclay corridor hosts the densest concentration of certified cloud capacity, with hyperscale and domestic providers co-locating facilities to serve financial services latency requirements. ANSSI's SecNumCloud evaluation center operates from this region, accelerating certification timelines for local operators. Defense contractors and pharmaceutical researchers in the Essonne cluster deploy confidential computing instances for classified dataset processing.
Auvergne-Rhône-Alpes
Manufacturing AI developers in Lyon drive edge-cloud convergence demand, combining 5G MEC infrastructure with localized GPU clusters for autonomous systems testing. The region's industrial automation heritage attracts automotive suppliers seeking sovereign inference capacity. Saint-Étienne's technical universities supply multi-cloud architecture talent to systems integrators serving this market.
Provence-Alpes-Côte d'Azur
Maritime logistics operators in Marseille favor consumption-based billing models for analytics workloads over traditional reserved capacity contracts. The port's digital twin initiatives require sub-10ms data processing for vessel traffic optimization. Local hospital groups pilot healthcare data federation platforms under EU Health Data Space preparatory frameworks.
Hauts-de-France
Energy-intensive data center investments concentrate near nuclear generation capacity in the Nord-Pas-de-Calais zone, hedging against grid repricing volatility. Cold climate advantages reduce cooling costs for hyperscale facilities serving northern European latency requirements. Lille's fintech cluster sources backup and disaster recovery services from certified domestic operators.
Occitanie
Aerospace supply chain digitization in Toulouse generates sovereign cloud demand for export-controlled engineering data. The region's satellite manufacturing ecosystem requires air-gapped backup architectures satisfying operational resilience directives. Montpellier's agritech startups deploy IoT-integrated platforms for precision farming analytics.
France Cloud Computing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with ANSSI-endorsed operators commanding pricing power in public-sector procurement while undifferentiated infrastructure providers compete on unit economics for enterprise burst workloads. The vendor base stratifies into three tiers: hyperscale platforms with localized sovereign offerings, domestic operators with full certification stacks, and regional specialists in vertical applications. Consolidation pressure intensifies as certification timelines extend and capital requirements for facility buildouts rise. Dominant competitive moves center on strategic partnerships for hybrid integration capabilities and geographic expansion into secondary French metros.
Within the certified domestic tier, OVHcloud anchors sovereign cloud positioning through ANSSI-validated infrastructure, while Scaleway occupies a price-performance position for developer-centric workloads. Microsoft Corporation represents the hyperscale adaptation archetype, having localized Azure capacity to satisfy France's cloud de confiance requirements for sensitive public contracts. These three entities exemplify the competitive vectors now shaping procurement decisions: certification depth, localization investment, and workload-specific optimization.
| Leading Market Players |
|---|
| OVHcloud |
| Microsoft Corporation |
| Amazon Web Services |
| Google LLC |
| Orange S.A. |
| IBM Corporation |
| Scaleway |
| Capgemini |
| OUTSCALE |
| Others |
Pricing and Supply Chain Analysis
Multi-cloud architecture specialists concentrated in the Paris-Saclay corridor command wage premiums that propagate through service pricing tiers, widening spreads between certified sovereign offerings and commodity infrastructure as ANSSI compliance timelines extend vendor qualification periods.
Pricing Analysis
Consumption-based commitment structures with granular pay-per-query billing are displacing traditional reserved instance contracts across the France cloud computing landscape. Pricing stratifies across SecNumCloud-certified sovereign tiers, standard hyperscale localization tiers, and uncertified economy infrastructure, with certification depth and data residency guarantees as primary differentiation drivers. Cost compression in the mid-market segment intensifies as Lyon and Marseille enterprises demand unbundled API pricing without professional services attach rates. SMB buyers exhibit highest price sensitivity, while defense contractors and pharmaceutical researchers in the Paris-Saclay cluster prioritize confidential computing capabilities over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from French financial institutions mandate multi-supplier qualification spanning domestic certified operators and localized hyperscale platforms, preventing single-vendor concentration. Hardware supply concentrates in Taiwan, South Korea, and the United States for advanced GPU and confidential computing processors. Data center construction draws from specialized cooling systems, nuclear power purchase agreements, and fiber interconnects as critical inputs. Single-source vulnerability in ANSSI certification capacity creates bottleneck risk for sovereign cloud expansion. Distribution runs through systems integrators and direct enterprise sales channels with professional services bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in France cloud computing rests on certification-driven premium tiering as ANSSI evaluation creates compliance moats that sustain pricing power against commodity hyperscale competition.
For Market Incumbents: Cement sovereign cloud positioning through accelerated SecNumCloud capacity expansion in the Paris-Saclay corridor before evaluation timelines extend further. Deepen backward integration into confidential computing hardware supply chains to secure AMD SEV-SNP and Intel TDX instance availability for defense and pharmaceutical workloads. Threat of emerging domestic operators with faster certification cycles demands preemptive facility investment. For New Entrants and Emerging Players: Enter via edge-AI convergence opportunities in Lyon and Toulouse manufacturing corridors, where 5G MEC and localized GPU clusters remain underserved by incumbent sovereign providers. White-space exists in consumption-based analytics platforms for Marseille maritime logistics and Montpellier agritech IoT deployments. Go-to-market angle should emphasize granular pay-per-query billing without three-year capacity commitments. For Investors and Strategic Acquirers: Hyperscale platforms with localized sovereign offerings are the most active acquirer in this space, seeking ANSSI-certified domestic operators to shortcut 18-24 month evaluation cycles. Long-term viability favors operators with dual capability stacks spanning confidential computing hardware and multi-cloud orchestration software. Signal to watch is acceleration in EU Health Data Space preparatory framework procurement, which would inflect demand for healthcare-compliant federation platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Deployment | AMD SEV-SNP and Intel TDX instances unlock classified workload markets previously reserved for air-gapped infrastructure. |
| SecNumCloud Certification Acceleration | ANSSI validation creates procurement eligibility moats for defense and healthcare contracts requiring data sovereignty. |
| Edge-AI Infrastructure Buildout | 5G MEC and GPU cluster convergence in Lyon and Toulouse captures autonomous systems testing demand. |
| Consumption-Based Billing Unbundling | Pay-per-query models for analytics workloads attract mid-market buyers seeking operational expenditure flexibility. |
| Healthcare Data Federation Platform | EU Health Data Space compliance positions operators for regional hospital group cross-institutional analytics procurement. |
Research Methodology
Bottom-up enterprise workload modeling reconciled against top-down hyperscale capex tracking forms the analytical core of this study. Primary interviews with cloud procurement officers, ANSSI certification leads, systems integration architects, and healthcare IT directors combined with secondary validation from SEC filings, hyperscaler infrastructure disclosures, and ANSSI evaluation registers. Trade data from French customs authorities and EU cloud procurement databases anchored supply-side triangulation against demand-side deployment surveys.
Historical trendline analysis across certified and non-certified infrastructure deployment patterns informed projection frameworks. Segmentation dimensions modeled include deployment architecture, service tier, organization scale, vertical application, and regional data center cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating regulatory compliance deadlines and workload migration timelines. Forecast inputs incorporated nuclear power purchase agreement repricing scenarios and ANSSI evaluation throughput capacity constraints.
Inputs from hyperscaler facility announcements and ANSSI certification registers were available through the study window; gaps in confidential computing hardware shipment data introduce uncertainty bands around edge-AI deployment velocity. Forecasts reflect documented assumptions regarding EU AI Act implementation timelines and SecNumCloud program expansion scope. Deviation in ANSSI evaluation cycle duration or nuclear grid capacity allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Based-Batch Processing Market
Cloud Computing
India Cloud Computing Market
Cloud Computing
Cloud Services Brokerage (CSB) Market
Cloud Computing
Public Cloud in BFSI Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
Cloud Continuum Market
Cloud Computing
Global Cloud Based ITSM Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Commerce Cloud Market
Cloud Computing
Global Server Virtualization Market
Cloud Computing
Cloud Computing in Industrial IoT Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Global Cloud Dictation Solution Market