
 Cloud Systems Management Software Market | 2026-2036
Cloud Systems Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Systems Management Software Market Intelligence
Platform licensing revenue is fragmenting across specialized workload orchestration, cost optimization, and policy governance modules. HashiCorp sustains technology leadership in infrastructure-as-code provisioning for multi-cloud estates. Nutanix dominates hyperconverged private cloud management with integrated compute and storage control planes.
Cloud systems management software comprises integrated toolsets for provisioning, monitoring, orchestrating, and governing distributed computing resources across heterogeneous environments, typically exposing REST APIs and supporting containerized workloads via Kubernetes operators. Its primary purpose is to enforce service-level objectives while minimizing operational expenditure through automated remediation and rightsizing. Hybrid Cloud deployment configurations capture the dominant margin pool as enterprises retain sensitive workloads on-premises while bursting transactional loads to public infrastructure. Security Management solutions within the solution layer are expanding fastest as zero-trust architectures mandate continuous compliance verification across ephemeral resources.
FDA 21 CFR Part 11 requirements for healthcare IT systems, EU GDPR data residency mandates enforced by national regulators, and HIPAA security rule provisions collectively shape product roadmaps toward encrypted audit trails and geographic access controls. The SEC's cybersecurity disclosure rules for publicly traded firms further accelerate procurement of real-time risk dashboards. Stakeholders must evaluate whether their current tooling stack can autonomously map regulatory control frameworks to dynamic cloud resource topologies without manual policy translation.
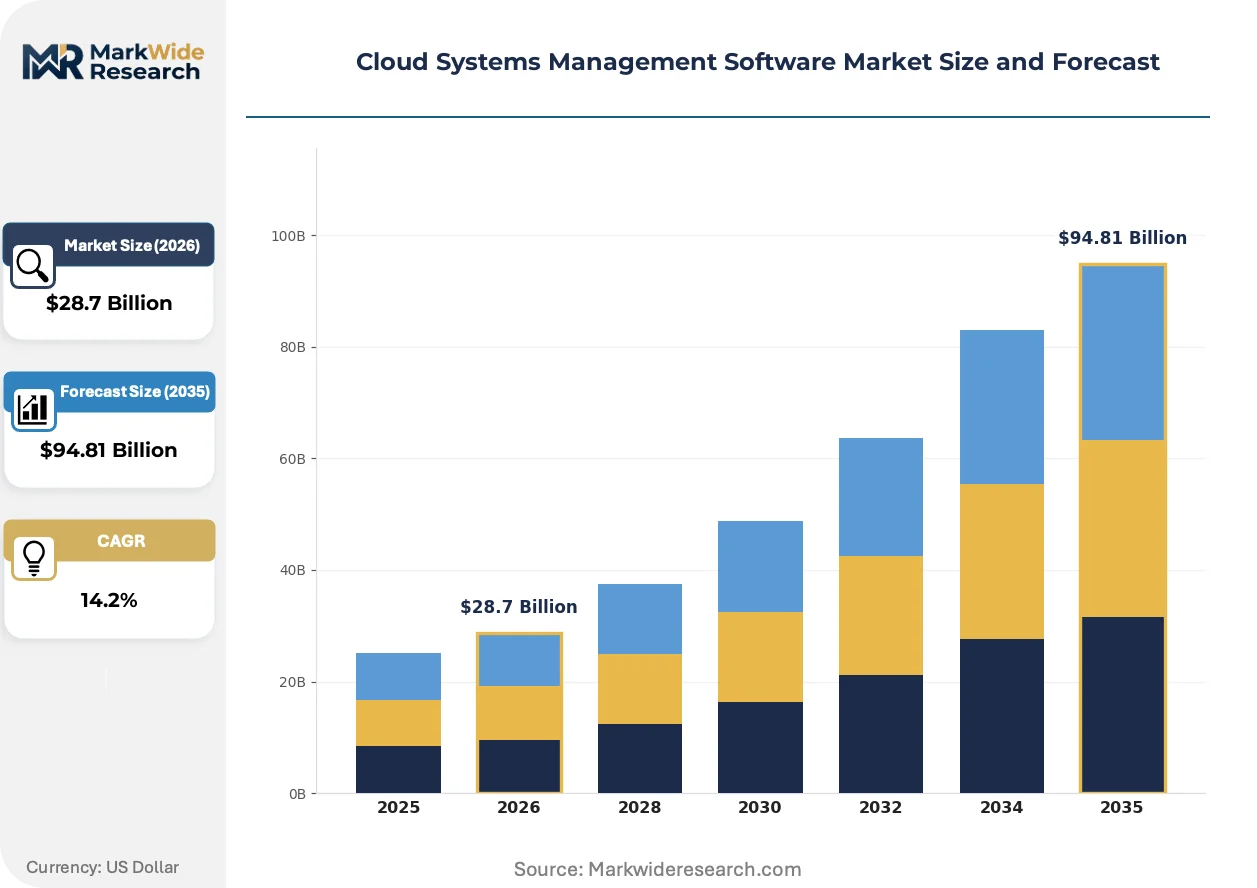
Market Dynamics
Hybrid cloud orchestration is fragmenting enterprise procurement patterns as BFSI IT departments simultaneously demand sovereign data controls and elastic compute burst capacity. Platform vendors face pressure to unify policy governance across on-premises Kubernetes estates and hyperscaler serverless functions without manual translation layers.
Growth Catalysts
- EU AI Act compliance mandates:Financial institutions in Germany, France, and the United Kingdom are procuring automated governance tooling to satisfy algorithmic accountability requirements for credit-scoring and fraud-detection workloads.
- Zero-trust security architectures:Continuous compliance verification across ephemeral containers is expanding procurement of real-time risk dashboards with encrypted audit trail capabilities.
- Healthcare IT modernization:FDA 21 CFR Part 11 requirements for electronic records are driving pharmaceutical and medical device manufacturers toward validated cloud management platforms with geographic access controls.
Market Restraints
- Specialized talent scarcity:Shortage of Site Reliability Engineers with multi-cloud Terraform and Kubernetes operator expertise limits enterprise implementation velocity.
- Legacy infrastructure lock-in:Proprietary VMware vSphere estates and mainframe-dependent batch systems resist API-native orchestration without costly middleware layers.
- Input cost volatility:Hyperscaler egress fees and reserved instance pricing unpredictability compress margins for managed service providers delivering fixed-price cloud optimization.
Strategic Opportunities
- Federated edge computing:Manufacturing and oil & gas operators in the United States and Saudi Arabia are deploying lightweight Kubernetes control planes for remote facility autonomy.
- Carbon-aware workload scheduling:EU Green Deal sustainability reporting requirements create demand for tools that route compute to low-carbon intensity regions and times.
- FinOps automation convergence:Integration of cost optimization engines with policy governance modules addresses procurement team demand for unified spend-and-risk visibility.
Industry Challenges
- Multi-framework compliance mapping:Security teams must manually reconcile SOC 2, ISO 27001, and sector-specific controls against dynamically provisioned resources lacking persistent identifiers.
- API versioning fragmentation:Hyperscaler control plane updates force quarterly integration rework for vendors maintaining connectors across AWS, Azure, and GCP.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Systems Management Software Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Healthcare, Education, BFSI, Manufacturing Solution: Monitoring, Automation, Security Management, Backup Service Type: Consulting, Integration, Support, Managed Services |
| Companies Covered | Apptio, Morpheus Data, Holori, Nutanix, CloudBolt, CloudHealth, Red Hat, HashiCorp, Flexera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Systems Management Software Market Strategic Shifts & Innovations
Platform engineering teams are collapsing traditional boundaries between infrastructure provisioning, cost management, and security policy enforcement. Vendors respond with modular architectures that expose unified REST APIs while permitting selective component procurement.
Kubernetes operators with embedded cost attribution logic are collapsing the distinction between workload orchestration and financial operations. Platform engineering teams at Fortune 500 manufacturers are deploying these controllers to enforce rightsizing policies before pod scheduling. The structural consequence is compression of standalone FinOps tooling margins as orchestration platforms absorb spend visibility natively.
The SEC's cybersecurity disclosure rules for publicly traded firms are mandating real-time incident reporting with materiality assessments. Chief Information Security Officers must now instrument cloud control planes for continuous evidence collection rather than periodic audit sampling. Healthcare and financial services verticals in the United States are accelerating procurement of automated compliance evidence generators to satisfy quarterly filing obligations.
Enterprise buying committees are consolidating vendor relationships around platforms delivering infrastructure-as-code, policy-as-code, and cost-as-code through single API contracts. Value-added resellers and systems integrators are repositioning as managed platform operators rather than implementation advisors. This pattern concentrates most visibly in Germany and the United Kingdom where regulated industries prioritize long-term support commitments over point solution innovation.
Cloud Systems Management Software Market Segmentation
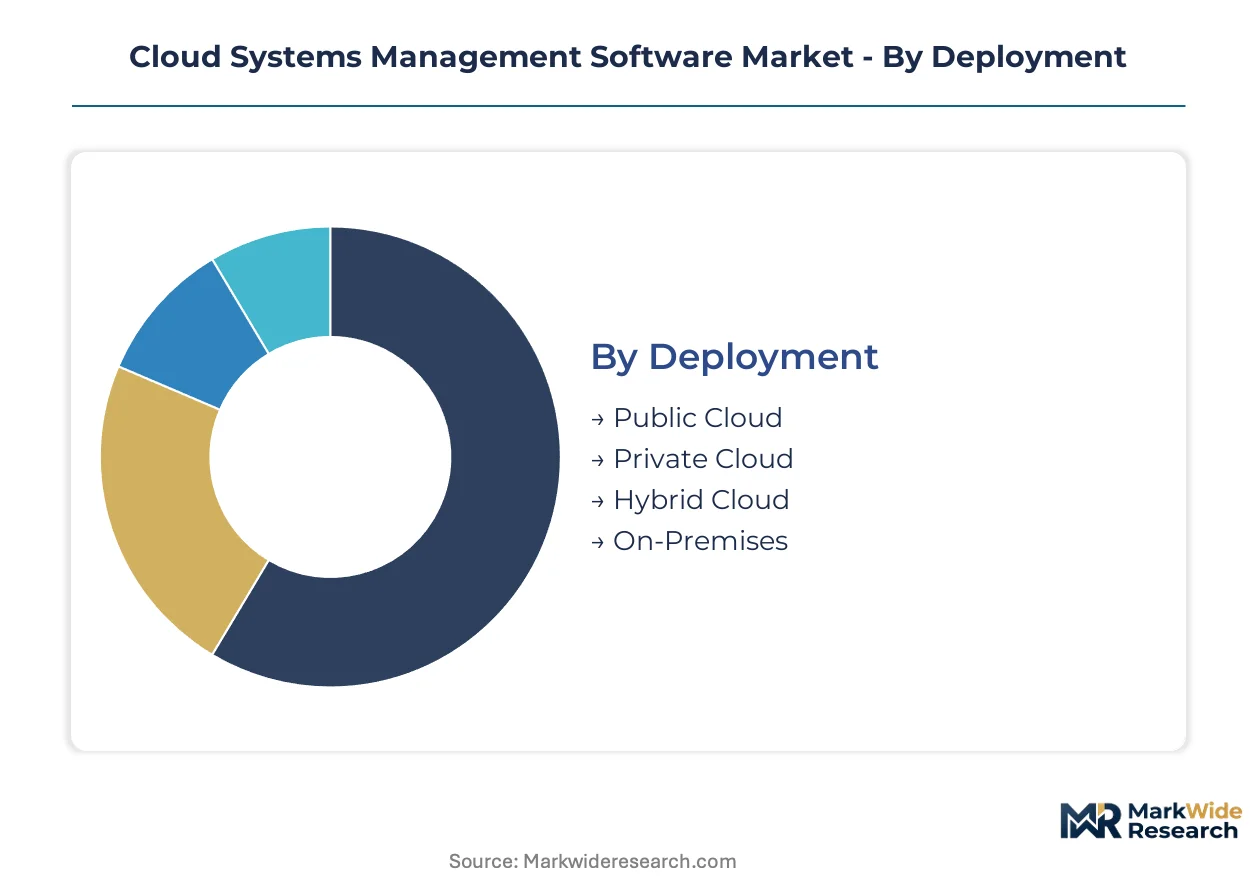
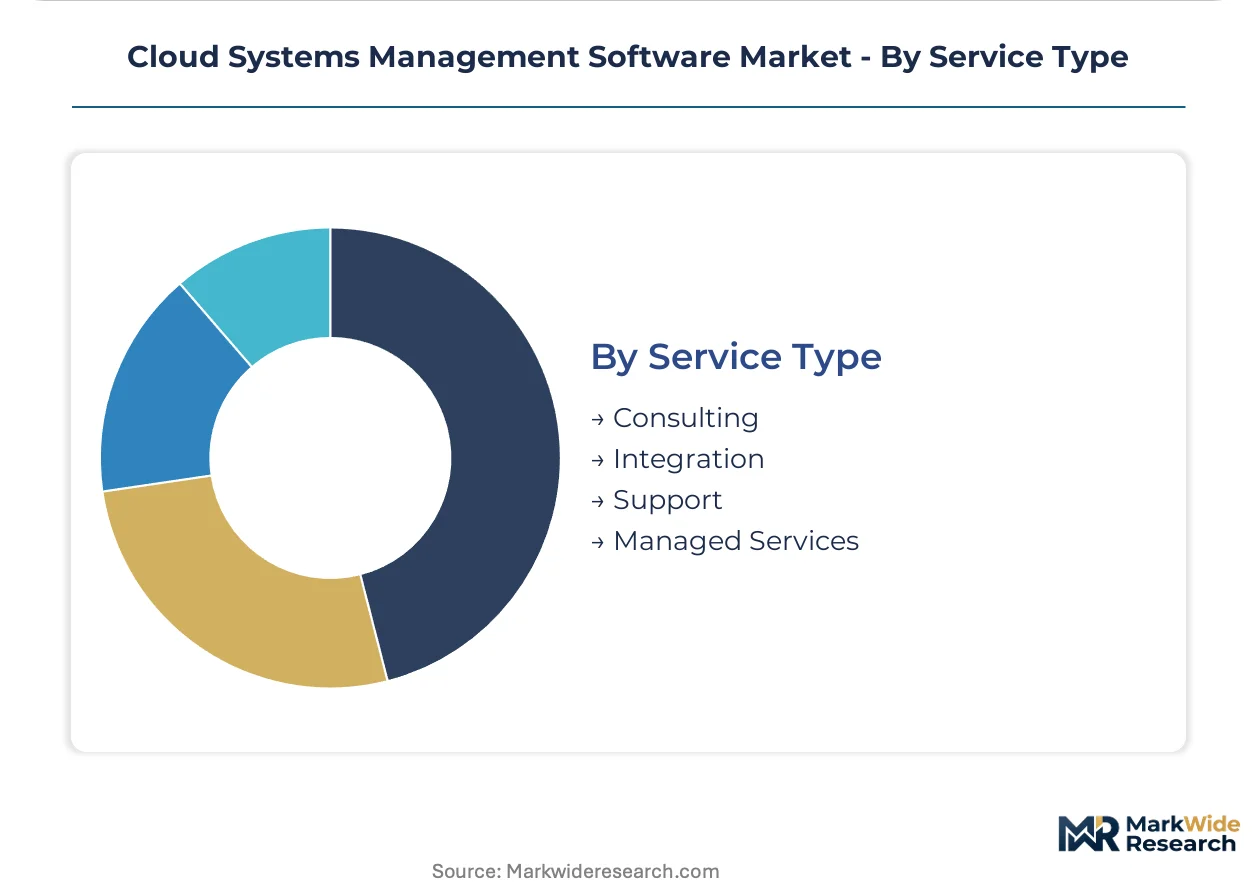
Cloud systems management software procurement patterns diverge sharply across deployment architectures and vertical compliance requirements. Understanding these segment boundaries enables vendors to align modular pricing with specific workload governance needs rather than selling undifferentiated platform licenses.
Deployment:
Use-case spectrum spans ephemeral burst computing to sovereign data retention mandates.
- Hybrid Cloud:Unified control planes orchestrate containerized workloads across on-premises Kubernetes estates and hyperscaler serverless functions. BFSI institutions in Germany and the United Kingdom prioritize this configuration to satisfy GDPR data residency while retaining elastic capacity for fraud-detection workloads.
- Private Cloud:Dedicated infrastructure with integrated compute-storage control planes enforces geographic access controls for sensitive records. Healthcare providers deploying FDA 21 CFR Part 11 validated systems drive procurement concentration here.
- Public Cloud:Shared infrastructure with API-native provisioning serves development and test environments. Cost optimization engines dominate purchasing criteria for this segment.
- On-Premises:Legacy estate management tools bridge mainframe batch systems and modern orchestration layers. Manufacturing facilities with air-gapped operational technology networks sustain residual demand.
The dominant share belongs to Hybrid Cloud, while Security Management integration is closing the gap fastest as zero-trust mandates harden.
End User:
Compliance burden intensity shapes procurement sophistication across verticals.
- BFSI:Algorithmic accountability requirements under EU AI Act drive automated governance tooling for credit-scoring pipelines. French and UK regulators enforce quarterly evidence collection for model drift monitoring.
- Healthcare:HIPAA security rule provisions and FDA validation requirements mandate encrypted audit trails with geographic access controls. Pharmaceutical manufacturers represent the highest-margin customer cohort.
- Manufacturing:Federated edge deployments for remote facility autonomy create demand for lightweight Kubernetes control planes. Oil and gas operators in the United States prioritize carbon-aware workload scheduling.
- Education:Cost-constrained institutions favor open-source orchestration with managed service overlays. Research universities with grant-funded infrastructure represent episodic large-deal volume.
BFSI commands the largest revenue pool, though Manufacturing is expanding most quickly through operational technology convergence.
Solution:
Functional module procurement is consolidating around unified policy engines.
- Security Management:Continuous compliance verification across ephemeral containers with real-time risk dashboards. SEC cybersecurity disclosure rules for publicly traded firms mandate quarterly filing automation.
- Automation:Infrastructure-as-code provisioning with embedded cost attribution logic collapses FinOps into orchestration platforms. Site Reliability Engineering teams at Fortune 500 manufacturers deploy these controllers for rightsizing enforcement.
- Monitoring:Observability pipelines with service-level objective tracking across distributed microservices. Baseline capability now table stakes rather than differentiator.
- Backup:Immutable snapshot management with ransomware recovery orchestration. Healthcare verticals drive premium pricing for validated recovery time objectives.
Security Management holds the dominant position, while Automation modules are climbing the fastest as platform engineering teams consolidate vendor relationships.
Service Type:
Delivery model preferences reflect internal capability maturity and regulatory exposure.
- Managed Services:Outsourced platform operations with fixed-price optimization commitments. German regulated industries prioritize long-term support contracts over point solution innovation.
- Integration:Middleware development for legacy VMware vSphere estates resisting API-native orchestration. Systems integrators reposition as managed platform operators here.
- Consulting:Control framework mapping to dynamic cloud resource topologies without manual policy translation. Short-cycle engagements face margin compression from automated assessment tools.
- Support:Tiered response commitments with escalation paths to engineering teams. Baseline expectation rather than revenue driver for enterprise accounts.
Managed Services captures the dominant share, with Integration services gaining traction fastest through legacy estate modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement elasticity varies sharply by regulatory exposure. German and French buyers prioritize compliance depth over unit cost, while US healthcare and manufacturing segments drive volume through operational technology convergence.
Germany
BFSI institutions in Frankfurt and Munich procure hybrid cloud orchestration platforms to satisfy GDPR data residency mandates. The Federal Financial Supervisory Authority enforces quarterly evidence collection for algorithmic accountability under EU AI Act implementation timelines. Bavarian automotive manufacturers deploy federated edge control planes for smart factory autonomy.
United States
Healthcare providers and pharmaceutical manufacturers demand FDA 21 CFR Part 11 validated systems with encrypted audit trails. SEC cybersecurity disclosure rules mandate real-time incident reporting with materiality assessments for publicly traded firms. Massachusetts and North Carolina biotech clusters accelerate procurement of automated compliance evidence generators.
United Kingdom
London-based financial institutions balance sovereign cloud controls against elastic compute requirements for fraud-detection workloads. The Financial Conduct Authority collaborates with EU regulators on cross-border algorithmic governance standards. Edinburgh and Manchester fintech hubs concentrate procurement of policy-as-code modules for credit-scoring pipelines.
France
Parisian banking groups automate governance tooling for model drift monitoring under CNIL supervision. The EU AI Act's risk-based classification system drives procurement of continuous compliance verification platforms. Lyon pharmaceutical manufacturers integrate carbon-aware workload scheduling to satisfy EU Green Deal sustainability reporting requirements.
Japan
Tokyo-based manufacturers deploy lightweight Kubernetes control planes for remote facility autonomy in automotive and electronics supply chains. METI guidelines on data sovereignty influence hybrid cloud architecture decisions. Osaka industrial clusters prioritize FinOps automation convergence for unified spend-and-risk visibility across multi-cloud estates.
Cloud Systems Management Software Market Key Industry Players
Infrastructure-centric platforms and policy-native specialists split the market along governance depth versus provisioning breadth. The vendor landscape organizes into three strategic archetypes: hyperscaler-agnostic orchestration engines, vertical compliance specialists, and integrated hyperconverged control plane providers. Consolidation pressure intensifies as enterprise buying committees demand unified API contracts spanning infrastructure-as-code, policy-as-code, and cost-as-code. Strategic partnerships between legacy systems integrators and cloud-native vendors accelerate legacy estate modernization cycles.
Within the policy-native specialist tier, HashiCorp and Flexera exemplify infrastructure-as-code provisioning expertise for multi-cloud estates. Nutanix occupies a position representing integrated hyperconverged private cloud management with unified compute and storage control planes. Red Hat anchors the open-source orchestration archetype through enterprise Kubernetes distribution and operator framework standardization.
| Leading Market Players |
|---|
| Apptio |
| Morpheus Data |
| Holori |
| Nutanix |
| CloudBolt |
| CloudHealth |
| Red Hat |
| HashiCorp |
| Flexera |
| Others |
Cost & Logistics Intelligence
Overcapacity in hyperscaler compute regions is compressing SaaS licensing margins while simultaneously expanding buyer negotiating leverage across enterprise procurement cycles. This utilization imbalance forces vendors to bundle professional services into subscription tiers, reshaping how platform engineering teams evaluate total cost of ownership against standalone module pricing.
Pricing Analysis
Managed service and integration revenue tiers now drive lifetime value capture as vendors pivot from perpetual licenses to consumption-based arrangements. Three-tier pricing structure across premium, standard, and economy levels segments by compliance certification depth, with GDPR-validated deployments commanding substantial premiums over baseline configurations. Pricing pressure stems from open-source Kubernetes distributions commoditizing core orchestration capabilities. Mid-market manufacturers exhibit highest price sensitivity, while BFSI institutions in Germany and France prioritize sovereign controls over unit cost optimization.
Supply Chain Analysis
Upstream feedstock for cloud management platforms centers on hyperscaler API infrastructure concentrated in the United States, Ireland, and Singapore. Core dependencies include Kubernetes distribution licensing, Terraform provider ecosystems, and compliance engine SDKs. Single-source vulnerability runs through HashiCorp's provider registry dominance for infrastructure-as-code provisioning. Distribution runs through value-added resellers repositioning as managed platform operators, with systems integrators capturing margin on legacy VMware vSphere bridging engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buying committees are consolidating vendor relationships, shifting procurement power toward Fortune 500 platform engineering teams capable of demanding unified API contracts spanning infrastructure, policy, and cost governance.
For Market Incumbents: Harden defensive moats by embedding FinOps automation natively into orchestration control planes before standalone cost optimization tools capture adjacent spend. Acquire policy-as-code specialists to address EU AI Act compliance mandates without manual translation layers. Expand managed services footprint in Frankfurt and London to secure long-term support commitments from regulated BFSI institutions. For New Entrants and Emerging Players: Build out lightweight Kubernetes control planes for federated edge deployments in United States manufacturing and Saudi Arabian oil and gas facilities, where operational technology convergence creates greenfield procurement opportunities. Target carbon-aware workload scheduling modules as the most penetrable niche, with EU Green Deal sustainability reporting requirements mandating real-time emissions attribution. Pursue OEM partnerships with industrial automation vendors to bypass direct enterprise sales cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among policy-native specialists with embedded compliance engine technology, suggesting superior long-term viability through regulatory tailwinds. Prioritize acquisition targets possessing validated healthcare sector deployments with FDA 21 CFR Part 11 audit trail capabilities. Watch for inflection signals in SEC cybersecurity disclosure rule enforcement accelerating real-time risk dashboard procurement among publicly traded firms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies infrastructure-as-code, policy-as-code, and cost-as-code through single API contracts for German BFSI buyers. |
| Acquisition of Specialist Firm | Absorbs FinOps automation capabilities before orchestration platforms commoditize standalone cost optimization tooling. |
| Strategic Partnership | Accelerates legacy VMware vSphere modernization through systems integrator repositioning as managed platform operators. |
| Product Launch | Addresses EU AI Act algorithmic accountability mandates with automated governance tooling for credit-scoring pipelines. |
| Geographic Expansion | Establishes sovereign cloud controls in United Kingdom and France to capture GDPR data residency procurement concentration. |
Research Approach
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, SEC cybersecurity filings, EU regulatory implementation timelines, and healthcare IT procurement databases. Interviews with platform engineering directors, CISOs at publicly traded firms, healthcare compliance officers, and systems integration specialists informed demand-side validation. Bottom-up sizing of module-level procurement and top-down reconciliation against vendor-reported subscription revenue established segment boundaries.
Forecast inputs span deployment architecture adoption curves, vertical compliance mandate enforcement timelines, and hyperscaler API versioning fragmentation costs across the analysis window. Segmentation dimensions modeled include hybrid versus sovereign deployment configurations, BFSI versus healthcare versus manufacturing vertical intensity, and solution layer consolidation patterns. CAGRs derive from elasticity-adjusted procurement velocity curves and regulatory deadline clustering effects.
Stress conditions across hyperscaler egress fee volatility, Site Reliability Engineer talent scarcity, and EU AI Act enforcement variance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation pacing and enterprise cloud migration saturation. Cross-checking against hyperscaler earnings call commentary on enterprise commitment volume is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud ECS Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Cloud Management Platform Market
Cloud Computing
Cloud Applications Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Community Cloud Market
Cloud Computing
Hadoop-As-A-Service (Haas) Market
Cloud Computing
Consumer Cloud Subscription Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Healthcare Cloud Computing Software Market
Cloud Computing
Global Marketing Cloud Platform Market
Cloud Computing
Dbaas and Cloud Database Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
Telecom Cloud Market