
 Public Cloud Application Infrastructure Services Market | 2026-2036
Public Cloud Application Infrastructure Services Market Size, Share, and Industry Trends Forecast 2026-2036
Public Cloud Application Infrastructure Services Market Outlook
Partner and reseller channel economics is reconfiguring as hyperscalers shift from volume-based rebates to consumption-linked co-sell incentives. Amazon Web Services (AWS) leverages its marketplace fee structure to capture recurring software revenue alongside infrastructure spend. Microsoft Azure anchors enterprise loyalty through bundled entitlements spanning productivity, security, and data platforms. Google Cloud differentiates on price-performance for compute-intensive AI training workloads.
Public Cloud Application Infrastructure Services encompass compute, storage, networking, and middleware resources delivered via shared, multi-tenant data centers with API-driven provisioning and metered billing. These services abstract physical hardware management, enabling developers to deploy containerized applications through orchestration layers such as Kubernetes without capital expenditure on servers. Platform-as-a-Service offerings now command the deepest margin pools as vendors integrate database, analytics, and AI tooling above raw infrastructure. Function-as-a-Service adoption accelerates fastest among event-driven architectures, though single-tenant deployments retain traction in BFSI for regulatory isolation.
FDA 21 CFR Part 11 guidelines for electronic records shape healthcare cloud deployments, while EU GDPR and the EU AI Act impose data residency and algorithmic accountability requirements that constrain cross-border workload placement. The SEC's cybersecurity disclosure rules for publicly traded firms now mandate incident reporting timelines that influence cloud monitoring architecture decisions. Stakeholders must weigh sovereign cloud certifications against latency-optimized edge locations when selecting primary regions for regulated workloads.
Market Dynamics
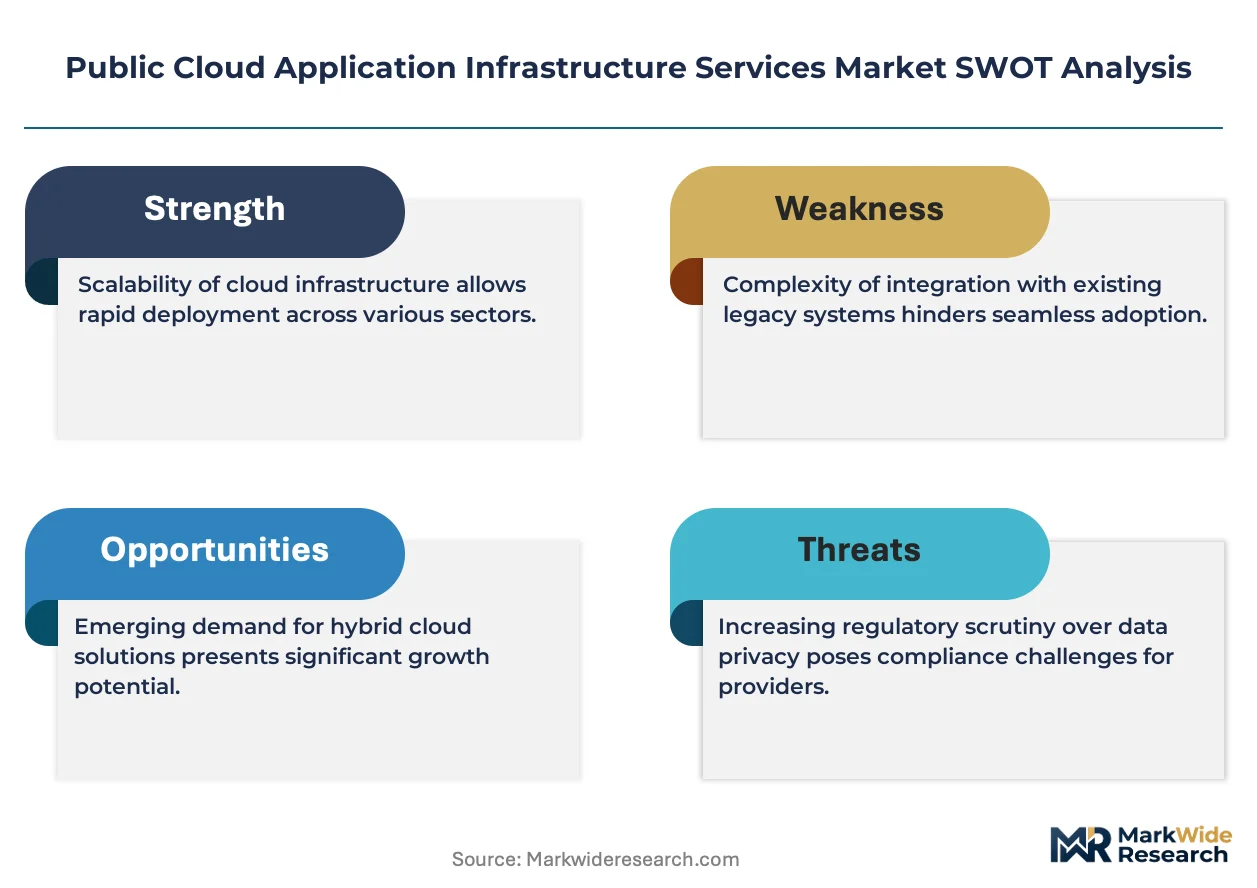
Hyperscaler marketplace fee structures are redistributing margin pools from infrastructure providers to platform-integrated software vendors, compressing standalone compute pricing while elevating data services and AI tooling premiums.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic accountability requirements under the EU AI Act are compelling financial services firms to deploy sovereign cloud architectures with auditable inference pipelines.
- Kubernetes orchestration standardization:Container orchestration layers now dominate automotive and industrial ERP migrations, with German manufacturers leading managed environment adoption.
- Event-driven serverless architectures:Function-as-a-Service deployment models are accelerating among retail and logistics operators processing high-velocity transaction streams.
Market Restraints
- Specialized silicon supply concentration:GPU and TPU availability for AI training workloads remains bottlenecked by Taiwan and South Korea foundry capacity.
- Cross-border data friction:GDPR data residency requirements impose latency penalties on workloads requiring EU-US synchronization.
- Substitution by private cloud:Single-tenant deployments retain traction in BFSI segments seeking regulatory isolation from multi-tenant infrastructure.
Strategic Opportunities
- Edge-to-cloud continuum in manufacturing:Industrial IoT convergence with managed Kubernetes creates white space for latency-optimized application platforms.
- Healthcare compliance specialization:FDA 21 CFR Part 11 validation frameworks for electronic records open specialized hosting segments.
- Carbon accounting integration:CSRD sustainability disclosure requirements create demand for workload-level emissions tracking and renewable energy matching.
Industry Challenges
- Platform engineering talent scarcity:Organizations struggle to hire engineers proficient in multi-cloud Kubernetes management and FinOps cost optimization.
- Legacy mainframe integration complexity:Financial institutions face protracted timelines connecting core banking systems to cloud-native microservices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Cloud Application Infrastructure Services Market |
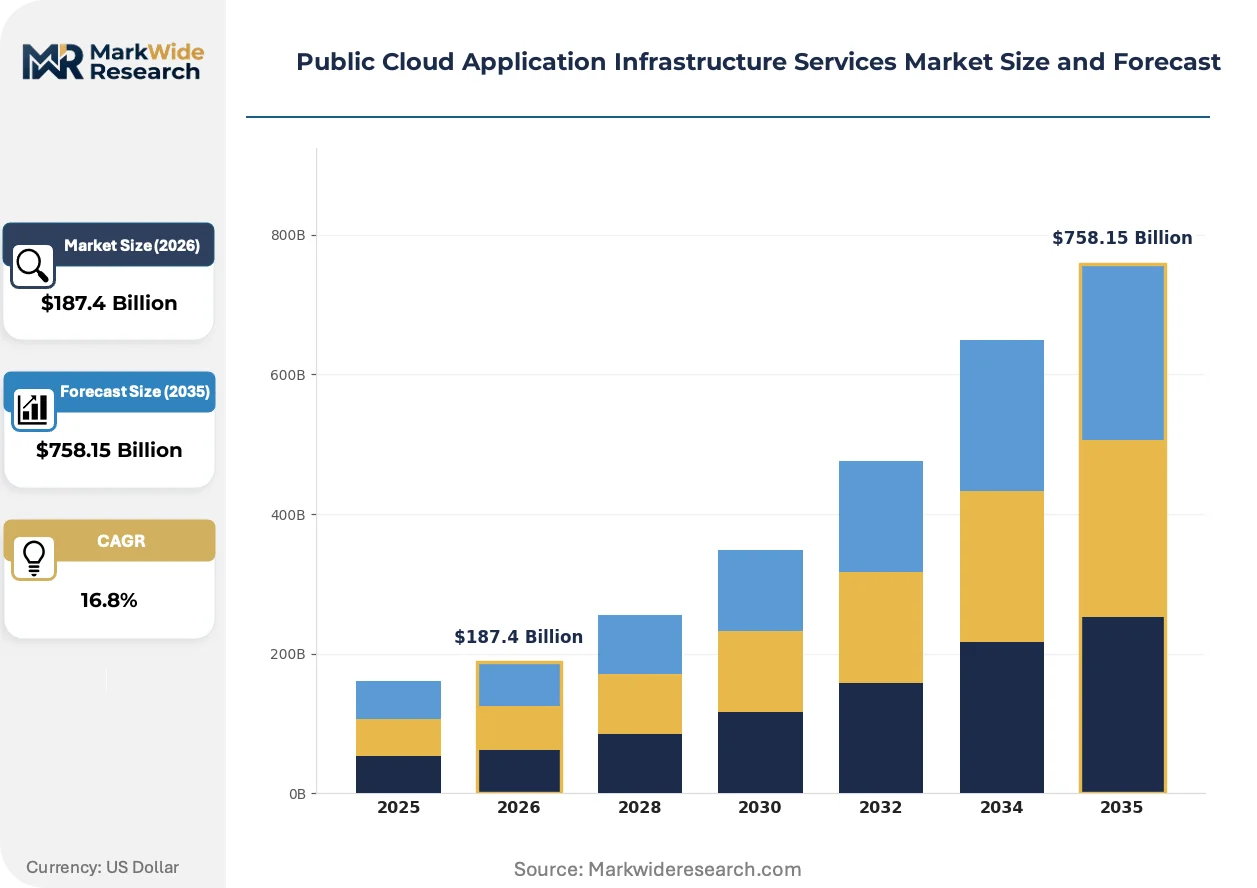
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: IaaS, PaaS, SaaS, FaaS Deployment Model: Single Tenant, Multi-Tenant, Hybrid Cloud, Community Cloud Customer Type: SMBs, Large Enterprises, Government, Educational Institutions End User: IT & Telecom, BFSI, Healthcare, Retail |
| Companies Covered | Amazon Web Services (AWS), Microsoft Azure, Google Cloud, Oracle Cloud Infrastructure, Alibaba Cloud, IBM Cloud, Tencent Cloud, SAP, OVHcloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Cloud Application Infrastructure Services Market Strategic Shifts
Workload abstraction layers are compressing the distinction between infrastructure and application platforms, enabling developers to deploy without managing underlying compute topology.
WebAssembly runtime environments are collapsing the boundary between edge and cloud execution, allowing automotive and industrial firms to deploy identical application binaries across factory floor gateways and hyperscaler regions. Siemens and Bosch pilot programs demonstrate sub-50 millisecond inference for quality control models. This convergence is collapsing separate edge and cloud procurement budgets into unified platform contracts.
CSRD sustainability disclosure mandates are forcing cloud consumers to demand granular carbon accounting for every workload hour. The regulation requires Scope 3 emissions reporting that captures supply chain energy consumption. German automotive suppliers now specify renewable energy matching and hourly carbon intensity metrics in vendor selection criteria.
Consumption-based commercial terms are displacing committed-use discount contracts as the dominant procurement framework. Enterprise buyers in financial services and healthcare are negotiating pay-per-request models for AI inference rather than reserved instance pools. This behavioral shift is most pronounced in London and Frankfurt, where treasury functions prioritize OpEx flexibility over long-term capacity planning.
Public Cloud Application Infrastructure Services Market Segmentation
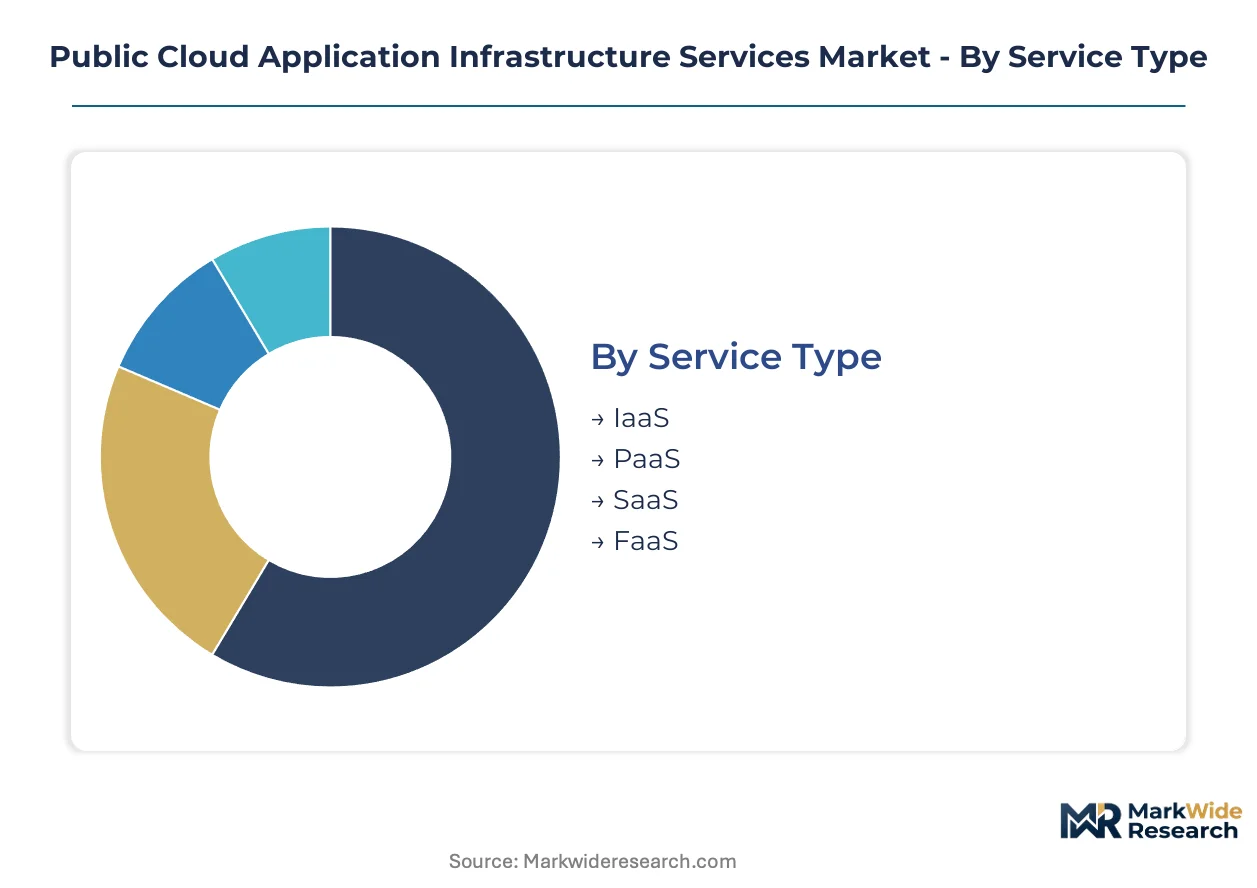
Segmentation in cloud infrastructure services reveals distinct operational and commercial patterns. Service type determines margin structure and renewal mechanics. Deployment model shapes compliance posture and capital efficiency. Customer type governs contract duration and support intensity. End user vertical dictates regulatory exposure and solution bundling.
Service Type:
After-sales-service intensity escalates sharply as vendors move up the abstraction stack from raw infrastructure to managed platforms.
- IaaS:Bare compute, storage, and networking resources provisioned through APIs. German automotive manufacturers consume IaaS for ERP system hosting where direct hardware control remains necessary. Procurement teams negotiate reserved instance pools against spot market arbitrage.
- PaaS:Integrated development environments with embedded database, analytics, and middleware tooling. Financial services firms in Frankfurt deploy PaaS for microservices architectures requiring rapid scaling without infrastructure management overhead.
- SaaS:Fully managed application layers with vendor-controlled updates and security patching. Healthcare providers leverage SaaS for electronic health records where FDA 21 CFR Part 11 validation frameworks apply.
- FaaS:Event-driven compute triggered by specific API calls or data streams. Retail and logistics operators in London process high-velocity transaction streams through pay-per-request billing models.
By volume, IaaS leads. By growth pace, FaaS is expanding most quickly.
Deployment Model:
Cost tier differentiation separates commodity multi-tenant offerings from premium single-tenant configurations with dedicated hardware isolation.
- Single Tenant:Physically isolated infrastructure stacks serving one client. BFSI segments in Switzerland and Luxembourg mandate single-tenant deployments for regulatory isolation from co-tenancy risks.
- Multi-Tenant:Shared physical resources with logical separation via hypervisors and container runtimes. Startups and digital-native firms prioritize multi-tenant economics for dev-test workloads.
- Hybrid Cloud:Orchestrated workload placement across on-premises data centers and public cloud regions. Industrial manufacturers in Stuttgart operate hybrid configurations for latency-sensitive factory floor systems.
- Community Cloud:Shared infrastructure among organizations with common compliance requirements. EU research consortia deploy community clouds to satisfy GDPR data residency while pooling specialized compute resources.
By volume, multi-tenant dominates. By growth pace, hybrid cloud is gaining share fastest.
Customer Type:
Application complexity scales with organizational size, driving divergent platform engineering and FinOps capability requirements.
- SMBs:Organizations with limited internal cloud expertise purchasing through managed service provider channels. UK mid-market retailers adopt serverless architectures to avoid platform engineering hiring.
- Large Enterprises:Multinational corporations with dedicated cloud centers of excellence negotiating enterprise discount programs. French banking groups maintain multi-year committed use agreements across three hyperscalers.
- Government:Public sector entities requiring sovereign cloud certifications and domestic data residency. German federal agencies specify ISO 27001 and BSI C5 compliance in procurement tenders.
- Educational Institutions:Universities and research organizations consuming grant-funded cloud credits for compute-intensive workloads. ETH Zurich and TU Munich leverage academic pricing tiers for AI training clusters.
By volume, large enterprises lead. By growth pace, government is climbing the fastest.
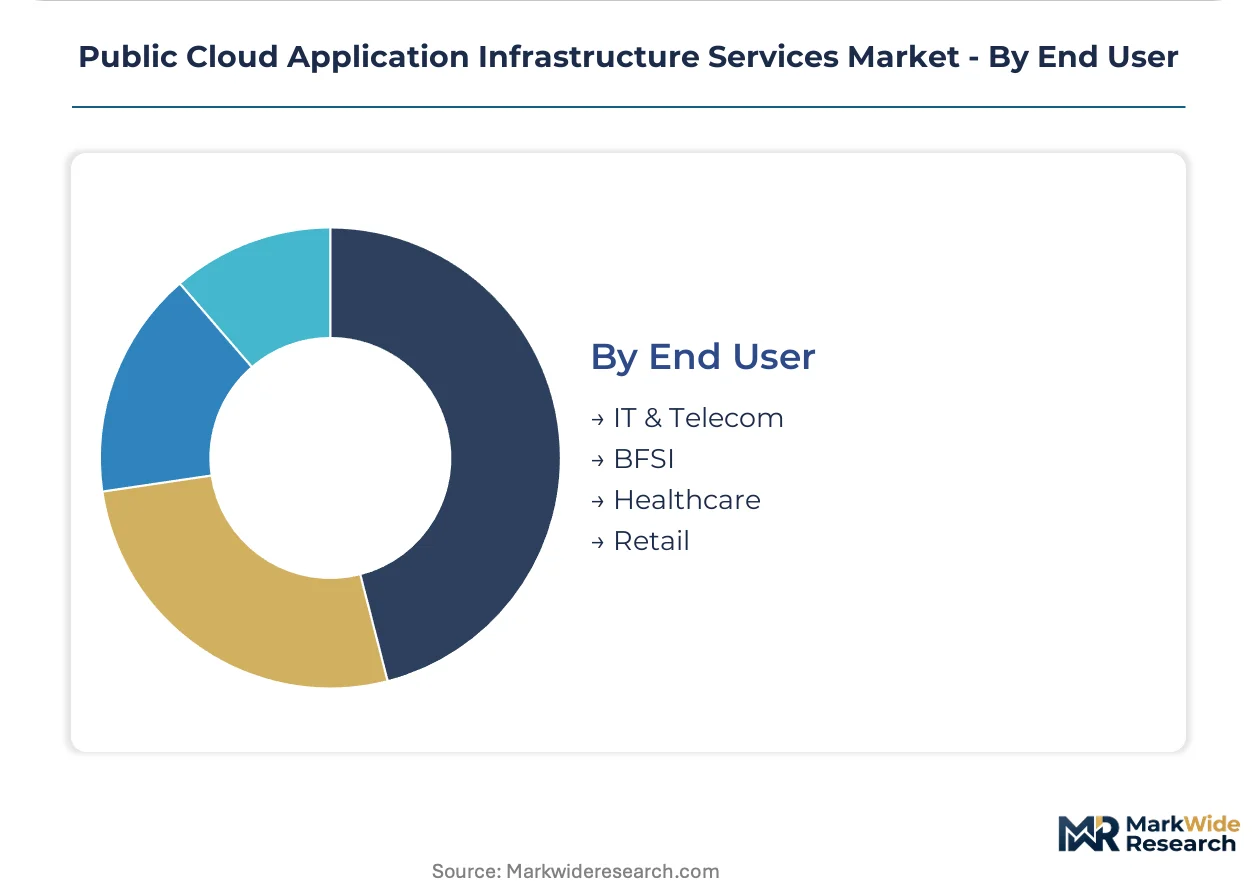
End User:
Maturity variation across verticals produces distinct procurement rhythms and solution integration patterns.
- IT & Telecom:Technology-native organizations with sophisticated multi-cloud management practices. Telefónica and Deutsche Telekom operate self-managed Kubernetes platforms across heterogeneous infrastructure.
- BFSI:Heavily regulated financial institutions balancing innovation velocity against compliance rigor. Dutch banks deploy sovereign cloud architectures to satisfy DNB supervisory expectations on operational resilience.
- Healthcare:Providers and life sciences firms navigating FDA and EMA validation requirements for electronic records. Danish hospital systems specify workload-level carbon accounting to meet CSRD disclosure mandates.
- Retail:Omnichannel merchants processing seasonal demand spikes and real-time personalization. Scandinavian fashion retailers adopt consumption-based commercial terms to align cloud spend with revenue volatility.
By volume, IT & Telecom leads. By growth pace, healthcare shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure pricing power concentrates in the United States while European markets command premium sovereign-certified configurations. German automotive manufacturers absorb 15-20% cost premiums for BSI C5 compliance. Indian hyperscaler regions compete aggressively on compute unit economics.
United States
Financial services firms in New York and Chicago drive sovereign cloud demand for SEC cybersecurity disclosure compliance. The SEC mandates incident reporting timelines that reshape monitoring architecture procurement. Silicon Valley technology clusters consume the highest density of GPU-enabled training instances.
Germany
Automotive ERP migrations to managed Kubernetes dominate Stuttgart and Munich industrial corridors. BSI C5 certification requirements filter vendor eligibility for federal procurement. Bavarian manufacturing consortia specify hourly carbon intensity metrics under CSRD disclosure mandates.
United Kingdom
London treasury functions prioritize consumption-based commercial terms over committed-use discounts. The Financial Conduct Authority's operational resilience rules influence multi-region redundancy architecture. Edinburgh and Manchester fintech clusters adopt pay-per-request billing for AI inference workloads.
India
Bengaluru and Hyderabad technology campuses expand hyperscaler region capacity for SaaS export markets. RBI data localization guidelines constrain cross-border workload placement for payment systems. Maharashtra banking consortia negotiate sovereign cloud configurations for core ledger isolation.
France
Paris banking groups maintain multi-year committed use agreements across three hyperscaler ecosystems. ANSM healthcare data requirements shape pharmaceutical cloud hosting specifications. Lyon and Toulouse aerospace clusters demand ISO 27001 certification for defense-adjacent workloads.
Public Cloud Application Infrastructure Services Market Competitive Environment
Hyperscale incumbents and sovereign specialists split the market into distinct capability tiers. Three hyperscalers capture the majority of enterprise workload volume through integrated platform ecosystems. Tier-two cloud providers compete on regulatory specialization and data residency guarantees. Competitive moves concentrate on marketplace fee restructuring and sovereign certification acquisition.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud exemplify divergent monetization strategies. AWS leverages marketplace fee structures to capture recurring software revenue alongside infrastructure consumption. Microsoft Azure anchors enterprise loyalty through bundled productivity and security entitlements. Google Cloud occupies a position emphasizing price-performance for compute-intensive AI training. Among European sovereign specialists, OVHcloud represents the regulatory-isolation archetype with domestic data center presence.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft Azure |
| Google Cloud |
| Oracle Cloud Infrastructure |
| Alibaba Cloud |
| IBM Cloud |
| Tencent Cloud |
| SAP |
| OVHcloud |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific cable routes linking Singapore to Los Angeles transmit pricing signals that hyperscalers use to arbitrage compute capacity across regions, compressing standard IaaS margins while elevating premiums for sovereign-certified configurations with BSI C5 or ISO 27001 validation.
Pricing Analysis
The customization-premium spread between standard multi-tenant compute and configured-to-order sovereign deployments reaches 15-20 percentage points in Germany. Three-tier pricing structure across premium, standard, and economy levels dominates procurement frameworks, with financial services firms absorbing certification premiums for algorithmic accountability under EU AI Act mandates. Cost compression in raw compute tiers is intensifying because hyperscaler marketplace fee structures redistribute margin pools to platform-integrated software vendors. SMB segments exhibit highest price sensitivity, prioritizing pay-per-request serverless models, while government buyers demonstrate lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Contract-manufacturing concentration for specialized AI training silicon rests on Taiwan Semiconductor Manufacturing and Samsung Foundry capacity in Taiwan and South Korea. Hyperscaler region buildouts draw from US, Ireland, and Singapore data center construction pipelines. GPU and TPU availability feeds from concentrated foundry output in East Asia. Single-source vulnerability in advanced node semiconductor fabrication creates procurement bottlenecks for compute-intensive workloads. Distribution runs through direct enterprise sales organizations and hyperscaler marketplace channels with consumption-linked co-sell incentives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Public cloud application infrastructure services occupy an early-cycle expansion phase as EU AI Act compliance mandates accelerate sovereign cloud adoption across financial services and automotive manufacturing verticals.
For Market Incumbents: Build switching-cost moats through deep integration of database, analytics, and AI tooling above raw infrastructure layers. Incumbents should anchor enterprise loyalty via bundled productivity and security entitlements spanning multi-year contracts. Sovereign certification acquisition in Germany and France filters vendor eligibility for federal procurement tenders. Marketplace fee restructuring captures recurring software revenue alongside infrastructure consumption, defending against standalone compute price erosion.
For New Entrants and Emerging Players: Build out specialized sovereign cloud configurations targeting BFSI segments in Switzerland and Luxembourg seeking regulatory isolation from multi-tenant infrastructure. Healthcare compliance specialization around FDA 21 CFR Part 11 validation frameworks represents the most penetrable white space. Carbon accounting integration for CSRD sustainability disclosure requirements offers differentiated positioning. A channel partnership route through managed service providers accelerates access to SMB buyers lacking internal platform engineering capabilities.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates spinning out captive cloud infrastructure units built for automotive ERP migrations. Long-term viability hinges on sustained enterprise workload consolidation and sovereign cloud premium durability. Acquisition candidates include regional sovereign specialists with domestic data center presence and BSI C5 or ISO 27001 certification portfolios. The signal to watch is hyperscaler capex allocation shifts toward GPU-enabled training clusters versus general-purpose compute expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | BSI C5 and ISO 27001 credentials unlock German federal procurement tenders. |
| Platform Integration | Embedded database and AI tooling deepens margin pools above raw infrastructure. |
| Consumption-Based Commercial Terms | Pay-per-request billing aligns cloud spend with revenue volatility in retail. |
| Edge-to-Cloud Continuum | WebAssembly runtime convergence collapses separate edge and cloud procurement budgets. |
| Carbon Accounting Integration | Hourly carbon intensity metrics satisfy CSRD disclosure mandates for automotive suppliers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud center of excellence leads, platform engineering directors, IT procurement officers, and channel partner executives. Secondary validation drew from SEC filings documenting hyperscaler capex allocations, EU regulatory filings tracking AI Act implementation, customs data on semiconductor equipment imports, and academic pricing tier disclosures from research institutions. Bottom-up triangulation across customer-type spending patterns and top-down reconciliation against vendor-reported infrastructure revenue produced convergent market sizing estimates.
Calibration against historical hyperscaler revenue disclosures and sovereign cloud certification adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type abstraction level, deployment model compliance posture, customer-type platform engineering maturity, and end-user vertical regulatory exposure. CAGRs were derived from curve-fitting adoption rates against penetration ceilings by segment. Forecast inputs incorporated GPU availability constraints from foundry capacity data and EU AI Act implementation timelines.
Stress conditions across semiconductor supply bottlenecks, cross-border data friction penalties, and sovereign certification backlog durations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding enterprise workload migration velocity and hyperscaler pricing discipline. Quarterly review of hyperscaler capex allocation shifts and sovereign cloud certification issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Public Finance Cloud Market
Cloud Computing
Cloud Management Platform Market
Cloud Computing
Telecom Cloud Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Global Cloud Business Email Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Consumer Cloud Subscription Market
Cloud Computing
Cloud Enablement Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
SME Cloud Market
Cloud Computing
Europe Cloud Computing Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Europe Mobile Cloud Market