
 Multi-Cloud Optimization Tools Market | 2026-2036
Multi-Cloud Optimization Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Cloud Optimization Tools Market Foresight
ISO 27001 certification cycles are bifurcating vendor viability in multi-cloud optimization, separating enterprise-ready platforms from point-solution providers. Microsoft leverages its Azure Arc control plane to extend hybrid visibility across AWS and Google Cloud estates. VMware anchors on-premises-to-cloud workload portability, sustaining relevance as enterprises retain private infrastructure. Flexera competes through software asset management integration, occupying a defensible niche in license-optimized cloud migration.
Multi-cloud optimization tools are software platforms that aggregate cost, performance, and governance telemetry across disparate cloud service providers, typically ingesting billing APIs, utilization metrics, and policy frameworks to automate workload placement and resource rightsizing. Their primary commercial purpose is eliminating redundancy and contractual waste in environments where enterprises operate simultaneously on Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Hybrid cloud deployment models command the largest existing footprint as regulated industries maintain sensitive data on private infrastructure while bursting to public capacity. Cost management solutions within the solution-type dimension generate the deepest margin pools, since FinOps teams prioritize immediate spend reduction over incremental performance gains. Security and compliance modules represent the fastest-expanding segment, driven by cross-border data residency mandates and sector-specific audit requirements.
FCC guidelines on telecommunications infrastructure resilience indirectly shape multi-cloud procurement patterns for US-based carriers, while GDPR and the EU AI Act impose algorithmic transparency and data-localization obligations that optimization vendors must embed as policy engines. ISO standards, SOC 2 Type II attestations, and country-specific financial services regulations collectively determine which platforms qualify for regulated industry RFPs. Stakeholders should monitor how NIS2 implementation across European member states recalibrates cross-border workload routing logic and vendor certification thresholds.
Market Dynamics
FinOps team maturation is compressing vendor evaluation cycles, forcing multi-cloud optimization platforms to demonstrate ROI within 90-day proof-of-concept windows rather than traditional annual procurement timelines.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Financial services firms in Germany and France must embed explainable workload routing into cloud orchestration stacks, creating procurement urgency for governance-embedded tools.
- Containerized workload portability:Kubernetes-native optimization layers enable burst capacity management across AWS, Azure, and Google Cloud without vendor lock-in penalties.
- US enterprise cloud sprawl:Fortune 500 technology departments average 4.7 distinct cloud contracts, generating redundant spend that optimization platforms target for elimination.
Market Restraints
- API rate limiting and data egress fees:Cloud providers impose throttling on third-party optimization tools accessing billing telemetry, degrading real-time visibility.
- Specialized FinOps talent scarcity:Enterprises in secondary US metro markets struggle to hire practitioners capable of interpreting multi-cloud cost allocation models.
- On-premises legacy integration friction:Mainframe-dependent insurers and banks face 18-24 month modernization timelines before optimization tools achieve full coverage.
Strategic Opportunities
- India's data localization requirements:RBI-mandated financial data residency creates demand for optimization tools that route sensitive workloads to domestic cloud regions while bursting non-sensitive compute internationally.
- Carbon-aware workload scheduling:Convergence of sustainability telemetry APIs with cost optimization engines enables emissions-weighted placement decisions.
- Embedded insurance procurement:Cloud cost overage protection products distributed through broker channels represent an underdeveloped revenue stream for optimization vendors.
Industry Challenges
- SOC 2 Type II attestation timelines:Vendor security audits consume 9-14 months, delaying enterprise sales cycles and consuming technical founder bandwidth.
- Cross-cloud identity federation complexity:IAM policy synchronization across AWS IAM, Azure AD, and Google Cloud IAM requires dedicated engineering resources that mid-market buyers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Cloud Optimization Tools Market |
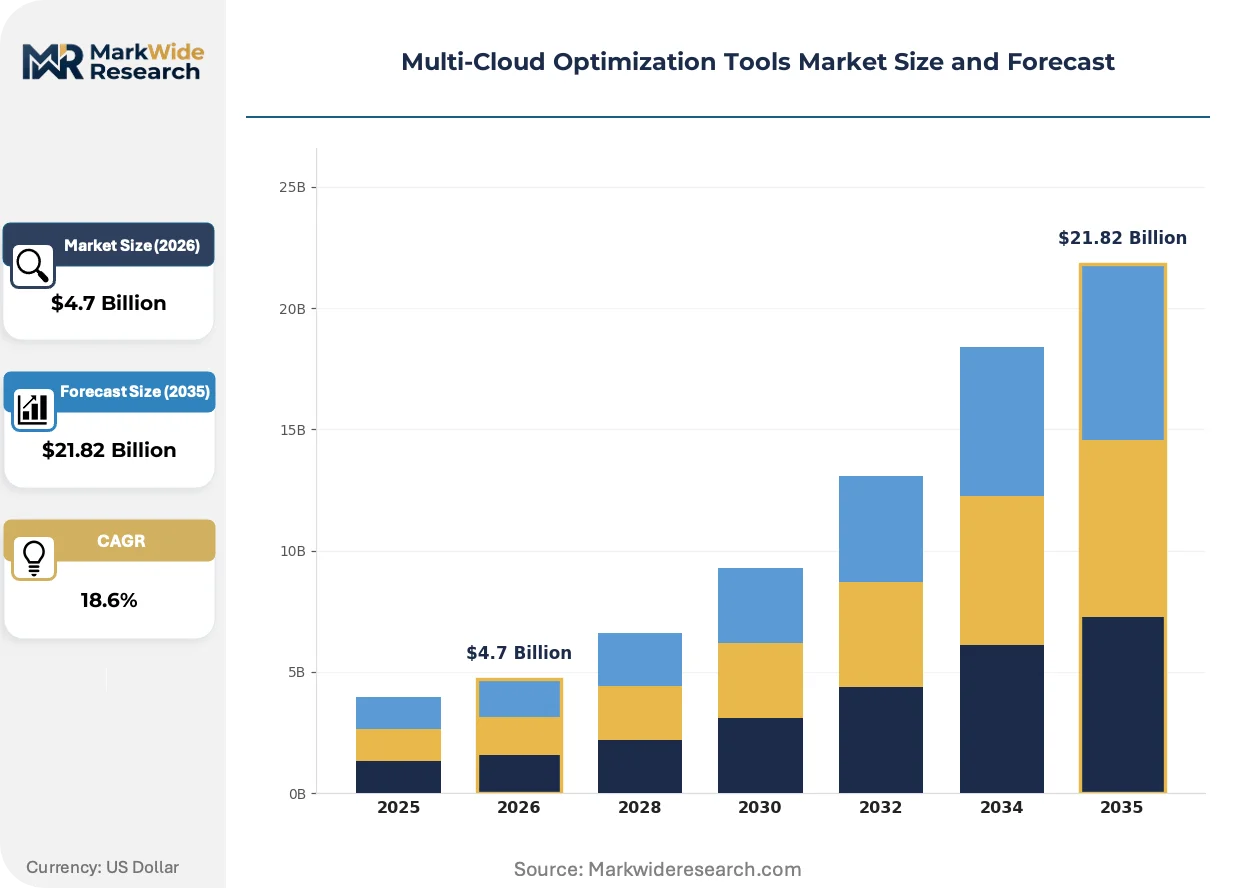
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Cost Management, Performance Monitoring, Security, Compliance Service Type: Consulting, Integration, Support, Training End User: SMEs, Large Enterprises, Government, Non-Profit |
| Companies Covered | Microsoft, Amazon, Google, IBM, VMware, Ternary, Morpheus Data, CloudBolt, Flexera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Cloud Optimization Tools Market Shifts & Advancements
Agentic AI architectures are redefining how optimization platforms interact with cloud control planes, shifting from rule-based automation toward autonomous workload negotiation.
Agentic cost optimization is fragmenting traditional FinOps workflows. These systems autonomously negotiate spot instance pricing and execute rightsizing decisions without human approval loops. Mid-market SaaS vendors with lean infrastructure teams adopt these capabilities fastest. The technology is fragmenting vendor competitive positioning, separating platforms with native AI agents from those reliant on static policy engines.
GDPR Article 44 transfer mechanism enforcement is tightening cross-border workload routing. European data protection authorities now require documented technical safeguards for optimization tools processing EU personal data in non-EU cloud regions. German automotive manufacturers and French healthcare providers face the strictest audit scrutiny, accelerating procurement of region-locked optimization stacks.
Consumption-based vendor pricing is displacing seat-license models across enterprise procurement. Buyers now demand optimization platforms that charge as a percentage of realized savings rather than fixed annual fees. This pattern concentrates most visibly among US-based technology companies with variable cloud spend, where finance teams refuse to commit to base rates during budget contraction cycles.
Multi-Cloud Optimization Tools Market Segmentation
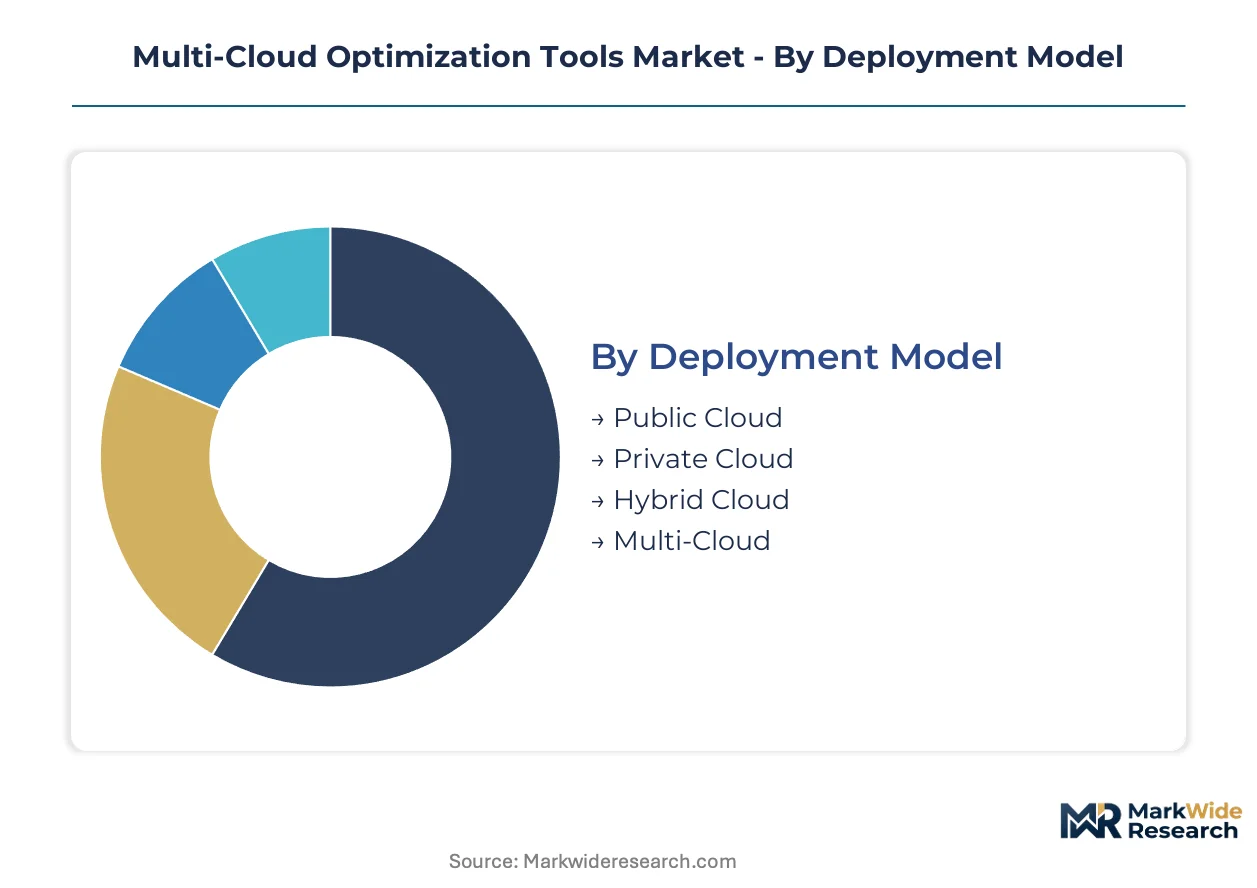
Multi-cloud optimization tools fragment across deployment architecture, functional purpose, service delivery, and buyer scale. Each segmentation axis carries distinct margin profiles and competitive intensity that reshape vendor go-to-market priorities.
Deployment Model:
Hybrid cloud deployments face intensifying substitution pressure from native cloud provider cost explorers, while pure multi-cloud orchestration layers defend through cross-provider arbitrage capabilities.
- Public Cloud:Optimization tools here ingest AWS, Azure, and Google Cloud billing APIs to automate reserved instance purchasing and spot market bidding. US SaaS vendors with variable compute loads concentrate demand for these capabilities as finance teams demand immediate spend visibility.
- Hybrid Cloud:Platforms bridge on-premises VMware estates with public burst capacity, maintaining workload portability through Kubernetes abstraction layers. German automotive manufacturers and French healthcare providers anchor procurement here due to GDPR Article 44 data residency constraints.
- Private Cloud:Tools optimize OpenStack and proprietary infrastructure stacks for regulated financial institutions. The RBI's data localization mandates in India drive domestic cloud region routing requirements.
- Multi-Cloud:Orchestration layers spanning three or more providers enable vendor-agnostic workload placement. Container-native optimization engines gain traction among mid-market technology companies seeking lock-in avoidance.
Hybrid cloud anchors the volume base while multi-cloud deployments gain share at the steepest rate.
Solution Type:
Cost management modules command the deepest margin pools through direct savings-linked pricing, whereas compliance solutions face pricing pressure from bundled security platforms.
- Cost Management:FinOps engines aggregate billing telemetry across providers to automate rightsizing and commitment-based discount capture. US Fortune 500 technology departments with fragmented cloud contracts generate the densest adoption.
- Security:Cross-cloud identity federation and policy synchronization tools address IAM complexity across AWS IAM, Azure AD, and Google Cloud IAM. EU AI Act algorithmic transparency requirements accelerate procurement for explainable workload routing.
- Performance Monitoring:Latency-optimized placement engines route workloads based on real-time infrastructure health. Containerized microservices architectures in Indian fintech drive demand for burst capacity management.
- Compliance:Policy engines embed GDPR, ISO 27001, and sector-specific audit frameworks into automated governance workflows. German insurers face the strictest technical safeguard documentation requirements.
Cost management solutions anchor revenue concentration while compliance modules expand most quickly.
Service Type:
Integration services absorb disproportionate technical founder bandwidth, creating margin compression that consulting and support offerings escape through recurring revenue structures.
- Consulting:FinOps maturity assessments and cloud cost baseline establishment for enterprises with legacy mainframe dependencies. US secondary metro markets face acute practitioner scarcity.
- Integration:API connectivity engineering to billing systems, ITSM platforms, and identity providers. SOC 2 Type II attestation timelines extend sales cycles for these engagements.
- Support:Tiered response commitments for production optimization platform operations. Large enterprises with 24/7 workload demands concentrate procurement here.
- Training:Certification programs for multi-cloud cost allocation interpretation and policy engine configuration. Mid-market SaaS vendors with lean infrastructure teams adopt self-service enablement fastest.
Integration services carry the heaviest delivery burden while training revenue climbs fastest.
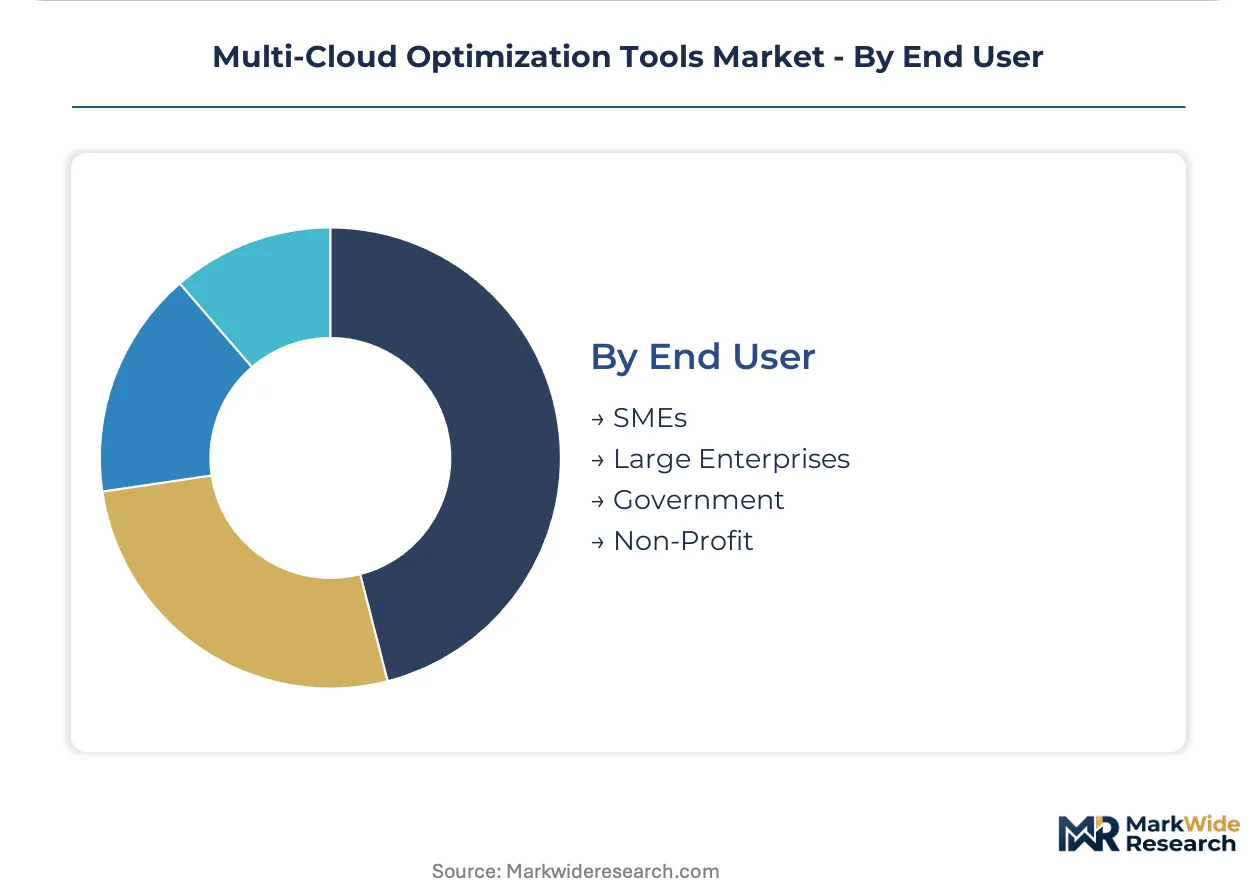
End User:
Large enterprises extract full platform value through dedicated FinOps teams, whereas SME adoption fragments across point solutions with narrower functional scope.
- Large Enterprises:Multi-cloud estates averaging 4.7 distinct cloud contracts drive demand for centralized optimization platforms with governance-embedded policy engines. US technology and financial services sectors concentrate procurement.
- SMEs:Lean teams prioritize agentic AI capabilities that autonomously execute rightsizing without human approval loops. Mid-market SaaS vendors adopt these autonomous negotiation features fastest.
- Government:FedRAMP and country-specific sovereign cloud certifications determine platform eligibility. FCC infrastructure resilience guidelines shape procurement patterns for US telecommunications carriers.
- Non-Profit:Grant-constrained budgets favor consumption-based pricing models tied to realized savings rather than fixed annual fees.
Large enterprises dominate current revenue while SME adoption accelerates most sharply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services firms and technology enterprises dominate procurement across major economies, with regulatory compliance and cloud sprawl driving geographic demand patterns. Sovereign data requirements and FinOps maturation create distinct national adoption profiles.
United States
Fortune 500 technology departments averaging 4.7 distinct cloud contracts generate dense demand for centralized optimization platforms. FCC infrastructure resilience guidelines shape procurement patterns for telecommunications carriers. Seattle and San Francisco Bay Area SaaS vendors with variable compute loads concentrate adoption of agentic cost optimization capabilities.
Germany
Automotive manufacturers and insurers anchor hybrid cloud deployment as GDPR Article 44 mandates strict data residency controls. KBA and BfDI enforcement of technical safeguard documentation accelerates region-locked optimization stack procurement. Stuttgart automotive clusters and Frankfurt financial services hubs drive governance-embedded tool adoption.
France
Healthcare providers and banking groups face strictest CNIL audit scrutiny for cross-border workload routing. EU AI Act algorithmic transparency requirements create procurement urgency for explainable orchestration stacks. Paris healthcare technology clusters and Lyon manufacturing hubs concentrate demand for compliance-automated platforms.
India
RBI-mandated financial data residency drives demand for domestic cloud region routing with international burst capacity. BIS standards and SEBI guidelines shape vendor qualification for regulated sector procurement. Mumbai fintech clusters and Bengaluru SaaS vendors adopt container-native optimization engines for lock-in avoidance.
United Kingdom
FCA-regulated insurers and asset managers prioritize ISO 27001-certified platforms for multi-cloud governance. Post-Brexit data adequacy negotiations with EU reshape cross-border workload placement logic. London financial services technology clusters and Manchester enterprise software vendors drive FinOps team maturation.
Multi-Cloud Optimization Tools Market Competitive Landscape
Player mix skews toward hyperscale cloud providers with control plane extensions, independent software vendors with FinOps specialization, and legacy infrastructure managers with hybrid portability capabilities. Hyperscale providers leverage billing API access advantages. Independent vendors compete through consumption-based pricing and autonomous AI agents. Legacy infrastructure specialists defend position through on-premises integration depth. Dominant competitive moves include strategic API partnerships with cloud providers and vertical integration into adjacent software asset management.
Within the hyperscale tier, Microsoft, Amazon, and Google exemplify control plane extension strategies. Microsoft leverages Azure Arc for cross-provider visibility. Amazon and Google anchor native optimization within their respective cloud estates. Among independent specialists, Flexera occupies a position representing license-optimized migration archetypes. VMware sits within the hybrid portability segment, sustaining relevance through Kubernetes abstraction layers for on-premises-to-cloud workload movement.
| Leading Market Players |
|---|
| Microsoft |
| Amazon |
| IBM |
| VMware |
| Ternary |
| Morpheus Data |
| CloudBolt |
| Flexera |
| Others |
Supply & Pricing Matrix
Ninety-day proof-of-concept windows now compress vendor evaluation cycles, concentrating pricing power with platforms that demonstrate immediate ROI and drawing procurement toward SaaS-native providers with leaner deployment architectures than legacy integration-heavy alternatives.
Pricing Analysis
Cost-plus contracts indexed to realized cloud savings dominate enterprise procurement, with vendors charging as a percentage of spend reduction rather than fixed annual fees. Price differentiation hinges on FinOps team maturity and SOC 2 Type II certification status, with large enterprises least sensitive and mid-market SaaS vendors most price-conscious. Pricing pressure stems from hyperscale cloud providers bundling native cost explorers at no marginal charge. Consumption-based models accelerate fastest among US technology companies with variable cloud spend.
Supply Chain Analysis
Just-in-time API integration preferences dominate as buyers demand real-time billing telemetry ingestion without strategic stockpiling of historical data reserves. Engineering talent concentrates in the United States, India, and Germany, with platform development drawing from Kubernetes-native toolchains and open-source policy frameworks. Supply chain risk centers on single-source vulnerability where hyperscale cloud providers throttle third-party API access. Distribution runs through direct enterprise sales with embedded professional services for legacy mainframe integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Native cloud provider cost management tools pose the central substitution threat, forcing independent optimization vendors to defend through cross-cloud arbitrage capabilities that hyperscalers cannot replicate without antitrust exposure.
For Market Incumbents: Fortify hybrid cloud integration depth through Kubernetes abstraction layers that preserve workload portability across AWS, Azure, and Google Cloud estates. Invest in ISO 27001 certification maintenance to sustain regulated industry RFP eligibility against emerging point-solution competitors. Prioritize agentic AI native development to separate from static policy engine architectures.
For New Entrants and Emerging Players: FedRAMP authorization fast-tracks unlock US government procurement channels where incumbent saturation remains lowest. Target mid-market SaaS vendors in secondary US metro markets facing acute FinOps practitioner scarcity. Lead with consumption-based pricing models that align vendor success to customer savings realization.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-embedded infrastructure play because regulatory complexity deepens moats for governance-automated platforms. Acquisition targets should display native AI agent architectures and vertical-specific policy engine templates. Monitor EU AI Act enforcement intensity as the signal for algorithmic transparency tooling demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Agentic AI Native Development | Autonomous workload negotiation separates platforms from static rule-based automation architectures. |
| Vertical Policy Engine Templates | Pre-configured GDPR and EU AI Act compliance modules accelerate German automotive and French healthcare procurement. |
| Hyperscaler API Partnership | Billing telemetry access agreements with AWS, Azure, and Google Cloud preserve real-time visibility against throttling. |
| FinOps Certification Program | Training revenue climbs fastest as mid-market SaaS vendors adopt self-service enablement for lean infrastructure teams. |
| Carbon-Aware Scheduling Integration | Sustainability telemetry APIs converge with cost engines to enable emissions-weighted placement decisions. |
Research Methodology
A standing panel of FinOps directors, cloud platform engineers, IT procurement officers, and compliance auditors provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, and regulatory enforcement databases. Bottom-up sizing of vendor-reported customer metrics triangulated with top-down cloud spend allocation models.
Consistency checks against external benchmarks validated volume and value outputs across deployment model, solution type, organization scale, and regional adoption pattern dimensions. CAGRs derived from fitted growth curves incorporating FinOps team maturation indices, regulatory implementation timelines, and cloud contract fragmentation rates. Agentic AI capability diffusion and consumption-based pricing penetration served as industry-specific forecast inputs.
Underlying assumptions cover steady EU AI Act enforcement progression and sustained API access terms from hyperscale providers, with deviation risk concentrated in regulatory acceleration or cloud provider vertical integration moves. Revision becomes warranted when native cloud provider optimization tool functionality crosses enterprise-grade governance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Global Multi Cloud Management Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
Cloud Microservices Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Cloud Based Information Governance Market
Cloud Computing
Hadoop-As-A-Service (Haas) Market
Cloud Computing
Cloud Data Warehouse Market
Cloud Computing
Government Cloud Computing Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
Indonesia Cloud Market
Cloud Computing
Global Cloud High-Performance Computing Market