
 UK Cloud Backup Market | 2026-2036
UK Cloud Backup Market Size, Share, and Industry Trends Forecast 2026-2036
UK Cloud Backup Market Analytics
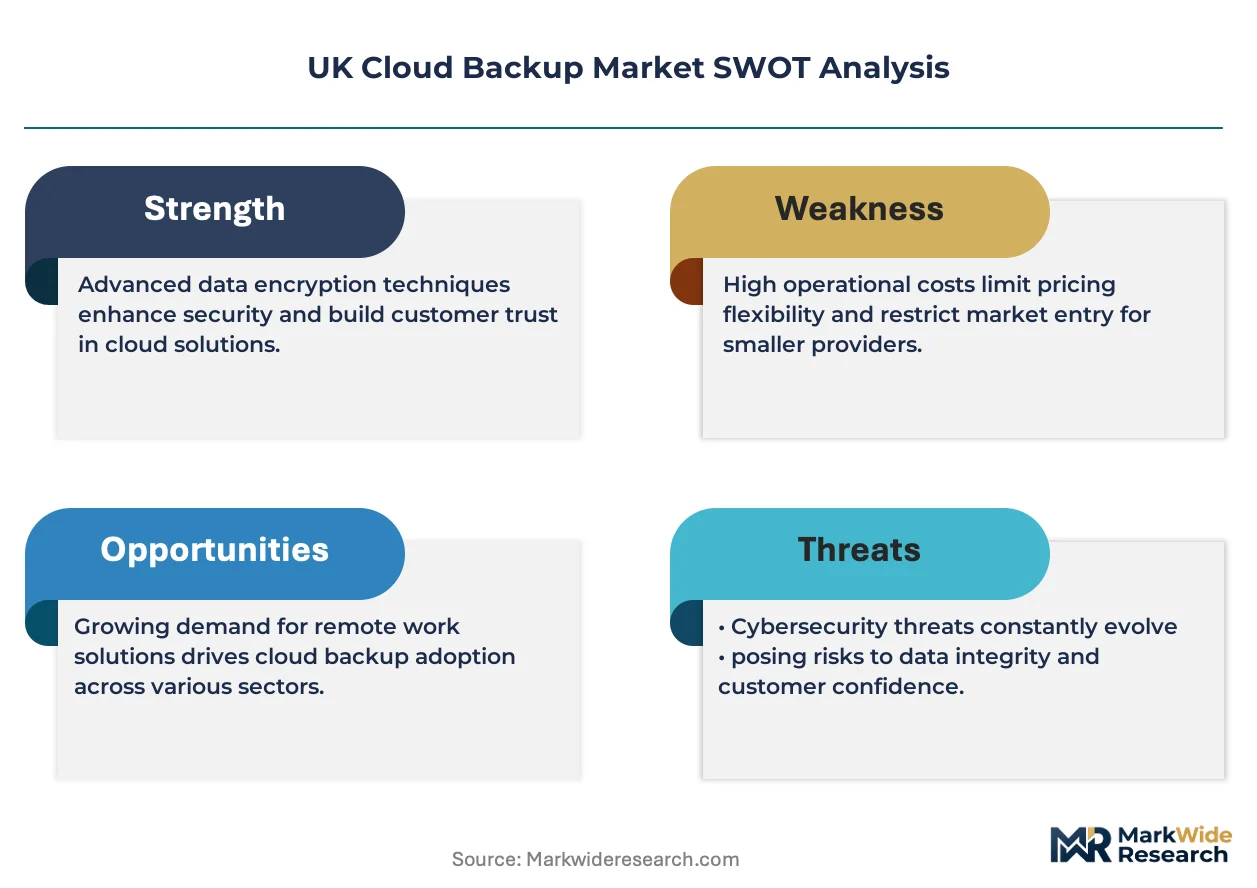
A chronic shortage of cloud-native data protection engineers is reorganizing how UK enterprises evaluate backup vendors. Microsoft Corporation leverages its Azure-native integration to anchor large financial services contracts in the City of London. Amazon Web Services Inc sustains momentum through its Outposts hybrid architecture, which appeals to firms navigating strict data residency rules. Datto Inc specializes in SME-focused continuity solutions, occupying a distinct tier below hyperscale providers.
UK Cloud Backup encompasses automated replication, encryption, and restoration of enterprise workloads across offsite cloud infrastructure, typically operating on 15-minute to 24-hour recovery point objectives depending on tier. The technology preserves business continuity against ransomware, hardware failure, and site-level disasters. Backup as a Service dominates revenue among service types due to its subscription predictability and minimal on-premise footprint. Hybrid Cloud deployment models are expanding fastest as regulated UK sectors mandate local data copies alongside cloud elasticity. Large Enterprises represent the deepest margin pool, though SME procurement is accelerating through bundled MSP offerings.
The UK Information Commissioner's Office enforces encryption and breach notification standards under UK GDPR, compelling vendors to certify immutable backup architectures. The Prudential Regulation Authority and Financial Conduct Authority mandate recovery time objectives for critical banking systems, directly shaping product specifications for financial sector buyers. Stakeholders must monitor how the National Cyber Security Centre's evolving ransomware guidance reshapes procurement criteria for government and critical infrastructure contracts.
Market Dynamics
Operational resilience mandates from the Prudential Regulation Authority are compressing recovery time objectives for UK financial institutions, forcing wholesale replacement of legacy tape-based backup architectures with immutable cloud-native alternatives.
Growth Catalysts
- PRA Operational Resilience Mandates:The UK Prudential Regulation Authority requires financial firms to demonstrate rapid recovery capabilities for critical systems, accelerating procurement of sub-15-minute recovery point objective solutions.
- UK GDPR Encryption Standards:Information Commissioner's Office enforcement of encryption-at-rest requirements drives enterprise adoption of certified immutable backup architectures with verifiable compliance documentation.
- Thames Valley Mid-Market Concentration:Technology and professional services clusters across Berkshire, Buckinghamshire, and Oxfordshire generate concentrated demand for scalable Backup-as-a-Service offerings.
Market Restraints
- Cloud-Native Talent Scarcity:Chronic undersupply of data protection engineers with Kubernetes and container-native backup expertise extends implementation timelines and inflates professional services costs.
- Data Residency Compliance Friction:Strict UK sovereignty requirements for certain public sector and defense workloads restrict vendor eligibility to providers with certified UK-only infrastructure footprints.
- Legacy Infrastructure Lock-In:Enterprises with substantial on-premise storage investments face high switching costs when migrating petabyte-scale historical archives to cloud-native formats.
Strategic Opportunities
- Scottish and Northern English Expansion:Underpenetrated enterprise markets in Edinburgh, Glasgow, and Manchester offer first-mover advantages for vendors establishing localized data center presence.
- AI-Driven Anomaly Detection Convergence:Integration of machine learning-based ransomware detection with backup orchestration creates differentiated positioning against commodity storage providers.
- Managed Service Provider Channel Development:Bundled MSP offerings targeting UK SMEs with limited internal IT capacity represent an underserved segment with subscription revenue potential.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Enterprises operating across Azure, AWS, and Google Cloud environments struggle to maintain consistent backup policies and recovery testing protocols.
- Immutable Architecture Certification Delays:Vendor compliance verification against NCSC ransomware guidance extends sales cycles for government and critical infrastructure contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Cloud Backup Market |
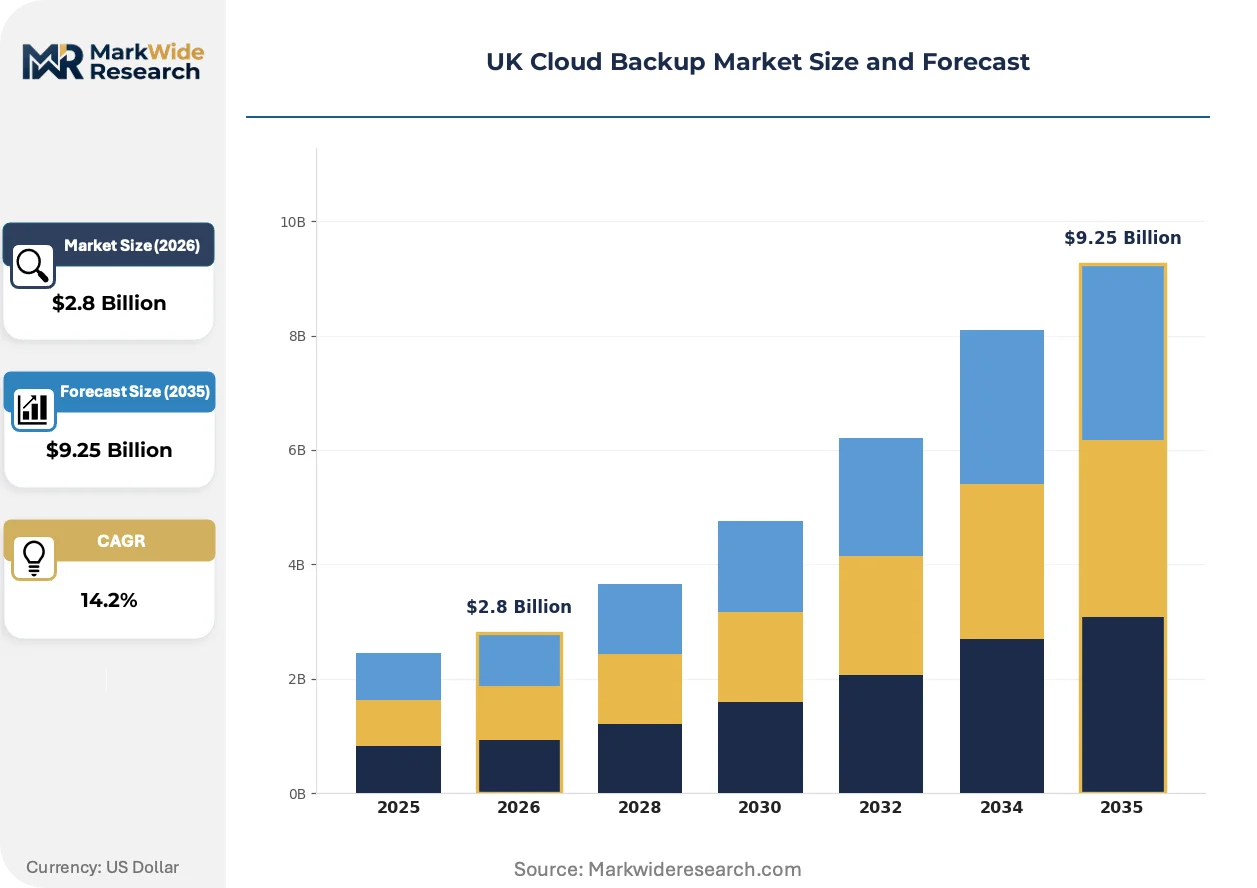
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Backup as a Service, Disaster Recovery as a Service, Data Archiving, Hybrid Backup Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: SMEs, Large Enterprises, Government, Educational Institutions Data Type: File Backup, Application Backup, Database Backup, Image Backup |
| Companies Covered | Microsoft Corporation, Carbonite Inc, Amazon Web Services Inc, Barracuda Networks Inc, Datto Inc, Google LLC, Oracle Corporation, Rackspace Hosting Inc, International Business Machines Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Cloud Backup Market Evolving Landscape
Immutable backup architectures with cryptographic verification are displacing traditional snapshot-based recovery methods across UK regulated industries, compressing vendor differentiation around resilience guarantees rather than storage economics alone.
Object-lock immutability with WORM (Write Once Read Many) enforcement is displacing conventional backup retention policies in UK financial services. Tier-one banks and insurance groups are mandating 30-90 day immutable retention windows with air-gapped logical separation. This architecture is displacing legacy deduplication appliances that lack native ransomware resistance, forcing incumbent storage vendors to rearchitect core platforms or cede position to cloud-native specialists.
The UK National Cyber Security Centre's evolving ransomware guidance is reshaping procurement specifications for government and critical national infrastructure buyers. Mandatory immutable backup requirements now appear in framework agreements for NHS trusts, utility operators, and transport authorities. Vendors without NCSC-acknowledged architectures face automatic disqualification from public sector tenders, creating a two-tier supply base segmented by compliance certification rather than price-performance.
Subscription-based consumption models are eroding perpetual license dominance among UK mid-market enterprises. Finance directors prefer operational expenditure classification for backup infrastructure, particularly when bundled with disaster recovery testing and compliance reporting services. This preference is most pronounced among Thames Valley technology firms and professional services groups with volatile headcount and data growth patterns.
UK Cloud Backup Market Segmentation
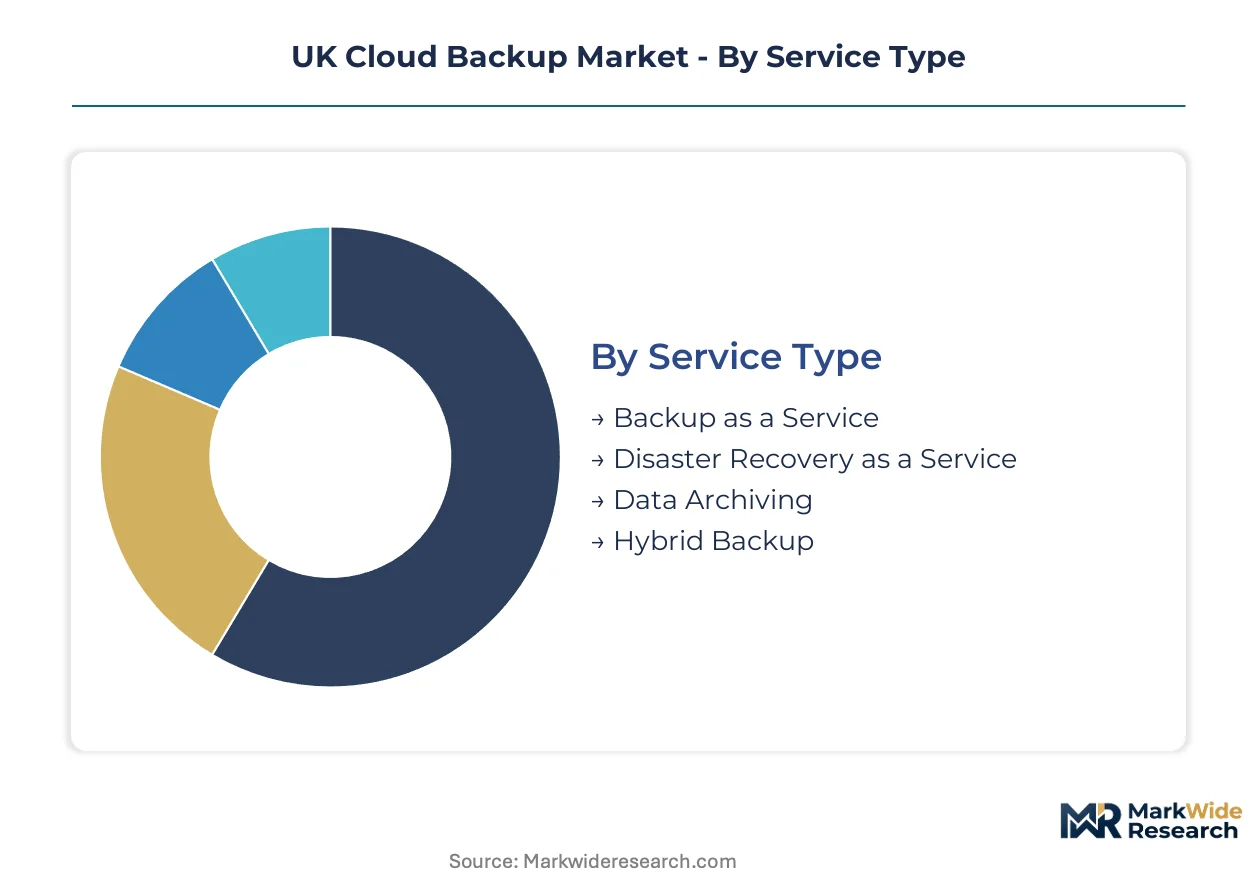
Segmentation in the UK Cloud Backup Market reveals how regulatory mandates reshape procurement patterns across service tiers and deployment architectures. Prudential Regulation Authority requirements and UK GDPR encryption standards create divergent compliance burdens that vendors must address through specialized offerings.
Service Type:
Regulatory differentiation separates subscription-based consumption from perpetual licensing, with compliance documentation requirements varying sharply across tiers.
- Backup as a Service:Subscription delivery of automated replication, encryption, and restoration functions with minimal on-premise footprint. Thames Valley technology firms and professional services clusters drive procurement through operational expenditure preferences and volatile data growth patterns.
- Disaster Recovery as a Service:Orchestrated failover and recovery testing services with guaranteed recovery time objectives. UK financial institutions facing Prudential Regulation Authority mandates concentrate demand for sub-15-minute recovery point objective solutions with verifiable compliance reporting.
- Data Archiving:Long-term retention for regulatory and legal hold requirements with immutable storage enforcement.
- Hybrid Backup:Integrated on-premise and cloud storage management for enterprises navigating legacy infrastructure transitions.
Established volume favors Backup as a Service; emerging adoption favors Disaster Recovery as a Service.
Deployment Model:
Cost tier differentiation separates hyperscale elasticity from sovereign infrastructure investments, with data residency rules dictating eligibility for public sector contracts.
- Hybrid Cloud:Combined local data copies with cloud elasticity, mandatory for regulated UK sectors requiring geographic separation of primary and secondary copies. NHS trusts and utility operators specify hybrid architectures in National Cyber Security Centre-aligned framework agreements.
- Public Cloud:Fully offsite infrastructure with consumption-based scaling, dominant among Thames Valley mid-market firms lacking capital for dedicated infrastructure.
- Private Cloud:Single-tenant dedicated environments for defense and critical national infrastructure workloads with strict sovereignty requirements.
- Multi-Cloud:Orchestrated backup across Azure, AWS, and Google Cloud environments, creating policy consistency challenges for enterprises with heterogeneous infrastructure.
Hybrid Cloud climbs the fastest among regulated sectors; Public Cloud retains broadest SME penetration.
End User:
Customer type segmentation reflects divergent internal capabilities, with procurement authority concentrating among organizations with dedicated compliance functions.
- Large Enterprises:Deep margin pool with dedicated procurement teams evaluating immutable backup architectures against Prudential Regulation Authority and Financial Conduct Authority mandates. City of London financial institutions anchor demand for certified compliance documentation.
- SMEs:Accelerating adoption through bundled MSP offerings, particularly across Berkshire, Buckinghamshire, and Oxfordshire technology corridors where internal IT capacity constraints favor outsourced continuity management.
- Government:National Cyber Security Centre framework compliance requirements restrict vendor eligibility to providers with acknowledged immutable architectures.
- Educational Institutions:Research data protection and student information system backup with variable funding cycles.
Large Enterprises command highest per-account value; SME procurement is gaining share fastest through channel bundling.
Data Type:
Application criticality determines recovery point objective specifications, with database and application tiers commanding premium pricing for near-continuous protection.
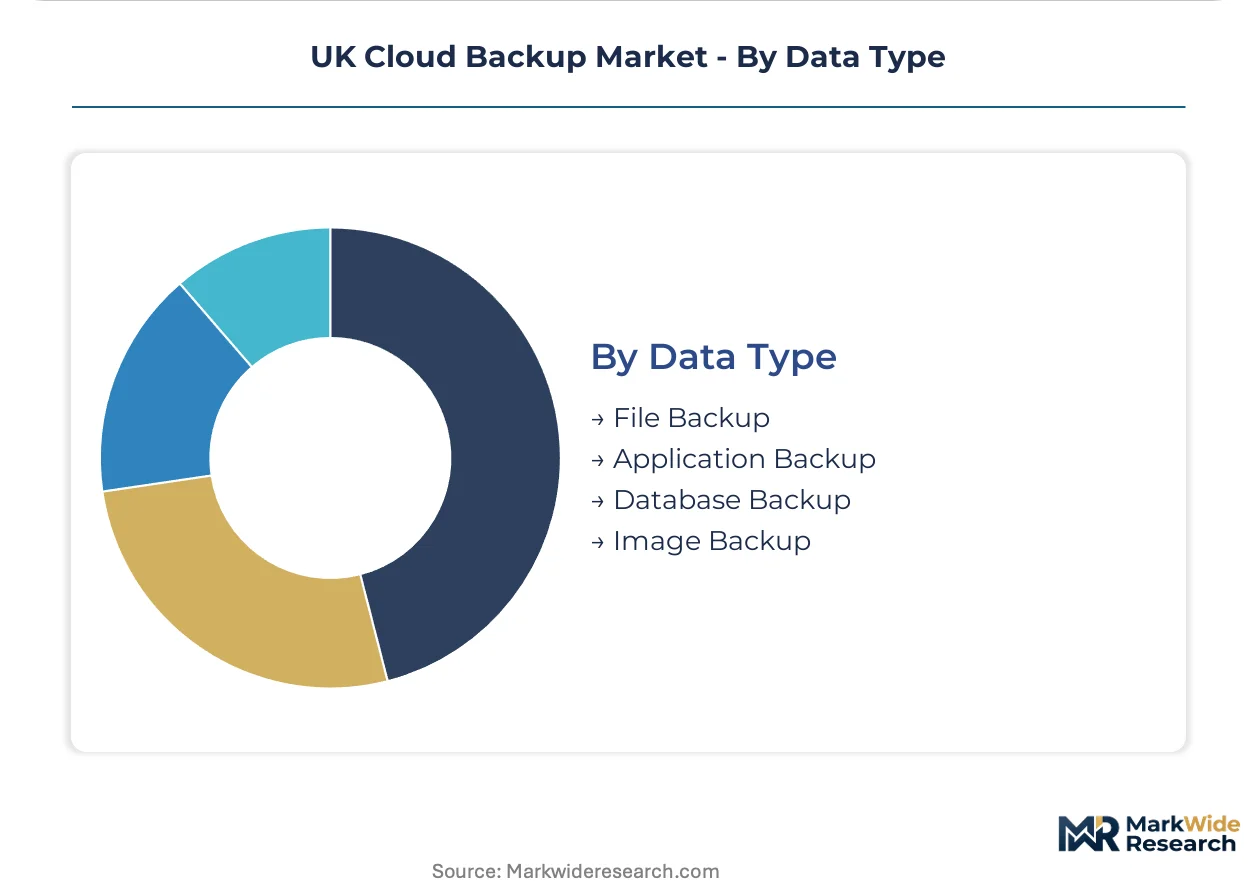
- Database Backup:Transaction-consistent replication for relational and NoSQL systems with point-in-time recovery capabilities. UK banking core systems mandate sub-15-minute recovery objectives under operational resilience rules.
- Application Backup:Container-aware and VM-consistent protection for cloud-native and legacy workloads, concentrating among enterprises with Kubernetes orchestration requirements.
- File Backup:Endpoint and unstructured data protection with deduplication optimization.
- Image Backup:Full system state capture for bare-metal recovery and ransomware remediation scenarios.
Database Backup holds steepest pricing power; Application Backup shows strongest expansion trajectory as containerization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in London and the Southeast while Scottish and Northern English markets trade at substantial discounts due to infrastructure density gaps and lower regulatory enforcement intensity.
London and the Southeast
Financial services concentration drives premium procurement for sub-15-minute recovery point objective solutions. Prudential Regulation Authority operational resilience mandates force City institutions to maintain certified immutable architectures. The Thames Valley corridor through Berkshire, Buckinghamshire, and Oxfordshire anchors mid-market technology firm adoption of Backup-as-a-Service subscriptions.
Midlands
Manufacturing and logistics clusters generate steady demand for hybrid cloud architectures balancing legacy system retention with cloud elasticity. Regional technology investment zones accelerate data center buildouts around Birmingham and Leicester. Professional services firms in Nottingham and Derby expand MSP-bundled continuity adoption.
North England
Manchester and Leeds financial services subsidiaries operate under lighter regulatory scrutiny than London headquarters, permitting longer recovery time objectives. Emerging technology corridors attract hyperscale provider edge deployments. Local government digital transformation programs create NHS-aligned procurement opportunities.
Scotland
Edinburgh's asset management and insurance sectors replicate London compliance standards with reduced vendor competition. Glasgow's public sector concentration depends on National Cyber Security Centre framework adherence. Underpenetrated enterprise markets offer first-mover positioning for localized data center presence.
Wales and Northern Ireland
Public sector and education procurement dominates regional demand patterns with stringent budget constraints. Cardiff and Belfast technology hubs develop specialized compliance expertise for cross-border data flows. Devolved administration IT modernization programs channel investment toward certified sovereign cloud providers.
UK Cloud Backup Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where hyperscale cloud providers anchor premium financial services contracts while specialized continuity vendors capture mid-market efficiency plays. The market consolidates around three strategic archetypes: hyperscale platform integrators, dedicated backup-as-a-service specialists, and legacy infrastructure incumbents retrofitting for immutability. Dominant competitive moves include geographic data center expansion to satisfy residency requirements and AI-driven anomaly detection integration to differentiate against commodity storage pricing.
Within the hyperscale tier, Microsoft Corporation and Amazon Web Services Inc exemplify platform-native integration strategies that lock in enterprise workloads through operational ecosystem entrenchment. Datto Inc occupies a distinct mid-market position representing specialist continuity vendors that bundle backup with disaster recovery testing to address SME capacity constraints. These three companies illustrate how vendor selection in this market tracks directly to buyer scale, regulatory exposure, and internal technical capability rather than pure feature comparison.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Carbonite Inc |
| Amazon Web Services Inc |
| Barracuda Networks Inc |
| Datto Inc |
| Google LLC |
| Oracle Corporation |
| Rackspace Hosting Inc |
| International Business Machines Corporation |
| Others |
Value Network & Pricing Analysis
NCSC ransomware guidance certification gates both vendor qualification and price differentiation in UK cloud backup procurement, compressing margins for uncertified providers while enabling premium positioning for architectures with immutable backup verification. Financial institutions facing Prudential Regulation Authority mandates absorb configured-to-order pricing for sub-15-minute recovery point objective solutions, whereas mid-market firms across the Thames Valley corridor negotiate standard SaaS-tiered subscriptions.
Pricing Analysis
Configured-to-order pricing for immutable backup architectures with cryptographic verification commands substantial premiums over standard Backup-as-a-Service subscriptions. Price differentiation centers on NCSC certification tier and recovery time objective performance, with certified providers capturing financial services contracts while commodity storage vendors compete on operational expenditure minimization. Pricing pressure stems from hyperscale providers bundling backup with broader cloud consumption credits, compressing standalone vendor margins. SMEs exhibit highest price sensitivity, prioritizing per-terabyte predictability over resilience guarantees.
Supply Chain Analysis
Inventory and lead-time constraints concentrate around cloud infrastructure provisioning, with UK data center capacity expansion lagging demand from regulated sectors requiring sovereign storage. Supply concentrates in Ireland, the Netherlands, and Germany for hyperscale cloud regions serving UK workloads, while specialized backup software development centers on the United States and Israel. Raw material dependencies include encryption hardware security modules, solid-state storage media, and fiber-optic interconnects. Single-source vulnerability characterizes certified immutable architecture components. Distribution runs through direct enterprise sales teams and managed service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK cloud backup penetration remains early-cycle, with operational resilience mandates from the Prudential Regulation Authority accelerating replacement of legacy tape architectures before regulatory deadlines tighten.
For Market Incumbents: Compound defensive positioning through NCSC certification investment and Scottish data center buildout to preempt regulatory expansion. Kubernetes-native backup capability scarcity threatens established vendors lacking container-aware orchestration. Vertical integration into AI-driven anomaly detection preserves margin against hyperscale bundling.
For New Entrants and Emerging Players: NCSC certification fast-track unlocks NHS trust and utility operator procurement channels currently restricted to acknowledged vendors. Scottish and Northern English enterprise markets offer penetrable white-space with localized infrastructure presence. Channel partnership with Thames Valley MSPs accelerates SME customer acquisition without direct sales overhead.
For Investors and Strategic Acquirers: PRA operational resilience deadline reshapes the acquisition landscape toward vendors with verifiable immutable architectures and financial services referenceability. Five-to-ten-year viability favors specialists with compliance documentation depth over commodity storage repositioning. Watch for NCSC guidance revision frequency as inflection indicator for procurement specification stringency.
| Strategic Initiative | Industry Significance |
|---|---|
| NCSC Certification Investment | Immutable architecture verification unlocks NHS trust and critical infrastructure framework eligibility. |
| Scottish Data Center Expansion | Localized sovereign infrastructure captures Edinburgh asset management compliance requirements. |
| MSP Channel Development | Bundled continuity offerings address Thames Valley SME capacity constraints through outsourced management. |
| AI Anomaly Detection Integration | Machine learning ransomware identification differentiates against hyperscale commodity storage pricing. |
| Kubernetes-Native Backup Development | Container-aware orchestration meets financial services cloud-native workload protection mandates. |
Research Methodology
Initial hypotheses were tested against primary input from chief technology officers, IT procurement officers, data protection engineers, and managed service provider principals and refined through secondary validation against SEC filings from hyperscale providers, NHS procurement databases, NCSC framework documentation, and Financial Conduct Authority regulatory notices. Bottom-up segmentation modeling triangulated with top-down market sizing across service type, deployment model, and end user categories.
Variance decomposition across the projection horizon isolated volume drivers from pricing dynamics within each segment. The analytical framework modeled deployment model adoption patterns, regulatory compliance tier penetration, and recovery point objective specification trends. CAGRs derived from segment-level growth trajectory aggregation, with inputs including cloud infrastructure capex disclosures and financial services technology spending surveys.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and hyperscale provider bundling continuity; material deviation in NCSC guidance revision pace or PRA deadline extension would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Commercial Cloud Market
Cloud Computing
Italy Cloud Computing Market
Cloud Computing
North America Professional Cloud Services Market
Cloud Computing
Public Cloud Application Services Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Brazil Cloud Computing Market
Cloud Computing
GPU As a Service (Gpuaas) Market
Cloud Computing
Public Finance Cloud Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Cloud Computing in Industrial IoT Market
Cloud Computing
Cloud Identity Management Market
Cloud Computing
United States Cloud Computing Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Commerce Cloud Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
Cloud VPN Market