
 Asia Pacific Cloud Computing Market | 2026-2036
Asia Pacific Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Cloud Computing Market Analytics
China's Personal Information Protection Law is recalibrating the cost-of-entry calculus for foreign cloud providers seeking mainland data center access. Alibaba Cloud leverages its domestic compliance architecture to sustain pricing advantages across state-affiliated enterprises. Amazon Web Services anchors its regional position through dedicated local zones in Singapore, Sydney, and Tokyo. Microsoft Azure differentiates via sovereign cloud offerings tailored to government and defense procurement frameworks.
Asia Pacific cloud computing encompasses the delivery of on-demand computing resources—spanning servers, storage, databases, networking, software, and analytics—over the internet through shared, multi-tenant infrastructure with service-level agreements typically guaranteeing 99.9% uptime or higher. Its primary purpose is to enable organizations to scale IT capacity without capital-intensive hardware procurement while supporting distributed workforces and real-time data processing across geographically dispersed operations. Public cloud deployment models command the dominant revenue share given hyperscaler economies of scale, though hybrid cloud configurations are gaining traction among large enterprises navigating data residency requirements. SaaS delivery leads service type adoption due to low friction implementation, while IaaS captures expanding margins as GPU-intensive workloads for artificial intelligence training proliferate across the region.
China's SAMR enforces cybersecurity review requirements for cloud services processing critical data, while India's TRAI and BIS shape telecom-linked cloud standards and data center certifications respectively. Japan's METI promotes cloud-first policies for public sector digitization, directly steering procurement toward domestic and allied foreign providers. Stakeholders must monitor evolving cross-border data flow restrictions and sovereign cloud mandates as these will determine viable operating models and partnership structures across the region.
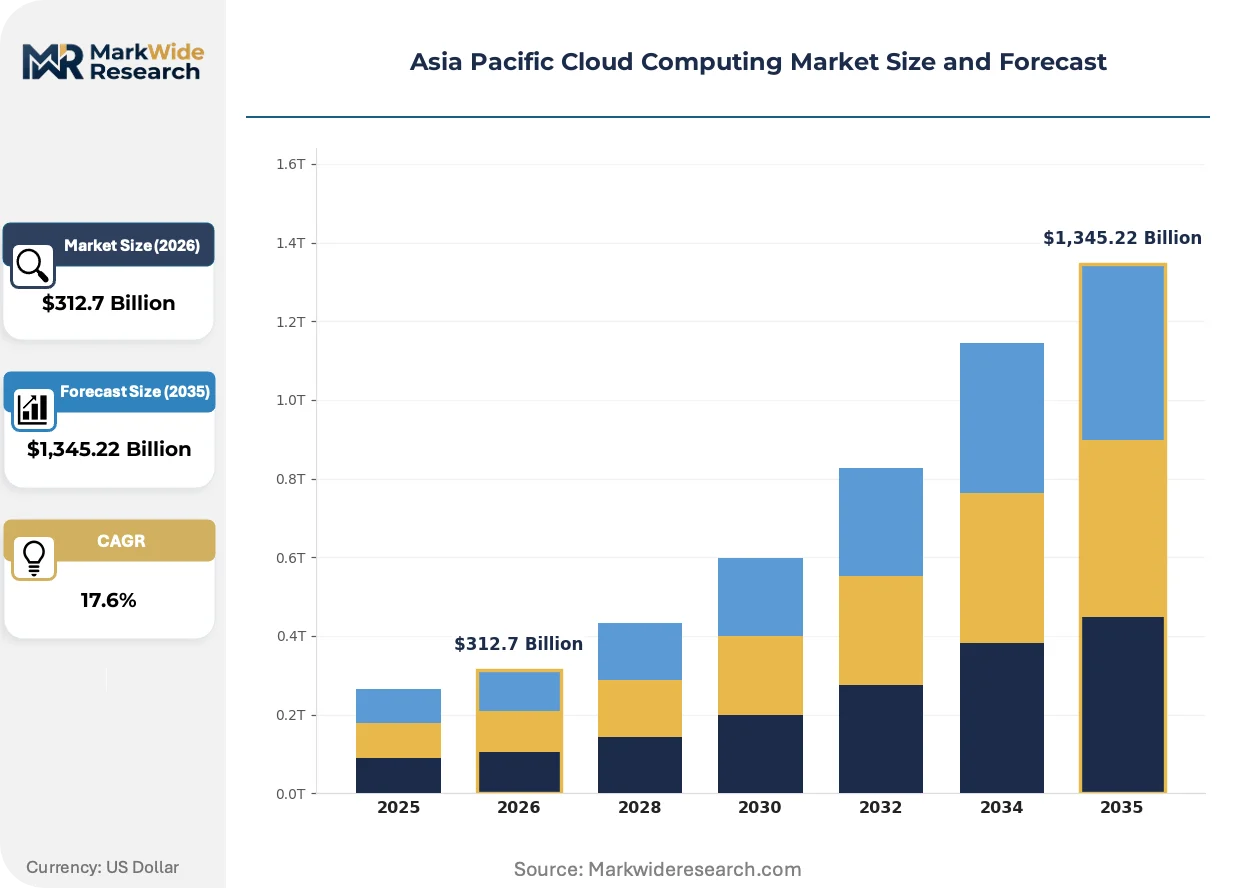
Market Dynamics
China's data localization mandates and dual carbon goals are forcing hyperscalers to redesign infrastructure deployment patterns across the region. This regulatory pressure is recalibrating cost structures and partnership requirements for every provider seeking mainland access.
Growth Catalysts
- India's digital public infrastructure build-out:Government cloud mandates for welfare delivery systems and tax platforms are generating sustained procurement pipelines. State data centers in Karnataka and Telangana anchor this expansion.
- GPU-intensive AI training workloads:Financial services institutions across Singapore and Hong Kong are provisioning dedicated compute clusters for model development. This application category commands premium infrastructure pricing.
- Japan's METI cloud-first policies:Public sector digitization directives steer government procurement toward certified domestic and allied foreign providers. Municipalities in Osaka and Fukuoka represent early implementation sites.
Market Restraints
- Cross-border data flow restrictions:China's SAMR cybersecurity reviews for critical data processing create compliance bottlenecks. Foreign providers face extended approval timelines for mainland service launches.
- Power infrastructure constraints:Data center build-outs in Vietnam and Indonesia encounter grid instability and renewable energy access limitations. Diesel backup dependency raises operational carbon intensity.
- Specialized talent scarcity:Cloud architecture and DevOps expertise concentrates in Sydney, Singapore, and Bangalore. Secondary markets face 40-60% salary premiums for comparable skill sets.
Strategic Opportunities
- Indonesia's underpenetrated enterprise segment:Mid-market manufacturers in Java and Sumatra remain on-premise dominant. Local language support and rupiah-denominated billing unlock adoption barriers.
- Sovereign cloud procurement frameworks:Australia's government cloud certification program creates compliant provider slots. Defense and intelligence contracts require air-gapped infrastructure with domestic staff vetting.
- Edge-to-cloud convergence:5G network slicing in South Korea and Japan enables distributed AI inference. Manufacturing quality control and autonomous logistics represent anchor applications.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises operating across Alibaba Cloud, AWS, and Azure environments face inconsistent API implementations and cost visibility gaps. FinOps tooling standardization remains immature.
- Legacy system integration friction:Mainframe-dependent financial institutions in Tokyo and Seoul require specialized middleware for cloud-native migration. Project timelines extend 18-36 months for core banking transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Cloud Computing Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $1,345.22 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Service Type: IaaS, PaaS, SaaS, FaaS End User: SMEs, Large Enterprises, Government, Educational Institutions Application: Data Storage, Disaster Recovery, Virtual Desktops, Application Hosting |
| Companies Covered | Alibaba Cloud, Oracle Cloud Infrastructure, Amazon Web Services, Huawei Cloud, Salesforce, Microsoft Azure, Tencent Cloud, IBM Cloud, Google Cloud, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Cloud Computing Market Evolving Landscape
Serverless computing architectures and sovereign cloud specializations are compressing traditional infrastructure procurement cycles across Asia Pacific enterprises. These shifts are redistributing vendor margins toward managed services and compliance automation layers.
Arm-based processor deployments in hyperscale data centers are rewriting performance-per-watt economics for cloud-native workloads. Alibaba Cloud and domestic Chinese providers are adopting custom silicon for AI inference and containerized applications. This hardware transition is enabling denser rack configurations while supporting mainland carbon reduction commitments.
Thailand's Personal Data Protection Act and similar frameworks across Southeast Asia are mandating data residency documentation and breach notification protocols. Cloud providers must maintain in-country legal representatives and audit trails for government inspection. Financial services and healthcare verticals in Bangkok and Kuala Lumpur represent the most affected buyer segments, with procurement now requiring compliance attestation as a gate criterion.
Consumption-based billing models are displacing reserved instance commitments among mid-market enterprises. Pay-per-query data warehouse pricing and auto-scaling container platforms reduce upfront capital requirements. This pattern is most visible among e-commerce and fintech operators in Mumbai and Jakarta, where transaction volatility makes capacity planning inherently uncertain.
Asia Pacific Cloud Computing Market Segmentation
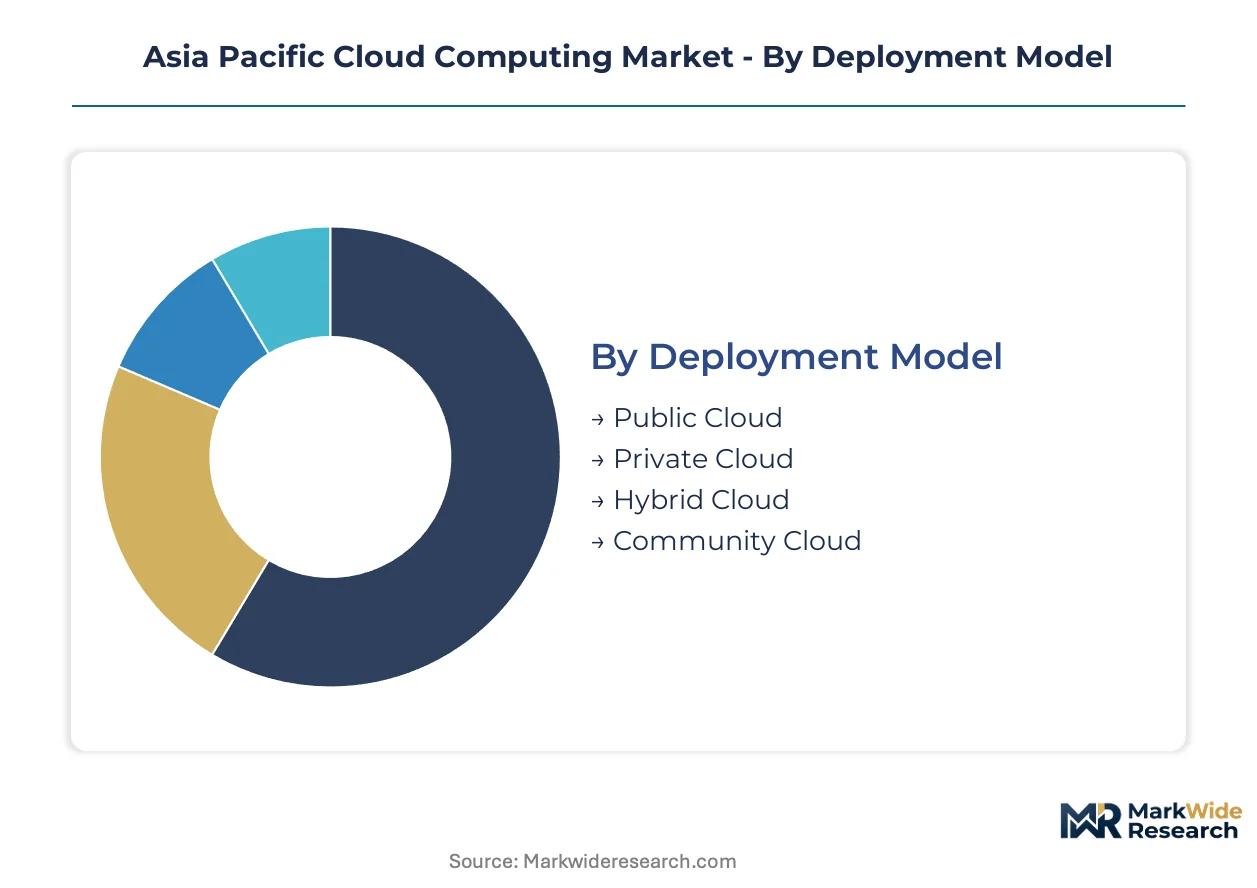
Cloud infrastructure procurement across Asia Pacific diverges sharply by organizational scale and regulatory exposure. Deployment model selection directly determines compliance architecture, cost structure, and vendor lock-in risk for buyers navigating data sovereignty mandates.
Deployment Model:
Public cloud dominates transaction volume while hybrid configurations capture premium margins from regulated enterprises.
- Public Cloud:Multi-tenant infrastructure delivers compute, storage, and networking via shared data center resources with 99.9% uptime SLAs. India's digital public infrastructure build-out and Southeast Asian fintech scaling are concentrating procurement here, though China's data localization mandates restrict foreign provider participation.
- Hybrid Cloud:Orchestrated workloads span on-premise private infrastructure and public cloud bursts, enabling sensitive data containment with elastic capacity. Japan's METI-certified government agencies and Australia's defense procurement frameworks are driving sovereign-compliant implementations.
- Private Cloud:Dedicated single-tenant environments hosted on-premise or in colocation facilities.
- Community Cloud:Shared infrastructure serving specific industry verticals or regulatory jurisdictions.
Today's leader: Public Cloud. Tomorrow's challenger: Hybrid Cloud.
Service Type:
SaaS delivers lowest-friction adoption while IaaS margins expand with GPU-intensive workload proliferation.
- SaaS:Pre-configured applications accessible via browser or API eliminate infrastructure management overhead. Mumbai's e-commerce operators and Jakarta's fintech platforms favor consumption-based billing for transaction-volatile operations.
- IaaS:Raw compute, storage, and networking resources provisioned on-demand enable custom stack construction. Singapore and Hong Kong financial institutions are provisioning dedicated GPU clusters for AI model training at premium infrastructure pricing.
- PaaS:Managed development environments abstract underlying infrastructure complexity.
- FaaS:Event-driven serverless execution charges per invocation rather than reserved capacity.
Current revenue concentration favors SaaS. Steepest expansion trajectory belongs to IaaS.
End User:
Large enterprises anchor infrastructure spend while government verticals impose steepest compliance requirements.
- Large Enterprises:Multi-divisional organizations with dedicated IT procurement functions negotiate enterprise licensing agreements and custom SLAs. Tokyo and Seoul financial institutions are extending 18-36 month timelines for core banking cloud migration.
- Government:Public sector entities subject to sovereign cloud mandates and domestic staff vetting requirements. Japan's municipal digitization in Osaka and Fukuoka and Australia's defense certification program exemplify procurement patterns.
- SMEs:Resource-constrained organizations prioritizing pay-as-you-scale economics over customization.
- Educational Institutions:Research universities and technical colleges provisioning computational resources for academic workloads.
Established anchor: Large Enterprises. Fastest share gain: Government.
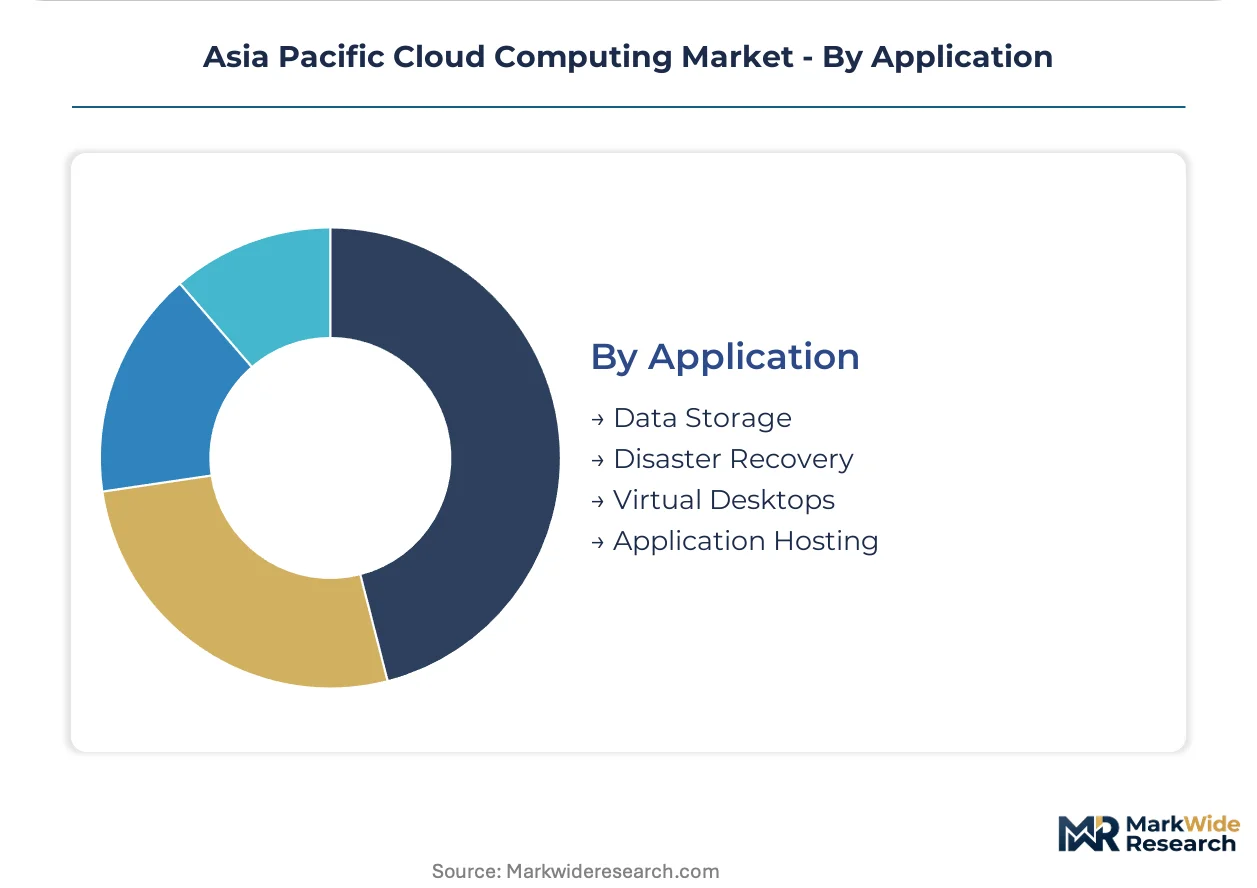
Application:
Data storage generates baseline volume while disaster recovery commands resilience premiums.
- Data Storage:Object, block, and file storage services with tiered durability guarantees. India's state data centers in Karnataka and Telangana anchor welfare system and tax platform archives.
- Disaster Recovery:Automated failover and backup orchestration ensuring business continuity across availability zones. Thailand's PDPA breach notification mandates and similar Southeast Asian frameworks are elevating this to gate-criterion status in Bangkok and Kuala Lumpur procurement.
- Virtual Desktops:Centralized desktop environments streamed to endpoint devices.
- Application Hosting:Managed runtime environments for custom and packaged software deployment.
Volume foundation: Data Storage. Margin expansion: Disaster Recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud computing infrastructure first achieved hyperscale commercial deployment in the United States during the mid-2000s, with Amazon Web Services launching its foundational storage and compute services in 2006. This operational model subsequently diffused across Asia Pacific through regional data center investments and localization mandates that recalibrated deployment patterns to sovereign requirements.
China
Domestic hyperscalers anchor infrastructure procurement for state-affiliated enterprises and digital platform operators. SAMR cybersecurity reviews enforce data localization for critical information processing, extending approval timelines for foreign provider market entry. Beijing and Shanghai metropolitan clusters concentrate GPU-intensive AI training deployments for financial services and autonomous vehicle development.
India
Government cloud mandates for welfare delivery systems and tax platforms generate sustained procurement pipelines from central and state agencies. TRAI and BIS shape telecom-linked cloud standards and data center certification requirements respectively. State data centers in Karnataka and Telangana anchor digital public infrastructure build-out for population-scale service delivery.
Japan
METI cloud-first policies steer public sector digitization toward certified domestic and allied foreign providers. Municipal implementations in Osaka and Fukuoka represent early procurement sites for sovereign-compliant infrastructure. Tokyo financial institutions extend 18-36 month migration timelines for core banking system modernization.
Singapore
Financial services institutions provision dedicated compute clusters for AI model development at premium infrastructure pricing. Dedicated local zones from foreign hyperscalers anchor regional hub operations for Southeast Asian market access. The city-state's data center capacity constraints are redirecting secondary workloads toward Johor and Batam.
Australia
Government cloud certification programs create compliant provider slots for defense and intelligence contracts requiring air-gapped infrastructure. Domestic staff vetting requirements and data residency documentation elevate procurement complexity for foreign operators. Sydney and Melbourne anchor enterprise demand while Perth serves resources sector edge computing requirements.
Asia Pacific Cloud Computing Market Competitive Landscape
The competitive structure tilts toward domestic hyperscalers in China and diversified global platforms across developed Asia Pacific markets. Vendor concentration remains elevated at the infrastructure layer where capital requirements for data center construction exceed $500 million per hyperscale facility. Three strategic archetypes dominate: China-based domestic champions leveraging compliance architecture, US-origin global hyperscalers deploying through local zones, and enterprise software incumbents extending into platform services. Competitive moves center on sovereign cloud partnership structures and Arm-based custom silicon deployments.
Among China-based hyperscalers, Alibaba Cloud and Huawei Cloud occupy positions shaped by mainland data localization mandates and dual carbon compliance requirements. Tencent Cloud sits within the same archetype with differentiated vertical exposure. Amazon Web Services and Microsoft Azure anchor the foreign provider tier through dedicated local zone investments in Singapore, Sydney, and Tokyo.
| Leading Market Players |
|---|
| Alibaba Cloud |
| Oracle Cloud Infrastructure |
| Amazon Web Services |
| Huawei Cloud |
| Salesforce |
| Microsoft Azure |
| Tencent Cloud |
| IBM Cloud |
| Google Cloud |
| Others |
Value Network & Pricing Analysis
Arm-based processor transitions in hyperscale data centers are compressing performance-per-watt economics while redrawing supplier concentration maps across mainland China and Taiwan. This silicon shift simultaneously lowers unit compute costs and tightens dependency on semiconductor fabrication clusters capable of custom chip production.
Pricing Analysis
Bundled managed services and unbundled raw infrastructure splits dominate Asia Pacific cloud procurement, with sovereign-compliant offerings commanding substantial premiums over standard multi-tenant configurations. Price differentiation rests on certification tier—government cloud accreditation versus enterprise-grade SLAs—and data residency documentation depth. Cost compression in entry-level compute tiers is intensifying because Alibaba Cloud and domestic Chinese providers leverage captive silicon supply. Mid-market manufacturers in Indonesia exhibit highest price sensitivity, while Singapore financial institutions provisioning GPU clusters for AI training show minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements from Japan's defense procurement frameworks and Australia's government cloud certification programs are forcing hyperscalers to qualify secondary component vendors for critical infrastructure. Hardware supply concentrates in Taiwan, South Korea, and mainland China for server motherboards, memory modules, and custom AI accelerators. Raw material dependencies span rare earth elements for magnetics, high-purity silicon for semiconductors, and copper for data center power distribution. Single-source vulnerability around advanced node chip fabrication presents structural risk. Distribution runs through direct enterprise sales teams for large contracts and certified channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific cloud computing has matured into a late-cycle quality market where procurement decisions increasingly favor providers with demonstrable sovereign compliance and carbon-attested infrastructure. This shift toward premium specifications reflects government verticals elevating certification grade to gate-criterion status.
For Market Incumbents: Cement regional hub positions by expanding dedicated local zones in Singapore, Sydney, and Tokyo to intercept multi-cloud procurement from financial institutions. Invest in Arm-based custom silicon development to defend margin position against domestic Chinese providers with captive semiconductor supply. METI certification maintenance and Australia's defense cloud accreditation represent non-negotiable table stakes for public sector access.
For New Entrants and Emerging Players: Capture white-space in Indonesia's underpenetrated manufacturing segment where mid-market enterprises in Java and Sumatra remain on-premise dominant. Local language support and rupiah-denominated billing unlock adoption barriers that foreign hyperscalers have neglected. A channel-first go-to-market through domestic systems integrators accelerates trust-building in this relationship-driven procurement environment.
For Investors and Strategic Acquirers: Roll-up economics work for regional managed services specialists because enterprise multi-cloud complexity is fragmenting procurement across dozens of integration and FinOps vendors. Long-term viability hinges on compliance automation capabilities and sovereign cloud partnership structures with government agencies. The signal to watch is acceleration in Australia's defense cloud certification pipeline and Japan's municipal digitization procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Unlocks Japan METI-certified procurement and Australia defense contracts requiring domestic staff vetting. |
| Arm-Based Silicon Development | Enables Alibaba Cloud and domestic providers to meet mainland dual carbon goals while cutting unit economics. |
| Edge-to-Cloud Platform Integration | Captures 5G network slicing opportunities in South Korea and Japan for manufacturing quality control applications. |
| Local Zone Geographic Expansion | Anchors foreign hyperscaler presence in Singapore, Sydney, and Tokyo for Southeast Asian market access. |
| Compliance Automation Layer Acquisition | Addresses Thailand PDPA and Southeast Asian data residency mandates elevating audit documentation to gate-criterion status. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured conversations with cloud procurement officers, platform engineers, channel partners, and government IT directors with secondary validation. Hyperscaler capex disclosures, data center development permits, and BIS certification records anchored supply-side sizing. Bottom-up deployment model adoption curves and top-down regional infrastructure spending aggregates were triangulated for convergence.
Comparable historical periods anchored the forecast window, with growth trajectory reference points drawn from prior technology infrastructure build-outs across the analysis window. Segmentation modeling spanned deployment model, organization scale, vertical regulatory exposure, and regional data sovereignty pattern. CAGRs were derived from fitted adoption curves incorporating GPU-intensive workload proliferation and government cloud mandate implementation pace.
Regulatory enforcement variance, sovereign cloud procurement acceleration, and Arm-based silicon yield rates are the dominant revision risks to the outlook. Deviation in China's SAMR cybersecurity review timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Computing Services Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
Platform As a Service (Paas) Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
North America Cloud Computing Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Cloud Identity Management Market
Cloud Computing
Italy Cloud Computing Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
Cloud Management for the Openstack Market
Cloud Computing
Cloud API Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Global Distributed Cloud Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market