
 North America Mobile Cloud Market | 2026-2036
North America Mobile Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mobile Cloud Market Analytics
Healthcare is restructuring the end-use vertical mix for North America mobile cloud services as telemedicine and remote patient monitoring expand data gravity toward edge infrastructure. Amazon Web Services leverages its GovCloud regions to anchor public sector contracts with federal agencies. Microsoft Azure sustains hybrid cloud dominance through Azure Stack integration with on-premises health systems. Google Cloud Platform differentiates on AI-optimized compute for real-time diagnostic workloads.
North America mobile cloud denotes distributed computing architectures where storage, processing, and application delivery occur via remote server infrastructure accessed through cellular and Wi-Fi networks on portable endpoints, typically requiring sub-100ms latency for interactive services. The primary commercial purpose centers on decoupling software functionality from local device constraints while enabling real-time synchronization across enterprise and consumer use cases. Public cloud deployment leads in absolute scale but hybrid configurations capture the fastest expansion as regulated industries demand data sovereignty. SaaS applications command the largest revenue pool among service types, though FaaS exhibits the steepest trajectory as developers adopt event-driven microservices architectures. Gaming and e-commerce applications concentrate margin-rich workloads requiring low-latency content delivery and elastic scaling.
FCC spectrum allocations for 5G mid-band directly shape mobile cloud capacity economics by determining available bandwidth density in metropolitan corridors. HIPAA security rules and state-level privacy frameworks such as California's CCPA impose encryption and access-control mandates that elevate compliance costs for healthcare-facing deployments. NIST cybersecurity standards further harden requirements for federal cloud procurement, filtering vendor eligibility. Stakeholders must monitor emerging FCC open RAN policies and state data-localization bills to anticipate infrastructure investment timing and partnership structures.
Market Dynamics
5G mid-band spectrum densification is compressing latency thresholds below 50ms across metropolitan corridors, forcing infrastructure providers to rearchitect edge node placement around FCC auction boundaries rather than traditional demand clustering.
Growth Catalysts
- FCC 5G Spectrum Auctions:Mid-band C-band allocations in the 3.7-3.98 GHz range unlock carrier aggregation capacity that mobile cloud providers leverage for guaranteed throughput SLAs in healthcare and autonomous vehicle applications.
- HIPAA Security Rule Expansion:HHS enforcement of encryption-at-rest mandates for patient-generated health data accelerates hybrid cloud adoption among regional hospital networks seeking on-premises control planes.
- AI Inference Offloading:Tensor Processing Unit integration at edge POPs enables real-time diagnostic workloads that local device silicon cannot execute, pulling compute gravity toward distributed infrastructure.
Market Restraints
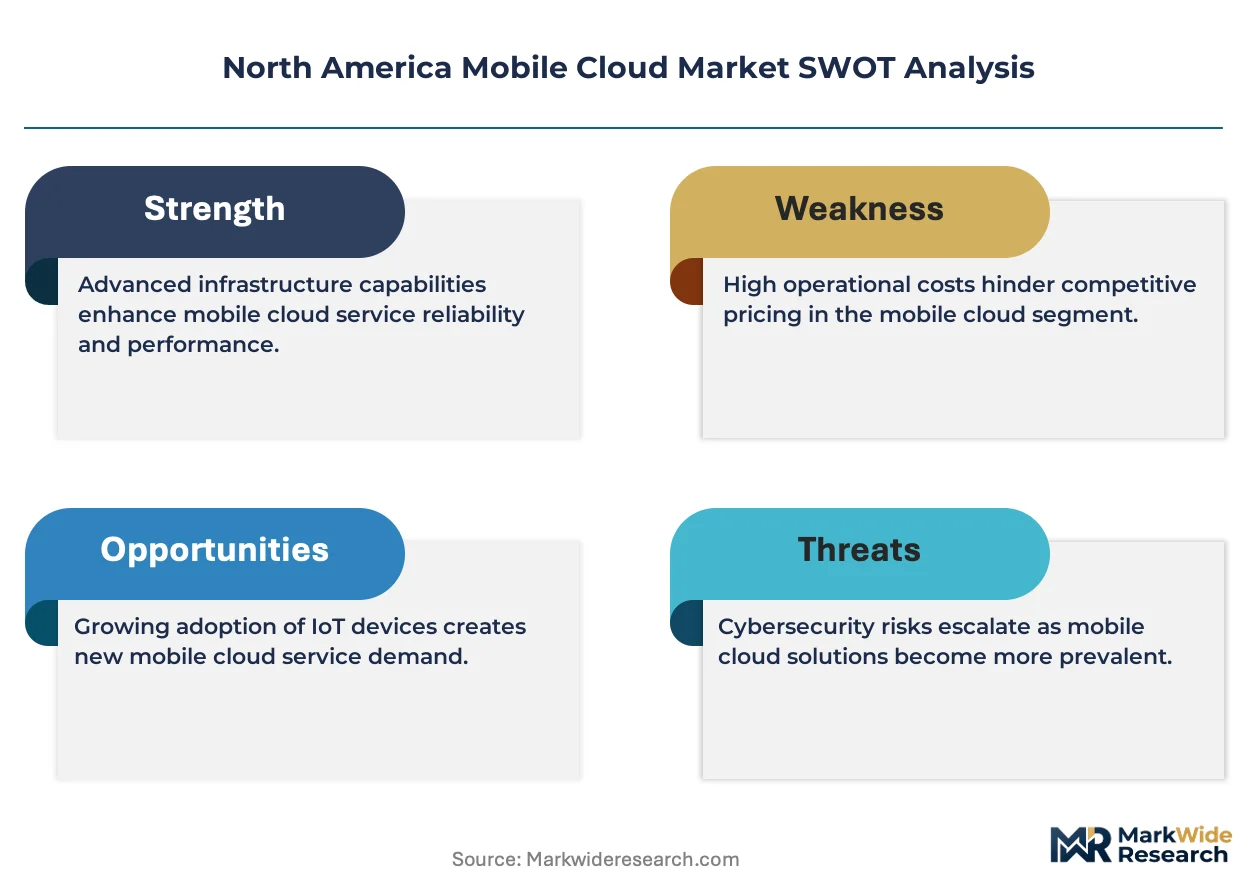
- Power Cost Volatility:Data center operators in Texas and California face electricity pricing swings tied to ERCOT and CAISO grid instability, compressing gross margins on high-availability deployments.
- Terrestrial Fiber Concentration:Last-mile connectivity in rural Montana and Wyoming depends on single-source incumbent carriers, creating chokepoints for guaranteed latency services.
- State Data Localization Friction:Divergent privacy frameworks between California's CCPA, Virginia's CDPA, and Colorado's CPA impose multi-jurisdictional compliance architectures that elevate legal overhead.
Strategic Opportunities
- Mexico Manufacturing Corridor:Nearshoring of automotive and electronics production to Baja California and Querétaro creates demand for cross-border mobile cloud nodes serving factory-floor IoT and predictive maintenance workloads.
- Indigenous Broadband Access:Tribal spectrum holdings and NTIA BEAD program funding enable sovereign network builds that mobile cloud providers can anchor through sovereign cloud partnerships.
- Grid-Interactive Edge:Convergence of battery storage systems with edge data centers allows operators to participate in demand-response markets, converting power flexibility into ancillary revenue streams.
Industry Challenges
- Container Orchestration Talent Scarcity:Kubernetes and serverless platform engineering skills concentrate in Seattle and San Francisco, forcing secondary market operators into compensation wars or remote hiring.
- Legacy Health System Integration:Epic and Cerner on-premises EMR architectures resist API-native refactoring, extending deployment timelines for hybrid cloud migrations at mid-sized hospital groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mobile Cloud Market |
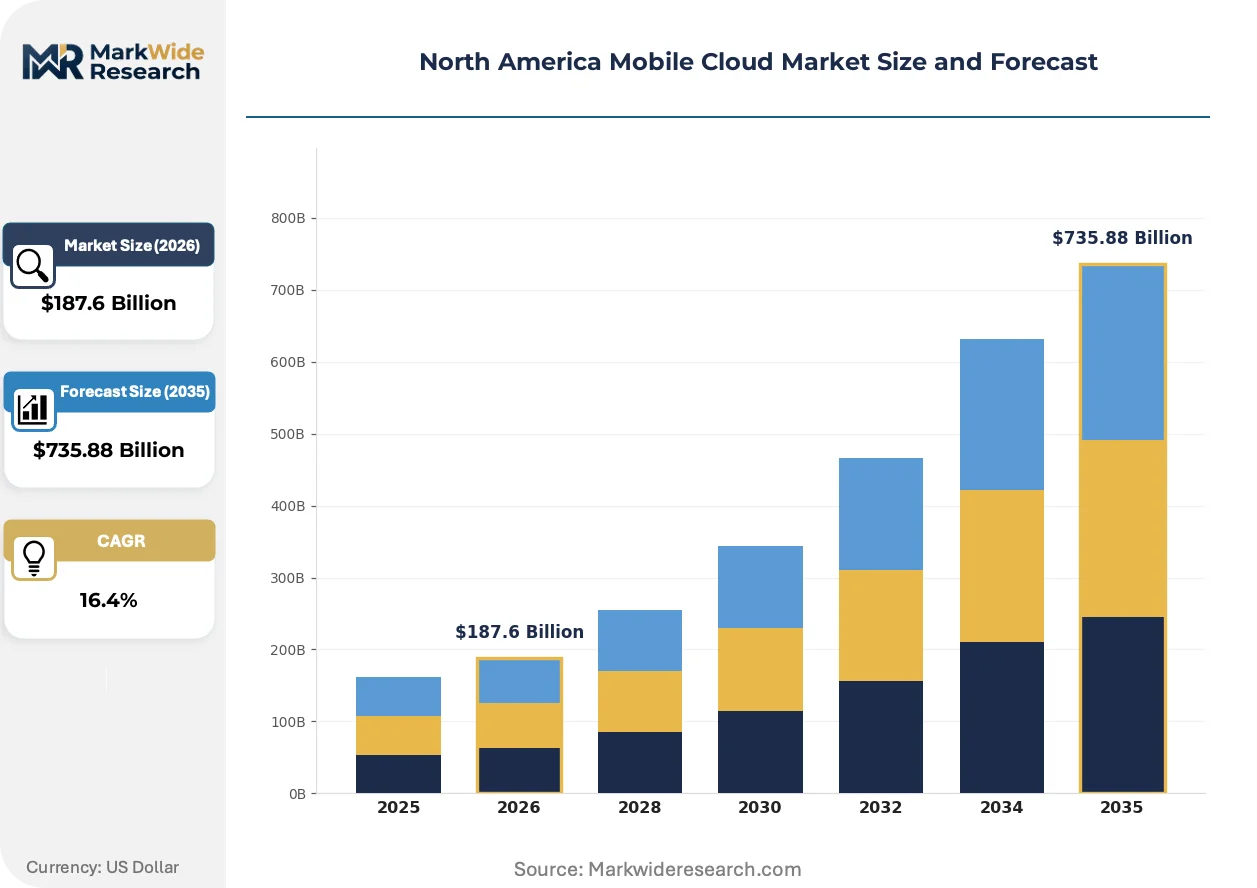
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $735.88 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: SaaS, PaaS, IaaS, FaaS End User: SMEs, Large Enterprises, Non-Profits, Government Application: Gaming, E-Commerce, Social Media, File Storage |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud Platform, IBM Cloud, Oracle Cloud Infrastructure, Apple, Salesforce, Akamai Technologies, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mobile Cloud Market Evolving Landscape
Edge-native application architectures are displacing centralized cloud models as latency-sensitive workloads proliferate across industrial, healthcare, and mobility use cases. This structural shift redefines competitive advantage around physical infrastructure density rather than hyperscale data center capacity.
Serverless computing is converging with 5G network slicing to create dedicated quality-of-service lanes for enterprise mobile applications. Manufacturing firms in Michigan and Ohio deploy function-as-a-service platforms at regional edge nodes to execute predictive maintenance algorithms without round-trip latency to core cloud regions. This convergence is compressing the addressable market for traditional virtual machine provisioning by enabling per-millisecond billing granularity that static infrastructure cannot match.
Canada's C-26 cybersecurity legislation and proposed critical infrastructure protection amendments impose incident reporting timelines that mobile cloud providers must embed into automated compliance pipelines. The industrial consequence is mandatory 24-hour breach disclosure to the Canadian Centre for Cyber Security, forcing architecture redesigns for cross-border data flows. Healthcare and financial services segments operating in Ontario and British Columbia are responding by segmenting Canadian-resident data into sovereign cloud instances with isolated key management infrastructure.
Enterprise procurement of mobile cloud services is fragmenting from centralized IT gatekeeping toward line-of-business self-service adoption. Manufacturing operations teams in Tennessee and Alabama now directly contract edge computing capacity for shop-floor analytics, bypassing traditional CIO approval workflows. This pattern concentrates most visibly in automotive supply chain verticals where plant managers prioritize uptime over enterprise-wide standardization, creating shadow IT governance challenges for central security teams.
North America Mobile Cloud Market Segmentation
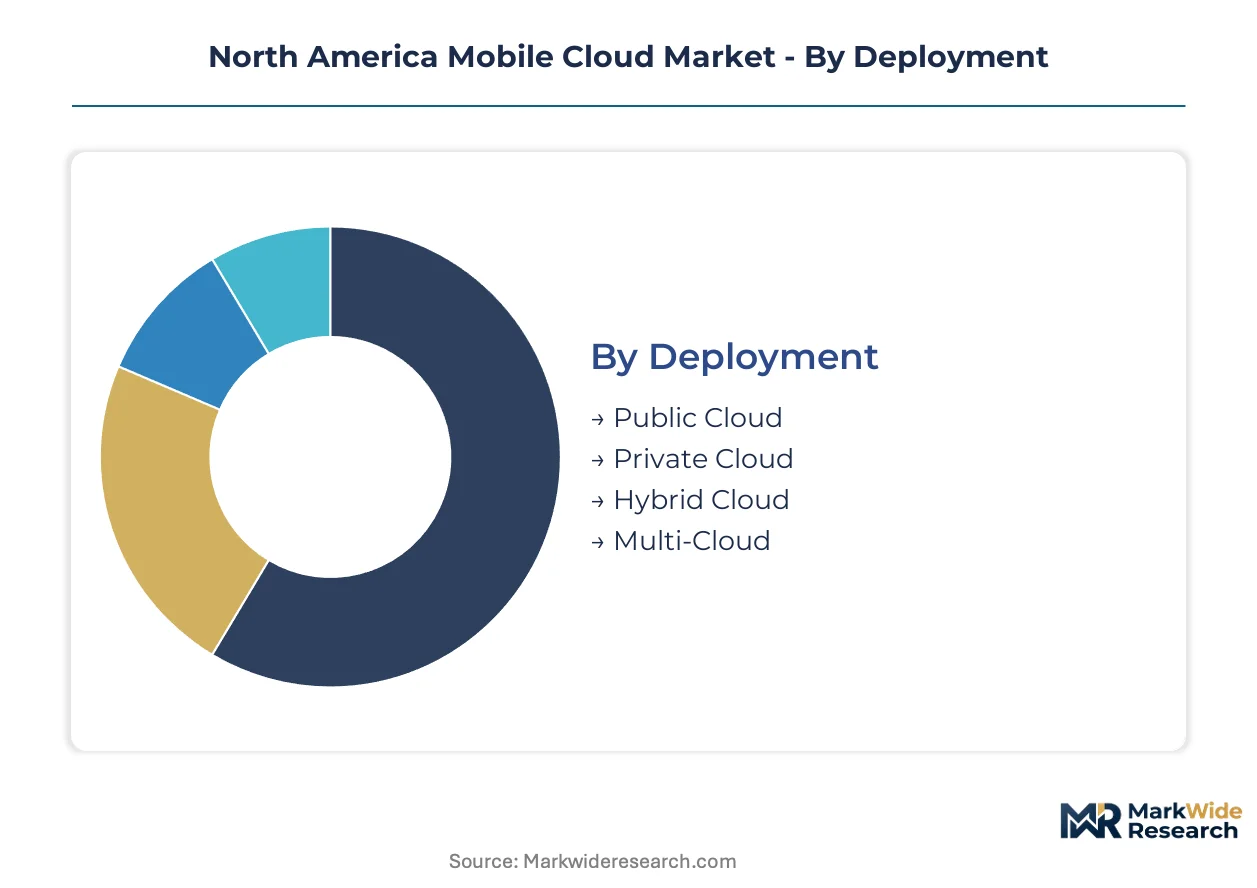
Mobile cloud segmentation in North America reflects divergent buyer priorities across regulated industries, latency-sensitive applications, and procurement governance models. Deployment architecture and service type selections directly determine compliance posture, operational expenditure profiles, and edge infrastructure requirements for enterprise buyers.
Deployment:
Buyers in this category differentiate primarily by data sovereignty requirements and workload sensitivity rather than cost optimization alone.
- Public Cloud:Shared infrastructure delivers elastic compute and storage through hyperscale provider networks. Demand concentrates in California's media and entertainment verticals where burst capacity for content rendering outweighs compliance overhead. FCC net neutrality enforcement shapes carrier interconnect pricing that flows through to public cloud egress cost structures.
- Hybrid Cloud:Split architectures maintain sensitive workloads on-premises while bursting non-critical operations to public infrastructure. Healthcare systems across Texas and Florida deploy hybrid configurations to satisfy HIPAA encryption-at-rest mandates for patient-generated data while leveraging cloud analytics for population health management.
- Private Cloud:Dedicated single-tenant infrastructure serves defense contractors and federal agencies requiring NIST 800-171 compliance. Procurement runs through FedRAMP-authorized vendors with isolated key management domains.
- Multi-Cloud:Orchestrated workloads across competing hyperscale providers reduce vendor lock-in and improve geographic redundancy. Financial services firms in New York and Chicago adopt multi-cloud strategies to satisfy state-level disaster recovery mandates while optimizing spot pricing arbitrage.
Public Cloud leads volumes today; Multi-Cloud is gaining share fastest.
Service Type:
Commercial buyers select service layers based on internal platform engineering maturity and application architecture complexity.
- SaaS:Pre-configured applications eliminate infrastructure management overhead for line-of-business buyers. Manufacturing operations teams in Tennessee and Alabama directly procure SaaS analytics tools for shop-floor optimization, bypassing centralized IT procurement workflows.
- FaaS:Event-driven compute executes code fragments without persistent server allocation. Automotive suppliers in Michigan deploy function-as-a-service at regional edge nodes for predictive maintenance algorithms requiring sub-50ms response times.
- PaaS:Managed development environments abstract underlying infrastructure for software engineering teams. Mid-sized healthcare IT vendors in Boston and Seattle leverage PaaS to accelerate FDA-regulated medical device software deployment timelines.
- IaaS:Raw compute, storage, and networking resources provide maximum architectural flexibility for sophisticated platform teams. Gaming studios in Vancouver and Los Angeles provision bare-metal GPU clusters through IaaS for real-time rendering workloads.
SaaS dominates revenue contribution; FaaS climbs the fastest as microservices architectures proliferate.
End User:
Organizational scale and capital access determine procurement sophistication and contract negotiation leverage in this category.
- Large Enterprises:Fortune 500 buyers command custom pricing, dedicated support tiers, and contractual data residency guarantees. Retail conglomerates operating across California, Texas, and New York negotiate multi-year commitments spanning thousands of edge locations.
- SMEs:Resource-constrained buyers prioritize consumption-based pricing and managed service overlays that minimize internal platform engineering headcount. Regional hospital networks in Arizona and Colorado adopt SME-targeted hybrid cloud bundles to satisfy HIPAA without dedicated security operations centers.
- Government:Federal, state, and municipal buyers operate under FedRAMP, StateRAMP, and CJIS compliance frameworks that filter vendor eligibility. Defense and civilian agencies procure through AWS GovCloud, Azure Government, and Google Cloud Public Sector regions.
- Non-Profits:Mission-driven organizations leverage provider grant programs and donated capacity for research and humanitarian applications. Academic medical centers in Boston and Houston access discounted cloud credits for genomic sequencing and epidemiological modeling.
Large Enterprises anchor contract value today; Government is expanding most quickly through sovereign cloud mandates.
Application:
Latency tolerance and data throughput requirements separate application verticals into distinct infrastructure procurement patterns.
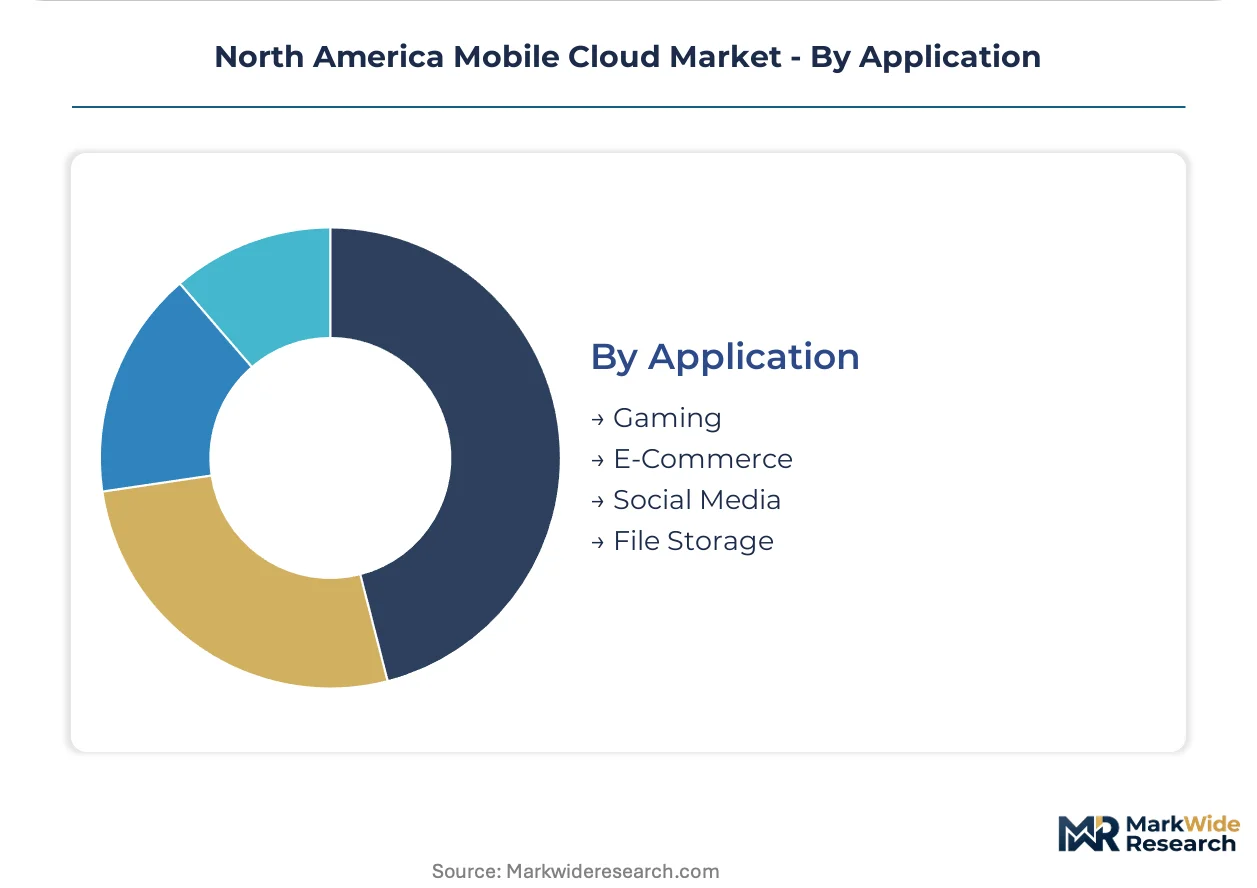
- Gaming:Real-time multiplayer synchronization and asset streaming demand sub-20ms latency through distributed edge nodes. Publishers in Montreal and Los Angeles provision regional capacity for battle royale and cloud gaming services where lag directly impacts monetization.
- E-Commerce:Elastic scaling for promotional events and personalized recommendation engines drives compute intensity. Retail platforms serving the San Francisco-to-San Diego corridor deploy auto-scaling container clusters to manage Black Friday and Prime Day traffic surges.
- Social Media:User-generated content ingestion and algorithmic feed curation require high-throughput object storage and AI inference. Platforms concentrate infrastructure in Northern Virginia and Oregon data center clusters with direct fiber access to submarine cable landing stations.
- File Storage:Archival and sync services prioritize durability and geographic redundancy over latency. Legal and financial services firms in New York and Toronto deploy cross-border replication to satisfy data residency and business continuity requirements.
E-Commerce generates the largest revenue pool; Gaming shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping mobile cloud infrastructure deployment as compliance cost differentials between jurisdictions accelerate cross-border capacity planning. Providers sequence edge node investments around FCC spectrum auctions, HIPAA enforcement zones, and provincial data residency mandates to optimize sovereign risk exposure.
United States
Healthcare systems in Texas and Florida drive hybrid cloud procurement to satisfy HIPAA encryption mandates while maintaining on-premises control planes for patient-generated data. FCC C-band auctions in the 3.7-3.98 GHz range determine carrier aggregation capacity for guaranteed throughput SLAs. Infrastructure concentrates in California's technology corridor from San Francisco to San Diego, where media verticals consume burst capacity for content rendering workloads.
Canada
C-26 cybersecurity legislation imposes 24-hour breach disclosure timelines to the Canadian Centre for Cyber Security, forcing architecture redesigns for cross-border data flows. Health Canada and provincial privacy commissioners enforce health data localization that segments Canadian-resident records into sovereign cloud instances. Toronto and Vancouver anchor financial services and gaming infrastructure clusters with direct submarine cable access.
Mexico
Nearshoring of automotive and electronics production to Baja California and Querétaro generates demand for cross-border mobile cloud nodes serving factory-floor IoT and predictive maintenance workloads. Federal telecommunications reform under IFT spectrum policies shapes carrier infrastructure economics. Mexico City Metro and Monterrey concentrate enterprise procurement as manufacturing operations teams directly contract edge capacity.
North America Mobile Cloud Market Competitive Landscape
Strategic partnerships dominate the current landscape as hyperscale providers anchor public sector contracts through sovereign cloud certifications and edge infrastructure joint ventures. The vendor base stratifies into three tiers: hyperscale platforms with federal authorization, regional specialists with vertical industry depth, and telecommunications carriers leveraging spectrum assets for network-edge convergence. Consolidation pressure intensifies as compliance costs filter vendor eligibility for healthcare and defense procurement. Portfolio diversification and geographic expansion represent the primary competitive vectors.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud Platform exemplify divergent positioning archetypes. AWS leverages GovCloud regions to anchor federal agency contracts with isolated key management domains. Microsoft sustains hybrid cloud dominance through on-premises integration architectures that satisfy HIPAA security rule expansions at regional hospital networks. Google differentiates on AI-optimized compute for real-time diagnostic workloads requiring Tensor Processing Unit integration at edge points of presence.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud Platform |
| IBM Cloud |
| Oracle Cloud Infrastructure |
| Apple |
| Salesforce |
| Akamai Technologies |
| Dell Technologies |
| Others |
Value Network & Pricing Analysis
Hyperscale-provider dominance against regional-edge-specialist fragmentation creates a bifurcated pricing architecture where AWS, Azure, and Google command 40-60% premiums for FedRAMP-authorized sovereign cloud instances while commodity colocation operators in secondary US markets compete on per-kilowatt power economics. This tier divergence feeds directly into supply chain configurations: premium-tier deployments anchor in Northern Virginia and Dallas-Fort Worth hyperscale campuses with diverse fiber paths and N+2 redundancy, while cost-optimized edge nodes concentrate in single-source carrier territories across the Mountain West where terrestrial fiber scarcity elevates transport costs.
Pricing Analysis
Distributor margins on hybrid cloud orchestration platforms compress to 8-12% as hyperscalers consolidate direct enterprise relationships, while systems integrators capture 25-35% markups on HIPAA-compliant deployment services. Pricing stratifies across premium sovereign-cloud tiers, standard multi-tenant public instances, and economy spot-compute pools. Cost compression in the economy tier intensifies because AWS, Microsoft, and Google engage in sustained price wars for GPU-accelerated workloads. Government buyers demonstrate lowest price sensitivity due to FedRAMP certification requirements that filter vendor pools, while SME manufacturing operations in Tennessee and Alabama exhibit highest sensitivity and bypass IT procurement for direct SaaS contracts.
Supply Chain Analysis
Regional distribution centers for edge computing hardware cluster in Phoenix, Dallas-Fort Worth, and Ashburn where Dell, HPE, and Super Micro maintain forward-stocked inventory for 48-hour rack integration. Supply draws from Taiwan and China for server motherboards and GPUs, South Korea for memory modules, and Mexico for sheet-metal enclosures and power distribution units. Single-source vulnerability in advanced AI accelerators from NVIDIA creates chokepoint risk for real-time diagnostic workloads. Distribution runs through carrier-neutral meet-me rooms and cloud exchange fabrics rather than traditional IT distributor networks, with last-mile fiber access determining effective delivery radius.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in North American mobile cloud services stems from AI inference workload premiums and sovereign-cloud certification arbitrage that allows authorized providers to capture 30-50% price premiums over standard public instances.
For Market Incumbents: Anticipate regulatory fragmentation between FCC open RAN mandates and state-level data localization bills by pre-positioning hybrid cloud architectures that segment Canadian-resident data into isolated key management domains. Defensive consolidation moves include acquiring Kubernetes talent in Seattle and San Francisco to address container orchestration scarcity, and securing long-term power purchase agreements with ERCOT and CAISO grid operators to lock in electricity cost structures. Priority levers rest on vertical integration into edge data center real estate in California's technology corridor and NIST 800-171 certification investment for defense contractor eligibility. For New Entrants and Emerging Players: Regional hospital networks in Arizona and Colorado represent an underserved buyer archetype seeking HIPAA-compliant hybrid bundles without dedicated security operations centers. White-space targets include sovereign cloud partnerships with tribal spectrum holders under NTIA BEAD program funding, and cross-border edge nodes serving automotive nearshoring corridors in Baja California and Querétaro. The most penetrable segment spans manufacturing operations teams in Tennessee and Alabama that procure shop-floor analytics through direct line-of-business contracts. Go-to-market execution should anchor on consumption-based pricing with managed service overlays that minimize internal platform engineering headcount. For Investors and Strategic Acquirers: Consolidation pressure builds where compliance costs for HIPAA encryption-at-rest and FedRAMP authorization filter vendor eligibility below sustainable scale thresholds. Long-term viability favors hyperscale platforms with federal authorization and regional specialists with vertical industry depth in healthcare or defense. Acquisition target archetypes include edge infrastructure operators with strategic real estate in FCC C-band auction boundaries and Kubernetes-native platform engineering teams. The signal to watch is FCC open RAN policy finalization timing, which will determine infrastructure investment sequencing and partnership structure economics.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | FedRAMP authorization unlocks federal agency contracts with 40-60% pricing premiums. |
| Edge Node Geographic Expansion | Proximity to FCC C-band boundaries reduces latency for autonomous vehicle workloads. |
| AI-Optimized Compute Investment | TPU integration at edge POPs enables real-time diagnostic workloads that command premium pricing. |
| Strategic Partnership with Telecom Carriers | Spectrum assets enable network-edge convergence for dedicated 5G network slicing. |
| Acquisition of Kubernetes Talent | Platform engineering scarcity in Seattle and San Francisco forces compensation wars or M&A. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cloud infrastructure executives, healthcare IT procurement officers, FCC policy analysts, and edge data center operators with secondary validation. Primary sources included hyperscaler capex disclosures, SEC 10-K infrastructure investment filings, and carrier spectrum auction participation records. Secondary data encompassed FCC C-band auction results, HHS HIPAA enforcement action databases, and NIST cybersecurity framework adoption metrics. Bottom-up triangulation aggregated individual edge node deployment announcements while top-down verification cross-checked against aggregate hyperscale region capacity expansion patterns.
Segment-weighting approaches distributed revenue projections across deployment architecture, service type, end-user scale, and application vertical with explicit modeling of healthcare regulatory compliance as a demand filter. The analytical framework applied variable growth coefficients across the projection horizon based on FCC spectrum release timelines and HIPAA enforcement intensity by state. CAGRs derived from historical hyperscale capex trajectories and edge infrastructure investment velocity. Industry-specific forecast inputs included 5G mid-band densification curves and AI inference workload migration patterns from on-premises to distributed edge architectures.
Underlying measurement precision varies by segment; public cloud and SaaS revenue pools carry tighter precision than sovereign cloud and FaaS trajectories where regulatory timing introduces uncertainty. Forecasts reflect documented assumptions regarding FCC policy implementation, HIPAA enforcement continuity, and hyperscaler competitive pricing behavior. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud API Market
Cloud Computing
United States Cloud Computing Market
Cloud Computing
Community Cloud Market
Cloud Computing
Global Cloud Office Services Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
GPU As a Service (Gpuaas) Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Cloud and Data Center Transformation Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
Public Cloud Application Infrastructure Services Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Cloud Database Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market