
 Cloud Managed Networking Market | 2026-2036
Cloud Managed Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Managed Networking Market Intelligence
The premium managed networking tier is rebalancing around AI-driven automation and zero-trust architectures, while commodity offerings stagnate on basic connectivity dashboards. Cisco dominates enterprise-grade hardware-software integration through its Meraki division. Juniper Networks differentiates on cloud-native routing intelligence for service provider backbones. HPE anchors mid-market hybrid deployments through its Aruba Central platform architecture.
Cloud managed networking refers to IT infrastructure administration where switching, routing, security, and access-point functions are orchestrated through centralized cloud controllers rather than on-premises management appliances, typically operating via encrypted tunnels with sub-100-millisecond policy propagation latency. The architecture eliminates truck rolls for branch configuration changes and enables elastic capacity scaling across distributed sites. Hybrid cloud deployment captures the largest installed base as enterprises retain sensitive traffic on private infrastructure while bursting analytics workloads to public substrates. Network monitoring and security management solution offerings command the deepest margin pools due to recurring subscription attach rates and compliance-driven renewal stickiness. Remote workforce connectivity use cases show the fastest expansion trajectory as permanent hybrid work policies harden post-pandemic.
FCC net neutrality rulings in the United States, EU NIS2 cybersecurity mandates, and China's MIIT cloud service licensing requirements collectively shape vendor certification burdens and cross-border data routing architectures. GDPR data residency clauses in Europe and China's GB standards for network equipment security testing create divergent compliance taxonomies that fragment product roadmaps. Stakeholders must evaluate whether multi-tenant controller architectures can satisfy jurisdiction-specific encryption and logging mandates without fragmenting operational consistency.
Market Dynamics
Zero-trust security mandates and AI-driven policy automation are compressing procurement cycles while fragmenting vendor qualification criteria across jurisdictions. Network buyers now prioritize controllers that unify threat intelligence with identity verification, forcing architectural consolidation.
Growth Catalysts
- EU NIS2 Directive:Cross-border cybersecurity obligations are compelling multi-site enterprises to replace on-premises appliances with centralized cloud controllers that automate compliance reporting.
- Healthcare digitization:Hospital systems deploying IoT-connected medical devices are adopting cloud-managed infrastructure to segment clinical networks from administrative traffic.
- SD-WAN convergence:Hybrid work policies are accelerating branch office upgrades that bundle secure access service edge with unified management platforms.
Market Restraints
- Controller concentration risk:Dependency on hyperscaler-hosted orchestration layers creates single-point-of-failure exposure during regional cloud outages.
- Semiconductor input volatility:Custom ASIC shortages for advanced switching silicon are extending hardware lead times beyond eighteen months.
- Data residency friction:China's MIIT licensing requirements and Russia's data localization laws are forcing redundant controller deployments that duplicate operational overhead.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for electronics production are attracting contract manufacturers that require scalable plant-floor networking without dedicated IT staff.
- Private 5G integration:Industrial campuses are converging cellular radio access networks with Wi-Fi management under single cloud dashboards for unified spectrum coordination.
- Outcome-based SLAs:Managed service providers are replacing per-port pricing with uptime-guaranteed contracts that align vendor revenue with network availability metrics.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises operating across AWS, Azure, and private infrastructure struggle to maintain consistent policy enforcement without controller sprawl.
- Legacy authentication protocols:Migration from RADIUS to certificate-based identity systems requires forklift upgrades of embedded systems with decade-long depreciation schedules.
- Certification timeline compression:FCC equipment authorization and EU CE marking processes are lagging behind product release cycles, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Managed Networking Market |
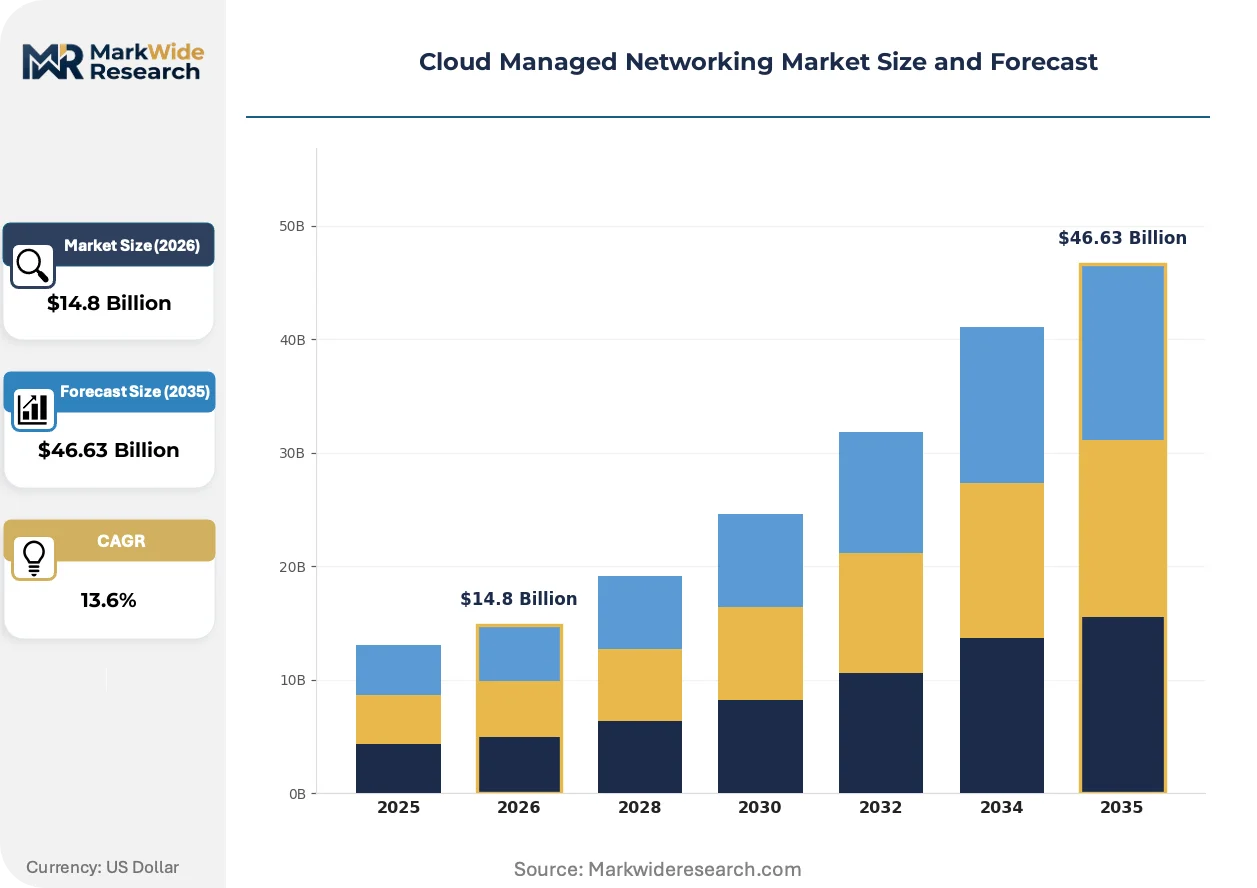
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Offering: Network Monitoring, Security Management, Configuration Management, Performance Optimization, Compliance Management Use Case: Remote Workforce Connectivity, Branch Network Management, Data Center Interconnect, IoT Device Integration, Network Automation End User Industry: Telecommunications, Manufacturing, Education, Government, Financial Services |
| Companies Covered | Nutanix, Meraki, Cisco, Broadcom, Juniper Networks, VMware, Alkira, Fortinet, HPE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Managed Networking Market Strategic Shifts & Innovations
Artificial intelligence is embedding directly into network control planes, shifting operational models from reactive ticketing to predictive remediation. This transformation is redrawing competitive boundaries between hardware specialists and software-native platforms.
Intent-based networking is expanding into enterprise campus deployments by translating business policies into automated configuration templates. Financial services institutions are piloting these systems for rapid branch provisioning. The technology is compressing deployment timelines from weeks to hours while reducing misconfiguration incidents.
The EU AI Act's risk classification framework is imposing documentation burdens on vendors deploying machine learning for anomaly detection. Network equipment manufacturers must now maintain algorithmic transparency logs for high-risk deployments. Healthcare and critical infrastructure buyers are prioritizing suppliers with pre-certified AI governance structures.
Enterprise procurement teams are consolidating vendor relationships around full-stack platforms rather than best-of-breed point solutions. Mid-market distributors are losing attach rates as direct-to-manufacturer subscription models displace traditional hardware resale. Germany's Mittelstand manufacturers exemplify this shift, negotiating enterprise agreements that bundle switching, security, and analytics under unified contracts.
Cloud Managed Networking Market Segmentation
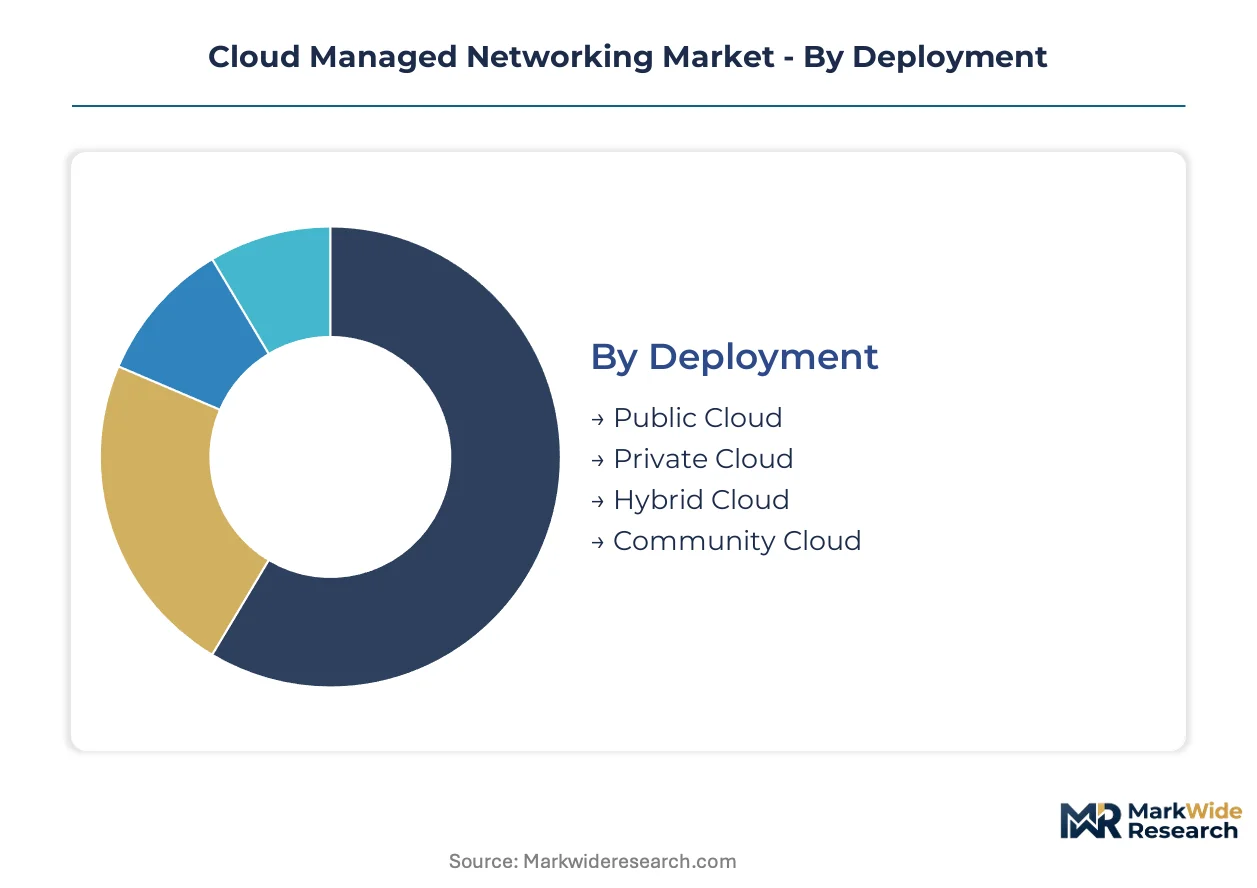
Cloud managed networking procurement decisions hinge on deployment architecture, solution depth, and operational use case. Each segmentation axis reveals distinct upgrade cycles, compliance burdens, and vendor qualification criteria that reshape competitive positioning across buyer tiers.
Deployment:
Replacement cycles for on-premises network appliances are compressing as enterprises migrate toward subscription-based orchestration models. Organizations now evaluate controller residency options against data sovereignty requirements and outage risk tolerance.
- Public Cloud:Fully hosted controller infrastructure delivers elastic scaling without capital expenditure. Financial services institutions in Singapore and Germany are standardizing on public deployments for non-sensitive traffic, driven by FCC net neutrality rulings that clarify cross-border data treatment.
- Private Cloud:Dedicated controller instances run within enterprise-owned data centers or sovereign facilities. Healthcare systems in France and government agencies across EU member states mandate private deployments to satisfy GDPR data residency clauses and EU NIS2 audit requirements.
- Hybrid Cloud:Split orchestration retains sensitive policy enforcement on-premises while bursting analytics to public substrates. Manufacturing clusters in Germany's Mittelstand segment favor hybrid architectures to segment operational technology networks from administrative systems.
- Community Cloud:Shared infrastructure serving consortia or sector-specific user groups with common compliance frameworks. University research networks and defense contractor collectives in the United States deploy community models to distribute certification costs.
Hybrid Cloud sits at the top of the volume ranking, with Public Cloud climbing the fastest as mid-market enterprises abandon depreciated appliance estates.
Solution Offering:
Margin concentration follows recurring subscription attach rates and compliance-driven renewal stickiness rather than perpetual license models. Vendors now bundle analytics and automation to displace point-product competitors.
- Network Monitoring:Real-time telemetry collection, flow analysis, and predictive alerting across distributed infrastructure. Telecommunications carriers in South Korea and Japan prioritize monitoring solutions with AI-embedded anomaly detection to reduce mean-time-to-resolution.
- Security Management:Unified threat intelligence, microsegmentation policy enforcement, and identity-aware access control. Critical infrastructure operators under EU NIS2 Directive mandates are consolidating security spend around cloud-native platforms with automated compliance reporting.
- Configuration Management:Centralized template deployment, drift detection, and version-controlled policy rollback. Retail branch networks with high churn rates leverage configuration automation to eliminate truck rolls.
- Performance Optimization:Application-aware routing, bandwidth allocation, and quality-of-service orchestration. Video-centric enterprises and broadcast media firms require sub-100-millisecond policy propagation for latency-sensitive workloads.
- Compliance Management:Automated evidence collection, audit trail generation, and regulatory mapping against jurisdiction-specific frameworks. Healthcare providers in the United States align HIPAA documentation with controller-native logging to reduce assessment preparation cycles.
Security Management commands the deepest margin pools, while Compliance Management is gaining share fastest among regulated verticals.
Use Case:
Operational priorities are fragmenting as permanent hybrid work policies harden and industrial IoT deployments scale. Procurement teams now specify outcome-based availability metrics rather than port-count pricing.
- Remote Workforce Connectivity:Secure access service edge integration, zero-trust client deployment, and home-office policy enforcement. Enterprise technology firms in the United States and United Kingdom are standardizing on cloud-managed remote access to replace legacy VPN concentrators.
- Branch Network Management:SD-WAN orchestration, local breakout optimization, and unified Wi-Fi switching across distributed sites. Quick-service restaurant chains and retail pharmacy networks require rapid provisioning for franchise expansion.
- Data Center Interconnect:Encrypted tunnel meshing, multi-cloud backbone optimization, and east-west traffic segmentation. Cloud service providers and colocation operators in Frankfurt, Singapore, and Ashburn demand programmable interconnection with API-driven provisioning.
- IoT Device Integration:Certificate-based onboarding, network slicing for sensor traffic, and protocol translation gateways. Manufacturing corridors in India under PLI scheme incentives are deploying scalable plant-floor networking without dedicated on-site IT staff.
- Network Automation:Intent-based policy translation, closed-loop remediation, and AI-driven capacity planning. Financial services institutions pilot these systems for rapid branch provisioning, compressing deployment timelines from weeks to hours.
Remote Workforce Connectivity leads current deployment volume, with Network Automation expanding most quickly as AI control planes mature.
End User Industry:
Vertical-specific certification requirements and procurement centralization patterns determine vendor selection criteria. Each industry imposes distinct resilience grades and audit documentation burdens.
- Telecommunications:Carrier-grade availability requirements, subscriber management integration, and regulatory interception compliance. National operators in Germany, Japan, and South Korea are converging cellular radio access networks with Wi-Fi management under single cloud dashboards.
- Manufacturing:Operational technology segmentation, deterministic latency guarantees, and private 5G integration. Industrial automation clusters in Germany prioritize centralized network orchestration platforms that unify spectrum coordination across cellular and unlicensed bands.
- Education:Multi-tenant campus architectures, guest access policy automation, and research network federation. University systems balance open collaboration requirements against ransomware defense imperatives.
- Government:Sovereign cloud mandates, classified network isolation, and supply chain security attestation. Defense and civilian agencies in the United States, France, and Australia enforce strict vendor nationality and component provenance rules.
- Financial Services:Real-time transaction network resilience, fraud detection integration, and regulatory reporting automation. Banking consortiums in Singapore and Switzerland demand outcome-based SLAs with uptime-guaranteed contracts.
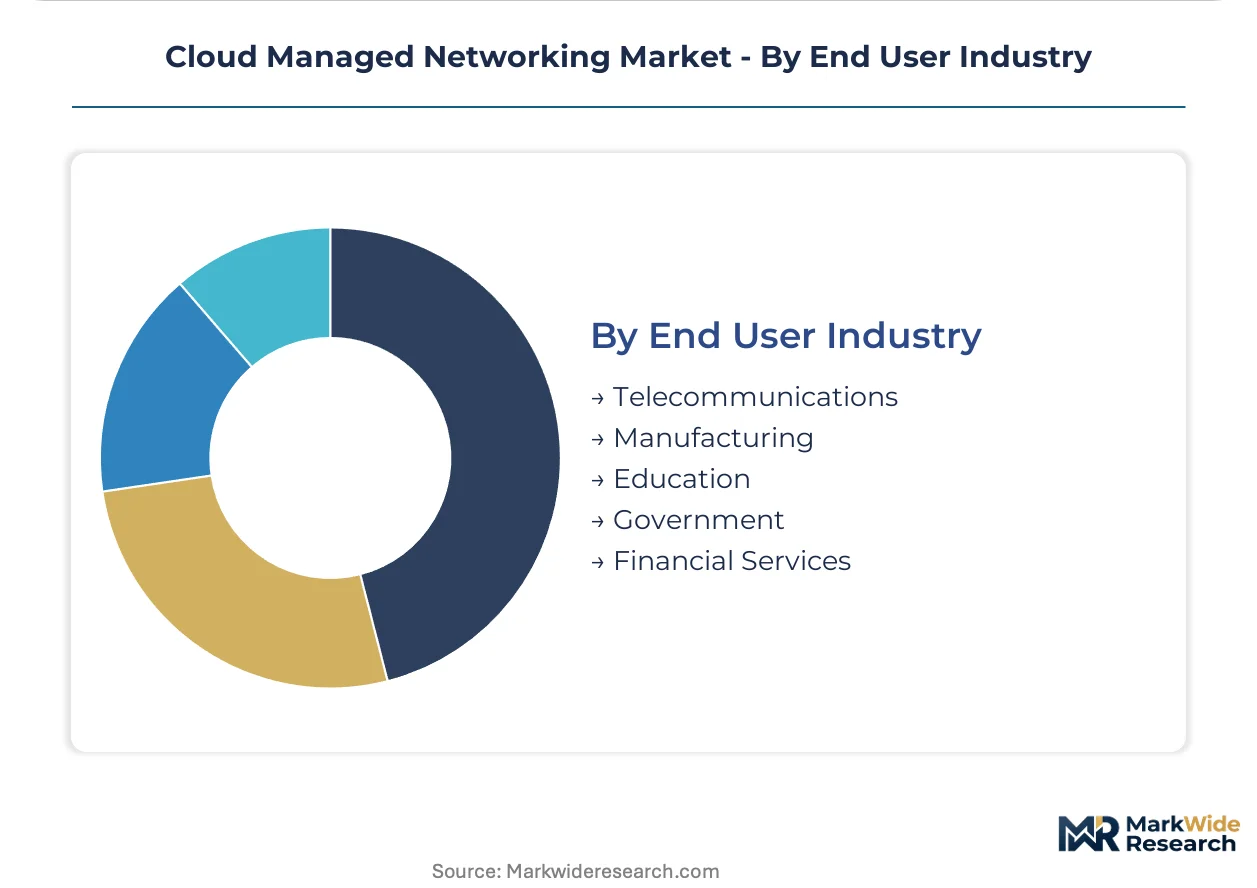
Telecommunications anchors current infrastructure spend, with Manufacturing showing the steepest expansion trajectory as private cellular deployments proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud networking engineering talent concentrates in Germany's Ruhr industrial corridor and California's Silicon Valley, anchoring dual poles of controller development and enterprise deployment expertise.
United States
Financial services institutions in Manhattan and cloud-native startups in Seattle drive controller demand for zero-trust branch architectures. FCC net neutrality rulings clarify cross-border data treatment for multi-tenant platforms. The Ashburn-Loudoun County data center cluster hosts hyperscale orchestration layers serving North American enterprise workloads.
Germany
Mittelstand manufacturers and automotive suppliers in Stuttgart and Munich prioritize centralized network orchestration for operational technology segmentation. EU NIS2 Directive mandates compel multi-site enterprises to automate compliance reporting through cloud controllers. Industrial automation clusters in Baden-Württemberg deploy private 5G integration with unified Wi-Fi management dashboards.
China
Electronics contract manufacturers under PLI-equivalent incentives require scalable plant-floor networking without dedicated IT staff. MIIT cloud service licensing requirements and GB standards for network equipment security testing force redundant controller deployments. Manufacturing corridors in Shenzhen and Dongguan converge cellular radio access networks with cloud-managed infrastructure.
India
PLI scheme incentives for electronics production attract contract manufacturers needing scalable networking across greenfield facilities. TRAI guidelines and data localization expectations shape vendor certification requirements. Manufacturing clusters in Tamil Nadu and Karnataka adopt cloud-managed infrastructure to segment operational technology from enterprise systems.
Singapore
Banking consortiums and maritime logistics operators demand outcome-based SLAs with uptime-guaranteed contracts. The Monetary Authority of Singapore's technology risk management guidelines enforce resilience standards for financial network infrastructure. The Jurong Innovation District serves as a testbed for private 5G and Wi-Fi convergence under single cloud dashboards.
Cloud Managed Networking Market Key Industry Players
Top-tier vendors anchor enterprise-grade hardware-software integration, while mid-market specialists compete on cloud-native routing intelligence and hybrid deployment flexibility. The vendor base stratifies across three functional tiers: full-stack platform providers, backbone-focused routing specialists, and security-centric access layer vendors. Dominant competitive moves include portfolio diversification into adjacent security and analytics domains, and geographic expansion through localized controller deployments satisfying data residency mandates.
Within the full-stack platform tier, Cisco and HPE exemplify integrated hardware-software architectures spanning switching, security, and analytics under unified subscription contracts. Juniper Networks occupies a position among backbone-focused specialists emphasizing cloud-native intelligence for service provider environments. These three anchors represent distinct strategic archetypes: Cisco embodies enterprise consolidation playbooks, HPE signals mid-market hybrid cloud penetration, and Juniper illustrates service provider backbone differentiation.
| Leading Market Players |
|---|
| Nutanix |
| Meraki |
| Cisco |
| Broadcom |
| Juniper Networks |
| VMware |
| Alkira |
| Fortinet |
| HPE |
| Others |
Cost & Logistics Intelligence
Mittelstand manufacturers in Germany anchor procurement volume for cloud-managed networking platforms, compressing vendor margins through consolidated enterprise agreements that bundle switching, security, and analytics under unified subscription contracts. This buyer concentration shifts pricing power toward volume-scaled SaaS tiers rather than per-port transactional models.
Pricing Analysis
Bundled full-stack platforms command premium attach rates against unbundled point solutions, with three-tier pricing structure across premium, standard, and economy levels differentiating by compliance certification depth and AI automation capabilities. Price differentiation hinges on GDPR audit readiness and zero-trust architecture maturity. Cost compression in the standard tier intensifies because hyperscaler-hosted controller commoditization erodes hardware-software integration premiums. Healthcare and government verticals show least price sensitivity due to EU NIS2 mandate urgency, while mid-market distributors face margin squeeze from direct manufacturer subscription displacement.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific semiconductor hubs complicates just-in-time delivery for custom ASIC-dependent switching hardware. Controller silicon fabrication concentrates in Taiwan, South Korea, and the United States, drawing from rare earth substrates and advanced lithography equipment. Single-source vulnerability runs through TSMC's leading-edge node allocation for merchant silicon vendors. Distribution runs through direct-to-enterprise subscription portals and hyperscaler marketplace integrations, bypassing traditional hardware resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-managed networking functions as a stable compounder, with EU regulatory mandates for automated compliance reporting creating durable renewal stickiness across multi-site enterprises.
For Market Incumbents: Extend platform consolidation into adjacent security analytics domains to defend against cloud-native routing specialists eroding service provider backbone share. Prioritize localized controller deployments in China and Russia to satisfy MIIT licensing and data localization requirements without fragmenting operational consistency. Deepen backward integration into custom switching silicon to insulate against ASIC shortage lead time extension. For New Entrants and Emerging Players: AI-native intent-based policy translation offers the most penetrable wedge for mid-market manufacturers lacking dedicated IT staff for legacy appliance forklift upgrades. Target India's PLI-funded electronics manufacturing corridors with plant-floor networking automation that segments operational technology without on-site engineering presence. Lead with API-first provisioning and outcome-based uptime guarantees rather than per-port pricing to bypass incumbent subscription lock-in. For Investors and Strategic Acquirers: Hyperscaler cloud divisions and telecommunications carriers are the most active acquirers in this space, seeking vertical integration into enterprise edge orchestration. Long-term viability rests on controller architecture portability across AWS, Azure, and sovereign cloud substrates. Monitor private 5G-Wi-Fi convergence deployment velocity in German industrial automation clusters as inflection indicator for manufacturing vertical penetration depth.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies threat intelligence with identity verification under single dashboards, compressing procurement cycles for NIS2-mandated enterprises. |
| Geographic Expansion | Localized controller instances in Shenzhen and Frankfurt satisfy GDPR and MIIT data residency without operational fragmentation. |
| Acquisition of Specialist Firm | Absorbs AI-native anomaly detection capabilities required for EU AI Act algorithmic transparency documentation burdens. |
| Product Launch | Introduces private 5G-radio convergence modules for spectrum coordination in Baden-Württemberg manufacturing clusters. |
| Strategic Partnership | Aligns managed service provider SLAs with uptime-guaranteed contracts linking vendor revenue to network availability metrics. |
Research Approach
Direct dialogue with network engineering directors, cloud procurement officers, compliance auditors, and managed service provider executives grounded qualitative assessment, cross-referenced against SEC filings from networking equipment vendors, hyperscaler capex disclosures, EU regulatory directive texts, and telecommunications carrier infrastructure spend reports. Bottom-up deployment sizing across public, private, hybrid, and community cloud architectures triangulated with top-down market aggregation from controller subscription revenue disclosures.
Segmentation outputs across deployment model, solution offering depth, operational use case, and end-user industry vertical fed into analytical framework spanning the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating EU NIS2 compliance deadline effects and healthcare IoT device proliferation rates. Forecast inputs included semiconductor lead time indices and hyperscaler data center build-out pipelines.
The model holds under stable regulatory enforcement timelines; deviation in EU AI Act implementation pace or MIIT licensing suspension would shift controller architecture investment priorities. Forecasts reflect documented assumptions about hybrid work policy permanence and industrial automation cluster expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud IDE Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
GPU As a Service (Gpuaas) Market
Cloud Computing
Cloud API Market
Cloud Computing
Global Cloud Business Email Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
North America Cloud Computing Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Cloud Management Market
Cloud Computing
Cloud Data Warehouse Market
Cloud Computing
SME Cloud Market