
 AI Platform Market | 2026-2036
AI Platform Market Size, Share, and Industry Trends Forecast 2026-2036
AI Platform Market Analysis
Enterprise demand is rotating from traditional IT buyers toward line-of-business executives who control operational budgets. Microsoft leverages its Azure ecosystem to anchor hybrid deployments across regulated industries. NVIDIA sustains technology leadership in GPU-accelerated training infrastructure. Amazon Web Services competes through multi-cloud orchestration tools that reduce vendor lock-in.
An AI platform is a software environment that provides pre-built machine learning frameworks, data pipelines, and model-serving infrastructure, typically requiring GPU clusters with terabyte-scale memory bandwidth and sub-millisecond inference latency. Its primary commercial purpose is to abstract infrastructure complexity so enterprises can deploy predictive models without building custom MLOps stacks. Cloud-based deployment captures the dominant share of new bookings because hyperscalers bundle compute credits with platform licenses. Natural language processing solutions are expanding fastest as enterprises deploy large language models for customer service automation. Machine learning platforms remain the margin pool where specialized chipsets and proprietary frameworks create pricing power.
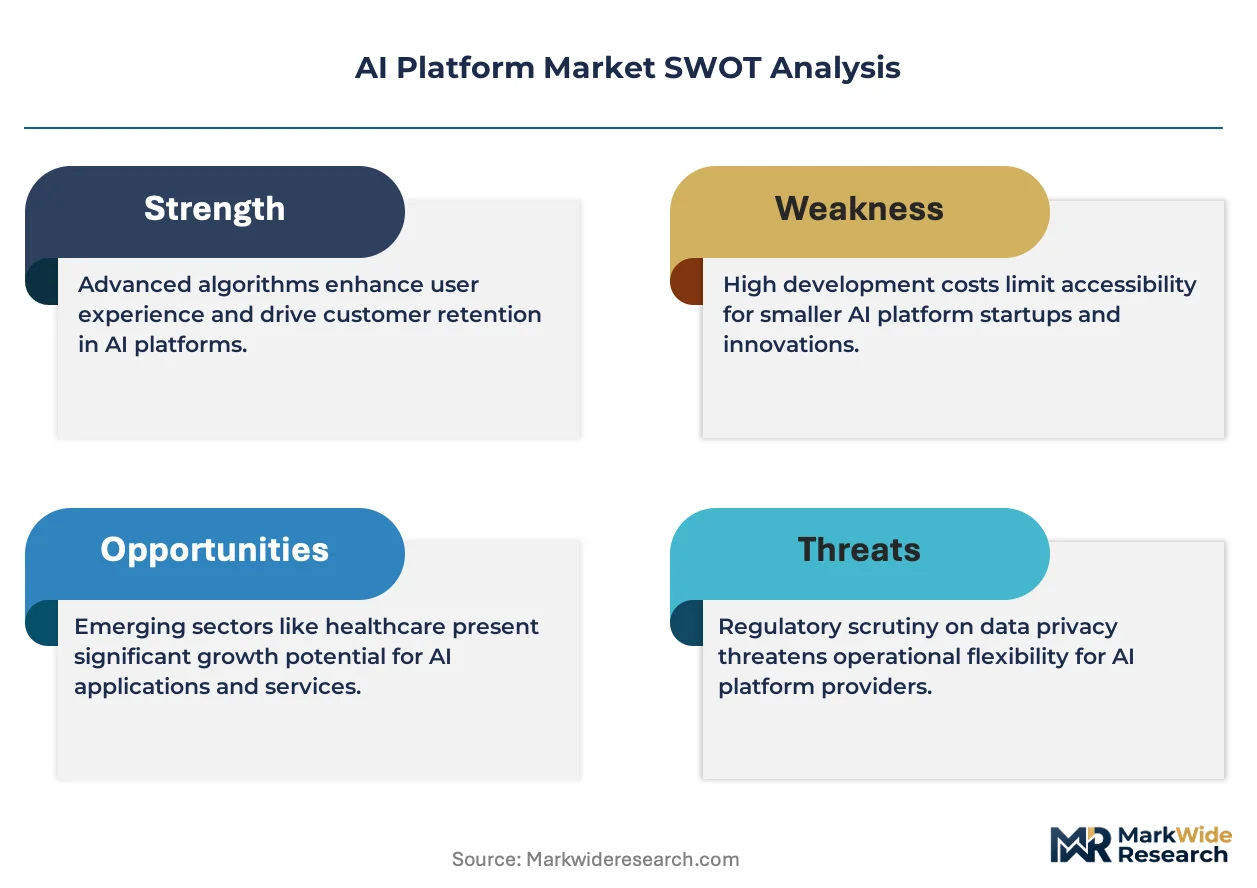
The EU AI Act imposes conformity assessments on high-risk applications, compelling platform vendors to embed audit trails and bias-testing modules. The FDA in the United States requires clinical validation for AI-enabled diagnostic tools, creating a dual-track compliance burden for healthcare-facing platforms. China's SAMR enforces algorithmic recommendation transparency rules that affect personalization engines. Stakeholders must monitor how divergent national AI governance frameworks fragment model deployment architectures.
Market Dynamics
Enterprise procurement authority is migrating from centralized IT departments to operational executives who control departmental budgets, compressing vendor sales cycles and forcing platform providers to restructure pricing around consumption metrics rather than perpetual licenses.
Growth Catalysts
- EU AI Act compliance mandates:High-risk application classifications require embedded audit infrastructure, creating mandatory upgrade cycles for existing deployments across healthcare and financial services.
- GPU cluster densification:Hyperscalers in Northern Virginia and Oregon are expanding terabyte-scale memory bandwidth facilities, reducing latency barriers for real-time inference workloads.
- Predictive diagnostics in healthcare:Hospital systems are accelerating procurement of clinical validation-ready platforms to automate radiology and pathology workflows.
Market Restraints
- NVIDIA supply concentration:Training infrastructure dependency on a single GPU architecture creates procurement bottlenecks and pricing volatility for compute-intensive workloads.
- FDA dual-track validation:Clinical AI tools require separate software and hardware clearance pathways, extending time-to-revenue for healthcare-facing vendors by 18-24 months.
- Specialized talent scarcity:MLOps engineering expertise concentrates in Seattle, San Francisco, and Boston, inflating compensation costs for platform deployment teams.
Strategic Opportunities
- India's BIS certification pathway:The country's standards body is developing AI system safety frameworks, opening early-mover advantages for compliant platform localization.
- Edge inference convergence:Model compression techniques combined with ARM-based neural accelerators are enabling on-device deployment without cloud dependency.
- Outcome-based pricing models:Healthcare providers are piloting contracts tied to diagnostic accuracy improvements, shifting vendor revenue from seat licenses to performance guarantees.
Industry Challenges
- Legacy EHR integration complexity:Hospital IT environments run fragmented data architectures that resist standardized API connections, forcing costly custom implementation work.
- Cross-border model portability:Divergent national governance frameworks fragment deployment architectures, requiring region-specific model variants that multiply engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Platform Market |
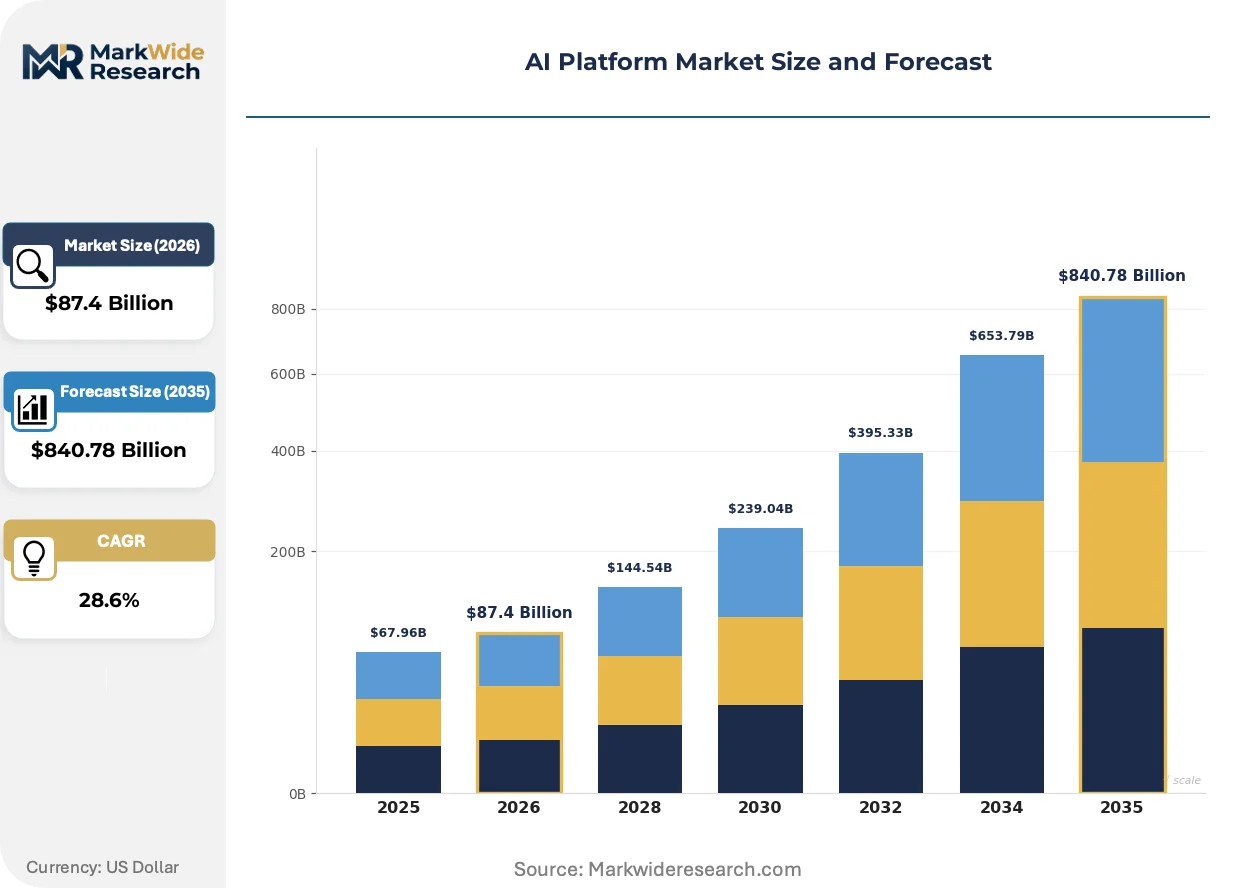
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $840.78 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Cloud Solution: Machine Learning, Natural Language Processing, Computer Vision, Data Analytics End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Application: Fraud Detection, Predictive Maintenance, Customer Segmentation, Personalization |
| Companies Covered | Microsoft, Google, Amazon Web Services, OpenAI, IBM, NVIDIA, Oracle, Salesforce, DataRobot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Platform Market Emerging Trajectories
Foundation model architectures are fragmenting into specialized vertical variants, while regulatory compliance becomes a product feature rather than an afterthought. Procurement authority continues decentralizing toward line-of-business executives.
Monolithic large language model stacks are decomposing into modular component architectures. Healthcare providers and financial institutions are adopting smaller, fine-tuned variants trained on proprietary datasets. This decomposition is compressing the competitive moat of generalist platforms while elevating domain-specific inference providers.
The EU AI Act's risk-based classification system is reshaping product roadmaps. High-risk application categories now require conformity assessment documentation and bias-testing modules as standard features. Healthcare platforms targeting European deployment are restructuring engineering teams to embed compliance automation into CI/CD pipelines.
Consumption-based procurement is displacing traditional enterprise licensing. Operational executives in manufacturing and retail are negotiating platform contracts tied to transaction volumes or inference call counts. This shift is most visible in the United States, where cloud marketplace purchasing channels now capture the dominant share of new bookings.
AI Platform Market Segmentation
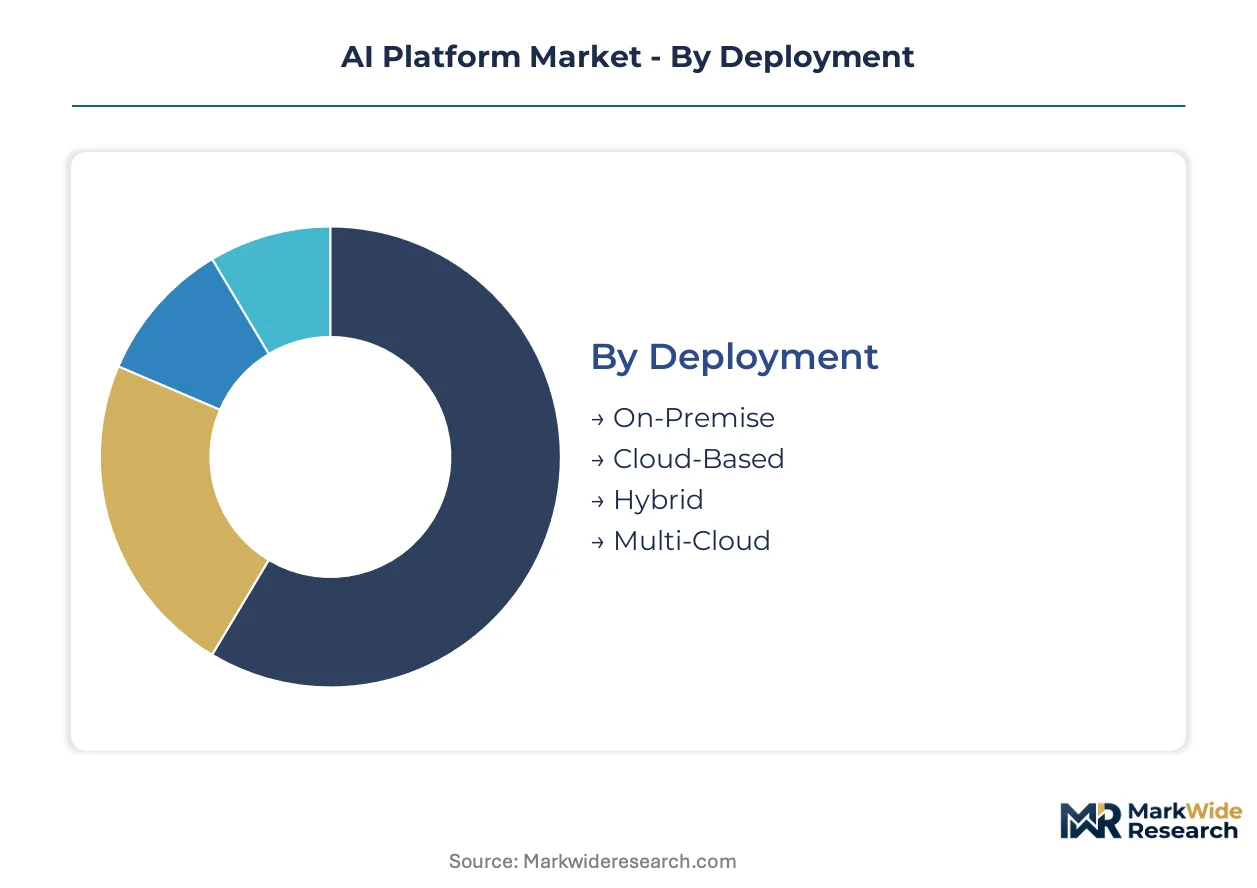
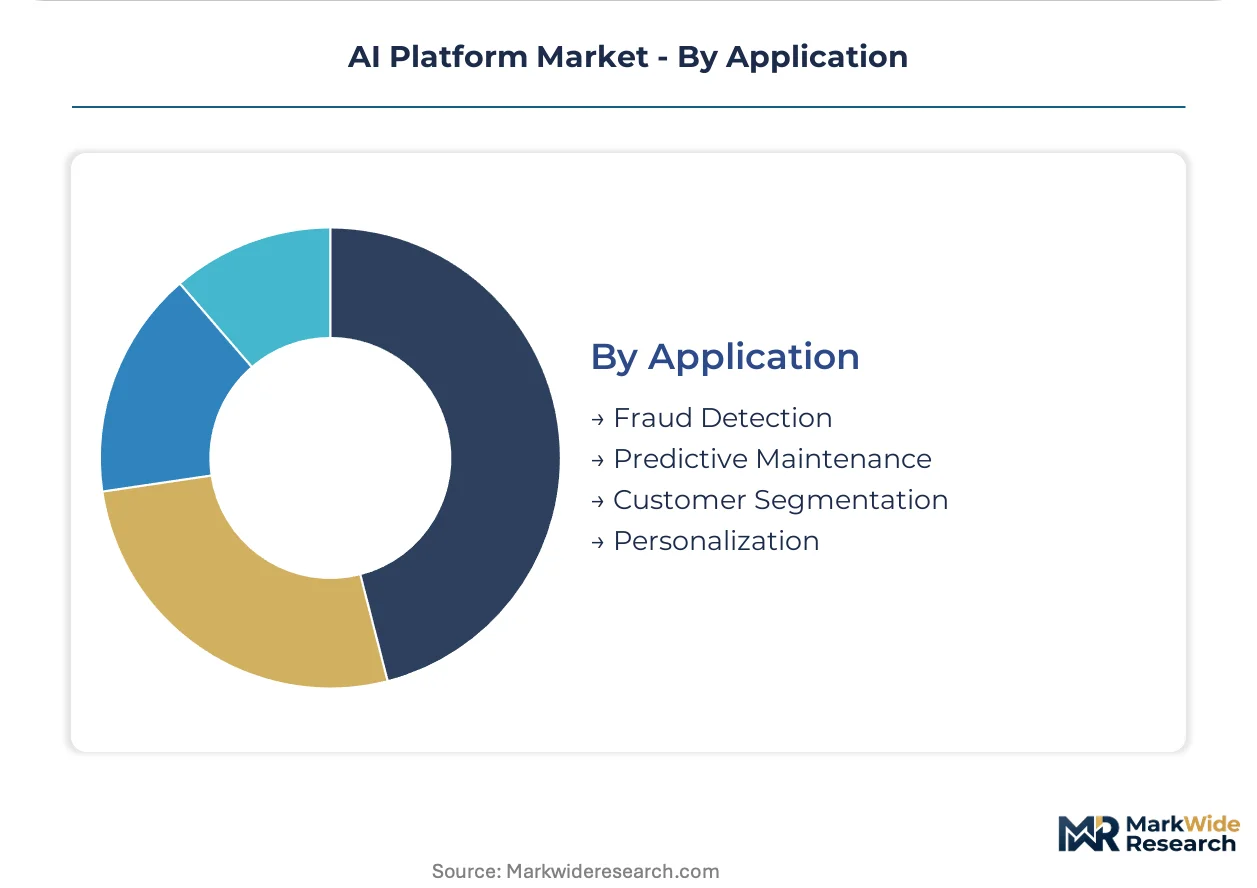
AI platform segmentation reveals where infrastructure investments concentrate and how procurement authority distributes across buyer types. The four-dimensional structure—deployment mode, solution stack, end-user scale, and application use case—determines pricing architecture and sales channel strategy for vendors competing in this market.
Deployment:
Margin pools concentrate in hybrid configurations where vendors bundle on-premise hardware with cloud orchestration licenses.
- Cloud-Based:Hyperscalers in Northern Virginia and Oregon anchor terabyte-scale memory bandwidth facilities, driving procurement from healthcare providers seeking clinical validation-ready platforms without capital expenditure. The EU AI Act's high-risk classification mandates are accelerating migration to audited cloud environments with embedded compliance automation.
- Hybrid:Microsoft leverages its Azure ecosystem to capture regulated industries requiring data sovereignty for patient records alongside burst compute for model training. Financial services firms in Frankfurt and Singapore negotiate consumption-based contracts spanning private GPU clusters and public inference endpoints.
- On-Premise:Defense contractors and national healthcare systems mandate air-gapped deployments for classified or patient data.
- Multi-Cloud:Amazon Web Services orchestration tools reduce vendor lock-in for enterprises hedging against single-provider concentration risk.
The dominant share belongs to Cloud-Based deployments, while Hybrid is closing the gap fastest as compliance requirements harden.
Solution:
Application intensity varies sharply by vertical, with healthcare and financial services driving divergent technology priorities.
- Natural Language Processing:Large language model decomposition into modular components is compressing generalist platform moats while elevating domain-specific inference providers. Hospital systems automate radiology report generation; retail chains deploy customer service automation with sub-millisecond latency requirements.
- Machine Learning:Proprietary frameworks and specialized chipsets create pricing power in training infrastructure. NVIDIA's GPU architecture concentration creates procurement bottlenecks for compute-intensive workloads across pharmaceutical discovery and algorithmic trading.
- Computer Vision:Manufacturing quality inspection and autonomous vehicle perception systems demand edge-optimized model compression.
- Data Analytics:Legacy EHR integration complexity forces costly custom implementation work for healthcare providers seeking predictive diagnostics.
Machine Learning retains the revenue concentration, though Natural Language Processing is expanding most quickly as enterprise automation budgets shift.
End User:
Budget authority migration from IT departments to operational executives restructures contract terms across buyer tiers.
- Large Enterprises:Manufacturing and retail operational executives negotiate platform contracts tied to transaction volumes or inference call counts through cloud marketplace purchasing channels. Consumption metrics displace perpetual licenses as procurement authority decentralizes.
- SMEs:Pre-built MLOps stacks abstract infrastructure complexity for organizations lacking Seattle, San Francisco, or Boston-based engineering talent. India's BIS certification pathway opens early-mover advantages for compliant platform localization targeting mid-market growth.
- Government Agencies:Dual-track FDA validation requirements extend time-to-revenue for healthcare-facing vendors by 18-24 months.
- Educational Institutions:Research computing grants drive GPU cluster access for foundation model training.
Large Enterprises command the dominant procurement volume, while SMEs are gaining share fastest as low-code deployment tools mature.
Application:
Use case specificity determines whether vendors compete on accuracy benchmarks or operational efficiency metrics.
- Personalization:China's SAMR enforces algorithmic recommendation transparency rules affecting engine architectures. Retailers pilot outcome-based contracts tied to conversion rate improvements, shifting revenue from seat licenses to performance guarantees.
- Fraud Detection:Real-time inference requirements drive GPU cluster densification in financial services hubs. Cross-border model portability challenges fragment deployment architectures for multinational banks operating under divergent national governance frameworks.
- Predictive Maintenance:Industrial IoT sensor integration demands edge inference convergence with ARM-based neural accelerators.
- Customer Segmentation:Marketing technology stacks integrate platform APIs for automated campaign orchestration.
Personalization holds the dominant application share, while Fraud Detection is climbing the fastest as real-time transaction volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler infrastructure concentrates in the United States, with Northern Virginia and Oregon hosting terabyte-scale memory bandwidth facilities. Cloud marketplace purchasing channels capture the dominant share of new bookings. Divergent national AI governance frameworks fragment model deployment architectures across jurisdictions.
United States
Hospital systems accelerate procurement of clinical validation-ready platforms for radiology automation. The FDA requires dual-track software and hardware clearance for AI-enabled diagnostic tools. Northern Virginia's GPU cluster densification reduces latency barriers for real-time inference workloads.
China
Domestic cloud providers expand foundation model training capacity for personalization engines. SAMR enforces algorithmic recommendation transparency rules affecting engine architectures. Beijing-Tianjin-Hebei anchors national AI infrastructure investments with state-backed compute subsidies.
Germany
Financial services firms in Frankfurt negotiate consumption-based contracts spanning private GPU clusters and public endpoints. The EU AI Act's high-risk classification mandates embedded audit infrastructure for banking applications. Bavaria's automotive sector deploys edge inference for manufacturing quality inspection.
India
Mid-market enterprises adopt pre-built MLOps stacks to bypass MLOps engineering talent scarcity. BIS is developing AI system safety frameworks with early-mover advantages for compliant platform localization. Karnataka's Bengaluru cluster concentrates software engineering capacity for platform deployment teams.
United Kingdom
Research institutions drive GPU cluster access for foundation model training through computing grants. GDPR compliance requirements shape data residency specifications for hybrid deployments. London's financial services sector pilots outcome-based contracts tied to fraud detection accuracy improvements.
AI Platform Market Vendor Landscape
Concentration sits with hyperscale cloud providers who bundle compute credits with platform licenses. The vendor base spans three tiers: infrastructure-anchored platforms, specialized ML tooling providers, and vertical-specific inference services. Strategic moves center on multi-cloud orchestration capabilities and compliance automation embedding.
Within the hyperscale tier, Microsoft leverages its Azure ecosystem to anchor hybrid deployments, while Amazon Web Services competes through multi-cloud orchestration tools. NVIDIA occupies a position as the specialized chipset layer for GPU-accelerated training infrastructure. These three entities represent the dominant competitive archetypes: ecosystem-integrated platforms, infrastructure-agnostic orchestrators, and hardware-dependent performance providers.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| OpenAI |
| IBM |
| NVIDIA |
| Oracle |
| Salesforce |
| DataRobot |
| Others |
Supply Flow & Price Mechanics
Terabyte-scale memory bandwidth facilities in Northern Virginia and Oregon generate steep scale economies that compress unit economics for GPU-accelerated training clusters. These hyperscaler concentrations simultaneously establish price floors for on-premise alternatives and create procurement leverage for cloud-based consumption models.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise consumption bands, with hyperscalers offering committed-use discounts that scale with inference call volume. Price differentiation hinges on certification grade—EU AI Act conformity assessment documentation commands premium positioning—and vertical integration depth of the underlying chipset stack. Pricing pressure stems from NVIDIA supply concentration creating procurement bottlenecks for training workloads. SMEs exhibit highest price sensitivity due to MLOps talent scarcity inflating deployment costs, while large enterprises negotiate favorable terms through cloud marketplace purchasing channels.
Supply Chain Analysis
Inventory lead times for GPU clusters stretch substantially due to single-source dependency on NVIDIA's foundry partnerships. Geographic supply concentration centers on Taiwan for advanced semiconductor fabrication, the United States for hyperscaler cloud infrastructure, and China for edge-optimized ARM-based neural accelerators. Raw material dependencies include high-bandwidth memory modules, specialized cooling systems, and rare earth elements for magnetics. Single-source vulnerability in GPU architecture creates systemic procurement risk. Distribution runs through direct hyperscaler marketplaces and channel partners serving regulated industries requiring compliance automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI platform adoption sits in early-cycle expansion as healthcare providers accelerate procurement of clinical validation-ready systems for radiology automation. Regulatory compliance mandates across the EU AI Act and FDA dual-track pathways create sustained upgrade tailwinds.
For Market Incumbents: Fortify hybrid deployment architectures by embedding EU AI Act conformity assessment automation into CI/CD pipelines. Expand GPU cluster densification in Northern Virginia to capture burst compute demand from financial services firms. Counter emerging specialized vertical inference providers by acquiring domain-specific model compression capabilities.
For New Entrants and Emerging Players: Anchor in India's BIS certification pathway to capture mid-market enterprises seeking pre-built MLOps stacks without Seattle or San Francisco-based engineering teams. Target healthcare providers in secondary US markets burdened by legacy EHR integration complexity. Pursue outcome-based pricing pilots tied to diagnostic accuracy improvements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized vertical inference providers over generalist foundation model platforms. Long-term viability rests on compliance automation depth and domain-specific dataset access. Monitor FDA dual-track clearance timelines as inflection indicator for healthcare-facing platform revenue recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Automation Embedding | EU AI Act mandates reshape product roadmaps for European healthcare deployment. |
| Vertical Model Specialization | Domain-specific inference providers capture radiology and pathology automation budgets. |
| Hybrid Cloud Expansion | Microsoft Azure ecosystem captures regulated industries requiring data sovereignty. |
| Edge Inference Convergence | ARM-based neural accelerators enable on-device deployment without cloud dependency. |
| Outcome-Based Contracting | Healthcare providers pilot performance guarantees tied to diagnostic accuracy improvements. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with platform engineers, IT procurement officers at hospital systems, MLOps specialists in Seattle and Boston, and channel partners serving financial services. Secondary validation drew from hyperscaler capex disclosures, SEC filings, FDA 510(k) clearance databases, and EU AI Act implementation guidance. Bottom-up deployment counts triangulated against top-down hyperscaler revenue attribution.
Across the analysis window, forecasts modeled deployment mode, solution stack, end-user scale, and application use case segmentation. CAGRs were derived from elasticity-adjusted adoption curves incorporating regulatory compliance mandate timelines and GPU supply constraints. Industry-specific inputs included clinical validation readiness scores and cloud marketplace transaction velocity.
Material uncertainties—NVIDIA supply chain disruptions, FDA clearance timeline extensions, and divergent national AI governance framework evolution—sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Global Legaltech Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Artificial Intelligence in Business Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Global Computer Assisted Coding Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market