
 Cloud Calling Market | 2026-2036
Cloud Calling Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Calling Market Outlook
Platform licensing revenue is reconfiguring margin pools away from perpetual hardware sales toward recurring software subscriptions. Microsoft leverages its Teams ecosystem to anchor enterprise communication stacks, while Cisco sustains dominance through deep integration of WebEx with networking infrastructure. RingCentral competes aggressively on channel breadth, extending its partner network to capture mid-market transitions from on-premise systems.
Cloud calling delivers voice, video, and messaging services over internet protocol infrastructure rather than traditional circuit-switched telephone networks, utilizing session initiation protocol signaling and WebRTC for browser-based real-time communication without plugin dependencies. Its primary commercial purpose is to replace capital-intensive private branch exchange hardware with elastic, API-accessible communication platforms. Public cloud deployment leads volume adoption among SMEs seeking minimal upfront investment, while UCaaS technology captures the fastest expansion as organizations consolidate fragmented collaboration tools into unified stacks. Voice services remain the mature revenue baseline, though integration services now command the highest margin pools by embedding communication into CRM and ERP workflows.
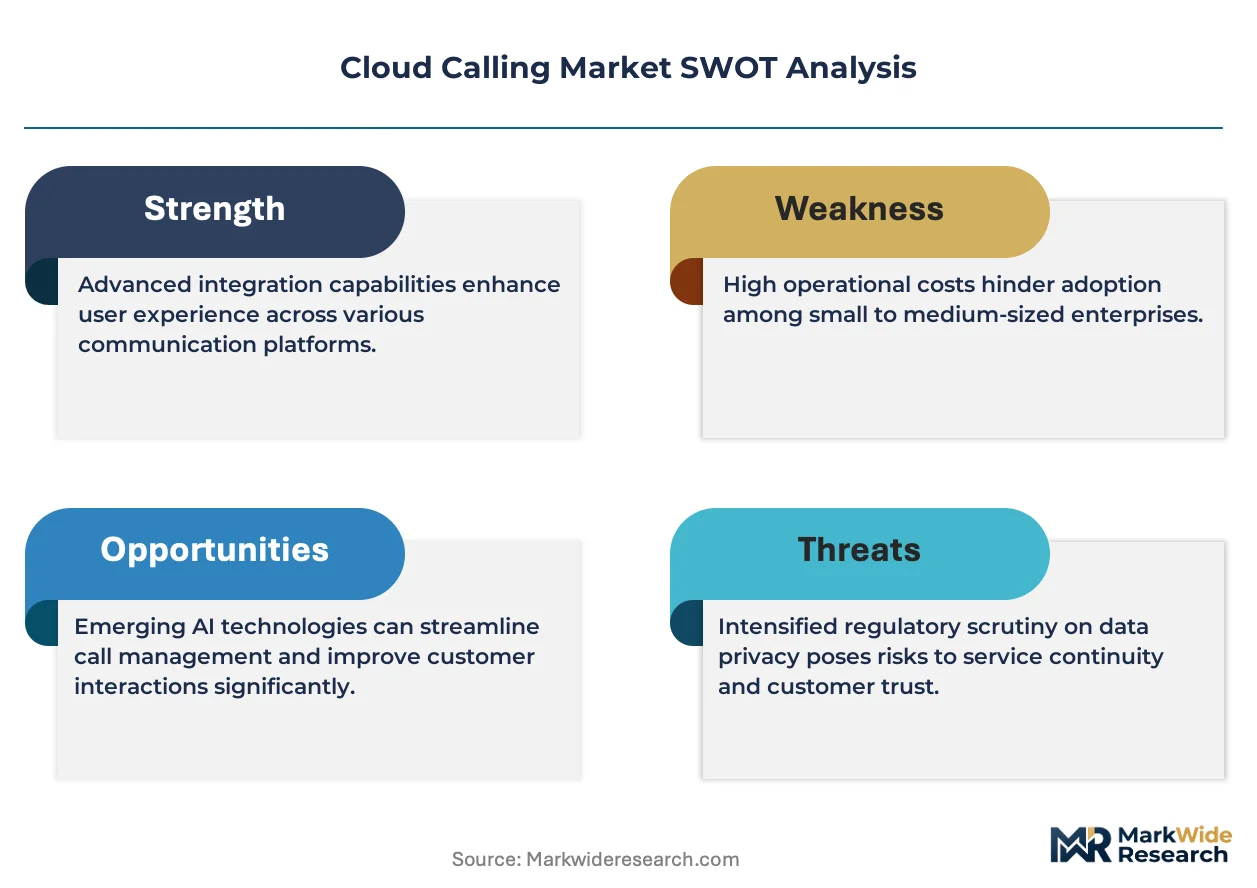
The FCC mandates emergency service location accuracy and net neutrality provisions that directly shape cloud calling provider architecture and service obligations. GDPR in Europe imposes strict data residency and consent frameworks on call recordings and metadata storage, restricting cross-border routing architectures. HIPAA in the United States governs how healthcare cloud calling platforms handle protected health information during telemedicine sessions. Stakeholders must monitor how diverging data sovereignty requirements fragment platform standardization and force region-specific infrastructure builds.
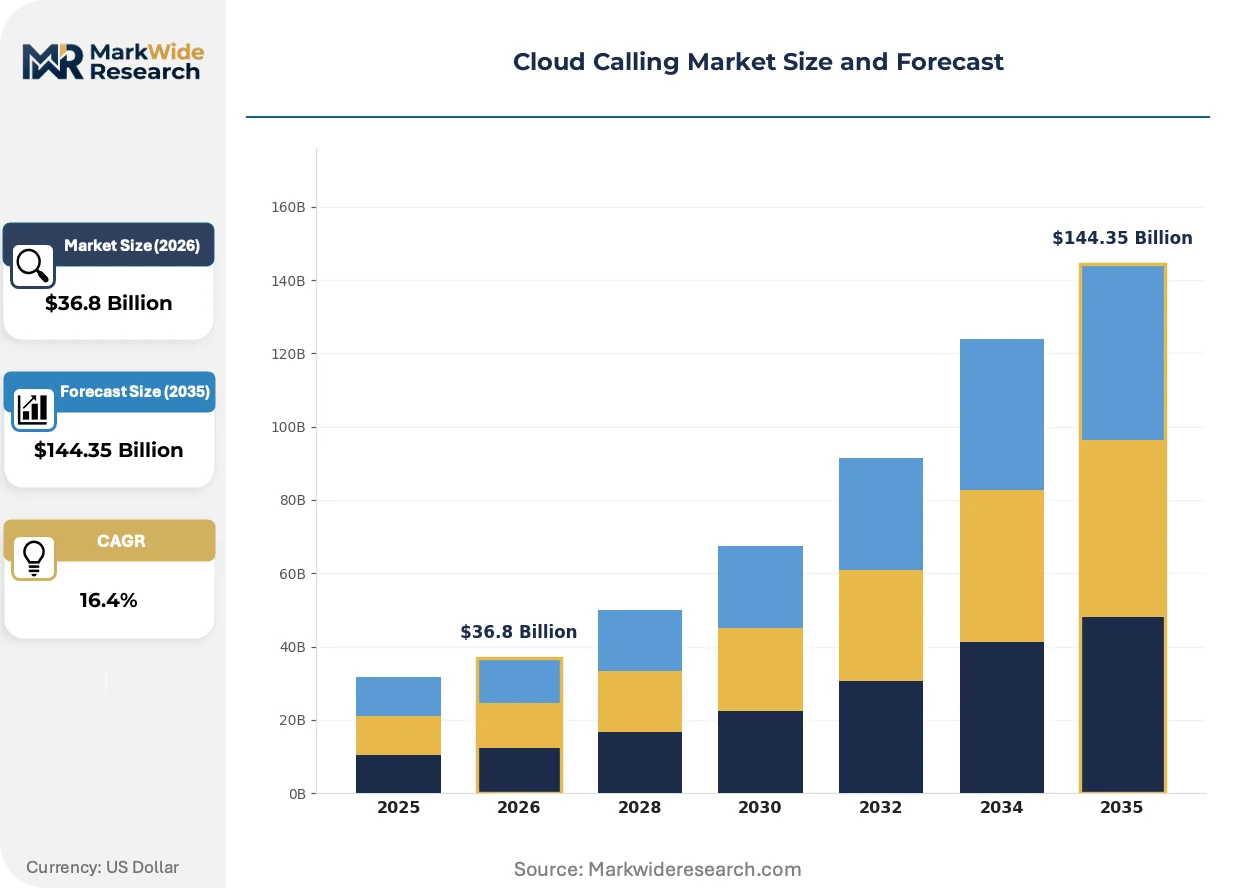
Market Dynamics
Enterprise migration from capital-intensive PBX hardware to elastic cloud-native platforms is compressing procurement cycles and redistributing margin pools toward recurring software subscriptions across the communication stack.
Growth Catalysts
- HIPAA-compliant telemedicine expansion:Healthcare providers deploy cloud calling to streamline patient-provider communication while meeting strict protected health information safeguards during remote consultations.
- WebRTC browser-native architecture:Elimination of plugin dependencies accelerates deployment velocity for mid-market enterprises seeking minimal IT overhead.
- FCC emergency calling mandates:Location accuracy requirements compel infrastructure investment that simultaneously elevates service reliability standards for all subscribers.
Market Restraints
- Cross-border data fragmentation:GDPR residency requirements restrict call recording architectures and force redundant infrastructure builds across European member states.
- Last-mile connectivity volatility:Quality-of-service guarantees remain contingent on broadband infrastructure unevenness, particularly in rural United States markets.
- Legacy system entrenchment:Sunk costs in on-premise PBX equipment extend replacement timelines for risk-averse institutional buyers.
Strategic Opportunities
- API-first communication embedding:Integration services command premium margins by embedding voice and video into CRM and ERP workflows.
- UCaaS consolidation demand:Organizations seek unified stacks replacing fragmented collaboration tools, creating whitespace for platform consolidation plays.
- Net neutrality architecture tailwinds:Evolving FCC service standards create compliance-driven upgrade cycles among established providers.
Industry Challenges
- SIP trunking expertise scarcity:Enterprises lack internal talent to manage session initiation protocol migrations and hybrid cloud configurations.
- Multi-vendor integration complexity:Interoperability gaps between cloud platforms and existing networking infrastructure prolong deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Calling Market |
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $144.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Technology: SIP, WebRTC, VoIP, UCaaS End User: Enterprises, SMEs, Call Centers, Non-Profits Service Type: Voice Services, Video Conferencing, Messaging, Integration Services |
| Companies Covered | Twilio Inc., RingCentral, Vonage Holdings Corp., Cisco, Microsoft, 8x8, Nextiva, Mitel Networks Corporation, Five9, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Calling Market Strategic Shifts
Real-time communication infrastructure is undergoing fundamental architectural transformation as browser-based protocols displace traditional telephony hardware and regulatory mandates reshape provider obligations.
WebRTC technology is digitizing voice and video delivery by enabling plugin-free browser communication through standardized JavaScript APIs. Healthcare providers and financial services firms adopt this architecture aggressively to reduce client friction. The technology is digitizing endpoint deployment economics, collapsing hardware provisioning from weeks to minutes.
The FCC continues refining emergency service location accuracy mandates that require cloud calling providers to transmit dispatchable address data with precise coordinate granularity. These obligations force architectural investments in geolocation databases and real-time routing verification. United States healthcare and education verticals face the steepest compliance ramps as they serve dispersed, mobile user populations.
Subscription-based procurement now dominates enterprise communication sourcing as buyers reject perpetual license models. Channel partners and direct sales teams unbundle professional services from platform fees to accelerate land-and-expand motions. Mid-market United States enterprises exhibit the fastest behavioral pivot, demanding month-to-month flexibility over multi-year hardware commitments.
Cloud Calling Market Segmentation
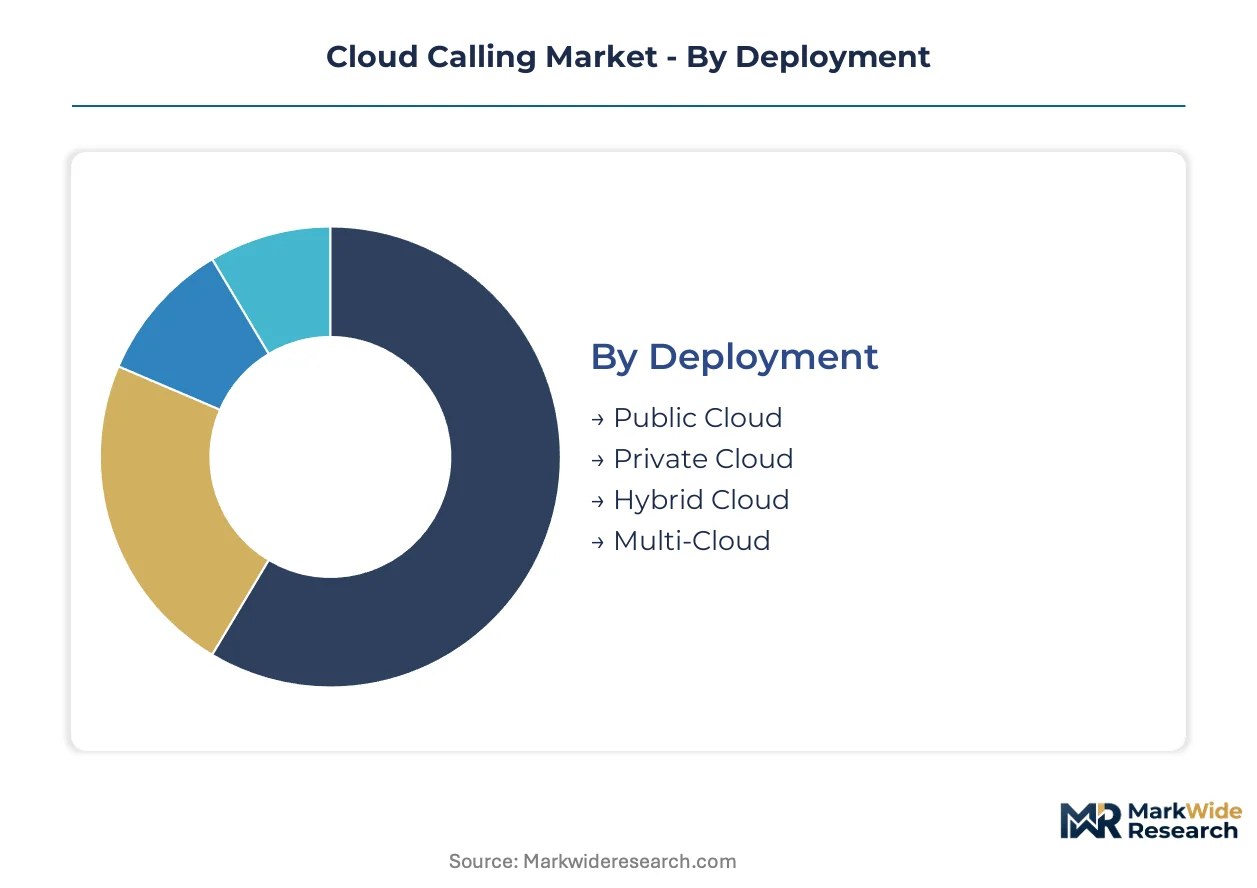
Cloud calling segmentation reveals distinct procurement patterns across infrastructure models, signaling protocols, and organizational scale. Deployment architecture determines capital intensity and compliance posture, while technology selection governs integration depth and user experience quality.
Deployment:
Use-case spectrum spans minimal-overhead startups to regulated institutions requiring sovereign data control.
- Public Cloud:Shared infrastructure delivers elastic capacity with zero hardware procurement. SMEs in the United States favor this model for month-to-month scalability without IT staffing expansion.
- Private Cloud:Dedicated tenant environments isolate workloads on single-organization infrastructure. Healthcare enterprises and financial institutions mandate this architecture for HIPAA and PCI-DSS compliance.
- Hybrid Cloud:Split workloads between on-premise systems and cloud burst capacity. Manufacturing firms deploy hybrid configurations to preserve legacy PBX investments while enabling remote worker connectivity.
- Multi-Cloud:Redundant distribution across AWS, Azure, and Google Cloud eliminates single-provider dependency. Large enterprises with distributed workforces adopt multi-cloud to negotiate pricing and ensure continuity.
The dominant share belongs to Public Cloud, while Hybrid Cloud is closing the gap fastest as enterprises seek migration pathways without wholesale replacement.
Technology:
Cost tier differentiation separates legacy protocol investments from browser-native modernization.
- SIP:Session Initiation Protocol remains the signaling backbone for carrier interconnection and PBX migration. Established enterprises with sunk infrastructure costs sustain SIP demand for trunking and interoperability.
- WebRTC:Browser-based real-time communication eliminates client software installation through standardized JavaScript APIs. Telemedicine platforms and customer service portals drive adoption for frictionless end-user access.
- VoIP:Voice-over-IP packet transmission underlies all cloud calling architectures. Residential and small business segments sustain VoIP volume through basic calling plans with minimal feature requirements.
- UCaaS:Unified Communications as a Service consolidates voice, video, messaging, and collaboration into single-stack subscriptions. Mid-market organizations seeking vendor consolidation are expanding UCaaS fastest.
UCaaS commands premium pricing tiers, while WebRTC is gaining share fastest among developer-embedded communication workflows.
End User:
Customer type determines feature complexity, integration requirements, and contract structure preferences.
- Enterprises:Multi-location organizations with 1,000+ employees demand API access, SSO integration, and custom analytics. These buyers negotiate multi-year contracts with professional services bundled for ERP and CRM embedding.
- SMEs:Small and mid-sized entities prioritize rapid deployment and predictable per-seat pricing. United States SMEs are migrating from legacy PBX fastest due to minimal capital reserves and distributed workforce pressures.
- Call Centers:High-volume voice operations require workforce management, quality monitoring, and predictive dialer integration. Outsourced customer service providers in India and the Philippines sustain concentrated demand for scalable agent licensing.
- Non-Profits:Budget-constrained organizations seek donated or discounted licensing through vendor philanthropy programs. Educational institutions and charitable foundations drive this segment with grant-funded technology refresh cycles.
Enterprises generate the largest revenue pool, while SMEs are expanding fastest as cloud-native platforms reduce minimum viable scale thresholds.
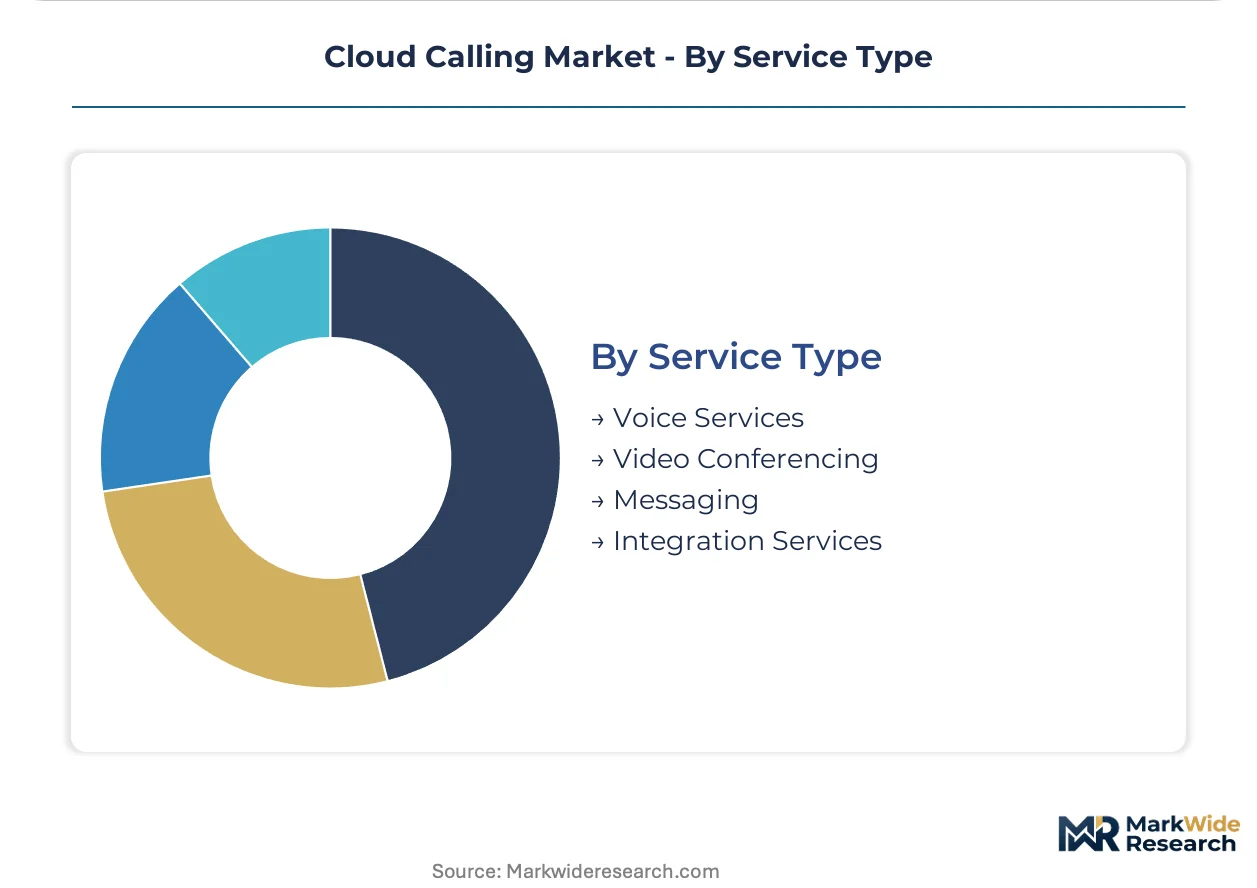
Service Type:
Margin concentration shifts from commoditized voice transport toward embedded integration value.
- Voice Services:PSTN replacement and toll-free numbering constitute the mature revenue baseline. Carriers compete on per-minute rates and number porting velocity, compressing margins toward utility economics.
- Video Conferencing:HD video rooms and webinar platforms command 40-60% premium over audio-only subscriptions. Healthcare telemedicine and legal deposition workflows sustain video demand despite meeting fatigue concerns.
- Messaging:SMS, team chat, and asynchronous collaboration tools integrate with voice for omnichannel continuity. Retail and logistics sectors deploy messaging for appointment reminders and delivery coordination.
- Integration Services:API development and workflow embedding into Salesforce, ServiceNow, and custom applications capture the highest margin pool. DevOps teams and system integrators drive this category as communication becomes programmable infrastructure.
Voice Services retains volume leadership, while Integration Services is climbing fastest as platform differentiation shifts from connectivity to contextual workflow embedding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Germany demonstrate the lowest price elasticity, absorbing premium UCaaS subscriptions for compliance-grade deployments, while SMEs in India prioritize per-seat cost minimization above feature depth. This demand-elasticity spectrum shapes regional vendor strategies and infrastructure investment priorities.
United States
Healthcare systems and financial institutions drive enterprise cloud calling procurement, with HIPAA-compliant telemedicine platforms expanding fastest in dispersed rural markets. The FCC mandates dispatchable location accuracy for emergency calls, forcing providers to rebuild geolocation databases. Silicon Valley and Seattle host the densest concentration of platform engineering talent, where Microsoft and Amazon Web Services anchor communication infrastructure development.
Germany
Automotive manufacturers and industrial machinery firms deploy private cloud calling for factory-floor integration with ERP systems. The BSI (Federal Office for Information Security) enforces strict data residency certifications that exclude non-EU infrastructure from sensitive deployments. Munich and Stuttgart industrial clusters demand hybrid architectures preserving on-premise PBX investments while enabling cloud burst capacity for remote engineering teams.
United Kingdom
Legal services and professional consulting firms sustain premium video conferencing demand despite post-pandemic meeting fatigue concerns. The Information Commissioner's Office enforces GDPR-derived call recording consent frameworks that complicate cross-border client engagements. London's financial district concentrates multi-cloud deployments across AWS, Azure, and Google Cloud to negotiate pricing and ensure regulatory continuity.
India
Business process outsourcing providers and IT services firms scale agent-licensed cloud calling for global customer support operations. TRAI (Telecom Regulatory Authority of India) governs VoIP interconnection tariffs and quality-of-service benchmarks for international call termination. Bangalore and Hyderabad technology parks concentrate mid-market UCaaS adoption as distributed workforce pressures accelerate legacy system replacement.
Japan
Manufacturing conglomerates and precision electronics firms integrate cloud calling with IoT-enabled production monitoring systems. METI (Ministry of Economy, Trade and Industry) promotes secure communication standards for critical infrastructure operators through industry-led certification programs. Tokyo-Osaka industrial corridors anchor private cloud deployments where data sovereignty requirements override cost considerations in vendor selection.
Cloud Calling Market Competitive Environment
Platform-native ecosystems and channel-centric specialists split the market into distinct competitive spheres with limited direct overlap. Microsoft leverages Office 365 tenant penetration to bundle communication services at scale, while Cisco sustains infrastructure-anchored relationships through networking hardware co-deployment. Pure-play UCaaS vendors compete on API accessibility and third-party integration breadth. Dominant competitive moves include strategic partnerships with CRM platforms and vertical-specific compliance certifications.
Within the ecosystem-anchored tier, Microsoft and Cisco exemplify divergent route-to-market strategies—Microsoft through software tenant expansion, Cisco through hardware-software convergence. RingCentral occupies a position representing channel-intensive distribution models. Among developer-platform specialists, Twilio anchors the API-first communication embedding archetype. These three companies collectively illustrate how competitive positioning stratifies across enterprise relationship depth versus developer ecosystem breadth.
| Leading Market Players |
|---|
| Twilio Inc. |
| RingCentral |
| Vonage Holdings Corp. |
| Cisco |
| Microsoft |
| 8x8 |
| Nextiva |
| Mitel Networks Corporation |
| Five9 |
| Others |
Value Chain & Pricing Dynamics
Hyperscaler data center concentration in the United States and Western Europe anchors infrastructure costs for cloud calling platforms, concentrating margin capture in software layers rather than raw compute provisioning. Platform providers compete on API accessibility and integration depth rather than transmission economics alone.
Pricing Analysis
Professional services and extended integration contracts drive lifetime value beyond base subscription fees. SaaS-tiered pricing stratifies across premium, standard, and economy tiers based on compliance certification level and API call volume entitlements. Cost compression in voice transport stems from carrier commoditization and WebRTC protocol standardization. SMEs exhibit highest price sensitivity, absorbing per-seat costs only below legacy PBX maintenance thresholds, while regulated healthcare and financial institutions accept premium tiers for HIPAA and PCI-DSS certification bundles.
Supply Chain Analysis
Extended payment terms from hyperscaler infrastructure providers and supply-chain finance facilities ease working capital pressure for platform vendors scaling multi-tenant deployments. Server hardware fabrication concentrates in Taiwan, South Korea, and China, while submarine cable infrastructure for transoceanic latency optimization draws from United States, United Kingdom, and Japan landing stations. Single-source vulnerability in specialized VoIP gateway chipsets creates procurement risk during semiconductor allocation cycles. Distribution runs through direct enterprise sales teams, value-added resellers, and telecommunications carrier partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud calling incumbents face substitution pressure from embedded communication features within productivity suites, requiring defensive architecture investments to preserve standalone platform relevance.
For Market Incumbents: Entrench API-first positioning by deepening Salesforce and ServiceNow integration certifications while accelerating WebRTC-native feature parity. Vertical integration into edge computing infrastructure reduces hyperscaler dependency and improves latency guarantees for emergency calling compliance. Threats from Microsoft Teams bundling demand differentiation through specialized healthcare and financial services compliance stacks. For New Entrants and Emerging Players: Mid-market manufacturing firms in Germany and Japan represent the most penetrable entry point, with hybrid cloud migration needs underserved by pure-play UCaaS vendors. Developer-centric API platforms for embedded communication in logistics and field service applications offer whitespace with lower incumbent saturation. Go-to-market through system integrator partnerships accelerates credibility without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward vertical-specific compliance specialists with established HIPAA or BSI certifications and channel relationships in healthcare or industrial automation. Long-term viability hinges on platform consolidation tolerance as enterprises reduce vendor fragmentation. Watch FCC net neutrality enforcement intensity as an inflection signal for infrastructure investment requirements and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Embedding voice and video into Salesforce and ServiceNow workflows captures premium integration services margins. |
| Compliance Certification Investment | HIPAA and BSI data residency certifications unlock regulated healthcare and German industrial procurement pipelines. |
| Hybrid Cloud Architecture Development | Split workload solutions preserve legacy PBX investments while enabling cloud burst capacity for remote teams. |
| Channel Partner Network Expansion | Value-added reseller relationships accelerate mid-market penetration without proportional direct sales headcount growth. |
| WebRTC-Native Feature Development | Browser-based communication eliminates client software friction and accelerates deployment velocity for telemedicine platforms. |
Study Parameters
A spread of perspectives from cloud platform engineering directors, enterprise IT procurement officers, telecommunications carrier partnership leads, and healthcare technology compliance officers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC filing databases, SEC 10-K infrastructure disclosure sections, hyperscaler capex reports, and GDPR enforcement case registries. Bottom-up deployment volume estimates triangulated against top-down addressable market sizing from enterprise communication spend benchmarks.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled across deployment architecture, organization size tier, vertical industry, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves and replacement cycle timing for legacy PBX estates. Industry-specific forecast inputs included FCC emergency calling mandate compliance deadlines and healthcare telemedicine reimbursement policy evolution.
Practitioners should monitor hyperscaler pricing volatility, net neutrality enforcement intensity, and cross-border data sovereignty rulings for early signals of forecast deviation. Macroeconomic contraction affecting enterprise software budgets, regulatory acceleration of encryption backdoor requirements, or breakthroughs in quantum-safe communication protocols would prompt revision of adoption trajectory assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Global Cloud Business Email Market
Cloud Computing
Cloud Database Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Automotive Cloud Based System Market
Cloud Computing
Public Cloud Application Infrastructure Services Market
Cloud Computing
Cloud Integration Software Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Global Server Virtualization Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
Cloud Continuum Market