
 India Automotive Advanced Driver Assistance Systems Market | 2026-2036
India Automotive Advanced Driver Assistance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Advanced Driver Assistance Systems Market Foresight
Software-defined feature subscriptions for highway assist and parking automation is pivoting how Tier-1 suppliers monetize ADAS beyond hardware sales. Robert Bosch GmbH leverages its Pune engineering center to localize radar fusion stacks for compact SUVs. Continental AG anchors its Chennai plant as the primary export hub for camera-based electronic control units serving ASEAN markets. DENSO Corporation competes through thermal-managed lidar modules designed for India's ambient temperature extremes.
Automotive Advanced Driver Assistance Systems integrate sensor fusion architectures combining millimeter-wave radar, CMOS cameras, and ultrasonic arrays with real-time decision algorithms to automate longitudinal and lateral vehicle control. The primary purpose spans collision mitigation, traffic jam piloting, and occupant monitoring across speed regimes from urban crawl to expressway cruise. Camera technology captures disproportionate engineering investment as Indian OEMs prioritize affordable computer-vision stacks over costly lidar for Level-2 autonomy. Adaptive Cruise Control dominates feature penetration in domestic passenger vehicles, while Automatic Emergency Braking draws regulatory tailwinds from impending mandatory fitment discussions.
Bharat NCAP protocols, AIS-140 telematics standards from the Automotive Research Association of India, and PLI scheme incentives for advanced automotive electronics collectively reshape supplier qualification criteria and localization timelines. The Ministry of Road Transport and Highways accelerates mandate consultations for autonomous emergency braking on new vehicle categories, compressing product development cycles for domestic Tier-1s. Stakeholders must monitor how state-level EV-ADAS bundling policies in Gujarat and Karnataka redirect procurement priorities away from standalone internal-combustion platforms.
Market Dynamics
Bharat NCAP safety mandates are compressing product development timelines as passenger vehicle OEMs scramble to integrate sensor fusion stacks across mid-tier model lines ahead of mandatory autonomous emergency braking consultations.
Growth Catalysts
- Bharat NCAP Protocols:Crash-test rating requirements from the Ministry of Road Transport and Highways are mandating ADAS fitment in mass-market passenger vehicles, creating immediate sensor procurement pull.
- PLI Scheme Incentives:Production-linked incentive structures for advanced automotive electronics are accelerating domestic manufacturing localization timelines for radar and camera modules.
- Maharashtra-Tamil Nadu Clusters:Concentrated automotive manufacturing ecosystems in these states anchor sensor assembly and software calibration capabilities, reducing supplier qualification friction.
Market Restraints
- Semiconductor Input Volatility:CMOS image sensor and radar chipset supply concentration in East Asian foundries exposes Tier-1s to allocation risk and price instability.
- Lidar Cost Structure:Thermal-managed lidar modules remain prohibitively expensive for compact SUV segments, capping penetration at premium vehicle tiers.
- AIS-140 Telematics Friction:Mandatory telematics hardware requirements from the Automotive Research Association of India divert engineering bandwidth from ADAS feature development.
Strategic Opportunities
- Gujarat-Karnataka EV-ADAS Bundling:State-level policy incentives linking electric vehicle subsidies to advanced safety feature fitment are redirecting procurement toward integrated platform development.
- Highway Assist Subscriptions:Software-defined monetization models for Level-2 automation features create recurring revenue streams beyond one-time hardware sales.
- Camera-Radar Fusion Convergence:Affordable computer-vision stacks combined with millimeter-wave radar are displacing lidar-dependent architectures in cost-sensitive segments.
Industry Challenges
- Sensor Fusion Engineering Gap:Real-time algorithm development for multi-modal radar-camera-ultrasonic integration outpaces available embedded software talent pools in domestic engineering centers.
- Bharat NCAP Certification Compression:Accelerated mandate timelines from the Ministry of Road Transport and Highways compress validation cycles for domestic Tier-1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Advanced Driver Assistance Systems Market |
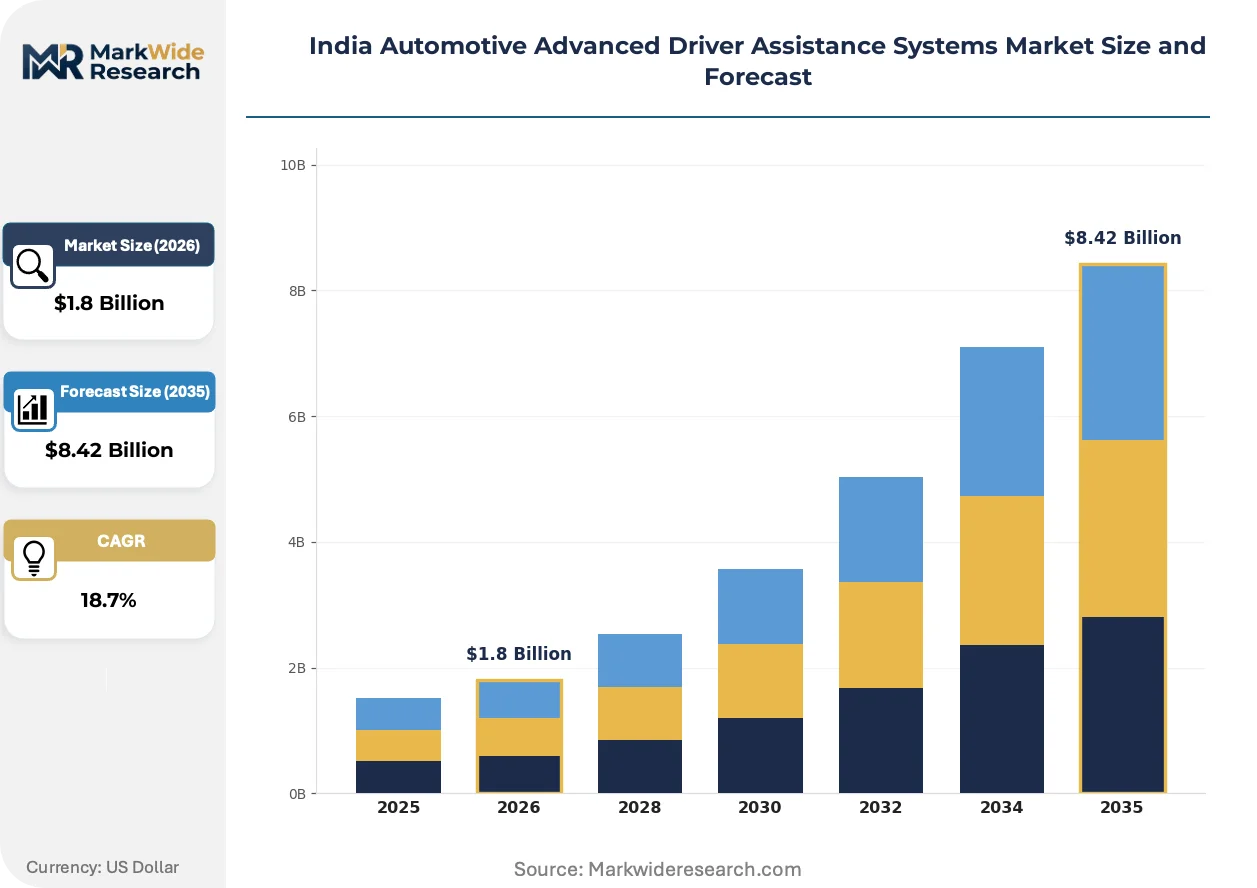
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Cruise Control, Lane Departure Warning, Automatic Emergency Braking, Blind Spot Detection End User: OEMs, Fleet Operators, Private Owners, Aftermarket Providers Technology: Radar, Lidar, Camera, Ultrasonic Feature: Navigation Assistance, Collision Avoidance, Parking Assistance, Driver Monitoring |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, ZF Friedrichshafen AG, Valeo SA, Magna International Inc, Autoliv Inc, Mobileye, Aptiv PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Advanced Driver Assistance Systems Market Shifts & Advancements
Sensor fusion architectures are actively displacing standalone safety modules as Indian OEMs prioritize integrated perception stacks capable of supporting both current Level-2 features and future autonomy roadmaps.
Camera-based electronic control units are expanding into compact SUV and mid-sedan segments as affordable CMOS sensor costs enable computer-vision deployment below premium price tiers. Maruti Suzuki and Hyundai Motor India are adopting these stacks for adaptive cruise control and lane-keeping assist. This expansion is compressing lidar's addressable market to flagship models while democratizing basic automation.
AIS-140 telematics standards from the Automotive Research Association of India are mandating GPS-enabled emergency response systems in all commercial vehicles and passenger transport categories. The regulation forces ADAS suppliers to integrate dual-purpose connectivity modules that satisfy both safety and tracking requirements. Bus and taxi fleet operators in Maharashtra face the steepest compliance curves as retrofit deadlines approach.
Fleet procurement of ADAS-equipped vehicles is rotating toward integrated safety-telecomatics bundles as logistics operators seek insurance premium reductions and driver monitoring capabilities. Large trucking consortia are specifying automatic emergency braking and driver drowsiness detection as standard fitment. This concentration is most visible in Tamil Nadu's commercial vehicle manufacturing corridor where Ashok Leyland and Daimler India anchor demand.
India Automotive Advanced Driver Assistance Systems Market Segmentation
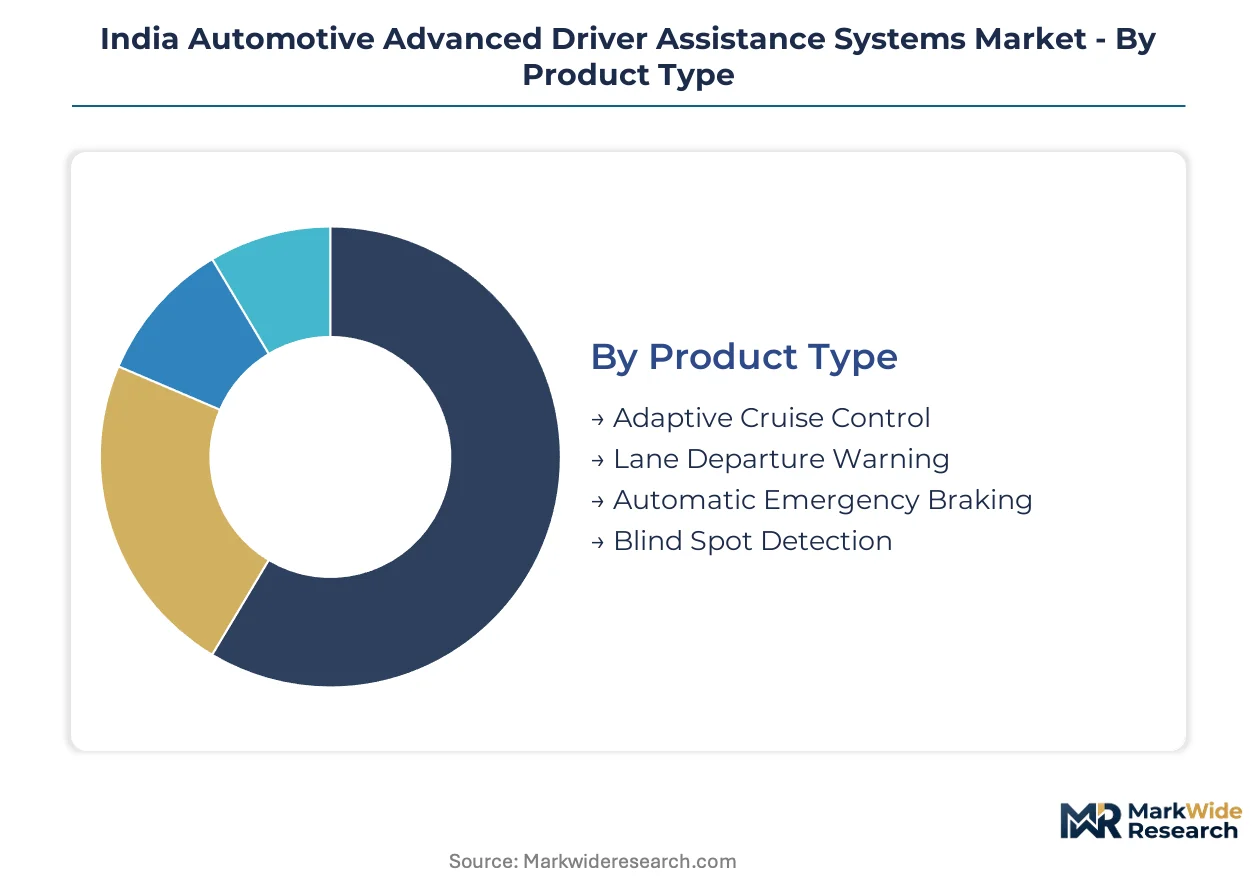
ADAS segmentation in India reflects how safety mandates cascade differently across vehicle price tiers and operational models. Understanding these splits reveals where Bharat NCAP pressure concentrates procurement pull versus where fleet economics or aftermarket retrofit create parallel demand channels.
Product Type:
Standalone warning systems dominate entry-level fitment while embedded control modules anchor mid-tier and premium integration strategies.
- Adaptive Cruise Control:Combines millimeter-wave radar with longitudinal control algorithms to maintain safe following distances. Maharashtra-based OEMs specify this as the baseline ADAS feature for compact SUVs targeting Bharat NCAP five-star ratings. PLI scheme incentives for radar module localization accelerate supplier qualification timelines.
- Automatic Emergency Braking:Fuses camera and radar inputs to execute autonomous braking when collision probability exceeds calibrated thresholds. Tamil Nadu passenger vehicle plants prioritize this for export-bound models facing ASEAN NCAP requirements. Impending Ministry of Road Transport and Highways mandate consultations compress development cycles for domestic Tier-1s.
- Lane Departure Warning:Computer-vision stack detecting unintentional lane drift through CMOS camera analysis.
- Blind Spot Detection:Ultrasonic or short-range radar arrays monitoring adjacent vehicle presence in mirror-occluded zones.
Adaptive Cruise Control leads volumes today; Automatic Emergency Braking is gaining share fastest.
End User:
Procurement authority fragments across entities with divergent compliance timelines and total-cost-of-ownership calculations.
- OEMs:Original equipment manufacturers integrate ADAS at factory level to satisfy Bharat NCAP crash-test protocols and differentiate mid-tier model lines. Maruti Suzuki and Hyundai Motor India specify sensor fusion stacks across compact SUV and mid-sedan segments.
- Fleet Operators:Logistics consortia and passenger transport fleets specify ADAS-telecomatics bundles to secure insurance premium reductions and satisfy AIS-140 tracking mandates. Tamil Nadu commercial vehicle corridors anchor concentrated demand from Ashok Leyland and Daimler India supply relationships.
- Private Owners:Individual vehicle purchasers accessing ADAS through factory fitment or authorized dealer upgrades.
- Aftermarket Providers:Independent installers retrofitting camera and ultrasonic systems to existing vehicle parc.
OEMs dominate current procurement; Fleet Operators are expanding most quickly.
Technology:
Cost-performance tradeoffs between sensing modalities determine which technologies penetrate which vehicle price tiers.
- Camera:CMOS-based computer vision capturing lane markings, traffic signs, and object classification through affordable sensor costs. Pune engineering centers localize image processing stacks for compact SUV deployment.
- Radar:Millimeter-wave arrays providing all-weather range and velocity data for adaptive cruise and emergency braking functions. Robert Bosch GmbH's Pune facility anchors domestic radar fusion development.
- Ultrasonic:Short-range acoustic sensing for parking assistance and low-speed obstacle detection.
- Lidar:Time-of-flight laser ranging offering high-resolution 3D point clouds; thermal-managed modules from DENSO Corporation address India's ambient temperature extremes.
Camera technology leads current fitment; Radar is climbing the fastest.
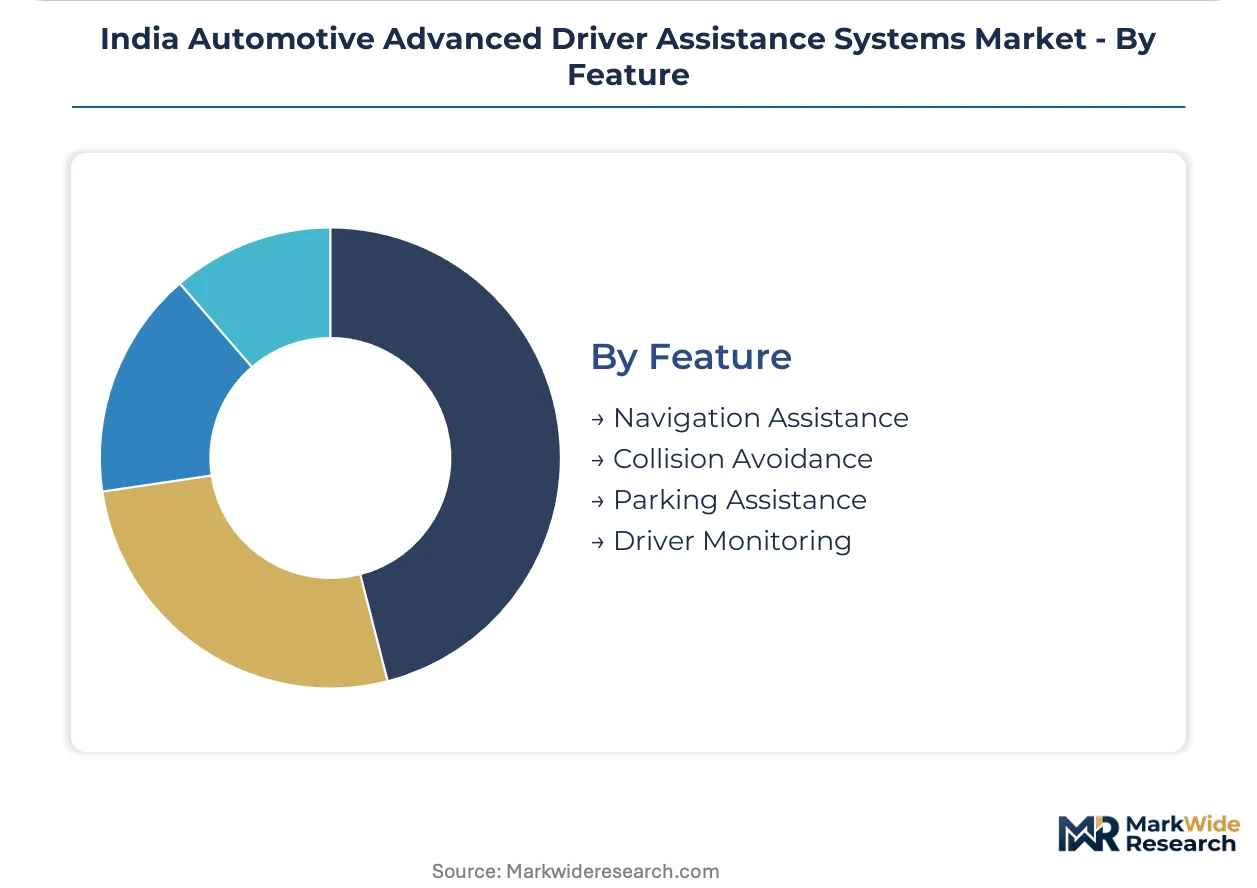
Feature:
Functional applications segment by whether they automate vehicle control or merely alert human operators.
- Collision Avoidance:Integrated sensor fusion executing autonomous braking and steering interventions. This feature category concentrates Bharat NCAP regulatory pressure and PLI scheme incentive eligibility.
- Navigation Assistance:GPS-augmented routing with real-time traffic integration and lane-level guidance.
- Parking Assistance:Automated steering and braking for parallel and perpendicular parking maneuvers.
- Driver Monitoring:In-cabin cameras detecting drowsiness, distraction, or medical emergency states.
Collision Avoidance leads feature penetration; Driver Monitoring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's ADAS deployment trajectory diverges sharply from China's state-orchestrated push, with state-level incentives and Bharat NCAP mandates driving heterogeneous adoption across domestic manufacturing clusters rather than centralized planning.
Maharashtra
Passenger vehicle OEMs concentrate sensor fusion procurement in Pune and Mumbai corridors to satisfy Bharat NCAP five-star targets for compact SUVs. The state's PLI scheme implementation for advanced automotive electronics compresses localization timelines for radar module assembly. Engineering centers in Pune anchor software calibration capabilities for camera-radar fusion stacks serving domestic and export-bound production.
Tamil Nadu
Commercial vehicle manufacturing corridors around Chennai generate concentrated demand for automatic emergency braking and driver monitoring systems from fleet operators. AIS-140 telematics mandates from the Automotive Research Association of India force dual-purpose module integration for bus and taxi consortia. Ashok Leyland and Daimler India supply relationships anchor sensor procurement volumes in this southern cluster.
Gujarat
State-level EV-ADAS bundling policies redirect procurement toward integrated electric platforms with advanced safety feature fitment. The Gujarat government's electric vehicle subsidy linkage to ADAS penetration accelerates Tier-1 supplier qualification for camera-based electronic control units. Automotive manufacturing zones in Sanand and Halol concentrate sensor assembly for mid-tier passenger vehicle lines.
Karnataka
Bengaluru's software ecosystem feeds embedded algorithm development for real-time sensor fusion, though hardware assembly remains limited. State electric vehicle policies mirror Gujarat's bundling approach, linking subsidy eligibility to Level-2 automation feature inclusion. The corridor between Bengaluru and Hosur hosts emerging calibration facilities for ultrasonic and camera modules.
Haryana
Delhi-NCR proximity positions Manesar and Gurgaon manufacturing zones as aftermarket retrofit hubs for camera and ultrasonic systems. Fleet operators in the national capital region specify ADAS-telecomatics bundles to satisfy insurance premium reduction criteria and impending mandate consultations. The cluster serves as a distribution node for Tier-1 suppliers targeting northern India commercial vehicle parc.
India Automotive Advanced Driver Assistance Systems Market Competitive Landscape
Top-tier vendors anchor premium-tier radar and camera fusion development, while mid-tier specialists compete on localized cost structures for compact SUV fitment. The supplier base organizes around three strategic archetypes: German-Japanese conglomerates with integrated sensor-to-software stacks, diversified automotive electronics houses with regional manufacturing footprints, and vision-system specialists licensing perception algorithms. Competitive moves concentrate on capacity expansion in Maharashtra-Tamil Nadu corridors and technology licensing partnerships to bridge sensor fusion engineering gaps.
Within the integrated conglomerate tier, Robert Bosch GmbH and Continental AG exemplify archetypes combining hardware manufacturing with localized software development. DENSO Corporation occupies a position representing Japanese thermal-management specialization adapted to Indian ambient conditions. These three entities anchor competitive dynamics through divergent approaches to radar fusion, camera-based control units, and lidar module design for cost-sensitive segments.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| ZF Friedrichshafen AG |
| Valeo SA |
| Magna International Inc |
| Autoliv Inc |
| Mobileye |
| Aptiv PLC |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between Bharat NCAP five-star compliant sensor fusion stacks and entry-level warning systems manifests in divergent pricing architectures and procurement network configurations across Maharashtra and Tamil Nadu manufacturing corridors. Premium-tier radar-camera fusion modules command sustained margins through localized software calibration capabilities, while commodity ultrasonic parking sensors face cost compression from unorganized aftermarket channels.
Pricing Analysis
Capacity additions in Maharashtra and Tamil Nadu are reshaping price floors for radar and camera modules as PLI scheme beneficiaries expand domestic assembly footprints. Three-tier pricing structure across premium, standard, and economy levels segments by sensor modality sophistication, with camera-radar fusion carrying brand premiums against standalone ultrasonic alternatives. Cost compression in economy-tier parking assistance stems from unorganized aftermarket import substitution. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership calculations, while premium passenger vehicle OEMs prioritize certification compliance over unit economics.
Supply Chain Analysis
Freight cost escalation from East Asian semiconductor hubs intensifies working capital pressure on Tier-1 suppliers managing radar chipset and CMOS image sensor inventories. Manufacturing concentration in Taiwan, South Korea, and Japan anchors sensor component supply, with domestic assembly in Pune and Chennai reducing finished module logistics exposure. Critical dependencies span silicon wafers, specialized optical glass, and automotive-grade microcontroller units. Single-source vulnerability in advanced node semiconductor fabrication represents structural supply chain risk. Distribution runs through OEM direct procurement contracts and authorized Tier-1 supplier networks serving aftermarket retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
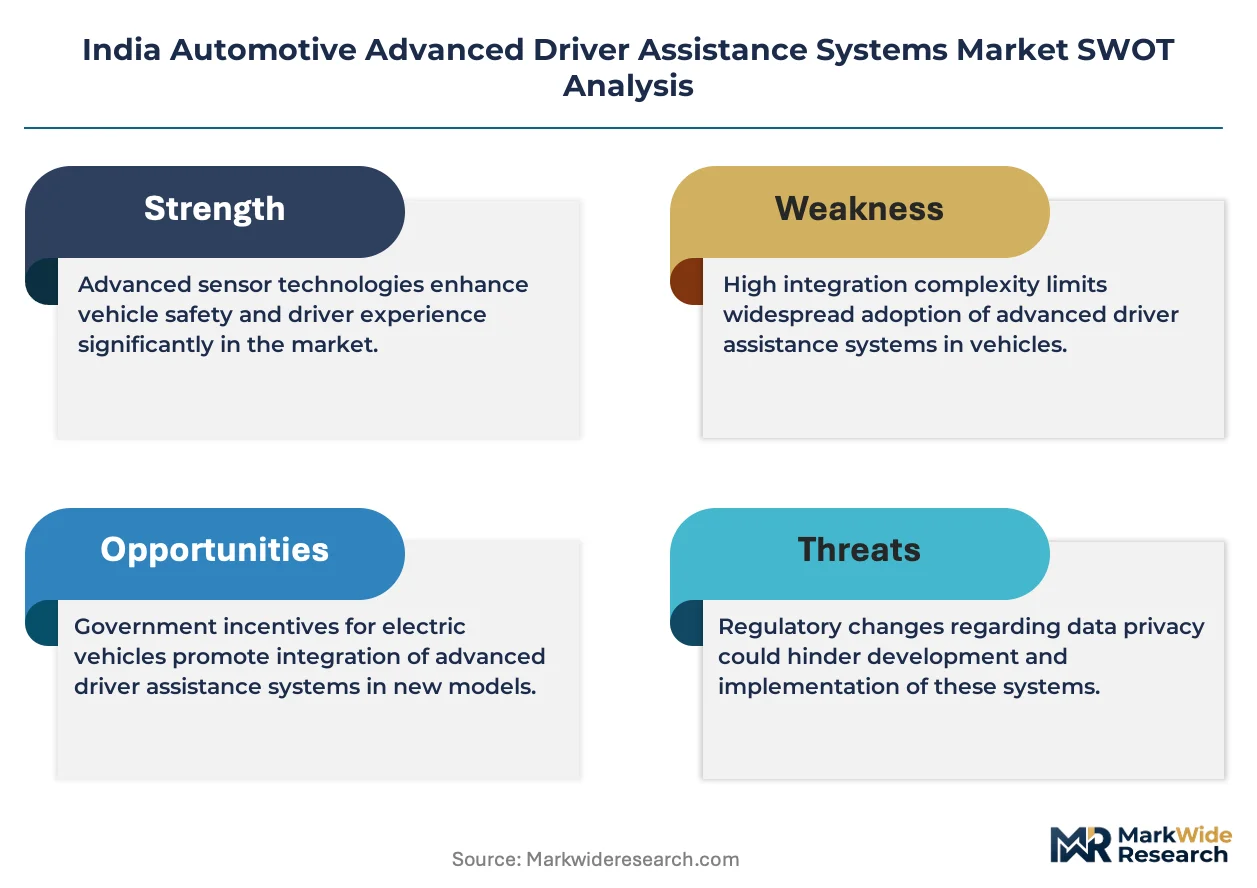
India Automotive Advanced Driver Assistance Systems Market operates as a stable compounder underpinned by regulatory tailwinds from Bharat NCAP mandate expansion and PLI scheme localization incentives that sustain procurement pull across vehicle price tiers.
For Market Incumbents: Deepen backward integration into radar module assembly and camera calibration software stacks to defend margin position against emerging domestic Tier-1 challengers. Prioritize certification investment for Bharat NCAP five-star compliance ahead of Ministry of Road Transport and Highways mandate consultations. Anchor capacity expansion in Maharashtra-Tamil Nadu corridors to capture PLI scheme benefits and reduce logistics cost exposure. For New Entrants and Emerging Players: Fleet operator procurement channels offer the most penetrable entry vector given AIS-140 telematics bundling requirements and insurance premium reduction specifications. Target commercial vehicle corridors in Tamil Nadu and Haryana where Ashok Leyland and Daimler India supply relationships concentrate demand. Pursue white-label sensor fusion module partnerships with domestic engineering centers lacking hardware manufacturing capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where sensor fusion engineering talent scarcity intersects with accelerated Bharat NCAP certification timelines compressing product development cycles. Long-term viability favors vertically integrated suppliers combining hardware manufacturing with localized software calibration capabilities. Monitor state-level EV-ADAS bundling policy expansion in Gujarat and Karnataka as inflection indicator for integrated platform procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Radar-Camera Fusion Stack Localization | PLI scheme incentives accelerate domestic assembly qualification for Bharat NCAP compliance. |
| Software-Defined Feature Subscription Launch | Highway assist monetization creates recurring revenue beyond one-time hardware sales. |
| Thermal-Managed Lidar Module Development | DENSO Corporation's ambient temperature engineering addresses India's climatic extremes. |
| Fleet Telematics-ADAS Bundle Integration | AIS-140 mandate compliance opens commercial vehicle procurement channel expansion. |
| Pune-Chennai Engineering Center Expansion | Sensor calibration capabilities reduce supplier qualification friction for OEM platform teams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operator specification managers with secondary validation from vehicle production databases, IHS Markit registration data, Ministry of Road Transport and Highways mandate consultation documents, and Automotive Research Association of India technical standards. Bottom-up sensor shipment modeling and top-down vehicle fitment penetration estimates were triangulated against PLI scheme beneficiary disclosures.
Segment-weighting approaches distributed value and volume projections across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions throughout the forecast period. CAGRs were derived from fitted penetration curves calibrated to Bharat NCAP timeline assumptions and PLI scheme localization trajectories. Industry-specific forecast inputs incorporated semiconductor allocation volatility indices and state-level EV-ADAS bundling policy adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply normalization, Bharat NCAP mandate acceleration, and East Asian foundry capacity expansion. Forecasts reflect documented assumptions about regulatory timeline adherence and PLI scheme continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
India Autonomous Navigation Market
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
Robotaxi Market
Autonomous Vehicles
Canada Autonomous Navigation Market