
 Adaptive Cruise Control (ACC) System Market | 2026-2036
Adaptive Cruise Control (ACC) System Market Size, Share, and Industry Trends Forecast 2026-2036
Adaptive Cruise Control (ACC) System Market Analysis
Fleet operators are collapsing the traditional OEM-centric procurement model for adaptive cruise control systems. Robert Bosch GmbH leverages its radar manufacturing scale to anchor supply contracts with European commercial vehicle builders. Denso Corporation competes through tight integration with Japanese automakers, while Aptiv PLC differentiates via camera-lidar fusion architectures for premium passenger segments.
Adaptive Cruise Control systems modulate vehicle speed autonomously through radar, lidar, or camera sensor fusion to maintain safe following distances without driver throttle input. Operating thresholds typically span 0 to 200 km/h with deceleration authority up to full emergency braking, serving both collision avoidance and traffic flow optimization objectives. Radar-based ACC still dominates unit volumes due to cost curves and all-weather reliability, though predictive ACC is expanding fastest as machine learning enables anticipatory braking beyond immediate obstacle detection. OEM fitment captures the largest revenue pool, while aftermarket providers occupy a narrower niche concentrated in retrofitting commercial fleets.
NHTSA mandates automatic emergency braking on new light vehicles in the United States, while Euro NCAP scoring protocols in Europe reward advanced ACC functionality with top-tier safety ratings. Japan's Ministry of Land, Infrastructure, Transport and Tourism aligns type approval standards with UNECE regulations, creating transnational compliance pressure for sensor harmonization. Stakeholders must monitor whether camera-dominant architectures achieve parity with radar systems under adverse weather conditions before committing platform roadmaps.
Market Dynamics
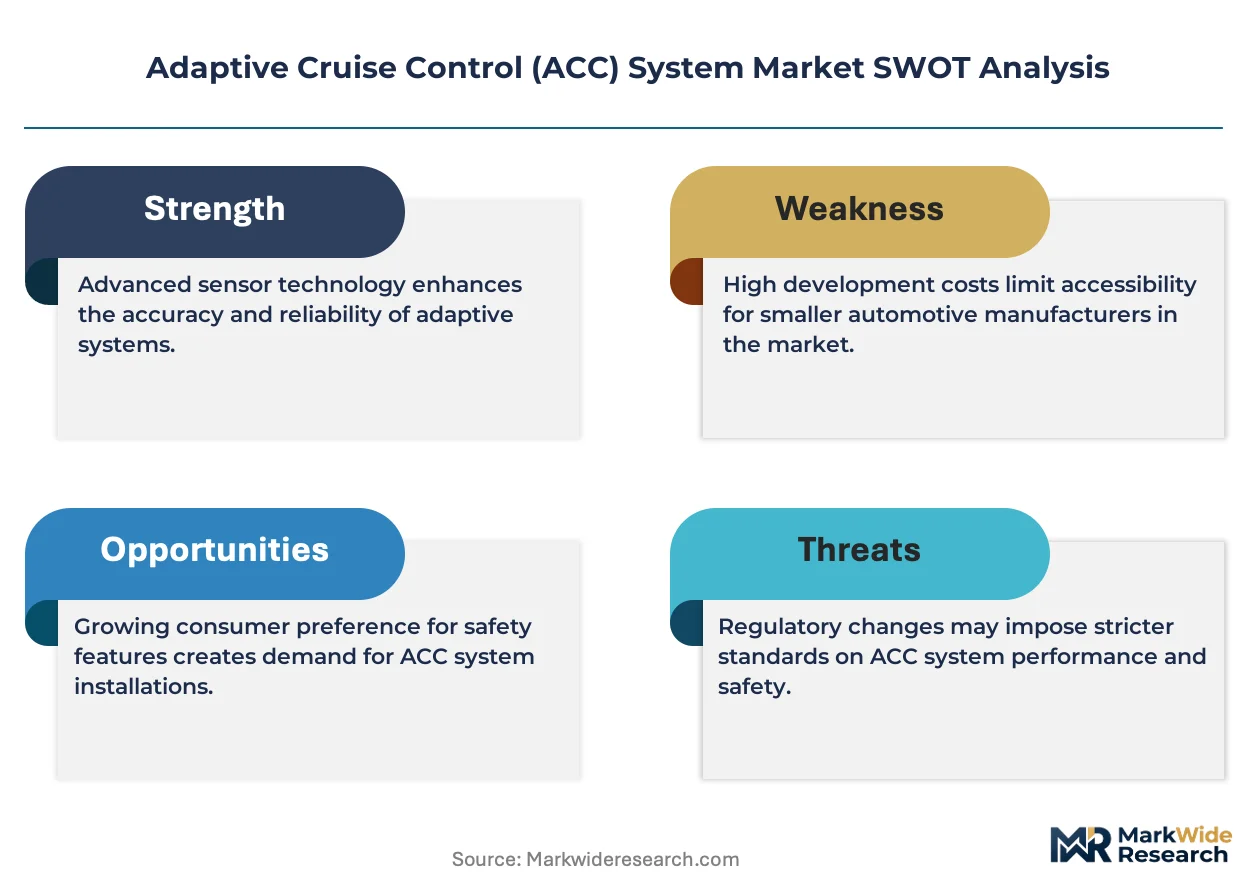
Predictive ACC architectures are forcing a platform split between radar-dominant and camera-lidar fusion approaches, with Tier-1 suppliers restructuring R&D allocation around machine-learning inference capabilities rather than legacy sensor hardware.
Growth Catalysts
- Euro NCAP safety scoring:Top-tier ratings now require advanced ACC functionality, compelling OEMs to standardize fitment across vehicle classes to maintain brand positioning in European showrooms.
- Commercial fleet telematics integration:Fleet operators in Germany and Japan are bundling predictive ACC with route optimization software, creating procurement pull-through from logistics end-users.
- Sensor fusion cost curves:Camera-lidar module prices are compressing faster than radar alternatives, enabling mid-market passenger vehicles to adopt previously premium-only ACC configurations.
Market Restraints
- Semiconductor input volatility:Radar MMIC and lidar ASIC supply remains concentrated among Taiwanese and South Korean foundries, exposing ACC module pricing to foundry capacity constraints.
- Adverse weather performance gaps:Camera-dominant architectures suffer degradation below 50-meter detection reliability in heavy precipitation, limiting full-radar substitution in Nordic and Alpine markets.
- UNECE type approval complexity:Cross-border harmonization gaps between Japanese MLIT standards and EU regulatory frameworks force redundant certification cycles for global platform vehicles.
Strategic Opportunities
- Aftermarket commercial retrofit:US long-haul trucking fleets represent underpenetrated demand for radar-based ACC add-ons, bypassing OEM captive supply through independent installer networks.
- AI Act compliance services:European ACC suppliers can monetize algorithmic transparency documentation and bias auditing as value-added offerings alongside hardware sales.
- V2X convergence:Integration of ACC with C-V2X roadside units enables anticipatory braking beyond sensor line-of-sight, opening urban corridor deployment in German smart highway pilots.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering for ISO 26262 ASIL-D compliance requires specialized expertise concentrated among German and Japanese automotive suppliers, constraining new entrant scaling.
- Legacy vehicle integration friction:Retrofitting ACC into pre-CAN-bus vehicle architectures demands bespoke gateway electronics, fragmenting aftermarket product economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adaptive Cruise Control (ACC) System Market |
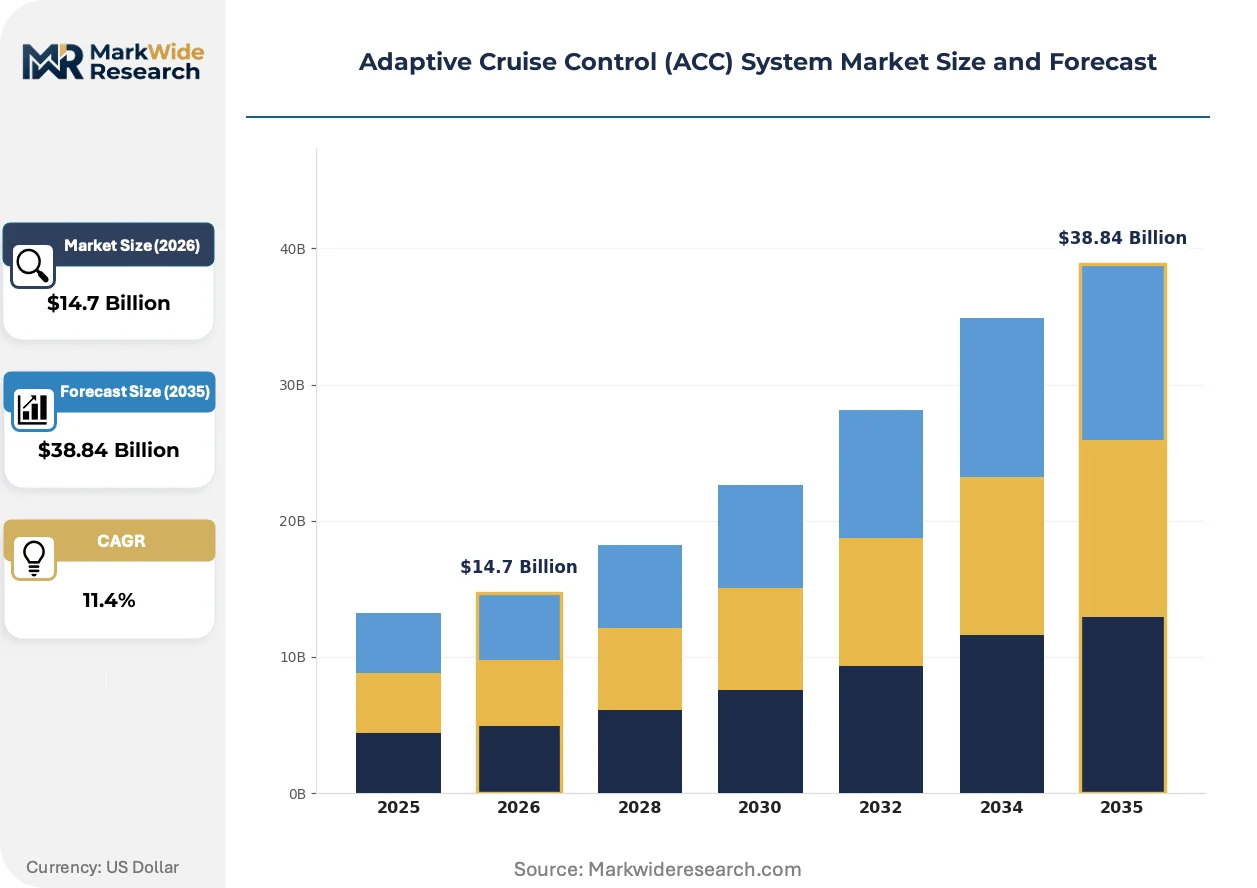
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard ACC, Dynamic ACC, Predictive ACC, Radar-based ACC Technology: Radar, Lidar, Camera, Ultrasonic End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Feature: Automatic Braking, Lane Keeping, Speed Regulation, Distance Control |
| Companies Covered | ZF Friedrichshafen AG, Magna International Inc., Robert Bosch GmbH, Valeo SA, Hyundai Mobis, Continental AG, Autoliv Inc., Aptiv PLC, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptive Cruise Control (ACC) System Market Emerging Trajectories
Machine-learning inference at the sensor edge is collapsing the traditional separation between perception and control layers, enabling anticipatory braking decisions that anticipate traffic pattern changes rather than reacting to immediate obstacles.
Camera-lidar fusion architectures are bifurcating the ACC supplier base into two distinct competency camps. Premium passenger OEMs in Germany and Japan are consolidating procurement around multi-sensor suites with redundant perception paths, while volume manufacturers in the United States are optimizing single-sensor radar configurations to preserve margin. This technical split is compressing mid-tier suppliers lacking depth in either pure-play radar or fused perception software.
NHTSA automatic emergency braking mandates for US light vehicles are accelerating ACC module standardization across OEM platform strategies. The regulation's phased implementation through 2029 is forcing Tier-1 suppliers to reallocate engineering resources from premium feature development to cost-optimized base-system compliance. Entry-level passenger segments face the steepest integration timeline compression as OEMs race to avoid federal penalties.
Fleet procurement departments are consolidating vendor relationships around integrated telematics-ACC contracts rather than discrete hardware purchases. US commercial vehicle lessors now specify predictive maintenance data streams as standard contract terms, displacing traditional spot-buy arrangements. This behavioral shift is most visible in German freight corridors where logistics operators demand ACC performance telemetry feed directly into dispatch optimization systems.
Adaptive Cruise Control (ACC) System Market Segmentation
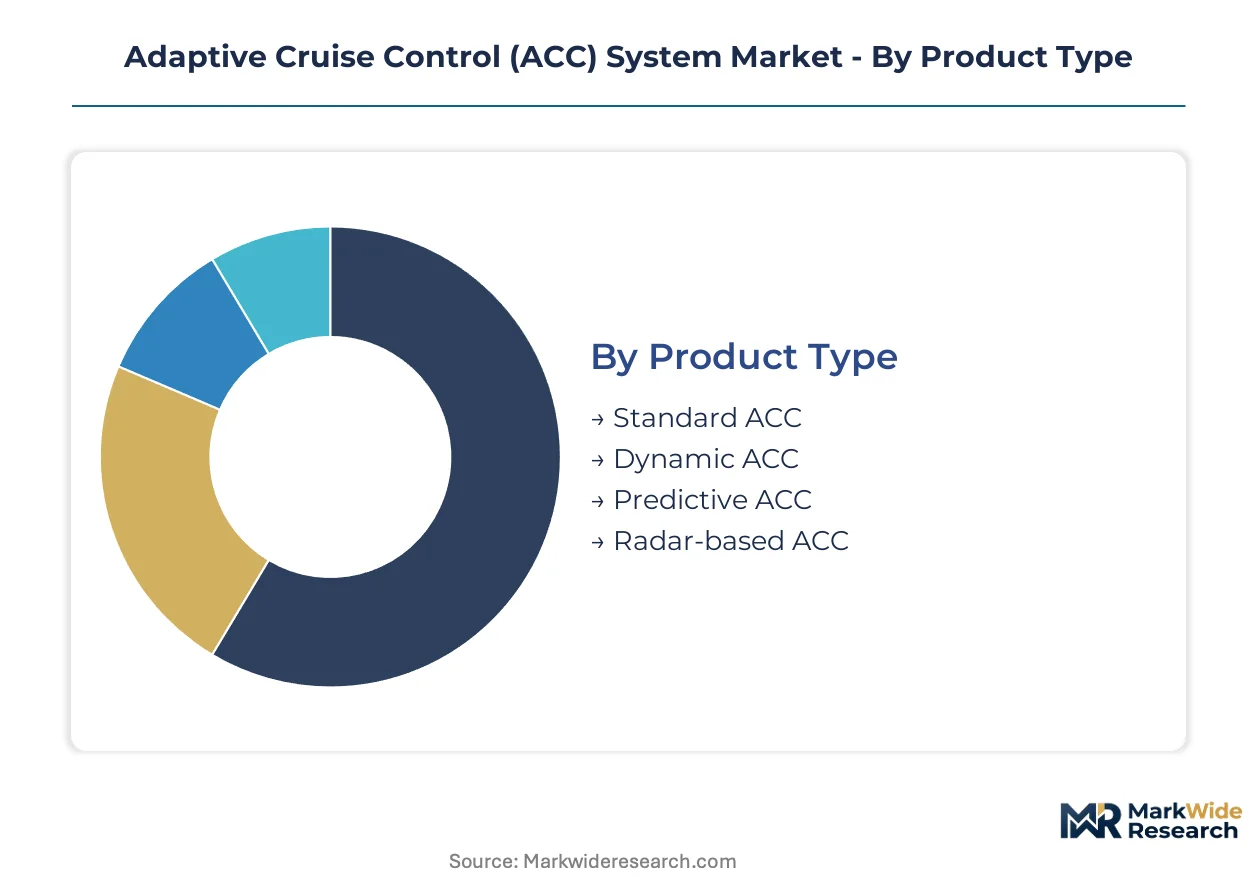
ACC system segmentation reveals how regulatory pressure and sensor economics split procurement strategies across vehicle classes. Tier-1 suppliers must align platform roadmaps with distinct compliance thresholds and cost-performance trade-offs in each category.
Product Type:
NHTSA mandates and Euro NCAP scoring protocols create tiered fitment obligations that reshape demand across ACC variants.
- Predictive ACC:Machine-learning algorithms enable anticipatory braking beyond immediate obstacle detection, with German freight corridors and Japanese logistics hubs driving fleet procurement. Euro NCAP's emphasis on advanced safety functionality accelerates standardization in premium European passenger segments.
- Radar-based ACC:Dominates unit volumes through all-weather reliability and compressed cost curves, serving Nordic and Alpine markets where camera systems degrade below 50-meter detection thresholds. NHTSA's automatic emergency braking rules reinforce radar's position in US base-system compliance.
- Standard ACC:Maintains following distance through basic radar or camera input without predictive capabilities, satisfying entry-level fitment requirements in cost-sensitive vehicle classes.
- Dynamic ACC:Adjusts speed parameters based on real-time traffic flow data, gaining traction in urban corridor deployments with V2X infrastructure integration.
Radar-based ACC handles the majority of throughput; Predictive ACC is expanding most quickly on share.
Technology:
Cost tier differentiation separates premium multi-sensor suites from single-sensor configurations optimized for margin preservation.
- Radar:Millimeter-wave arrays deliver consistent performance across precipitation and lighting conditions, anchoring volume production for US and European OEM platform strategies. Taiwanese and South Korean foundry concentration for MMIC components exposes pricing to semiconductor capacity constraints.
- Camera:Computer-vision architectures achieve cost parity below lidar alternatives, enabling mid-market passenger vehicle adoption previously restricted to premium segments. Heavy precipitation degradation limits full substitution in adverse-climate geographies.
- Lidar:Provides centimeter-level ranging accuracy for redundant perception paths in German and Japanese premium OEM specifications.
- Ultrasonic:Supports low-speed parking-adjacent functions rather than highway-speed ACC deployment.
Radar captures the dominant installation base; Camera-lidar fusion commands the steepest expansion trajectory.
End User:
Customer type determines whether procurement flows through captive OEM supply or independent aftermarket channels.
- OEMs:Integrate ACC modules at platform design phase, with NHTSA's phased mandate through 2029 compressing engineering timelines for cost-optimized base-system compliance. Standardized fitment across vehicle classes protects brand positioning in safety-scoring jurisdictions.
- Fleet Operators:Bundle predictive ACC with route optimization software in Germany and Japan, specifying telemetry feeds into dispatch systems as standard contract terms.
- Aftermarket Providers:Serve retrofit demand in US long-haul trucking through independent installer networks, bypassing OEM captive supply.
- Vehicle Assemblers:Coordinate Tier-1 module integration for regional production footprints.
OEMs absorb the largest revenue pool; Fleet operators are gaining procurement leverage fastest.
Feature:
Functional maturity separates regulatory-mandated capabilities from discretionary premium additions.
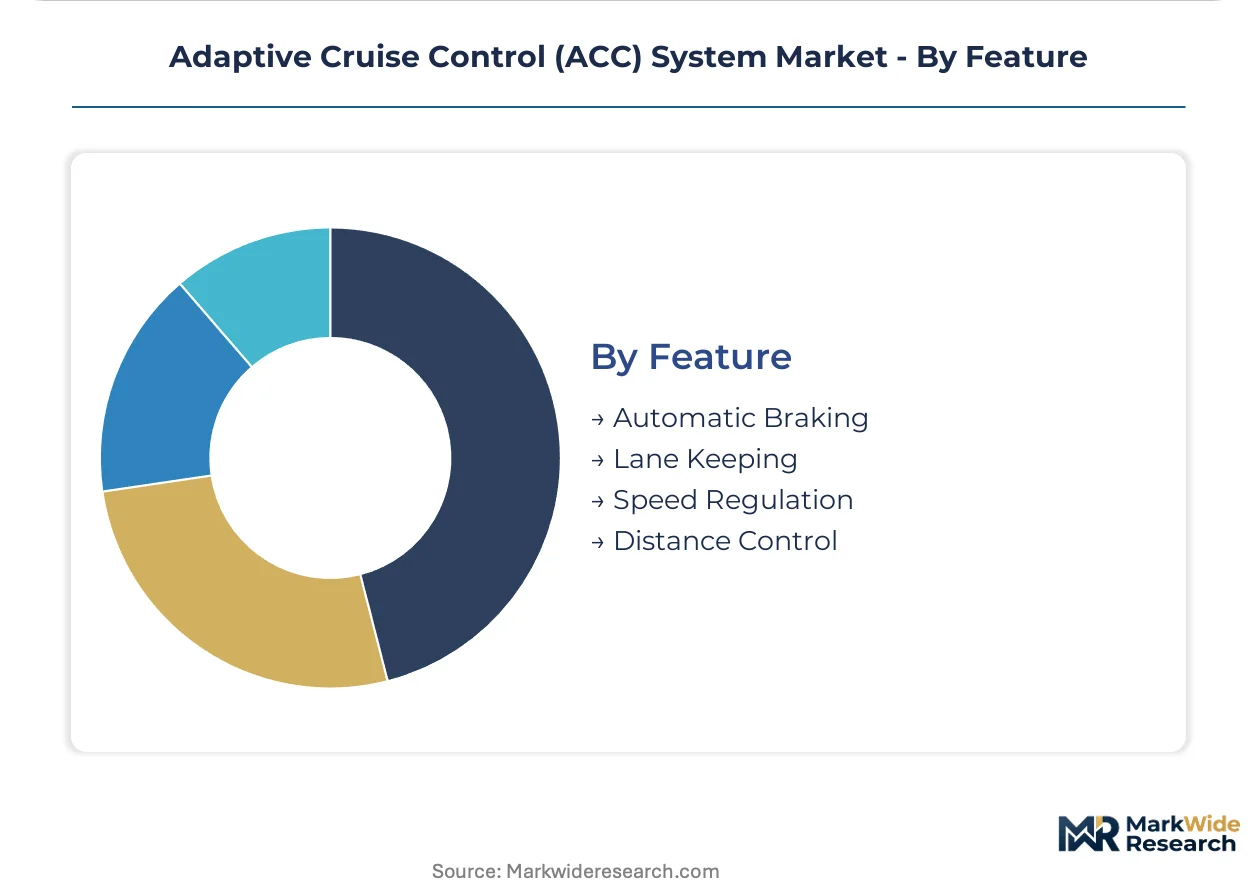
- Automatic Braking:NHTSA mandates this capability for new US light vehicles, forcing Tier-1 resource reallocation from premium feature development to compliance-focused engineering. Euro NCAP scoring rewards integration with top-tier safety ratings.
- Distance Control:Core ACC functionality maintaining safe following intervals through sensor fusion, required across all regulatory jurisdictions.
- Speed Regulation:Adjusts vehicle velocity to posted limits or driver-set parameters without throttle input.
- Lane Keeping:Adjacent driver-assistance feature often bundled with ACC in integrated ADAS packages.
Automatic Braking anchors regulatory compliance; Distance Control represents the foundational capability across all product tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German Tier-1 suppliers anchor radar module production for European OEM platforms. Japanese sensor manufacturers concentrate lidar fusion development around Nagoya and Tokyo industrial corridors. US regulatory mandates through NHTSA compress engineering timelines for Detroit-based automakers.
United States
Long-haul trucking fleets in Texas and California drive aftermarket retrofit demand for radar-based ACC add-ons. NHTSA's automatic emergency braking mandate phases through 2029, forcing Tier-1 suppliers to reallocate engineering resources toward cost-optimized base-system compliance. Detroit's automotive corridor accelerates platform standardization across entry-level passenger segments to avoid federal penalties.
Germany
Premium OEMs in Bavaria and Baden-Württemberg consolidate procurement around multi-sensor camera-lidar fusion suites. Euro NCAP safety scoring protocols reward advanced ACC functionality with top-tier ratings, compelling standardized fitment across vehicle classes. Stuttgart's supplier cluster advances predictive ACC algorithms for anticipatory braking in dense Autobahn traffic conditions.
Japan
Logistics operators in the Kanto and Kansai regions bundle predictive ACC with route optimization software. MLIT aligns type approval standards with UNECE regulations, creating transnational compliance pressure for sensor harmonization. Nagoya's automotive belt tightens integration between Denso and domestic OEMs for machine-learning inference capabilities.
South Korea
Hyundai-Kia's integrated supply chain in Gyeonggi Province compresses camera-lidar module cost curves for mid-market adoption. Foundry concentration for radar MMIC components among South Korean semiconductor fabricators exposes ACC module pricing to capacity constraints. Seoul's R&D corridor advances edge-computing architectures for sensor fusion at the module level.
China
Domestic OEMs in Shanghai and Guangdong accelerate camera-dominant ACC adoption despite precipitation performance gaps. MIIT standards for intelligent connected vehicles create parallel certification requirements alongside UNECE frameworks. Shenzhen's electronics cluster supplies computer-vision processors that undercut radar-based alternatives on unit economics.
Adaptive Cruise Control (ACC) System Market Vendor Landscape
Concentration sits with diversified automotive Tier-1 suppliers possessing captive radar manufacturing and OEM platform integration capabilities. The vendor base separates into three strategic archetypes: German industrial conglomerates with sensor hardware scale, Japanese keiretsu-affiliated electronics specialists, and North American diversified suppliers with software fusion expertise. Competitive moves center on machine-learning R&D allocation restructuring and strategic partnerships for V2X infrastructure integration.
Among German-based diversified suppliers, ZF Friedrichshafen AG and Continental AG anchor the radar-dominant hardware tier, while Robert Bosch GmbH exemplifies the integrated sensor-to-software archetype with captive manufacturing scale. Denso Corporation represents the Japanese keiretsu model of tight OEM supply integration. These three entities occupy positions that define the competitive boundary between cost-optimized single-sensor configurations and premium multi-sensor fusion architectures.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Magna International Inc. |
| Robert Bosch GmbH |
| Valeo SA |
| Hyundai Mobis |
| Continental AG |
| Autoliv Inc. |
| Aptiv PLC |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Euro NCAP safety scoring protocols gate both supplier qualification and price differentiation simultaneously, forcing Tier-1 vendors to absorb certification costs upfront while OEMs tier procurement across premium multi-sensor and economy radar-only configurations.
Pricing Analysis
NHTSA's automatic emergency braking mandate dictates the pricing tier structure across the ACC market, compressing margins on base-system radar configurations while preserving premium capture for camera-lidar fusion suites. Three-tier pricing structure across premium, standard, and economy levels separates predictive ACC with machine-learning inference from radar-dominant compliance systems and legacy standard ACC without anticipatory braking. Cost compression in entry-level passenger segments is intensifying because Tier-1 suppliers must reallocate engineering resources toward mandate compliance. Fleet operators in Germany and Japan exhibit the lowest price sensitivity due to bundled telematics contracts, while US aftermarket retrofit buyers face the highest cost consciousness.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for radar MMIC and lidar ASIC components, creating geographic concentration that feeds from Taiwanese foundry capacity and South Korean memory integration. Raw material dependencies center on gallium arsenide substrates, silicon photonics wafers, and specialized automotive-grade resins for sensor housing. Single-source vulnerability in millimeter-wave radar chip supply exposes module pricing to foundry allocation decisions. Distribution runs through captive OEM supply chains for passenger vehicles and independent installer networks for commercial fleet retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ACC market sits in a cyclical recovery phase driven by NHTSA's phased mandate timeline through 2029, which forces OEM platform standardization and creates predictable procurement pull-through regardless of near-term vehicle demand fluctuations.
For Market Incumbents: Compound defensive positioning through backward integration into radar MMIC manufacturing and captive machine-learning R&D centers in Stuttgart and Nagoya. Camera-lidar fusion entrants threaten premium segment margins, making ISO 26262 ASIL-D certification depth the critical lever for contract retention with German and Japanese OEMs. Capacity discipline in radar module production preserves pricing power against cost-optimized Asian competitors. For New Entrants and Emerging Players: Lead with aftermarket commercial retrofit targeting US long-haul trucking fleets in Texas and California, where independent installer networks bypass established OEM supply relationships. AI Act compliance documentation services in Europe represent the most penetrable white-space, offering algorithmic transparency auditing as a recurring revenue layer alongside hardware sales. Go-to-market execution should anchor on fleet telematics integration partnerships rather than discrete module pitches. For Investors and Strategic Acquirers: NHTSA's 2029 enforcement deadline reshapes the acquisition landscape toward Tier-1 suppliers with proven mandate compliance engineering and existing OEM platform integration. Long-term viability over the next decade hinges on machine-learning inference capabilities at the sensor edge rather than legacy hardware scale. Watch for V2X infrastructure deployment signals in German smart highway pilots as the inflection indicator for next-generation ACC demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | NHTSA compliance timelines force OEMs to consolidate ACC variants across vehicle classes. |
| Sensor Fusion R&D Investment | Camera-lidar architectures capture premium procurement from Bavarian and Baden-Württemberg OEMs. |
| Aftermarket Channel Expansion | Independent installer networks unlock US long-haul fleet demand outside captive supply. |
| V2X Infrastructure Partnership | C-V2X roadside integration enables anticipatory braking beyond sensor line-of-sight in urban corridors. |
| AI Act Compliance Service Launch | Algorithmic transparency documentation monetizes regulatory burden for European ACC suppliers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, engaging Tier-1 supplier procurement directors, OEM platform engineers, fleet telematics managers, and aftermarket distributor principals. Secondary validation drew from NHTSA rulemaking dockets, Euro NCAP test protocols, vehicle production databases, and UNECE type approval registries. Bottom-up module shipment estimates triangulated against top-down OEM fitment projections.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, sensor technology, end-user channel, and vehicle class. CAGRs were derived from regression analysis against regulatory mandate phase-ins and fleet procurement cycle timing. Forecast inputs incorporated foundry capacity utilization for radar MMIC supply and Euro NCAP scoring protocol evolution.
Forecasts assume regulatory continuity in NHTSA automatic emergency braking rules and Euro NCAP safety scoring; material policy shifts would require re-modeling. Semiconductor input volatility and cross-border harmonization gaps between MLIT and UNECE frameworks represent specific revision risks. Recalibration cycles align with material shifts in foundry capacity allocation and V2X deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automotive AI Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Europe IoT Connected Cars Market
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Driverless Taxi Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
India Autonomous Navigation Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Africa Autonomous Navigation Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market