
 Autonomous Vehicles and Car Patent Market | 2026-2036
Autonomous Vehicles and Car Patent Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Vehicles and Car Patent Market Insights
Fleet operator demand is expanding as logistics providers and ride-sharing platforms build captive patent portfolios to reduce licensing exposure. Alphabet leverages its Waymo subsidiary to anchor autonomous navigation patents across urban mobility applications. Toyota Motor sustains hybrid-electric autonomous integration through dense patent thickets in powertrain coordination. Nvidia dominates AI training hardware patents that underpin machine learning inference at the vehicle edge.
Autonomous vehicles and car patents encompass intellectual property protecting self-driving system architectures, sensor configurations, decision algorithms, and vehicle-to-infrastructure communication protocols, typically filed under international patent classification codes covering B60W (vehicle control systems) and G05D (position control). These patents secure competitive positioning in markets where software-defined functionality determines commercial viability. Sensor fusion and LiDAR technology segments attract the densest patent activity due to hardware-software integration complexity and high R&D sunk costs. Machine learning applications within computer vision represent the fastest-expanding filing category as neural network architectures replace rules-based perception stacks. Fleet management applications command premium licensing terms because operational data feedback loops create compounding algorithmic advantages.
NHTSA in the United States, the EU AI Act framework in Europe, and MIIT standards in China collectively shape patentability thresholds by mandating traceable decision logic and validated safety envelopes. These regulators require documentation that directly influences claim construction and prior art boundaries in autonomous system patents. Stakeholders must monitor how jurisdictional safety certifications fragment into incompatible technical standards that multiply patent filing obligations across export markets.
Market Dynamics
Fleet operators are consolidating autonomous patent portfolios to secure algorithmic advantages in logistics networks, while NHTSA and EU AI Act compliance requirements reshape claim construction boundaries for safety-critical systems.
Growth Catalysts
- EU AI Act traceability mandates:Documentation requirements for autonomous decision logic are expanding patentable subject matter in validated safety envelopes across European deployment zones.
- Sensor fusion complexity:Hardware-software integration in LiDAR and computer vision stacks creates dense patent thickets that protect high R&D sunk costs.
- Michigan R&D clustering:OEM concentration in Detroit-Warren corridor accelerates cross-licensing activity and reduces transaction costs for powertrain coordination patents.
Market Restraints
- LiDAR component supply concentration:Specialized photonics manufacturing concentrates in Bavaria and California, creating single-source vulnerability for tier-one autonomous system integrators.
- NHTSA testing protocol fragmentation:Evolving safety validation requirements delay patent grant timelines and increase claim amendment costs for urban navigation systems.
- Rules-based perception substitution:Legacy deterministic algorithms face displacement by neural architectures, eroding value of established patent estates in structured environments.
Strategic Opportunities
- Vehicle-to-infrastructure communication:5G-V2X protocol standardization in Germany and Japan creates whitespace for cross-border patent licensing in smart corridor deployments.
- Fleet data feedback loops:Operational telemetry from captive logistics networks compounds algorithmic advantages and supports premium licensing terms for continuous learning systems.
- MIIT autonomous vehicle certification:China's national standards for machine learning inference at the vehicle edge mandate documentation that aligns with patent claim construction practices.
Industry Challenges
- Machine learning engineer scarcity:Specialized talent for neural architecture search and edge optimization commands compensation premiums that strain R&D budgets.
- Multi-jurisdictional filing obligations:Incompatible safety certifications across NHTSA, EU AI Act, and MIIT frameworks multiply prosecution costs for export-market patent families.
- Prior art boundary uncertainty:Rapid evolution of transformer-based perception models complicates novelty assessments and opposition proceedings in computer vision patent classes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Vehicles and Car Patent Market |
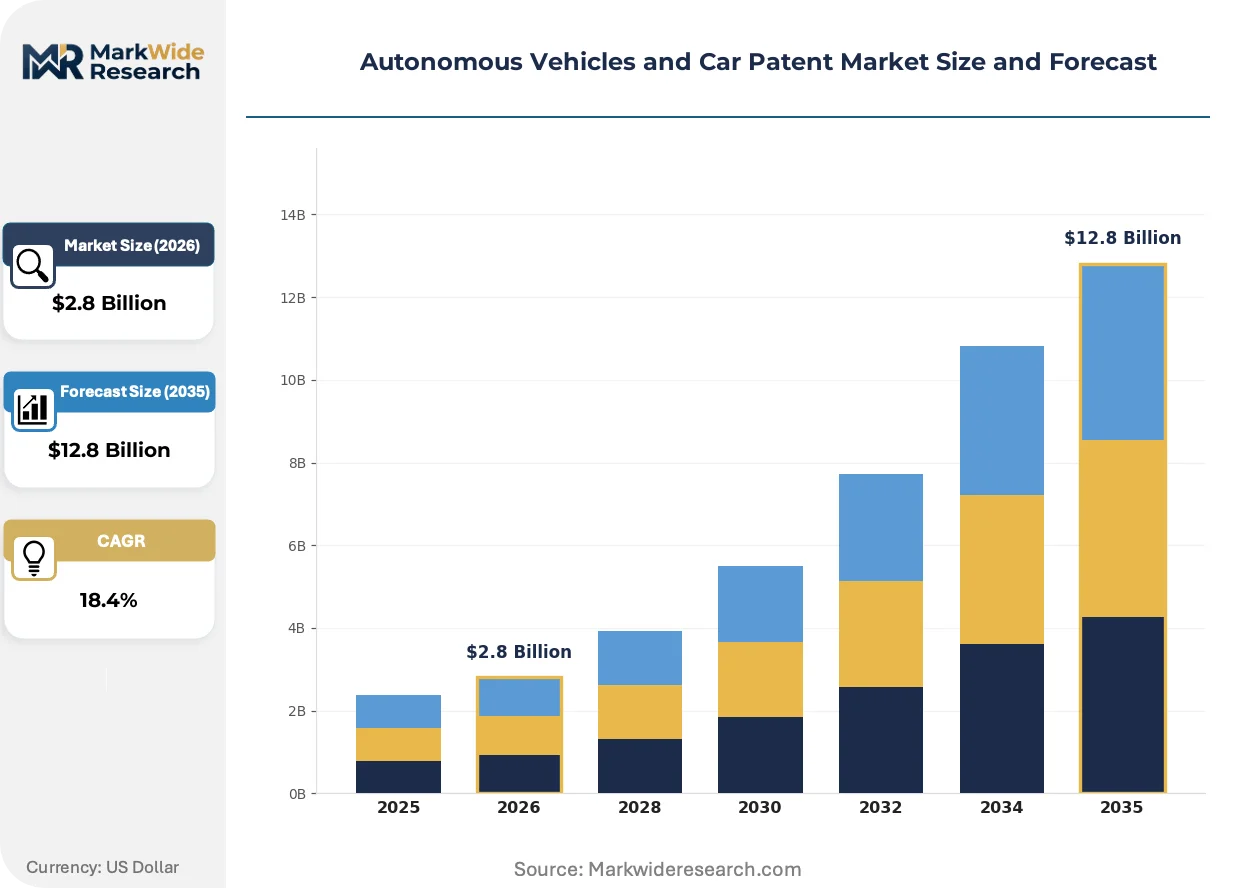
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Cars, Commercial Vehicles, Delivery Drones, Autonomous Boats Technology: Sensor Fusion, LiDAR, Computer Vision, Machine Learning Application: Ride-Sharing, Logistics, Personal Transportation, Fleet Management End User: OEMs, Fleet Operators, Government Agencies, Technology Companies |
| Companies Covered | Baidu, Alphabet, Toyota Motor, General Motors, Ford, Nvidia, Waymo, Bosch, Tesla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Vehicles and Car Patent Market Trends and Innovations
Neural network architectures are replacing rules-based perception stacks across autonomous navigation systems, compressing development cycles and redrawing competitive boundaries in patentable subject matter.
End-to-end deep learning for urban driving is consolidating previously fragmented perception-planning-control pipelines into unified differentiable architectures. Tier-one suppliers and fleet operators are adopting these consolidated stacks to reduce sensor calibration overhead and simplify safety validation documentation. This consolidation is compressing patent licensing opportunities in discrete component categories while expanding protection scope for integrated system claims.
The EU AI Act's risk-based classification for autonomous systems is mandating human oversight interfaces and decision traceability requirements that directly influence patent claim construction. Industrial consequence includes expanded filing activity in explainable AI and attention-mechanism documentation that satisfies both regulatory and examination standards. German automotive suppliers are most affected, accelerating patent prosecution timelines to align with anticipated 2025 enforcement windows.
Long-term patent licensing agreements are displacing per-unit royalty structures as fleet operators seek cost predictability across autonomous vehicle deployment scales. Tier-two logistics providers and municipal transit authorities are driving this shift, favoring capped annual payments over variable exposure. California and Michigan-based OEMs are most visible in this transition, structuring multi-year cross-licenses that bundle navigation, sensor fusion, and powertrain coordination intellectual property.
Autonomous Vehicles and Car Patent Market Segmentation
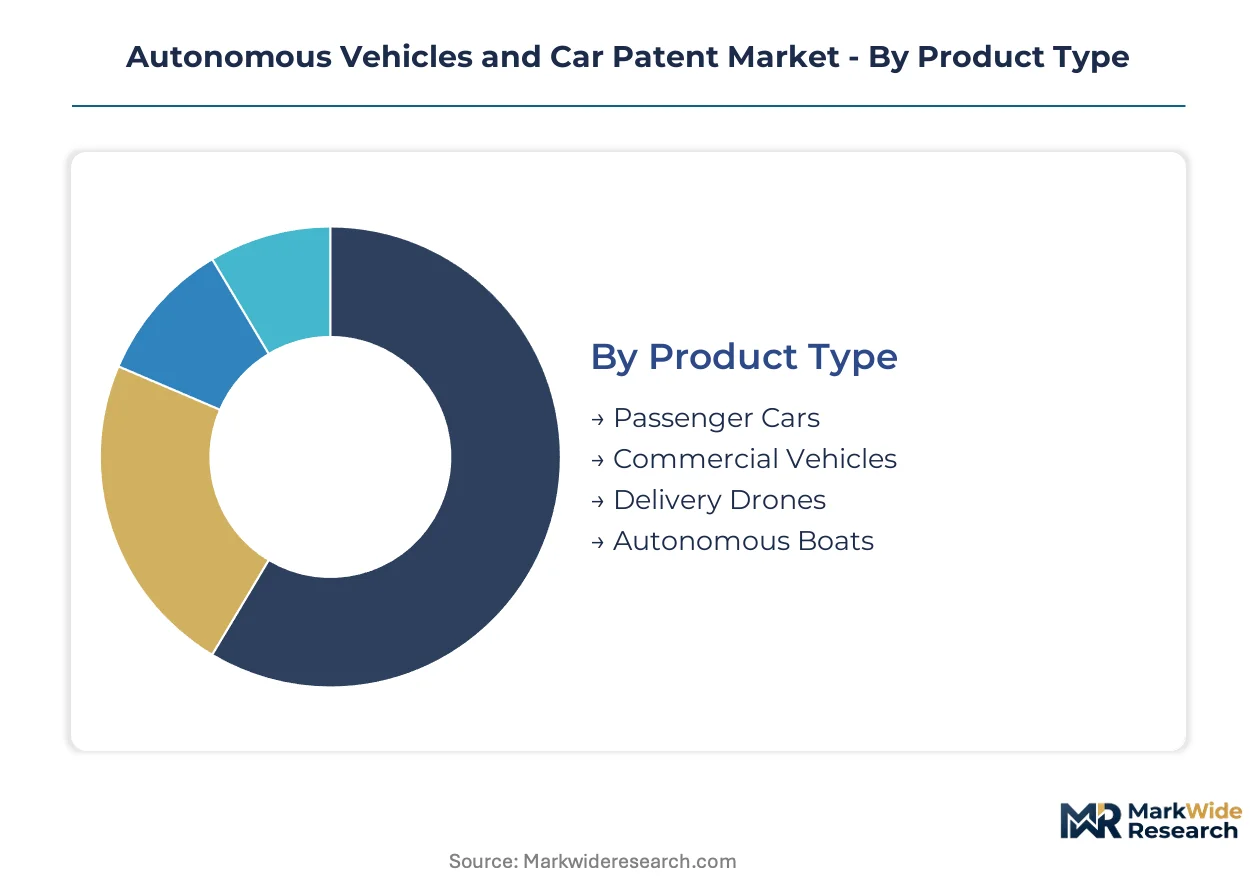
Patent filing intensity varies sharply across vehicle platforms and technology layers. Segmentation reveals where R&D investment concentrates and which intellectual property categories command premium licensing multiples.
Product Type:
Passenger cars dominate patent volume while commercial vehicles attract higher per-patent valuations due to fleet-scale deployment economics.
- Passenger Cars:Urban navigation and safety systems generate dense filing activity in B60W classification codes. California and Bavaria concentrate development where OEMs cluster R&D operations for consumer autonomous features.
- Commercial Vehicles:Long-haul trucking patents command premium terms due to operational data feedback loops that compound algorithmic advantages. Highway corridor deployments in the United States and Germany drive sensor fusion claims for predictable environments.
- Delivery Drones:Low-altitude airspace navigation patents are expanding most quickly as logistics providers build captive portfolios for last-mile automation.
- Autonomous Boats:Maritime collision avoidance and docking systems attract specialized filing activity in coastal logistics zones.
Mature deployment sits with passenger cars. Newer deployment is concentrated in delivery drones.
Technology:
Hardware-software integration complexity determines where patent thickets form and which categories resist commoditization pressure.
- Sensor Fusion:Multi-modal perception architectures integrating camera, radar, and LiDAR inputs create the densest patent thickets. German automotive suppliers concentrate claims here due to high R&D sunk costs and calibration complexity.
- LiDAR:Photonics hardware patents cluster in California and Bavaria where specialized manufacturing concentrates. Supply constraints for tier-one integrators sustain premium licensing terms despite solid-state technology advances.
- Computer Vision:Neural network architectures for object detection are climbing the fastest as transformer-based models replace convolutional approaches in urban navigation systems.
- Machine Learning:Edge inference optimization and neural architecture search attract filing activity from semiconductor vendors supporting vehicle-side computation.
Hardware-intensive segments retain pricing power. Software-centric categories face faster obsolescence cycles.
Application:
Operational scale and data ownership structure determine patent commercialization strategy across use cases.
- Ride-Sharing:Urban mobility platforms drive dense filing in navigation and passenger safety systems. California-based operators leverage operational data to refine machine learning models and secure defensive patent positions.
- Logistics:Warehouse-to-door automation commands premium licensing as fleet operators consolidate captive portfolios to reduce third-party exposure. Highway corridor deployments in the United States and Germany concentrate development.
- Personal Transportation:Consumer autonomous features attract defensive filing from established OEMs protecting brand positioning in premium vehicle segments.
- Fleet Management:Telematics and predictive maintenance patents gain share fastest as logistics providers seek algorithmic advantages from operational telemetry feedback loops.
Captive fleet deployment offers stronger patent monetization than consumer-facing applications.
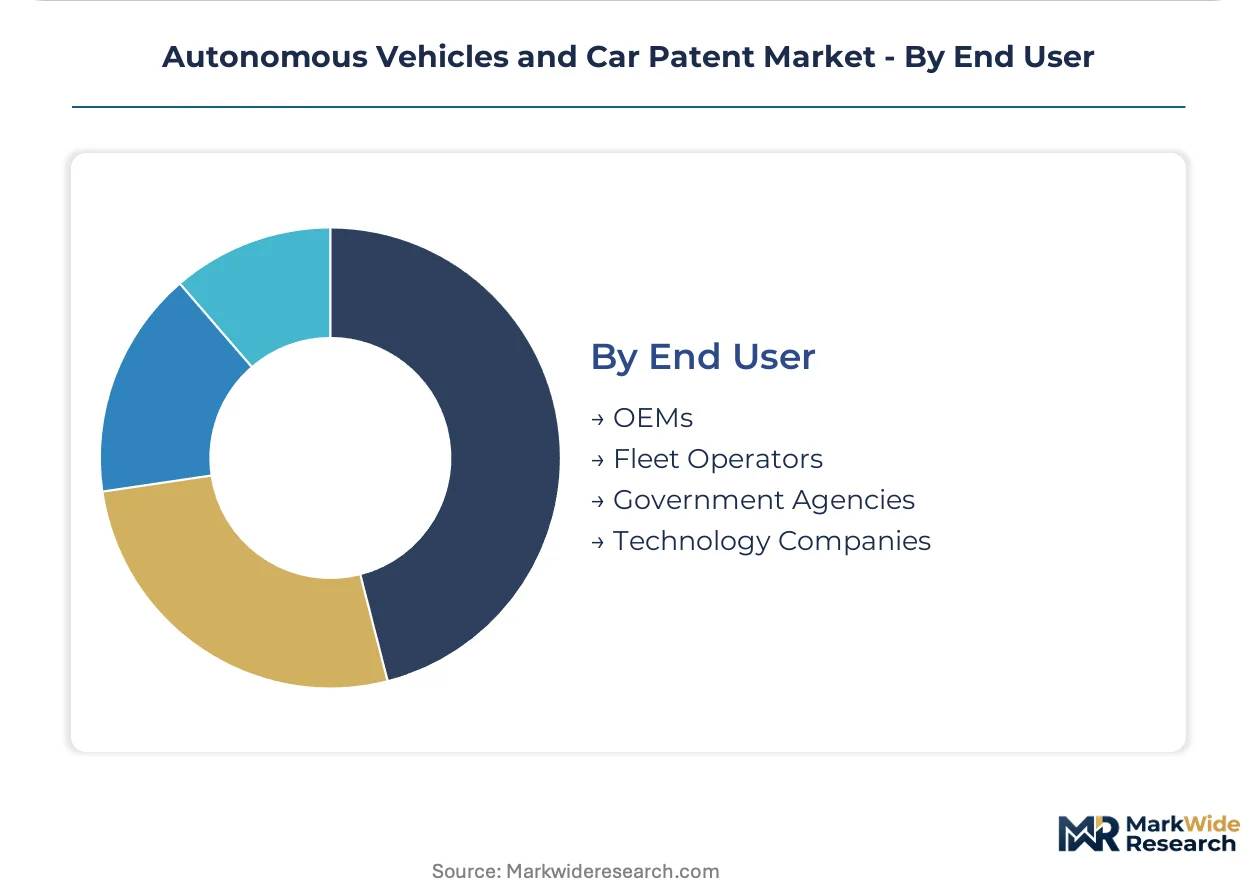
End User:
Patent acquisition motives diverge between defensive portfolio builders and offensive licensing seekers.
- OEMs:Vertically integrated manufacturers file dense thickets protecting powertrain coordination and vehicle control architectures. Michigan and Bavaria concentration accelerates cross-licensing activity.
- Fleet Operators:Logistics providers and ride-sharing platforms build defensive portfolios to reduce licensing exposure. Long-term agreements displace per-unit royalties as these stakeholders seek cost predictability.
- Government Agencies:Public transit authorities and municipal regulators drive standard-essential patent development for vehicle-to-infrastructure communication protocols.
- Technology Companies:Semiconductor and software vendors concentrate claims in AI training hardware and edge inference optimization, supporting machine learning deployment at the vehicle edge.
Technology companies are gaining share fastest in AI-centric patent classes. OEMs retain dominance in mechanical system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in the United States, Germany, China, Japan, and South Korea concentrate autonomous patent filing activity where OEMs cluster R&D operations and regulators mandate safety documentation. These five markets generate the densest intellectual property thickets and shape cross-border licensing frameworks.
United States
Waymo and General Motors anchor urban navigation patent development in California and Michigan. NHTSA testing protocols for autonomous vehicle safety validation expand claim construction requirements. The Detroit-Warren corridor accelerates cross-licensing negotiations among OEMs seeking powertrain coordination patents.
Germany
Bosch and automotive suppliers drive sensor fusion patent density in Bavaria and Baden-Württemberg. The EU AI Act's traceability mandates reshape documentation standards for explainable AI claims. Munich-Stuttgart industrial clusters concentrate LiDAR photonics manufacturing and calibration IP.
China
Baidu builds defensive patent portfolios for ride-sharing and logistics applications in Beijing and Shenzhen. MIIT certification requirements for machine learning inference at the vehicle edge align with patent claim construction practices. Yangtze River Delta and Pearl River Delta R&D centers file dense thickets in computer vision and edge optimization.
Japan
Toyota Motor sustains hybrid-electric autonomous integration patents through dense powertrain coordination claims in Aichi and Tokyo. METI standards for vehicle-to-infrastructure communication influence 5G-V2X protocol development. Nagoya-Tokyo corridors concentrate telematics and predictive maintenance IP for fleet management systems.
South Korea
Seoul Capital Area technology companies concentrate AI training hardware and edge inference optimization patents. National standards for autonomous vehicle deployment mandate documentation that supports patent prosecution timelines. Busan-Ulsan industrial zones attract filing activity in semiconductor-vehicle integration architectures.
Autonomous Vehicles and Car Patent Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fleet-scale deployment and AI-native architectures. The market structures around three tiers: vertically integrated OEMs with dense mechanical system portfolios, technology vendors anchoring AI-centric patent classes, and fleet operators building defensive positions to reduce licensing exposure. Dominant competitive moves include long-term cross-licensing agreements displacing per-unit royalties, and strategic consolidation of sensor fusion and computer vision IP to capture algorithmic advantages from operational data feedback loops.
Within the technology vendor tier, Alphabet and Nvidia exemplify divergent patent strategies—Alphabet through its Waymo subsidiary anchoring urban navigation portfolios, Nvidia dominating AI training hardware claims that underpin edge inference. Among established OEMs, Toyota Motor and General Motors occupy positions defined by powertrain coordination thickets and hybrid-electric autonomous integration. Baidu represents the fleet-operator archetype, building captive portfolios to reduce third-party licensing exposure in logistics and ride-sharing applications.
| Leading Market Players |
|---|
| Baidu |
| Alphabet |
| Toyota Motor |
| General Motors |
| Ford |
| Nvidia |
| Waymo |
| Bosch |
| Tesla |
| Others |
Pricing and Supply Chain Analysis
Patent-thicket density bifurcation between sensor-fusion hardware and commoditized perception software manifests in divergent licensing economics and geographically concentrated component sourcing. Premium claims in LiDAR photonics and multi-modal calibration command sustained royalty rates, while neural architecture patents face faster value erosion as transformer models displace legacy convolutional approaches.
Pricing Analysis
Volume-heavy passenger car patents trade at thinner margins than commercial vehicle claims where fleet-scale deployment justifies premium terms. Pricing stratifies across hardware-intensive sensor fusion, mid-tier computer vision licensing, and economy-level rules-based perception estates. Cost compression in deterministic algorithm portfolios is intensifying because neural architectures are substituting legacy perception stacks. Logistics providers exhibit lowest price sensitivity due to captive data feedback loops; tier-two automotive suppliers face highest pressure from cross-licensing consolidation.
Supply Chain Analysis
Specialized photonics manufacturing rests on Bavarian and Californian precision optics producers, with secondary clustering in South Korean semiconductor foundries. Critical inputs span indium phosphide wafers, MEMS scanning mirrors, and edge AI accelerators. Single-source vulnerability concentrates in solid-state LiDAR emitters where tier-one integrators lack qualified alternatives. Distribution runs through OEM-direct licensing for powertrain coordination, technology vendor marketplaces for AI training hardware, and fleet operator cross-licenses for logistics automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous vehicle patent market sits in a technology-transition phase as end-to-end deep learning consolidates previously fragmented perception-planning-control pipelines, displacing rules-based architectures that anchored legacy patent estates.
For Market Incumbents: Acquire sensor fusion calibration IP to thicken defensive positions against neural architecture substitution. Consolidate powertrain coordination claims through Michigan and Bavaria cross-licensing blocs. Vertical integration into LiDAR photonics manufacturing reduces single-source exposure from Bavarian component suppliers. NHTSA documentation requirements for traceable decision logic demand accelerated prosecution timelines to maintain claim validity. For New Entrants and Emerging Players: Enter via fleet data feedback loop patents in logistics automation where operational telemetry compounds algorithmic advantages. Target commercial vehicle highway corridor deployments in the United States and Germany where environmental predictability reduces safety validation burden. Pursue 5G-V2X protocol standardization whitespace in German-Japanese smart corridor initiatives. White-space concentration sits in explainable AI documentation satisfying EU AI Act oversight mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in semiconductor-vehicle integration specialists commanding edge inference optimization capabilities. Five-to-ten year viability hinges on patent estates surviving neural architecture obsolescence cycles. Target acquisition archetypes: captive fleet operators with compounding data advantages, and AI-native tier-one suppliers with consolidated perception stacks. Signal to watch: MIIT certification alignment with patent claim construction practices accelerating Chinese filing velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Patent Consolidation | Dense thickets in multi-modal perception protect high R&D sunk costs against neural substitution. |
| EU AI Act Compliance Documentation | Explainable AI filing activity accelerates to align with German enforcement windows. |
| Fleet Data Feedback Loop Monetization | Operational telemetry from captive logistics networks supports premium licensing terms. |
| Cross-Border 5G-V2X Licensing | Protocol standardization in Germany and Japan creates whitespace for smart corridor IP. |
| LiDAR Photonics Backward Integration | Upstream control over Bavarian and Californian manufacturing reduces supply vulnerability. |
Research Methodology
Multi-period observation of patent grant timelines, classification code migration patterns, and licensing agreement structures anchored the trend analysis, supplemented by interviews with autonomous systems R&D directors, IP portfolio managers at OEMs, fleet operator procurement leads, and NHTSA regulatory affairs specialists. Secondary validation drew from USPTO assignment records, EPO patent family databases, MIIT certification filings, and WIPO PCT publication trends. Bottom-up patent counting across B60W and G05D classifications triangulated against top-down market sizing from technology vendor revenue disclosures.
Input-output matrices mapped patent filing intensity to deployment scale projections across vehicle platforms, technology layers, and application segments throughout the forecast period. Segmentation dimensions modeled include hardware-software integration complexity, fleet versus consumer ownership structure, and jurisdictional regulatory cluster. CAGRs were derived from patent grant velocity trends correlated with autonomous vehicle deployment milestones. Industry-specific forecast inputs encompass NHTSA testing protocol evolution timelines and EU AI Act documentation mandate implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT certification fragmentation scenarios and transformer-based perception model prior art boundary disputes. Forecasts reflect documented assumptions regarding neural architecture substitution rates and cross-jurisdictional safety standard harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
Connected Vehicle Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Robotaxi Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market