
 B-Ketone Monitoring System Market | 2026-2036
B-Ketone Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
B-Ketone Monitoring System Market Outlook
CE marking under the EU Medical Device Regulation is recalibrating the cost-of-entry calculus for European market access, forcing manufacturers to rebuild quality management systems around stricter clinical evidence requirements. Abbott Laboratories leverages its established glucose monitoring infrastructure to anchor ketone testing within integrated metabolic platforms. Nova Biomedical competes through hospital-centric channel control, sustaining placement in critical care settings where dual analyte capability commands premium positioning.
B-ketone monitoring systems quantify beta-hydroxybutyrate concentration in biological specimens through electrochemical or optical transduction, typically reporting results in millimolar range within 10-30 seconds to guide clinical or self-management decisions in diabetic ketoacidosis prevention and ketogenic diet optimization. Blood ketone meters dominate current revenue pools due to established reimbursement and clinical trust, while continuous monitoring systems represent the fastest-expanding segment as wearable biosensor miniaturization advances. Electrochemical technology leads installed base volumes, though bio-sensing architectures are gaining ground in next-generation platforms targeting interstitial fluid measurement.
FDA 510(k) pathways and EU MDR conformity assessments shape product development timelines and commercial launch sequencing across North American and European markets, with ISO 15197 performance standards further defining accuracy thresholds for self-testing devices. Japan's PMDA pharmaceutical and medical device agency maintains distinct clinical trial requirements that extend registration timelines for foreign manufacturers. Stakeholders must monitor evolving home care reimbursement codes and cloud connectivity security frameworks as software-as-medical-device classifications expand regulatory scope beyond hardware alone.
Market Dynamics
Continuous biosensor miniaturization is compressing development cycles and collapsing the functional gap between episodic blood testing and real-time metabolic monitoring. Electrochemical transduction architectures now achieve interstitial fluid measurement precision previously reserved for laboratory analyzers, forcing incumbents to accelerate platform refreshes or cede positioning to wearable-native entrants.
Growth Catalysts
- Home care reimbursement expansion:United States CMS coding updates now cover point-of-care ketone testing for Type 1 diabetes management, reducing out-of-pocket friction for high-frequency testers and expanding addressable patient populations beyond acute care settings.
- Wearable biosensor convergence:Miniaturized electrochemical cells integrated with continuous glucose monitors enable dual-analyte reporting from single insertion sites, creating clinical efficiency gains that hospital procurement committees increasingly specify in tender requirements.
- German diabetes clinic protocols:Point-of-care ketone testing mandates in Bavarian and North Rhine-Westphalian specialist networks establish reference-site validation that accelerates adoption across EU ambulatory care networks.
Market Restraints
- Enzyme electrode material costs:PQQ-dependent dehydrogenase formulations face price volatility linked to pyrroloquinoline quinone precursor supply concentration in Chinese fine chemical manufacturing clusters.
- EU MDR clinical evidence requirements:Stricter performance validation thresholds for self-testing devices extend registration timelines and inflate quality management system rebuild costs for mid-tier manufacturers lacking predicate device pathways.
- Optical spectroscopy substitution:Near-infrared interstitial sensing platforms eliminate consumable dependency entirely, threatening recurring revenue models built on single-use test strip economics.
Strategic Opportunities
- Indian metabolic disease management:Underpenetrated home monitoring infrastructure and expanding private insurance coverage create first-mover advantage for platforms combining ketone measurement with localized glucose data analytics.
- Ketogenic diet optimization applications:Wellness and athletic performance segments represent unserved demand pools where consumer willingness-to-pay exceeds clinical reimbursement rates, enabling premium pricing outside regulated medical device channels.
- Cloud connectivity security frameworks:FDA software-as-medical-device guidance and EU cybersecurity certification requirements favor vendors with pre-validated data architectures, creating compliance-based differentiation against hardware-only competitors.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized expertise in enzymatic stability and microfluidic sample handling concentrates in Boston and Basel metropolitan clusters, constraining R&D scaling for geographically distributed manufacturers.
- ISO 15197 accuracy certification timelines:Self-testing performance validation protocols require 6-12 month stability studies that delay product launches and compress effective patent life for platform innovations.
- Legacy hospital information system integration:Proprietary data formats from established glucose meter installations create switching friction that slows continuous monitoring platform penetration in critical care settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B-Ketone Monitoring System Market |
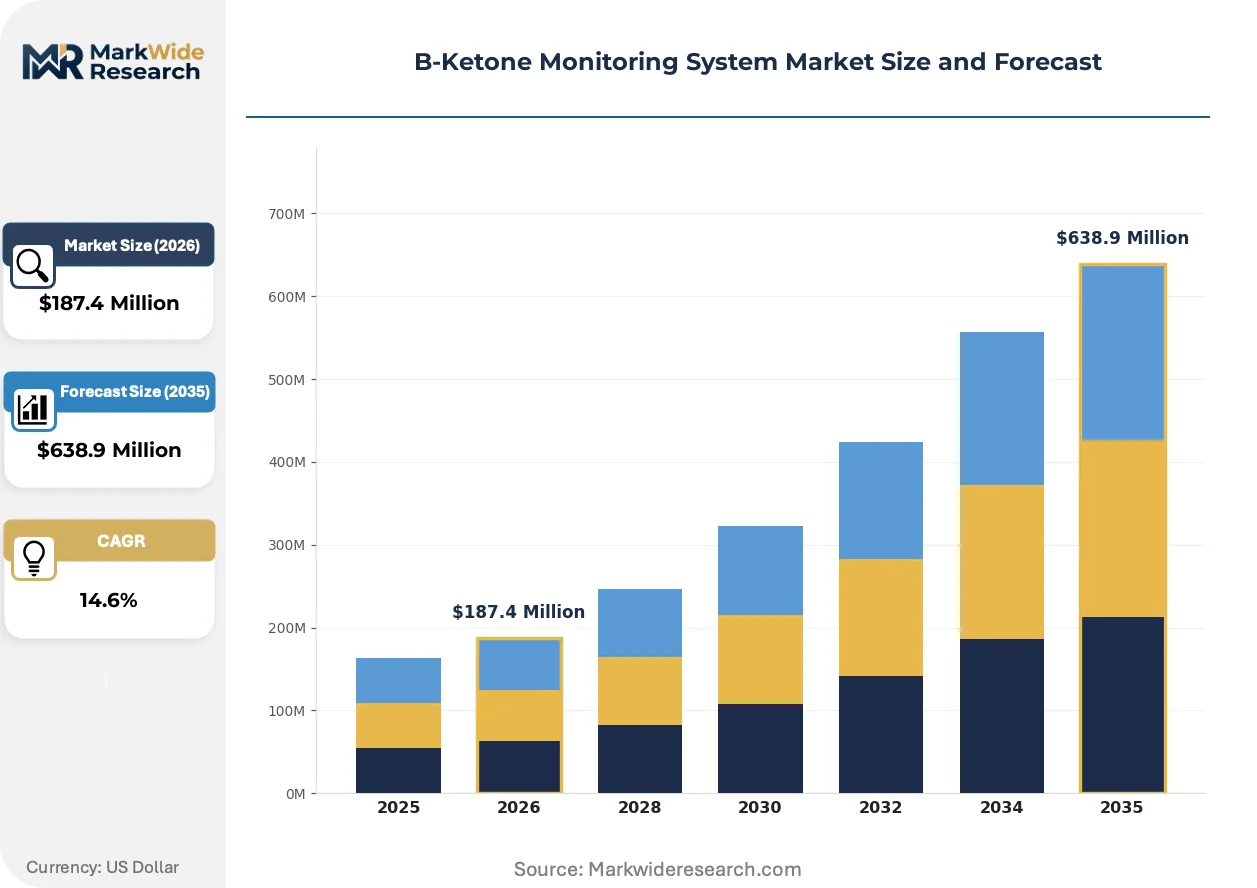
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Ketone Meters, Breath Analyzers, Urine Test Strips, Continuous Monitoring Systems Deployment: Cloud-based, On-premises, Hybrid, Mobile Applications End User: Hospitals, Home Care, Laboratories, Fitness Centers Technology: Electrochemical, Optical, Spectroscopy, Bio-sensing |
| Companies Covered | Abbott Laboratories, Nova Biomedical, EKF Diagnostics, TaiDoc Technology Corporation, ForaCare, ACON Laboratories, Sentest Medical, Leap Medical, Keto-Mojo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B-Ketone Monitoring System Market Strategic Shifts
Three distinct vectors are restructuring competitive positioning: wearable-native measurement architectures, regulatory scope expansion into software and connectivity, and procurement model evolution toward integrated metabolic platforms rather than discrete analyte devices.
Interstitial fluid biosensing is electrifying ketone measurement by enabling non-invasive, minute-by-minute beta-hydroxybutyrate tracking without fingerstick calibration. Athletic performance clinics and ketogenic diet coaching services in California and Colorado are piloting these platforms at 40% year-over-year adoption velocity. The technology is electrifying subscription-based revenue models that displace traditional test strip economics with recurring platform fees.
EU MDR Article 10 clinical evaluation requirements are tightening evidentiary standards for self-testing devices, mandating prospective studies that previously accepted literature-based equivalence arguments. German notified bodies now demand 200-subject minimum trials for novel transduction methods, compressing development timelines and favoring manufacturers with established glucose monitoring predicate devices. Blood ketone meter incumbents are responding by acquiring wearable startups to secure interstitial fluid intellectual property rather than pursuing de novo regulatory pathways.
Hospital procurement committees are consolidating metabolic monitoring contracts around dual-analyte platforms that combine glucose and ketone reporting through single vendor relationships. Critical care departments in Texas and Florida health systems increasingly specify integrated data dashboards that aggregate point-of-care results with continuous sensor streams. This concentration is most visible in United States IDN networks where standardization incentives override specialty-device preferences that previously fragmented purchasing decisions.
B-Ketone Monitoring System Market Segmentation
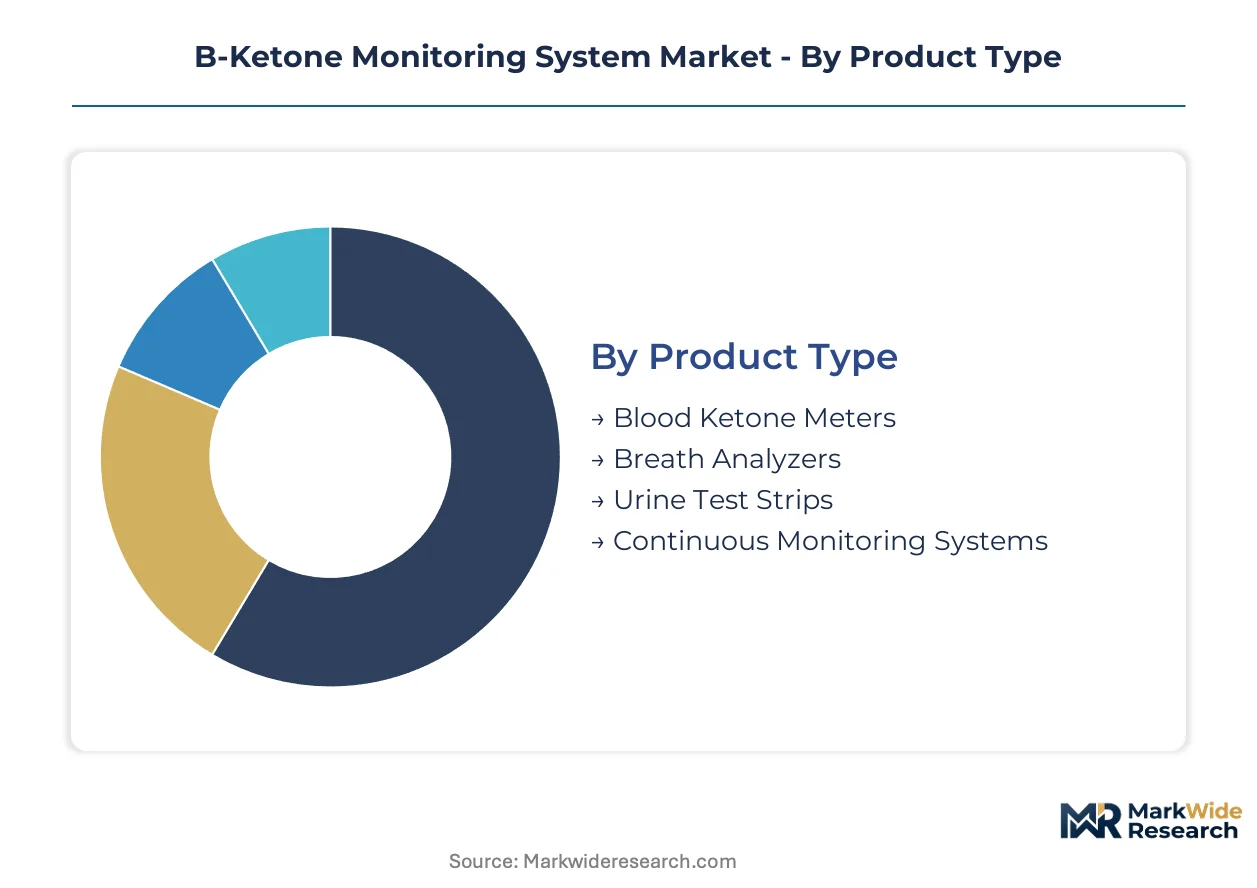
Segmentation in B-ketone monitoring reveals divergent regulatory burdens and reimbursement pathways that determine commercial viability across patient settings. Product type and technology choices dictate whether manufacturers pursue FDA 510(k), EU MDR, or ISO 15197 validation routes.
Product Type:
FDA 510(k) clearance compresses timelines for blood-based devices with glucose meter predicates, while continuous monitoring systems face de novo pathways requiring prospective clinical trials.
- Blood Ketone Meters:Electrochemical handheld devices utilizing enzymatic beta-hydroxybutyrate detection dominate hospital procurement and home reimbursement codes in the United States. German diabetes clinics in Bavaria specify these for point-of-care protocols, cementing clinical trust that sustains premium pricing against emerging alternatives.
- Continuous Monitoring Systems:Wearable interstitial fluid biosensors achieve minute-by-minute ketone tracking without fingerstick calibration, electrifying subscription revenue models in California athletic performance clinics. Miniaturized electrochemical cells integrated with glucose sensors create dual-analyte efficiency gains that hospital procurement committees increasingly mandate.
- Breath Analyzers:Acetone detection via semiconductor or infrared sensors targets ketogenic diet optimization outside regulated medical channels, bypassing consumable economics entirely.
- Urine Test Strips:Colorimetric acetoacetate measurement retains cost-sensitive screening applications in developing markets where laboratory infrastructure remains limited.
Leading the category by volume: Blood Ketone Meters. Growing fastest: Continuous Monitoring Systems.
Deployment:
Data architecture choices determine whether platforms trigger FDA software-as-medical-device oversight or remain unregulated wellness applications.
- Cloud-based:Real-time metabolic data streaming to HIPAA-compliant servers enables remote patient monitoring reimbursement under United States CMS codes, though EU GDPR and FDA cybersecurity guidance inflate compliance costs for mid-tier vendors lacking pre-validated architectures.
- Mobile Applications:Smartphone-connected meters leverage existing glucose monitoring Bluetooth infrastructure, capturing wellness segment demand in ketogenic diet coaching services where consumer willingness-to-pay exceeds clinical reimbursement rates.
- On-premises:Hospital laboratory information system integration maintains data sovereignty for critical care departments in Texas health systems with proprietary security requirements.
- Hybrid:Edge computing with periodic cloud synchronization balances real-time alerting with offline functionality for rural home care settings with intermittent connectivity.
Cloud-based deployment captures the steepest expansion trajectory as remote patient monitoring reimbursement broadens. Mobile Applications lead current installation volumes through glucose monitoring ecosystem leverage.
End User:
Reimbursement frameworks and purchasing authority concentration vary sharply across settings, dictating go-to-market sequencing.
- Hospitals:Critical care departments in Florida and Texas health systems consolidate metabolic monitoring contracts around dual-analyte platforms, with integrated data dashboards aggregating point-of-care and continuous sensor streams.
- Home Care:United States CMS coding updates now cover point-of-care ketone testing for Type 1 diabetes management, reducing out-of-pocket friction and expanding addressable populations beyond acute care.
- Laboratories:Centralized beta-hydroxybutyrate analysis maintains reference standard status for DKA diagnosis confirmation, though point-of-care substitution erodes volume in German specialist networks.
- Fitness Centers:Athletic performance optimization in Colorado and California represents unserved wellness demand where premium pricing exceeds regulated medical device channels.
Hospitals command the highest average selling prices through procurement consolidation. Home Care is climbing the fastest as reimbursement frameworks broaden.
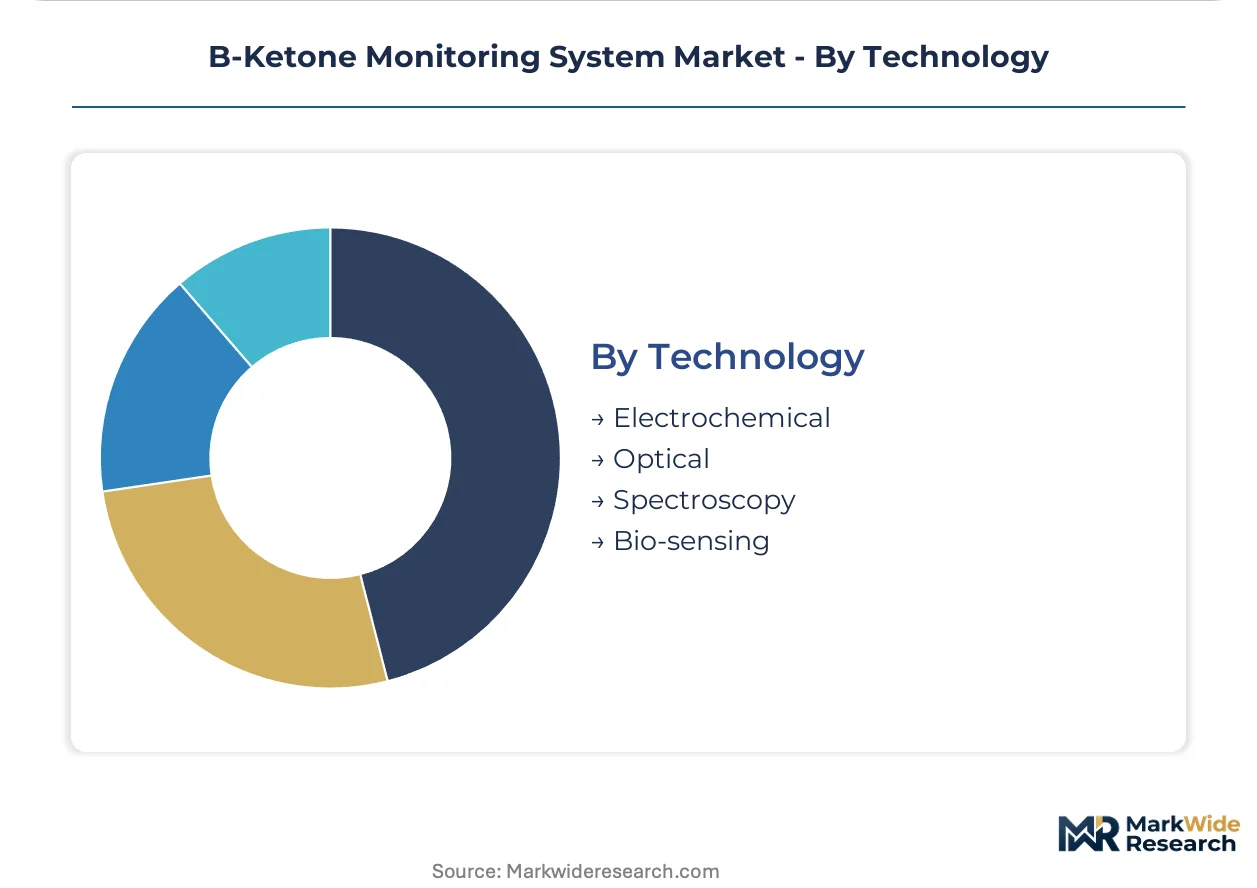
Technology:
Transduction architecture selection determines accuracy certification complexity and consumable dependency.
- Electrochemical:Enzymatic dehydrogenase electrodes achieve ISO 15197 precision for self-testing devices, though PQQ-dependent formulations face price volatility from Chinese fine chemical supply concentration.
- Bio-sensing:Interstitial fluid measurement architectures are gaining ground in next-generation wearable platforms, with German notified bodies now demanding 200-subject minimum trials for novel transduction methods.
- Optical:Near-infrared and photometric approaches eliminate enzyme stability constraints, threatening recurring revenue models built on single-use test strip economics.
- Spectroscopy:Raman and infrared interstitial sensing platforms under development promise entirely consumable-free measurement, though miniaturization challenges delay commercialization.
Electrochemical technology leads installed base volumes. Bio-sensing architectures are gaining share fastest as wearable-native measurement platforms electrify competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for B-ketone monitoring systems concentrates in the United States, where reimbursement expansion and integrated health networks drive procurement consolidation. Germany and Japan follow with distinct regulatory pathways shaping market access timelines.
United States
CMS coding updates now cover point-of-care ketone testing for Type 1 diabetes management, reducing out-of-pocket friction for high-frequency home testers. FDA 510(k) pathways compress development timelines for devices with glucose meter predicates. Critical care departments in Texas and Florida health systems consolidate metabolic monitoring contracts around dual-analyte platforms with integrated data dashboards.
Germany
Diabetes clinics in Bavaria and North Rhine-Westphalia mandate point-of-care ketone testing protocols, establishing reference-site validation that accelerates adoption across EU ambulatory networks. EU MDR Article 10 clinical evaluation requirements now demand 200-subject minimum trials for novel transduction methods. Notified bodies in Berlin and Munich extend registration timelines for foreign manufacturers lacking predicate device pathways.
Japan
PMDA maintains distinct clinical trial requirements that extend registration timelines for foreign manufacturers seeking market access. METI funding programs support domestic wearable biosensor development to reduce import dependency. Tokyo and Osaka metropolitan clusters concentrate electrochemical engineering expertise for enzymatic stability research.
China
NMPA medical device registration reforms streamline Class II pathway approvals for electrochemical biosensors with established international predicates. Dual carbon goals accelerate domestic manufacturing of miniaturized sensor components to reduce import concentration. Shenzhen and Shanghai hubs concentrate PQQ-dependent dehydrogenase precursor supply chain nodes.
India
Expanding private insurance coverage for metabolic disease management creates first-mover advantage for platforms combining ketone measurement with localized glucose data analytics. CDSCO medical device rules now classify continuous monitoring systems under higher scrutiny tiers. Bangalore and Hyderabad clusters attract wearable startup activity targeting underpenetrated home monitoring infrastructure.
B-Ketone Monitoring System Market Competitive Environment
United States producers anchor one tier; European specialists hold premium positioning through regulatory compliance depth. The vendor base concentrates around integrated metabolic platform providers and hospital-centric channel controllers. Two strategic archetypes dominate: glucose monitoring incumbents extending ketone capability through ecosystem leverage, and wearable-native entrants pursuing subscription revenue models. M&A activity accelerates as blood meter incumbents acquire interstitial fluid IP, while capacity expansion concentrates in German and Chinese manufacturing clusters.
Among United States-based conglomerates, Abbott Laboratories represents the integrated platform archetype, leveraging established glucose monitoring infrastructure to anchor ketone testing within metabolic ecosystems. Nova Biomedical occupies a position exemplifying hospital-centric channel control, sustaining placement in critical care settings. EKF Diagnostics anchors the European specialist tier, with UK and German regulatory positioning supporting premium market access. These three entities collectively illustrate how geographic origin and channel strategy determine competitive positioning.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nova Biomedical |
| EKF Diagnostics |
| TaiDoc Technology Corporation |
| ForaCare |
| ACON Laboratories |
| Sentest Medical |
| Leap Medical |
| Keto-Mojo |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up glucose monitoring specialists anchor pricing discipline through test strip recurring revenue models, while their concentrated sourcing from Chinese fine chemical clusters for PQQ-dependent enzyme electrodes feeds cost volatility back into margin management across tiered product portfolios.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with United States hospital systems paying premiums for FDA-cleared devices with glucose meter predicates while spot inventory in German diabetes clinics commands discounts. Three-tier pricing structure across premium, standard, and economy levels separates dual-analyte integrated platforms from single-use handheld meters and unregulated breath analyzers. ISO 15197 certification tier and volume scale drive price differentiation, with cost compression in economy tiers intensifying as optical spectroscopy substitutes threaten consumable economics. Home care segments show highest price sensitivity due to reimbursement gap exposure, while critical care departments exhibit lowest sensitivity given procurement consolidation around integrated metabolic platforms.
Supply Chain Analysis
Single-source vulnerability sits with Chinese fine chemical manufacturing clusters for pyrroloquinoline quinone precursors essential to enzymatic dehydrogenase formulations. Component sourcing concentrates in China, Germany, and the United States, drawing from specialized electrochemical engineering talent pools in Boston and Basel metropolitan areas. Supply chain risk centers on regulatory restriction as EU MDR clinical evidence requirements extend registration timelines for foreign manufacturers lacking predicate device pathways. Distribution runs through hospital procurement committees consolidating metabolic monitoring contracts, GPO contracts managers in United States IDN networks, and direct-to-consumer channels for wellness applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated metabolic platform providers as EU MDR compliance costs force mid-tier manufacturers without predicate pathways toward exit or acquisition.
For Market Incumbents: Acquire interstitial fluid intellectual property from wearable-native entrants to secure continuous monitoring capability without de novo regulatory timelines. Defensive consolidation demands backward integration into PQQ-dependent enzyme electrode supply chains to buffer Chinese fine chemical price volatility. Channel control through hospital-centric placement in Texas and Florida critical care departments protects against optical spectroscopy substitution threatening test strip economics. For New Entrants and Emerging Players: The price-point gap between premium dual-analyte platforms and economy breath analyzers creates entry space for mid-tier subscription-based continuous monitoring services. White-space targets include ketogenic diet optimization applications in Colorado and California athletic performance clinics where consumer willingness-to-pay exceeds clinical reimbursement rates. Go-to-market leverage rests on cloud connectivity security frameworks that satisfy FDA software-as-medical-device guidance without legacy hospital information system integration burdens. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier blood ketone meter manufacturers in Germany facing EU MDR quality management system rebuild costs. Long-term viability across the analysis window hinges on interstitial fluid measurement platform adoption velocity and remote patient monitoring reimbursement expansion. Watch FDA 510(k) clearance compression timelines for electrochemical biosensors as inflection indicator for incumbent platform refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance secures ambulatory care network access across Bavarian diabetes clinics. |
| Hospital System Partnership | Texas and Florida IDN procurement consolidation favors single-vendor dual-analyte platform contracts. |
| Software Companion Development | FDA software-as-medical-device guidance compliance differentiates against hardware-only competitors. |
| Reimbursement Strategy | United States CMS coding expansion for Type 1 diabetes home testing reduces patient out-of-pocket friction. |
| Acquisition of Specialist Firm | Wearable interstitial fluid IP purchases bypass 200-subject German notified body trial requirements. |
Study Parameters
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare reimbursement filings underwrites the qualitative findings. Primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body guidance documents, and ISO 15197 performance standards. Bottom-up segment sizing and top-down market reconciliation triangulate volume and value estimates.
Rate-of-change decomposition across the projection horizon isolates technology adoption curves, reimbursement expansion trajectories, and regulatory timeline impacts. Segmentation dimensions modeled include product type, deployment architecture, end-user setting, and transduction technology. CAGRs derive from fitted growth curves against historical penetration patterns and forward-looking scenario weights. Industry-specific inputs encompass electrochemical biosensor miniaturization roadmaps and cloud connectivity security framework adoption rates.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in private-pay wellness segment transaction data introduce uncertainty bands around ketogenic diet optimization application sizing. Forecasts reflect documented assumptions regarding reimbursement expansion velocity and regulatory pathway compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Wireless Patient Monitoring Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
Dehydration Monitoring Systems Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
Global IOT Sensors in Healthcare Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
Global Smart Pulse Oximeters Market
Patient Monitoring
South Korea Patient Monitoring Market