
 United States Patient Monitoring Market | 2026-2036
United States Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
United States Patient Monitoring Market Analytics
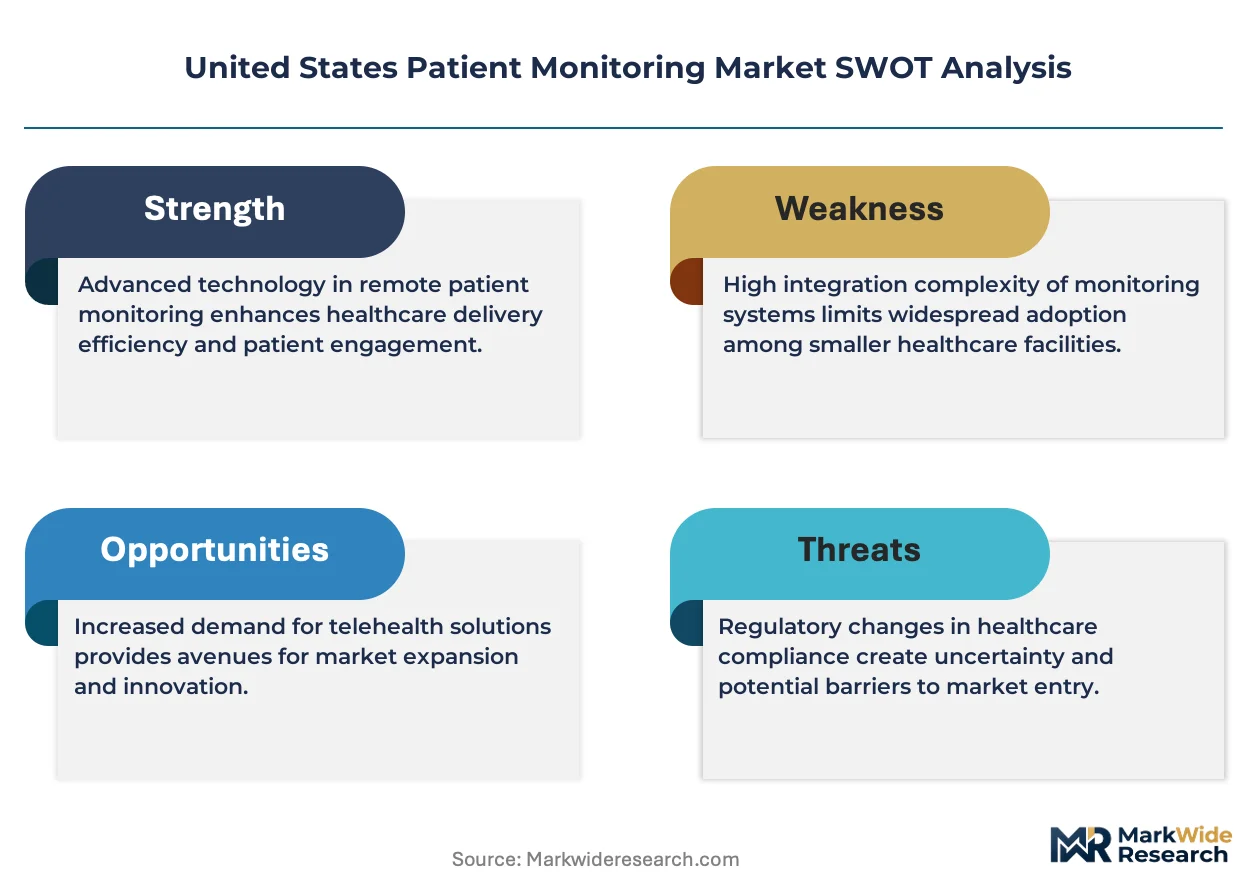
FDA 510(k) premarket notification volume for patient monitoring devices is expanding, raising compliance costs for new entrants while favoring incumbents with established quality management systems. Medtronic leverages its vertically integrated cardiac monitoring pipeline to sustain recurring revenue from implantable devices. Philips Healthcare anchors its position through enterprise-wide patient monitoring platforms that integrate with hospital IT infrastructure. GE Healthcare competes on monitoring hardware manufacturing scale and imaging-modality bundling.
Patient monitoring encompasses systems that acquire, process, and display physiological parameters including electrocardiography waveforms, pulse oximetry values, capnography readings, and invasive blood pressure measurements with sampling rates typically exceeding 250 Hz for cardiac applications. These devices serve primarily to enable early detection of clinical deterioration, guide therapeutic interventions, and reduce adverse events in acute and ambulatory care settings. Cardiac monitors and multi-parameter monitors represent the most mature revenue pools where replacement cycles and telemetry upgrades drive steady demand, while wearable and wireless deployment configurations capture the fastest expansion as health systems pursue continuous monitoring beyond traditional bedside settings. Cloud-based architectures are displacing on-premise installations among integrated delivery networks seeking centralized data analytics.
FDA digital health oversight, CMS hospital outpatient prospective payment rules, and HIPAA security requirements collectively determine product design priorities, reimbursement eligibility, and data architecture choices for manufacturers. The FDA's pre-certification pilot for software-based monitoring is shifting some validation burdens toward post-market surveillance. Stakeholders must track evolving interoperability mandates from the Office of the National Coordinator for Health IT that will condition market access on certified health data exchange capabilities.
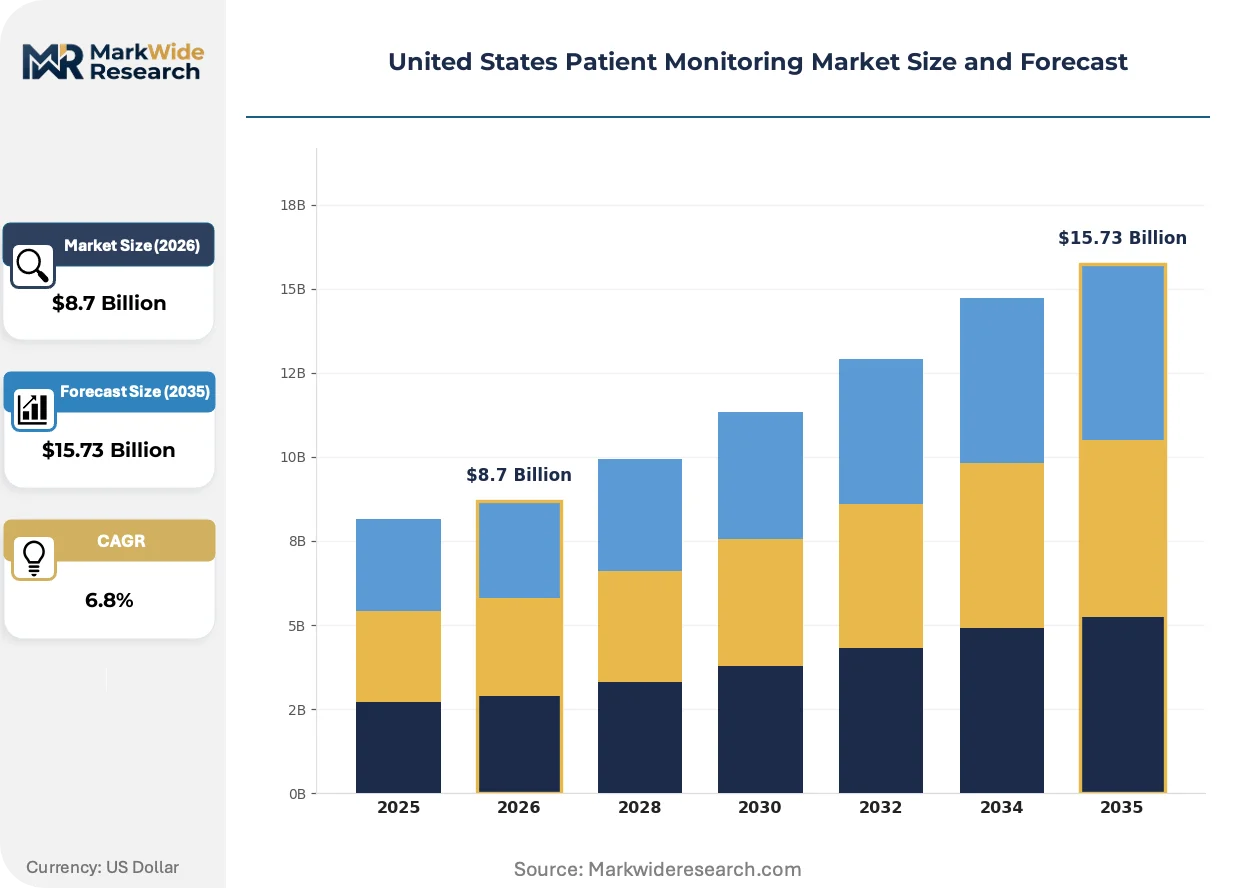
Market Dynamics
CMS value-based reimbursement penalties are compressing hospital margins and forcing capital reallocation toward remote patient monitoring infrastructure that prevents costly readmissions. This regulatory pressure is restructuring procurement priorities across integrated delivery networks.
Growth Catalysts
- Hospital Readmissions Reduction Program:CMS penalties for excessive 30-day readmissions are compelling health systems to deploy continuous monitoring solutions that flag deterioration before acute episodes require rehospitalization.
- FDA Pre-Certification Pilot:The agency's streamlined pathway for software-based monitoring devices is compressing time-to-market for algorithm-driven diagnostic tools and lowering validation burdens for qualified manufacturers.
- Texas-California-Florida demand concentration:Aging demographics and health system consolidation in these three states are generating disproportionate procurement volume for enterprise monitoring platforms.
Market Restraints
- Semiconductor component volatility:Patient monitors depend on specialized analog-to-digital converters and MEMS sensors whose supply concentrates among Asian foundries, exposing manufacturers to input cost swings and allocation constraints.
- Interoperability mandate friction:ONC certification requirements for health data exchange capabilities are forcing costly architectural redesigns for legacy device portfolios that lack modern API infrastructure.
- Substitution from consumer wearables:Apple Watch and similar devices with ECG and blood oxygen capabilities are capturing low-acuity monitoring demand that previously flowed to medical-grade hardware.
Strategic Opportunities
- Rural hospital telemedicine integration:Critical access hospitals in the Mountain West and Great Plains lack on-site intensivist coverage and represent underserved demand for centralized telemetry and automated early warning systems.
- AI-augmented alarm management:Machine learning algorithms that reduce false positive alerts are creating differentiation opportunities for vendors addressing alarm fatigue, which CMS now tracks as a patient safety metric.
- Home-based acute care expansion:CMS Hospital at Home waivers are extending reimbursement to remote monitoring for conditions traditionally requiring inpatient admission, opening new deployment configurations beyond facility walls.
Industry Challenges
- Biomedical engineering talent scarcity:Health systems face persistent shortages of technicians qualified to maintain networked monitoring infrastructure, forcing vendors to absorb training and remote support costs.
- EHR integration complexity:Epic and Cerner deployments vary significantly across health systems, requiring costly customization of device-to-record data pipelines that delay implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Patient Monitoring Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Monitors, Respiratory Monitors, Neuro Monitors, Multi-Parameter Monitors Deployment: Cloud-Based, On-Premise, Hybrid, Portable End User: Hospitals, Home Care, Ambulatory Surgical Centers, Nursing Homes Technology: Wireless, Digital, Wearable, Invasive |
| Companies Covered | Medtronic, Philips Healthcare, GE Healthcare, Masimo Corporation, Abbott Laboratories, Mindray, Welch Allyn, Dräger Medical, Nihon Kohden, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Patient Monitoring Market Evolving Landscape
Wireless and wearable form factors are redrawing the boundaries between acute and ambulatory monitoring, enabling physiological surveillance that follows patients across care settings rather than tethering them to bedside hardware.
Bluetooth Low Energy and ultra-wideband connectivity is decentralizing data acquisition from centralized nursing stations to distributed patient-worn sensors. Health systems in Texas and Florida are deploying these configurations for early mobility protocols in surgical recovery. The shift is compressing telemetry infrastructure spend while expanding continuous monitoring coverage to hallways, chairs, and transitional care units.
FDA's evolving guidance on artificial intelligence and machine learning in medical devices is creating compliance pathways for adaptive algorithms that improve with real-world use. The agency's predetermined change control plans allow manufacturers to update models without new 510(k) submissions. Cardiac monitoring and sepsis prediction algorithms are the first categories benefiting from this regulatory accommodation.
Health system purchasing committees are consolidating vendor relationships and demanding enterprise-wide platforms that standardize monitoring hardware across med-surg, ICU, and emergency departments. This concentration is displacing point-solution vendors who lack integrated device families. The pattern is most visible in California, where large systems like Kaiser Permanente and Sutter Health are reducing their supplier bases to simplify training, maintenance, and data analytics.
United States Patient Monitoring Market Segmentation
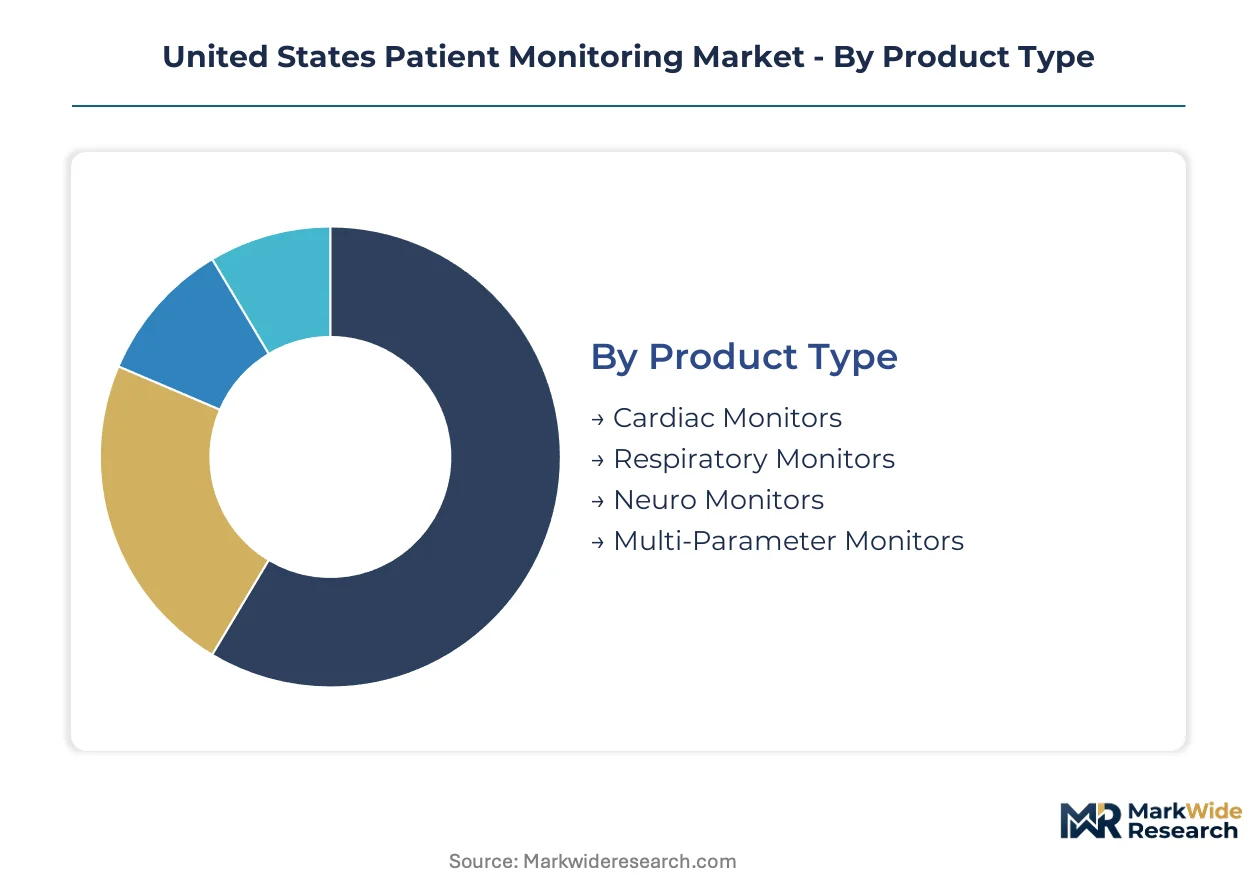
Segmentation in the United States patient monitoring market reveals how procurement priorities diverge across care settings and technology architectures. Hospital capital committees evaluate segments through distinct lenses: upfront infrastructure investment, interoperability requirements, and alignment with CMS reimbursement incentives.
Product Type:
Capital-intensity varies sharply across product categories, with implantable and enterprise-scale systems demanding the heaviest upfront investment while bedside devices operate on shorter replacement cycles.
- Cardiac Monitors:These systems capture electrocardiography waveforms at sampling rates exceeding 250 Hz, with telemetry-enabled configurations requiring dedicated wireless infrastructure. Demand concentrates in Florida and Texas health systems where aging cardiovascular patient volumes strain telemetry capacity. Medtronic and Philips dominate procurement through vertically integrated device and service bundles.
- Multi-Parameter Monitors:Integrated platforms simultaneously track ECG, pulse oximetry, capnography, and invasive blood pressure through modular architectures. California's consolidated delivery networks like Kaiser Permanente are standardizing enterprise-wide deployments to reduce training complexity and spare parts inventory.
- Respiratory Monitors:Capnography and spirometry devices for ventilator synchronization and sedation monitoring.
- Neuro Monitors:Intracranial pressure and electroencephalography systems for ICU neurology and trauma centers.
Most installed capacity flows through Cardiac Monitors. Expansion is steepest in Multi-Parameter Monitors.
Deployment:
Architectural choices increasingly hinge on health system scale and IT maturity, with cloud migration accelerating among integrated delivery networks seeking centralized analytics.
- Cloud-Based:SaaS architectures enable remote telemetry centers and AI-augmented alarm management without on-premise server farms. Texas Medical Center affiliates and Florida-based HCA facilities are migrating monitoring data lakes to cloud infrastructure to support predictive analytics initiatives. ONC interoperability mandates favor API-native cloud platforms over legacy client-server installations.
- Hybrid:Configurations blend edge computing for real-time waveform processing with cloud storage for longitudinal analytics. California health systems deploy hybrid models to satisfy HIPAA security requirements while enabling remote intensivist coverage for rural affiliates.
- On-Premise:Traditional server-based installations retained by critical access hospitals with limited IT bandwidth.
- Portable:Battery-powered monitors for intra-hospital transport and emergency response teams.
Cloud-Based deployments are gaining share fastest among multi-hospital systems. Hybrid architectures serve the longest tail of mid-size regional networks.
End User:
Customer-type segmentation exposes diverging procurement authority structures, with hospital purchasing committees wielding enterprise-scale budgets against fragmented home care decision-making.
- Hospitals:Acute care facilities drive the majority of capital expenditure through multi-year telemetry refresh cycles and enterprise platform consolidations. CMS Hospital Readmissions Reduction Program penalties are redirecting capital toward continuous monitoring infrastructure in Texas, California, and Florida med-surg units.
- Home Care:Post-acute and chronic disease management settings are expanding fastest under CMS Hospital at Home waivers. Florida's Medicare Advantage penetration and Texas's rural hospital closures are accelerating remote patient monitoring procurement for home-based acute care.
- Ambulatory Surgical Centers:Freestanding facilities with focused monitoring needs for procedural sedation and recovery.
- Nursing Homes:Long-term care operators facing staffing shortages and regulatory pressure for fall detection and vital sign surveillance.
Hospitals absorb the dominant share of monitoring capital. Home Care is climbing the fastest as reimbursement shifts toward site-neutral payment.
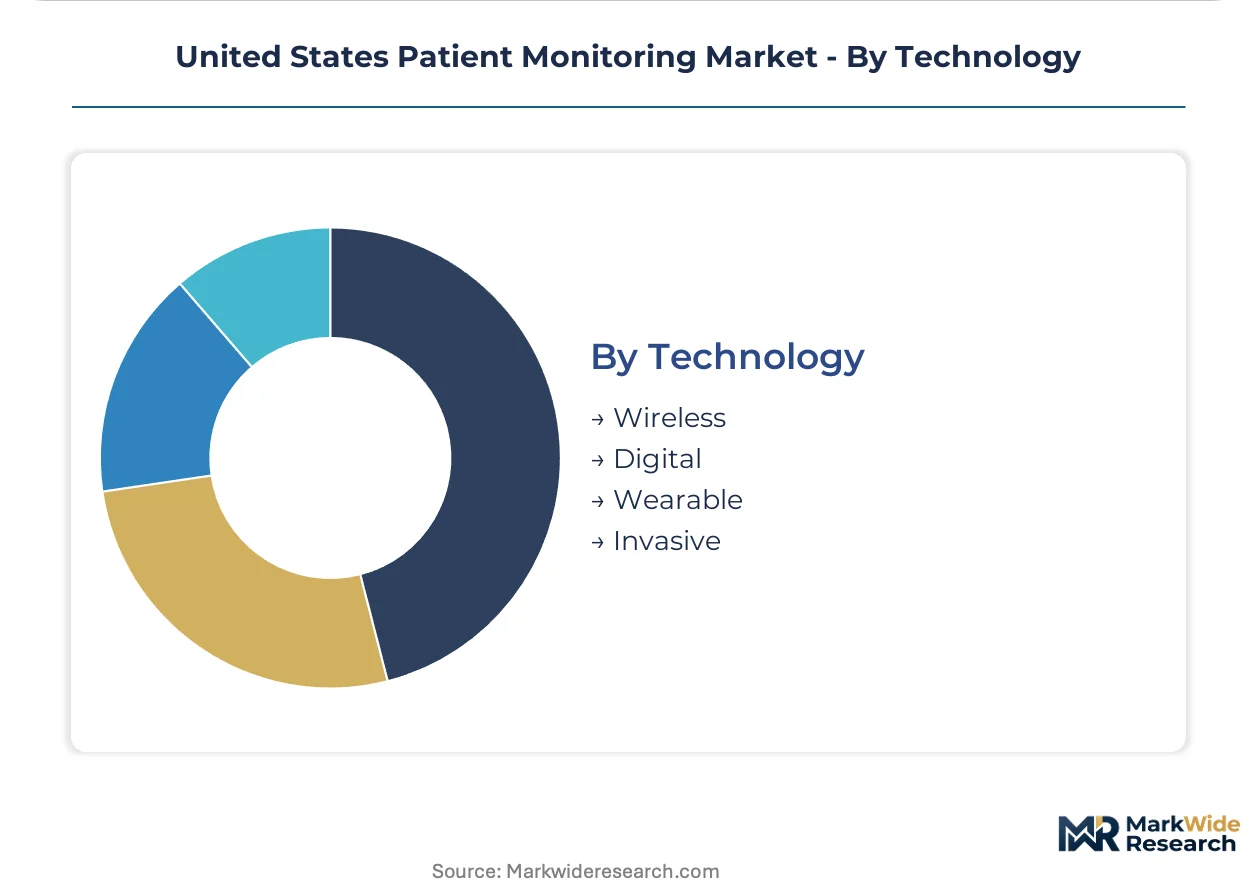
Technology:
Technology segmentation tracks the physical interface between patient physiology and data acquisition, with wireless and wearable form factors redrawing traditional boundaries between acute and ambulatory surveillance.
- Wireless:Bluetooth Low Energy and ultra-wideband connectivity decentralizes monitoring from nursing stations to patient-worn sensors. Texas and Florida health systems deploy wireless telemetry for early mobility protocols in surgical recovery, compressing infrastructure spend while expanding continuous coverage to hallways and chairs.
- Wearable:Patch-based and wrist-worn sensors enable physiological surveillance across care transitions. FDA's evolving software-as-a-medical-device guidance is clearing algorithm-driven wearables for cardiac arrhythmia detection, though clinical validation requirements favor established vendors over consumer electronics entrants.
- Digital:Software-defined monitoring platforms with algorithmic signal processing.
- Invasive:Catheter-based pressure and flow measurements for ICU hemodynamic management.
Wireless technology carries the largest installed base. Wearable configurations are expanding most quickly as health systems pursue monitoring beyond facility walls.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States patient monitoring industry traces its commercial origins to Minnesota's medical device corridor in the 1950s, where cardiac pacemaker innovation spawned the telemetry systems that now dominate hospital procurement. Texas, California, and Florida have since emerged as the primary demand centers, driven by aging demographics and health system consolidation.
Texas
The Texas Medical Center in Houston anchors the nation's largest concentration of hospital beds, driving enterprise-scale telemetry procurement for cardiac and multi-parameter monitoring systems. CMS Hospital Readmissions Reduction Program penalties have redirected capital toward continuous monitoring infrastructure in Dallas-Fort Worth med-surg units. San Antonio's military health system operates as a testbed for wearable deployment configurations in veteran rehabilitation settings.
California
Kaiser Permanente and Sutter Health are consolidating vendor relationships across their integrated delivery networks, standardizing monitoring hardware to reduce training complexity and spare parts inventory. FDA's pre-certification pilot for software-based devices has accelerated clearances for algorithm-driven diagnostic tools developed in Silicon Valley. The Los Angeles-Long Beach metro generates concentrated procurement volume for cloud-based telemetry platforms serving multi-hospital systems.
Florida
Medicare Advantage penetration and rural hospital closures are accelerating remote patient monitoring procurement for home-based acute care under CMS Hospital at Home waivers. HCA facilities are migrating monitoring data lakes to cloud infrastructure to support predictive analytics initiatives. The Tampa Bay and Miami metropolitan areas concentrate demand for wireless telemetry supporting early mobility protocols in surgical recovery.
Illinois
Chicago's academic medical centers drive demand for neuro monitoring systems in Level I trauma and ICU neurology applications. The state's central location supports distribution logistics for manufacturers serving the Midwest hospital market. Northwestern Medicine and Advocate Aurora are deploying hybrid cloud-edge architectures to satisfy HIPAA security requirements while enabling remote intensivist coverage for rural affiliates.
Massachusetts
Greater Boston's biotechnology cluster generates early-stage demand for next-generation wearable sensors and AI-augmented alarm management systems. Massachusetts General Hospital and Brigham and Women's Hospital operate as clinical validation sites for FDA software-as-a-medical-device clearances. The state's health IT infrastructure maturity attracts pilot deployments of Bluetooth Low Energy and ultra-wideband connectivity configurations.
United States Patient Monitoring Market Competitive Landscape
The competitive structure tilts toward vertically integrated conglomerates with established quality management systems and enterprise-wide platform capabilities. FDA 510(k) premarket notification volume is expanding, raising compliance costs for new entrants while favoring incumbents with decades of regulatory navigation experience. Three archetypes dominate: diversified medical technology conglomerates, pure-play monitoring specialists, and imaging-modality bundlers. M&A activity concentrates on software capabilities and AI algorithm portfolios, while strategic partnerships with cloud infrastructure providers accelerate SaaS migration timelines.
Among diversified medical technology conglomerates, Medtronic leverages its vertically integrated cardiac monitoring pipeline to sustain recurring revenue from implantable devices. Philips Healthcare anchors its position through enterprise-wide patient monitoring platforms that integrate with hospital IT infrastructure. GE Healthcare competes on monitoring hardware manufacturing scale and imaging-modality bundling, representing the scale-driven archetype in capital equipment procurement cycles.
| Leading Market Players |
|---|
| Medtronic |
| Philips Healthcare |
| GE Healthcare |
| Masimo Corporation |
| Abbott Laboratories |
| Mindray |
| Welch Allyn |
| Dräger Medical |
| Nihon Kohden |
| Others |
Value Network & Pricing Analysis
Specialized analog-to-digital converters and MEMS sensors flow from Asian foundries through tiered procurement channels, with FDA certification tiers separating premium enterprise platforms from standard bedside configurations and economy-grade portable units. Component volatility in semiconductor inputs compresses margins for manufacturers lacking long-term supply agreements while rewarding incumbents with captive sourcing relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with FDA 510(k) clearance status and enterprise-scale deployment volume serving as the primary differentiation drivers. Pricing pressure stems from CMS reimbursement compression and health system consolidation demanding standardized fleet pricing across multi-hospital networks. Critical access hospitals exhibit highest price sensitivity due to constrained capital budgets, while integrated delivery networks in Texas and California prioritize total cost of ownership over per-unit acquisition cost.
Supply Chain Analysis
Reverse-logistics flows for telemetry hardware refurbishment and implantable device explant recovery create secondary revenue streams for manufacturers with field service infrastructure. Component sourcing concentrates in Taiwan, South Korea, and Japan for specialized sensors and signal processors, with final assembly anchored in domestic facilities to satisfy FDA quality system requirements. Single-source vulnerability in analog-to-digital converter supply exposes manufacturers to allocation constraints during semiconductor demand surges. Distribution runs through group purchasing organizations and direct hospital contracts, with regional service depots supporting maintenance and calibration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas health systems face lower labor costs for biomedical engineering talent compared to California and Massachusetts, creating geographic arbitrage opportunities for vendors establishing remote technical support hubs.
For Market Incumbents: Cement enterprise-wide platform positions through backward integration into cloud infrastructure and AI algorithm development, defending against substitution from consumer wearable entrants by emphasizing FDA-cleared diagnostic accuracy and EHR interoperability. Prioritize certification investment in FDA's pre-certification pilot to compress competitor time-to-market advantages.
For New Entrants and Emerging Players: Begin with rural hospital telemedicine integration in the Mountain West and Great Plains, where intensivist coverage gaps create urgent demand for centralized telemetry and automated early warning systems. Target critical access hospitals through SaaS-based alarm management solutions that reduce upfront capital requirements and leverage remote technical support models.
For Investors and Strategic Acquirers: Consolidation pressure builds where software-defined monitoring platforms lack algorithmic differentiation and cloud-native architecture. Long-term viability favors targets with FDA-cleared AI portfolios and established health system pilot deployments. Monitor CMS Hospital at Home waiver permanence as inflection signal for home-based acute care infrastructure valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Enrollment | Accelerates algorithm-driven device clearances through streamlined post-market surveillance pathways. |
| Hospital System Partnership | Secures enterprise-wide standardization commitments from Kaiser Permanente and Sutter Health networks. |
| Cloud Infrastructure Migration | Enables predictive analytics for HCA facilities and Texas Medical Center affiliates. |
| AI-Augmented Alarm Management | Addresses CMS patient safety metrics and reduces false positive burden for nursing staff. |
| Reimbursement Strategy Development | Aligns remote monitoring deployment with CMS Hospital Readmissions Reduction Program incentives. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and FDA regulatory affairs specialists grounded this analysis, combined with secondary validation against FDA 510(k) filings, CMS Medicare cost reports, hospital procurement databases, and group purchasing organization contract disclosures. Bottom-up and top-down triangulation cross-validated segment-level demand estimates against health system capital expenditure patterns.
Bottom-up modeling of device replacement cycles, telemetry upgrade timelines, and remote monitoring deployment rates across the projection horizon anchored volume forecasts, while top-down reconciliation against health system IT capital budgets validated value projections. Segmentation dimensions included product type, deployment architecture, end-user setting, and wireless versus wearable technology form factors. CAGRs derived from historical procurement velocity adjusted for CMS reimbursement rule changes and FDA regulatory pathway evolution.
Several conditions sit outside the modeled scope, including unanticipated FDA guidance revisions, semiconductor supply disruptions exceeding historical volatility bands, and CMS site-neutral payment expansion beyond current waiver programs. Forecasts reflect assumptions regarding health system consolidation continuity and interoperability mandate implementation timelines. Practitioners should monitor FDA pre-certification pilot expansion, ONC API certification deadlines, and Medicare Advantage remote monitoring coverage determinations for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market
Patient Monitoring
Global Body Temperature Monitoring Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Global Vital Sign Monitoring Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
Global IOT Sensors in Healthcare Market
Patient Monitoring
Patient Monitoring Devices Market
Patient Monitoring
Online Patient Observation Market