
 Bio-Based Leather Market | 2026-2036
Bio-Based Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Leather Market Analysis
Automotive OEMs is unwinding traditional petrochemical hide contracts faster than apparel manufacturers, creating a demand rotation toward interior-grade bio-based substrates. MycoWorks leverages mycelium cultivation expertise to anchor supply relationships with luxury vehicle programs. Beyond Leather Materials specializes in apple-waste fiber formulations that compete on tensile performance against conventional synthetics. Modern Meadow sustains laboratory-scale collagen engineering that positions it for medical-adjacent leather applications.
Bio-based leather denotes engineered materials derived from agricultural biomass, fungal mycelium, or cultivated collagen matrices, processed through enzymatic tanning or mechanical felting to achieve specified abrasion resistance above 50,000 Martindale cycles and elongation-at-break parameters matching bovine hide. These materials serve as direct replacements for animal hides and polyurethane-coated fabrics in applications requiring soft-touch surfaces with verified lifecycle carbon footprints. Mushroom leather occupies the fastest-expanding margin pool as automotive interior specifications harden around volatile organic compound thresholds, while vegetable-tanned variants dominate current volume through established Italian and Portuguese tannery infrastructure. Piñatex commands premium positioning within accessories and small leather goods where fiber visibility functions as a design feature rather than a defect.
The EU Green Deal and REACH chromium restrictions are reshaping product standards by prohibiting hexavalent chromium in consumer goods, forcing reformulation across established tanning corridors. ECHA's evolving criteria for biodegradable material claims are tightening market access for partially synthetic blends that lack compostability certification. Stakeholders must monitor whether upcoming EU taxonomy classifications classify mycelium-derived substrates as fully circular inputs, a determination that would unlock green financing instruments for production scale-up decisions.
Market Dynamics
EU Green Deal mandates on chromium phase-outs are compressing traditional tanning capacity while redirecting capital toward enzymatic processing infrastructure. Automotive interior specifications on volatile organic compound thresholds are accelerating qualification timelines for mycelium-derived substrates.
Growth Catalysts
- REACH chromium restrictions:ECHA prohibitions on hexavalent chromium in consumer goods are forcing Italian and Portuguese tanneries to retool toward vegetable-tanning lines. This regulatory pressure is pulling demand toward certified bio-based alternatives.
- Luxury automotive procurement:German OEMs are embedding mycelium-based seat covers into next-generation vehicle programs as sustainability reporting requirements tighten under CSRD scope 3 disclosure rules.
- Pineapple leaf fiber processing:Mechanized decortication breakthroughs in the Philippines are reducing fiber preparation costs by half, expanding raw material availability for Piñatex-style formulations.
Market Restraints
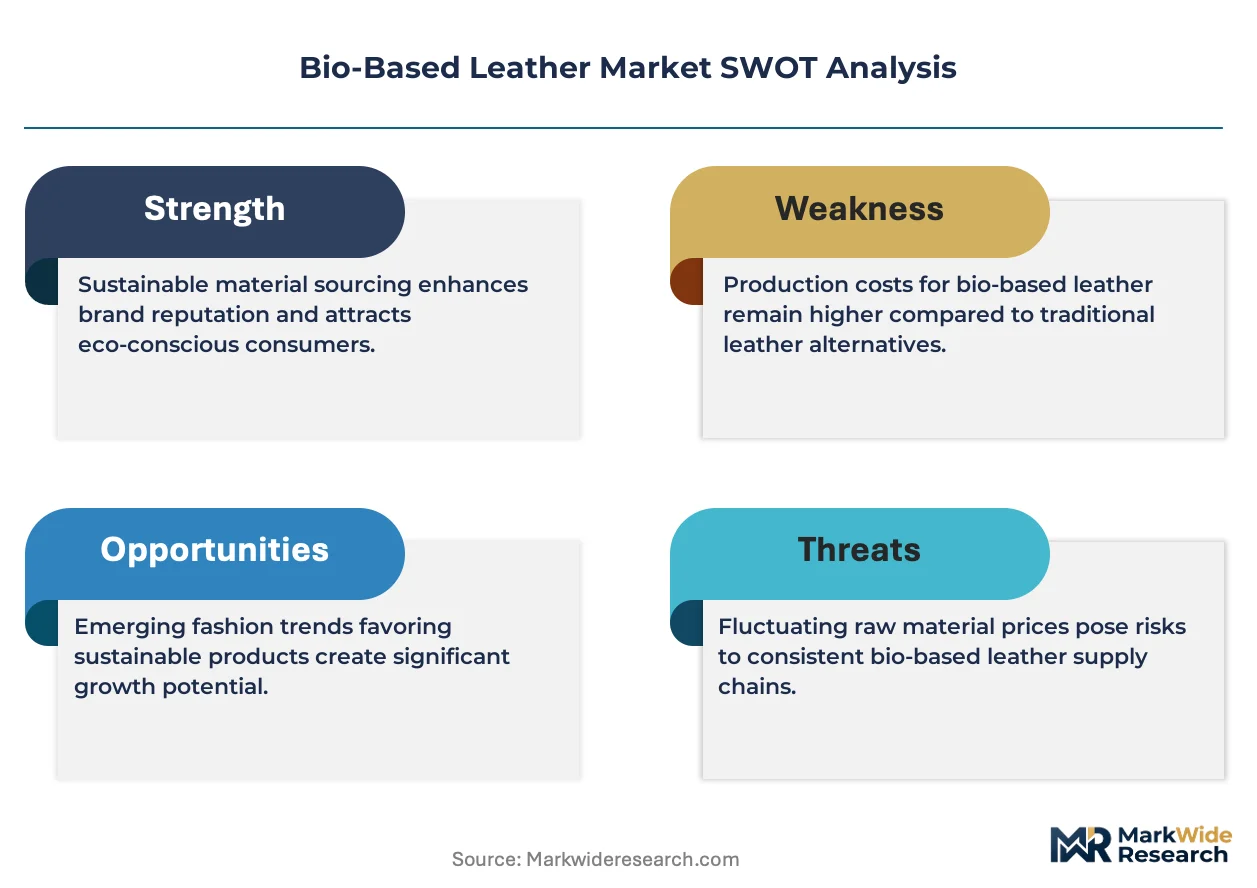
- Input cost volatility:Agricultural biomass feedstock prices fluctuate with weather patterns and competing food demand, compressing margin predictability for mycelium cultivators.
- Supply concentration risk:Mycelium spawn production concentrates in specialized Dutch and American biotechnology facilities, creating single-source vulnerability for scaled material programs.
- Performance certification gaps:Standardized abrasion testing protocols for bio-based substrates lag behind bovine hide benchmarks, delaying automotive tier-one approvals.
Strategic Opportunities
- Medical-adjacent applications:Laboratory-cultivated collagen matrices qualify for implantable device coatings under MDR Class III pathways, opening premium pricing tiers beyond consumer goods.
- EU taxonomy alignment:Pending circular economy classifications for fungal-derived materials would unlock green bond financing for production scale-up decisions.
- Direct-to-brand channels:Footwear makers in Milan and São Paulo are bypassing traditional tannery intermediaries to contract directly with bio-material processors for exclusive fiber formulations.
Industry Challenges
- Enzymatic tanning expertise scarcity:Formulation chemists with cross-training in biocatalysis and leather finishing are concentrated in legacy Italian industrial districts, limiting replication elsewhere.
- Compostability certification timelines:Industrial composting validation under EN 13432 requires 12-18 month testing cycles, delaying market access claims for new substrate launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Leather Market |
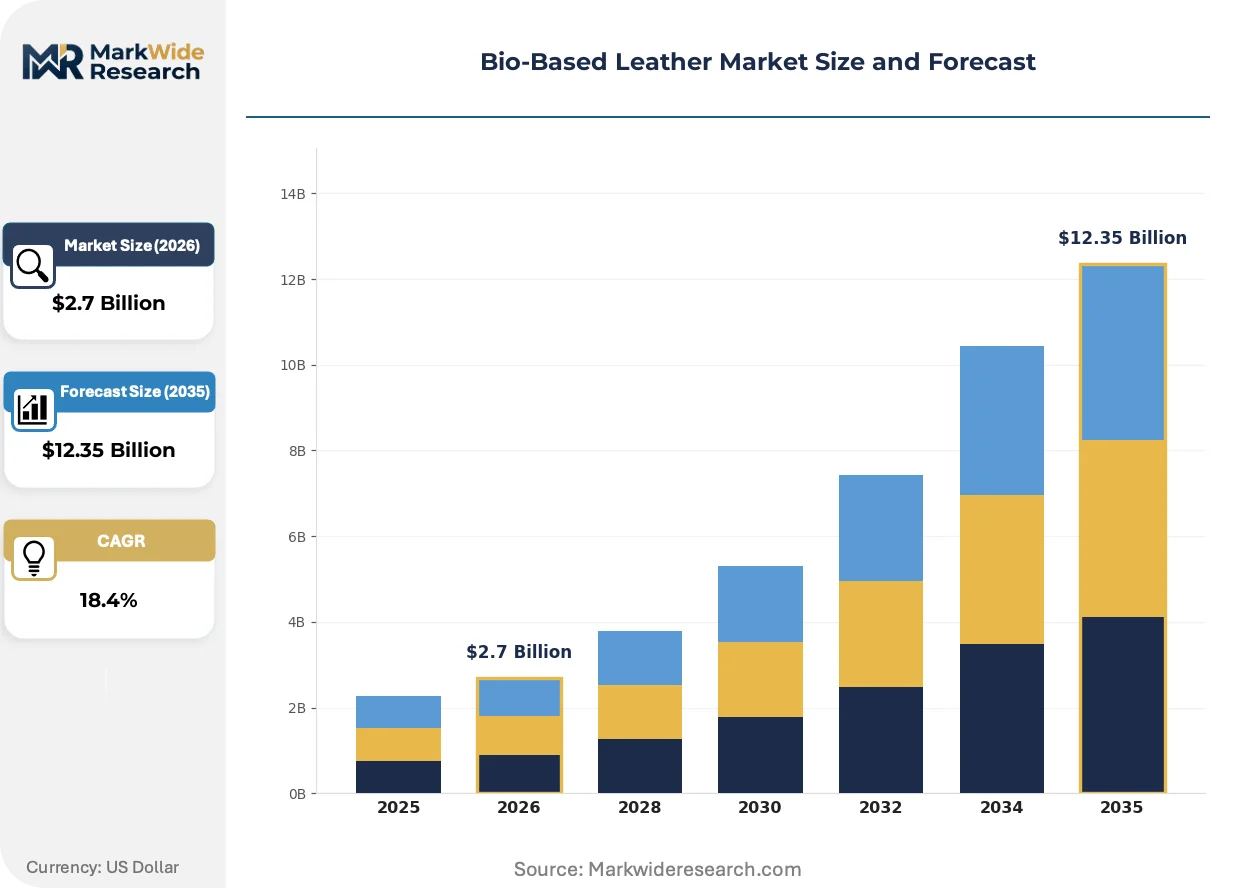
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $12.35 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Tanned, Mushroom Leather, Piñatex, Other Fiber-Based Application: Footwear, Accessories, Upholstery, Automotive Interiors End User: Retail, Apparel Manufacturers, Designers, Automotive OEMs Distribution Channel: Online Retail, Exclusive Stores, Wholesalers, Direct Sales |
| Companies Covered | Modern Meadow, Beyond Leather Materials, Natural Fiber Welding, Inc., VEGEA, Fruitleather Rotterdam, MycoWorks, Ananas Anam Ltd., Ecovative LLC, Bolt Threads Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Leather Market Emerging Trajectories
Processing technologies are converging with end-use specifications to compress development cycles. Material engineers now co-design with automotive interior teams from substrate conception rather than post-formulation qualification.
Mycelium cultivation systems are displacing traditional hide tanning in luxury vehicle programs. BMW and Mercedes-Benz procurement teams are qualifying Reishi-derived seat substrates for 2027 model year introductions. This displacement is compressing the addressable market for chromium-tanned automotive grades.
ECHA's evolving biodegradable material criteria are tightening compositional thresholds for synthetic blend content. Partially petroleum-derived substrates now face exclusion from compostability claims in German and French consumer goods. Premium accessories brands are responding by reformulating toward 100% bio-based fiber matrices.
Automotive OEMs are consolidating supplier relationships around vertically integrated bio-material processors. Direct contracting replaces multi-tier leather supply chains in German and Italian manufacturing clusters. This concentration is most visible in Bavaria and Piedmont, where seat assembly plants now source mycelium substrates from single-source cultivators with in-house finishing capability.
Bio-Based Leather Market Segmentation
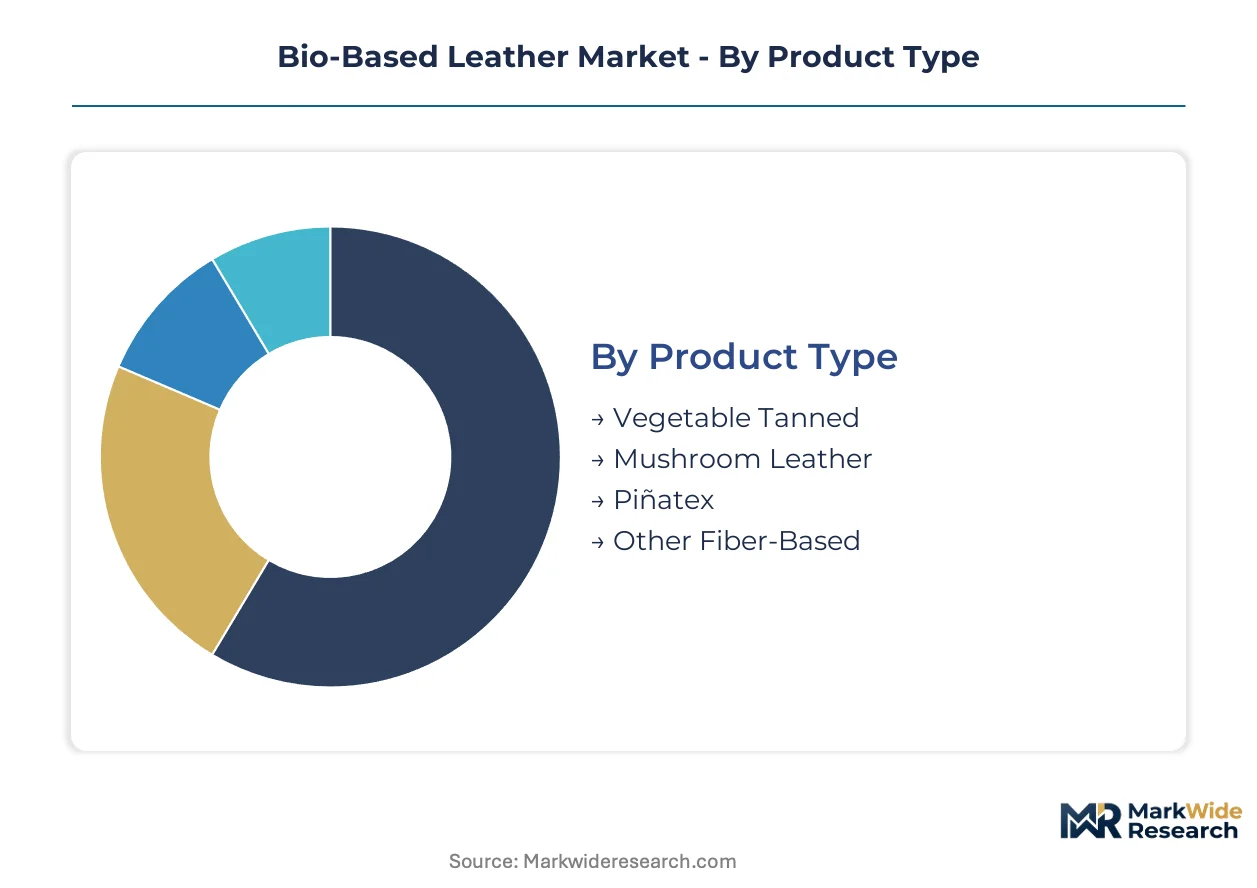
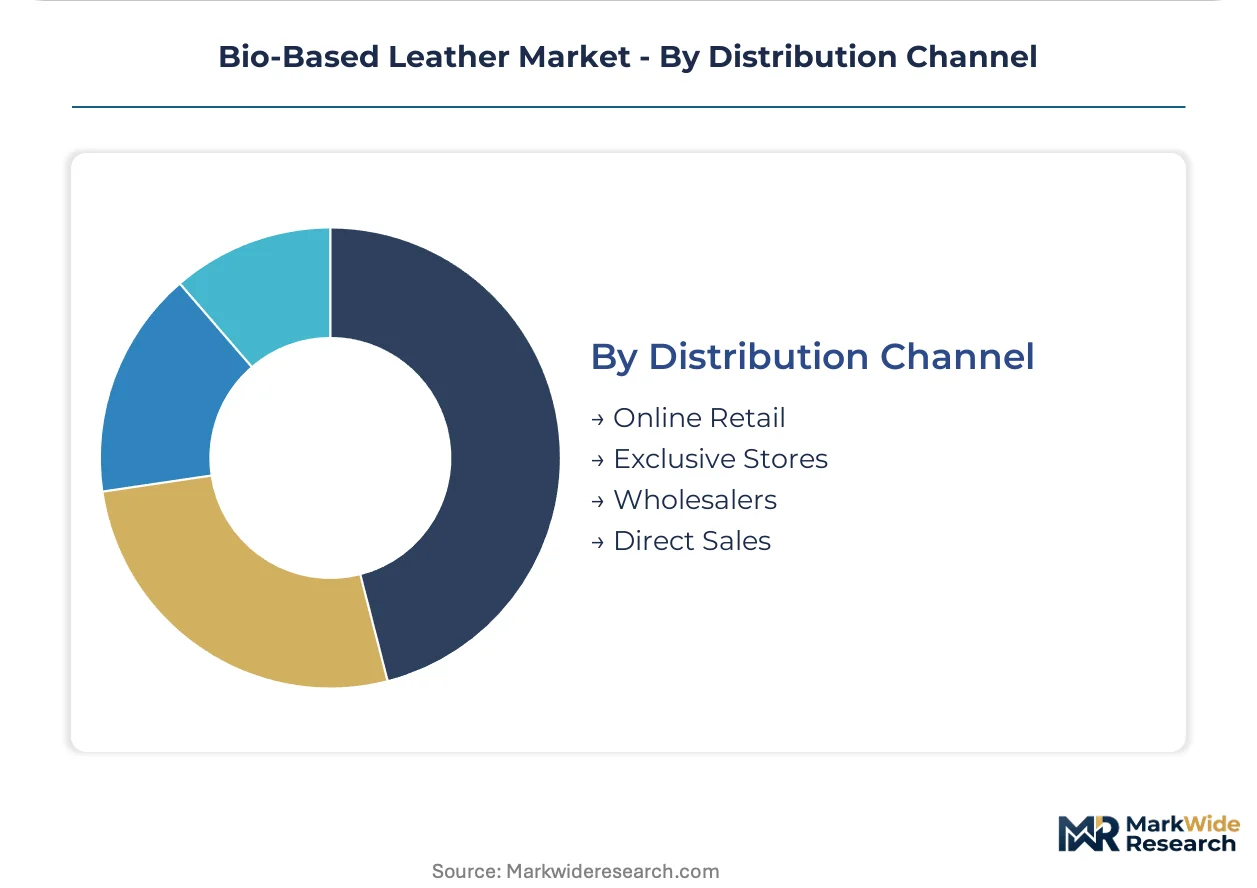
Segmentation in bio-based leather reveals how material specifications diverge across procurement channels. Channel selection directly determines which formulations achieve commercial scale versus niche positioning.
Product Type:
Channel access varies sharply by material chemistry—automotive OEMs source through qualified tier-one suppliers while accessories brands buy direct from cultivators.
- Mushroom Leather:Mycelium-derived substrates achieve specified abrasion resistance above 50,000 Martindale cycles through controlled cultivation in Dutch and American biotechnology facilities. German luxury automotive programs are consolidating procurement around single-source cultivators with in-house finishing capability. This segment is where expansion concentrates.
- Vegetable Tanned:Traditional plant-based tanning chemistry processes hides through quebracho and mimosa extracts in established Italian and Portuguese tannery infrastructure. REACH chromium restrictions are compressing traditional tanning capacity while redirecting capital toward enzymatic processing lines. This segment dominates installed base.
- Piñatex:Pineapple leaf fiber formulations from Philippine mechanized decortication supply premium accessories and small leather goods where fiber visibility functions as a design feature.
- Other Fiber-Based:Apple-waste and agricultural residue matrices compete on tensile performance against conventional synthetics in footwear applications.
Vegetable tanned materials dominate installed base. Mushroom leather is where expansion concentrates.
Application:
Cost tier stratification separates premium positioning from volume plays—automotive and luxury footwear command price premiums while upholstery faces commodity pressure.
- Automotive Interiors:Interior-grade bio-based substrates must meet volatile organic compound thresholds under tightening EU Green Deal mandates. BMW and Mercedes-Benz procurement teams are qualifying mycelium-derived seat substrates for next-generation vehicle programs.
- Footwear:Premium Italian footwear clusters in Milan and São Paulo are bypassing traditional tannery intermediaries to contract directly with bio-material processors for exclusive fiber formulations.
- Accessories:Small leather goods and bags utilize Piñatex fiber visibility as a deliberate aesthetic element rather than a quality compromise.
- Upholstery:Furniture applications face compressed margins as enzymatic tanning expertise scarcity limits supplier replication outside legacy Italian industrial districts.
Footwear commands premium pricing through direct-brand channels. Automotive interiors represent the steepest expansion trajectory as sustainability reporting requirements tighten under CSRD scope 3 disclosure rules.
End User:
Customer type determines contract structure—automotive OEMs demand multi-year supply agreements while designers purchase on spot markets.
- Automotive OEMs:German manufacturers embed sustainability mandates into procurement specifications, consolidating supplier relationships around vertically integrated bio-material processors with proven finishing capability.
- Apparel Manufacturers:Volume footwear producers in Portugal and Spain source vegetable-tanned variants through established tannery infrastructure for mid-market positioning.
- Designers:Independent creators in Milan and Paris access mycelium and fiber-based materials through direct-to-processor channels for limited-run collections.
- Retail:Consumer-facing brands face compostability certification timelines of 12-18 months under EN 13432, delaying market access claims for new substrate launches.
Automotive OEMs anchor premium demand. Apparel manufacturers represent volume scale potential as mechanized fiber processing reduces input costs.
Distribution Channel:
Supply concentration risk shapes channel selection—spawn production bottlenecks favor direct contracting over multi-tier distribution.
- Direct Sales:Single-source relationships between automotive seat assembly plants and mycelium cultivators eliminate intermediary margins in Bavaria and Piedmont manufacturing clusters.
- Wholesalers:Traditional leather merchants in Italian industrial districts aggregate vegetable-tanned volumes for fragmented footwear and accessories producers.
- Exclusive Stores:Premium accessories brands in Paris and London operate flagship retail to communicate fiber provenance and sustainability credentials.
- Online Retail:Direct-to-consumer channels serve designer and independent creator segments with small-batch bio-based materials.
Wholesalers dominate legacy volume flows. Direct sales channels are gaining share fastest as automotive OEMs unwind traditional petrochemical hide contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philippine pineapple leaf fiber exports supply European accessories manufacturers while Dutch mycelium spawn moves into German automotive supply chains. Italian tanneries retool enzymatic lines to capture displaced chromium-tanned volumes. These three trade corridors define regional competitive positioning.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg consolidate procurement around single-source mycelium cultivators for 2027 vehicle programs. REACH chromium restrictions under ECHA enforcement compress traditional tanning capacity. Stuttgart and Munich seat assembly plants now source bio-based substrates through direct contracting rather than multi-tier leather merchants.
Italy
Premium footwear clusters in Milan and Tuscany bypass traditional tannery intermediaries for exclusive fiber formulations. The EU Green Deal mandates phase-outs of hexavalent chromium in consumer goods. Piedmont's vegetable-tanning infrastructure redirects capital toward enzymatic processing lines as Portuguese competitors capture mid-market volume.
Netherlands
Specialized biotechnology facilities in the Randstad concentrate mycelium spawn production for scaled material programs. ECHA's evolving biodegradable material criteria tighten compositional thresholds for synthetic blend content. Dutch cultivators with in-house finishing capability anchor supply relationships with luxury automotive OEMs across the border.
Philippines
Mechanized decortication breakthroughs in pineapple-growing regions reduce fiber preparation costs by half. The country's agricultural processing sector expands raw material availability for Piñatex-style formulations. Philippine leaf fiber exports supply premium accessories brands in Paris and London where fiber visibility functions as deliberate aesthetic design.
France
Paris-based accessories brands operate flagship retail to communicate fiber provenance and sustainability credentials. CSRD scope 3 disclosure rules tighten sustainability reporting requirements for luxury goods manufacturers. French consumer goods face exclusion from compostability claims under ECHA criteria if synthetic blend content exceeds tightening thresholds.
Bio-Based Leather Market Vendor Landscape
Player mix skews toward biotechnology cultivators with materials science capabilities rather than traditional tannery operators. The vendor base separates into three tiers: mycelium specialists with automotive qualification, agricultural fiber processors with mechanized decortication, and enzymatic tanning chemists concentrated in legacy industrial districts. Competitive moves center on backward integration into spawn production and direct-to-brand contracting that eliminates intermediary margins.
Among mycelium-focused cultivators, MycoWorks and Ecovative LLC represent the biotechnology archetype with controlled cultivation systems. Modern Meadow occupies a position within laboratory-scale collagen engineering for medical-adjacent applications. These three exemplify how player mix concentrates around fungal-derived substrates rather than hide-tanning incumbents.
| Leading Market Players |
|---|
| Modern Meadow |
| Beyond Leather Materials |
| Natural Fiber Welding, Inc. |
| VEGEA |
| Fruitleather Rotterdam |
| MycoWorks |
| Ananas Anam Ltd. |
| Ecovative LLC |
| Bolt Threads Inc. |
| Others |
Supply Flow & Price Mechanics
Mycelium substrate substitution for chromium-tanned automotive hides simultaneously relocates production toward Dutch biotechnology facilities and compresses margin premiums previously captured by Italian tannery intermediaries. This displacement redirects pricing power toward cultivators with captive spawn production and in-house finishing capability.
Pricing Analysis
Next-generation mycelium formulations command substantial premiums over established vegetable-tanned grades and legacy petroleum-based synthetics. Three-tier pricing structure across premium, standard, and economy levels stratifies by abrasion certification tier and automotive qualification status. Pricing pressure stems from Philippine pineapple fiber mechanization reducing input costs for mid-market accessories. Automotive OEMs exhibit lowest price sensitivity due to CSRD disclosure mandates, while furniture upholstery buyers face acute margin compression.
Supply Chain Analysis
The Netherlands and United States anchor mycelium spawn production for scaled automotive programs. Philippine agricultural processing supplies pineapple leaf fiber, while Italian enzymatic tanning chemistry serves premium footwear clusters. Raw material flows draw from Dutch biotechnology facilities, Philippine decortication plants, and established Mediterranean tannery infrastructure. Single-source vulnerability concentrates in specialized spawn cultivators. Distribution runs through direct contracting between automotive seat assembly plants and integrated bio-material processors, bypassing traditional leather merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal chromium phase-outs and REACH enforcement create a high-growth disruption window as regulatory mandates forcibly displace legacy tanning capacity. This technological-regulatory inflection compresses incumbent repositioning timelines while opening white-space for qualified substitutes.
For Market Incumbents: Fortify enzymatic processing capabilities through backward integration into biocatalysis R&D and captive vegetable extract supply. Italian tannery operators must accelerate retooling timelines before Portuguese competitors capture mid-market volume. Certification investment in EN 13432 compostability pathways defends positioning against emerging mycelium specialists.
For New Entrants and Emerging Players: EN 13432 compostability fast-track offers regulatory differentiation for fiber-based formulations targeting accessories brands. White-space concentrates in medical-adjacent collagen matrices where MDR Class III pathways justify premium pricing. Direct-to-brand contracting with Milan footwear clusters bypasses entrenched tannery distribution.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Dutch biotechnology cultivators possessing automotive qualification and in-house finishing infrastructure. Five-to-ten year viability hinges on EU taxonomy circular economy classification unlocking green financing. The signal to watch is ECHA's final determination on mycelium substrate compositional thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spawn Production | Captive mycelium cultivation eliminates single-source vulnerability for automotive tier-one suppliers. |
| EN 13432 Compostability Certification | Industrial composting validation unlocks premium positioning in German and French consumer goods. |
| Direct-to-Brand Contracting | Bypassing tannery intermediaries captures margin previously allocated to Italian leather merchants. |
| Automotive Qualification Programs | BMW and Mercedes-Benz seat substrate approvals establish reference credibility for tier-one procurement. |
| Medical-Adjacent Collagen Development | MDR Class III implantable device coatings open pricing tiers beyond consumer applications. |
Methodological Framework
Desk research of ECHA regulatory filings, EU Green Deal implementation documents, and automotive OEM sustainability disclosures preceded structured interviews with bio-material processors, enzymatic tanning chemists, tier-one automotive suppliers, and luxury footwear procurement leads. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of publicly listed material companies, and industry association production statistics. Bottom-up volume modeling triangulated against top-down market sizing across segmentation dimensions.
Variance decomposition separates volume growth from pricing trajectory across the projection horizon. Segmentation modeling incorporates material chemistry, application end-use, customer contract structure, and regional regulatory cluster. CAGRs derive from regression analysis of historical procurement patterns and forward assessment of automotive program adoption curves. Forecast inputs include mechanized fiber processing cost curves and ECHA enforcement timelines.
Decision-makers should treat outputs as directional under sustained REACH chromium restriction enforcement and EU taxonomy circular economy classification assumptions; material deviation would warrant model refresh. Recalibration cycles align with regulatory determination milestones and automotive program qualification announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Injectable Nanomedicine Market
Others
TWS Micro-Battery Market
Others
United States Cigarette Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Europe Postal Services Market
Others
Versatile Video Coding Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Metal Air Battery Market
Others
Storage Dewars Market
Others
Latin America Fire Sprinklers Market
Others
Advanced Combat Helmet Market
Others
Thermal Energy Flow Metering Solutions Market
Others
Billet Market
Others
Profilometer Market
Others
Global Cigarette Packaging Market
Others
Smart Home Technologies Market