
 Dental Ceramics Market | 2026-2036
Dental Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Ceramics Market Analysis
High-translucency zirconia is collapsing the price premium once commanded by layered porcelain restorations. Kyocera Corporation leverages its fine-ceramics heritage to dominate Japanese supply chains for dental-grade alumina substrates. Straumann anchors European demand through vertically integrated milling center networks. CeramTec GmbH specializes in medical-grade zirconia formulations that differentiate its output from commodity industrial ceramics.
Dental ceramics are inorganic, non-metallic materials—typically zirconia, alumina, or lithium disilicate glass-ceramics—sintered at temperatures exceeding 1,350°C to achieve flexural strengths above 900 MPa and tailored optical properties matching natural dentition. CAD/CAM technology leads production volume by enabling same-day chairside restorations, while 3D printing represents the fastest-growing fabrication method for complex bridge frameworks. Porcelain retains mature share in anterior veneer applications where translucency requirements are most demanding.
The FDA regulates dental ceramics under Class II medical device pathways requiring 510(k) clearance for permanent implantation, while ISO 6872 sets international mechanical and biocompatibility benchmarks that gate export access. The EU Medical Device Regulation imposes stricter clinical evidence requirements on zirconia implant abutments than preceding directives. Stakeholders must monitor evolving reimbursement codes for chairside milling versus laboratory-fabricated restorations, as payor policy increasingly dictates technology selection.
Market Dynamics
CAD/CAM chairside milling is collapsing the traditional laboratory outsourcing model as dental clinics invest in same-day restoration capability, compressing fabrication timelines from two weeks to under two hours and reshaping value capture across the supply chain.
Growth Catalysts
- ISO 6872 compliance mandates:International mechanical and biocompatibility benchmarks are gating export access for Asian manufacturers, forcing quality upgrades that expand addressable market share for certified producers in Germany and Japan.
- Digital workflow integration:Intraoral scanner penetration in North American and European dental practices is accelerating ceramic restoration volume by eliminating physical impression bottlenecks and reducing remake rates.
- High-translucency zirconia formulations:Advanced sintering protocols are enabling monolithic restorations that match layered porcelain aesthetics, opening anterior applications previously reserved for glass-ceramics.
Market Restraints
- Yttria supply concentration:Rare earth processing for dental-grade zirconia stabilizers concentrates in Chinese refining operations, exposing raw material costs to export quota volatility and geopolitical friction.
- Sintering furnace energy intensity:Kiln operations exceeding 1,350°C require substantial electricity inputs, with European energy price spikes compressing margins for independent laboratories lacking renewable power purchase agreements.
- Polymer-based provisional restorations:3D-printed resin interim crowns are extending acceptable temporary lifespans, delaying permanent ceramic placement in price-sensitive patient segments.
Strategic Opportunities
- Indian dental tourism corridors:Mumbai and Bangalore are emerging as ceramic restoration fabrication hubs for Middle Eastern and African patients seeking cost arbitrage on complex bridge work.
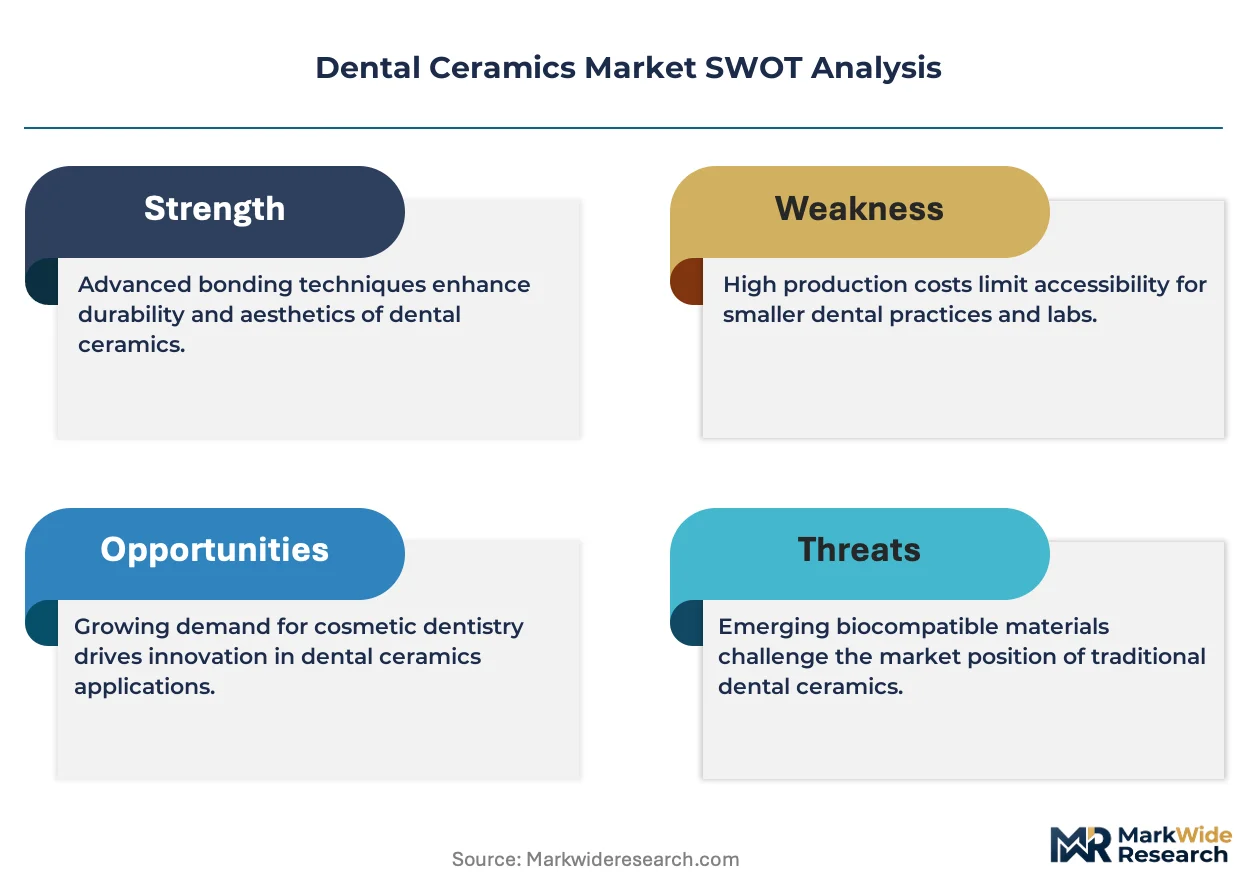
- EU MDR clinical evidence pathways:Stricter documentation requirements for zirconia implant abutments are creating first-mover advantages for manufacturers with pre-existing clinical trial databases.
- AI-powered shade matching:Machine vision systems integrated with spectrophotometers are converging with CAD software to automate aesthetic prescription translation, reducing technician skill barriers.
Industry Challenges
- CAD/CAM technician certification gaps:Chairside milling adoption outpaces accredited training programs, leaving clinics dependent on manufacturer field support for complex case troubleshooting.
- Biocompatibility testing timelines:FDA 510(k) clearance for novel ceramic compositions requires extended cytotoxicity and sensitization studies, stretching product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Ceramics Market |
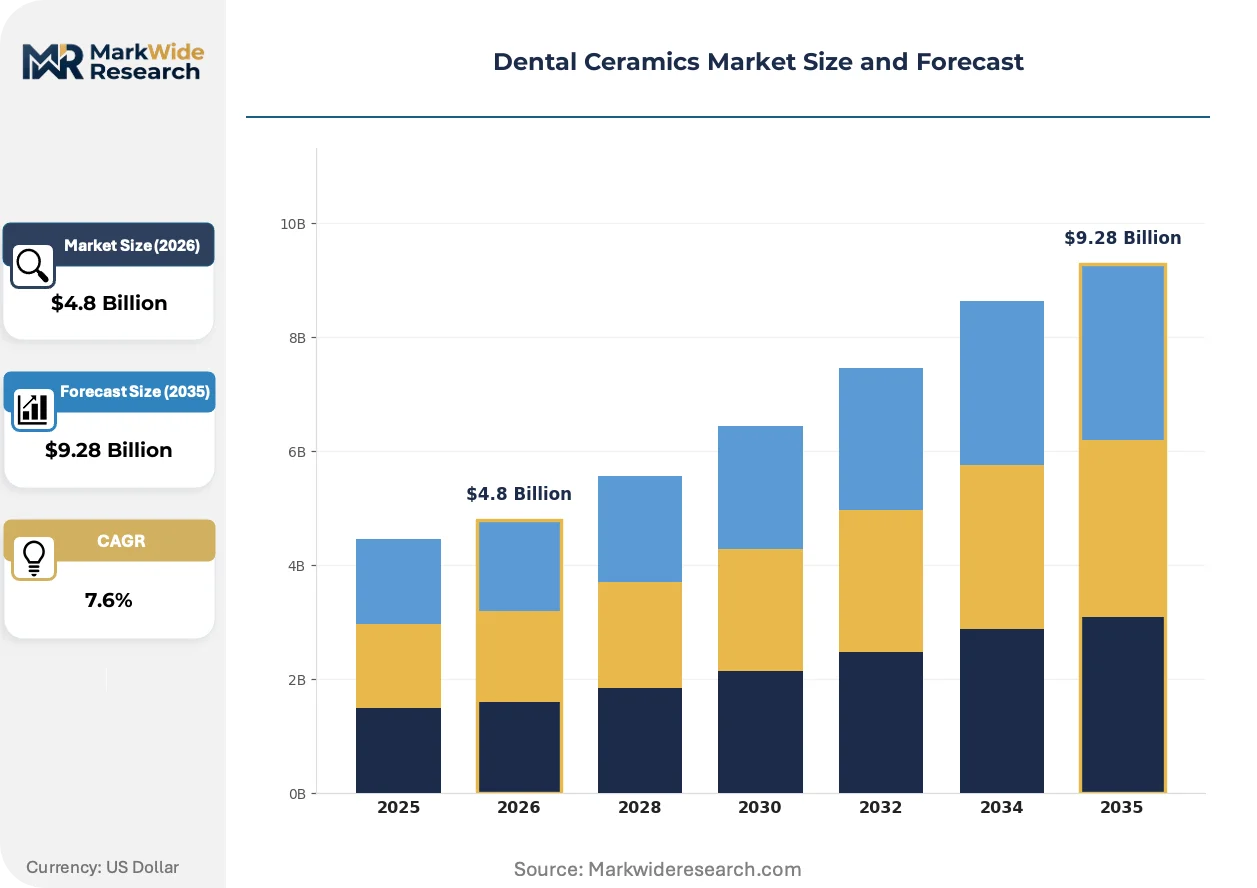
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Alumina, Zirconia, Glass-ceramics End User: Dental Clinics, Laboratories, Hospitals, Dental Schools Application: Crowns, Bridges, Inlays, Veneers Technology: CAD/CAM, Sintering, 3D Printing, Pressing |
| Companies Covered | Kyocera Corporation, Saint-Gobain Ceramic Materials, CeramTec GmbH, Zimmer Biomet Holding Inc., NGK Spark Plug Co., Ltd., CoorsTek, Inc., Morgan Advanced Materials, Straumann, 3M Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Ceramics Market Emerging Trajectories
Material science breakthroughs and regulatory tightening are simultaneously expanding performance boundaries and raising compliance thresholds, forcing reinvestment across manufacturing footprints and quality systems.
Multi-layer gradient zirconia is decomposing the traditional premium-mid-economy material hierarchy by delivering esthetic depth without hand-layered porcelain veneering. German and Swiss dental laboratories are adopting these pre-shaded blanks at accelerating velocity. The technology is compressing technician labor hours per unit while collapsing the price spread between monolithic and layered restoration categories.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data for zirconia implant components, a significant escalation from prior directive obligations. Manufacturers must now maintain active implant registries or face notified body audit failures. Zirconia abutment suppliers with limited European installed bases are exiting the market rather than absorbing compliance infrastructure costs.
Dental group purchasing organizations are consolidating procurement authority across multi-clinic networks, displacing individual practitioner material selection autonomy. Suppliers now negotiate directly with DPO administrators who standardize on single-source ceramic systems. This concentration is most visible in US metropolitan markets where private equity-backed dental platforms control substantial restoration volume.
Dental Ceramics Market Segmentation
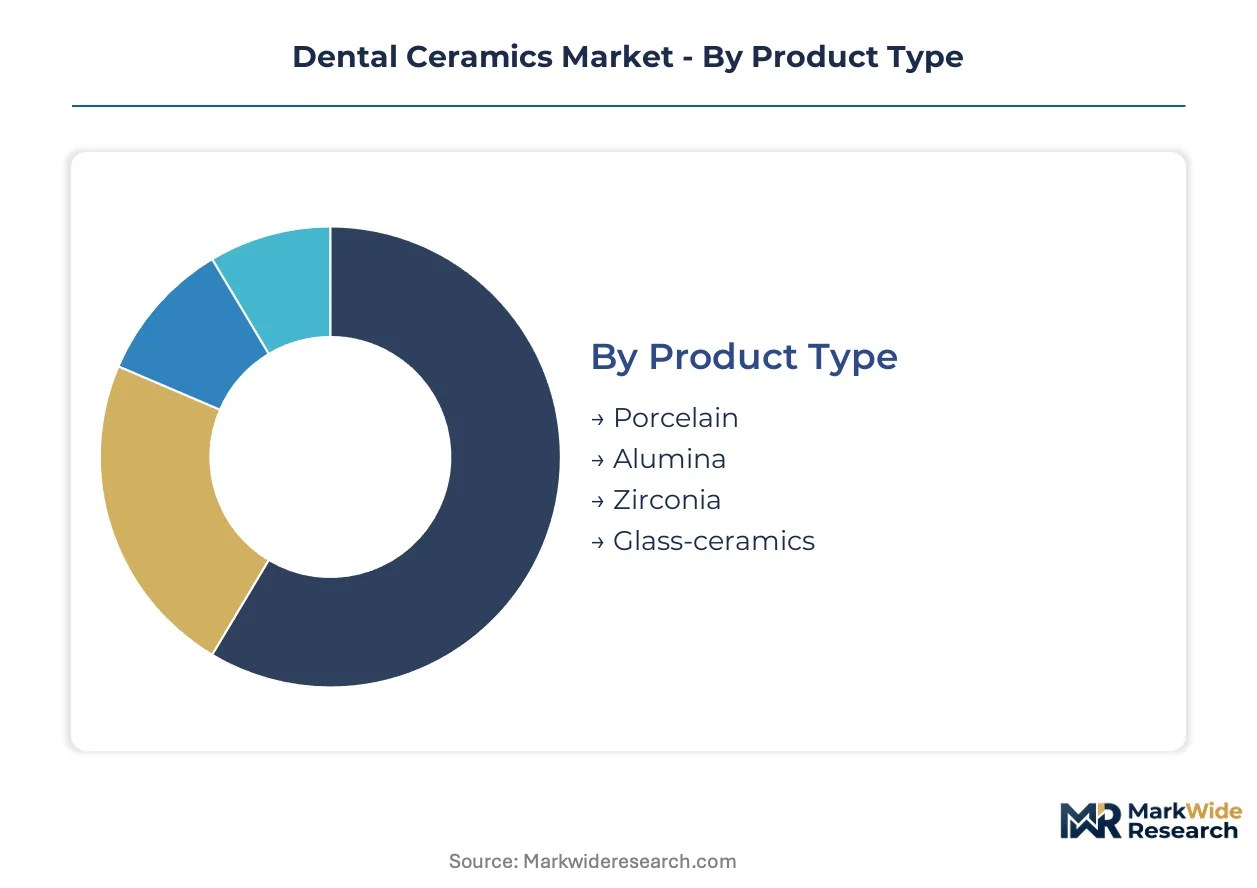
Dental ceramics segmentation reveals distinct channel economics. Material chemistry determines laboratory versus chairside routing. Technology choice separates same-day delivery from two-week outsourcing cycles. End-user concentration in Germany and Japan shapes premium segment development.
Product Type:
Channel mix varies sharply by material. Zirconia and glass-ceramics flow predominantly through CAD/CAM-enabled clinics for same-day placement. Porcelain and alumina retain stronger laboratory dependency due to layering and custom shading requirements.
- Zirconia:Yttria-stabilized tetragonal polycrystals deliver flexural strengths exceeding 900 MPa. Demand concentrates in German milling centers around Stuttgart for multi-unit bridge frameworks, driven by ISO 6872 certification requirements gating export access.
- Glass-ceramics:Lithium disilicate formulations offer tailored translucency matching natural dentition. Japanese dental clinics in Tokyo and Osaka prioritize this material for anterior veneer applications where aesthetic demands are most stringent.
- Porcelain:Feldspathic and leucite-reinforced compositions remain the reference standard for layered restorations requiring technician hand-craftsmanship.
- Alumina:High-purity alumina substrates serve specialized implant abutment applications where biocompatibility testing timelines extend FDA 510(k) pathways.
By volume, zirconia leads. By growth pace, glass-ceramics is expanding most quickly.
End User:
Cost tier separation distinguishes procurement patterns. Dental clinics capture premium pricing for chairside convenience. Laboratories compete on unit economics for complex bridge work.
- Dental Clinics:Chairside milling investments enable same-day restoration delivery, compressing patient visit counts and capturing value previously flowing to outsourced laboratories.
- Laboratories:German facilities cluster around Munich for access to CeramTec GmbH zirconia formulations, maintaining quality differentiation through technician certification programs.
- Hospitals:Academic medical centers integrate dental ceramics within broader oral surgery workflows, prioritizing implant abutment supply security over per-unit cost minimization.
- Dental Schools:Training institutions standardize on specific ceramic systems to simplify curriculum delivery and equipment procurement.
Procurement authority is shifting toward dental group purchasing organizations, eroding individual practitioner autonomy across all tiers.
Application:
Volume concentration follows restoration complexity. Single-unit crowns dominate fabrication throughput. Multi-unit bridges command premium pricing per tooth equivalent.
- Crowns:Monolithic zirconia formulations displace porcelain-fused-to-metal in posterior applications, driven by biocompatibility preferences and metal-free marketing.
- Bridges:Three-unit and longer span frameworks require high-translucency zirconia or layered porcelain to manage flexural stress across pontic spans.
- Veneers:Minimal-preparation lithium disilicate restorations concentrate demand in aesthetic-focused practices serving affluent patient segments.
- Inlays:Conservative cavity preparations favor glass-ceramic or composite alternatives over full-coverage ceramic crowns.
Bridge work generates highest revenue per case. Crown volume sustains manufacturing scale.
Technology:
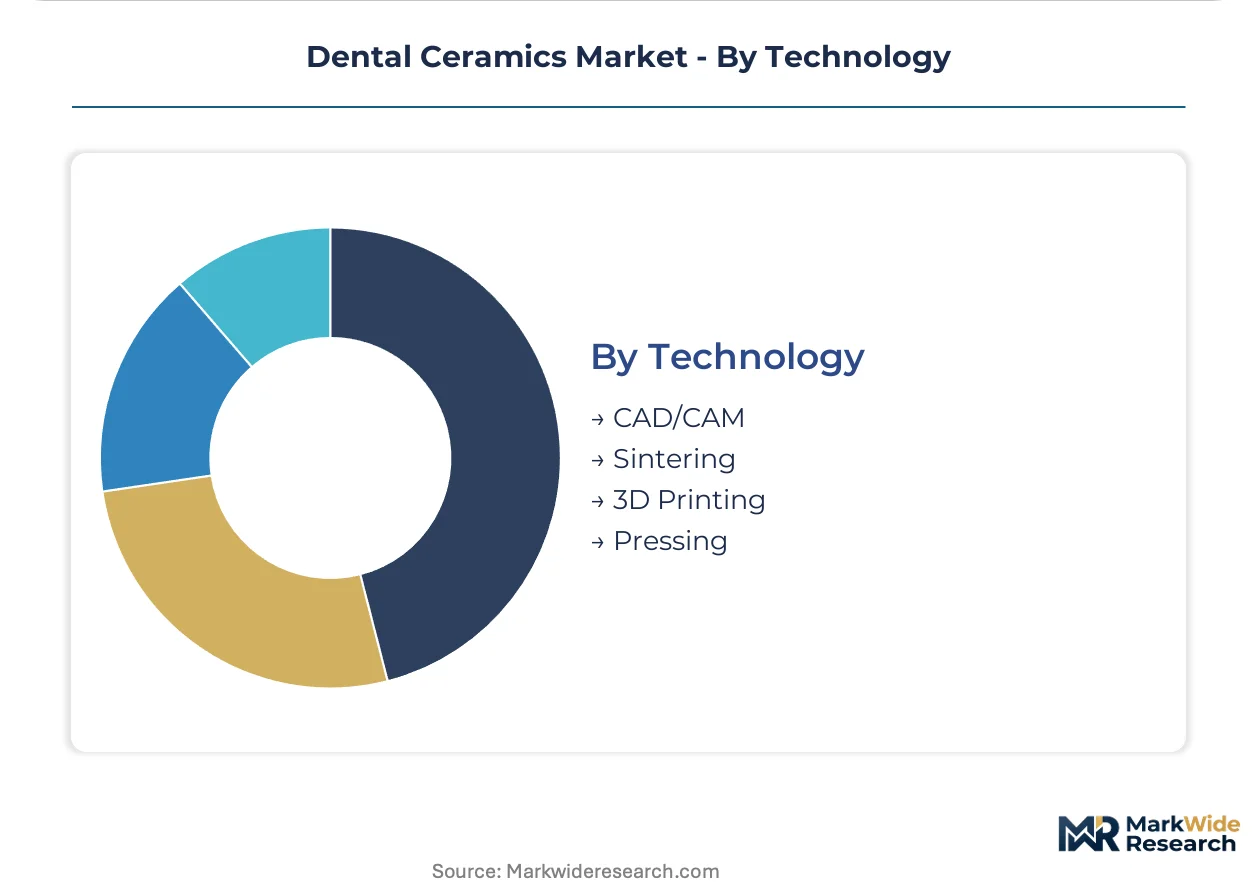
Maturity curves separate established from emerging fabrication methods. Sintering and pressing represent baseline capabilities. Additive methods are climbing the fastest.
- CAD/CAM:Intraoral scanner integration with chairside milling units eliminates physical impression bottlenecks, reducing remake rates and accelerating cash conversion cycles.
- Sintering:Furnace operations exceeding 1,350°C consume substantial electricity, with European energy price spikes compressing margins for independent laboratories lacking renewable power purchase agreements.
- 3D Printing:Photopolymer and binder-jet methods for ceramic-filled resins enable complex bridge framework geometries impractical for subtractive milling.
- Pressing:Heat-pressed glass-ceramic ingots retain share in anterior applications where technician-controlled crystallization optimizes optical properties.
CAD/CAM dominates current throughput. 3D printing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German clinics absorb premium zirconia costs through statutory reimbursement frameworks, while Indian patients drive demand for cost-optimized glass-ceramic alternatives. Brazil's private dental insurance expansion creates mid-tier volume concentration between these extremes.
Germany
Dental laboratories around Stuttgart and Munich cluster for access to ISO 6872-certified zirconia supply chains. The EU Medical Device Regulation imposes stricter clinical evidence requirements on implant abutments than preceding directives. Baden-Württemberg facilities dominate multi-unit bridge fabrication for export markets.
United States
Private equity-backed dental platforms consolidate procurement authority across metropolitan networks, standardizing ceramic system selection. FDA 510(k) clearance pathways for novel compositions require extended cytotoxicity studies. Chairside milling penetration concentrates in Texas and Florida where group practice density is highest.
Japan
Tokyo and Osaka clinics prioritize lithium disilicate glass-ceramics for anterior veneer applications with stringent aesthetic demands. METI industrial policy supports fine-ceramics manufacturing heritage through targeted R&D subsidies. Kyushu-based suppliers anchor alumina substrate production for domestic dental laboratories.
India
Mumbai and Bangalore fabrication hubs serve Middle Eastern and African patients seeking cost arbitrage on complex bridge work. Central Drugs Standard Control Organization biocompatibility notifications govern imported ceramic materials. Maharashtra's dental tourism corridors expand CAD/CAM technician training capacity.
Brazil
Private insurance coverage expansion drives ceramic restoration volume in São Paulo and Rio de Janeiro state markets. ANVISA medical device registration requirements align with international ISO standards for import clearance. Southeast laboratory clusters specialize in pressed glass-ceramic production for price-sensitive segments.
Dental Ceramics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium positioning concentrates among vertically integrated milling network operators and medical-grade formulation specialists. Mid-tier competition fragments across regional ceramic blank suppliers and equipment-integrated material providers. Dominant competitive moves include laboratory network acquisition and chairside system bundling.
Among Japanese fine-ceramics manufacturers, Kyocera Corporation exemplifies technology-led positioning through substrate specialization heritage. German precision ceramics anchors CeramTec GmbH within medical-grade zirconia formulation tiers. Swiss dental technology integration represents Straumann's archetype through captive milling center networks. These three occupy distinct competitive spaces rather than direct confrontation.
| Leading Market Players |
|---|
| Kyocera Corporation |
| Saint-Gobain Ceramic Materials |
| CeramTec GmbH |
| Zimmer Biomet Holding Inc. |
| NGK Spark Plug Co., Ltd. |
| CoorsTek, Inc. |
| Morgan Advanced Materials |
| Straumann |
| 3M Advanced Materials |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German sintering furnaces exceeding 1,350°C operations sets price floors for ISO 6872-certified zirconia blanks, compressing margins for independent laboratories lacking renewable power purchase agreements while concentrating premium pricing power among vertically integrated milling networks.
Pricing Analysis
ISO 6872 compliance dictates the pricing tier structure across dental ceramics, separating certified German and Japanese producers from uncertified Asian competitors. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade differentiation and FDA 510(k) clearance status. Cost compression in economy-grade alumina substrates is intensifying because Chinese yttria stabilizer export quotas feed raw material volatility. Dental clinics with chairside milling capability show least price sensitivity, while Indian dental tourism patients exhibit highest cost consciousness.
Supply Chain Analysis
Rare earth refining concentration in Chinese yttria processing operations underwrites supply vulnerability for dental-grade zirconia stabilizers. Manufacturing draws from German precision ceramics clusters around Stuttgart, Japanese fine-ceramics heritage in Kyushu, and emerging Indian fabrication hubs in Mumbai. Raw material dependencies include yttrium oxide, high-purity alumina powders, and lithium disilicate glass-ceramic ingots. Single-source vulnerability concentrates in Chinese rare earth export quotas. Distribution runs through dental group purchasing organizations consolidating procurement across US metropolitan networks and European laboratory consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technician certification scarcity for CAD/CAM chairside milling operations constrains clinic expansion velocity, creating acquisition premiums for training-capable institutions and equipment-integrated material suppliers with captive education infrastructure.
For Market Incumbents: Fortify ISO 6872 certification moats through backward integration into medical-grade zirconia formulation production, absorbing CeramTec GmbH-style specialty suppliers before EU MDR clinical evidence requirements escalate compliance costs. Defend against 3D-printed resin interim crown substitution by bundling permanent ceramic placement with chairside system leases, locking clinics into proprietary material ecosystems. For New Entrants and Emerging Players: Differentiate on AI-powered shade matching automation, targeting US dental group purchasing organizations standardizing procurement across private equity-backed multi-clinic platforms. Exploit technician certification gaps in Indian dental tourism corridors, offering turnkey CAD/CAM training partnerships to Maharashtra fabrication hubs serving Middle Eastern cost-arbitrage patients. For Investors and Strategic Acquirers: Dental laboratory networks with captive milling centers and ISO 6872 export certification represent the most defensible acquisition archetype, capturing value migration from outsourced fabrication to same-day chairside delivery. Long-term viability hinges on regulatory compliance infrastructure rather than commodity ceramic blank production. Monitor EU MDR notified body audit failure rates as inflection indicator for zirconia implant abutment supplier exits.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 6872 Certification Investment | Quality benchmark gates export access for German milling centers serving international bridge work demand. |
| Backward Integration into Yttria Supply | Captive rare earth stabilizer sourcing insulates Japanese producers from Chinese export quota volatility. |
| AI-Powered Shade Matching Development | Machine vision integration reduces technician skill barriers for anterior veneer aesthetic prescriptions. |
| Dental Group Purchasing Organization Partnership | Multi-clinic network consolidation displaces individual practitioner material selection autonomy in US markets. |
| CAD/CAM Technician Training Academy Launch | Certification capacity scarcity creates competitive moat for equipment-integrated material suppliers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, ISO 6872 certification registries, and EU MDR notified body audit disclosures, combining interviews with dental laboratory technicians, CAD/CAM equipment procurement officers, and ceramics manufacturing R&D directors with customs trade data and dental group purchasing organization contract filings. Bottom-up restoration volume estimates triangulate against top-down materials consumption analysis.
Segmentation dimensions modeled include material chemistry tier, fabrication technology maturity, end-user channel concentration, and application complexity across the projection horizon. CAGRs derive from installed base penetration curves for intraoral scanners and sintering furnace capacity utilization. Forecast inputs incorporate EU MDR compliance cost absorption rates and Indian dental tourism patient flow trajectories.
Decision-makers should treat outputs as directional under assumptions of continued ISO 6872 certification stringency and stable Chinese rare earth export policy; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR post-market surveillance requirements and energy price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Content Experience Platforms Market
Others
Hotel Wardrobe Market
Others
Hearables Market
Others
Internet Protocol Television (IPTV) Market
Others
High-End Servers Market
Others
Digital Tattoos Market
Others
UK Cat Food Market
Others
Mobile MRI Services Market
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
Dandelion Market
Others
Global Recruitment and Staffing Market
Others
Shisha Tobacco Market
Others
Coalescing Filter Market
Others
Global Hair Loss Treatment Products Market
Others
United States Printed Signage Market
Others
North America Forklift Truck Market