
 Profiling Floats Market | 2026-2036
Profiling Floats Market Size, Share, and Industry Trends Forecast 2026-2036
Profiling Floats Market Insights
Autonomous thermal-energy harvesting is rewriting how profiling floats sustain months-long oceanographic missions without surface retrieval. Seatrec leverages solid-state phase-change engines to power deep-water profiling cycles across extended deployments. Teledyne Webb Research anchors its position through decades of proven float reliability and dense sensor integration. Naval Research Laboratory sustains government-backed development of next-generation buoyancy engines for defense and climate monitoring applications.
Profiling floats are self-propelled or passively drifting instruments that adjust buoyancy via oil-filled bladders or thermal engines to cycle vertically through water columns, typically descending to depths exceeding 2,000 meters while logging conductivity, temperature, and pressure data for ocean and subsurface characterization. The cylindrical type dominates manufacturing due to hydrodynamic efficiency and standardized sensor payload accommodation. High-density polyethylene hulls are displacing legacy metal designs across oilfield logging applications where corrosion resistance and neutral buoyancy control prove critical. Formation evaluation commands the largest application share as operators demand real-time pore-pressure and fracture-gradient data during extended-reach drilling programs.
The Bureau of Safety and Environmental Enforcement mandates subsurface monitoring protocols that directly expand float deployment in US federal waters. ISO 13628-7 subsea production system standards shape material selection and pressure-rating requirements for downhole measurement tools. The EPA's offshore discharge regulations further compel operators toward closed-loop logging systems that profiling floats increasingly support. Stakeholders must weigh thermal-engine maturation against battery-powered alternatives as mission durations extend and regulatory scrutiny on seabed equipment intensifies.
Market Dynamics
The Profiling Floats Market is being fundamentally restructured by the transition from battery-dependent power systems to autonomous thermal-harvesting architectures. This shift is compressing operational costs and extending mission durations beyond traditional retrieval cycles.
Growth Catalysts
- ISO 13628-7 Subsea Standards:These specifications mandate pressure-rated instrumentation for subsea production systems, compelling operators to adopt certified profiling floats for formation evaluation workflows.
- Polymer-composite hulls:High-density polyethylene designs are replacing legacy metal constructions in offshore logging applications, eliminating corrosion-driven maintenance intervals and enabling deeper operational ratings.
- Gulf Coast corridor concentration:Federal lease activity and subsea infrastructure investment across Louisiana and Texas waters are generating sustained procurement demand from drilling contractors.
Market Restraints
- Specialized sensor supply concentration:Precision conductivity-temperature-depth sensor manufacturing clusters in select Asian manufacturing hubs create single-source vulnerability for float assemblers.
- Buoyancy engine technical limitations:Solid-state phase-change thermal engines face depth-band constraints that restrict deployment in ultra-deepwater zones exceeding 4,000 meters.
- EPA offshore discharge compliance costs:Closed-loop logging system mandates impose capital burdens on smaller operators, consolidating procurement authority among integrated majors.
Strategic Opportunities
- Defense and climate monitoring convergence:Government-backed buoyancy engine development programs are opening dual-use procurement channels for mission-extended profiling systems.
- Real-time data telemetry integration:Satellite uplink and acoustic modem convergence is enabling shore-side monitoring of subsea pore-pressure dynamics without surface vessel standby.
- Extended-reach drilling programs:Horizontal well architectures in unconventional reservoirs are creating demand for mobile formation evaluation tools that wireline systems cannot access.
Industry Challenges
- Oceanographic systems integration expertise:The intersection of marine engineering, sensor calibration, and subsea hydrodynamics requires cross-functional talent pools that remain shallow in most labor markets.
- Pressure-vessel certification timelines:Third-party validation of composite hull integrity for repeated deep-pressure cycling extends product development schedules by 12-18 months.
- Legacy platform interoperability:New autonomous floats must interface with existing subsea communication networks and data management systems without full infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Profiling Floats Market |
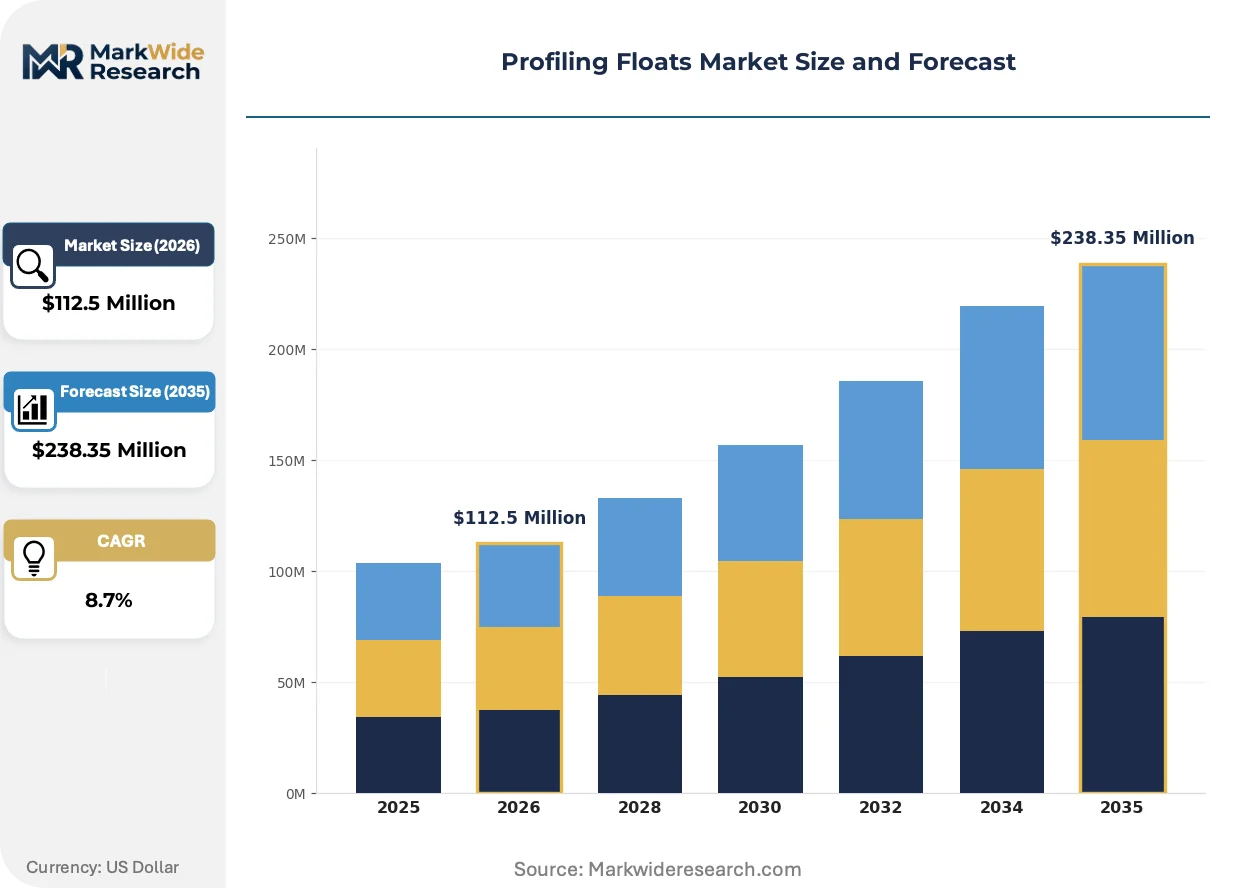
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $238.35 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cylindrical, Spherical, Elliptical, Conical, Rectangular Material: Polypropylene, High-Density Polyethylene, PVC, Acrylic, Nylon Application: Oilfield Logging, Downhole Measurement, Wellbore Stability, Formation Evaluation, Borehole Imaging End User Industry: Oil & Gas Exploration, Drilling Contractors, Reservoir Management, Subsurface Engineering |
| Companies Covered | Seatrec, Teledyne Webb Research, Naval Research Laboratory, IFREMER, CSIRO, JAMSTEC, Chinese Academy of Sciences, Alfred Wegener Institute, MetOcean Telematics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Profiling Floats Market Trends and Innovations
Thermal-energy harvesting architectures are displacing electrochemical power as the dominant design paradigm for extended-duration oceanographic missions. This transition is reshaping supplier capabilities, certification requirements, and operator procurement specifications across offshore exploration and research segments.
Solid-state phase-change engines convert ocean thermal gradients into mechanical work for buoyancy modulation. Offshore drilling contractors in the United States Gulf Coast are piloting these systems for formation evaluation programs lasting six months or longer. The technology is migrating from research-vessel deployments to commercial oilfield logging applications where surface retrieval costs dominate operational economics.
The Bureau of Safety and Environmental Enforcement mandates subsurface monitoring protocols for all drilling activities in federal waters. These requirements are accelerating float deployment for real-time pore-pressure surveillance during extended-reach programs. Operators are responding by specifying ISO-compliant instrumentation packages that satisfy both safety regulators and internal risk management frameworks.
Integrated service contracts now bundle float provision with data interpretation and equipment maintenance. Major exploration companies are displacing equipment purchase models with performance-based arrangements where contractors retain ownership and responsibility for uptime. This restructuring is most visible among Gulf Coast independents seeking to reduce capital intensity while maintaining access to advanced subsea measurement capabilities.
Profiling Floats Market Segmentation
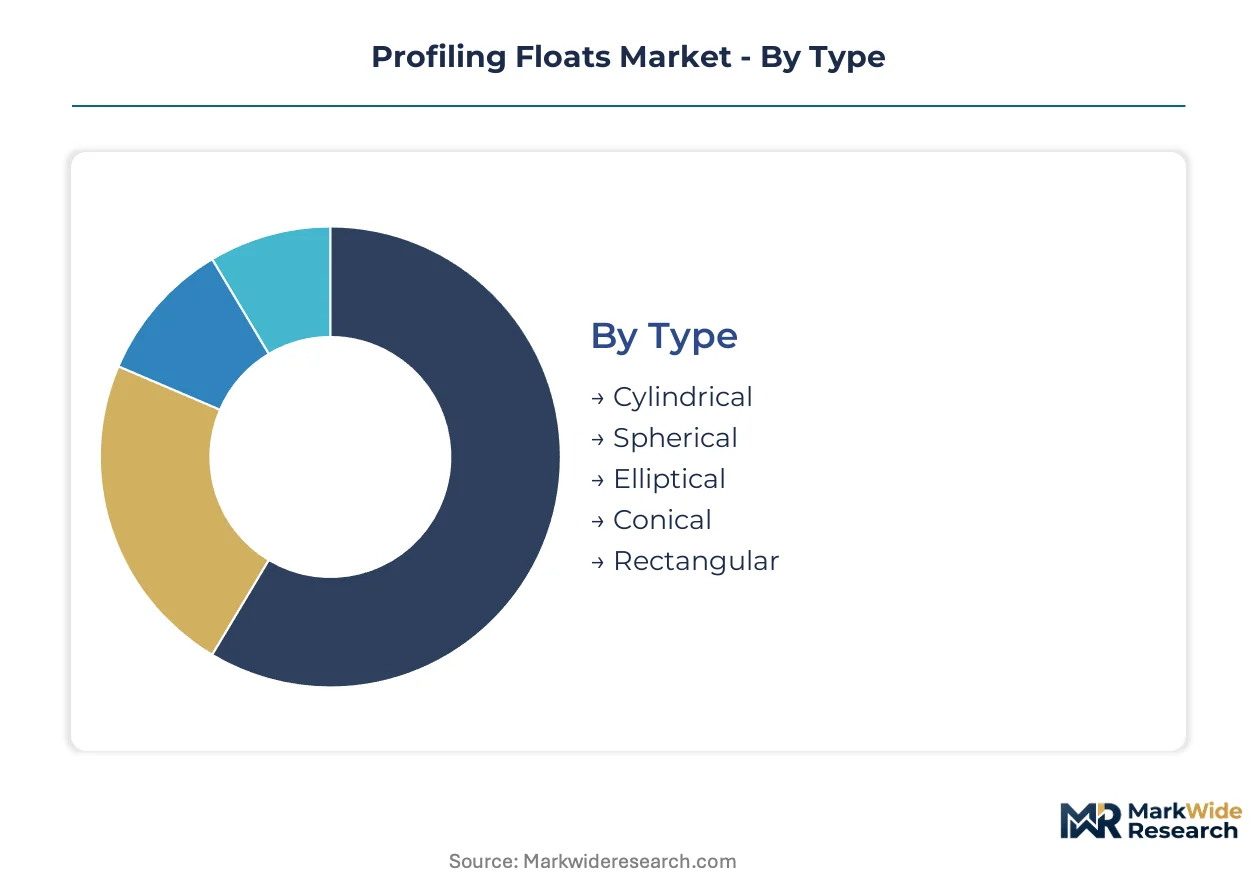
Profiling floats serve divergent operational requirements across oceanographic research and hydrocarbon extraction, necessitating precise segmentation by hull geometry, material composition, and deployment context. Each dimension carries distinct engineering trade-offs between pressure tolerance, sensor payload capacity, and maintenance burden.
Type:
Mature hydrodynamic designs dominate commercial deployments, while emerging geometries address specialized sensing arrays and ultra-deepwater pressure regimes.
- Cylindrical:The dominant hull configuration features uniform cross-sectional geometry that minimizes drag coefficients across ascent-descent cycles. Gulf Coast drilling contractors specify cylindrical floats for extended-reach formation evaluation programs where standardized sensor payload accommodation reduces integration costs.
- Spherical:Isotropic pressure distribution enables superior depth ratings without structural reinforcement penalties. Spherical designs are concentrating in ultra-deepwater zones off Louisiana where seabed pressures exceed 4,000-meter equivalents and hull integrity failures carry catastrophic recovery costs.
- Elliptical:Hybrid geometry balancing directional stability with reduced frontal area for high-current environments.
- Conical:Tapered profiles optimized for rapid descent phases in time-critical logging operations.
- Rectangular:Flat-panel construction accommodating non-standard sensor footprints in research-vessel deployments.
Cylindrical retains volume leadership; spherical holds the steepest expansion curve.
Material:
Cost tier stratification separates commodity thermoplastics from engineered polymers with enhanced pressure-cycling fatigue resistance.
- High-Density Polyethylene:Linear polymer chains yield exceptional chemical inertness against hydrocarbon exposure and seawater electrolytes. HDPE hulls are displacing legacy metal constructions across Texas-Louisiana offshore corridors where corrosion-driven maintenance intervals previously dominated operational economics.
- Polypropylene:Lower density than polyethylene enables reduced ballast requirements for neutral buoyancy calibration. Polypropylene concentrates in shallow-water logging applications where pressure differentials remain below 500 meters and material cost minimization drives procurement decisions.
- PVC:Rigid thermoplastic offering intermediate pressure ratings at commodity pricing tiers.
- Acrylic:Optical clarity supporting integrated camera payloads in borehole imaging configurations.
- Nylon:Engineering polymer selected for abrasive environments with particulate-laden drilling fluids.
High-Density Polyethylene commands the installed base; polypropylene is climbing fastest on cost-sensitive tenders.
Application:
Customer type segmentation distinguishes integrated operators pursuing real-time formation data from service companies delivering interpreted outputs.
- Formation Evaluation:Comprehensive pore-pressure, permeability, and lithology characterization during drilling operations. Supermajors operating Gulf of Mexico federal leases mandate continuous formation evaluation to satisfy Bureau of Safety and Environmental Enforcement subsurface monitoring protocols.
- Oilfield Logging:Post-drilling measurement of reservoir properties through wireline-conveyed or autonomous instrument packages. Independent drilling contractors in Texas shale plays are adopting autonomous float-based logging to eliminate surface vessel standby costs.
- Downhole Measurement:In-situ pressure-temperature monitoring during completion and production phases.
- Wellbore Stability:Real-time geomechanical surveillance to prevent lost circulation and well control incidents.
- Borehole Imaging:High-resolution acoustic and optical mapping of casing and formation features.
Formation Evaluation generates the largest procurement volumes; Oilfield Logging is gaining share fastest on autonomous deployment economics.
End User Industry:
Geography concentration aligns with federal lease activity and subsea infrastructure density along the United States Gulf Coast.
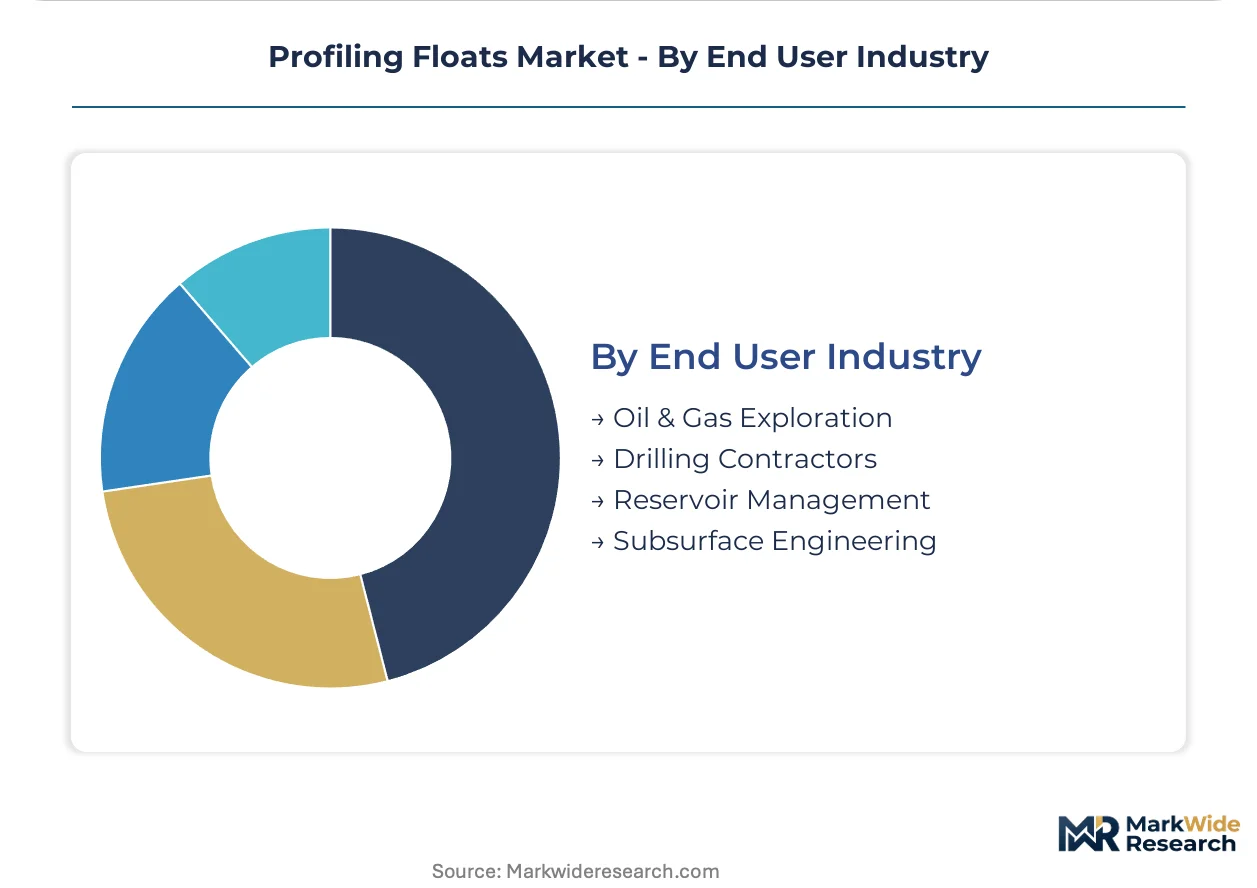
- Oil & Gas Exploration:Supermajor and large-cap independent operators conducting frontier and near-field exploration in federal waters. Exploration divisions headquartered in Houston specify profiling floats for pre-drill site surveys and real-time pore-pressure monitoring during wildcat programs.
- Drilling Contractors:Service companies providing rig-based and autonomous logging services on day-rate or integrated project bases. Contract drillers operating across Louisiana and Texas state-federal boundaries are consolidating procurement through multi-year equipment leasing arrangements.
- Reservoir Management:Production-phase surveillance of depletion patterns and secondary recovery performance.
- Subsurface Engineering:Specialized consultancies delivering geomechanical and petrophysical interpretation services.
Oil & Gas Exploration dominates capital deployment; Drilling Contractors are expanding most quickly on performance-based contracting structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated oilfield service buyers concentrate procurement authority along the United States Gulf Coast, where federal lease activity and subsea infrastructure density create sustained demand for autonomous measurement systems. Drilling contractors and exploration divisions headquartered in Houston anchor regional purchasing volumes.
United States
The Gulf Coast corridor from Texas to Louisiana generates the dominant share of commercial float deployment for formation evaluation and extended-reach drilling programs. The Bureau of Safety and Environmental Enforcement mandates subsurface monitoring protocols that directly expand float procurement in federal waters. Houston hosts the headquarters of supermajor exploration divisions and contract drilling firms consolidating multi-year equipment leasing arrangements.
China
State-backed oceanographic institutions drive research-grade float deployment for climate monitoring and deep-water scientific missions. The Chinese Academy of Sciences operates under national dual carbon goals that prioritize autonomous marine data collection infrastructure. Qingdao and Tianjin harbor the primary assembly and calibration facilities for domestic profiling float manufacturing.
Japan
JAMSTEC and affiliated research bodies sustain government-funded deployment of deep-water profiling systems for Pacific Ocean monitoring. METI programs support thermal-engine development for extended-duration oceanographic missions. Yokosuka and Kobe concentrate hull fabrication and pressure-vessel testing capabilities for regional float production.
Germany
The Alfred Wegener Institute anchors European demand for polar and deep-sea research float applications. ECHA chemical safety regulations and REACH compliance requirements shape material selection for hull polymers deployed in North Atlantic conditions. Bremerhaven hosts specialized pressure-cycling certification facilities serving regional research vessel operators.
France
IFREMER operates the largest European fleet of autonomous profiling floats for sustained ocean observation programs. National research funding under the EU Green Deal marine strategy accelerates replacement cycles for legacy battery-powered systems. Toulon and Brest concentrate subsea engineering talent pools and hydrodynamic testing infrastructure.
Profiling Floats Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where research institutions and commercial oilfield service providers represent distinct buyer archetypes. The vendor base organizes around three strategic archetypes: government-backed research laboratories, privately held sensor integration specialists, and diversified marine instrumentation conglomerates. Competitive moves concentrate on thermal-engine technology licensing and multi-year integrated service contracting rather than equipment sales.
Among research-laboratory anchors, the Naval Research Laboratory exemplifies government-funded buoyancy engine development for defense and climate monitoring convergence. Teledyne Webb Research occupies a position within the diversified instrumentation tier, representing decades of proven float reliability heritage. Seatrec sits within the technology-specialist archetype, anchoring solid-state phase-change thermal harvesting approaches for mission-extended deployments.
| Leading Market Players |
|---|
| Seatrec |
| Teledyne Webb Research |
| Naval Research Laboratory |
| IFREMER |
| CSIRO |
| JAMSTEC |
| Chinese Academy of Sciences |
| Alfred Wegener Institute |
| MetOcean Telematics |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Asian sensor manufacturing hubs compresses margins for float assemblers while simultaneously granting procurement leverage to Gulf Coast drilling contractors negotiating multi-year equipment leases. This utilization asymmetry rewards buyers who consolidate volume commitments and penalizes smaller operators unable to access tier-one supplier schedules.
Pricing Analysis
Cost-plus contracts with Bureau of Safety and Environmental Enforcement compliance indexation dominate procurement between integrated majors and drilling contractors. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13628-7 certified instrumentation from uncertified alternatives and research-grade configurations. Pricing pressure stems from thermal-engine commoditization as Seatrec's phase-change architecture licenses proliferate. Independent operators exhibit acute price sensitivity; supermajors prioritize mission reliability over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard as hull fabricators absorb working capital strain from composite pressure-vessel certification delays. Geographic concentration centers on China for precision conductivity-temperature-depth sensors, Japan for thermal-engine components, and Germany for pressure-cycling validation equipment. Raw material dependencies include high-density polyethylene resin, solid-state phase-change alloys, and satellite telemetry modules. Single-source vulnerability in Asian sensor manufacturing creates procurement risk. Distribution runs through integrated service contractors who bundle float provision with data interpretation and maintenance obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Profiling Floats Market exhibits cyclical recovery characteristics anchored to federal Gulf of Mexico lease sale schedules and subsea infrastructure replacement waves. Operators who timed procurement to low-utilization windows capture sustained cost advantages.
For Market Incumbents: Pre-empt thermal-engine commoditization by securing exclusive licensing arrangements with Naval Research Laboratory buoyancy engine programs. Incumbents should consolidate sensor integration capabilities through backward integration into Asian manufacturing partnerships, insulating against conductivity-temperature-depth supply concentration. Defensive patent filings around solid-state phase-change architectures will forestall margin erosion from emerging technology specialists. For New Entrants and Emerging Players: Establish a beachhead in oilfield logging services for Texas shale independents seeking to eliminate surface vessel standby costs. White-space targets include autonomous float-based wellbore stability monitoring and real-time geomechanical surveillance during extended-reach programs. A performance-based contracting structure—retaining equipment ownership and guaranteeing uptime—differentiates entrants from capital-sale incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward technology-specialist archetypes with proven thermal-engine deployments and government research laboratory relationships. Long-term viability hinges on dual-use defense-climate monitoring convergence and sustained federal research funding. The signal to watch is Bureau of Safety and Environmental Enforcement mandate expansion into production-phase subsurface monitoring, which would inflect demand beyond drilling-only applications.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal-Engine Technology Licensing | Seatrec's phase-change architecture transfers to commercial oilfield logging, displacing battery-dependent alternatives. |
| Integrated Service Contracting | Performance-based arrangements shift capital burden from Gulf Coast independents to equipment-retaining contractors. |
| Composite Hull Certification Investment | Third-party validation of high-density polyethylene pressure-cycling integrity accelerates product development timelines. |
| Real-Time Data Telemetry Integration | Satellite uplink and acoustic modem convergence enables shore-side monitoring without surface vessel standby. |
| Government Research Partnership | Naval Research Laboratory buoyancy engine programs open dual-use procurement channels for defense applications. |
Research Methodology
The analysis maps cylindrical, spherical, and elliptical hull configurations alongside high-density polyethylene and polypropylene material tiers, each validated through drilling contractor procurement directors, subsea engineering consultants, and Bureau of Safety and Environmental Enforcement compliance officers. Primary interviews with thermal-engine developers and composite pressure-vessel fabricators combined with secondary validation from ISO 13628-7 certification records, EPA offshore discharge filings, and Gulf Coast federal lease activity databases. Bottom-up unit deployment estimates and top-down market sizing triangulate through sensor payload cost structures and equipment leasing rate benchmarks.
Assumptions held fixed include Bureau of Safety and Environmental Enforcement mandate scope, thermal-engine depth-band limitations, and Asian sensor manufacturing concentration; variables tested include federal lease sale frequency, polymer resin pricing volatility, and acoustic modem reliability improvements. Segmentation dimensions encompass hull geometry, material composition, application context, and end-user industry across the projection horizon. CAGRs derive from deployment trajectory modeling against infrastructure replacement cycles and exploration capital allocation patterns.
Stress conditions across thermal-engine maturation timelines, composite hull fatigue failure rates, and Gulf Coast hurricane disruption frequency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution thresholds. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
PC As a Service Market
Others
UK Real Estate Hospitality Market
Others
Port Replicator Market
Others
Gas Holders Market
Others
Asia Pacific Contract Packaging Market
Others
South Korea Smart Home Market
Others
Nonlinear Editing System Market
Others
Cloud Advertising Market
Others
India Battery E-Commerce Market
Others
Handheld Mobile Computers Market
Others
Connected TV Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Electric Pallet Jack Truck Market
Others
Global Application Testing Services Market
Others
Smart Badge Market
Others
Bimodal Identity Management Solutions Market