
 Middle East and Africa Halal Food & Beverage Market | 2026-2036
Middle East and Africa Halal Food & Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Halal Food & Beverage Market Insights
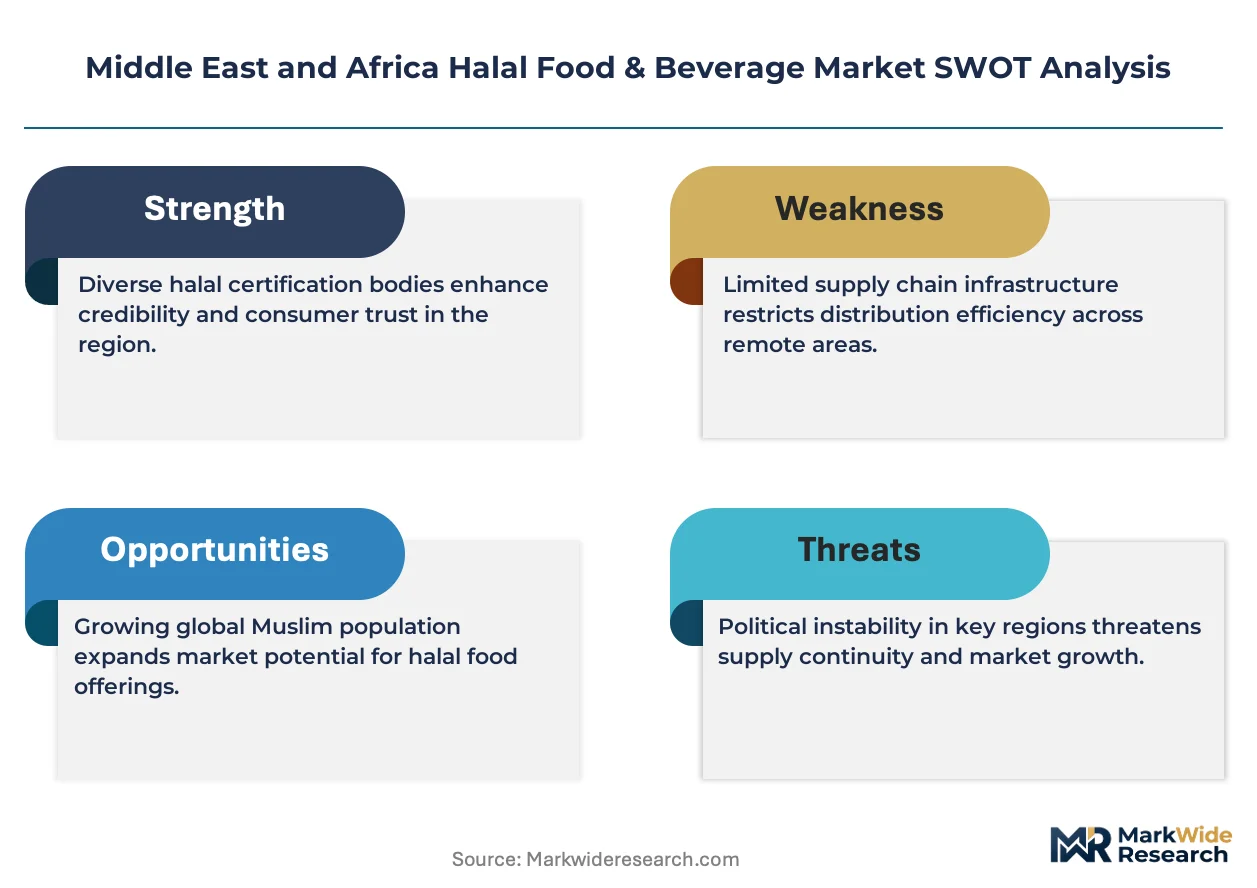
A shift from fragmented local sourcing to consolidated multi-supplier contracts is restructuring procurement across Middle East and Africa halal protein supply chains. JBS SA leverages its Brazilian slaughterhouse network to anchor frozen beef shipments into Egyptian and Saudi ports. Tanmiah Food Company sustains domestic poultry capacity through backward integration into feed milling and hatchery operations. Al Islami Foods competes on brand recognition in Gulf retail freezers through decades of UAE shelf presence.
Halal food and beverage encompasses products manufactured, stored, and distributed under Islamic dietary law, requiring slaughter by a Muslim invoking Allah's name, complete blood drainage, and absence of pork derivatives, alcohol, or cross-contamination with non-halal items. Meat commands the largest revenue pool due to protein centrality in Middle Eastern and North African cuisines and the cost premium of certified slaughter. Online retail represents the fastest-expanding distribution channel as Saudi and UAE logistics platforms build cold-chain last-mile capability for fresh and frozen halal goods. Household end use dominates volume but restaurants and catering yield higher per-unit margins through bulk protein contracts and menu certification fees.
Saudi Food and Drug Authority, Emirates Authority for Standardization and Metrology, and South African National Halaal Authority each enforce distinct slaughter, labeling, and facility audit protocols that fragment compliance costs for multi-country suppliers. Egypt's national food safety regulator and Nigeria's halal certification bodies are introducing import inspection regimes that delay entry for uncertified shipments. Stakeholders must monitor divergence between Gulf harmonization initiatives and sub-Saharan national standards when planning regional distribution architecture.
Market Dynamics
Consolidation of halal protein procurement contracts across Gulf Cooperation Council food service channels is compressing supplier margins while favoring vertically integrated operators with captive slaughterhouse capacity and multi-country certification coverage.
Growth Catalysts
- SFDA Traceability Mandates:Saudi Food and Drug Authority slaughterhouse digitization requirements are accelerating investment in blockchain-enabled halal verification systems across Red Sea port corridors.
- UAE Retail Infrastructure Modernization:Emirates Authority for Standardization and Metrology streamlined facility audit protocols are reducing certification timelines for cold-chain halal distribution centers in Dubai and Abu Dhabi.
- Egyptian Import Inspection Regimes:The country's national food safety regulator is formalizing halal certification reciprocity agreements that ease entry for pre-certified Brazilian and Turkish protein shipments.
Market Restraints
- Feed Cost Volatility:Saudi and UAE poultry integrators face margin compression from imported soybean and corn price swings that captive feed milling cannot fully hedge.
- Slaughterhouse Concentration Risk:Brazilian beef suppliers anchor over half of frozen halal shipments into Jeddah and Port Said, creating single-geography supply vulnerability.
- Cross-Contamination Technical Limits:Shared cold-storage facilities in Nigerian and Kenyan logistics hubs complicate segregation of halal and non-halal protein streams.
Strategic Opportunities
- Nigeria's Emerging Certification Framework:The country's nascent halal accreditation bodies present first-mover positioning for suppliers establishing compliant distribution nodes in Lagos and Kano.
- Convergence of Blockchain and Cold-Chain IoT:Real-time temperature monitoring tied to immutable halal provenance records is opening premium pricing tiers for traceable fresh meat.
- Quick-Commerce Channel Expansion:Saudi and UAE rapid-delivery platforms are building dedicated halal dark-store networks that bypass traditional retail slotting fees.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:Divergent audit protocols between South African National Halaal Authority and Gulf standardization bodies force redundant facility inspections.
- Legacy ERP Integration Friction:Mid-scale Egyptian and Jordanian processors struggle to embed halal traceability modules into existing inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Halal Food & Beverage Market |
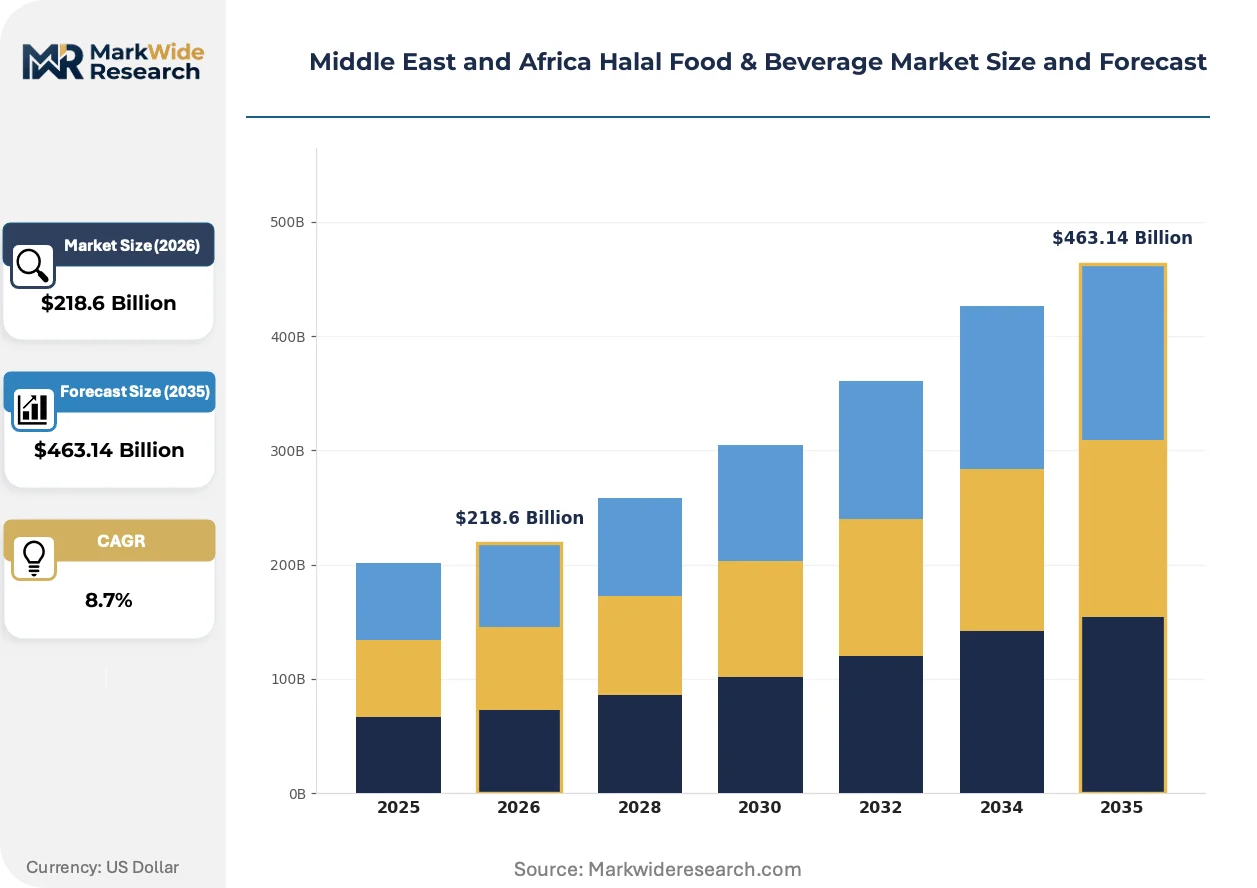
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $463.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Dairy, Snacks, Beverages Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Customer Type: Muslim Consumers, Non-Muslim Consumers, Retailers, Food Service End Use: Household, Restaurants, Catering, Food Processing |
| Companies Covered | Al Islami Foods, Podravka Gulf FZE, JBS SA, BRF SA, Al Rawdah Foods, Marfrig Global Foods, Tanmiah Food Company, Al Kabeer Group ME, The Egyptian Food Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Halal Food & Beverage Market Trends and Innovations
Digital verification infrastructure and channel fragmentation are restructuring how halal integrity is guaranteed and monetized across Middle East and Africa protein supply chains.
Blockchain-based halal certification platforms are integrating slaughterhouse data, logistics temperature records, and retail point-of-sale verification into unified provenance ledgers. Saudi food service distributors and UAE hypermarket chains are piloting these systems for high-value fresh meat SKUs. This integration is compressing audit costs while enabling real-time revocation of compromised batches.
Saudi Food and Drug Authority mandatory electronic traceability for all imported red meat is forcing slaughterhouse-level digitization across Brazilian and Australian export facilities. The regulation requires API-connected health certificates and lot-level tracking from abattoir to retail shelf. Egyptian and Jordanian importers are responding by pre-qualifying only suppliers with SFDA-integrated certification systems.
Quick-commerce platforms in Riyadh and Dubai are displacing traditional retail freezer dominance for impulse halal protein purchases. Young household buyers now favor 30-minute delivery of fresh certified poultry over weekly hypermarket stocking. This behavioral pivot is most visible in Saudi Arabia's central region, where dark-store density supports sub-hour fresh meat fulfillment.
Middle East and Africa Halal Food & Beverage Market Segmentation
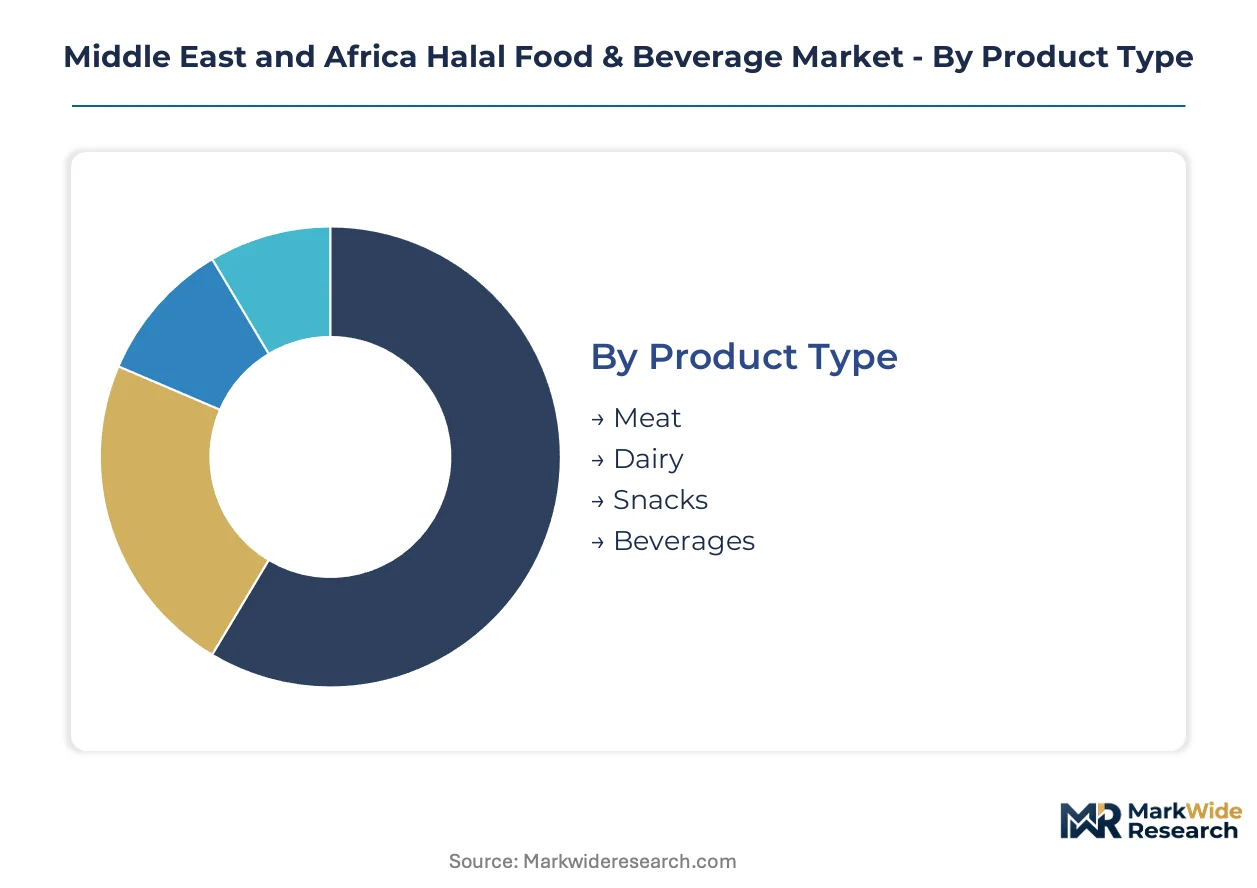
Halal food and beverage segmentation in the Middle East and Africa reflects divergent certification standards, channel infrastructure maturity, and protein-centric consumption patterns. Understanding these divisions reveals where procurement consolidation, digitization investment, and margin compression concentrate across the value chain.
Product Type:
Upgrade cycles in halal product portfolios track protein price volatility and cold-chain reliability improvements, with operators refreshing frozen and fresh meat assortments most aggressively.
- Meat:Certified beef, poultry, and lamb products requiring Islamic slaughter protocols with complete blood drainage and Muslim-invoked blessings. Demand clusters in Saudi Arabia and UAE food service channels where JBS SA and Tanmiah Food Company anchor procurement contracts through captive slaughterhouse capacity. SFDA traceability mandates are accelerating blockchain-enabled verification investments for Red Sea port entries.
- Dairy:Milk, cheese, and yogurt products free from non-halal animal rennet and alcohol-based additives. UAE retail infrastructure modernization is expanding chiller shelf space for premium imported dairy, though margin pressure persists from feed cost volatility affecting regional producers.
- Snacks:Packaged confectionery and savory items certified for halal ingredient compliance. Nigerian and Kenyan logistics hubs struggle with cross-contamination risks in shared cold-storage facilities.
- Beverages:Non-alcoholic drinks including halal-certified juices, soft drinks, and functional beverages. Egyptian import inspection regimes are formalizing certification reciprocity for pre-qualified Turkish and Brazilian suppliers.
Meat sits at the top of the volume ranking, with Beverages climbing the fastest as young consumers shift from traditional retail to quick-commerce impulse purchases.
Distribution Channel:
Channel cost tiers separate premium-positioned specialty operators from volume-driven supermarket chains, with online platforms capturing margin through bypassed slotting fees.
- Supermarkets:Large-format retail with dedicated halal freezer and fresh meat counters. Al Islami Foods leverages decades of UAE shelf presence to defend position in Dubai and Abu Dhabi hypermarket chains.
- Convenience Stores:Small-footprint urban outlets for immediate-consumption halal snacks and beverages. Riyadh and Jeddah density supports 24-hour certification-compliant replenishment cycles.
- Online Retail:E-commerce platforms with cold-chain last-mile capability for fresh and frozen halal goods. Saudi and UAE rapid-delivery dark-store networks are displacing traditional retail freezer dominance for impulse protein purchases.
- Specialty Stores:Ethnic grocers and halal butchers serving concentrated Muslim populations. Lagos and Kano distribution nodes present first-mover positioning as Nigeria's certification framework matures.
Supermarkets retain the largest transaction volume, with Online Retail gaining share fastest through sub-hour fresh meat fulfillment in Saudi Arabia's central region.
Customer Type:
Customer margins stratify across bulk contract scale, with food service operators yielding highest per-unit returns through menu certification fees and protein volume commitments.
- Muslim Consumers:Primary demand base requiring strict Sharia-compliant certification for all purchases. Gulf Cooperation Council states anchor per-capita spending as retail infrastructure modernizes.
- Non-Muslim Consumers:Secondary segment attracted to halal products for perceived quality and safety standards. Egyptian and Jordanian processors report rising non-Muslim trial rates for certified poultry.
- Retailers:Supermarket and convenience store operators procuring certified inventory for resale. Emirates Authority for Standardization and Metrology streamlined audit protocols reduce certification timelines for compliant distribution centers.
- Food Service:Restaurants, hotels, and catering operations sourcing bulk halal proteins. Consolidated procurement contracts across GCC channels favor vertically integrated operators with multi-country certification coverage.
Food Service commands the highest per-transaction value, with Non-Muslim Consumers expanding most quickly as quality associations spread beyond core religious demand.
End Use:
Application maturity separates established household consumption from emerging food processing integration, with restaurants and catering yielding superior margins through certification premiums.
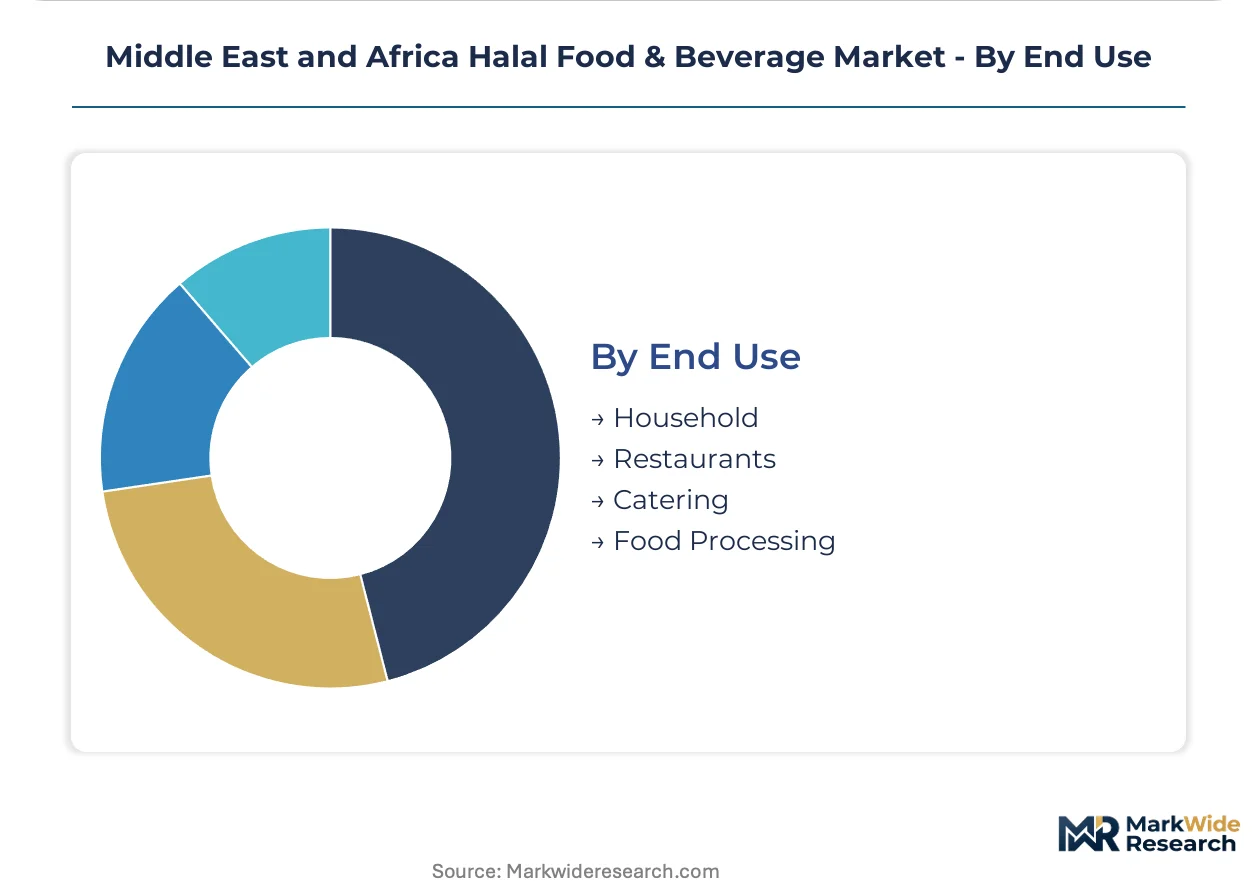
- Household:Direct consumer purchase for home preparation and consumption. Weekly hypermarket stocking patterns persist in older demographics while young buyers favor quick-commerce fresh poultry delivery.
- Restaurants:Dine-in and quick-service establishments requiring menu-level halal certification. Saudi Food and Drug Authority mandates on slaughterhouse traceability tighten compliance requirements for imported protein suppliers.
- Catering:Event and institutional food service with bulk protein contracts. South African National Halaal Authority audit protocols create redundant inspection burdens for multi-country suppliers serving GCC and sub-Saharan markets simultaneously.
- Food Processing:Industrial ingredient procurement for manufactured halal products. Mid-scale Egyptian and Jordanian processors face legacy ERP integration friction when embedding halal traceability modules.
Household end use dominates absolute volume, with Food Processing showing the steepest expansion trajectory as manufacturers seek certified ingredient security for export-ready production lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Cooperation Council states anchor halal protein procurement consolidation, with Saudi Arabia and the United Arab Emirates driving cold-chain infrastructure investment across Red Sea and Arabian Gulf port corridors.
Saudi Arabia
Food service channels in Riyadh and Jeddah are expanding multi-supplier contracts for certified poultry and beef. SFDA mandates on slaughterhouse traceability are accelerating blockchain-enabled verification investments for imported red meat shipments. The Eastern Province's industrial cities host expanding cold-storage capacity serving quick-commerce dark-store networks.
United Arab Emirates
Dubai and Abu Dhabi hypermarket chains are modernizing retail freezer infrastructure for premium halal protein assortment. Emirates Authority for Standardization and Metrology streamlined facility audit protocols are compressing certification timelines for distribution centers. Sharjah's logistics free zones concentrate cross-docking operations for re-export to African markets.
Egypt
Cairo-based processors are integrating halal traceability modules into legacy ERP systems for export-ready production lines. The national food safety regulator is formalizing certification reciprocity agreements with Brazilian and Turkish authorities. Alexandria and Port Said anchor frozen protein import inspection and redistribution to North African markets.
South Africa
Cape Town and Johannesburg food manufacturers face redundant audit burdens from South African National Halaal Authority protocols diverging from Gulf standards. Poultry integrators are hedging feed cost exposure through captive milling operations in the Western Cape. Durban's port infrastructure handles re-export volumes to sub-Saharan markets lacking domestic certification capacity.
Nigeria
Lagos and Kano distribution nodes present first-mover positioning as nascent halal accreditation bodies mature. Shared cold-storage facilities in Lagos logistics hubs complicate segregation compliance for protein imports. Abuja's regulatory framework is introducing import inspection regimes that delay entry for uncertified shipments from Middle Eastern suppliers.
Middle East and Africa Halal Food & Beverage Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue quick-commerce partnerships and blockchain-verified premium positioning. The supplier base concentrates around vertically integrated poultry operators and Brazilian beef exporters with multi-country certification coverage. Three archetypes dominate: Gulf-based domestic integrators with backward feed control, South American exporters leveraging slaughterhouse scale, and regional distributors building dark-store networks. Competitive intensity centers on procurement contract consolidation and SFDA-integrated traceability system deployment.
Among Brazil-based protein exporters, JBS SA and Marfrig Global Foods exemplify scale-driven archetypes anchored in slaughterhouse network coverage for frozen beef shipments. Within Gulf domestic integration, Tanmiah Food Company and Al Islami Foods represent contrasting models—one sustaining capacity through upstream feed and hatchery control, the other defending retail freezer position through decades of UAE shelf presence. These three names illustrate how geographic origin and structural positioning shape competitive viability under tightening traceability mandates.
| Leading Market Players |
|---|
| Al Islami Foods |
| Podravka Gulf FZE |
| JBS SA |
| BRF SA |
| Al Rawdah Foods |
| Marfrig Global Foods |
| Tanmiah Food Company |
| Al Kabeer Group ME |
| The Egyptian Food Company |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between SFDA-integrated premium proteins and commodity-grade frozen imports manifests in divergent margin structures across Saudi and UAE procurement channels. Premium tiers command traceability-linked pricing power through blockchain-verified cold-chain guarantees, while standard-tier suppliers absorb feed cost volatility without pricing leverage.
Pricing Analysis
Input-cost pass-through from Brazilian soybean and corn markets compresses margins for Gulf poultry integrators operating captive feed mills. Three-tier pricing structure across premium blockchain-verified, standard certified, and economy-grade frozen tiers separates JBS SA's Red Sea port shipments from Tanmiah's domestic integrated production. Pricing pressure stems from Egyptian import inspection reciprocity agreements accelerating Turkish and Brazilian supplier competition. Food service operators show lowest price sensitivity through menu certification fees, while household quick-commerce buyers exhibit highest elasticity to fresh poultry premiums.
Supply Chain Analysis
Feed grain supply rests on Brazilian and Argentinian agricultural exports, with Gulf integrators hedging through forward contracts on Chicago Board of Trade benchmarks. Halal protein sourcing concentrates in Brazil, Saudi Arabia, and Turkey, with Egyptian and Nigerian redistribution nodes expanding. Single-source vulnerability runs through Brazilian beef slaughterhouses anchoring over half of Jeddah frozen shipments. Distribution runs through Dubai's Jebel Ali free zone cross-docking facilities for African re-export and Riyadh's quick-commerce dark-store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa halal food and beverage market compounds steadily as Gulf retail infrastructure modernization and SFDA digitization mandates institutionalize certification premiums across protein supply chains.
For Market Incumbents: Deepen backward integration into hatchery and feed milling operations to offset imported grain price volatility threatening margin stability. Expand multi-country certification coverage beyond Gulf standards to capture Egyptian and Nigerian regulatory reciprocity opportunities. Prioritize blockchain-enabled traceability system deployment ahead of SFDA mandatory electronic health certificate requirements. For New Entrants and Emerging Players: Capture Nigeria's nascent halal accreditation framework by establishing compliant Lagos and Kano distribution nodes before import inspection regimes mature. Target quick-commerce dark-store partnerships in Saudi Arabia's central region where sub-hour fresh meat fulfillment displaces traditional retail freezer dominance. Lead with IoT-temperature monitoring bundled with certification compliance to differentiate from legacy cold-chain operators. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale Egyptian and Jordanian processors possessing export-ready production lines but lacking integrated traceability modules. Long-term viability favors operators with captive slaughterhouse capacity and multi-jurisdiction certification coverage spanning Gulf and sub-Saharan standards. Watch for SFDA API integration completion rates as inflection indicator for premium-tier pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | SFDA-mandated electronic health certificates compress audit costs while enabling real-time batch revocation for premium meat SKUs. |
| Quick-Commerce Dark-Store Expansion | Riyadh and Dubai rapid-delivery networks bypass traditional retail slotting fees for impulse fresh poultry purchases. |
| Multi-Jurisdiction Certification Coverage | Simultaneous Gulf and sub-Saharan accreditation reduces redundant inspection burdens for cross-regional protein suppliers. |
| Backward Feed Integration | Captive milling operations in Saudi Arabia and UAE hedge imported soybean and corn price volatility affecting poultry margins. |
| Nigerian Distribution Node Establishment | First-mover positioning in Lagos and Kano captures emerging halal accreditation framework before import inspection regimes tighten. |
Research Methodology
Coverage spans Gulf Cooperation Council states, North Africa, and sub-Saharan Africa, with primary inputs from each regional cluster. Primary interviews engaged halal certification body directors, cold-chain logistics operators, food service procurement managers, and retail category buyers across Saudi Arabia, UAE, Egypt, and Nigeria. Secondary validation drew from SFDA regulatory filings, Emirates Authority for Standardization and Metrology audit protocols, customs and trade data for Red Sea protein imports, and industry association reports. Bottom-up protein volume modeling triangulated against top-down market sizing from retail infrastructure investment disclosures.
Rate-of-change decomposition anchored forecast construction across the analysis window, segmenting by product type, distribution channel, and end-use application alongside certification tier and geographic regulatory cluster. CAGRs derived from trend extrapolation of procurement contract consolidation patterns, quick-commerce penetration trajectories, and traceability mandate implementation timelines. Industry-specific inputs included feed grain price volatility indices, slaughterhouse digitization adoption curves, and cold-chain last-mile density metrics.
Feed cost volatility, regulatory reciprocity negotiation delays, and blockchain verification system deployment lags are the dominant revision risks to modeled projections. Forecasts reflect assumptions about SFDA mandate adherence timelines and Gulf retail modernization investment continuity. A small set of named triggers—Brazilian harvest yields, Nigerian accreditation body maturation rates, and Egyptian import inspection staffing levels—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Bakery Packaging Market
Others
APAC Machine Vision Systems Market
Others
Performance Testing Tools Market
Others
Brazil Passenger Vehicles Lubricants Market
Others
Global Multi Domain Controller Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Mobile Retina Services Market
Others
Global Digital Market
Others
Liquid Density Meters Market
Others
Asia-Pacific Medical Simulation Market
Others
Europe Meditation Market
Others
5G Tester Market
Others
Residential Electrical Conduit Market
Others
Global Multi-Access Edge Computing Market
Others
Storm Surge Barriers Market
Others
Internet of Things Testing Market