
 Storm Surge Barriers Market | 2026-2036
Storm Surge Barriers Market Size, Share, and Industry Trends Forecast 2026-2036
Storm Surge Barriers Market Analytics
Municipal procurement channels for coastal defense infrastructure is narrowing as federal disaster resilience funding in the United States consolidates around fewer pre-qualified engineering consortiums. Boskalis Westminster leverages its dredging and marine construction heritage to dominate North Sea and Gulf Coast project pipelines. Van Oord anchors its competitive stance through integrated design-build capabilities for movable barrier systems. AECOM competes by positioning its climate risk advisory services upstream of capital allocation decisions by port authorities and city governments.
Storm surge barriers are engineered hydraulic structures—typically comprising steel or reinforced concrete gate systems with pontoons, seals, and foundation pilings designed to withstand hydrostatic pressures exceeding 100 kilonewtons per square meter—deployed to prevent seawater inundation of coastal population centers and critical infrastructure during extreme weather events. Permanent barriers fabricated from steel and concrete command the majority of installed capacity due to their multi-decade design life and integration with levee networks, while modular and inflatable systems fabricated from geotextiles and reinforced fabrics represent the fastest-expanding category as emergency management agencies prioritize rapid-deploy assets for flood-prone areas. Marine ports and coastal cities constitute the densest concentration of application-specific demand, driven by asset concentration and insurability requirements.
The U.S. Army Corps of Engineers coordinates with FEMA and state environmental regulators to enforce coastal construction standards that mandate freeboard elevations and structural load certifications, directly shaping supplier qualification thresholds and project timelines. In Europe, the EU Floods Directive and national water boards in the Netherlands impose iterative safety assessments that force barrier operators to demonstrate failure-mode resilience under climate-adjusted sea-level scenarios. Stakeholders must monitor how evolving probabilistic flood risk mapping by federal agencies reshapes benefit-cost ratios for proposed barrier investments.
Market Dynamics
Coastal municipalities are consolidating procurement authority around pre-qualified engineering consortiums as federal disaster resilience funding channels narrow, compressing vendor access and elevating technical qualification thresholds for storm surge barrier contracts.
Growth Catalysts
- Hurricane frequency intensification:Coastal municipalities in the United States face mounting asset protection mandates, accelerating capital allocation toward engineered hydraulic structures with multi-decade design life.
- EU Floods Directive iterative assessments:National water boards in the Netherlands now require climate-adjusted sea-level scenario modeling, forcing barrier operators to demonstrate failure-mode resilience and upgrade legacy installations.
- Geotextile modular systems:Emergency management agencies prioritize rapid-deploy inflatable barriers fabricated from reinforced fabrics for flood-prone areas lacking permanent infrastructure.
Market Restraints
- Steel and concrete input volatility:Foundation pilings and reinforced concrete gate systems face commodity price swings that destabilize project cost estimates during extended construction timelines.
- Marine construction labor scarcity:Specialized underwater welding and dredging expertise concentrates in North Sea and Gulf Coast geographies, creating bottleneck risks for concurrent project execution.
- Environmental impact review friction:State environmental regulators in the United States mandate extended consultation periods for coastal construction permits, elongating project approval cycles.
Strategic Opportunities
- Vietnam Mekong Delta investments:Sustained infrastructure commitment across Southeast Asian delta regions creates demand for integrated design-build movable barrier capabilities.
- Room for the River program alignment:Dutch adaptive water management policies reshape procurement specifications toward multifunctional barrier designs combining flood defense with ecological corridor functions.
- Climate risk advisory upstream positioning:Port authorities and city governments seek pre-capital allocation consulting services to justify benefit-cost ratios for proposed barrier investments.
Industry Challenges
- Probabilistic flood risk mapping integration:Federal agencies are recalculating hydrological models, forcing barrier operators to recertify structural load certifications against revised freeboard elevation requirements.
- Legacy levee network interoperability:New steel gate installations must interface with existing reinforced concrete infrastructure, complicating foundation piling alignment and seal compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storm Surge Barriers Market |
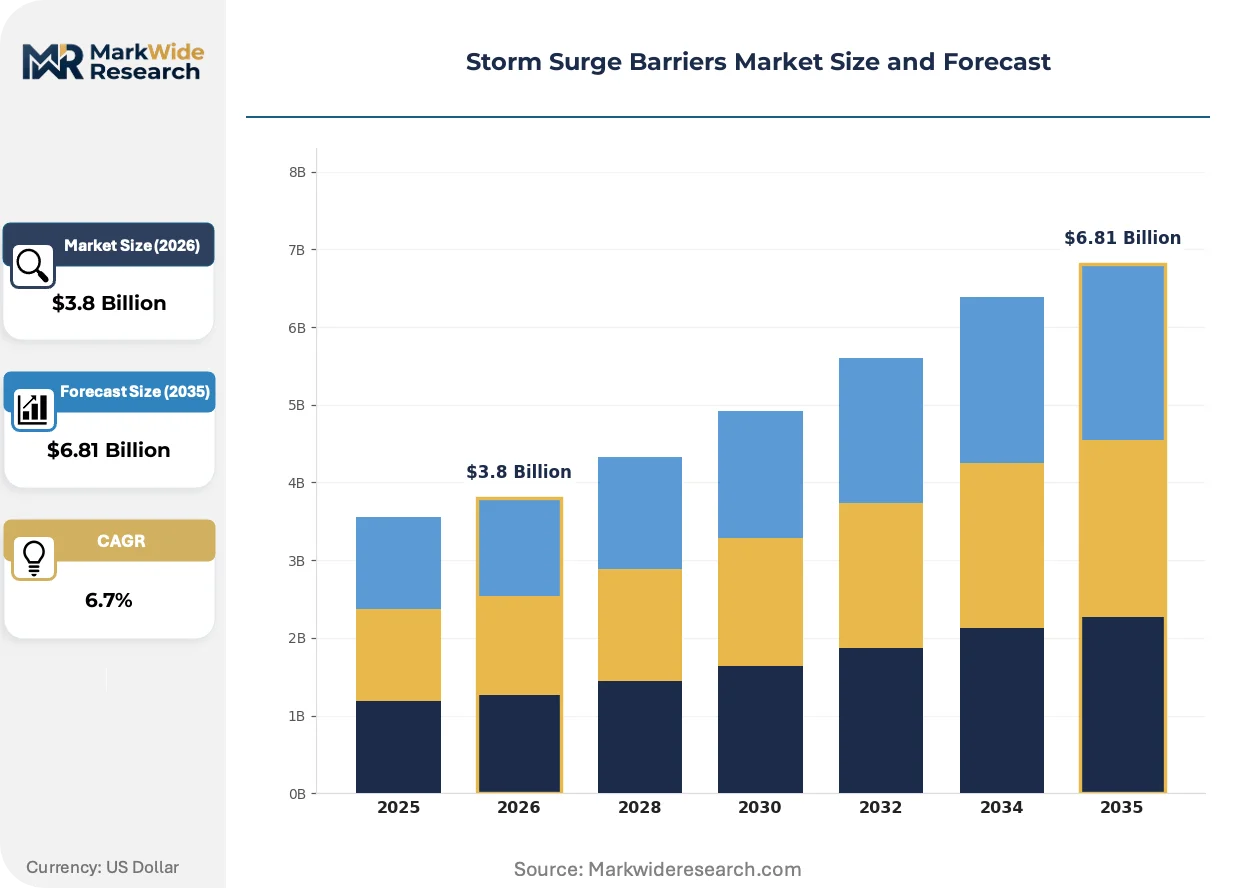
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Temporary Barriers, Inflatable Barriers, Modular Barriers, Permanent Barriers Material: Steel, Concrete, Inflatable Fabric, Geotextiles Application: Cities, Coastal Infrastructure, Marine Ports, Flood-Prone Areas Installation Method: Fixed Installation, Mobile Installation, Automated Systems, Manual Setup |
| Companies Covered | Boskalis Westminster, Royal HaskoningDHV, Van Oord, Jan De Nul Group, AECOM, Mott MacDonald, Royal BAM Group, China Communications Construction Company, Kiewit Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storm Surge Barriers Market Evolving Landscape
Barrier engineering is migrating toward multifunctional designs that integrate ecological and recreational functions alongside hydraulic protection, reshaping how coastal municipalities evaluate procurement specifications and long-term asset value.
Modular inflatable barrier technology is migrating from emergency response inventories into permanent municipal preparedness frameworks. Flood-prone jurisdictions in the United States are stockpiling geotextile systems for rapid deployment ahead of hurricane landfall. This capability is compressing the acceptable response window for temporary protection, altering how permanent and deployable assets are balanced in coastal defense portfolios.
The EU Floods Directive now mandates climate-adjusted safety assessments that extend beyond historical flood frequency analysis. Barrier operators in the Netherlands must demonstrate resilience under sea-level rise scenarios through 2100. Steel and concrete gate systems face accelerated upgrade cycles as iterative safety assessments force retrofitting of legacy installations to meet probabilistic failure thresholds.
Coastal cities are unbundling design, construction, and long-term operation responsibilities across specialized consortiums rather than awarding turnkey contracts. Port authorities in Southeast Asia now separate capital construction from decades-long maintenance obligations. Vietnam and Indonesia represent the most visible geographies where this fragmentation is concentrating vendor specialization and reshaping competitive qualification requirements.
Storm Surge Barriers Market Segmentation
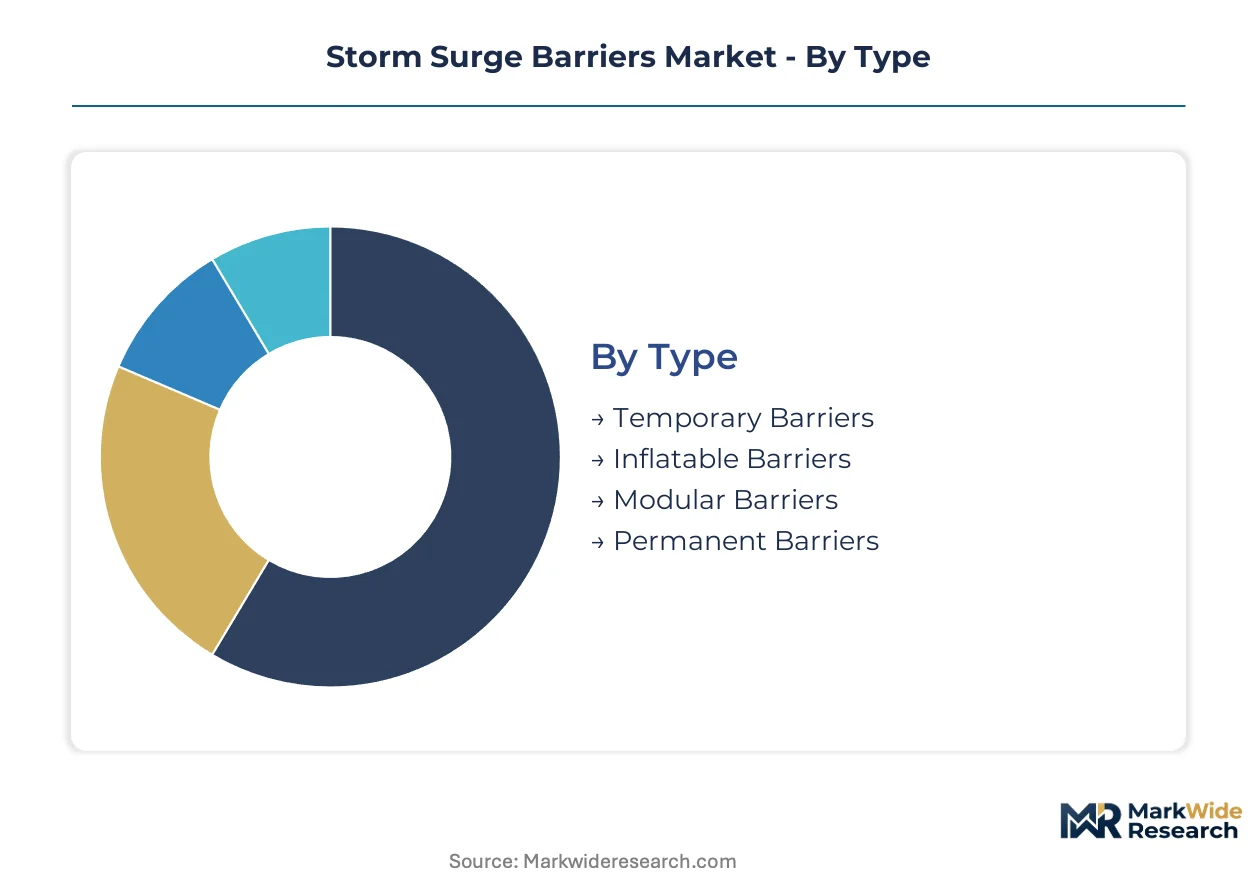
Storm surge barrier procurement diverges sharply across deployment permanence, material durability, and operational tempo. Municipal buyers weight capital intensity against response speed when allocating budgets across segment categories.
Type:
Deployment permanence shapes engineering specifications and procurement cycles for coastal defense infrastructure.
- Permanent Barriers:Reinforced concrete and steel gate systems anchor to foundation pilings with design lives exceeding fifty years. Dutch water boards and U.S. Army Corps of Engineers specifications concentrate demand around Rotterdam, New Orleans, and New York Harbor installations.
- Modular Barriers:Prefabricated steel or concrete units assemble on-site for semi-permanent deployment. Southeast Asian delta municipalities in Vietnam and Indonesia prioritize these for phased coastal defense buildouts where full capital commitment faces political or fiscal constraints.
- Inflatable Barriers:Reinforced fabric tubes deploy rapidly via water or air inflation for emergency response scenarios.
- Temporary Barriers:Sandbag arrays, portable flood walls, and demountable steel panels protect against short-duration surge events.
Permanent barriers command the established base. The steepest expansion runs through modular systems.
Material:
Material selection trades hydrostatic load capacity against deployment velocity and ecological integration requirements.
- Concrete:Reinforced concrete gate structures withstand hydrostatic pressures exceeding 100 kilonewtons per square meter. North Sea and Gulf Coast projects specify high-performance marine concrete formulations for foundation pilings and monolithic barrier walls.
- Steel:Corrosion-resistant alloy gate systems enable movable barrier mechanisms with precision sealing surfaces. Rotterdam's Maeslantkering and Thames Barrier installations demonstrate steel's dominance in high-cycle operational environments.
- Geotextiles:Woven polypropylene and polyester fabrics form deployable tube systems for rapid flood response.
- Inflatable Fabric:PVC-coated polyester or polyurethane membranes create portable dam structures for emergency management inventories.
Concrete and steel anchor the installed capacity base. Geotextile systems are climbing the fastest as emergency preparedness budgets expand.
Application:
Asset concentration and insurability mandates concentrate barrier investment around population centers and trade infrastructure.
- Marine Ports:Container terminals and liquid bulk facilities require uninterrupted operations during surge events. Houston, Rotterdam, and Singapore port authorities specify integrated barrier-levee systems protecting billions in cargo throughput capacity.
- Cities:Dense coastal populations drive engineered hydraulic protection for subway systems, power substations, and wastewater treatment plants. New York City's post-Hurricane Sandy investments illustrate municipal capital allocation toward multi-billion-dollar barrier networks.
- Coastal Infrastructure:Highways, rail corridors, and energy transmission lines traverse vulnerable coastal zones.
- Flood-Prone Areas:Agricultural and low-density residential zones receive priority for rapid-deploy temporary solutions.
Marine ports and cities concentrate the revenue base. Flood-prone rural areas are gaining share fastest as federal disaster resilience funding broadens eligibility criteria.
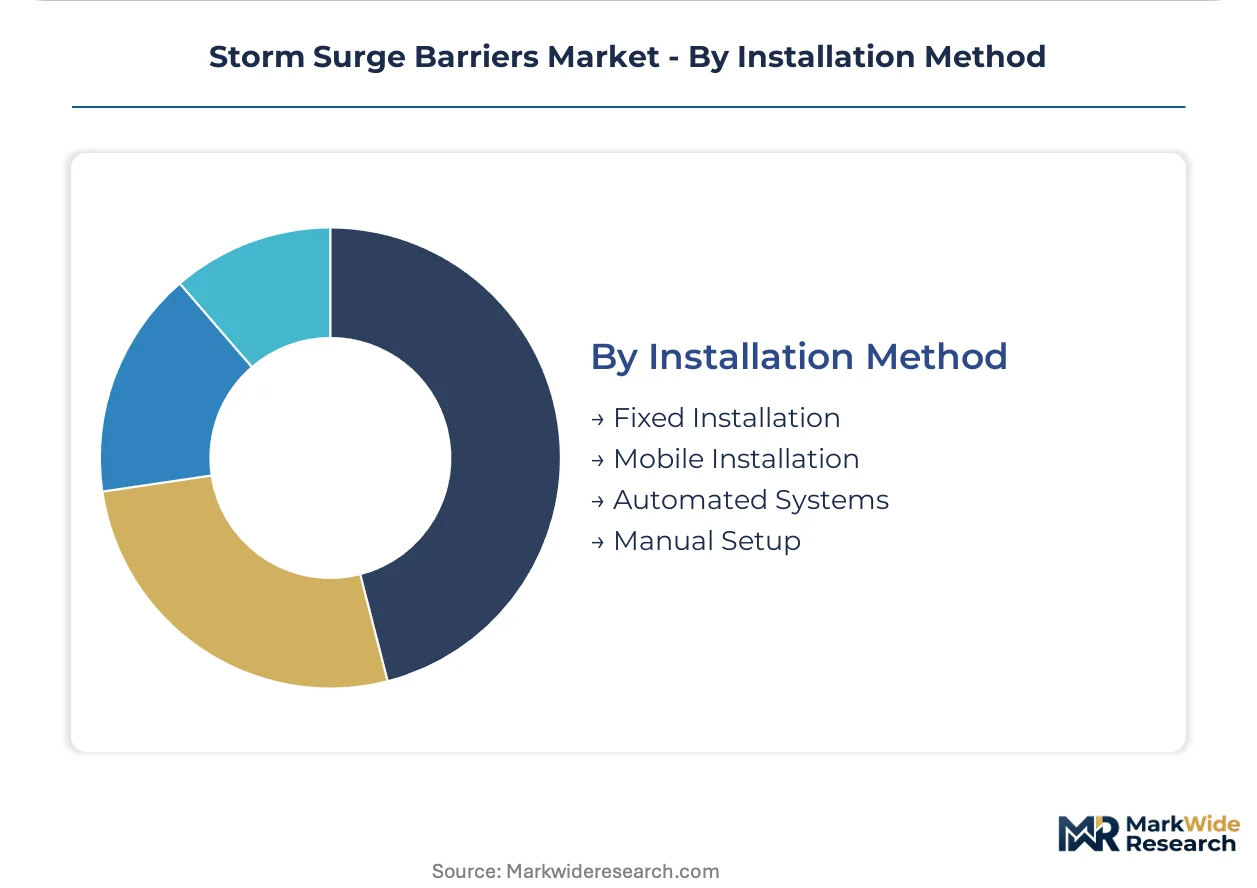
Installation Method:
Operational tempo requirements differentiate capital-intensive fixed infrastructure from adaptive response capabilities.
- Fixed Installation:Permanent foundation systems with integrated gate mechanisms demand multi-year construction timelines and deep geological surveying. Netherlands Delta Programme and U.S. coastal storm risk management projects standardize on fixed installations for critical protection levels.
- Automated Systems:Sensor-triggered closure mechanisms reduce personnel risk and response latency during rapid-onset surge events. Thames Barrier and Venice MOSE operations demonstrate automated protocol maturity.
- Mobile Installation:Barge-mounted or trailer-transported barriers relocate between protection points based on storm trajectory forecasts.
- Manual Setup:Crew-deployed temporary systems require pre-positioned equipment inventories and trained response teams.
Fixed installations anchor the capital stock. Automated systems are expanding most quickly as labor scarcity and safety protocols drive mechanization investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal disaster resilience funding is consolidating procurement authority around pre-qualified engineering consortiums in coastal municipalities. The U.S. Army Corps of Engineers coordinates with FEMA to enforce construction standards mandating freeboard elevations. European water boards impose iterative safety assessments under climate-adjusted scenarios.
United States
Hurricane frequency intensification drives capital allocation toward engineered hydraulic structures with multi-decade design life. The Army Corps of Engineers mandates structural load certifications and freeboard elevations through coastal storm risk management programs. New York Harbor and Gulf Coast installations concentrate demand for reinforced concrete gate systems and foundation pilings.
Netherlands
The Room for the River program reshapes procurement specifications toward multifunctional barrier designs combining flood defense with ecological corridors. National water boards require climate-adjusted sea-level scenario modeling through 2100 under EU Floods Directive mandates. Rotterdam anchors North Sea project pipelines with steel gate systems like the Maeslantkering demonstrating high-cycle operational maturity.
Vietnam
Mekong Delta investments signal sustained infrastructure commitment for integrated design-build movable barrier capabilities. The government prioritizes phased coastal defense buildouts where full capital commitment faces political constraints. Delta municipalities concentrate demand for prefabricated modular units assembled on-site.
Indonesia
Jakarta's coastal defense upgrades concentrate procurement around unbundled design, construction, and long-term operation responsibilities. National disaster management authorities align with international climate finance mechanisms for barrier investments. The capital region exemplifies Southeast Asian fragmentation of vendor specialization across capital construction and maintenance obligations.
United Kingdom
The Thames Barrier demonstrates automated protocol maturity for sensor-triggered closure mechanisms reducing personnel risk. Environment Agency assessments mandate failure-mode resilience under revised hydrological models. London concentrates demand for steel gate systems with precision sealing surfaces in high-cycle operational environments.
Storm Surge Barriers Market Competitive Landscape
On the supply side, the industry is consolidating around engineering consortiums with integrated marine construction and hydraulic design capabilities. Specialized underwater welding and dredging expertise concentrates in North Sea and Gulf Coast geographies, creating tiered qualification thresholds. Three archetypes dominate: heritage marine contractors with dredging lineages, integrated design-build specialists for movable systems, and climate risk advisory firms positioning upstream of capital allocation. Competitive moves center on pre-qualification for federal funding channels and geographic expansion into Southeast Asian delta regions.
Among heritage marine contractors, Boskalis Westminster and Van Oord occupy positions reflecting North Sea and Gulf Coast project concentration. Jan De Nul Group exemplifies the scale-driven archetype with dredging and marine construction lineage. AECOM represents the advisory-positioning vector, anchoring competitive stance through climate risk services upstream of port authority and municipal decisions. These three collectively illustrate how vendor access compresses around technical qualification thresholds and pre-qualified consortium status.
| Leading Market Players |
|---|
| Boskalis Westminster |
| Royal HaskoningDHV |
| Van Oord |
| Jan De Nul Group |
| AECOM |
| Mott MacDonald |
| Royal BAM Group |
| China Communications Construction Company |
| Kiewit Corporation |
| Others |
Value Network & Pricing Analysis
Rotterdam's marine construction cluster concentrates specialized dredging and underwater welding capacity that shapes pricing power for North Sea and Gulf Coast barrier projects. Steel and concrete input volatility feeds directly into project cost estimates, compressing margins for contractors unable to lock in long-term material offtake.
Pricing Analysis
Certification level under EU Floods Directive and U.S. Army Corps of Engineers standards creates the primary spread between premium and standard-tier bids. Project-based contract structures dominate, with price differentiation resting on structural load certification tier and geographic delivery complexity. Cost compression in modular geotextile systems is intensifying as emergency management agencies consolidate procurement volumes. Municipal buyers exhibit highest price sensitivity for temporary barrier inventories, while port authorities demonstrate lowest sensitivity given cargo throughput protection mandates.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Dutch water boards and Southeast Asian development banks stabilize contractor cash flow through multi-year construction timelines. Manufacturing concentration centers on the Netherlands, United States, and China for steel gate systems and reinforced concrete formulations. Raw material dependencies draw from marine-grade steel alloys, high-performance concrete admixtures, and geotextile polymers. Single-source vulnerability runs through specialized underwater welding labor pools concentrated in North Sea and Gulf Coast geographies. Distribution runs through pre-qualified engineering consortiums directly to federal and municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from rapidly deployable geotextile systems that compete for emergency preparedness budgets against permanent steel and concrete infrastructure.
For Market Incumbents: Harden technical qualification thresholds by deepening backward integration into marine steel fabrication and concrete admixture production. Secure pre-qualified consortium status with U.S. Army Corps of Engineers and Dutch water boards before federal disaster resilience funding channels narrow further. Anchor capacity in Rotterdam and Gulf Coast clusters where specialized labor scarcity creates defensive moats against emerging competitors. For New Entrants and Emerging Players: Pursue white-space opportunities in Vietnam's Mekong Delta and Indonesia's Jakarta coastal zone where unbundled design-build contracts fragment vendor specialization. Target modular barrier segments for phased coastal defense buildouts facing political capital constraints. Lead with climate risk advisory services upstream of municipal procurement decisions to establish relationships before capital allocation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated design-build specialists with movable barrier system expertise over pure-play dredging contractors. Long-term viability hinges on climate-adjusted sea-level scenario capabilities across the projection horizon. Watch for inflection signals in federal probabilistic flood risk mapping recalibrations that trigger legacy asset upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Captures margin from marine-grade alloy gate production for Rotterdam and Gulf Coast projects. |
| Climate Risk Advisory Service Launch | Positions upstream of port authority capital allocation decisions in Southeast Asian delta regions. |
| Modular Barrier Manufacturing Scale-Up | Addresses emergency management agency demand for rapid-deploy geotextile inventories. |
| Automated Closure System Development | Reduces personnel risk for Thames Barrier and Venice MOSE operational environments. |
| Long-Term Maintenance Contract Separation | Aligns with Vietnam and Indonesia procurement fragmentation across capital and operational phases. |
Research Methodology
Cross-validation between primary interviews with coastal defense engineers, water board procurement officers, and marine construction project managers and secondary validation through EU Floods Directive compliance filings, U.S. Army Corps of Engineers coastal storm risk management documentation, and national water board safety assessment records anchors the qualitative findings. Bottom-up project pipeline tracking across Rotterdam, New Orleans, New York Harbor, and Southeast Asian delta municipalities triangulates with top-down federal disaster resilience funding allocation analysis.
Calibration against historical barrier installation cost data and operational expenditure patterns across permanent steel gate and modular geotextile segments shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include barrier permanence tier, material durability grade, application type, and installation method complexity. CAGRs derive from iterative safety assessment upgrade cycles and climate-adjusted sea-level scenario integration into procurement specifications.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed marine contractors or accelerated geotextile technology maturation would shift outcomes. Macroeconomic volatility in steel and concrete commodity markets, regulatory tightening under revised EU Floods Directive mandates, or breakthrough advances in inflatable barrier durability would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Internet of Things Testing Market
Others
Liquid-Cooled Heat Sink Market
Others
Eye Balm Market
Others
Baking Paper Market
Others
Stichtite Market
Others
Italy Automotive Adaptive Lighting System Market
Others
Sprockets Market
Others
Short Video Applications Market
Others
Global Molded Plastics Market
Others
Reinforcement Geosynthetics Market
Others
5G Devices Market
Others
Mexico 3D Printing Construction Market
Others
France 3D Printing Construction Market
Others
Global Webinar and Webcast Market
Others
Fresh Durian Market
Others
Cloud Gaming Baas Market