
 Surgical Imaging Robots Market | 2026-2036
Surgical Imaging Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Imaging Robots Market Analysis
China is fragmenting as domestic manufacturers scale robotic imaging assembly while foreign incumbents defend premium positions. Intuitive Surgical leverages its installed base of da Vinci systems to cross-sell imaging modules. Stryker Corporation anchors its Mako platform with proprietary CT-to-robot registration workflows. Medtronic competes through its Hugo system ecosystem, integrating third-party imaging feeds.
Surgical imaging robots combine motorized manipulator arms with intraoperative imaging modalities to enable real-time instrument navigation during minimally invasive procedures; systems typically integrate 0.3-0.5 mm positional accuracy with sub-second image refresh rates to maintain surgical precision. Robotic systems occupy the dominant revenue tier due to capital intensity and service contract attachment, while imaging software captures expanding margin pools as hospitals prioritize AI-enhanced visualization and predictive analytics over hardware-only procurement. Fluoroscopy-guided applications lead procedural volume in orthopedic and cardiovascular segments, though MRI-integrated platforms command premium pricing for neurosurgical interventions.
FDA 510(k) and de novo pathways govern US market entry for autonomous navigation features, while EU MDR and CE marking impose stricter clinical evidence requirements on software-as-medical-device components. Japan's PMDA and China's NMPA maintain divergent cybersecurity standards for connected surgical platforms, complicating global product harmonization. Stakeholders must monitor regulatory divergence on AI-enabled decision support to prioritize development roadmaps and market sequencing.
Market Dynamics
Hospital procurement committees now prioritize AI-enhanced visualization over standalone hardware, compressing capital cycles and forcing vendors to unbundle software subscriptions from robot sales.
Growth Catalysts
- FDA 510(k) streamlining:The FDA's de novo pathway for autonomous navigation features accelerates US market entry for robotic imaging platforms with real-time instrument tracking.
- Japan's metropolitan surgical centers:Dense patient populations in Tokyo and Osaka drive concentrated demand for MRI-integrated neurosurgical robots with sub-millimeter accuracy.
- Fluoroscopy-guided orthopedic applications:Aging populations in Germany and the US expand procedural volumes for knee and hip replacement robotics with intraoperative CT registration.
Market Restraints
- Neodymium magnet supply concentration:China's dominance in rare earth processing creates input cost volatility for MRI-compatible robotic motor assemblies.
- EU MDR clinical evidence requirements:Stricter software-as-medical-device validation timelines extend CE marking cycles for AI-enabled decision support modules.
- Conventional open surgery:Established clinical workflows and lower capital requirements in rural hospital systems resist robotic conversion despite superior outcomes.
Strategic Opportunities
- India's tier-2 city hospital networks:Underpenetrated secondary markets present white space for mobile C-arm robotic platforms with flexible financing models.
- Hybrid operating room retrofit:Convergence of surgical robotics with intraoperative MRI and angiography systems enables premium pricing in neurovascular interventions.
- Japan's PMDA cybersecurity harmonization:Evolving connected device standards create first-mover advantage for vendors with pre-validated data integrity architectures.
Industry Challenges
- Mechatronics engineering talent scarcity:Shortage of specialists combining surgical workflow knowledge with precision robotics design constrains R&D velocity.
- Legacy PACS integration complexity:Hospital IT departments struggle to synchronize proprietary robotic imaging feeds with existing radiology infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Imaging Robots Market |
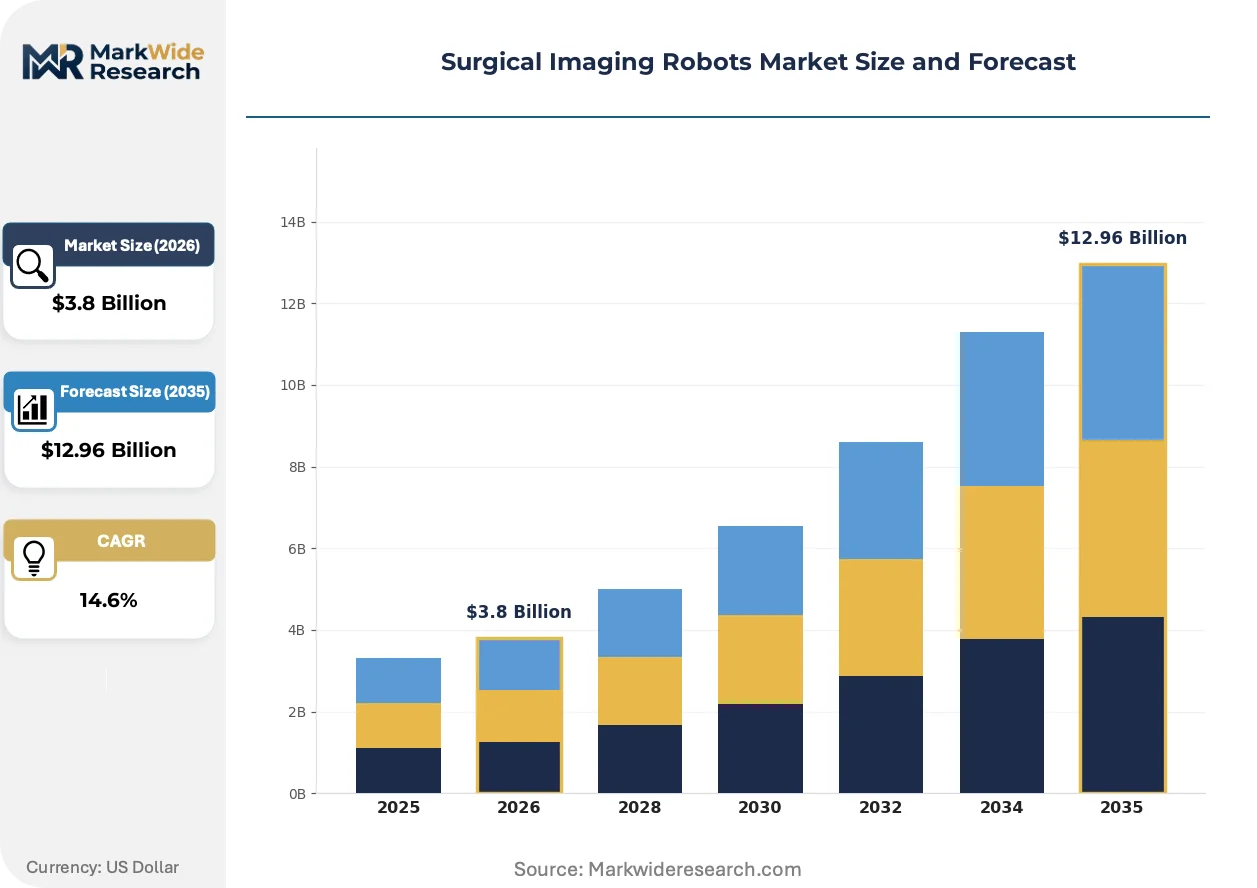
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Imaging Software, Guidance Tools, Control Interfaces End User: Hospitals, Ambulatory Surgical Centers, Research Laboratories, Diagnostic Centers Technology: Fluoroscopy, CT Imaging, MRI Systems, Ultrasound Application: Orthopedic Surgery, Neurosurgery, Cardiovascular Procedures, Oncology |
| Companies Covered | Intuitive Surgical, Stryker Corporation, Medtronic, Johnson & Johnson, Zimmer Biomet, Smith+Nephew, CMR Surgical, Asensus Surgical, Brainlab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Imaging Robots Market Emerging Trajectories
Real-time surgical visualization is fragmenting across multiple imaging modalities, forcing vendors to architect open-platform software stacks that ingest third-party data streams rather than proprietary closed systems.
Holographic light-field displays are virtualizing the surgeon's spatial relationship to anatomy. Academic medical centers in Germany and the US are piloting glasses-free 3D visualization for robotic-assisted procedures. This technology is virtualizing the conventional monitor-based surgical cockpit, compressing the physical footprint required in crowded operating theaters.
The EU MDR's software classification rules are redefining regulatory scope for AI-enhanced imaging algorithms. Manufacturers must now generate clinical evidence for real-time decision support features previously treated as accessory functions. Cardiovascular robotic platforms face the steepest compliance burden due to the MDR's heightened scrutiny of autonomous navigation in critical vessel territories.
Hospital supply chains are consolidating vendor relationships around integrated platform ecosystems. German university hospital networks now demand bundled service contracts spanning hardware, software updates, and predictive maintenance analytics. This consolidation favors vendors with captive imaging technology rather than those dependent on third-party modality partnerships.
Surgical Imaging Robots Market Segmentation
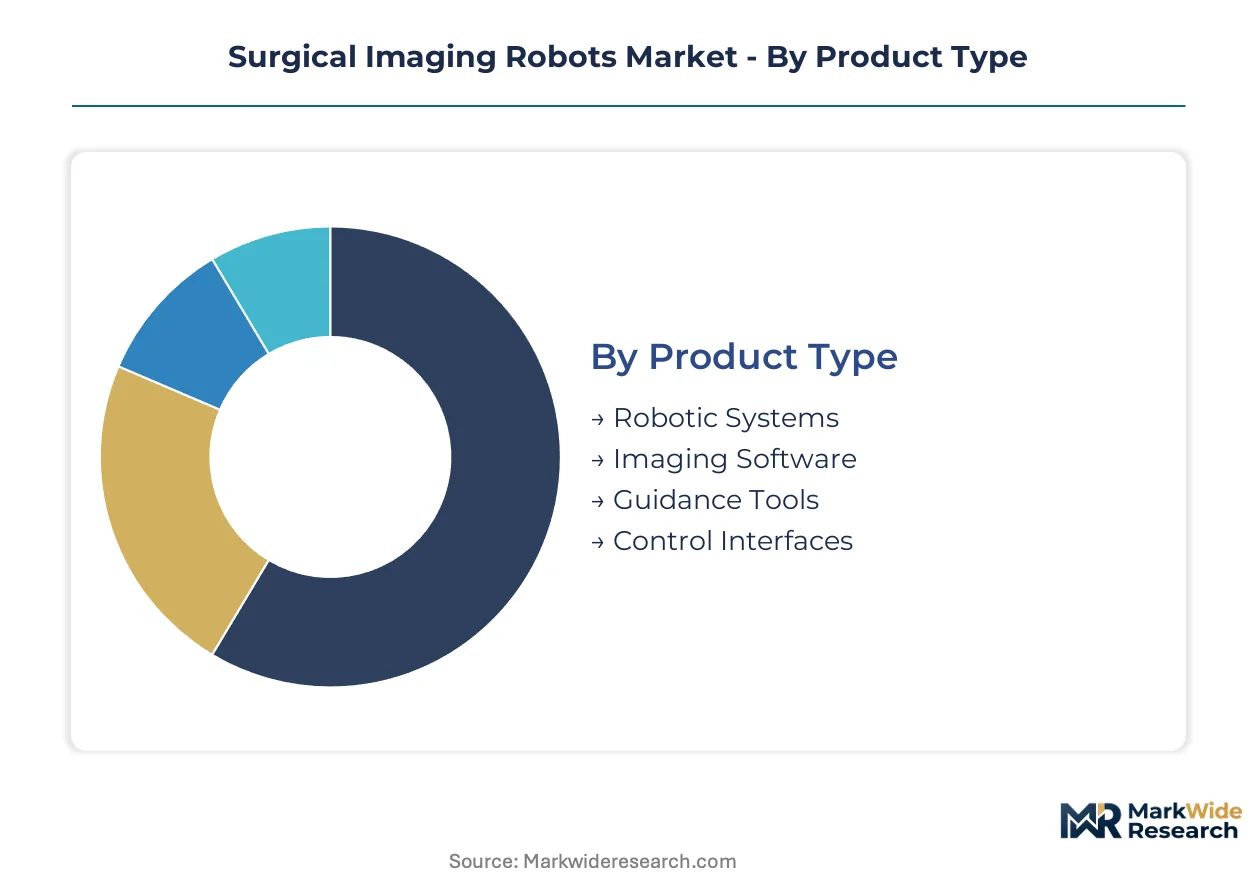
Segmentation in surgical imaging robots reveals distinct service intensity profiles across hardware and software tiers. Vendor profitability depends on matching product architecture to the maintenance and upgrade cadence each segment demands.
Product Type:
After-sales-service intensity varies dramatically across this category, with capital equipment requiring multi-year field engineering contracts while software layers monetize through recurring subscription renewals.
- Robotic Systems:Motorized manipulator platforms integrating 0.3-0.5 mm positional accuracy with intraoperative imaging hardware. Demand concentrates in Germany's university hospital networks where bundled service contracts spanning predictive maintenance analytics command premium pricing.
- Imaging Software:AI-enhanced visualization modules and predictive analytics platforms processing real-time instrument navigation data. Procurement committees in Japan's metropolitan surgical centers prioritize unbundled software subscriptions over hardware-only procurement, compressing traditional capital cycles.
- Guidance Tools:Surgical planning and navigation accessories including CT-to-robot registration workflows.
- Control Interfaces:Surgeon consoles and haptic feedback systems governing robotic arm manipulation.
By volume, Robotic Systems leads. By growth pace, Imaging Software is expanding most quickly.
End User:
Cost tier stratification separates high-acuity inpatient settings from outpatient facilities seeking flexible financing models.
- Hospitals:Integrated health systems performing complex multi-specialty procedures with dedicated hybrid operating room infrastructure. North American hospital systems are accelerating procurement of full-platform robotic ecosystems with captive imaging technology rather than third-party modality partnerships.
- Ambulatory Surgical Centers:Outpatient facilities specializing in high-volume orthopedic and cardiovascular interventions. India's tier-2 city hospital networks present white space for mobile C-arm robotic platforms with lease-based acquisition structures.
- Research Laboratories:Academic medical centers piloting glasses-free 3D holographic visualization and autonomous navigation features.
- Diagnostic Centers:Imaging-focused facilities requiring preoperative planning integration with surgical workflows.
By installed base, Hospitals dominate. By expansion trajectory, Ambulatory Surgical Centers are gaining share fastest.
Technology:
Application specificity drives modality selection, with soft-tissue interventions demanding magnetic resonance compatibility while bone-focused procedures favor radiation-based guidance.
- Fluoroscopy:Real-time X-ray guidance systems delivering sub-second image refresh rates for instrument tracking. Aging populations in Germany and the US are expanding procedural volumes for knee and hip replacement robotics with intraoperative fluoroscopic registration.
- MRI Systems:Magnetic resonance-integrated platforms enabling sub-millimeter accuracy for neurosurgical interventions. Dense patient populations in Tokyo and Osaka drive concentrated demand despite neodymium magnet supply concentration creating input cost volatility.
- CT Imaging:Computed tomography registration for preoperative planning and intraoperative verification.
- Ultrasound:Portable acoustic imaging for soft-tissue navigation and vascular access procedures.
By procedure count, Fluoroscopy leads. By pricing premium, MRI Systems commands the highest tier.
Application:
Regulatory scrutiny intensity varies by anatomical risk, with neurovascular territories facing heightened compliance burdens under EU MDR software classification rules.
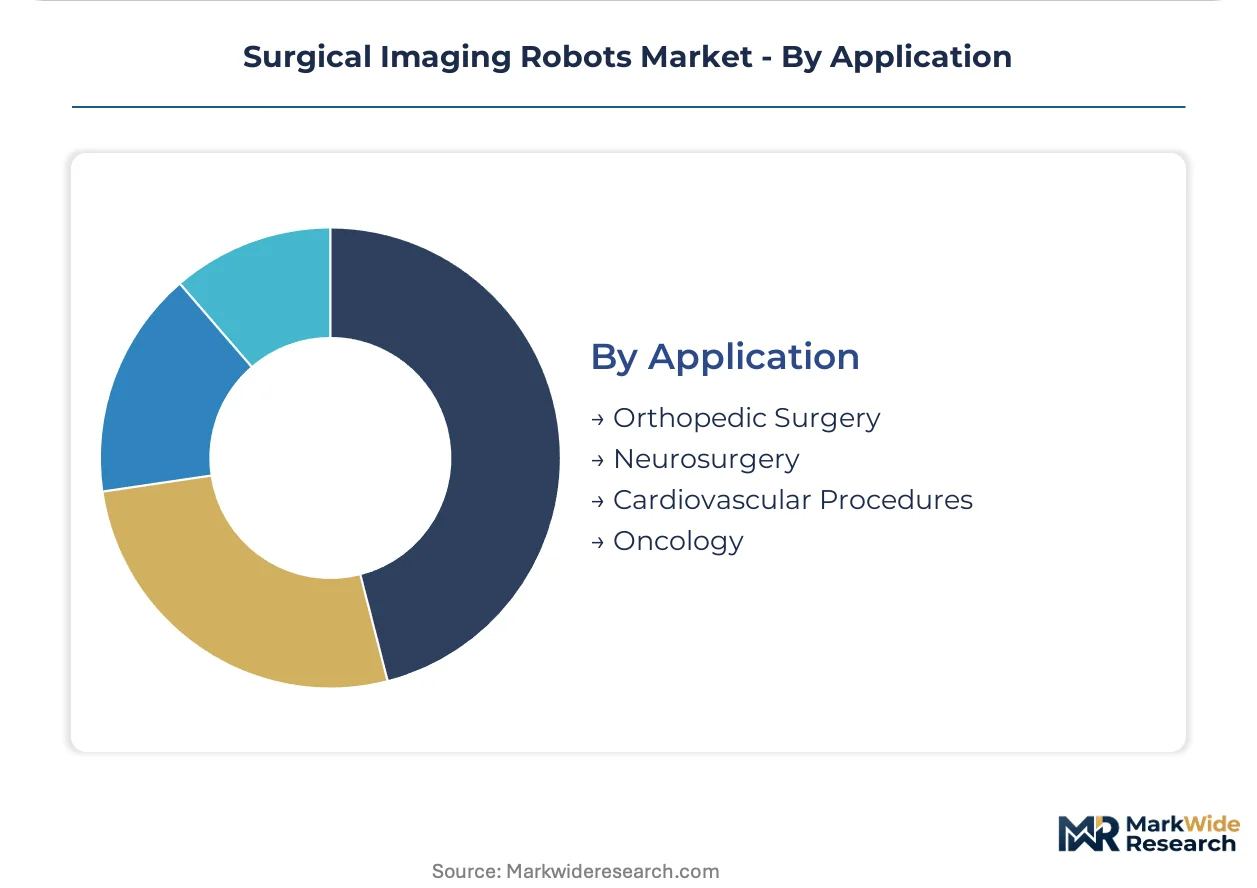
- Orthopedic Surgery:Knee, hip, and spine procedures leveraging robotic assistance for implant positioning. Fluoroscopy-guided applications lead procedural volume due to standardized workflows and reproducible outcomes.
- Neurosurgery:Brain and spinal cord interventions requiring sub-millimeter accuracy and intraoperative MRI compatibility. Academic medical centers in Germany and the US are piloting holographic light-field displays for glasses-free 3D visualization in robotic-assisted procedures.
- Cardiovascular Procedures:Coronary and structural heart interventions with autonomous navigation in critical vessel territories.
- Oncology:Tumor resection and biopsy procedures integrating real-time margin assessment.
By current penetration, Orthopedic Surgery leads. By technology complexity, Neurosurgery sets the frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket clearance pathways anchor the United States as the dominant geography for surgical imaging robot deployment. Hospital systems across the country are accelerating procurement of integrated robotic platforms with AI-enhanced visualization capabilities.
United States
Metropolitan surgical centers in Boston and Houston drive concentrated demand for MRI-integrated neurosurgical robots. The FDA's de novo pathway streamlines market entry for autonomous navigation features with real-time instrument tracking. Academic medical centers in California pilot glasses-free 3D holographic visualization for robotic-assisted procedures.
Germany
University hospital networks prioritize bundled service contracts spanning predictive maintenance analytics and software updates. EU MDR software classification rules impose stricter clinical evidence requirements on AI-enabled decision support modules. Industrial clusters in Baden-Württemberg concentrate precision mechatronics engineering talent for robotic motor assemblies.
Japan
Dense patient populations in Tokyo and Osaka sustain demand for sub-millimeter accuracy neurosurgical platforms. PMDA cybersecurity standards for connected surgical platforms are evolving toward harmonization with international data integrity architectures. Metropolitan surgical centers lead adoption of fluoroscopy-guided orthopedic applications for aging demographics.
China
Domestic manufacturers scale robotic imaging assembly while foreign incumbents defend premium positions in tier-1 cities. NMPA maintains divergent cybersecurity standards from Western regulators, complicating global product harmonization. Yangtze River Delta industrial corridors concentrate rare earth processing for MRI-compatible motor components.
India
Tier-2 city hospital networks present white space for mobile C-arm robotic platforms with lease-based acquisition structures. CDSCO regulatory frameworks are adapting to software-as-medical-device classifications for AI-enhanced imaging. Maharashtra and Karnataka host emerging distribution hubs for flexible financing models in outpatient surgical centers.
Surgical Imaging Robots Market Vendor Landscape
Integrated platform vendors and modular component specialists split the market along the hardware-software boundary. Capital intensity and service contract attachment favor vendors with captive imaging technology over third-party modality partnerships. Two strategic archetypes dominate: ecosystem orchestrators bundling robotics with proprietary imaging workflows, and focused imaging software vendors unbundling subscriptions from hardware sales. Competitive moves concentrate on M&A for AI visualization capabilities and strategic partnerships for PACS integration.
Among United States-based ecosystem orchestrators, Intuitive Surgical and Stryker Corporation exemplify the integrated platform archetype, leveraging installed bases to cross-sell imaging modules and anchor proprietary registration workflows. Medtronic occupies a position representing the open-ecosystem approach, integrating third-party imaging feeds rather than captive modality technology. These three anchors illustrate the strategic divergence between closed and open architecture models reshaping procurement committee preferences.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker Corporation |
| Medtronic |
| Johnson & Johnson |
| Zimmer Biomet |
| Smith+Nephew |
| CMR Surgical |
| Asensus Surgical |
| Brainlab |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta industrial corridors concentrate rare earth processing capacity for neodymium magnets, feeding directly into MRI-compatible robotic motor assemblies and amplifying pricing power for integrated platform vendors who captive-source these critical components.
Pricing Analysis
Geographic price spreads between German university hospital networks and India's tier-2 city facilities exceed threefold, reflecting divergent service bundling intensity. Three-tier pricing structure across premium, standard, and economy levels segments by after-sales service depth and AI-enhanced visualization capabilities. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers scale assembly capacity. Ambulatory surgical centers exhibit highest price sensitivity, while North American integrated health systems prioritize predictive maintenance analytics over unit acquisition cost.
Supply Chain Analysis
Upstream feedstock for MRI-compatible motor assemblies draws from China's rare earth processing dominance, Japan's precision magnet fabrication, and Germany's precision mechatronics engineering clusters. Neodymium, dysprosium, and terbium constitute critical magnetic material inputs. Single-source vulnerability in Yangtze River Delta rare earth refining exposes vendors to input cost volatility. Distribution runs through direct field engineering contracts for capital equipment and cloud-based subscription delivery for imaging software modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement committee consolidation around integrated platform ecosystems has shifted buyer power toward vendors offering bundled hardware-software-service contracts, fragmenting standalone component suppliers.
For Market Incumbents: Entrench proprietary CT-to-robot registration workflows and predictive maintenance analytics as non-substitutable service layers. Deepen backward integration into MRI-compatible motor assemblies to offset neodymium magnet supply concentration. Counter emerging domestic Chinese manufacturers by accelerating FDA de novo pathway submissions for autonomous navigation features. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 city hospital networks through mobile C-arm platforms with lease-based acquisition structures. Target ambulatory surgical centers seeking unbundled imaging software subscriptions over capital-intensive robot procurement. Deploy flexible financing models as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Long-term, this sits as a software-margin-expansion play because imaging software captures expanding margin pools as procurement committees prioritize AI-enhanced visualization over hardware-only procurement. Acquisition targets should feature validated data integrity architectures for PMDA cybersecurity harmonization. Watch EU MDR software classification enforcement intensity as the inflection signal for compliance-cost barriers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Pathway Submission | Accelerates US market entry for autonomous navigation with real-time instrument tracking capabilities. |
| CE Marking Pathway Investment | Addresses EU MDR software-as-medical-device validation requirements for AI-enhanced decision support modules. |
| Hospital System Partnership | Secures bundled service contracts spanning predictive maintenance analytics in German university networks. |
| Software Companion Development | Enables unbundled subscription monetization separate from capital-intensive robotic hardware sales cycles. |
| Reimbursement Strategy | Aligns procedural coding with fluoroscopy-guided orthopedic applications for aging demographic expansion. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with robotic systems engineers, hospital purchasing committee members, biomedical equipment specialists, and GPO contracts managers. Secondary validation drew from FDA 510(k) and de novo clearance databases, EU MDR technical documentation, hospital procurement contract registries, and PMDA cybersecurity guidance publications. Bottom-up installed base modeling and top-down healthcare capital expenditure forecasting were triangulated for cross-verification.
Calibration against historical robotic platform deployment rates and imaging software subscription renewal patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture tier, end-user facility type, imaging modality integration, application specificity, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity to demographic aging patterns and capital cycle compression trends in hospital procurement behavior.
Stress conditions across neodymium magnet supply disruption, EU MDR software classification enforcement intensity, and PMDA cybersecurity standard harmonization timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory pathway stability and hospital IT infrastructure readiness. Material shifts in rare earth export restriction policy or FDA autonomous navigation classification precedent would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Weightbearing Low Dose (CT) Systems Market
Medical Imaging
United States Digital X-Ray Devices Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
Wireless Ultrasound Scanner Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
Diagnostic X-Ray System Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
Imaging Agents Market
Medical Imaging
South Korea Digital X-Ray Market