
 United Kingdom Magnetic Resonance Imaging Market | 2026-2036
United Kingdom Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Magnetic Resonance Imaging Market Analytics
Domestic imaging equipment refurbishment specialists are expanding capacity to serve NHS capital-constrained trusts. Siemens Healthineers leverages its Erlangen engineering base to sustain magnet technology leadership across British teaching hospitals. GE Healthcare anchors its UK position through intensive service contracts with regional radiology networks. Koninklijke Philips NV competes via diagnostic workflow software bundled with scanner hardware.
Magnetic Resonance Imaging employs superconducting magnets generating field strengths from 0.2 to 7 Tesla, using radiofrequency coils and gradient systems to excite hydrogen nuclei and reconstruct tomographic images without ionizing radiation. Closed MRI systems dominate hospital procurement due to superior signal-to-noise ratios for neuro-oncology protocols, while extremity MRI technology captures outpatient facilities seeking lower capital footprints for musculoskeletal diagnostics. Functional MRI applications command premium positioning in research institutes mapping cortical activation patterns.
MHRA enforces UKCA marking requirements for electromagnetic compatibility and patient safety, while NHS England's Diagnostic Imaging Dataset mandates standardized reporting that shapes scanner utilization benchmarks. NICE technology appraisals determine reimbursement eligibility for advanced cardiac and oncological MRI sequences. Stakeholders must monitor NHS capital allocation cycles and MHRA divergence from EU MDR timelines to anticipate procurement windows and compliance burdens.
Market Dynamics
NHS capital allocation cycles and MHRA post-market surveillance intensification are compressing procurement timelines while elevating compliance burdens for magnetic resonance imaging deployments across British hospital trusts.
Growth Catalysts
- NHS Diagnostic Backlog Reduction Mandate:Hospital trusts are accelerating scanner procurement to address accumulated imaging delays, with tertiary centers in London and South East England prioritizing high-field system installations.
- UKCA Marking Enforcement:MHRA electromagnetic compatibility requirements are standardizing safety protocols, creating predictable certification pathways that reduce vendor qualification friction for domestic trusts.
- Functional MRI Research Expansion:Neuroscience institutes are deploying advanced cortical mapping sequences, driving demand for 7 Tesla research-dedicated systems at Oxford, Cambridge, and Imperial College facilities.
Market Restraints
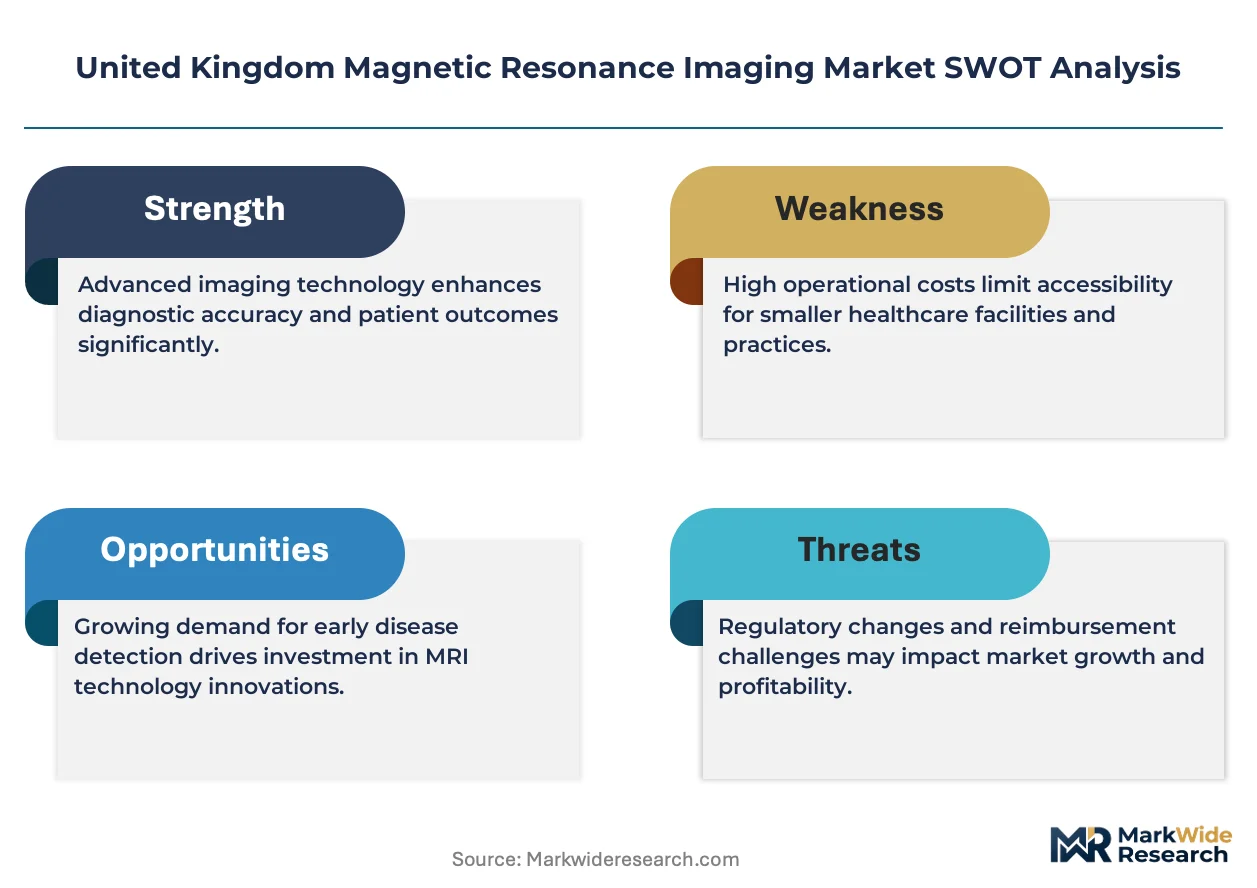
- Liquid Helium Supply Concentration:Superconducting magnet cooling depends on constrained global helium extraction, with Qatar and the United States controlling over eighty percent of refined supply to British OEM service networks.
- Capital Intensity Barriers:Closed-bore 3 Tesla systems require infrastructure investments exceeding fifteen million pounds per installation, excluding NHS trusts with deferred maintenance backlogs from procurement eligibility.
- Workforce Pipeline Constraints:Radiographer training programs produce insufficient qualified operators to match scanner deployment velocity, particularly for advanced cardiac and oncological sequence protocols.
Strategic Opportunities
- Extremity MRI Outpatient Penetration:Lower-field dedicated systems for musculoskeletal diagnostics are capturing private clinic and community hospital segments seeking reduced capital footprints outside London concentration zones.
- Refurbishment Service Scaling:Domestic equipment remanufacturing specialists are building capacity to serve capital-constrained regional trusts, extending asset lifecycles through magnet re-energization and gradient coil replacement.
- NICE Technology Appraisal Alignment:Advanced cardiac MRI sequence reimbursement eligibility determinations are creating procurement justification frameworks that accelerate adoption of stress-perfusion protocols.
Industry Challenges
- Specialized Engineering Talent Scarcity:Superconducting magnet cryogenic system maintenance requires expertise concentrated among aging field service engineers, with apprenticeship pipelines failing to replace retirement-driven attrition.
- Legacy System Integration Complexity:PACS and RIS connectivity protocols vary across NHS trust IT estates, forcing customization overhead for each scanner deployment that compresses vendor margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Magnetic Resonance Imaging Market |
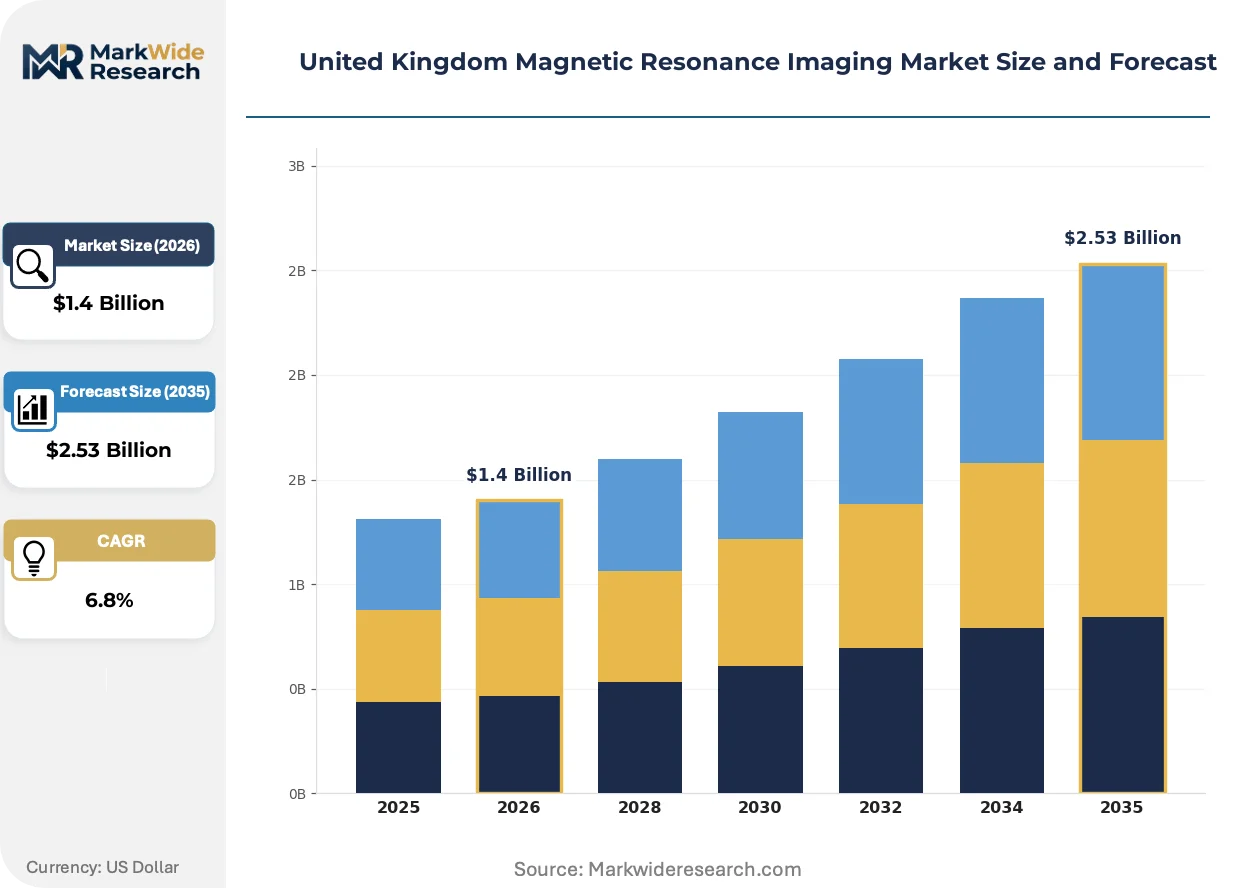
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open MRI, Closed MRI, Extremity MRI, Functional MRI End User: Hospitals, Diagnostic Imaging Centers, Research Institutes, Outpatient Facilities Technology: High Field MRI, Low Field MRI, Extremity MRI Technology, 3T MRI Application: Neurology, Oncology, Cardiology, Musculoskeletal |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips NV, Canon Medical Systems Corporation, Philips Healthcare, Hitachi, United Imaging, Esaote SpA, FUJIFILM Holdings Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Magnetic Resonance Imaging Market Evolving Landscape
Artificial intelligence reconstruction algorithms and helium-free magnet technologies are restructuring capital deployment patterns while regulatory divergence from EU MDR timelines creates compliance complexity for multinational suppliers.
Helium-free superconducting magnet designs utilizing conduction cooling are decentralizing deployment feasibility for mid-field diagnostic systems. Regional NHS trusts previously excluded by cryogenic infrastructure requirements are now qualifying for 1.5 Tesla installations. This technology is decentralizing imaging capacity from London-centric tertiary concentration toward community hospital networks.
MHRA post-market surveillance rulemaking for electromagnetic medical devices is tightening adverse event reporting obligations beyond EU MDR baselines. British teaching hospitals must now maintain enhanced vigilance documentation for gradient coil failures and quench events. High-volume neuro-oncology centers are responding by investing in predictive maintenance telemetry systems.
Trust-level radiology network consolidation is consolidating procurement authority from individual hospitals to regional imaging collaboratives. NHS England Diagnostic Imaging Dataset standardization mandates are enabling benchmark-driven vendor selection across merged purchasing entities. This concentration is most visible in the Midlands and North West England, where five-network structures now govern scanner allocation decisions.
United Kingdom Magnetic Resonance Imaging Market Segmentation
Magnetic resonance imaging procurement patterns across British healthcare infrastructure diverge sharply by clinical setting, magnetic field specification, and anatomical focus. Understanding these fault lines reveals where NHS capital concentrates and where private operators are carving alternative pathways.
Product Type:
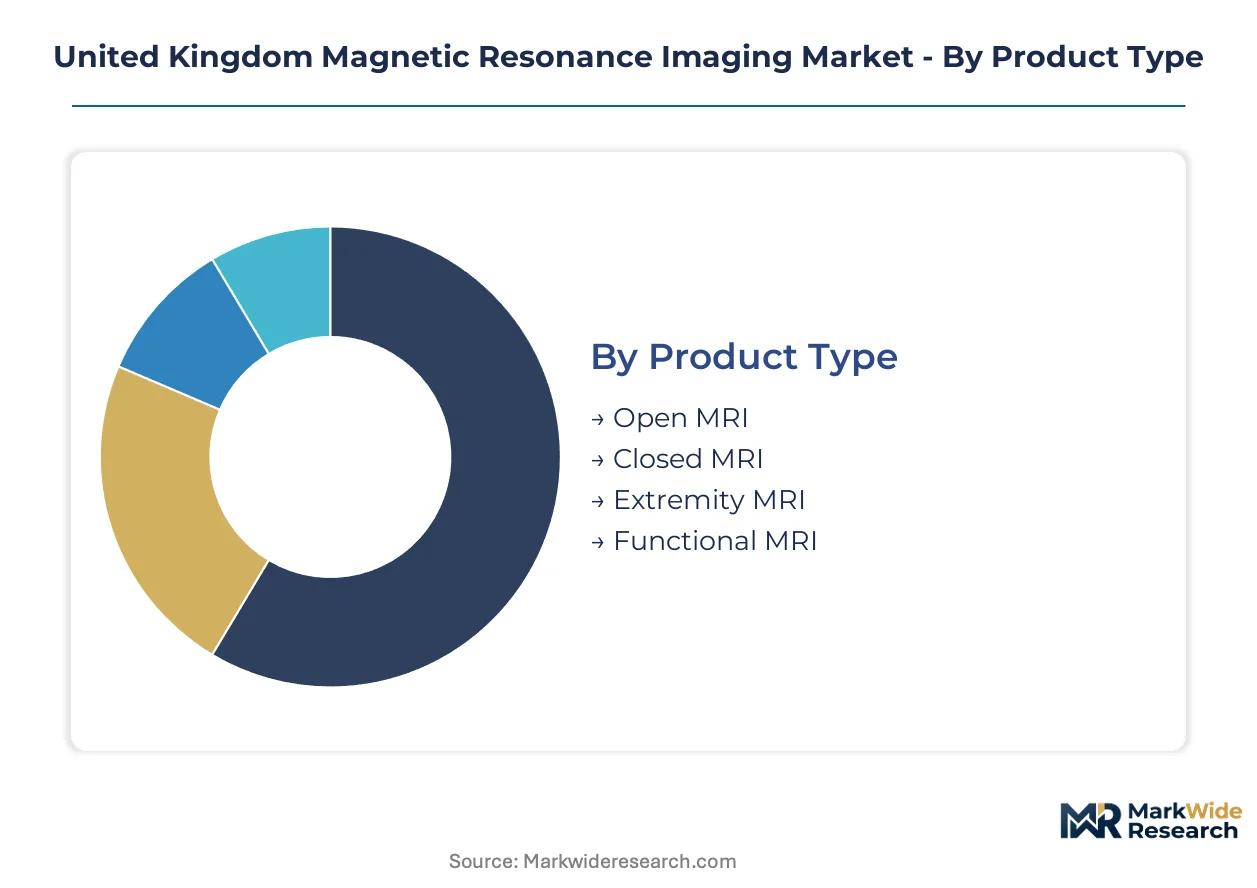
Closed MRI systems dominate procurement volume while extremity configurations capture margin through outpatient specialization.
- Closed MRI:Superconducting bore designs generating 1.5 to 3 Tesla field strengths deliver superior signal-to-noise ratios for neuro-oncology and cardiac protocols. NHS tertiary trusts in London and South East England prioritize these systems for diagnostic backlog reduction, though helium dependency constrains rural deployment.
- Extremity MRI:Dedicated limb-imaging systems operate at lower field strengths with reduced capital footprints, attracting private musculoskeletal clinics in Manchester and Birmingham seeking to bypass hospital referral queues.
- Open MRI:C-shaped magnet architectures accommodate claustrophobic patients and larger body habitus, serving niche pediatric and bariatric segments within community hospital networks.
- Functional MRI:Blood-oxygen-level-dependent imaging sequences map cortical activation patterns, commanding premium positioning at Oxford, Cambridge, and Imperial College neuroscience institutes.
Today's leader: Closed MRI. Tomorrow's challenger: Extremity MRI.
End User:
Institutional purchasing power concentrates in consolidated hospital trusts while research institutes drive specification innovation.
- Hospitals:NHS foundation trusts and teaching hospitals account for the bulk of 3 Tesla system installations, with procurement authority shifting toward regional imaging collaboratives in the Midlands and North West England.
- Research Institutes:University-affiliated neuroscience and cardiovascular research centers specify 7 Tesla ultra-high-field systems for cortical mapping and microstructural imaging, funding through UK Research and Innovation grants rather than clinical reimbursement.
- Diagnostic Imaging Centers:Independent operators in London and Edinburgh compete on appointment availability, favoring 1.5 Tesla workhorse systems with rapid throughput protocols.
- Outpatient Facilities:Community-based musculoskeletal clinics in Bristol and Leeds deploy extremity-dedicated systems for same-day sports injury diagnosis outside hospital radiology queues.
Hospital trusts anchor current procurement volume. Research institutes are climbing the fastest as 7 Tesla adoption accelerates.
Technology:
Field strength tiers separate premium diagnostic capability from accessible mid-range deployment.
- High Field MRI:Systems operating at 3 Tesla and above resolve microstructural tissue detail for oncological staging and cardiac viability assessment, concentrating at specialist centers with dedicated cardiac MRI technologists.
- 3T MRI:The specific 3 Tesla specification has become the NHS gold standard for neuro-oncology protocols, with NICE technology appraisals determining reimbursement eligibility for advanced sequences.
- Low Field MRI:0.5 to 1 Tesla systems serve cost-constrained regional trusts and private operators prioritizing capital efficiency over spectroscopic resolution.
- Extremity MRI Technology:Dedicated limb-imaging platforms at 0.2 to 1 Tesla enable point-of-care musculoskeletal diagnosis without full-body magnet infrastructure.
High Field MRI commands specification leadership. Helium-free conduction cooling is expanding Low Field MRI's addressable market.
Application:
Anatomical specialization drives sequence protocol development and technologist training investment.
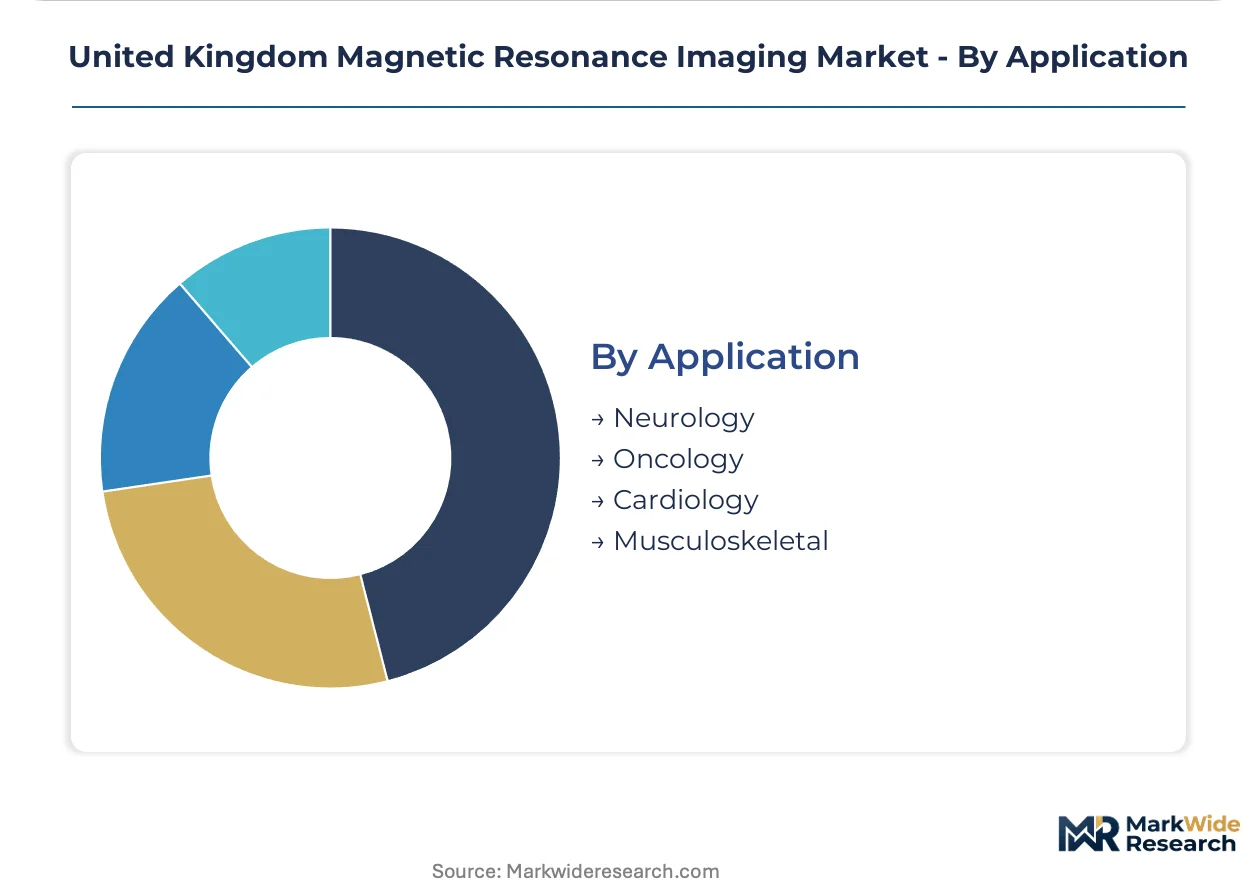
- Neurology:Brain and spinal cord imaging protocols generate the highest scan volumes across British hospital trusts, with functional MRI and diffusion tensor imaging commanding premium reimbursement where NICE appraisals support clinical utility.
- Oncology:Whole-body staging and treatment response monitoring sequences drive 3 Tesla utilization at cancer centers, with multiparametric MRI for prostate and liver emerging as standard-of-care.
- Cardiology:Stress-perfusion and late gadolinium enhancement protocols require specialized technologist training, constraining deployment to centers with dedicated cardiac MRI services.
- Musculoskeletal:Knee, shoulder, and hip imaging represents the highest-volume outpatient indication, feeding demand for extremity-dedicated systems in community settings.
Neurology holds current volume dominance. Cardiology presents the steepest expansion trajectory as stress-perfusion protocols gain NICE reimbursement eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates MRI manufacturing engineering while British hospital trusts drive procurement volume through NHS capital programs. France maintains research leadership through ultra-high-field neuroscience installations. Italy and Spain expand outpatient imaging networks to reduce public system bottlenecks.
Germany
German engineering clusters in Erlangen and Munich sustain superconducting magnet technology leadership for export across European hospital networks. BfArM medical device regulations align with EU MDR frameworks while maintaining streamlined conformity assessment pathways. Siemens Healthineers anchors magnet production in Erlangen, supplying 3 Tesla systems to British teaching hospitals through direct service contracts.
United Kingdom
NHS England Diagnostic Imaging Dataset mandates standardize reporting protocols that shape scanner utilization benchmarks across hospital trusts. MHRA post-market surveillance rules for electromagnetic medical devices tighten adverse event documentation obligations beyond EU baselines. London and South East England tertiary centers concentrate the highest imaging volumes, driving procurement priority for high-field neuro-oncology systems.
France
French university hospitals deploy 7 Tesla research-dedicated MRI systems for cortical mapping through ANR-funded neuroscience programs. ANSM medical device vigilance requirements enforce gradient coil failure reporting that shapes maintenance protocol investments. Paris-Saclay and Lyon neuroscience clusters lead functional MRI adoption for psychiatric and cognitive research applications.
Italy
Italian private diagnostic chains expand extremity MRI capacity in Milan and Rome to capture musculoskeletal outpatient demand outside public hospital queues. AIFA reimbursement determinations for advanced cardiac sequences influence procurement justification frameworks. Northern Italy's Lombardy region concentrates independent imaging center investment through regional healthcare autonomy policies.
Spain
Spanish autonomous community health systems in Catalonia and Madrid prioritize 1.5 Tesla workhorse installations to clear diagnostic backlogs in public hospital networks. AEMPS medical device regulations coordinate with EU MDR implementation timelines while maintaining national vigilance databases. Barcelona and Madrid radiology networks consolidate procurement authority through regional imaging collaboratives mirroring NHS England structures.
United Kingdom Magnetic Resonance Imaging Market Competitive Landscape
German producers anchor the premium-tier magnet technology segment; Japanese and Dutch specialists hold mid-field and diagnostic workflow positions. The vendor structure concentrates around three integrated imaging conglomerates with full-stack capabilities, supplemented by regional refurbishment operators and extremity-dedicated specialists. Archetypes include superconducting magnet technology leaders, diagnostic software-integrated platform providers, and capital-efficient refurbishment service builders. Competitive dynamics center on intensive service contract anchoring and helium-free magnet technology licensing.
Within the premium-tier magnet technology segment, Siemens Healthineers and GE Healthcare exemplify integrated conglomerates with engineering depth. Koninklijke Philips NV occupies a position emphasizing diagnostic workflow software bundled with scanner hardware. Canon Medical Systems Corporation represents the Japanese specialist archetype with concentrated presence in select European hospital networks. These three anchors illustrate the competitive structure: German engineering leadership, American service contract intensity, and Dutch software-hardware integration.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Philips Healthcare |
| Hitachi |
| United Imaging |
| Esaote SpA |
| FUJIFILM Holdings Corporation |
| Others |
Value Network & Pricing Analysis
NHS regional imaging collaboratives concentrate procurement authority across merged purchasing entities, anchoring contract-based long-term offtake as the dominant pricing model for high-field scanner deployments. Three-tier pricing structure across premium, standard, and economy levels separates 7 Tesla research systems from 3 Tesla clinical workhorses and 1.5 Tesla refurbished installations.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for superconducting magnet components, compressing margins on mid-field system sales to British regional trusts. Price differentiation centers on helium-free conduction cooling certification and MHRA UKCA marking tier, with tertiary centers showing least price sensitivity due to UK Research and Innovation grant funding. Cost compression in the refurbished equipment tier is intensifying because domestic remanufacturing specialists are scaling magnet re-energization capacity.
Supply Chain Analysis
Single-source vulnerability sits with Qatar and the United States for refined liquid helium supply to British OEM service networks. Superconducting magnet manufacturing draws from Germany, Japan, and the Netherlands for cryogenic system components, gradient coil windings, and radiofrequency electronics. Tariff exposure on Chinese-sourced rare earth elements for permanent magnet subassemblies threatens cost stability. Distribution runs through Siemens Healthineers Erlangen engineering base, GE Healthcare regional service hubs, and Philips diagnostic workflow software licensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MHRA post-market surveillance divergence from EU MDR timelines creates regulatory arbitrage opportunities for vendors prioritizing UKCA marking pathways over CE marking investments. Helium supply concentration in Qatar versus conduction cooling manufacturing scale-up in Germany presents a cost-structure differential for procurement strategy.
For Market Incumbents: Lock in intensive service contract anchoring with NHS regional imaging collaboratives to defend against domestic refurbishment specialist encroachment. Prioritize helium-free magnet technology licensing to reduce cryogenic infrastructure dependency for capital-constrained community hospital networks. Vertical integration into predictive maintenance telemetry addresses MHRA adverse event reporting intensification. For New Entrants and Emerging Players: Launch via extremity MRI outpatient clinic partnerships in Manchester, Birmingham, and Leeds to bypass London-centric tertiary procurement concentration. Target musculoskeletal diagnostic centers with lowest 3 Tesla penetration and highest private referral queue volumes. Pursue NICE technology appraisal alignment for stress-perfusion cardiac sequences as reimbursement justification accelerant. For Investors and Strategic Acquirers: Domestic equipment refurbishment specialists are the most active acquirer category in this space, consolidating regional service capabilities to extend asset lifecycles. Long-term viability rests on helium-free magnet technology adoption curves and radiographer training pipeline expansion rates. Watch NHS capital allocation cycle timing as the inflection signal for procurement window acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Free Magnet Technology Licensing | Reduces cryogenic infrastructure dependency for regional NHS trusts outside London concentration zones. |
| NICE Technology Appraisal Alignment | Creates reimbursement justification frameworks accelerating stress-perfusion cardiac MRI protocol adoption. |
| Regional Imaging Collaborative Partnership | Consolidates procurement authority from individual hospitals to merged purchasing entities in Midlands and North West England. |
| Predictive Maintenance Telemetry Investment | Addresses MHRA gradient coil failure and quench event reporting obligations beyond EU MDR baselines. |
| Radiographer Training Pipeline Expansion | Resolves workforce constraints limiting advanced cardiac and oncological sequence protocol deployment velocity. |
Research Methodology
Direct dialogue with NHS trust procurement directors, biomedical engineering leads, GPO contracts managers, and MHRA regulatory affairs specialists grounded this analysis in operational reality. Secondary validation drew from NHS England Diagnostic Imaging Dataset publications, MHRA post-market surveillance guidance documents, NICE technology appraisal records, and UK Research and Innovation grant disbursement data. Bottom-up trust-level scanner deployment tracking triangulated against top-down OEM revenue segmentation.
Bottom-up modeling segmented the market by field strength tier, clinical application, end-user institution type, and geographic procurement cluster across the analysis window. CAGRs were derived from trust capital allocation cycle timing, helium supply constraint trajectories, and workforce pipeline expansion rates. Forecast inputs incorporated NICE reimbursement eligibility determinations and MHRA regulatory divergence timelines.
Several conditions sit outside the modeled scope, including EU MDR alignment reversals, Qatar helium export policy shifts, and radiographer strike action impacts. Forecasts reflect documented assumptions about NHS capital maintenance backlog clearance rates and helium-free magnet technology cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Diagnostic Ultrasound Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Italy Mammography Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
China VNA and PACS Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
United Kingdom Mammography Market