
 Edge Computing Market | 2026-2036
Edge Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Edge Computing Market Analysis
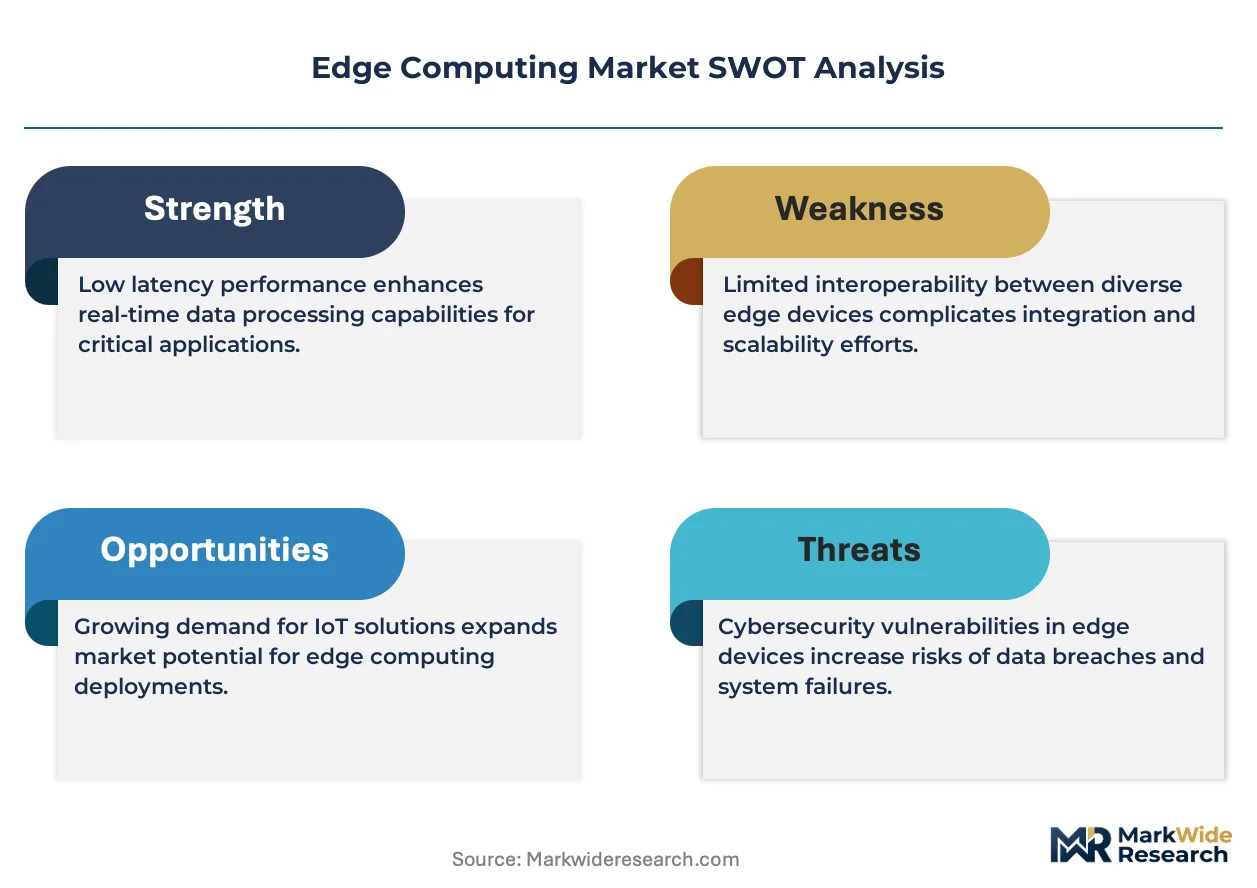
Platform licensing revenue is tilting away from pure cloud subscriptions toward hybrid edge orchestration stacks. Hewlett Packard Enterprise dominates enterprise-grade edge hardware with its integrated server-gateway portfolios. Amazon Web Services leverages its Outposts and Wavelength services to extend cloud APIs into telco edge locations. NVIDIA anchors high-performance AI inference at the edge through its GPU-accelerated computing platforms.
Edge computing processes data geographically proximate to its source using distributed nodes with sub-50 millisecond latency thresholds, enabling real-time analytics without centralized cloud round-trips. Industrial Automation applications command the deepest margin pools as factory operators pay premiums for deterministic control systems. Edge Analytics technology is expanding fastest as machine learning inference shifts from hyperscale data centers to local nodes. Hybrid Cloud deployment models attract the largest capital commitments from enterprises seeking workload portability between on-premises infrastructure and cloud backbones.
FCC spectrum rules in the United States shape private 5G network deployments that underpin industrial edge connectivity. The EU AI Act and GDPR collectively mandate data localization, directly stimulating European edge infrastructure buildouts. Stakeholders must monitor how national cybersecurity certification schemes fragment interoperability standards across jurisdictions.
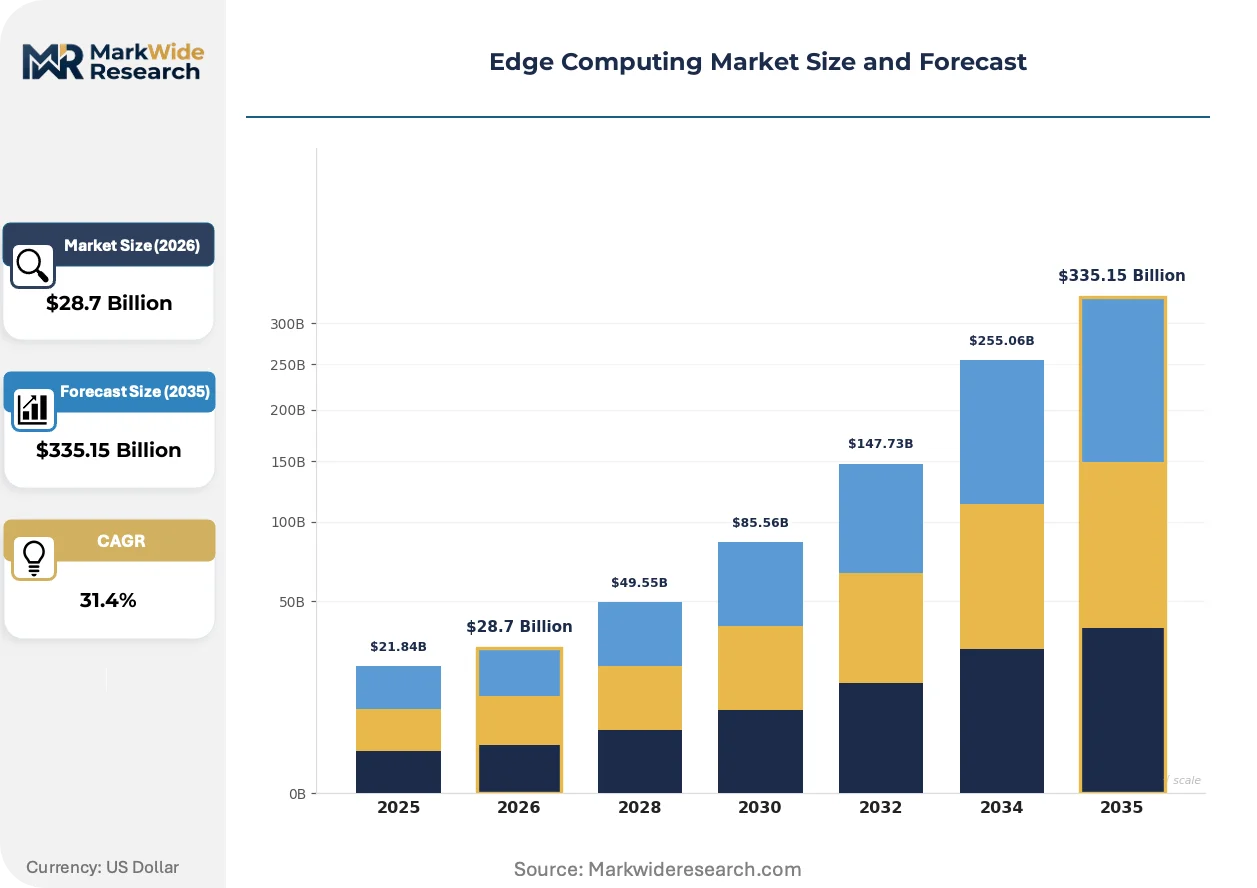
Market Dynamics
The edge computing market is undergoing structural reconfiguration as latency-sensitive workloads migrate from centralized hyperscale facilities to distributed nodes positioned within 50 milliseconds of data sources. Manufacturing automation, autonomous systems, and real-time inference pipelines are forcing infrastructure architects to abandon cloud-first assumptions in favor of geographically dispersed compute topologies.
Growth Catalysts
- EU AI Act compliance mandates:European operators face binding requirements for localized data processing, directly stimulating edge infrastructure deployment across Germany, France, and the Netherlands.
- Predictive maintenance workflows:Automotive and heavy machinery producers in Germany's industrial corridor are expanding edge node density to enable sub-20-millisecond anomaly detection on production lines.
- Private 5G spectrum allocation:FCC rules in the United States are unlocking licensed spectrum for industrial campuses, creating dedicated connectivity layers that bypass public network congestion.
Market Restraints
- Silicon supply concentration:Advanced GPU and AI accelerator fabrication remains concentrated among a limited set of foundry operators, creating procurement bottlenecks for edge server vendors.
- Interoperability fragmentation:Divergent national cybersecurity certification schemes across jurisdictions are forcing redundant hardware validation cycles that extend deployment timelines.
- Energy input cost volatility:Edge data centers lack the scale efficiencies of hyperscale facilities, exposing operators to disproportionate electricity price swings that compress operating margins.
Strategic Opportunities
- Healthcare AI inference at the point of care:Hospitals and diagnostic imaging centers represent underpenetrated deployment sites for FDA-regulated edge devices that process patient data without cloud transmission.
- Japan's METI industrial digitization incentives:Government-backed subsidies for smart factory infrastructure are creating dedicated funding pools for edge computing integration in automotive and electronics manufacturing.
- Convergence of edge analytics with digital twin platforms:Real-time simulation workloads are creating demand for hybrid architectures that combine local inference with cloud-based model training.
Industry Challenges
- Embedded systems firmware expertise scarcity:The talent pool for low-latency kernel optimization and real-time operating system configuration remains shallow relative to cloud-native development skills.
- Legacy industrial protocol integration:Brownfield manufacturing environments operate on decades-old fieldbus standards that require costly protocol translation gateways to interface with modern edge compute nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge Computing Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $335.15 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Cities, Industrial Automation, Remote Monitoring, Connected Vehicles Technology: IoT Devices, Edge Gateways, Fog Computing, Edge Analytics Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud End User: Manufacturing, Healthcare, Retail, Telecommunications |
| Companies Covered | Hewlett Packard Enterprise, Amazon Web Services, Cisco Systems, Dell Technologies, Microsoft, Intel, NVIDIA, IBM, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge Computing Market Emerging Trajectories
Workload placement logic is inverting as deterministic latency requirements override cost-optimization priorities that previously favored centralized cloud consolidation. Infrastructure architects now design for geographic proximity first, with cost as a secondary constraint.
GPU-accelerated inference engines are migrating from hyperscale data centers to factory floor nodes and cellular base stations. Automotive quality engineers and telecommunications operators are adopting these platforms at accelerated procurement cycles. This technology shift is compressing the acceptable latency window for industrial vision systems from hundreds of milliseconds to single-digit thresholds.
The EU AI Act and GDPR are jointly mandating data localization for high-risk AI applications, prohibiting cross-border transfers of inference outputs in sensitive categories. European machinery producers and healthcare device manufacturers must now maintain sovereign compute capacity within national boundaries. German automotive suppliers are responding by establishing dedicated edge zones within existing factory footprints rather than relying on cloud region proximity.
Industrial buyers are consolidating vendor relationships around integrated hardware-software stacks that reduce operational complexity. Discrete procurement of servers, networking, and orchestration platforms is giving way to single-source edge platform contracts. This pattern is most pronounced in the United States, where FCC-enabled private 5G deployments are being bundled with compute infrastructure under multi-year managed service agreements.
Edge Computing Market Segmentation
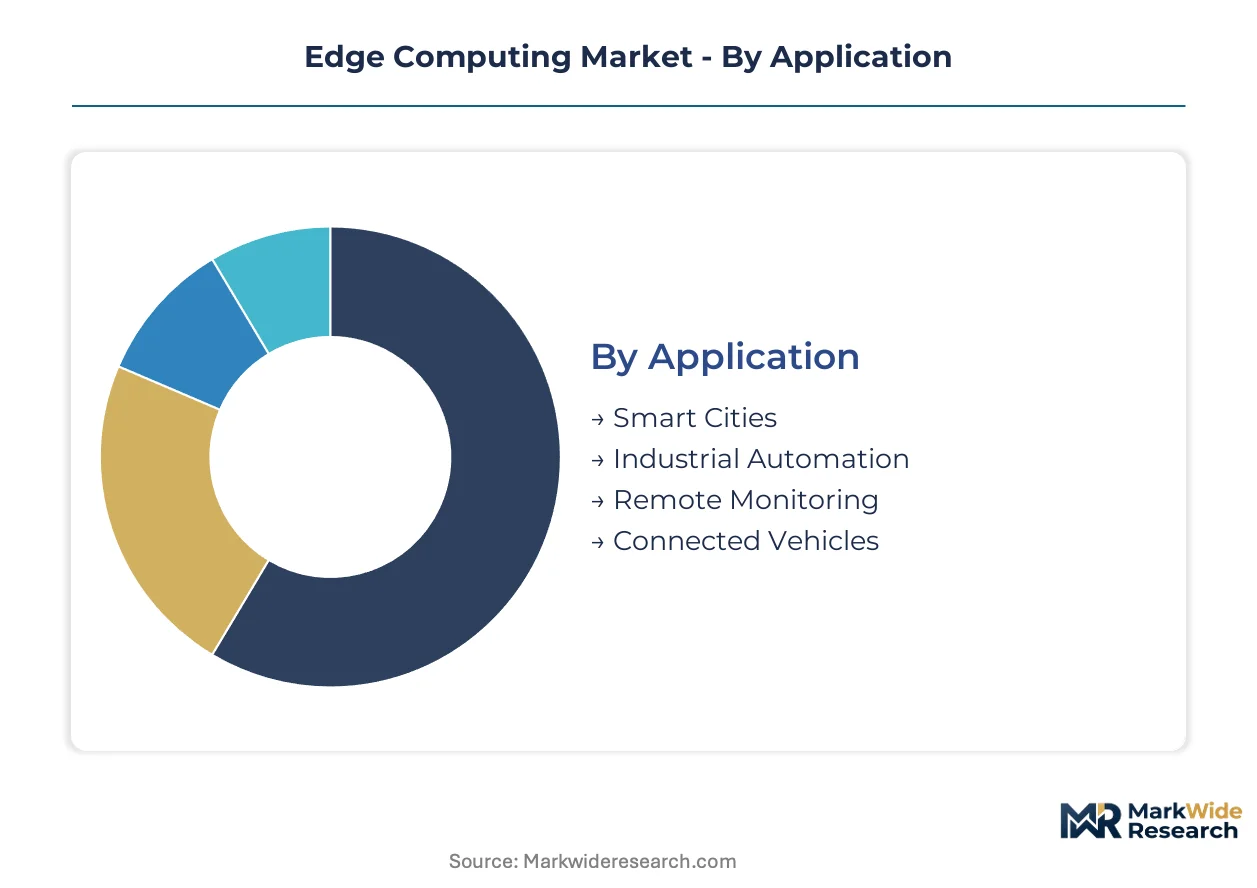
Edge computing architectures serve radically different latency, sovereignty, and scalability requirements across use cases. Segmentation reveals where infrastructure investments concentrate and which deployment patterns command premium pricing.
Application:
Smart city traffic orchestration, factory floor control, and vehicle-to-infrastructure communication each impose distinct millisecond thresholds on compute placement.
- Smart Cities:Municipal operators deploy edge nodes at traffic intersections and utility substations to process video analytics and sensor fusion locally. Demand clusters in Germany's urban centers where GDPR mandates restrict cloud data egress from public surveillance systems.
- Industrial Automation: Deterministic control systems for robotic assembly and quality inspection require sub-10-millisecond feedback loops. German automotive suppliers in Baden-Württemberg anchor the deepest investment pools for these deployments.
- Remote Monitoring: Oil field operators and renewable energy farms use satellite-linked edge nodes for predictive equipment diagnostics in bandwidth-constrained environments.
- Connected Vehicles:Cellular vehicle-to-everything (C-V2X) infrastructure demands roadside edge computing for collision avoidance and traffic coordination.
The dominant share belongs to Industrial Automation, while Smart Cities is closing the gap fastest.
Technology:
Hardware-software boundaries blur as integrated stacks replace discrete component procurement.
- IoT Devices:Sensors and actuators with embedded microcontrollers form the data generation layer. Manufacturing lines in Japan's Aichi Prefecture drive volume for vibration and thermal monitoring endpoints.
- Edge Gateways:Protocol translation and local aggregation nodes bridge legacy industrial equipment with modern IP networks. FCC-enabled private 5G deployments in Texas and Ohio industrial parks accelerate gateway refresh cycles.
- Fog Computing:Distributed compute nodes between edge devices and cloud cores handle regional workload balancing for multi-site enterprises.
- Edge Analytics:GPU-accelerated inference engines process machine learning models at data sources. Healthcare imaging centers in France deploy these for radiological analysis without patient data transmission.
Edge Analytics claims the steepest expansion trajectory as AI inference migrates from centralized facilities.
Deployment Model:
Workload portability requirements and data sovereignty rules dictate architecture choices.
- On-Premises:Dedicated compute infrastructure within facility boundaries serves classified defense applications and regulated healthcare environments. German machinery producers favor this model for EU AI Act compliance.
- Hybrid Cloud:Orchestrated workloads span local edge nodes and hyperscale cloud backbones. Retail chains in the United States adopt this pattern for inventory optimization across distribution networks.
- Public Cloud:Managed edge services extend cloud provider APIs to distributed points of presence. Telecommunications operators leverage these for rapid service deployment without capital-intensive hardware ownership.
- Private Cloud:Single-tenant edge infrastructure serves financial services and government agencies with stringent isolation requirements.
Hybrid Cloud attracts the largest capital commitments, though On-Premises is gaining share fastest among regulated European industries.
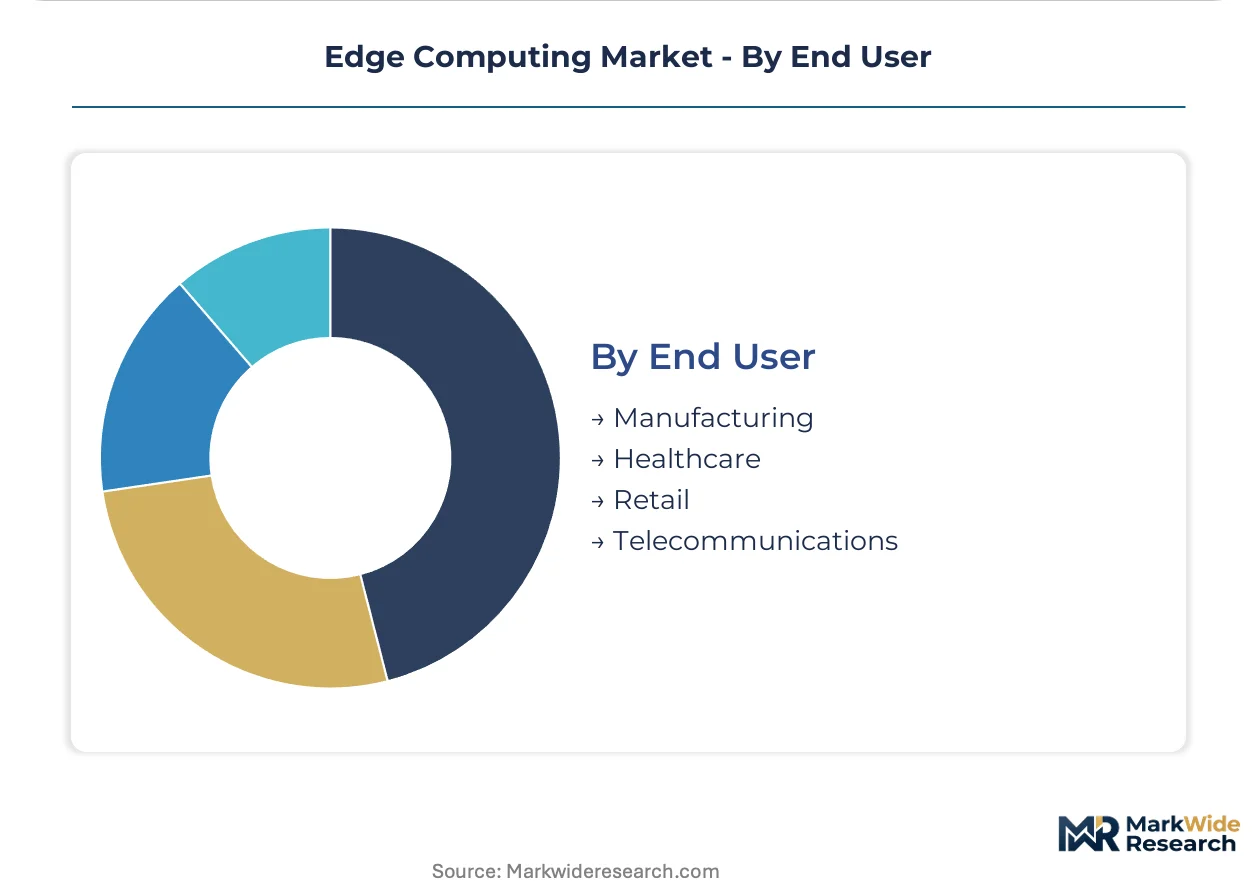
End User:
Sector-specific latency tolerances and compliance burdens create divergent procurement patterns.
- Manufacturing:Automotive and electronics producers deploy edge nodes for real-time quality control and predictive maintenance. Japan's METI subsidies accelerate smart factory adoption in Toyota City and surrounding industrial clusters.
- Healthcare:Hospitals and diagnostic centers process imaging and patient monitoring data locally to satisfy HIPAA and GDPR constraints. FDA-regulated edge devices are expanding fastest in surgical robotics and point-of-care diagnostics.
- Retail:Computer vision systems for inventory management and checkout automation drive edge node deployment in distribution centers and flagship stores.
- Telecommunications:Mobile network operators install edge computing at cellular base stations to support low-latency enterprise services and network function virtualization.
Manufacturing retains the dominant position, while Healthcare is expanding most quickly as regulatory pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers prioritize latency performance over unit economics, while European purchasers absorb premium pricing to satisfy regulatory mandates. Asian manufacturers represent the most price-elastic demand segment, optimizing for total cost of ownership across high-volume deployments.
United States
Private 5G network buildouts by industrial operators and autonomous vehicle testing corridors drive infrastructure investment. FCC spectrum allocation rules for CBRS and millimeter-wave bands enable dedicated campus connectivity. Edge node deployment concentrates in Texas and Ohio industrial parks where automotive suppliers process real-time quality data.
Germany
Automotive and heavy machinery producers demand sub-20-millisecond predictive maintenance systems for production line continuity. EU AI Act compliance mandates localized data processing for high-risk AI applications, prohibiting cloud egress. Baden-Württemberg's industrial corridor anchors the deepest investment pools for deterministic control systems.
Japan
Electronics manufacturers and automotive suppliers accelerate smart factory digitization under government-backed incentives. METI subsidies for industrial infrastructure create dedicated funding pools for edge computing integration. Toyota City and surrounding Aichi Prefecture clusters drive volume for vibration monitoring and thermal sensing endpoints.
France
Healthcare imaging centers and diagnostic facilities deploy GPU-accelerated inference engines for radiological analysis without patient data transmission. GDPR and ANSM regulations mandate strict data localization for medical AI applications. Paris and Lyon metropolitan areas concentrate deployment of FDA-equivalent regulated edge devices.
China
Industrial internet platforms and smart manufacturing initiatives push edge node density into factory environments. MIIT standards for industrial digitization guide infrastructure architecture decisions. Yangtze River Delta manufacturing hubs prioritize real-time analytics for electronics and automotive component production.
Edge Computing Market Vendor Landscape
Capability concentration sits with integrated hardware-software stack providers; scale advantage sits with hyperscale cloud operators extending distributed infrastructure. The market structures around three tiers: enterprise server vendors with gateway portfolios, telecommunications equipment suppliers with private network integration expertise, and cloud providers monetizing API extensions to edge locations. Dominant competitive moves include strategic partnerships between industrial automation specialists and connectivity vendors, plus portfolio diversification into managed edge services.
Within the integrated infrastructure tier, Hewlett Packard Enterprise and Dell Technologies exemplify full-stack positioning through server-gateway combinations. NVIDIA occupies a distinct position anchoring GPU-accelerated inference platforms that migrate AI workloads from centralized facilities to factory-floor nodes. Among hyperscale cloud operators, Amazon Web Services represents the archetype of extending cloud APIs into telco edge locations through managed service offerings.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Amazon Web Services |
| Cisco Systems |
| Dell Technologies |
| Microsoft |
| Intel |
| NVIDIA |
| IBM |
| Huawei Technologies |
| Others |
Supply Flow & Price Mechanics
Taiwan's foundry capacity for advanced AI accelerators dictates pricing power across the edge server supply base, with GPU allocation constraints propagating cost premiums through enterprise hardware procurement cycles.
Pricing Analysis
Managed service contracts and extended support agreements generate lifetime value multiples exceeding three times initial hardware revenue. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale-integrated stacks from bare-metal gateway offerings. Cost compression in mid-tier orchestration software is intensifying because open-source Kubernetes distributions erode proprietary platform premiums. Automotive OEMs in Germany's Baden-Württemberg corridor exhibit lowest price sensitivity, while Southeast Asian electronics assemblers optimize aggressively for total cost of ownership.
Supply Chain Analysis
US Commerce Department export controls on advanced GPU and AI accelerator shipments to designated markets fragment procurement channels for edge infrastructure vendors. Advanced semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, while edge gateway assembly draws from China, Mexico, and Vietnam. Supply chain vulnerability rests on single-source dependency for CoWoS advanced packaging capacity. Distribution runs through direct OEM relationships for enterprise deployments and telecommunications equipment distributors for private 5G-integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems firmware expertise and real-time kernel optimization talent sit in chronic undersupply relative to cloud-native development skills, compressing deployment velocity for latency-critical applications.
For Market Incumbents: Pre-empt firmware talent scarcity by acquiring specialist embedded engineering boutiques in Germany's industrial corridor and Japan's Aichi Prefecture. Establish captive training pipelines for real-time operating system configuration. Lock in multi-year GPU allocation agreements with foundry partners before export control expansion tightens supply further.
For New Entrants and Emerging Players: Healthcare imaging centers in France and diagnostic facilities under ANSM jurisdiction represent the most penetrable entry point for FDA-equivalent regulated edge devices. Mid-market manufacturing automation in Japan's METI-subsidized smart factory clusters offers second-tier opportunity. Lead with sovereign data compliance as the go-to-market wedge against hyperscale cloud incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because workload placement logic permanently inverts toward geographic proximity. Target vertically integrated edge platform specialists with private 5G deployment expertise and healthcare regulatory clearance. Watch FCC spectrum auction participation rates and EU AI Act enforcement intensity as inflection indicators for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Private 5G Spectrum Acquisition | FCC-enabled campus networks bypass public congestion for deterministic industrial control. |
| GPU-Accelerated Inference Platform Integration | NVIDIA EGX stacks migrate AI workloads from hyperscale facilities to factory-floor nodes. |
| EU AI Act Compliance Certification | GDPR-mandated data localization creates premium pricing for sovereign edge infrastructure. |
| Healthcare Regulatory Clearance Pathway | FDA and ANSM approvals unlock point-of-care diagnostic imaging without cloud transmission. |
| Managed Edge Service Partnership | Telecommunications operators bundle compute infrastructure under multi-year service agreements. |
Methodological Framework
Operator-level perspectives from plant engineers, IT infrastructure directors, telecommunications procurement officers, and industrial automation specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, FCC spectrum allocation records, and EU regulatory implementation guidance. Bottom-up deployment sizing triangulated against top-down market aggregation across the analysis window.
Scenario-bracketing framed low, base, and high cases reflecting regulatory enforcement variance and silicon supply disruption probabilities. Segmentation dimensions modeled include deployment model, application latency tier, end-user vertical, and regional regulatory cluster. CAGRs derived from S-curve adoption patterns fitted to historical infrastructure technology diffusion. Forecast inputs incorporated private 5G spectrum auction timelines and EU AI Act implementation phases.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles and electricity price volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and foundry capacity expansion. Material shifts in export control scope or cybersecurity certification fragmentation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market
Emerging and Next Generation Technologies
Global Terahertz Technology Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Swarm Intelligence Market