
 Swarm Computing Market | 2026-2036
Swarm Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Swarm Computing Market Outlook
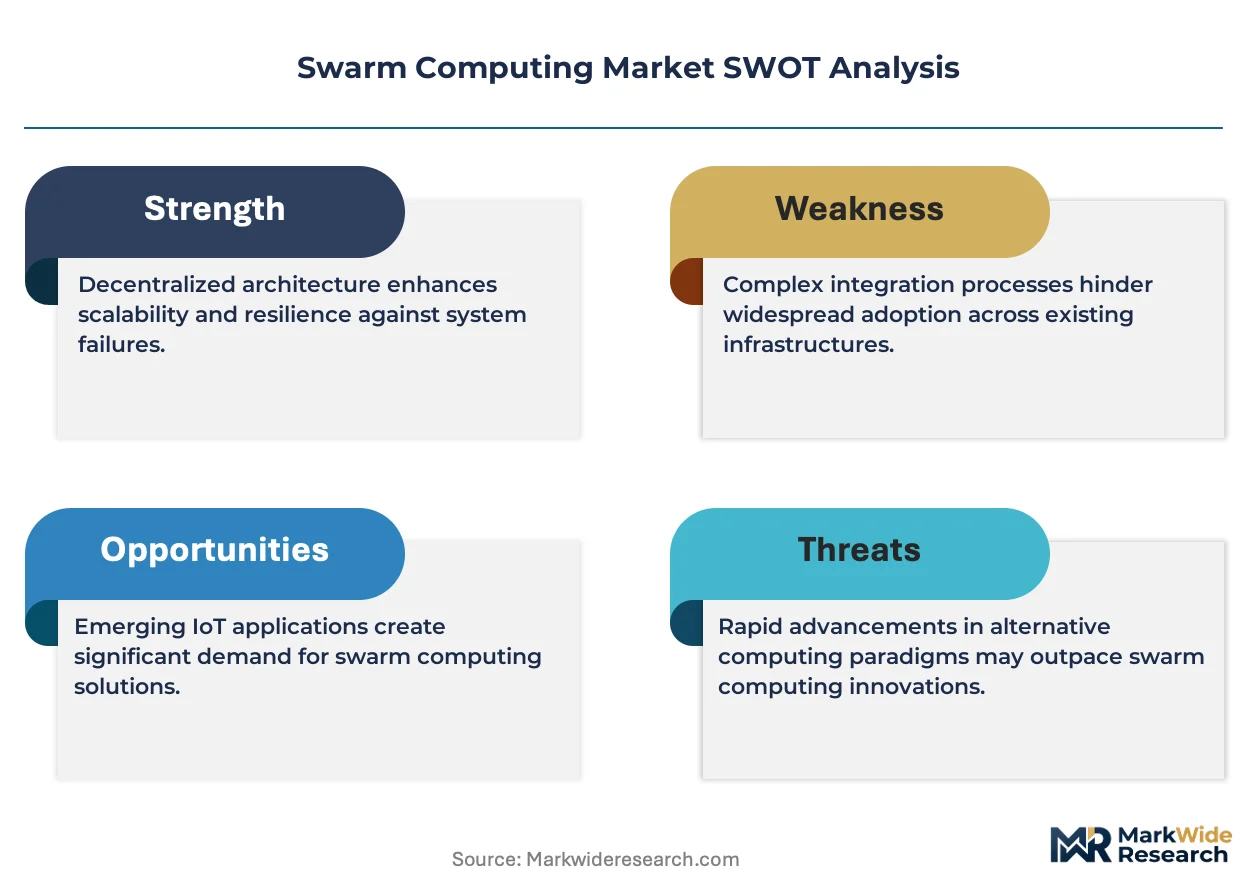
North American cloud infrastructure investment is broadening the addressable base for distributed swarm orchestration. Samsung Electronics leverages its semiconductor fabrication scale to anchor edge-node production for latency-sensitive deployments. Robert Bosch GmbH sustains deep manufacturing automation expertise that competes directly with emerging robotics-native entrants. AGILOX specializes in autonomous mobile robot fleets, occupying a defensible niche in warehouse logistics where task allocation algorithms determine operational throughput.
Swarm computing denotes decentralized architectures where numerous autonomous agents coordinate without centralized control, typically operating via consensus protocols, local sensing, and emergent collective behavior to solve optimization or spatial distribution problems. Systems rely on microsecond-level inter-node communication, fault-tolerant topology management, and stochastic task routing to maintain operational coherence across dynamic environments. Cloud-based deployment leads current infrastructure spending as enterprises prioritize scalable orchestration layers, while edge computing segments capture the fastest expansion due to manufacturing floor requirements for sub-10-millisecond response loops. Healthcare end users represent concentrated margin pools where regulatory validation of diagnostic swarms commands premium pricing structures.
The EU AI Act imposes conformity assessment obligations on autonomous decision-making collectives, compelling vendors to document algorithmic traceability across agent networks. ISO standards for collaborative robot safety intersect with national telecommunications regulations governing spectrum allocation for dense device meshing. Stakeholders must monitor evolving liability frameworks that assign accountability when distributed agent actions produce unintended system-level outcomes.
Market Dynamics
Algorithmic transparency mandates from the EU AI Act are compressing deployment timelines for multi-agent systems across automotive and logistics sectors, forcing vendors to rearchitect consensus protocols for auditability before scale commercialization.
Growth Catalysts
- EU AI Act conformity pathways:The regulation's risk-based classification for autonomous decision-making collectives creates compliance-driven replacement cycles in industrial automation corridors.
- Sub-10-millisecond manufacturing loops:Edge-node density requirements on production floors are pulling fault-tolerant topology management into standard procurement specifications.
- Germany's industrial automation corridor:Concentrated demand from autonomous logistics fleets in automotive manufacturing anchors volume deployment for latency-sensitive orchestration layers.
Market Restraints
- Spectrum allocation bottlenecks:National telecommunications regulations governing dense device meshing create deployment friction in warehouse logistics environments.
- Microsecond-level communication hardware:Specialized inter-node components face supply concentration among semiconductor fabrication facilities with limited second-source options.
- Liability framework fragmentation:Evolving accountability standards for distributed agent actions produce jurisdictional uncertainty that extends legal review cycles.
Strategic Opportunities
- Healthcare diagnostic swarms:Regulatory validation of emergent collective behavior in medical imaging creates premium pricing structures for FDA-compliant agent networks.
- ISO collaborative robot safety convergence:Intersection with swarm coordination protocols opens standardization pathways for human-agent workspace integration.
- Cloud-to-edge orchestration hybrids:Enterprises are bifurcating infrastructure spending between scalable central layers and manufacturing-floor response loops.
Industry Challenges
- Stochastic task routing expertise:Talent scarcity in distributed optimization algorithms limits vendor capacity to configure emergent behavior for specific operational environments.
- Multi-jurisdiction conformity assessments:Documentation of algorithmic traceability across agent networks requires specialized compliance functions with limited talent pools.
- Legacy SCADA integration:Brownfield manufacturing sites require protocol translation layers that introduce latency incompatible with sub-10-millisecond requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swarm Computing Market |
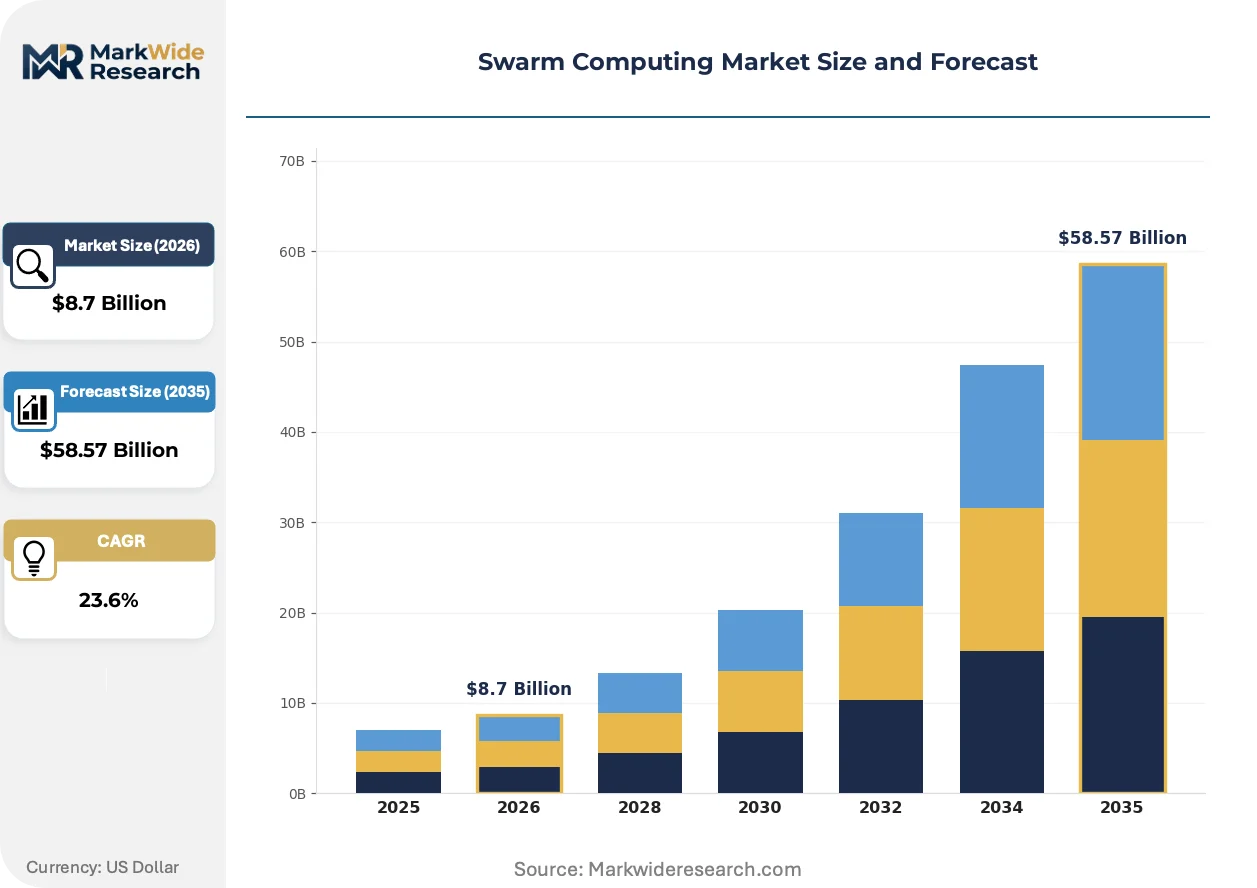
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Healthcare, Automotive, Manufacturing, Retail Technology: Machine Learning, Artificial Intelligence, IoT, Microservices Application: Data Analytics, Real-Time Processing, Task Allocation, Resource Management |
| Companies Covered | NTT Data, Wipro Limited, Samsung Electronics, Unanimous A.I., AGILOX, Robert Bosch GmbH, Sentien Robotics, LLC, Reach Labs, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swarm Computing Market Strategic Shifts
Consensus protocol architectures are fragmenting into specialized implementations as end-use verticals demand sector-specific optimizations rather than general-purpose coordination frameworks.
Distributed ledger-inspired verification mechanisms for agent-state synchronization are modularizing into pluggable middleware components. Automotive manufacturers in Stuttgart and Wolfsburg are embedding these modules directly into fleet management stacks. This modularizing approach compresses vendor lock-in by enabling swap-in replacement of coordination engines without full system rewrites.
The EU AI Act's documentation requirements for high-risk autonomous systems are forcing vendors to maintain immutable audit trails across agent decision trees. Industrial automation suppliers in Bavaria are pre-certifying consensus algorithms to accelerate customer deployment timelines. Healthcare diagnostic applications face the steepest compliance burden, with EMA-aligned validation protocols adding eighteen to twenty-four months to commercialization schedules.
Buyers in warehouse logistics are unbundling hardware procurement from algorithm licensing, forcing vendors to price coordination software separately from edge-node hardware. This unbundling compresses margin capture for integrated system providers while opening entry points for pure-play orchestration specialists. The shift is most visible in German distribution centers, where procurement teams now run competitive tenders for fleet hardware and task-allocation software as distinct categories.
Swarm Computing Market Segmentation
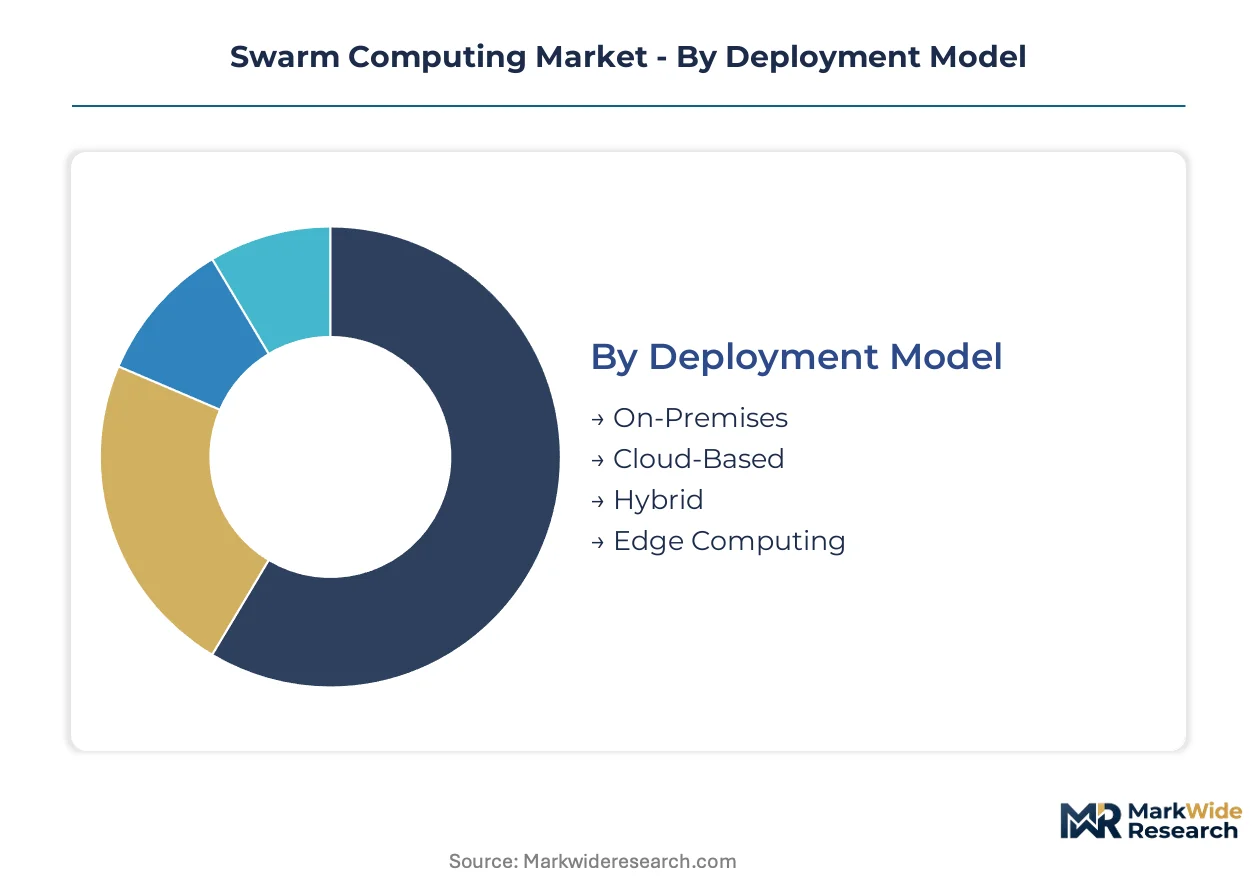
Swarm computing architectures fragment sharply across deployment topologies and latency requirements. End-use verticals impose divergent compliance burdens and throughput specifications that reshape vendor product roadmaps. Understanding these segment boundaries reveals where standardization pressures concentrate versus where customization commands premium positioning.
Deployment Model:
Cloud-based deployments anchor current infrastructure spending with scalable orchestration layers, while edge computing segments capture the steepest expansion trajectory driven by manufacturing floor requirements for sub-10-millisecond response loops.
- Cloud-Based:Centralized orchestration platforms aggregate agent-state synchronization across distributed node populations. German automotive manufacturers in Stuttgart and Wolfsburg deploy these layers for fleet-wide coordination of autonomous logistics vehicles, though latency to factory floors forces hybrid architectures.
- Edge Computing:Microsecond-level inter-node communication operates without round-trip dependency on central infrastructure. Bavarian industrial automation corridors demand this topology for fault-tolerant manufacturing loops where SCADA integration introduces protocol translation friction.
- On-Premises:Air-gapped deployments satisfy defense and critical infrastructure operators with sovereign data requirements.
- Hybrid:Bifurcated workloads split training and model refinement to cloud layers while inference executes at edge nodes.
Today's leader: Cloud-Based. Tomorrow's challenger: Edge Computing.
End User:
Healthcare diagnostic applications command the most concentrated margin pools where regulatory validation of emergent collective behavior creates eighteen-to-twenty-four-month commercialization delays, while automotive manufacturing generates volume deployment through autonomous logistics fleet standardization.
- Healthcare:Diagnostic swarms in medical imaging require FDA and EMA-aligned validation protocols for emergent collective behavior. Premium pricing structures reward vendors who pre-certify consensus algorithms, though documentation burdens for high-risk autonomous systems under the EU AI Act extend legal review cycles significantly.
- Manufacturing:Warehouse logistics in German distribution centers unbundle hardware procurement from algorithm licensing. Procurement teams now tender fleet hardware and task-allocation software separately, compressing margin capture for integrated providers while opening entry for pure-play orchestration specialists.
- Automotive:Autonomous logistics fleets in production facilities drive standardization of latency-sensitive orchestration specifications.
- Retail:Inventory management applications prioritize cost minimization over sub-10-millisecond response requirements.
Healthcare captures margin concentration. Manufacturing drives volume standardization.
Technology:
Machine learning and artificial intelligence layers differentiate through stochastic optimization capabilities, while IoT connectivity faces spectrum allocation bottlenecks under national telecommunications regulations governing dense device meshing.
- Machine Learning:Distributed optimization algorithms enable emergent task routing without centralized control. Talent scarcity in stochastic task routing expertise limits vendor capacity to configure behavior for specific operational environments, particularly in brownfield manufacturing sites.
- IoT:Dense device meshing depends on microsecond-level communication hardware with supply concentration among limited semiconductor fabrication facilities. FCC and national European regulators govern spectrum allocation, creating deployment friction in warehouse logistics environments.
- Artificial Intelligence:High-risk classification under EU AI Act conformity pathways forces algorithmic traceability documentation across agent networks.
- Microservices:Modular consensus protocol implementations enable swap-in replacement of coordination engines without full system rewrites.
Machine learning anchors functional differentiation. Microservices enable vendor flexibility.
Application:
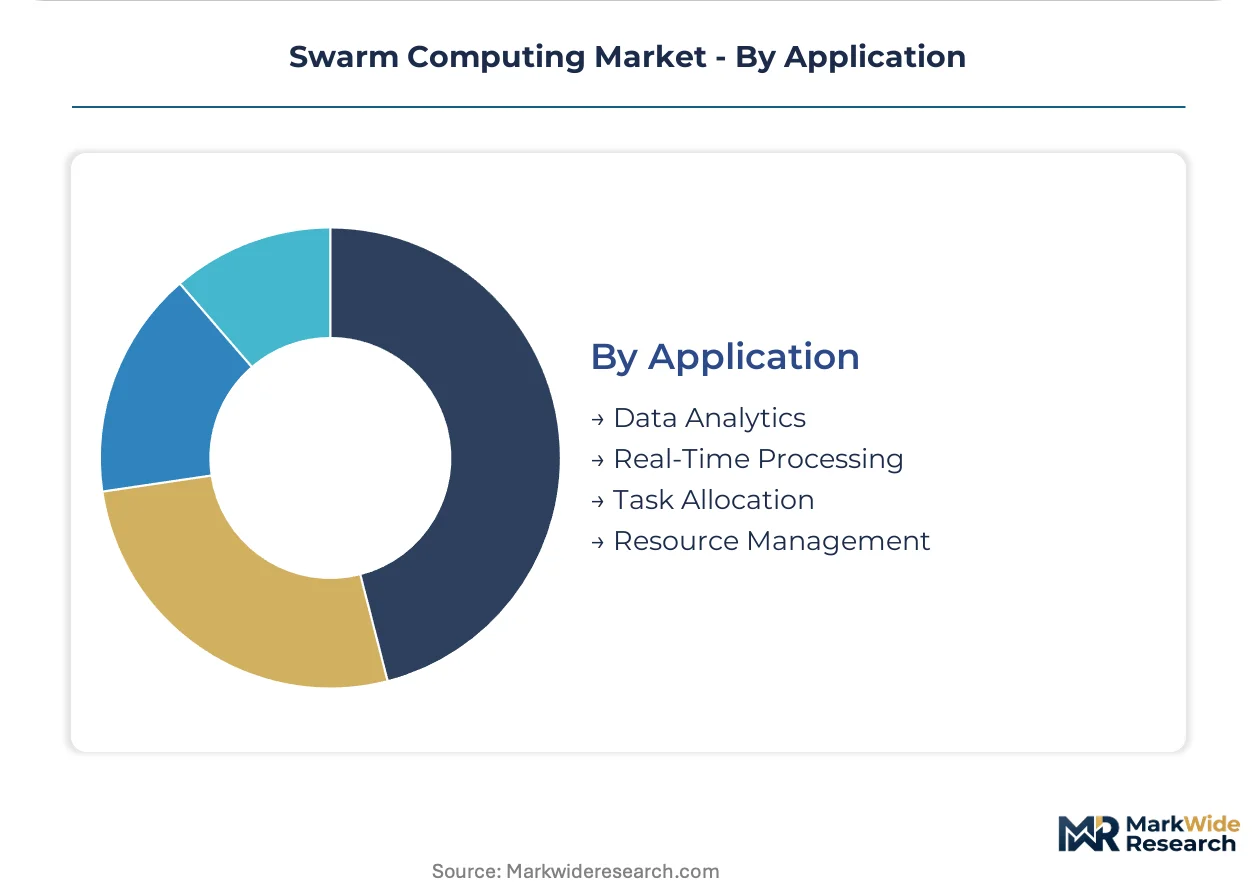
Task allocation algorithms determine operational throughput in warehouse logistics where AGILOX and comparable fleet operators compete on coordination efficiency, while real-time processing applications face the steepest hardware requirements for sub-10-millisecond loops.
- Task Allocation:Optimization of spatial distribution problems across autonomous mobile robot fleets. German distribution centers benchmark vendors on throughput per square meter, with procurement teams evaluating consensus protocol efficiency separately from edge-node hardware specifications.
- Real-Time Processing:Sub-10-millisecond response loops for manufacturing floor control. Fault-tolerant topology management and microsecond-level inter-node communication create procurement specifications that exclude legacy SCADA integration due to protocol translation latency.
- Data Analytics:Post-hoc aggregation of swarm behavior patterns for operational refinement and predictive maintenance.
- Resource Management:Dynamic load balancing across heterogeneous agent populations with varying computational capacity.
Task allocation commands procurement attention. Real-time processing imposes the tightest technical constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates industrial automation demand while the United States drives cloud orchestration investment, creating divergent procurement patterns across Atlantic markets.
Germany
Stuttgart and Wolfsburg anchor autonomous logistics fleet deployment for automotive manufacturing. The EU AI Act imposes conformity assessment obligations on multi-agent systems operating in high-risk industrial environments. Bavaria's industrial automation corridor generates concentrated demand for sub-10-millisecond edge computing topologies in brownfield manufacturing sites.
United States
Cloud infrastructure investment from hyperscale operators broadens the addressable base for distributed swarm orchestration platforms. FCC spectrum allocation regulations govern dense device meshing in warehouse logistics environments. The Pacific Northwest hosts semiconductor fabrication facilities supplying microsecond-level communication hardware with limited second-source alternatives.
China
MIIT standards for industrial internet platforms accelerate domestic adoption of consensus protocol architectures in smart manufacturing zones. GB standards for collaborative robot safety intersect with national telecommunications regulations on spectrum allocation. The Yangtze River Delta concentrates edge-node production capacity for latency-sensitive deployments.
Japan
METI industrial digitization programs channel procurement toward fault-tolerant topology management in precision manufacturing. JIS standards for collaborative workspace safety create compliance pathways for human-agent integration. The Kansai region around Osaka hosts specialized vendors in stochastic task routing algorithms.
South Korea
MFDS regulatory frameworks for medical device software shape validation protocols for healthcare diagnostic swarms. The Seoul Capital Area concentrates demand for real-time processing applications in semiconductor fabrication facilities. National AI investment programs underwrite edge computing infrastructure for manufacturing floor control systems.
Swarm Computing Market Competitive Environment
German producers anchor the industrial automation tier; South Korean and Japanese specialists hold semiconductor and precision manufacturing positions. The vendor base separates into integrated system providers, pure-play orchestration software vendors, and edge-node hardware fabricators. Three archetypes dominate: robotics-native entrants with fleet management expertise, industrial conglomerates with manufacturing automation legacy, and cloud-native platforms with scalable orchestration layers. Competitive moves concentrate on unbundling hardware from software procurement and pre-certifying consensus algorithms to compress deployment timelines.
Within the industrial conglomerate tier, Robert Bosch GmbH and Continental AG exemplify deep manufacturing automation expertise competing directly with emerging entrants. Samsung Electronics anchors semiconductor fabrication scale for edge-node production. AGILOX occupies a defensible position in warehouse logistics where task allocation algorithms determine operational throughput. Unanimous A.I. and Reach Labs represent the pure-play orchestration software vector, while NTT Data and Wipro Limited sit within IT services integrators bridging cloud-to-edge deployments.
| Leading Market Players |
|---|
| NTT Data |
| Wipro Limited |
| Samsung Electronics |
| Unanimous A.I. |
| AGILOX |
| Robert Bosch GmbH |
| Sentien Robotics, LLC |
| Reach Labs |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EU AI Act-compliant orchestration layers and uncertified commodity alternatives shapes both procurement premiums and supplier qualification hurdles. Vendors bearing pre-validated consensus algorithms command substantial markups in German automotive corridors, while buyers absorbing compliance documentation costs internally source from lower-tier hardware fabricators in Asian manufacturing zones.
Pricing Analysis
Direct-to-OEM discount structures dominate procurement for autonomous logistics fleets in Stuttgart and Wolfsburg, compressing distributor margins to single-digit percentages. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated healthcare diagnostic swarms from manufacturing-floor task allocation engines and retail inventory modules. Price differentiation hinges on algorithmic traceability documentation depth and microsecond-level communication hardware specifications. Cost compression in edge-node components intensifies as Samsung Electronics and comparable semiconductor fabricators expand captive production capacity. Healthcare end users exhibit lowest price sensitivity due to eighteen-to-twenty-four-month regulatory validation timelines that lock in vendor relationships.
Supply Chain Analysis
Workforce availability constraints in Taiwanese semiconductor foundries and South Korean memory fabrication facilities are tightening component lead times for microsecond-level communication hardware. Supply concentration centers on Germany for industrial automation integration expertise, South Korea for edge-node semiconductor production, and China for dense device meshing hardware assembly. Raw material dependencies include advanced lithography equipment, gallium nitride substrates for high-frequency switching, and rare earth elements for precision sensor arrays. Single-source vulnerability in extreme ultraviolet lithography systems creates systemic exposure for advanced node production. Distribution runs through specialized industrial automation integrators in Bavaria and direct procurement teams at major automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate where vendors automate compliance documentation workflows and shift healthcare buyers toward subscription-based orchestration licensing. Cost-down pressure from unbundled hardware-software procurement is compressing integrated system providers while rewarding pure-play algorithm specialists.
For Market Incumbents: Deploy pre-certification investments to accelerate EU AI Act conformity pathways for customers in high-risk industrial classifications. Robert Bosch GmbH and comparable industrial conglomerates should anchor backward integration into edge-node semiconductor sourcing to offset supply concentration in Taiwanese fabrication facilities. Consolidation of stochastic task routing talent pools through targeted hiring in the Kansai region around Osaka defends against robotics-native entrants poaching algorithm development capacity. For New Entrants and Emerging Players: Cloud-native orchestration platforms represent the most penetrable vector for warehouse logistics buyers unbundling hardware from software procurement. Target German distribution centers running competitive tenders for task-allocation algorithms separate from AGILOX fleet hardware specifications. SaaS-based consensus protocol licensing with per-robot monthly fees bypasses capital expenditure approval cycles that delay integrated system sales. For Investors and Strategic Acquirers: Consolidation pressure builds where pure-play orchestration specialists accumulate FDA and EMA validation protocols that would require eighteen-to-twenty-four-month replication timelines. Long-term viability favors vendors with demonstrated algorithmic traceability documentation across agent networks under EU AI Act high-risk classifications. Acquisition target archetypes include stochastic task routing boutiques in Osaka and healthcare diagnostic swarm validators with completed FDA submission pathways. Signal to watch: procurement team unbundling velocity in German automotive corridors as indicator of software-only vendor addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification of Consensus Algorithms | Compresses EU AI Act deployment timelines for Bavarian industrial automation customers. |
| Cloud-to-Edge Orchestration Hybrid Development | Captures bifurcated infrastructure spending patterns across German manufacturing floors. |
| Healthcare Diagnostic Swarm Validation | Unlocks premium pricing structures through FDA and EMA-aligned emergent behavior documentation. |
| Stochastic Task Routing Talent Acquisition | Addresses capability scarcity limiting vendor configuration capacity for brownfield manufacturing sites. |
| Unbundled Software Licensing Model | Aligns with procurement team practices in German distribution centers separating hardware from algorithm tenders. |
Study Parameters
Multiple input streams — primary interviews with fleet operations managers and industrial automation procurement leads, secondary validation through EU regulatory filing databases and semiconductor trade flow records, and technical specification analysis of consensus protocol implementations — were reconciled through bottom-up and top-down triangulation. Stakeholder engagement spanned CTOs at autonomous logistics providers, plant engineers in Stuttgart automotive facilities, biomedical imaging specialists evaluating diagnostic swarms, and channel partners distributing edge-node hardware. Secondary sources included FCC spectrum allocation dockets, EMA medical device guidance documents, MIIT industrial internet platform standards, and customs records tracking microsecond-level communication component trade.
Historical deployment trajectories across cloud-based and edge computing topologies were cross-referenced against panel input from vendor sales operations and end-user procurement committees. Segmentation dimensions modeled encompass deployment model, end-use vertical, technology layer, and application type, with additional granularity on latency requirement tiers and regulatory risk classifications. CAGRs were derived from installed base growth rates, replacement cycle compression under EU AI Act conformity pathways, and average selling price evolution across unbundled software licensing transitions. Forecast inputs incorporated semiconductor fabrication capacity expansion timelines and spectrum allocation regulatory proceedings in key national jurisdictions.
The model assumes a particular technology adoption path; alternative pathways for fault-tolerant topology management in brownfield SCADA integration scenarios would alter the outlook for edge computing segment expansion. Forecasts reflect documented assumptions regarding EU AI Act enforcement consistency and semiconductor supply chain normalization. Material deviation in FCC or national European spectrum allocation decisions, or in extreme ultraviolet lithography equipment availability, warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
North America Next Generation Computing Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market