
 Breast Lesion Localization Device Market | 2026-2036
Breast Lesion Localization Device Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Lesion Localization Device Market Outlook
Non-radioactive magnetic materials are expanding their share of the localization device mix as hospitals phase out radioactive seed programs to eliminate nuclear medicine handling costs and disposal complexity. Hologic Inc. leverages its integrated mammography-to-surgery workflow platform to anchor its position across imaging and intervention suites. Becton, Dickinson and Company sustains broad hospital access through its multi-modality distribution network spanning wire and seed portfolios. Merit Medical Systems competes on interventional radiology channel control, where its catheter-based delivery systems occupy a differentiated niche in outpatient biopsy settings.
Breast lesion localization devices are instruments and materials placed in or near suspicious breast tissue to guide surgical excision or biopsy, typically incorporating radiopaque wires, radioactive or magnetic seeds, radar reflectors, or electromagnetic transponders with localization accuracy measured in millimeters. Their primary commercial purpose is to reduce re-excision rates and preserve healthy tissue during breast-conserving surgery. Magnetic seed localization is capturing margin pools as the fastest-growing product type, driven by elimination of scheduling constraints tied to nuclear medicine availability. Ultrasound-guided deployment dominates technology utilization due to real-time visualization and absence of ionizing radiation, though MRI-guided localization is extending into dense-tissue patient subsets where mammographic targeting fails.
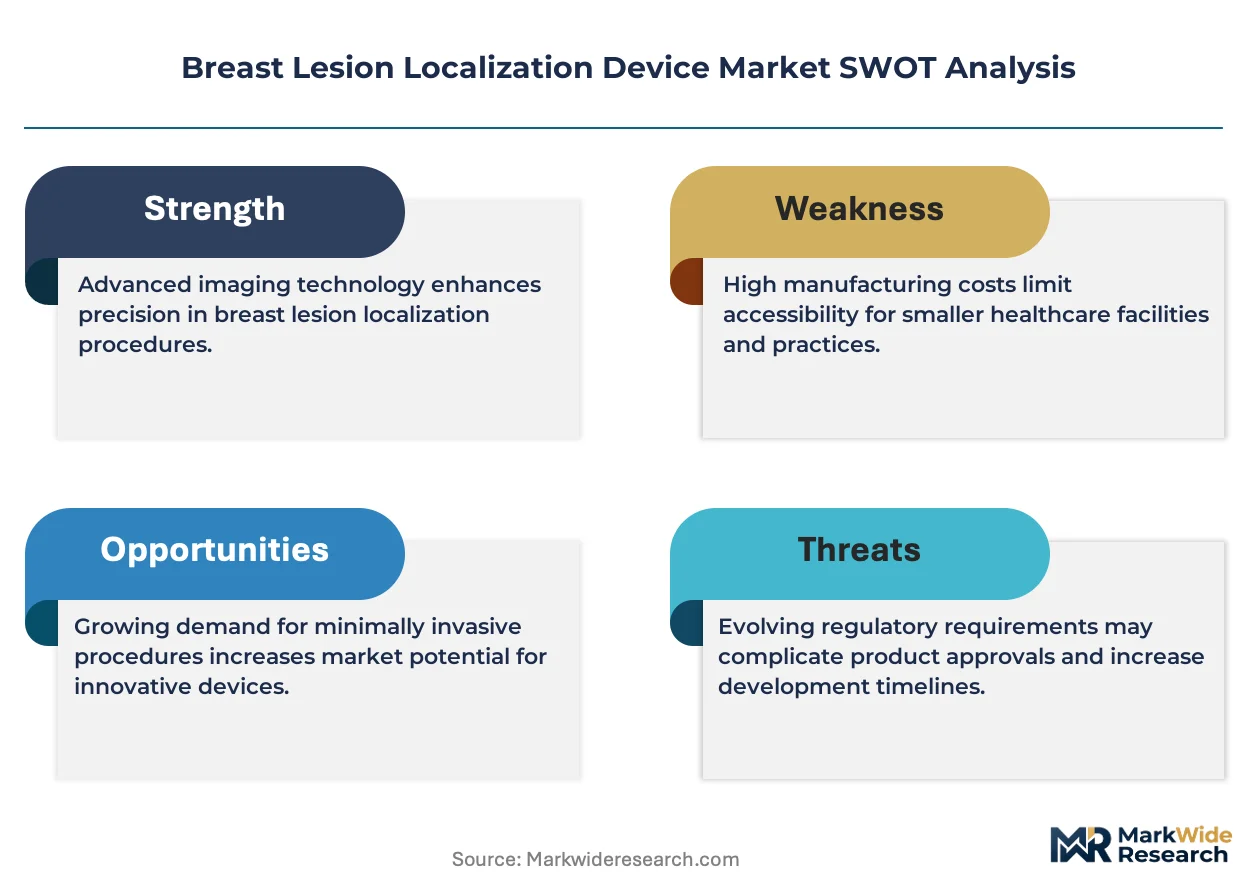
FDA 510(k) clearance pathways shape product development timelines and predicate-device selection for manufacturers entering the United States market, while the EU MDR technical documentation and clinical evaluation requirements are forcing portfolio rationalization among smaller device firms. The EPA maintains oversight of radioactive seed disposal protocols, creating compliance friction that accelerates magnetic alternative adoption. Stakeholders must monitor reimbursement coding decisions for magnetic seed placement in outpatient settings, as these will determine whether hospital cost savings translate into sustained manufacturer pricing power.
Market Dynamics
Magnetic seed localization is absorbing procedural volume from radioactive wire systems as hospitals eliminate nuclear medicine dependencies and same-day scheduling constraints. This technology shift reconfigures capital allocation across imaging suites and surgical departments.
Growth Catalysts
- EU MDR standardization:Updated technical documentation requirements in Europe are accelerating product homogenization and clearing pathways for magnetic seed market entry.
- Outpatient biopsy expansion:Interventional radiology suites in the United States are scaling same-day localization-to-excision workflows that magnetic seeds uniquely enable.
- Japan screening scale-up:Population-wide breast cancer screening program expansion is concentrating device demand in metropolitan hospital networks.
Market Restraints
- Rare earth magnet supply:Neodymium price volatility and China-dominant processing capacity create input cost exposure for magnetic seed manufacturers.
- FDA 510(k) predicate limitations:Narrow predicate device availability for novel magnetic configurations extends clearance timelines and elevates regulatory risk.
- Radioactive seed legacy infrastructure:Existing nuclear medicine handling protocols and disposal contracts in mature hospitals delay magnetic conversion decisions.
Strategic Opportunities
- Dense-tissue MRI localization:Mammographic targeting failures in dense breast tissue populations are opening MRI-guided deployment applications.
- Germany ambulatory surgery center channel:Outpatient reimbursement parity for magnetic seed placement is enabling channel expansion beyond traditional hospital suites.
- Ultrasound-MRI convergence:Hybrid imaging workstations combining real-time ultrasound visualization with MRI planning software are compressing procedural steps.
Industry Challenges
- Interventional radiology training gaps:Magnetic seed deployment requires distinct needle-handling techniques that existing wire-trained radiologists must acquire through simulation-based programs.
- EMR integration complexity:Surgical scheduling systems and imaging archives demand API-level connectivity with localization device tracking software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Lesion Localization Device Market |
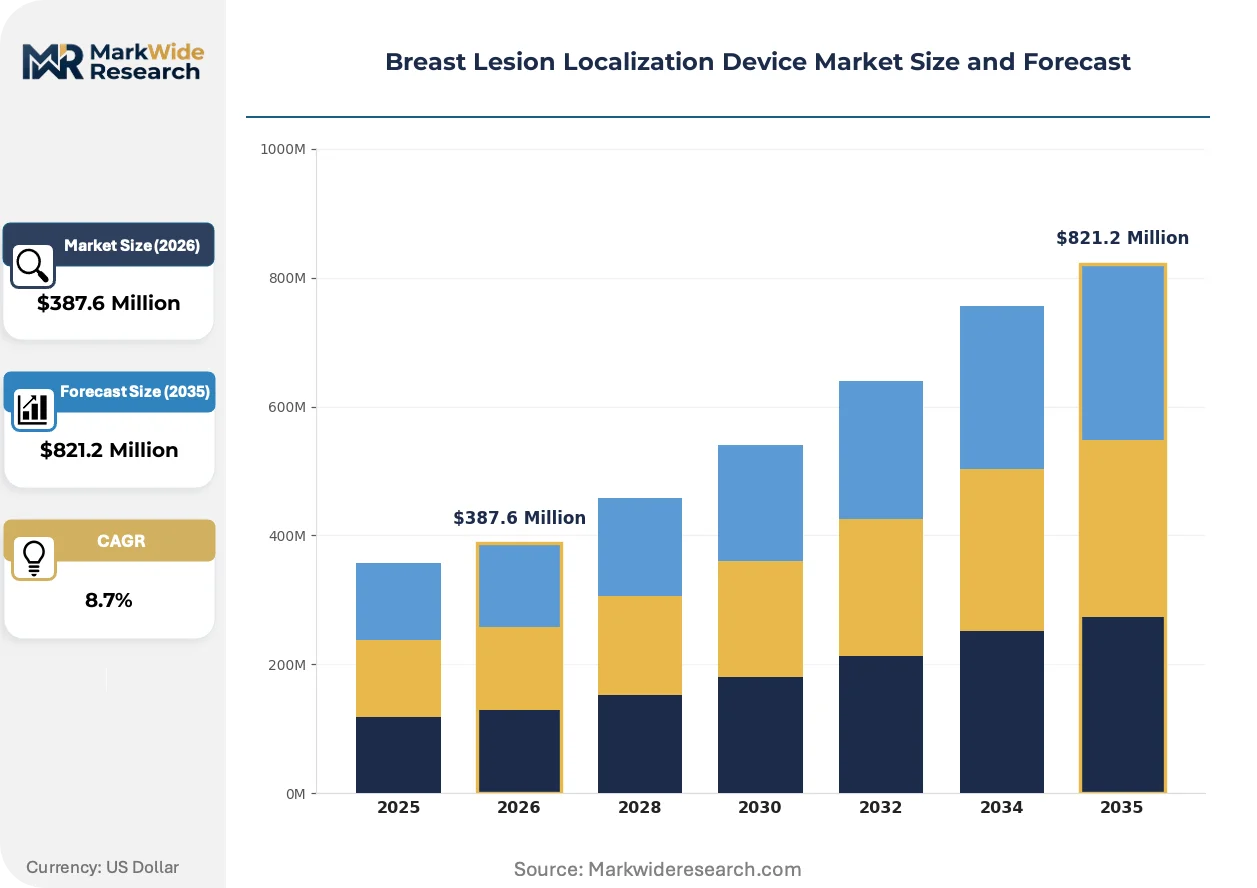
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Localization, Radioactive Seed Localization, Magnetic Seed Localization, Other Technology: Ultrasound, MRI, X-ray, CT End User: Hospitals, Outpatient Clinics, Diagnostic Imaging Centers, Cancer Treatment Centers Application: Breast Cancer Surgery, Biopsy Guidance, Treatment Localization, Others |
| Companies Covered | Hologic Inc., Becton, Dickinson and Company, Merit Medical Systems, Cook Medical, Argon Medical Devices, GE Healthcare, Koninklijke Philips N.V., Cianna Medical, Leica Biosystems Nussloch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Lesion Localization Device Market Strategic Shifts
Device miniaturization and non-radioactive material science are converging to redefine procedural workflows. Three distinct developments are compressing the gap between detection and excision.
Magnetic seed technology is absorbing volume from traditional wire localization as hospital systems prioritize scheduling flexibility. Academic medical centers in the United States are converting breast surgery suites first, driven by same-day availability and elimination of nuclear medicine coordination. This absorption is compressing the addressable market for radioactive alternatives and redirecting R&D budgets toward magnetic material refinement.
EU MDR clinical evaluation requirements are forcing portfolio rationalization among smaller device manufacturers. The updated technical documentation burden elevates compliance costs and favors firms with established quality management systems. European notified bodies are concentrating review resources on magnetic seed submissions, accelerating standardization while delaying market entry for novel wire configurations.
Hospital procurement departments are consolidating supplier relationships around integrated imaging-to-surgery platforms. Single-vendor contracts spanning mammography, biopsy, and localization are displacing point-product purchasing in integrated delivery networks. This concentration is most visible in United States health systems pursuing operational standardization across regional hospital clusters.
Breast Lesion Localization Device Market Segmentation
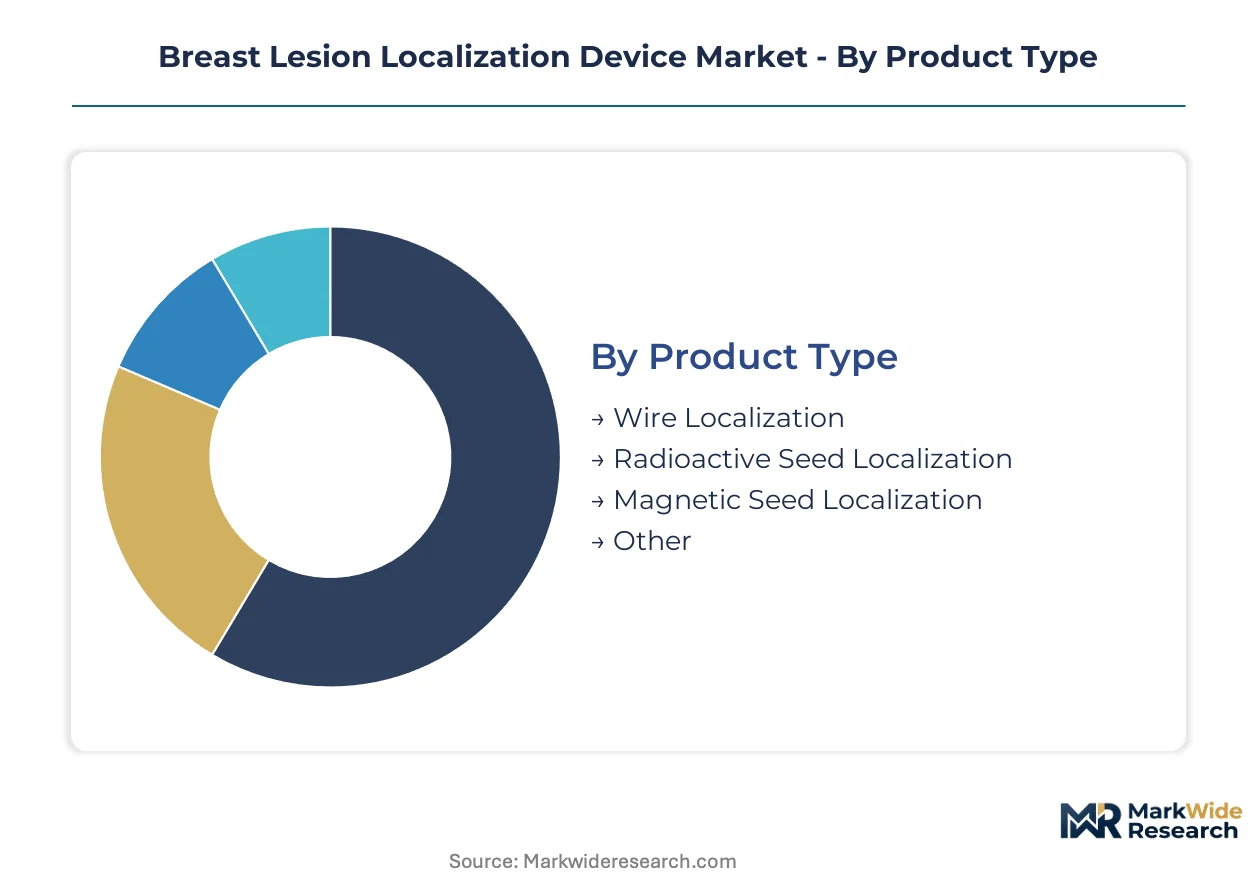
Segmentation in breast lesion localization devices reveals how procedural workflows, imaging infrastructure, and reimbursement pathways fragment demand across distinct buyer profiles. Understanding these divisions exposes where capital concentrates and where technology transitions accelerate.
Product Type:
Procurement priorities diverge sharply between institutions maintaining legacy nuclear medicine infrastructure and those pursuing scheduling flexibility.
- Magnetic Seed Localization:Biocompatible iron oxide or metallic alloy seeds detectable via handheld magnetic sensors eliminate same-day surgery coordination with nuclear medicine departments. United States academic medical centers are converting suites fastest, driven by outpatient reimbursement codes that reward streamlined workflows.
- Radioactive Seed Localization:Iodine-125 or palladium-103 implants require nuclear medicine handling protocols and specialized disposal contracts. Germany retains installed base concentration where existing regulatory compliance investments delay magnetic conversion timelines.
- Wire Localization:Radiopaque hookwire systems anchored to external stabilization plates remain prevalent in cost-constrained settings with limited interventional radiology staffing.
- Other:Radar reflector and electromagnetic transponder alternatives occupy niche applications in hybrid imaging protocols.
Volume sits with wire localization; growth tilts toward magnetic seed systems.
Technology:
Imaging modality selection tracks tissue density profiles and real-time visualization requirements across patient populations.
- Ultrasound:Real-time needle guidance without ionizing radiation dominates biopsy workflows in outpatient clinics. Japan's dense breast screening cohorts are expanding ultrasound-guided deployment where mammographic sensitivity degrades.
- MRI:Magnetic resonance localization addresses targeting failures in extremely dense tissue and preoperative staging of multifocal disease. United States tertiary centers are integrating MRI-to-surgery navigation platforms for complex cases.
- X-ray:Stereotactic mammography guidance retains volume in screening-detected calcification targeting across European hospital networks.
- CT:Computed tomography localization supports thoracic wall lesions and post-mastectomy reconstruction planning in specialized cancer treatment centers.
Ultrasound commands procedure volume; MRI applications are climbing the fastest.
End User:
Facility type determines capital allocation between integrated surgical suites and distributed diagnostic networks.
- Hospitals:Comprehensive breast surgery programs with embedded interventional radiology departments absorb magnetic seed systems through centralized procurement. Germany's university hospital networks are standardizing across regional clusters.
- Outpatient Clinics:Same-day biopsy-to-localization workflows favor portable magnetic detection hardware and disposable seed configurations. United States ambulatory surgery centers are expanding fastest under site-of-service differential reimbursement.
- Diagnostic Imaging Centers:Mammography-focused facilities concentrate wire and seed deployment for referral to external surgical providers.
- Cancer Treatment Centers:Multidisciplinary oncology programs integrate localization into neoadjuvant therapy monitoring protocols.
Hospitals retain installed base dominance; outpatient clinics are gaining share fastest.
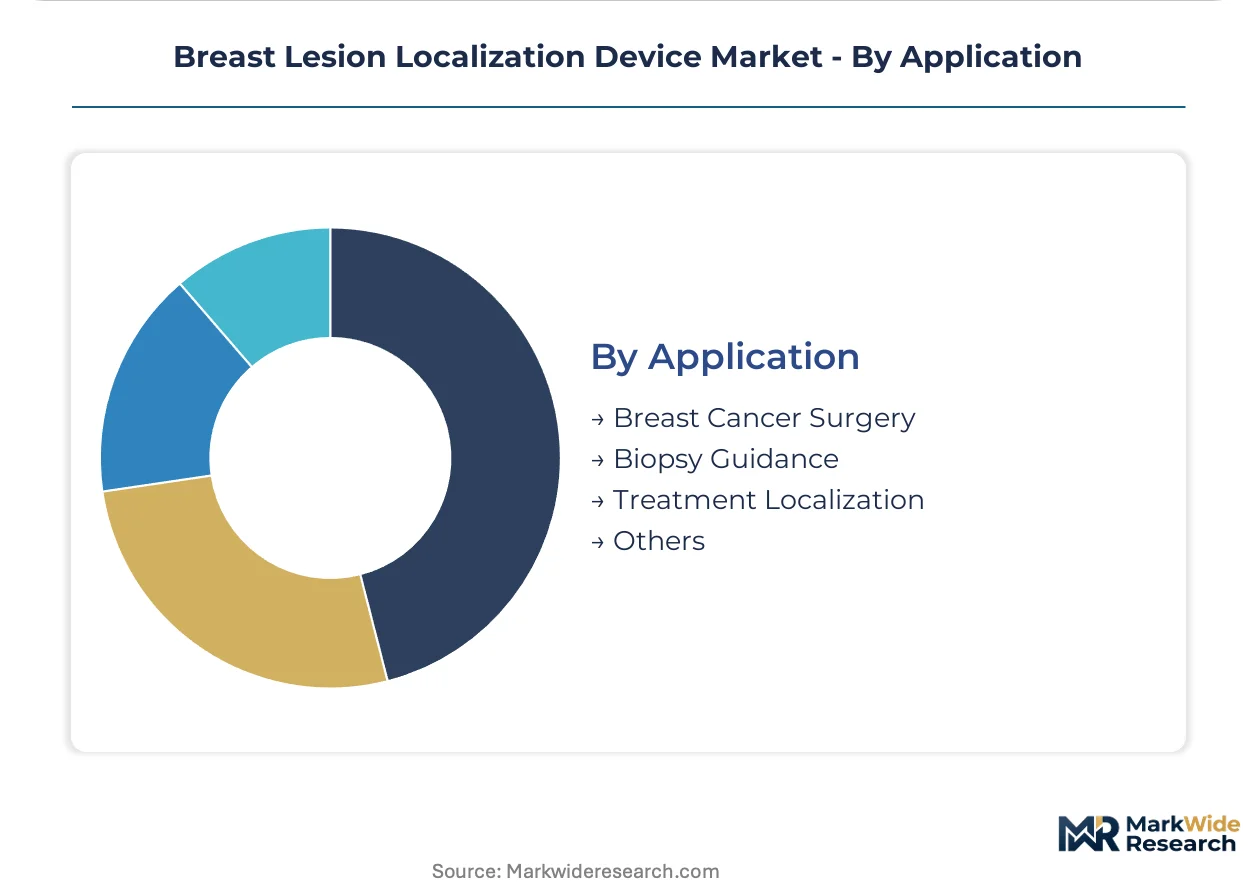
Application:
Clinical intent shapes device specification between definitive excision and diagnostic sampling pathways.
- Breast Cancer Surgery:Tumor bed localization for breast-conserving procedures demands millimeter accuracy and margin assessment integration. Japan's screening program expansion is concentrating surgical volume in metropolitan hospital networks.
- Biopsy Guidance:Tissue sampling for histopathological confirmation favors rapid deployment and minimal patient discomfort. United States interventional radiology suites are scaling same-day magnetic seed placement for subsequent surgical referral.
- Treatment Localization:Radiation therapy fiducial placement and cryoablation targeting require specialized seed compositions compatible with adjuvant modalities.
- Others:Research protocols and novel therapeutic delivery applications occupy experimental niches in academic settings.
Surgical applications anchor revenue concentration; biopsy guidance is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device procurement concentrates in hospital networks running population-wide breast cancer screening programs. Magnetic seed systems are displacing radioactive alternatives fastest where same-day surgery scheduling commands premium value.
United States
Academic medical centers in Boston, New York, and Los Angeles are converting breast surgery suites to magnetic seed workflows under outpatient reimbursement codes that reward streamlined scheduling. FDA 510(k) clearance pathways for predicate magnetic devices are accelerating product standardization. The Mayo Clinic and MD Anderson networks are anchoring magnetic seed adoption across regional hospital clusters.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia retain radioactive seed installed bases where existing nuclear medicine compliance investments delay conversion timelines. EU MDR technical documentation requirements are forcing portfolio rationalization among domestic device distributors. The Charité Berlin and Heidelberg University Hospital systems are piloting MRI-guided localization for dense-tissue patient subsets.
Japan
Metropolitan hospital networks in Tokyo, Osaka, and Nagoya are scaling magnetic seed deployment alongside population-wide screening program expansion. PMDA regulatory harmonization with FDA predicate pathways is compressing product registration timelines. The National Cancer Center Japan is coordinating magnetic seed standardization across designated cancer care hospitals.
United Kingdom
NHS England procurement frameworks are consolidating supplier relationships around integrated imaging-to-surgery platforms in London, Manchester, and Birmingham hospital trusts. NICE technology appraisal pathways are evaluating magnetic seed cost-effectiveness against wire localization baselines. The Royal Marsden and Guy's Hospital are anchoring magnetic adoption in southeast England cancer networks.
France
Public hospital networks in Paris, Lyon, and Marseille are maintaining wire localization prevalence where interventional radiology staffing constraints limit magnetic seed deployment. ANSM regulatory oversight of medical device vigilance is elevating quality management system requirements for magnetic seed manufacturers. The Institut Curie and Gustave Roussy are specializing in MRI-guided localization for complex multifocal cases.
Breast Lesion Localization Device Market Competitive Environment
Portfolio diversification dominates the current landscape as device manufacturers extend from mammography into intervention workflows. The vendor base concentrates around imaging-system incumbents and interventional radiology specialists, with tiered competitive positions separating integrated platform providers from point-product suppliers. Three archetypes define positioning: full-stack imaging-to-surgery vendors, interventional catheter specialists, and diagnostic imaging pure-plays. M&A activity and strategic distribution partnerships represent the dominant competitive moves reshaping channel access.
Among imaging-integrated vendors, Hologic Inc. and GE Healthcare occupy positions exemplifying the full-stack archetype, anchoring competitive dynamics around workflow platform control. Merit Medical Systems and Cook Medical represent the interventional specialist tier, with catheter-based delivery expertise distinguishing their channel positioning. These named entities illustrate how competitive advantage fragments across imaging ownership, interventional radiology relationships, and regulatory clearance breadth rather than concentrating in any single capability domain.
| Leading Market Players |
|---|
| Hologic Inc. |
| Becton, Dickinson and Company |
| Merit Medical Systems |
| Cook Medical |
| Argon Medical Devices |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Cianna Medical |
| Leica Biosystems Nussloch GmbH |
| Others |
Value Chain & Pricing Dynamics
Neodymium oxide price volatility on the Shanghai Metals Market cascades through magnetic seed manufacturing into three-tier pricing structure across premium, standard, and economy levels, with FDA-cleared devices commanding material premiums over CE-marked equivalents and wire localization systems anchoring the economy tier through commodity stainless steel inputs.
Pricing Analysis
Volume sits with wire localization at economy price points; margins concentrate in magnetic seed systems at premium tiers. Price differentiation hinges on FDA 510(k) clearance status and integrated software companion offerings. Pricing pressure stems from hospital procurement consolidation around single-vendor imaging platforms. Outpatient clinics exhibit highest price sensitivity; academic medical centers prioritize workflow integration over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing capacity for neodymium-iron-boron magnetic alloys. Raw material sourcing draws from China, Malaysia, and Australia for rare earth oxides, with biocompatible polymer coatings anchored in Germany and the United States. Tariff exposure on processed magnetic materials presents structural risk. Distribution runs through interventional radiology device distributors and hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR technical documentation requirements erect barrier-to-entry moats favoring incumbents with established quality management systems.
For Market Incumbents: Acquire interventional radiology training simulation assets to accelerate magnetic seed deployment competency among wire-trained clinicians. Consolidate GPO contract positions before reimbursement coding finalization for outpatient magnetic seed placement. Threat substitution from radar reflector alternatives demands preemptive R&D in hybrid localization technologies. Channel control through embedded software companions represents the critical defensive lever. For New Entrants and Emerging Players: MRI-guided localization for dense-tissue patient subsets offers technology-first wedge positioning against mammography-incumbent portfolios. Target Germany ambulatory surgery centers where outpatient reimbursement parity enables channel expansion without hospital infrastructure investment. White-space concentration in MRI-to-surgery navigation software companions supports partnership-based go-to-market with imaging workstation vendors. For Investors and Strategic Acquirers: Distressed-cycle entries favor EU MDR-compliant device manufacturers with cleared magnetic seed portfolios in Germany. Long-term viability hinges on reimbursement coding capture in United States outpatient settings. Acquisition target archetype: interventional radiology specialists with catheter-based delivery expertise and notified body relationships. Signal to watch: CMS provisional codes for magnetic seed placement in ambulatory surgical centers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device selection accelerates magnetic seed clearance timelines in United States academic centers. |
| CE Marking Pathway | EU MDR technical documentation investment clears competitive field for notified body-resourced manufacturers. |
| Hospital System Partnership | Integrated imaging-to-surgery contracts with Hologic or GE platforms lock out point-product competitors. |
| Software Companion Development | EMR integration APIs with Epic or Cerner systems reduce surgical scheduling friction for magnetic workflows. |
| Reimbursement Strategy | CPT code advocacy for outpatient magnetic seed placement determines pricing power sustainability. |
Study Parameters
FDA 510(k) premarket notification database, EU MDR notified body submission records, and CMS Medicare reimbursement coding archives formed the secondary backbone for this analysis. Primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers validated procedural volume assumptions and technology adoption timelines. Bottom-up facility-level demand modeling triangulated against top-down manufacturer revenue segmentation.
Historical trendline analysis of radioactive seed displacement rates informed projection framework construction across product type, technology modality, end-user facility, and application intent segmentation dimensions. CAGRs were derived from fitted growth curves applied to procedural volume trajectories. Forecast inputs incorporated PMDA regulatory harmonization timelines and dense-breast screening penetration rates.
Several conditions sit outside the modeled scope, including novel therapeutic delivery applications and research protocol volumes. Forecasts reflect assumptions around reimbursement coding finalization and rare earth supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Education Microscope Market
Medical Devices
Global Veress Needle Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Ovulation Microscope Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Direct Energy Medical Devices Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Cyclotron Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Global Spinal Motion Preservation Device Market