
 Vascular Imaging Systems Market | 2026-2036
Vascular Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Imaging Systems Market Analytics
Outpatient facilities are rotating toward minimally invasive vascular diagnostics, displacing traditional hospital-based catheterization labs for routine peripheral artery disease screening. Siemens Healthineers leverages its dual-source CT portfolio to dominate cardiac imaging workflows in European day-surgery centers. GE Healthcare anchors its position through AI-enabled image reconstruction that reduces contrast dye volumes. Koninklijke Philips N.V. competes on integrated hybrid operating room designs combining angiography with surgical navigation.
Vascular imaging systems comprise modalities that visualize blood vessel anatomy, hemodynamics, and pathology using ionizing radiation, magnetic fields, or acoustic waves, with spatial resolution thresholds typically below 0.5 millimeters for coronary stent assessment. These systems enable interventional planning, post-surgical surveillance, and real-time guidance during endovascular procedures across cardiology and neurology departments. Ultrasound segments occupy the largest installed base due to portability and absence of radiation exposure, yet 3D imaging technology captures the fastest expansion as interventionalists demand rotational datasets for complex aortic repairs. CT scan applications in peripheral vascular disease generate concentrated margin pools where bundled payment models reward rapid throughput.
The FDA enforces radiation safety standards under 21 CFR 1020.32, compelling vendors to embed dose tracking and automatic exposure control in angiography systems sold to US providers. EMA's Medical Device Regulation requires clinical evidence portfolios for contrast injector accessories, lengthening approval timelines but raising barriers against low-cost imports. Stakeholders must monitor how CMS reimbursement shifts toward site-neutral payments reshape capital allocation between hospital systems and independent diagnostic centers.
Market Dynamics
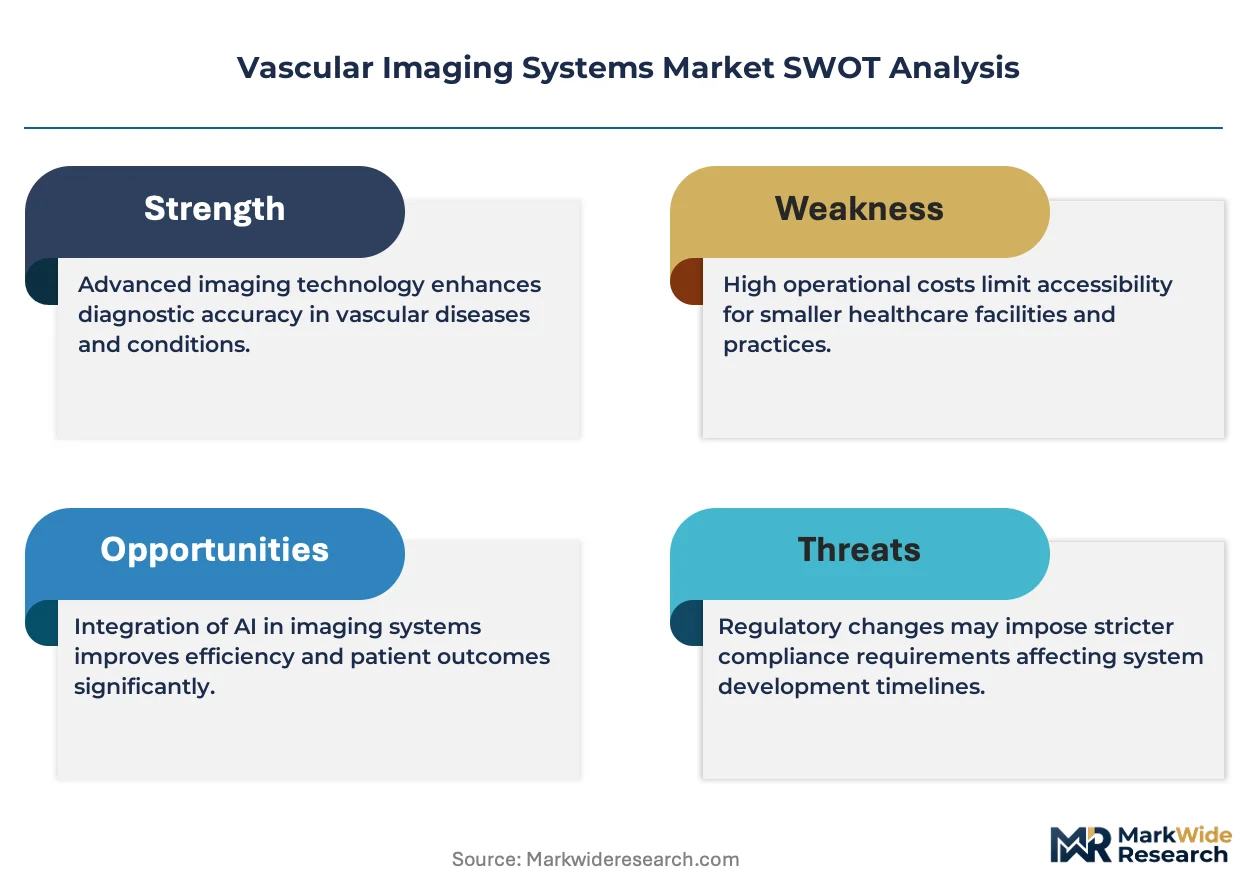
Hospital procurement committees are consolidating vendor relationships around single-source CT-angiography contracts, compressing the competitive field from multi-modal purchasing toward integrated platform commitments. This concentration dynamic favors manufacturers with full-stack imaging portfolios over specialized device suppliers.
Growth Catalysts
- Low-dose protocol mandates:FDA's 21 CFR 1020.32 updates force dose tracking integration, accelerating replacement cycles for aging angiography suites in US cardiac centers.
- Peripheral artery disease screening:Bundled payment models for Medicare beneficiaries reward rapid vascular assessment throughput, pulling CT-based diagnostics into outpatient settings.
- 3D rotational angiography:German university hospital consortia standardize on rotational platforms for interventional neuroradiology, creating reference-site effects across European training networks.
Market Restraints
- Contrast agent cost volatility:Iodinated contrast supply concentrates among three chemical manufacturers, exposing imaging centers to price shocks during production disruptions.
- EMA MDR compliance friction:Extended clinical evidence requirements for injector accessories delay market entry for innovative contrast delivery systems.
- Ultrasound substitution ceiling:Portable Doppler systems capture routine venous screening, capping premium CT-angiography penetration in superficial vessel assessment.
Strategic Opportunities
- Site-neutral payment arbitrage:CMS reimbursement parity between hospital outpatient departments and independent diagnostic centers creates margin expansion for ambulatory vascular imaging investments.
- AI reconstruction convergence:Deep learning algorithms paired with photon-counting CT detectors enable sub-millisievert coronary angiography, opening pediatric and repeat-screening applications.
- Hybrid OR integration:Surgical navigation systems merging intraoperative angiography with robotic guidance capture premium pricing in aortic endograft placement.
Industry Challenges
- Interventional radiologist training pipelines:Fellowship programs produce insufficient neuroradiology specialists to operate advanced rotational angiography suites at installed capacity.
- Legacy PACS integration complexity:New 3D imaging workstations require middleware layers to communicate with decade-old hospital archive systems, extending deployment timelines.
- CE mark renewal under MDR:Existing angiography system registrations face substantial clinical data gaps, forcing manufacturers to sponsor retrospective safety studies for continued European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Imaging Systems Market |
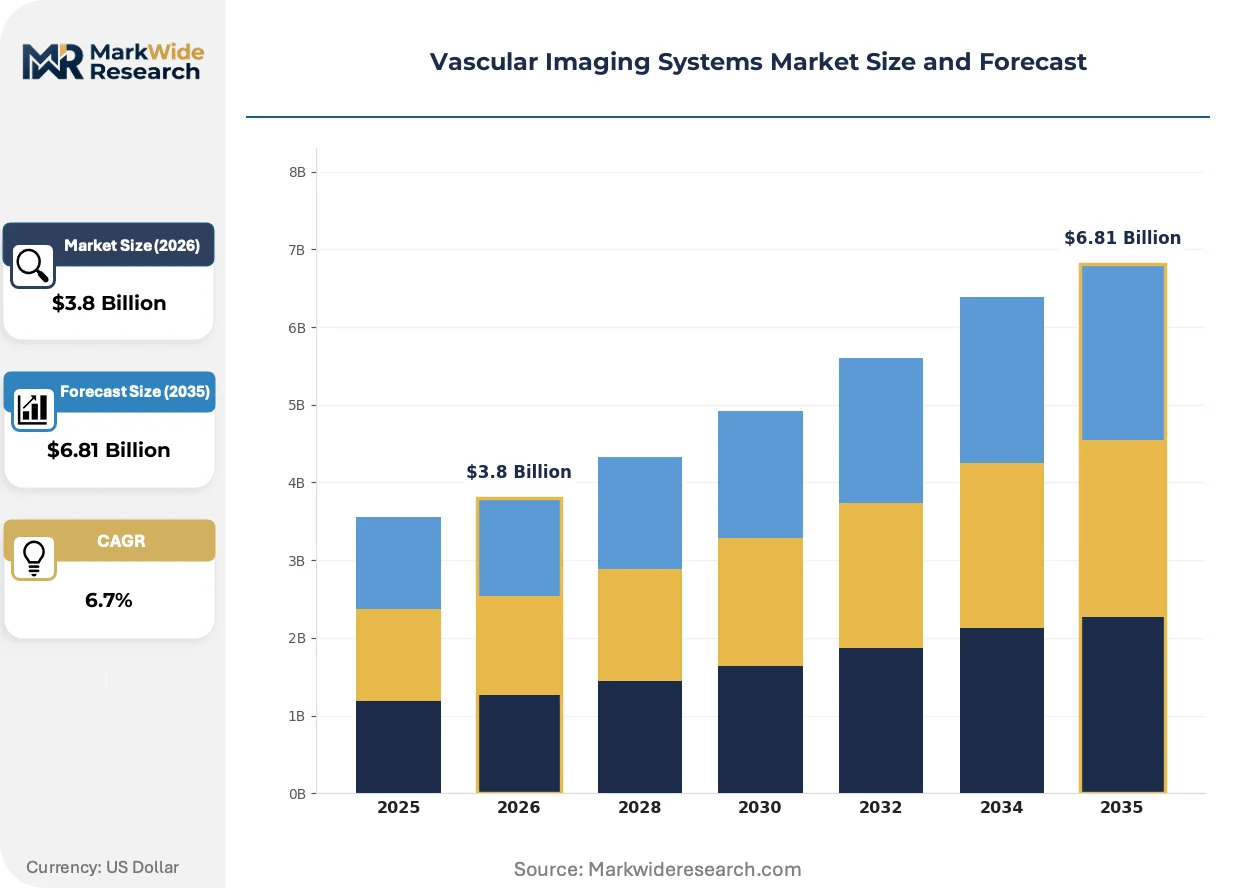
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, MRI, CT Scan, Angiography Technology: Digital Imaging, Contrast Media, 3D Imaging, Real-time Imaging End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Facilities Application: Cardiology, Neurology, Oncology, Peripheral Vascular Disease |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems Corporation, FUJIFILM Corporation, Hitachi Medical Corporation, Samsung Medison Co., Ltd., Abbott Laboratories, Hologic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Imaging Systems Market Evolving Landscape
Photon-counting detector technology is redefining spatial resolution thresholds in coronary imaging, while regulatory pressure on radiation exposure accelerates software-based dose optimization. These forces are compressing the technology refresh cycle and redrawing competitive boundaries between CT and angiography modalities.
Photon-counting CT is fragmenting the traditional energy-integrating detector market by enabling material decomposition at sub-millimeter resolution. Cardiac imaging departments in tertiary US hospitals are piloting these systems for coronary stent patency assessment. The technology is fragmenting procurement decisions, forcing separate capital allocations for hardware upgrades rather than incremental software enhancements.
EMA's Medical Device Regulation is extending approval timelines for contrast injector accessories by demanding prospective clinical evidence portfolios. Manufacturers must now sponsor safety studies for legacy product lines seeking renewal. European distributors are responding by consolidating supplier relationships to reduce regulatory compliance overhead across fragmented accessory portfolios.
Service unbundling is separating equipment hardware from software maintenance and contrast supply contracts. Independent diagnostic centers in Germany now negotiate three-year hardware leases with per-scan consumable pricing rather than bundled capital purchases. This shift concentrates purchasing power among multi-site imaging networks capable of standardizing protocols across distributed CT fleets.
Vascular Imaging Systems Market Segmentation
Segmentation in vascular imaging reveals how substitution pressure and reimbursement models fragment capital allocation across modalities. Procurement committees weigh portability against resolution thresholds when matching technology to clinical setting.
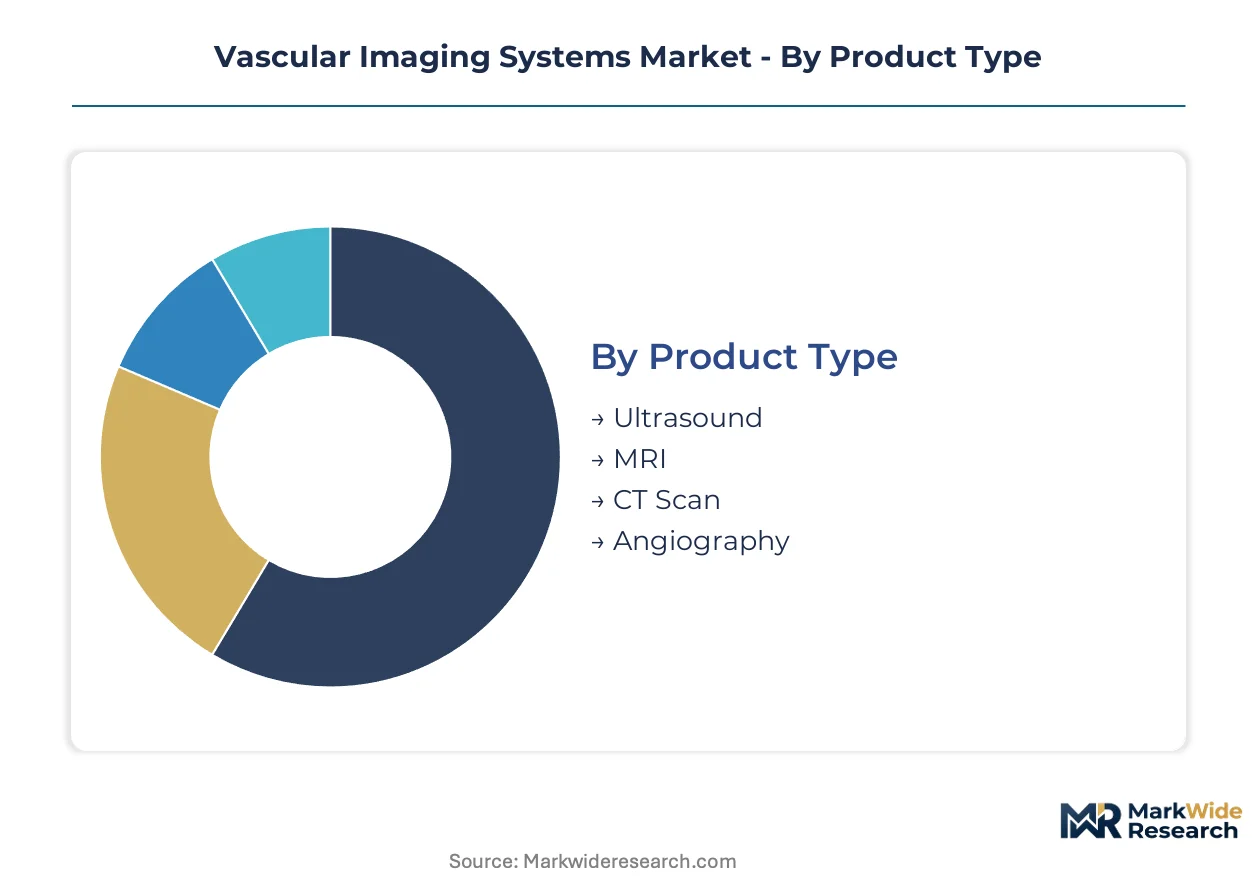
Product Type:
Ultrasound systems face the most acute substitution pressure from handheld Doppler devices that displace cart-based units in routine venous screening.
- Ultrasound:Acoustic wave-based modalities operate without ionizing radiation, enabling point-of-care deployment in emergency departments and ambulatory settings. Demand concentrates in German outpatient networks where portable systems support same-day discharge protocols for deep vein thrombosis evaluation.
- CT Scan:X-ray computed tomography delivers sub-millimeter spatial resolution for coronary stent assessment and peripheral artery disease mapping. US hospital networks are replacing aging angiography suites with CT-based vascular platforms to comply with FDA dose optimization mandates under 21 CFR 1020.32.
- MRI:Magnetic resonance angiography provides non-contrast alternatives for patients with renal impairment.
- Angiography:Digital subtraction systems remain essential for interventional guidance during endovascular procedures.
Ultrasound retains volume leadership; CT Scan holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium photon-counting platforms from standard energy-integrating detectors in European procurement decisions.
- 3D Imaging:Rotational angiography platforms generate volumetric datasets for complex aortic repairs and interventional neuroradiology. German university hospital consortia have standardized on these systems, creating reference-site effects across European training networks.
- Digital Imaging:Flat-panel detector technology enables rapid image acquisition with reduced radiation exposure. Demand clusters in US cardiac centers upgrading to dose-tracked angiography suites under updated FDA guidance.
- Contrast Media:Iodinated and gadolinium-based agents enhance vessel delineation in CT and MRI workflows.
- Real-time Imaging:Intraoperative fluoroscopy guides endovascular procedures with immediate feedback.
Digital Imaging dominates installed base; 3D Imaging is climbing the fastest.
End User:
Customer type determines capital intensity, with hospital networks favoring integrated platform purchases over diagnostic center preference for modular upgrades.
- Hospitals:Tertiary medical centers deploy hybrid operating rooms combining angiography with surgical navigation for aortic endograft placement. North American hospital networks are consolidating vendor relationships around single-source CT-angiography contracts.
- Diagnostic Centers:Independent imaging facilities negotiate three-year hardware leases with per-scan consumable pricing. German multi-site networks standardize protocols across distributed CT fleets to maximize throughput under bundled payment models.
- Outpatient Facilities:Day-surgery centers rotate toward minimally invasive vascular diagnostics for routine peripheral artery disease screening.
- Research Institutes:Academic medical centers pilot photon-counting CT detectors for pediatric applications.
Hospitals command the largest capital allocation; Diagnostic Centers are gaining share fastest.
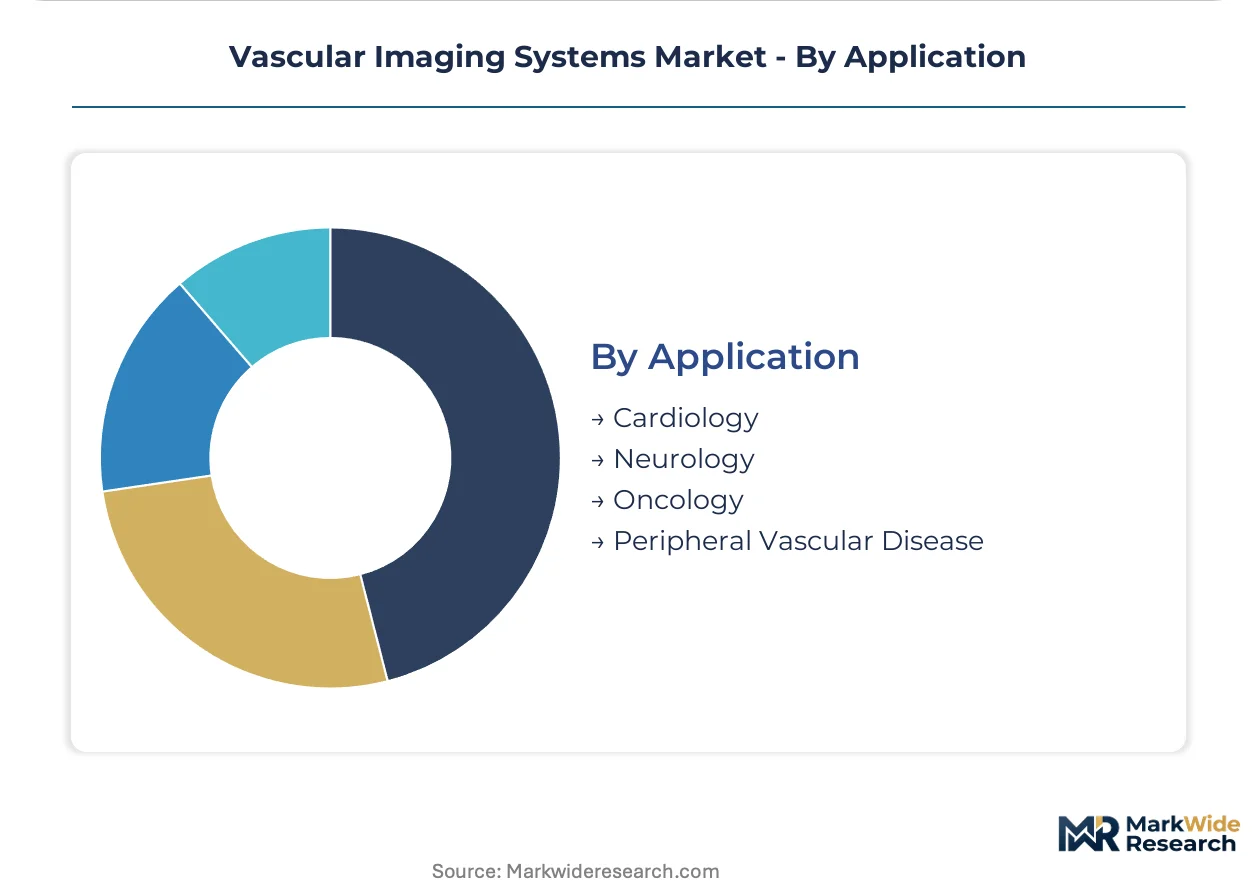
Application:
Maturity gradients separate established cardiology workflows from emerging neurology applications requiring specialized interventional expertise.
- Cardiology:Coronary angiography and stent assessment represent the most mature vascular imaging segment. Siemens Healthineers leverages dual-source CT portfolios to dominate cardiac workflows in European day-surgery centers.
- Peripheral Vascular Disease:Lower-extremity artery evaluation generates concentrated margin pools where bundled payment models reward rapid throughput. US Medicare reimbursement shifts are pulling CT-based diagnostics into outpatient settings for this indication.
- Neurology:Interventional neuroradiology demands rotational angiography platforms with specialized operator training.
- Oncology:Tumor vessel mapping supports treatment planning and response monitoring.
Cardiology retains procedure volume leadership; Peripheral Vascular Disease shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters concentrate in Germany, the United States, Japan, and the Netherlands, with assembly operations and R&D facilities anchoring regional supply chains. Procurement patterns diverge sharply across these markets based on reimbursement structures and regulatory timelines.
United States
FDA dose optimization mandates under 21 CFR 1020.32 are accelerating replacement cycles for aging angiography suites in cardiac centers. Hospital networks in Texas and the Northeast Corridor are consolidating vendor relationships around single-source CT-angiography contracts. The Cleveland Clinic and Mayo Clinic anchor reference-site networks that standardize protocols across multi-state health systems.
Germany
University hospital consortia in Bavaria and Baden-Württemberg have standardized on 3D rotational angiography platforms for interventional neuroradiology. EMA Medical Device Regulation requirements are extending approval timelines for contrast injector accessories, forcing distributors to consolidate supplier relationships. Siemens Healthineers maintains dual-source CT manufacturing in Forchheim, anchoring European cardiac imaging supply.
Japan
PMDA streamlined review pathways for AI-enabled image reconstruction software are reducing time-to-market for photon-counting CT systems. Metropolitan Tokyo hospitals pilot pediatric coronary applications using sub-millisievert protocols. Hitachi Medical Corporation and Canon Medical Systems anchor domestic manufacturing clusters in Kanto and Kansai regions.
China
NMPA priority review channels for innovative medical devices are accelerating market entry for photon-counting detector platforms. Tertiary hospitals in Beijing and Shanghai are replacing imported angiography systems with domestically assembled hybrid OR configurations. Local manufacturers are capturing share in peripheral vascular CT segments through government procurement preferences.
Netherlands
Philips Healthcare anchors European R&D for integrated hybrid operating room designs in Eindhoven. Dutch university medical centers in Amsterdam and Utrecht serve as reference sites for surgical navigation systems merging intraoperative angiography with robotic guidance. EMA MDR compliance requirements are concentrating distribution networks around fewer, larger supplier relationships.
Vascular Imaging Systems Market Competitive Landscape
Concentration sits with diversified imaging conglomerates holding full-stack portfolios across CT, MRI, and angiography modalities. Three to five manufacturers capture the majority of premium-tier hospital contracts, while specialized ultrasound vendors occupy ambulatory and point-of-care segments. Strategic archetypes include integrated platform suppliers, modular component specialists, and AI software layer providers. Competitive moves center on photon-counting detector R&D partnerships and service unbundling into hardware lease-per-scan consumable models.
Among diversified imaging conglomerates, Siemens Healthineers, GE Healthcare, and Koninklijke Philips N.V. exemplify the integrated platform archetype. Siemens Healthineers occupies a position anchored in dual-source CT cardiac workflows. GE Healthcare represents AI-enabled image reconstruction capabilities that reduce contrast dye volumes. Koninklijke Philips N.V. sits within the hybrid OR integration tier, combining angiography with surgical navigation systems. These three manufacturers collectively anchor reference-site networks across German university consortia and US cardiac centers.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| FUJIFILM Corporation |
| Hitachi Medical Corporation |
| Samsung Medison Co., Ltd. |
| Abbott Laboratories |
| Hologic Inc. |
| Others |
Value Network & Pricing Analysis
FDA 21 CFR 1020.32 dose optimization standards simultaneously gate supplier qualification and stratify price tiers, forcing manufacturers to absorb certification costs while hospitals pay premiums for compliant platforms. This regulatory anchor compresses margins on legacy angiography systems while photon-counting CT platforms command hardware premiums.
Pricing Analysis
FDA 21 CFR 1020.32 dictates the pricing tier structure across US vascular imaging procurement, separating dose-tracked angiography suites from grandfathered installations. Three-tier pricing stratifies across premium photon-counting CT, standard dual-source CT, and economy refurbished angiography systems. Cost compression in the standard tier intensifies as German university hospital consortia consolidate purchasing power. Independent diagnostic centers exhibit highest price sensitivity, deferring upgrades until lease-per-scan models mature.
Supply Chain Analysis
Germany and Japan anchor precision detector fabrication and rotational gantry assembly for angiography platforms. Supply chains draw from iodinated contrast chemical manufacturers concentrated in the United States and Europe, plus rare-earth scintillator materials sourced through Chinese processing facilities. Single-source vulnerability concentrates in photon-counting detector crystal growth, where two suppliers control semiconductor-grade cadmium zinc telluride. Distribution runs through hospital procurement committees and GPO contracts in North America, direct manufacturer relationships in German university consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vascular imaging fragmentation creates opportunity niches as site-neutral payment parity pulls diagnostics from hospital campuses toward ambulatory settings. This demand-side shift splinters capital allocation across integrated platform suppliers and modular component specialists.
For Market Incumbents: Fortify reference-site networks in German neuroradiology consortia and US cardiac centers to lock in protocol standardization. Deepen backward integration into photon-counting detector manufacturing to reduce single-source crystal supply risk. Accelerate AI reconstruction software development to defend against pure-play algorithm entrants threatening hardware attach rates.
For New Entrants and Emerging Players: Lead with per-scan consumable pricing models targeting German multi-site diagnostic networks seeking hardware lease flexibility. Capture white space in portable Doppler ultrasound for US outpatient venous screening, where hospital procurement committees show lowest vendor loyalty. Pursue hospital-at-home partnership channels for remote vascular monitoring applications.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-enabled image reconstruction software, reducing barrier thresholds for algorithm-centric entrants. Long-term viability favors platform suppliers with installed base leverage for recurring software revenue. Watch photon-counting CT adoption curves in pediatric applications as signal for technology substitution inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting CT Platform Launch | FDA 21 CFR 1020.32 compliance enables pediatric coronary applications at sub-millisievert doses. |
| AI Reconstruction Software Development | Deep learning algorithms reduce iodinated contrast volumes, lowering procurement cost volatility exposure. |
| Hybrid OR Integration Partnership | Surgical navigation systems capture premium pricing in aortic endograft placement workflows. |
| Site-Neutral Payment Reimbursement Strategy | CMS parity between hospital outpatient and independent diagnostic centers reshapes capital allocation. |
| Contrast Injector Accessory CE Marking | EMA MDR clinical evidence requirements raise barriers against low-cost import competition. |
Research Methodology
Initial hypotheses were tested against primary input from interventional radiologists, hospital procurement committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EMA medical device registration databases, CMS Medicare reimbursement schedules, and hospital capital expenditure disclosures. Bottom-up installed base modeling triangulated with top-down market sizing across modality segments.
Variance decomposition structured the analytical framework across product type, technology tier, end-user facility scale, and application maturity over the projection horizon. CAGRs derived from replacement cycle analysis, technology diffusion curves, and reimbursement elasticity modeling. Forecast inputs incorporated photon-counting detector adoption rates and AI reconstruction software attachment trends.
The analysis sits within stated boundaries; outcomes outside sustained FDA dose optimization enforcement or EMA MDR compliance timelines would require recalibration. Forecasts reflect assumptions on interventionalist training pipeline capacity and contrast chemical supply stability. Recalibration cycles align with material shifts in CMS reimbursement parity implementation and photon-counting CT reference-site validation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Portable Cardiology Ultrasound Systems Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
PET Radiotracer Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Pediatric Imaging Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
Global Dental Radiology and Dental Imaging Devices Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Nuclear Imaging Devices Market
Medical Imaging
Germany Magnetic Resonance Imaging Market