
 Asia-Pacific Feed Antioxidants Market | 2026-2036
Asia-Pacific Feed Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Antioxidants Market Outlook
China's GB standards for feed additive safety is hardening the cost-of-entry calculus for imported antioxidant suppliers seeking market access. BASF SE leverages its synthetic antioxidant manufacturing scale to sustain pricing power across Southeast Asian distributor networks. Cargill anchors its position through backward integration into raw material sourcing for ethoxyquin and BHT production. Adisseo competes by specializing in species-specific antioxidant premix formulations tailored to tropical climate stressors.
Asia-Pacific feed antioxidants comprise chemical compounds or natural extracts added to animal feed to inhibit lipid oxidation and preserve nutritional integrity, typically formulated at inclusion rates of 100-500 grams per metric ton depending on substrate vulnerability and storage duration. Their primary commercial purpose centers on extending feed shelf life, protecting fat-soluble vitamins, and maintaining palatability across extended supply chains in humid subtropical climates. Synthetic antioxidants currently occupy the largest product type position due to cost efficiency, though natural formulations derived from tocopherols and rosemary extracts are gaining fastest growth momentum as aquaculture operations seek clean-label certification pathways. The poultry application segment leads volume consumption, while ruminant applications concentrate margin pools in premium protected choline and bypass fat formulations.
India's BIS feed additive standards, China's SAMR registration requirements, and Japan's MAFF-affiliated feed safety committees collectively shape product registration timelines, residue limit protocols, and cross-border trade documentation burdens. Australia's TGA-equivalent agricultural chemical regulator and South Korea's MFDS-aligned feed control measures further complicate harmonization for multinational suppliers operating across the region. Stakeholders must monitor the divergence between ASEAN harmonized standards and country-specific enforcement capacities when prioritizing registration investments and local partnership structures.
Market Dynamics
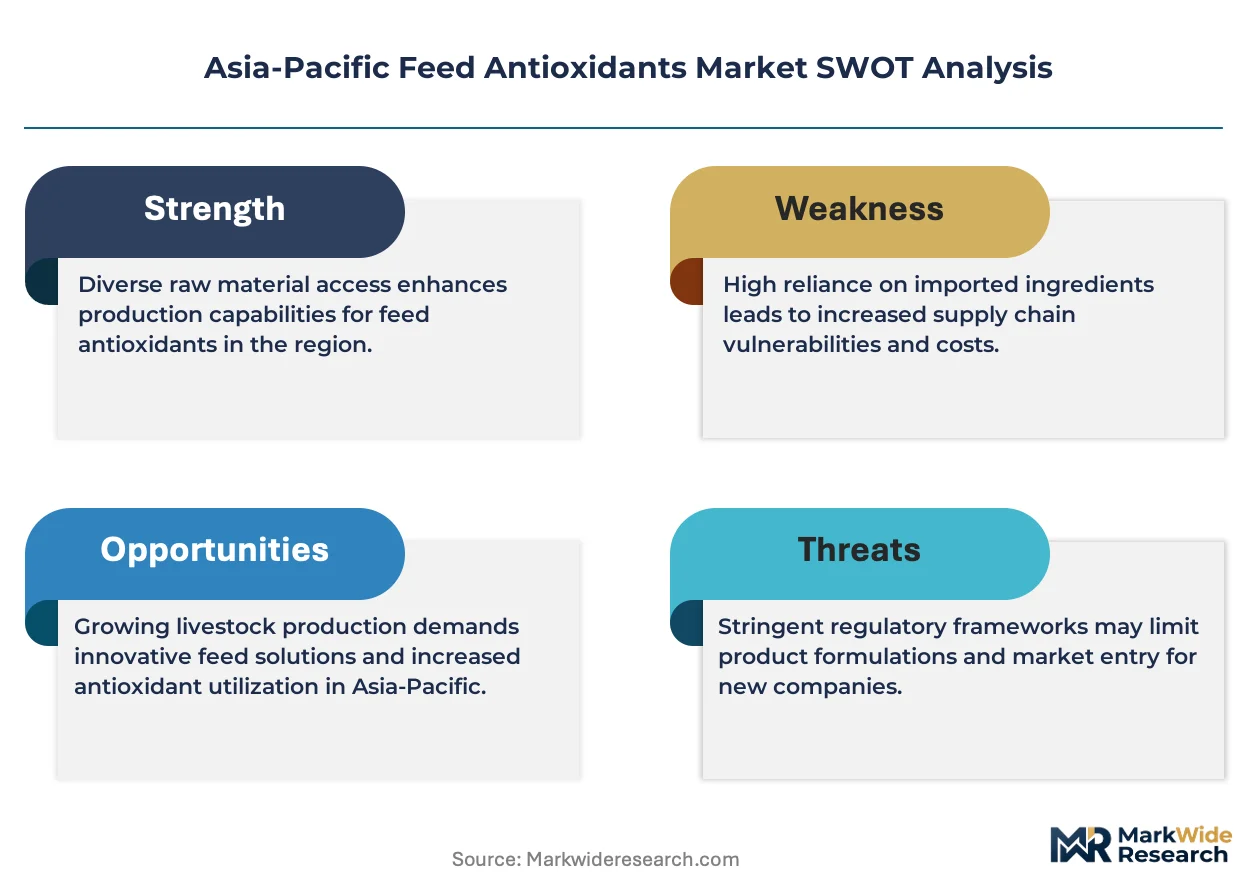
Regulatory divergence between China's SAMR registration protocols and India's BIS feed additive standards is fragmenting market access pathways for antioxidant suppliers. This compliance multiplicity forces manufacturers to maintain parallel formulation portfolios and country-specific dossier investments.
Growth Catalysts
- Vietnam's Mekong Delta commercial farming corridor:Integrated poultry operations are upgrading from synthetic to natural antioxidant solutions to meet export certification requirements for EU-bound meat shipments.
- China's GB standards tightening:Stricter residue limit protocols for ethoxyquin in aquaculture feeds are accelerating replacement demand for tocopherol-based alternatives across coastal shrimp farming provinces.
- Tropical climate stressors:Humidity-induced lipid oxidation in extended supply chains is elevating antioxidant inclusion rates in feed formulations stored beyond 60 days.
Market Restraints
- Synthetic antioxidant price volatility:Petrochemical feedstock fluctuations for BHT and ethoxyquin production compress margin stability for cost-sensitive Southeast Asian distributors.
- Natural extract supply concentration:Rosemary extract sourcing clusters in Mediterranean processing facilities create geographic vulnerability for Asia-Pacific formulators seeking clean-label inputs.
- Regulatory friction from Japan's MAFF:Extended safety evaluation timelines for novel antioxidant molecules delay product registration by 18-24 months versus ASEAN harmonized pathways.
Strategic Opportunities
- Philippines' underpenetrated aquaculture sector:Milkfish and tilapia farming operations in Visayas region lack antioxidant adoption protocols, presenting first-mover positioning for technical service providers.
- India's FSSAI-aligned feed safety expansion:Mandatory traceability requirements for imported additives create partnership openings for local contract manufacturers with established testing infrastructure.
- Encapsulation technology convergence:Microencapsulation of tocopherols with chitosan coatings enables controlled release in ruminant bypass fat applications, commanding premium positioning.
Industry Challenges
- Toxicology dossier compilation expertise:Shortage of regulatory affairs specialists familiar with both China's GB standards and South Korea's MFDS-aligned feed control measures extends registration preparation cycles.
- Multi-country certification synchronization:Divergent residue limit protocols between Australia's TGA-equivalent agricultural chemical regulator and ASEAN harmonized standards force redundant analytical testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Antioxidants Market |
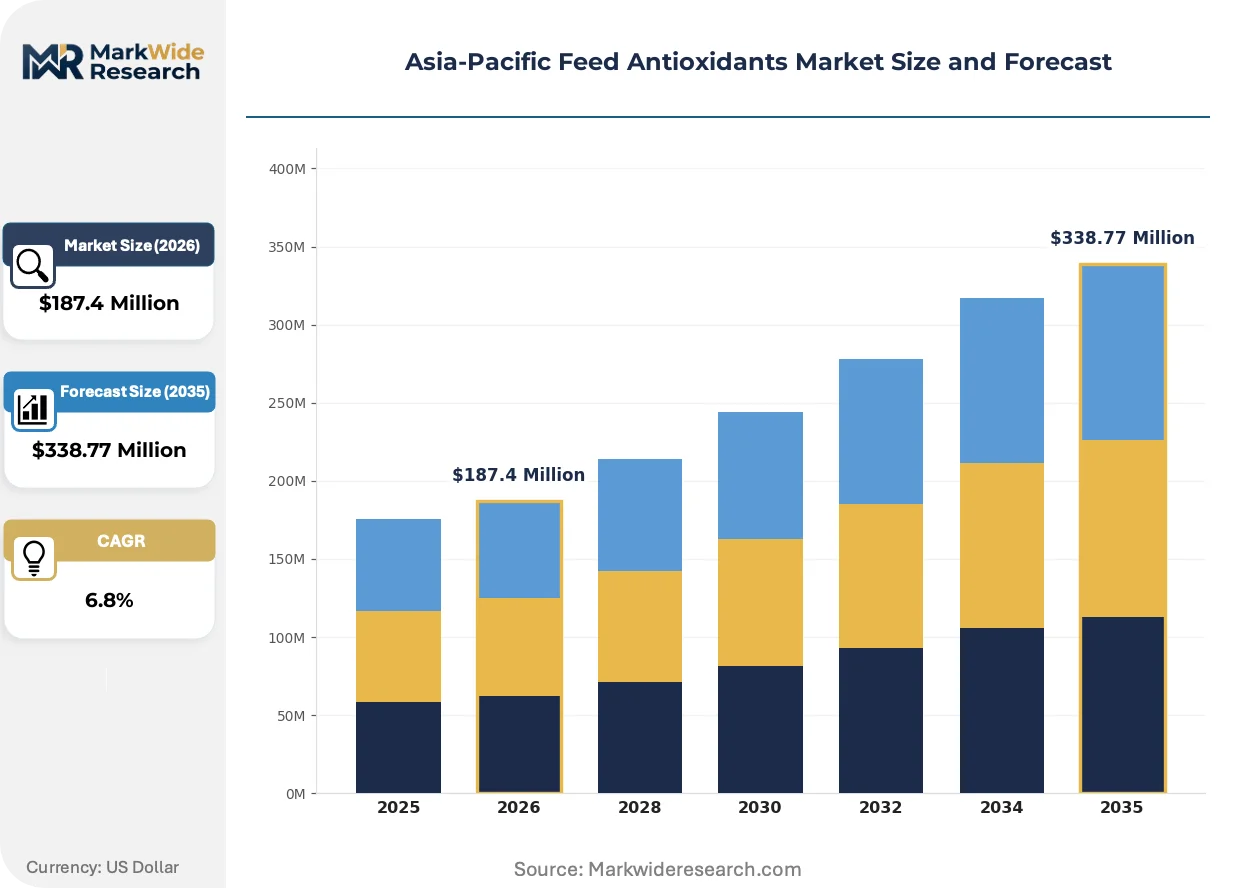
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Nutraceutical, Premix Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granular, Tablet Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | AllTech, Cargill, BASF SE, Adisseo, Archer Daniels Midland Company, Kemin Industries, DSM-Firmenich AG, Perstorp, Novus International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Antioxidants Market Strategic Shifts
Biotechnology-derived antioxidants and precision delivery systems are displacing commodity synthetic formulations across premium feed segments. These innovations target oxidative stability in high-value aquaculture and specialized ruminant nutrition applications.
Microencapsulated tocopherol formulations with chitosan coatings are rewriting stability performance benchmarks for tropical storage conditions. Shrimp feed manufacturers in Thailand and Indonesia are adopting these systems at 2-3x the pace of poultry compounders. The technology is compressing synthetic antioxidant pricing power in premium aquaculture channels while enabling clean-label certification pathways for EU export compliance.
China's SAMR has tightened GB standard enforcement for imported feed additives, mandating enhanced residue testing documentation at port of entry. Foreign suppliers now face extended customs clearance timelines and batch-specific analytical certificate requirements. Aquaculture antioxidant importers are responding by pre-positioning inventory in bonded warehouses near Qingdao and Guangzhou to buffer regulatory delays.
Integrated poultry operations in Vietnam and Thailand are consolidating procurement authority at headquarters level, displacing decentralized buying through provincial distributors. Large-scale Mekong Delta farming groups now negotiate directly with antioxidant manufacturers for volume-contracted supply agreements. This concentration is most visible in Vietnam's commercial broiler sector, where top-ten producers control 60% of antioxidant purchasing decisions.
Asia-Pacific Feed Antioxidants Market Segmentation
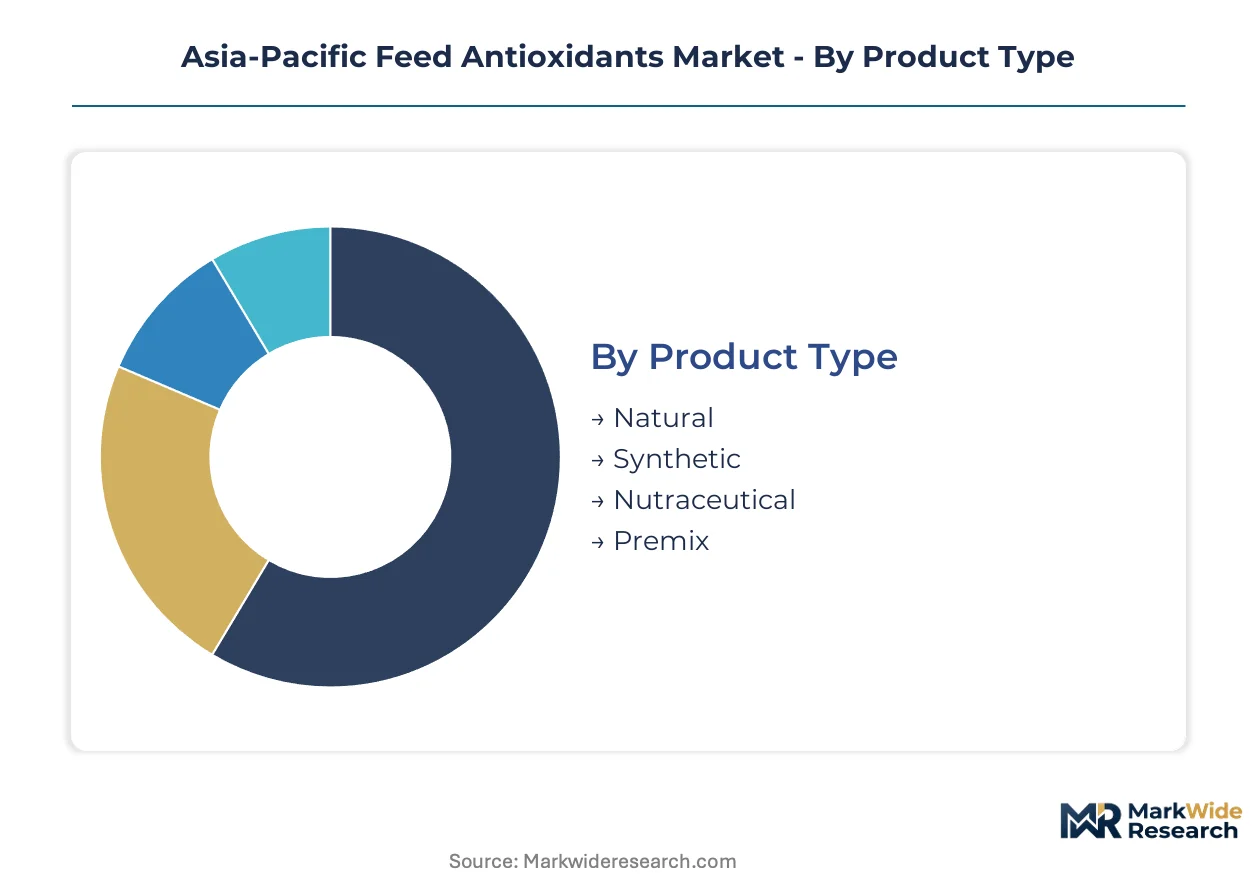
Feed antioxidant suppliers configure product portfolios across four intersecting dimensions. Each segmentation axis carries distinct margin profiles, regulatory exposure, and technical service requirements that shape go-to-market economics.
Product Type:
Synthetic formulations dominate volume throughput while natural extracts command premium positioning in certified export channels.
- Synthetic:Petrochemical-derived antioxidants including BHT, ethoxyquin, and butylated hydroxyanisole deliver cost-efficient oxidation inhibition at inclusion rates of 100-300 grams per metric ton. Vietnam's Mekong Delta integrated poultry operations rely on synthetic grades for domestic-market broiler production where clean-label premiums do not apply.
- Natural:Tocopherol concentrates and rosemary extract formulations enable EU-compliant residue profiles for aquaculture export certification. China's coastal shrimp farming provinces are accelerating replacement of ethoxyquin with tocopherol-based alternatives under tightened GB standard enforcement.
- Nutraceutical:Functional antioxidant blends with added bioactive compounds target stress mitigation in high-density farming systems.
- Premix:Species-specific antioxidant complexes formulated with mineral carriers for tropical climate stability.
Mature deployment sits with Synthetic. Newer deployment is concentrated in Natural.
Application:
Poultry and aquaculture represent opposing ends of the price-performance spectrum for antioxidant specification.
- Poultry:Broiler and layer operations across Southeast Asia constitute the largest consumption base, with inclusion rates escalating in extended supply chains exceeding 60 days storage. Thailand's commercial farming sector drives standardization of antioxidant protocols for integrated operations.
- Aquaculture:Shrimp and finfish feed manufacturers face the steepest clean-label compliance requirements for EU and North American export markets. Indonesian and Thai aquafeed compounders are adopting microencapsulated tocopherol systems at accelerated pace.
- Swine:Sow and grower-finisher diets utilize antioxidants primarily for vitamin stability in pelleted formulations.
- Ruminants:Protected choline and bypass fat applications concentrate margin pools in premium dairy nutrition segments.
Volume leadership belongs to Poultry. Margin expansion concentrates in Aquaculture.
Form:
Physical format selection hinges on feed manufacturing infrastructure and climate exposure during storage.
- Powder:Standardized particle-size antioxidants for dry mash and pelleted feed integration, dominant in compound feed mills with pneumatic handling systems.
- Liquid:Oil-soluble formulations for post-pelleting fat application and aquafeed extrusion processes, gaining adoption in Thailand's shrimp feed sector.
- Granular:Dust-free handling properties suit on-farm mixing operations in Vietnam's provincial distributor networks.
- Tablet:Slow-release formats for specialized ruminant applications requiring rumen bypass protection.
Powder formats retain infrastructure lock-in. Liquid formats are climbing fastest in aquaculture channels.
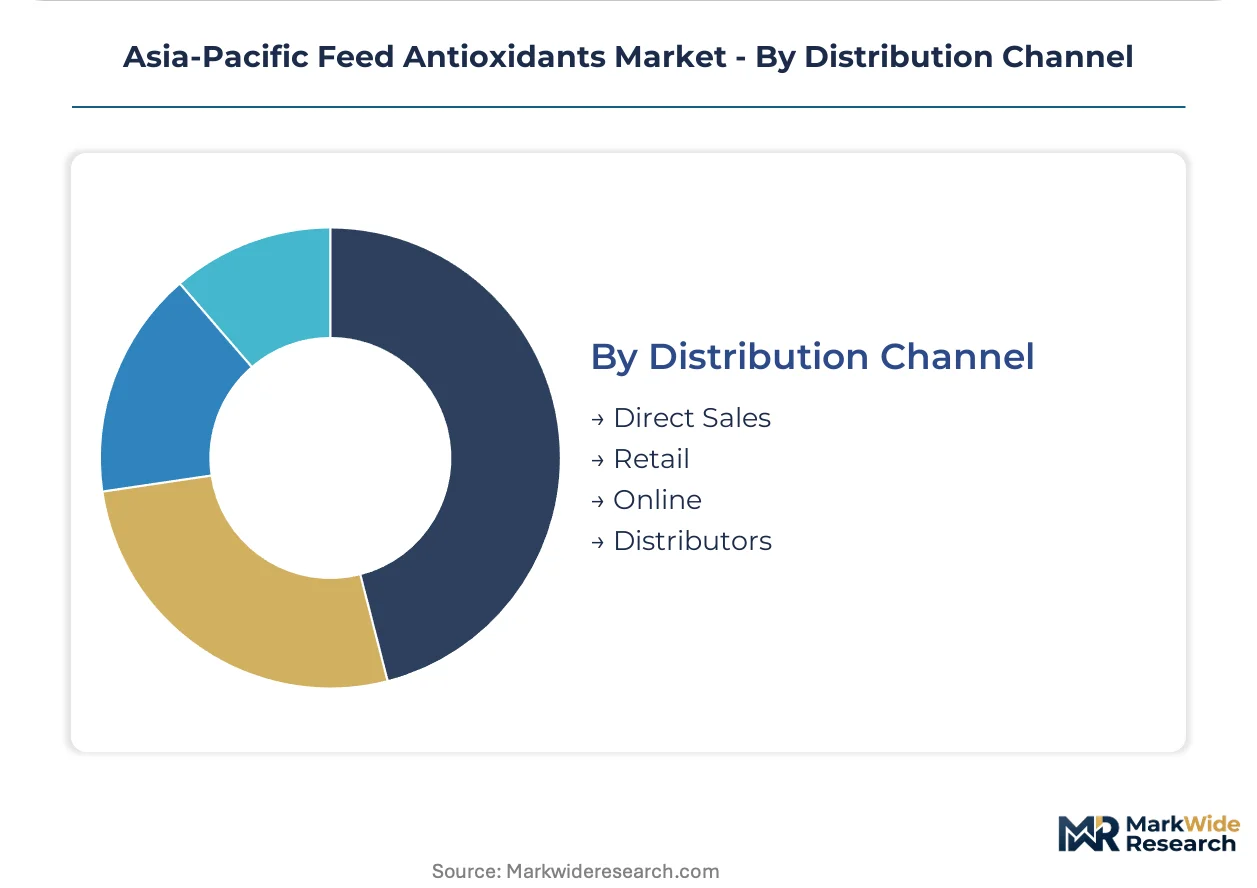
Distribution Channel:
Channel structure is bifurcating between centralized procurement authority and residual decentralized access.
- Direct Sales:Volume-contracted supply agreements between antioxidant manufacturers and integrated farming groups, now controlling 60% of Vietnam's commercial broiler sector procurement decisions.
- Distributors:Provincial feed additive traders serving mid-scale compounders and independent farms across Indonesia's outer islands.
- Retail:Packaged antioxidant products for smallholder operations in Philippines' Visayas region milkfish farming corridor.
- Online:Emerging procurement channel for technical documentation and sample ordering, constrained by hazardous material shipping regulations.
Direct Sales is consolidating share fastest. Retail persists where farming fragmentation exceeds integration thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta Economic Zone concentrates integrated poultry procurement authority, driving antioxidant specification upgrades across Southeast Asian supply chains. China's coastal special economic zones anchor synthetic antioxidant manufacturing scale, while India's feed safety corridors reshape import compliance architecture.
China
Coastal shrimp farming provinces in Guangdong and Shandong are accelerating tocopherol-based antioxidant replacement under SAMR's tightened GB standard enforcement for ethoxyquin residues. The Yangtze River Delta feed manufacturing cluster buffers regulatory delays through bonded warehouse pre-positioning near Qingdao and Guangzhou ports.
Vietnam
Commercial broiler operations in the Mekong Delta corridor are consolidating procurement decisions at headquarters level, displacing provincial distributor networks. Top-ten integrated poultry producers now control sixty percent of antioxidant purchasing volume through direct manufacturer negotiations.
Thailand
Shrimp feed compounders in Samut Sakhon and Surat Thani provinces are adopting microencapsulated tocopherol systems at two to three times the pace of poultry formulators. Thailand's Department of Fisheries aligns residue protocols with EU export certification requirements for aquaculture operations.
India
Poultry integrators in Haryana and Telangana are upgrading feed safety protocols under FSSAI-aligned traceability mandates for imported additives. Local contract manufacturers with established testing infrastructure capture partnership opportunities from mandatory documentation requirements.
Indonesia
Aquafeed producers in East Java and South Sulawesi face clean-label compliance pressure for EU-bound shrimp exports, driving natural antioxidant substitution. Provincial distributor networks across outer islands retain residual market access for mid-scale compounders outside integrated procurement systems.
Asia-Pacific Feed Antioxidants Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base clusters around three strategic archetypes: multinational chemical conglomerates with synthetic manufacturing scale, nutrition specialists with species-specific formulation expertise, and regional distributors with provincial network penetration. Dominant competitive moves include backward integration into raw material sourcing and direct supply agreement consolidation with integrated farming groups.
Among diversified nutrition conglomerates, Cargill and BASF SE exemplify scale-driven positioning through captive supply chain control. Adisseo occupies a specialist tier with tropical climate formulation focus. These three anchors represent divergent strategic postures: manufacturing scale concentration, raw material integration depth, and climate-specific technical service specialization.
| Leading Market Players |
|---|
| AllTech |
| Cargill |
| BASF SE |
| Adisseo |
| Archer Daniels Midland Company |
| Kemin Industries |
| DSM-Firmenich AG |
| Perstorp |
| Novus International |
| Others |
Value Chain & Pricing Dynamics
Family-owned Mediterranean processing facilities dominate rosemary extract supply, concentrating pricing power among natural antioxidant formulators while forcing Asia-Pacific buyers into long-term offtake commitments to secure clean-label inputs. This ownership pattern tightens margin discipline across synthetic and natural product tiers as petrochemical feedstock volatility intersects with botanical sourcing bottlenecks.
Pricing Analysis
Short lead-time premiums command pricing power in Vietnam's Mekong Delta corridor where integrated poultry groups pre-position inventory ahead of monsoon logistics disruptions. Contract-based long-term offtake agreements dominate procurement, with price differentiation driven by certification grade (EU-compliant residue profiles versus domestic-market synthetic grades) and volume scale. Pricing pressure stems from ethoxyquin replacement demand under China's SAMR enforcement, compressing synthetic antioxidant margins while elevating tocopherol premiums. Mid-scale compounders in Indonesia's outer islands exhibit highest price sensitivity; premium aquaculture exporters in Thailand show least.
Supply Chain Analysis
Single-source vulnerability sits with rosemary extract processing concentrated in Mediterranean facilities, exposing Asia-Pacific natural antioxidant formulators to geographic concentration risk. Raw material dependencies draw from Chinese petrochemical feedstocks for BHT and ethoxyquin, Vietnamese poultry integration for tocopherol demand signaling, and Indonesian aquafeed expansion for clean-label pull. Tariff exposure on EU-bound botanical imports creates structural supply chain risk. Distribution runs through direct manufacturer agreements with integrated farming groups displacing provincial distributor networks across Vietnam and Thailand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into raw material sourcing anchors competitive positioning as Cargill's captive ethoxyquin supply and BASF's synthetic manufacturing scale demonstrate. Controlling upstream petrochemical or botanical inputs determines margin sustainability.
For Market Incumbents: Acquire rosemary extract processing capacity in Mediterranean sourcing clusters to secure clean-label supply chains against natural antioxidant demand acceleration. Build technical service infrastructure in Vietnam's Mekong Delta to defend direct supply agreements against Adisseo's species-specific formulation specialization. Threat substitution by microencapsulated tocopherol systems demands R&D investment in chitosan coating technologies. For New Entrants and Emerging Players: India's FSSAI-aligned traceability mandates open a window for partnership with local contract manufacturers possessing established testing infrastructure. Target Philippines' Visayas region milkfish farming corridor where antioxidant adoption protocols remain underdeveloped. Go-to-market angle: technical service bundling with residue testing documentation to satisfy emerging mandatory import requirements. For Investors and Strategic Acquirers: Consolidation of procurement authority at Vietnam's top-ten integrated poultry producers is the leading indicator that direct sales channel control will determine long-term viability. Target acquisition archetype: regional distributors with provincial network penetration convertible to technical service platforms. Signal to watch: SAMR batch-specific analytical certificate requirements extending customs clearance timelines, favoring pre-positioned inventory players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Cargill's captive ethoxyquin supply secures margin stability against petrochemical price swings. |
| Microencapsulation Technology Licensing | Thai shrimp feed compounders adopt chitosan-coated tocopherols at accelerated pace for EU compliance. |
| Direct Supply Agreement Consolidation | Vietnam's Mekong Delta poultry groups now control sixty percent of antioxidant procurement decisions. |
| Regulatory Affairs Capacity Buildout | Shortage of China GB and South Korea MFDS specialists extends registration preparation cycles. |
| Natural Extract Supply Partnership | Mediterranean rosemary processing concentration creates partnership openings for Asia-Pacific formulators. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving feed formulators, regulatory affairs specialists at antioxidant manufacturers, procurement directors at integrated poultry groups, and technical service managers at distributor networks. Secondary sources included China's SAMR registration databases, India's FSSAI import documentation, ASEAN harmonized standard protocols, and Vietnam's customs clearance records. Bottom-up volume modeling triangulated against top-down market sizing across product type and application dimensions.
Granularity-level modeling deployed country-specific regulatory cluster analysis, species-specific formulation requirements, and climate-zone storage duration parameters. Segmentation dimensions included synthetic versus natural product type, poultry versus aquaculture versus ruminant application, powder versus liquid versus granular form, and direct sales versus distributor versus retail channel. CAGRs derived from slope-log regression across annualized volume and value estimates, incorporating ethoxyquin replacement timelines and microencapsulation adoption curves as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for biotechnology-derived antioxidant molecules would alter the outlook. Forecasts reflect assumptions on SAMR enforcement consistency, EU residue protocol stability, and monsoon logistics reliability. Deviation in China's GB standard implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia-Pacific Soil Treatment Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
ASEAN Livestock Disinfectant Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Indonesia Herbicide Market