
 Asia-Pacific Feed Binders Market | 2026-2036
Asia-Pacific Feed Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Binders Market Outlook
Distributor networks across Southeast Asia are rewriting how feed binders reach midsize aquaculture and poultry operations. Cargill Inc. leverages its integrated supply chain to control bulk delivery channels from manufacturing hubs in Thailand and Indonesia. Borregaard ASA specializes in lignin-based binder formulations that sustain premium positioning among environmentally conscious compound feed producers. Alltech competes through yeast-derived technologies that anchor its reputation for palatability enhancement across ruminant applications.
Asia-Pacific feed binders comprise adhesive additives—typically polysaccharides, proteins, lignosulfonates, or synthetic polymers—that cohere feed ingredients into stable pellets, powders, or granules resistant to water degradation and mechanical fracture during handling. These materials functionally reduce feed waste, improve nutrient digestibility, and enable precise dosing of medicated or supplemented rations across intensive livestock systems. Plant-based sources, particularly wheat gluten and guar gum derivatives, dominate volume due to cost accessibility and regulatory familiarity, though synthetic binders command disproportionate margin pools in aquaculture where water stability requirements are most stringent. Pellet formulations lead value contribution because pelleting lines require higher binder inclusion rates than mash or liquid systems, while aquaculture application shows the fastest structural expansion as shrimp and marine fish diets shift toward high-performance extruded feeds.
India's FSSAI and China's Ministry of Agriculture and Rural Affairs enforce divergent but tightening contaminant limits and labeling standards that shape product registration timelines and reformulation costs across the region. REACH-equivalent chemical notification protocols in South Korea and Japan further segment market access, favoring suppliers with established regulatory dossiers over opportunistic exporters. Stakeholders must monitor how ASEAN harmonization initiatives reconcile these national frameworks, as regulatory alignment will determine which binder technologies achieve scalable cross-border deployment without redundant compliance investment.
Market Dynamics
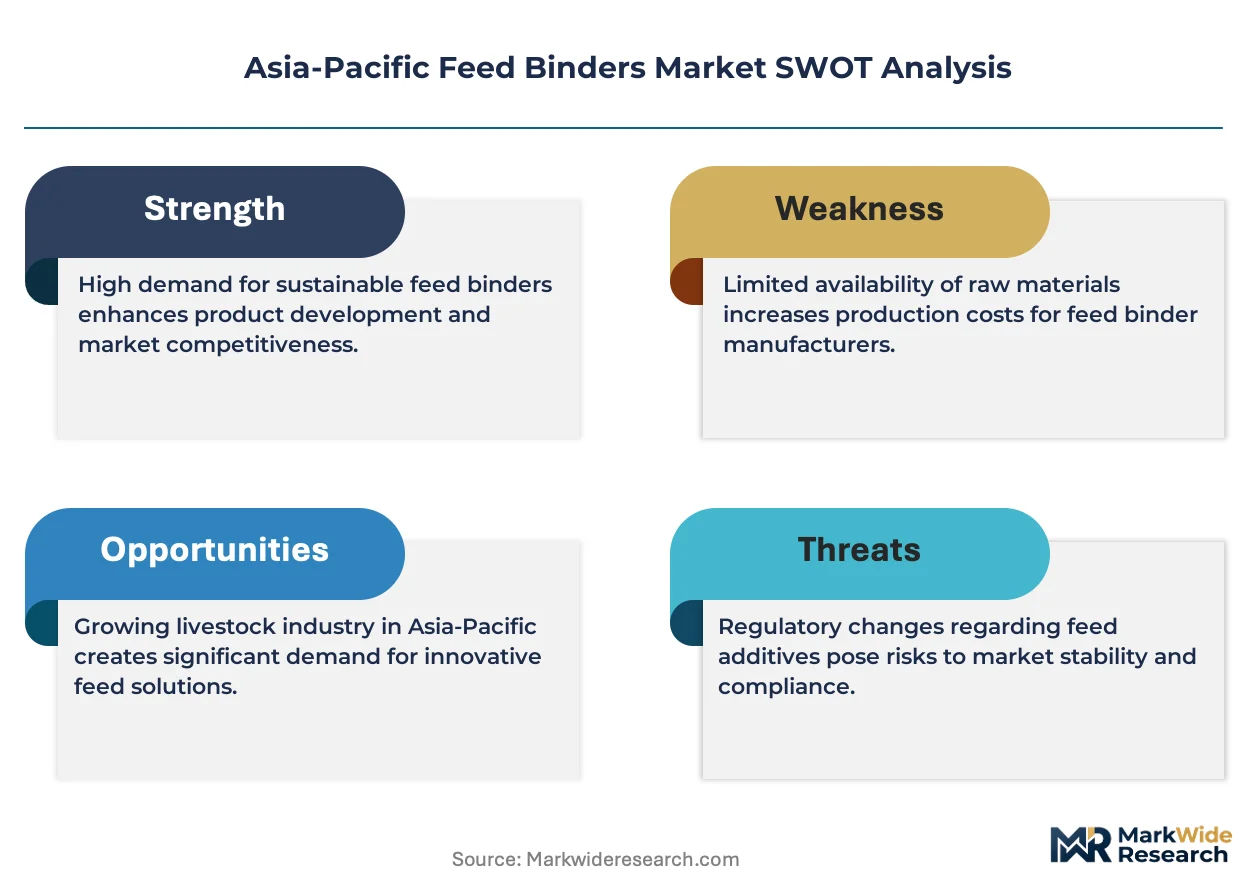
Intensive aquaculture expansion across Vietnam and Indonesia is forcing binder suppliers to reformulate for water stability standards that exceed traditional livestock specifications, compressing product development cycles and reshaping regional procurement priorities.
Growth Catalysts
- China's coastal cluster concentration:Shrimp and marine fish feed production hubs in Guangdong and Fujian provinces generate concentrated demand for high-performance extruded feed binders with superior water resistance profiles.
- FSSAI directive enforcement:India's feed safety authority mandates stricter additive compliance documentation, accelerating formalization of previously informal binder supply relationships and favoring registered suppliers with established dossiers.
- Extrusion technology diffusion:Advanced pelleting equipment adoption across Indonesian aquaculture operations requires higher inclusion-rate binders, expanding addressable product volumes per ton of finished feed produced.
Market Restraints
- Guar gum price volatility:Plant-based binder feedstock costs fluctuate with monsoon-dependent Indian agricultural output, squeezing formulation margins for cost-optimized compound feed producers.
- Thai manufacturing concentration:Bulk production gravity in Southeast Asian hubs creates single-source vulnerability for distributors serving fragmented Indonesian and Vietnamese buyer bases.
- Synthetic polymer substitution ceiling:Premium aquaculture applications require water stability beyond lignosulfonate or protein-based binder performance limits, forcing continued reliance on petrochemical-derived alternatives with regulatory exposure.
Strategic Opportunities
- Philippine aquaculture underpenetration:Archipelago geography and fragmented farm structures have delayed intensive feed adoption, creating first-mover positioning for binder suppliers establishing technical service presence in Mindanao and Visayas.
- Dual carbon goal alignment:China's MEE carbon intensity targets incentivize lignin-based binder adoption as lower-emission alternatives to synthetic polymers in ruminant feed applications.
- Direct-to-farm digital channels:E-commerce platforms and mobile-enabled ordering systems bypass traditional distributor layers for midsize Vietnamese shrimp operations, enabling margin capture and customer data accumulation.
Industry Challenges
- REACH-equivalent dossier compilation:South Korea and Japan chemical notification protocols demand toxicological and environmental fate data that smaller regional suppliers lack resources to generate independently.
- Extrusion equipment integration complexity:Binder performance must be calibrated to specific screw configurations and thermal profiles, requiring technical field support capabilities that strain lean distribution organizations.
- Multi-jurisdiction labeling harmonization:Divergent ASEAN national standards for additive declaration and maximum inclusion rates force SKU proliferation and inventory management complexity for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Binders Market |
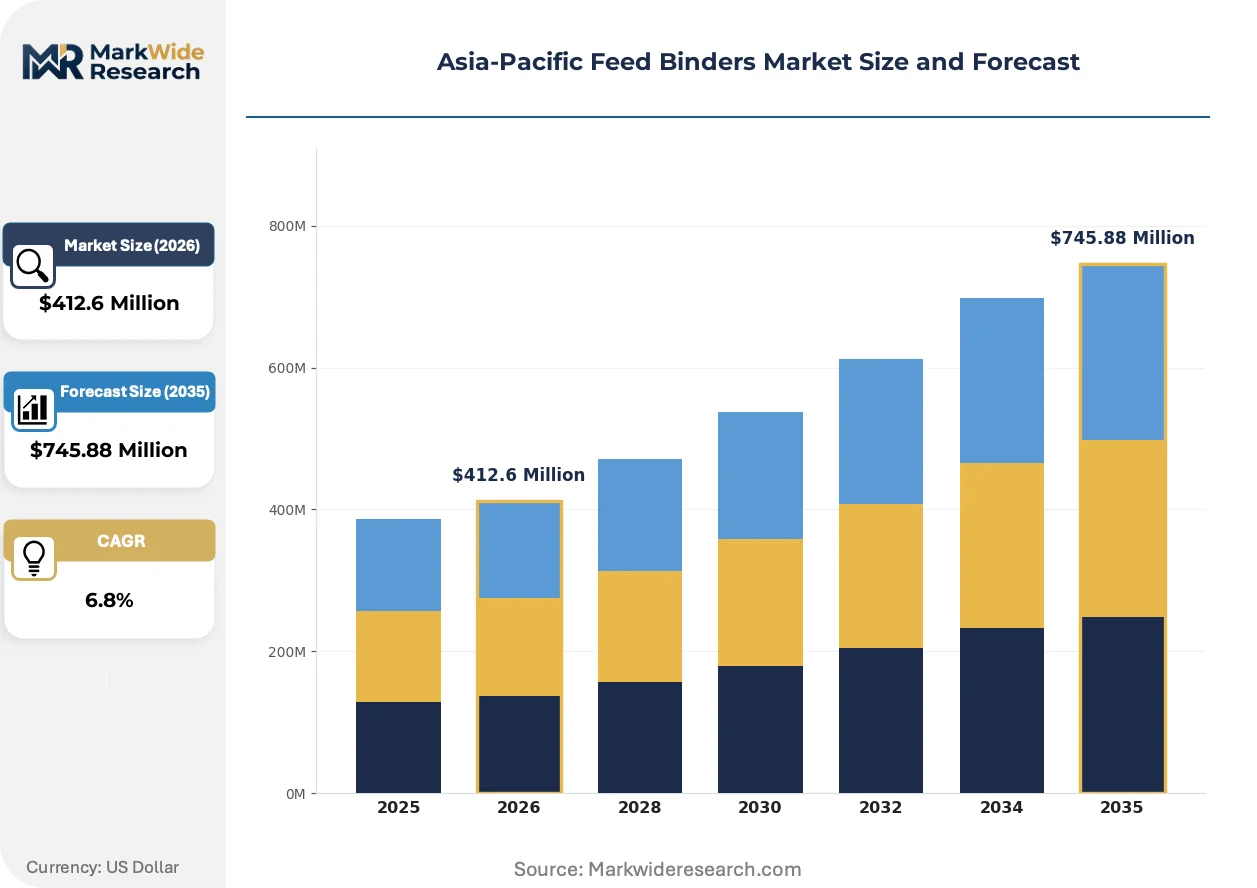
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Powders, Granules, Liquids Source: Plant-Based, Animal-Based, Synthetic, Mineral-Based Application: Poultry, Swine, Ruminants, Aquaculture Delivery Mode: Direct, Bulk, Packaged, Others |
| Companies Covered | Archer Daniels Midland Company, Cargill Inc., DuPont de Nemours and Company, Kemin Industries, Inc., Alltech, FMC Corporation, Borregaard ASA, Adisseo, Gelita AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Binders Market Strategic Shifts
Digital formulation tools and precision dosing systems are compressing the traditional trial-and-error cycle for binder optimization, while regulatory pressure on chemical inputs accelerates bio-based alternative development across the region.
Enzymatic modification of lignosulfonate structures is virtualizing the performance gap between plant-derived and synthetic aquaculture binders. Vietnamese shrimp feed producers are adopting these enhanced natural formulations at pace as water stability testing protocols standardize. The technology is virtualizing premium pricing structures that previously reserved synthetic polymers for high-value marine species applications.
China's Ministry of Agriculture and Rural Affairs is tightening contaminant limits and traceability requirements for feed additives entering the national supply chain. Industrial consequence includes extended product registration timelines and reformulation costs for suppliers lacking pre-established regulatory dossiers. Aquaculture binder categories face the most acute compliance pressure as shrimp and marine fish exports require documentation meeting import market standards.
Buyer consolidation among integrated aquaculture operators in Indonesia and Vietnam is compressing traditional distributor margins and favoring suppliers with direct technical service capabilities. Regional compound feed manufacturers are consolidating procurement functions and centralizing supplier qualification, displacing fragmented local distributor relationships. This pattern is most visible in East Java and the Mekong Delta where large-scale shrimp farming cooperatives now negotiate binder supply directly with manufacturers.
Asia-Pacific Feed Binders Market Segmentation
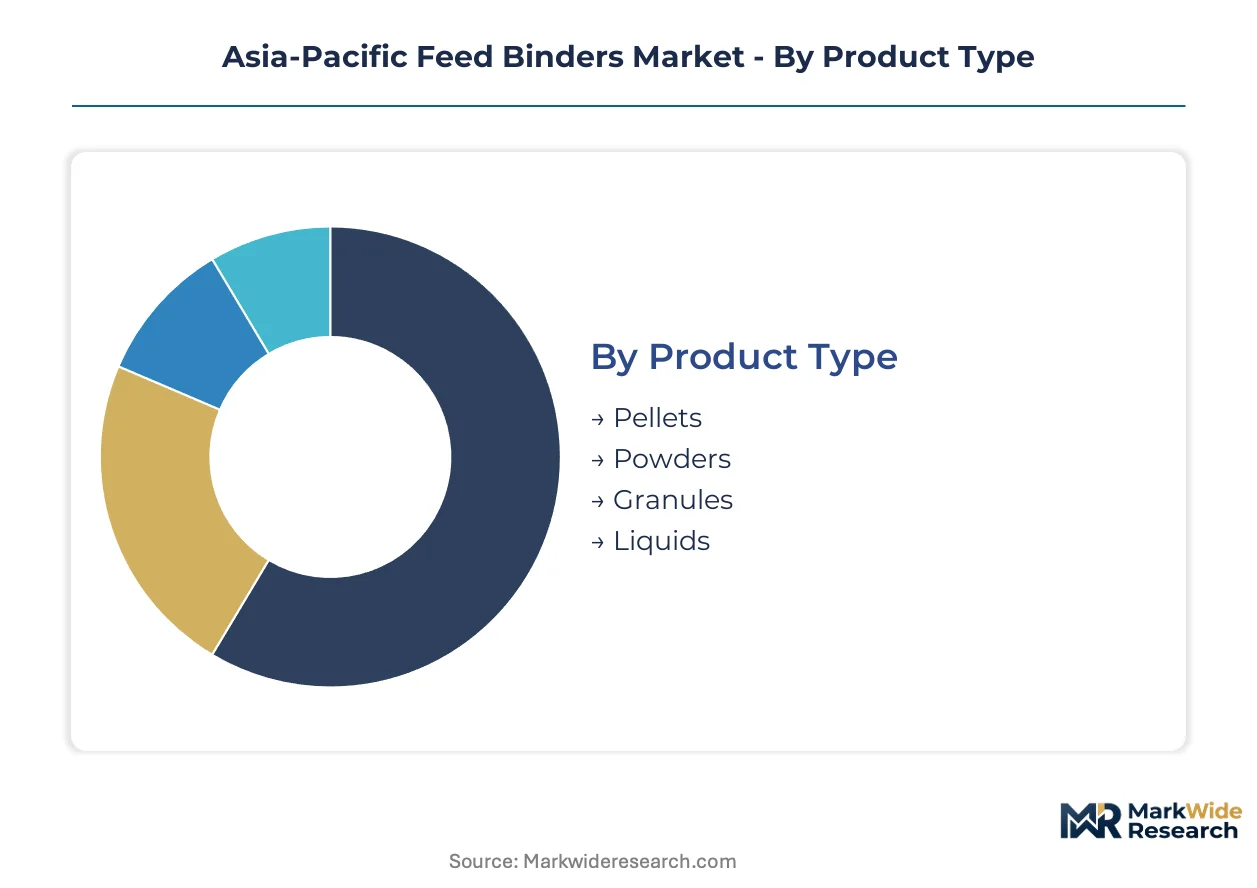
Feed binder segmentation in Asia-Pacific reflects divergent technical requirements across livestock systems. Pellet durability demands, water stability thresholds, and regulatory compliance burdens vary sharply between aquaculture operations and terrestrial animal production, forcing suppliers to maintain formulation flexibility across multiple specification tiers.
Product Type:
Mature pelleting infrastructure dominates volume, though emerging extrusion technologies are reshaping performance requirements across coastal manufacturing clusters.
- Pellets:Cylindrical compressed feed forms requiring elevated binder inclusion rates to withstand mechanical handling and transport stress. Demand concentrates in Guangdong and Fujian province feed mills serving intensive shrimp operations where extruded pellet water stability determines commercial acceptance.
- Powders:Finely ground feed matrices with lower binder thresholds, prevalent in backyard poultry systems and smallholder swine operations across Vietnam's Mekong Delta. FSSAI registration requirements are accelerating formalization of previously informal powder binder supply channels in India.
- Granules:Intermediate particle size formats balancing flowability with binding efficiency, adopted by midscale Indonesian poultry integrators seeking equipment compatibility without full pelleting capital investment.
- Liquids:Suspension or solution binders applied via spray systems in specialized aquaculture feed lines, commanding premium positioning in marine fish diet production where precise dosing accuracy outweighs cost sensitivity.
Pellets retain volume leadership; liquids hold the steepest expansion curve as high-performance aquaculture feed diffusion accelerates.
Source:
Cost tier stratification separates commodity plant derivatives from performance-optimized synthetic formulations, with regulatory pressure compressing the middle tier.
- Plant-Based:Wheat gluten, guar gum, and starch derivatives constitute the accessible volume tier, though monsoon-dependent Indian agricultural output generates feedstock price volatility that squeezes formulation margins for cost-optimized compound feed producers.
- Synthetic:Petrochemical-derived polymers including polyvinyl alcohol and acrylic copolymers deliver superior water stability for premium aquaculture applications. China's MEE carbon intensity targets are intensifying scrutiny of synthetic binder lifecycle emissions, creating reformulation pressure.
- Animal-Based:Gelatin and collagen-derived binders occupy niche positioning in pet food and specialty ruminant applications, constrained by FSSAI and SAMR traceability documentation requirements that extend registration timelines.
- Mineral-Based:Bentonite and sepiolite clay binders serve regional ruminant markets, particularly across Australia's pastoral zones where pellet durability requirements remain modest relative to aquaculture specifications.
Plant-based sources dominate tonnage; synthetic formulations command the highest per-kilogram realization despite regulatory headwinds.
Application:
Customer type fragmentation separates fragmented backyard operations from consolidated industrial integrators, with procurement centralization reshaping supplier access patterns.
- Aquaculture:Shrimp and marine fish feed production generates the most stringent water stability specifications, with Vietnamese and Indonesian operations driving adoption of enhanced natural binders as testing protocols standardize across export-oriented supply chains.
- Poultry:Broiler and layer operations across India and Thailand constitute the volume foundation, though FSSAI directive enforcement is displacing informal binder relationships in favor of registered suppliers with established compliance dossiers.
- Swine:Post-ASF recovery herd rebuilding in China and Vietnam is concentrating demand among large-scale integrators with centralized procurement functions, compressing traditional distributor margins.
- Ruminants:Dairy and beef feed applications favor lignosulfonate and plant-protein binders, with China's dual carbon goals incentivizing lower-emission alternatives to synthetic polymers in this segment.
Poultry maintains the broadest geographic penetration; aquaculture is climbing the fastest as intensive farming displaces traditional extensive systems.
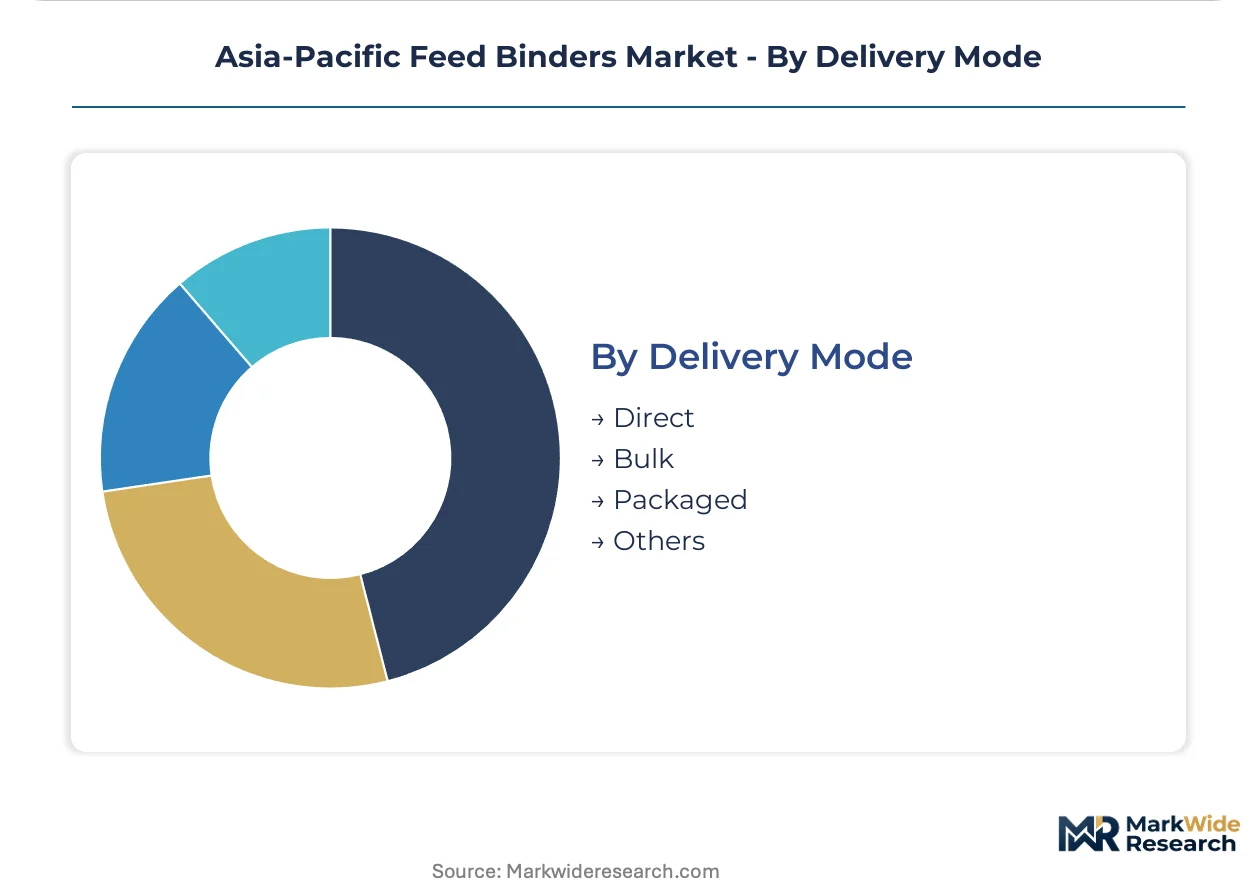
Delivery Mode:
Supply concentration in Thai manufacturing hubs creates channel vulnerability that digital platforms are beginning to circumvent.
- Direct:Manufacturer-to-farm relationships are consolidating among large Vietnamese shrimp cooperatives and Indonesian poultry integrators, enabling technical service integration and margin capture previously absorbed by distributor layers.
- Bulk:Tanker and silo truck delivery dominates high-volume compound feed mill procurement across China's coastal clusters, with Cargill's integrated supply chain controlling critical bulk logistics corridors from Thailand and Indonesia.
- Packaged:25-50kg bag formats serve fragmented midsize operations across the Philippine archipelago and India's tier-two poultry belts, where distributor networks retain relevance despite gradual e-commerce encroachment.
- Others:Containerized intermediate bulk containers and mobile blending units address remote aquaculture sites in Mindanao and Sulawesi where infrastructure gaps prevent conventional delivery modes.
Bulk delivery captures the highest volume throughput; direct channels are gaining share fastest as buyer consolidation proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's coastal manufacturing clusters while Indonesian and Vietnamese buyers absorb transport premiums from Thai production hubs. This asymmetry shapes procurement centralization patterns across Southeast Asian aquaculture belts.
China
Shrimp and marine fish feed production hubs in Guangdong and Fujian provinces generate concentrated demand for high-performance extruded binders. The Ministry of Agriculture and Rural Affairs enforces tightening contaminant limits and traceability requirements that extend product registration timelines. Dalian and Qingdao processing centers are consolidating procurement functions for integrated aquaculture operators serving export markets.
India
Poultry integrators across Haryana and Punjab are formalizing previously informal binder supply relationships under FSSAI directive enforcement. The feed safety authority mandates stricter additive compliance documentation and registration dossiers. Mumbai-Pune industrial corridors are attracting technical service investments from suppliers seeking to anchor western India distribution networks.
Vietnam
Mekong Delta shrimp farming cooperatives are negotiating direct manufacturer relationships, compressing traditional distributor margins. The Ministry of Agriculture and Rural Development aligns with export market documentation standards for aquaculture feed additives. Can Tho and Bac Lieu processing clusters are adopting enhanced natural binder formulations as water stability testing protocols standardize.
Indonesia
East Java poultry integrators and Sulawesi aquaculture operations are driving adoption of higher inclusion-rate binders for advanced extrusion equipment. National feed safety regulations are fragmenting across provincial implementations pending ASEAN harmonization. Surabaya manufacturing zones remain dependent on Thai-sourced bulk deliveries despite infrastructure investments in domestic production capacity.
Thailand
Integrated supply chain operators control critical bulk logistics corridors serving fragmented Indonesian and Vietnamese buyer bases. The Department of Livestock Development enforces additive registration requirements that favor established suppliers with pre-existing dossiers. Bangkok-Rayong industrial zones concentrate regional manufacturing gravity, creating single-source vulnerability for cross-border distribution networks.
Asia-Pacific Feed Binders Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with formulation expertise. The vendor base organizes around three tiers: multinational agribusiness conglomerates with captive supply chains, regional chemical manufacturers with cost-optimized plant-derived portfolios, and niche technology licensors with enzymatic or yeast-derived specializations. Consolidation pressures favor players with established regulatory dossiers across multiple jurisdictions. Competitive moves center on backward integration into feedstock sourcing and technical service deployment for aquaculture application support.
Among multinational agribusiness operators, Cargill Inc. and Archer Daniels Midland Company exemplify platform-scale positioning with integrated logistics control. Borregaard ASA represents the specialty chemical archetype with lignin-based formulation expertise. These anchors illustrate how geographic production gravity and regulatory dossier depth determine scalable cross-border access.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Inc. |
| DuPont de Nemours and Company |
| Kemin Industries, Inc. |
| Alltech |
| FMC Corporation |
| Borregaard ASA |
| Adisseo |
| Gelita AG |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Thai lignosulfonate production facilities is compressing spot pricing for standard-grade binders while tightening margins for regional compound feed manufacturers dependent on imported formulations. This utilization imbalance concentrates pricing power among integrated suppliers with captive Thai manufacturing assets, forcing smaller distributors to absorb transport premiums or cede share to direct-channel competitors.
Pricing Analysis
Configured-to-order pricing for enzymatically modified lignin binders commands spreads exceeding standard guar gum derivatives by factors tied to water stability certification tiers. Three-tier pricing structure across premium aquaculture-certified, standard livestock-grade, and economy powder formats stratifies the market, with FSSAI registration costs accelerating formalization of previously informal economy channels. Pricing pressure stems from guar gum feedstock volatility linked to Indian monsoon patterns, squeezing formulation margins for cost-optimized producers. Backyard poultry operations across Vietnam's Mekong Delta exhibit highest price sensitivity, while export-oriented shrimp cooperatives prioritize performance over unit cost.
Supply Chain Analysis
Export-control scrutiny on synthetic polymer precursor chemicals limits cross-border flows of petrochemical-derived aquaculture binders into Vietnamese processing clusters. Manufacturing gravity centers on Thailand, Indonesia, and coastal China, with Bangkok-Rayong industrial zones controlling critical bulk logistics corridors. Raw material dependencies include Indian guar gum harvests, Nordic lignin sulfonate shipments, and acrylic copolymer feedstocks from South Korean petrochemical complexes. Single-source vulnerability runs through Thai manufacturing concentration, where infrastructure gaps prevent rapid supplier switching for Indonesian buyers. Distribution runs through integrated agribusiness platforms for large integrators, while fragmented midsize operations retain packaged-goods distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for extrusion equipment calibration and water stability testing are expanding faster than commodity binder tonnage, creating recurring revenue layers that outperform hardware margins. This service-attach dynamic rewards suppliers with field engineering capabilities over pure manufacturing plays.
For Market Incumbents: Entrench regulatory dossier advantages across ASEAN jurisdictions before harmonization protocols flatten compliance barriers. Deepen backward integration into Indian guar gum sourcing to hedge monsoon-driven feedstock volatility. Cargill-scale integrated logistics networks represent the primary defensive moat against emerging direct-channel competitors targeting Vietnamese shrimp cooperatives. For New Entrants and Emerging Players: Establish a beachhead in Philippine aquaculture feed markets where archipelago geography has delayed intensive binder adoption and technical service presence remains sparse. Mindanao shrimp farming clusters and Visayas marine fish operations offer first-mover positioning with minimal incumbent field support infrastructure. Partner with mobile-enabled ordering platforms to bypass entrenched distributor layers serving fragmented midsize operations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic lignin modification sub-segments as process standardization reduces equipment scale requirements. Five-to-ten-year viability favors suppliers with dual capabilities across plant-derived and synthetic binder portfolios, hedging regulatory shifts in China's MEE carbon intensity frameworks. Monitor FSSAI enforcement intensity as the signal indicating formalization velocity for India's previously informal binder supply channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Sourcing | Captive Indian guar gum supply hedges monsoon volatility squeezing formulation margins. |
| Technical Service Network Deployment | Field engineering presence in Mekong Delta shrimp clusters captures calibration-contract recurring revenue. |
| Enzymatic Lignin Modification Scale-Up | Enhanced natural formulations bridge performance gaps to synthetic polymers under China's MEE scrutiny. |
| Direct-to-Farm Digital Channel Buildout | Mobile ordering platforms bypass distributor layers for Vietnamese midsize aquaculture operations. |
| ASEAN Regulatory Dossier Harmonization | Cross-border registration alignment reduces redundant compliance investment for multi-country suppliers. |
Study Parameters
A spread of perspectives from compound feed procurement directors, aquaculture farm operations managers, lignin technology R&D leads, and regional distributor principals converged on the working assumptions shaping this analysis. Primary field engagement with Vietnamese shrimp cooperative technical staff and Indonesian poultry integrator supply chain heads combined with secondary validation from FSSAI directive documentation, China's Ministry of Agriculture and Rural Affairs contaminant limit circulars, ASEAN trade flow databases, and customs records for guar gum and lignosulfonate shipments. Bottom-up tonnage estimates from feed mill consumption patterns triangulated against top-down binder inclusion rate assumptions across pelleting and extrusion equipment configurations.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions spanning product type, source category, livestock application, and delivery mode granularity. CAGRs derived from equipment installation trajectories, aquaculture intensification curves, and regulatory compliance cost absorption rates. Key forecast inputs included extrusion technology diffusion patterns in Indonesian processing clusters and FSSAI registration velocity for previously informal powder binder channels.
Sensitivities concentrate around Indian monsoon variability affecting guar gum pricing, ASEAN harmonization timeline shifts, and Chinese carbon intensity target stringency for synthetic polymer alternatives. Forecasts reflect documented assumptions on feedstock cost trajectories and equipment adoption curves. Material shifts in Thai manufacturing capacity utilization or Vietnamese direct-channel penetration rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
Triazole Fungicides Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
Artificial Humus Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Agricultural Surfactants Market