
 Horticulture LED Lighting Market | 2026-2036
Horticulture LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Horticulture LED Lighting Market Intelligence
DLC Premium qualification for horticultural fixtures is collapsing the competitive field as energy-efficiency benchmarks rise. Signify Holding leverages its vertical integration across LED chip and luminaire production to sustain cost advantages in commercial greenhouse deployments. OSRAM GmbH anchors its position through deep spectral research partnerships with European agricultural institutes. Cree LED competes on thermal management architectures that extend fixture lifespan in high-humidity growing environments.
Horticulture LED lighting comprises solid-state luminaires engineered to deliver photosynthetically active radiation in specific wavelength bands, typically spanning 400–700 nm with tunable red-blue ratios and supplemental far-red output, manufactured through chip-on-board assembly and precision phosphor deposition for controlled spectral power distribution. Full-spectrum systems dominate margin pools by commanding premium positioning among research institutions requiring reproducible daylight-mimicking output, while multi-spectrum configurations lead volume growth as indoor farms adopt programmable wavelength switching between vegetative and flowering stages. Quantum dot technology differentiates emerging product lines by enabling narrower full-width-at-half-maximum emission peaks than conventional phosphor-converted alternatives.
EPA Energy Star certification and the EU Ecodesign Directive shape minimum efficacy thresholds that filter subscale manufacturers from transatlantic markets, while China's GB standards for agricultural lighting equipment govern export eligibility from dominant manufacturing bases. The US Department of Agriculture and the Netherlands' national agricultural extension service both publish spectral guidelines that influence procurement specifications for commercial growers. Stakeholders must monitor divergence between regional photosynthetic photon efficacy standards and emerging circadian rhythm research that could redefine optimal spectral recipes for crop-specific applications.
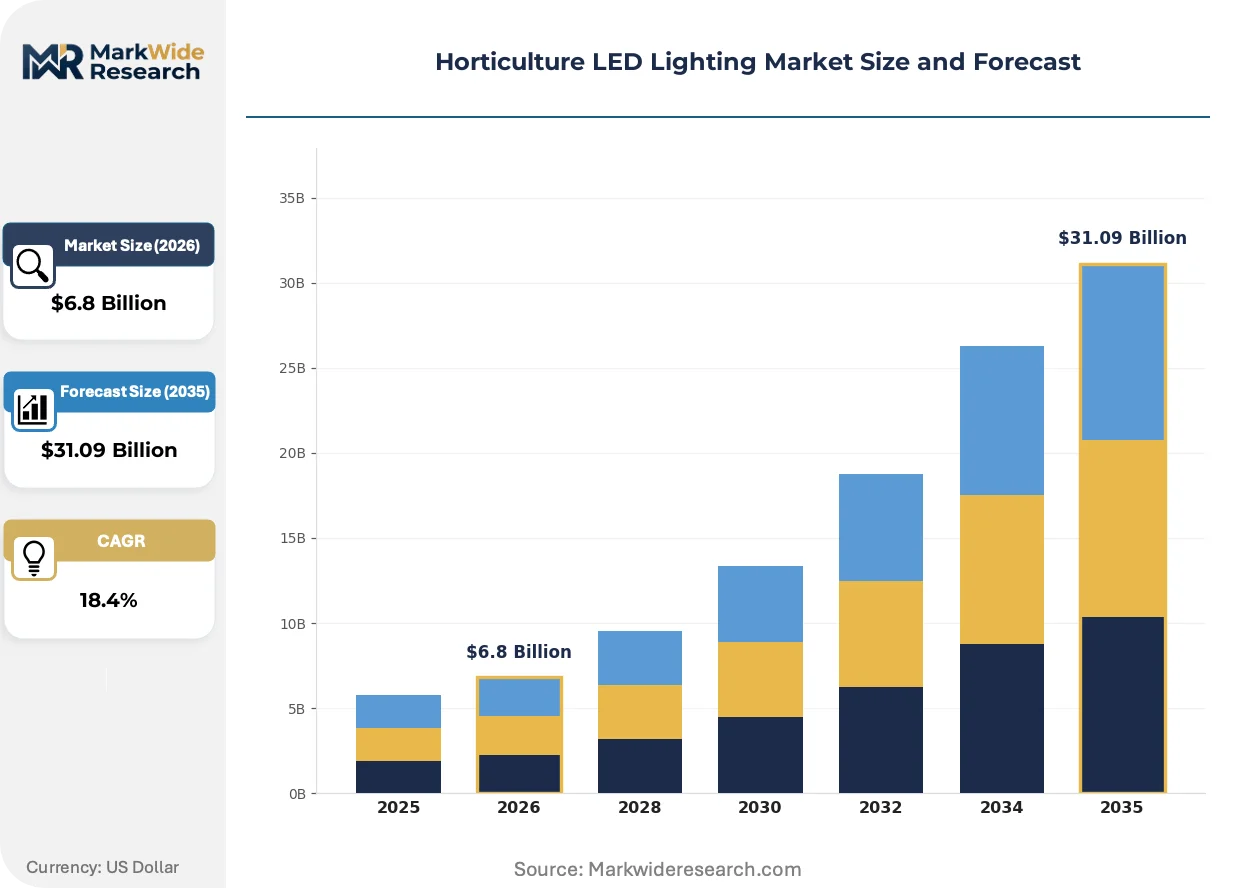
Market Dynamics
The EU F-Gas Regulation's phase-out of legacy high-pressure sodium fixtures is compressing replacement cycles across European greenhouse operations, forcing capital allocation toward solid-state horticultural systems ahead of natural end-of-life schedules.
Growth Catalysts
- EU Green Deal carbon neutrality mandates:Netherlands greenhouse clusters face binding emission reduction targets that disqualify conventional lighting from new installation permits.
- Controlled-environment agriculture expansion:Vertical farming operations in urban peripheries demand programmable spectral output that legacy technologies cannot deliver.
- Quantum dot phosphor deposition:Narrower emission peaks enable crop-specific photon delivery recipes that improve yield per square meter in research-institute trials.
Market Restraints
- Epitaxial wafer supply concentration:Gallium nitride substrate production clusters in East Asian foundries expose fixture manufacturers to input cost volatility and allocation constraints.
- Photosynthetic photon efficacy plateau:Conventional chip-on-board architectures approach theoretical conversion limits without fundamental material science breakthroughs.
- Legacy infrastructure lock-in:Existing greenhouse electrical distribution and thermal management systems require costly retrofitting to support LED load profiles and reduced heat output.
Strategic Opportunities
- US Inflation Reduction Act energy-efficiency credits:Commercial growers qualify for accelerated depreciation on horticultural LED installations that exceed DLC Premium efficacy thresholds.
- Far-red supplementation protocols:Emerging photomorphogenic research creates demand for tunable 700-800 nm output in pharmaceutical crop cultivation.
- Direct-to-farm specification channels:Bypassing traditional electrical distributors through agricultural extension partnerships captures margin and installation scheduling control.
Industry Challenges
- Spectral recipe IP fragmentation:Proprietary light protocols developed by seed companies and agricultural universities create licensing complexity for fixture manufacturers seeking crop-optimized presets.
- Certification timeline compression:DLC Premium qualification cycles and EPA Energy Star testing protocols delay product launches as efficacy benchmarks rise mid-development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horticulture LED Lighting Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Végétatif, Floraison, Multi-Spectrum, Full-Spectrum Technology: Quantum Dot, Hybrid, Conventional, Smart Lighting End User: Commercial Growers, Research Institutions, Indoor Farms, Home Gardeners Application: Aquaponics, Hydroponics, Vertical Farming, Greenhouses |
| Companies Covered | Signify Holding, OSRAM GmbH, Cree LED, Heliospectra AB, Gavita International B.V., Hortilux Schreder, Bridgelux Inc., California LightWorks, Fluence Bioengineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horticulture LED Lighting Market Strategic Shifts & Innovations
Photobiology research is rewriting procurement specifications as growers abandon one-size-fits-all illumination in favor of stage-specific spectral programming. Three developments are compressing competitive timelines.
Quantum dot technology is decomposing the traditional phosphor-converted white LED architecture in premium horticultural fixtures. Research institutions with reproducibility requirements are adopting narrow full-width-at-half-maximum emitters for daylight-mimicking output. This spectral precision is compressing margin pools for conventional chip-on-board manufacturers that cannot match emission peak control.
REACH substance restrictions on heavy-metal phosphors are forcing reformulation of horticultural LED conversion layers across European supply chains. Manufacturers must qualify alternative rare-earth dopants without degrading photosynthetic photon efficacy metrics. Greenhouse operators in the Netherlands and Belgium are prioritizing RoHS-compliant fixtures in public-tender specifications ahead of formal mandate deadlines.
Buyer specification authority is migrating from electrical contractors to crop scientists and agricultural extension specialists. University research partnerships now precede commercial greenhouse procurement decisions, displacing distributor-led sales processes. This expertise-driven channel shift is most visible in North American cannabis cultivation and European tomato propagation operations.
Horticulture LED Lighting Market Segmentation
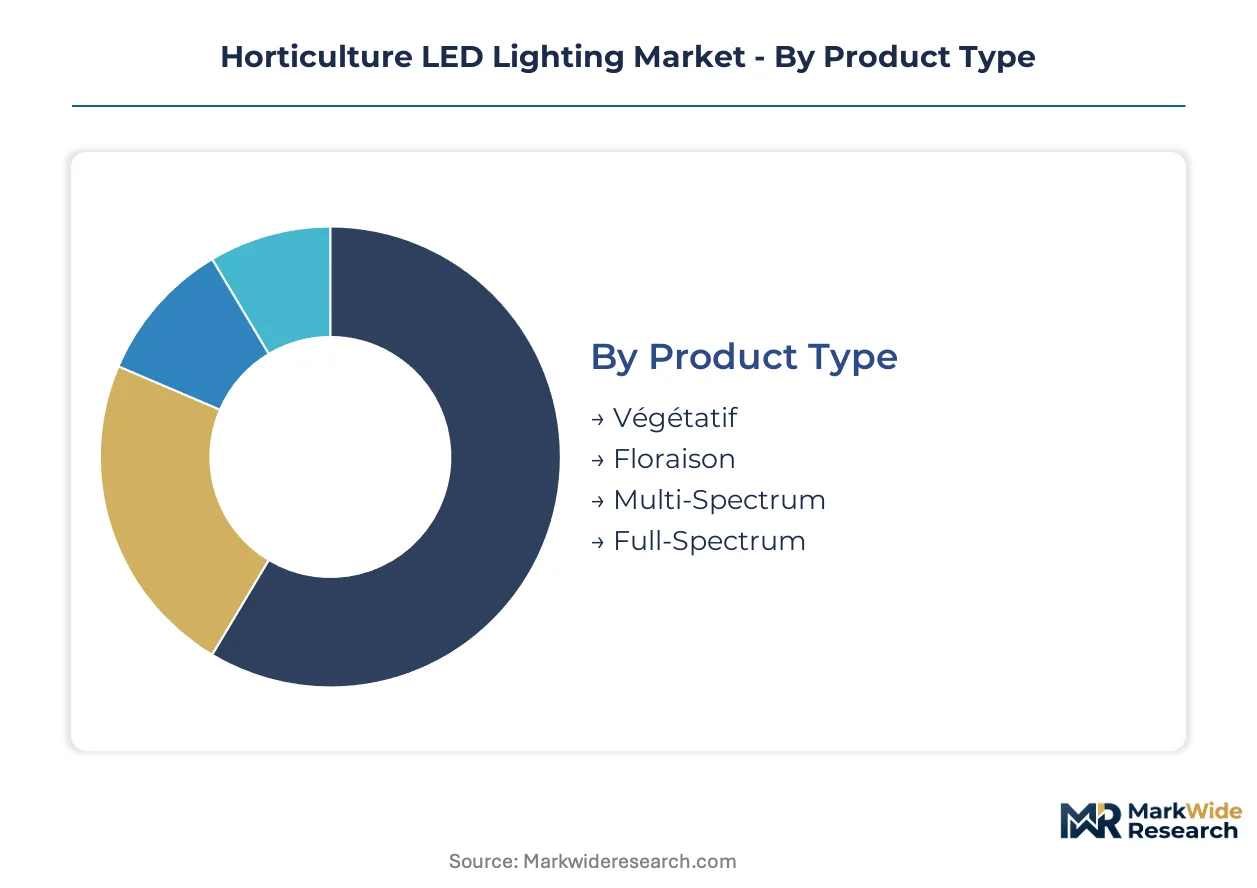
Segmentation in horticulture LED lighting reveals how spectral engineering, installation environment, and buyer sophistication create distinct margin architectures. Procurement authority varies sharply across these divides, with research institutions demanding reproducible output specifications while commercial growers prioritize programmable intensity cycles.
Product Type:
Substitution pressure from legacy high-pressure sodium systems falls unevenly across spectral configurations, with single-purpose fixtures facing steeper displacement risk than tunable alternatives.
- Full-Spectrum:Engineered to replicate natural daylight across 400-700 nm with balanced red-blue ratios and minimal spectral gaps. Research institutions in the Netherlands and Belgium specify these systems for reproducible photobiology trials requiring consistent daily light integral measurements. Premium positioning sustains margins despite higher unit costs.
- Multi-Spectrum:Programmable platforms enabling wavelength switching between vegetative and reproductive growth stages through independent channel control. Vertical farming operations in urban peripheries drive specification requirements for stage-specific photon delivery that legacy technologies cannot match.
- Végétatif:Blue-weighted output optimized for leafy green production and root development phases.
- Floraison:Red-dominant spectral profiles targeting flowering and fruiting crop stages.
Multi-spectrum configurations retain volume leadership; full-spectrum systems hold the steepest expansion curve in institutional procurement channels.
Technology:
Cost tier stratification separates premium emitters from commodity chip-on-board assemblies, with efficacy thresholds determining qualification for utility rebate programs.
- Quantum Dot:Nanocrystal phosphors achieving narrower full-width-at-half-maximum emission peaks than conventional rare-earth alternatives. Research greenhouses in Denmark and Sweden adopt these emitters for crop-specific photon recipes that improve yield per square meter in controlled trials.
- Smart Lighting:Sensor-integrated platforms with automated dimming, spectral tuning, and environmental feedback loops. Commercial greenhouse operators in Spain deploy these systems to synchronize artificial photoperiods with natural daylight fluctuations.
- Hybrid:Combines quantum dot emitters with conventional phosphor-converted architectures for cost-optimized spectral flexibility.
- Conventional:Chip-on-board assemblies using standard phosphor deposition techniques, facing margin compression from efficacy plateau constraints.
Conventional technology retains volume leadership; quantum dot platforms represent the fastest-growing trajectory as narrow-band emitters penetrate premium installations.
End User:
Customer type determines specification complexity, with institutional buyers demanding spectral validation documentation that home gardeners disregard.
- Commercial Growers:Large-scale greenhouse and warehouse operations requiring DLC Premium-qualified fixtures for utility incentive eligibility. Tomato and cucumber propagation facilities in the Netherlands specify multi-channel systems with far-red supplementation capabilities.
- Indoor Farms:Controlled-environment agriculture operations in repurposed industrial buildings prioritizing vertical rack integration and reduced thermal load. These buyers favor low-profile fixtures with passive cooling architectures.
- Research Institutions:Universities and agricultural extension services requiring calibrated spectral output for reproducible photobiology studies.
- Home Gardeners:Residential hobbyists purchasing through e-commerce channels with minimal technical specification requirements.
Commercial growers retain volume leadership; indoor farms gain share fastest as urban periphery development accelerates.
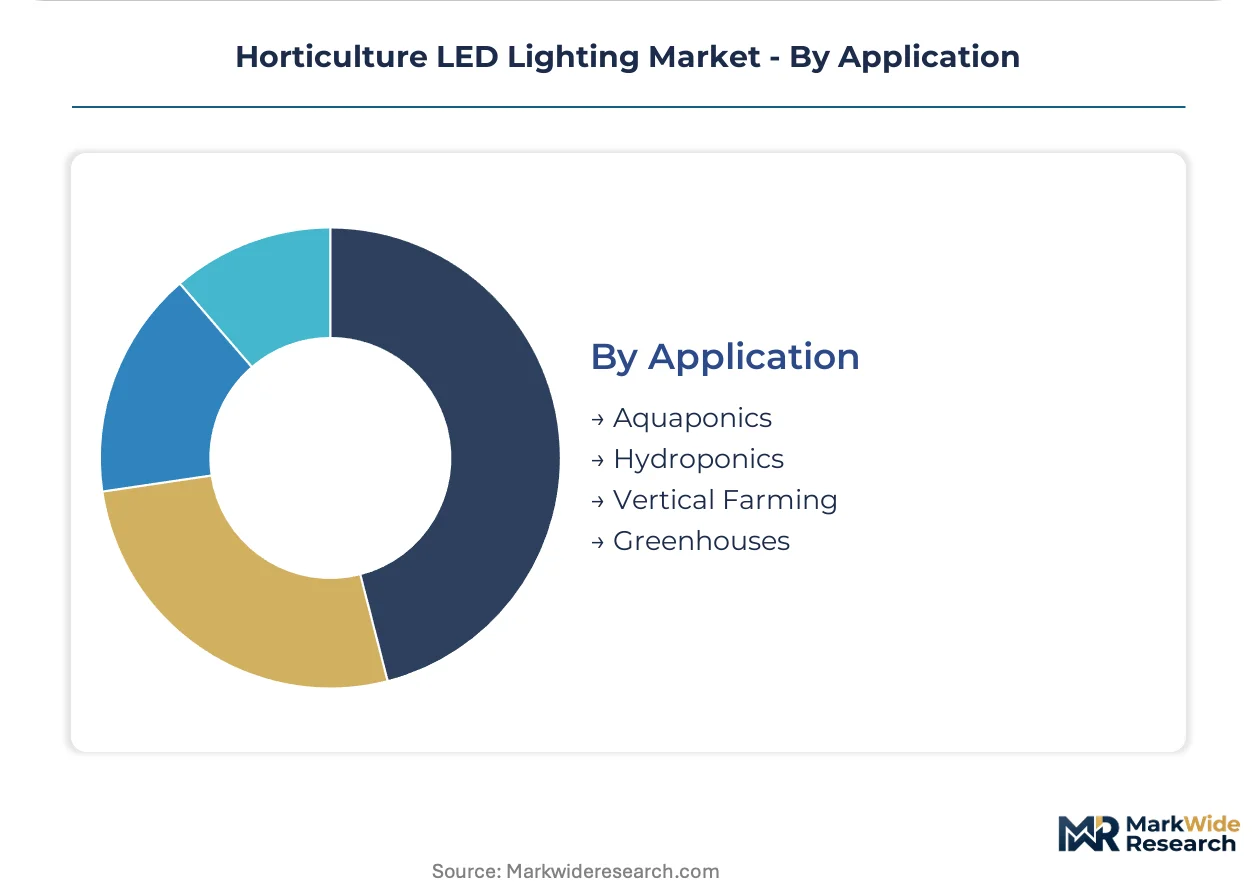
Application:
Installation environment dictates thermal management and moisture ingress protection requirements, with aqueous growing systems demanding specialized housing ratings.
- Greenhouses:Supplemental lighting installations in glass or polycarbonate structures requiring compatibility with existing climate control infrastructure. Dutch greenhouse clusters drive specification standards for full-spectrum systems that integrate with automated shading mechanisms.
- Vertical Farming:Multi-tier racked systems in climate-controlled warehouses where artificial light constitutes the sole photosynthetic energy source. These installations prioritize programmable spectral output and reduced fixture height to maximize cultivation density.
- Hydroponics:Soil-less cultivation systems using nutrient film technique or deep water culture requiring IP-rated fixtures for high-humidity environments.
- Aquaponics:Integrated fish-and-plant systems where lighting must accommodate both aquatic ecosystem stability and crop photon requirements.
Greenhouse applications retain volume leadership; vertical farming climbs the fastest as urban food production expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Dutch dominance in perishable horticulture exports, creating concentrated demand for precision lighting systems across the surrounding greenhouse belt.
Netherlands
Westland and Aalsmeer greenhouse clusters drive specification requirements for full-spectrum systems with far-red supplementation capabilities. The EU F-Gas Regulation accelerates replacement cycles for legacy high-pressure sodium installations ahead of 2025 phase-out deadlines. Wageningen University research partnerships now precede commercial procurement decisions for tomato propagation facilities.
United States
Vertical farming operations in Chicago and New York City peripheries demand programmable multi-spectrum platforms for leafy green production. The Inflation Reduction Act energy-efficiency credits accelerate depreciation schedules for DLC Premium-qualified fixtures exceeding efficacy thresholds. California's Central Valley cannabis cultivation facilities prioritize spectral validation documentation from agricultural extension services.
Germany
Bavarian research greenhouses and Baden-Württemberg controlled-environment agriculture startups specify quantum dot emitters for narrow-band photon delivery experiments. REACH substance restrictions on heavy-metal phosphors force reformulation of conversion layers across European supply chains. Munich-based agricultural institutes publish spectral guidelines that influence procurement specifications for commercial growers.
China
Yangtze River Delta manufacturing bases supply chip-on-board assemblies to fixture producers worldwide under GB standards for agricultural lighting equipment. Dual carbon goals drive domestic greenhouse retrofit programs in Shandong Peninsula vegetable production zones. Shenzhen and Hangzhou vertical farming ventures adopt smart lighting platforms with automated dimming and environmental feedback loops.
United Kingdom
Greater London peri-urban indoor farms prioritize low-profile fixtures with passive cooling architectures for vertical rack integration. The Department for Environment, Food and Rural Affairs consults on minimum efficacy thresholds aligned with EU Ecodesign Directive benchmarks. Cambridge agricultural research clusters specify calibrated spectral output for reproducible photobiology studies.
Horticulture LED Lighting Market Key Industry Players
Listed leaders compete with private specialists across capital access and R&D scale, creating a tiered structure where public companies sustain multi-year spectral research programs while private operators capture niche installation contracts. The vendor base separates into three archetypes: vertically integrated luminaire manufacturers, component specialists focused on chip-on-board assemblies, and systems integrators bundling lighting with climate control infrastructure. Dominant competitive moves include strategic partnerships with agricultural research institutes and capacity expansion in East Asian epitaxial wafer supply chains.
Among Dutch- and German-based lighting incumbents, Signify Holding, OSRAM GmbH, and Cree LED occupy positions spanning the full value chain from LED chip production through fixture assembly. Signify exemplifies the vertically integrated archetype through captive supply of core components. OSRAM represents the research-intensive tier with institutional partnerships driving spectral protocol development. Cree LED anchors the thermal engineering specialist segment, with company nomenclature indicating focus on emitter performance in demanding environmental conditions.
| Leading Market Players |
|---|
| Signify Holding |
| OSRAM GmbH |
| Cree LED |
| Heliospectra AB |
| Gavita International B.V. |
| Hortilux Schreder |
| Bridgelux Inc. |
| California LightWorks |
| Fluence Bioengineering |
| Others |
Cost & Logistics Intelligence
Sixteen-to-twenty-week lead times for gallium nitride epitaxial wafers compress pricing power at the fixture level, as East Asian foundry allocation constraints force manufacturers to absorb input volatility or pass through costs to greenhouse operators already facing F-Gas Regulation compliance deadlines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates DLC Premium-qualified fixtures with far-red supplementation from mid-tier multi-spectrum systems and entry-level chip-on-board assemblies. Price differentiation centers on certification grade and volume scale, with Dutch greenhouse clusters negotiating aggregate procurement discounts exceeding standard distributor margins. Cost compression in the economy tier is intensifying because REACH substance restrictions on heavy-metal phosphors force reformulation expenses. Home gardeners exhibit highest price sensitivity, while research institutions prioritize spectral validation documentation over unit cost.
Supply Chain Analysis
Inventory buffers for quantum dot phosphors rarely exceed thirty days as rare-earth dopant availability fluctuates with mining output from China and processing capacity in Germany. Gallium nitride substrate production clusters in Taiwan, South Korea, and China, while precision phosphor deposition equipment draws from Japanese and Dutch suppliers. Single-source vulnerability concentrates in epitaxial wafer supply, where three foundries control qualification pathways for horticultural-grade emitters. Distribution runs through agricultural extension partnerships and electrical distributors serving greenhouse clusters, with direct-to-farm channels gaining specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The horticulture LED lighting market is exiting a capital expenditure trough as EU Green Deal carbon neutrality mandates force replacement cycles ahead of natural end-of-life schedules.
For Market Incumbents: Secure captive supply of gallium nitride substrates through long-term offtake agreements with East Asian foundries, insulating margin structures from allocation volatility. Deepen spectral research partnerships with Wageningen University and comparable agricultural institutes to embed proprietary light protocols into fixture presets, creating switching costs against emerging competitors. For New Entrants and Emerging Players: Anchor in North American cannabis cultivation facilities where agricultural extension validation requirements remain fragmented and specification authority has not yet consolidated around incumbent research partnerships. Target vertical farming operations in secondary US metropolitan peripheries lacking established distributor relationships, deploying SaaS-integrated lighting platforms with automated environmental feedback as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming horticultural lighting divisions lacking dedicated agricultural channel infrastructure. The five-to-ten-year viability window favors platforms with quantum dot emitter integration and software-defined spectral programming capabilities. Monitor DLC Premium qualification timelines as the inflection indicator—compression in certification cycles signals intensifying competitive pressure and margin compression ahead.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Supply | Captive gallium nitride sourcing from Taiwanese foundries insulates margin structures from allocation volatility. |
| Quantum Dot Phosphor Deposition Scale-Up | Narrow-band emitter manufacturing in Germany satisfies REACH compliance while capturing premium research-institution demand. |
| Agricultural Extension Partnership Expansion | Direct specification channels with Wageningen University and USDA extension services displace distributor-led sales processes. |
| Smart Lighting Platform Integration | Sensor-integrated systems with automated dimming synchronize artificial photoperiods with natural daylight fluctuations in Spanish greenhouses. |
| Far-Red Supplementation Protocol Development | Tunable 700-800 nm output capabilities address emerging photomorphogenic research in pharmaceutical crop cultivation. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial greenhouse operators, vertical farm facility managers, agricultural extension specialists, and LED fixture procurement leads at research institutions. Secondary validation drew from EU Ecodesign Directive filings, EPA Energy Star certification databases, DLC Premium qualification records, and SEC 10-K disclosures from listed lighting manufacturers. Bottom-up demand modeling triangulated against top-down market sizing across spectral configuration, technology tier, and installation environment dimensions.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmented projections by product type, end-user sophistication, application environment, and regional regulatory cluster. CAGRs were derived from regression analysis of historical replacement cycles, policy mandate timelines, and controlled-environment agriculture expansion rates. Industry-specific inputs included photosynthetic photon efficacy trajectories, F-Gas Regulation phase-out schedules, and utility incentive program qualification thresholds.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable gallium nitride substrate availability; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Technologies
Broadacre Cropping Software Market
Agricultural Technologies
Post Harvesting Technologies Market
Agricultural Technologies
Global Agriculture Supply Chain Management Market
Agricultural Technologies
Global Food and Agriculture Technology and Products Market
Agricultural Technologies
Plant Phenotyping Market
Agricultural Technologies
Europe Agricultural Enzymes Market
Agricultural Technologies
Global Greenhouse Soil Market
Agricultural Technologies
Farming As a Service Market
Agricultural Technologies
Agricultural Drones Market
Agricultural Technologies
Agriculture Machine to Machine (M2M) Market