
 Global Agricultural Chelates Market | 2026-2036
Global Agricultural Chelates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Chelates Market Foresight
Specialty fertilizer distribution is rewriting procurement patterns across agricultural input channels. BASF SE leverages its integrated chelate production network to secure supply continuity for European distributors. Yara International ASA anchors its position through direct farm advisory programs that bundle chelated micronutrients with precision application protocols. Nouryon competes on manufacturing scale, operating dedicated EDTA and EDDHA facilities that serve multiple continental markets.
Agricultural chelates are coordination complexes formed between metal ions and organic ligands such as EDTA, DTPA, or EDDHA, designed to maintain nutrient bioavailability across varying soil pH conditions. These compounds prevent micronutrient precipitation in alkaline or calcareous soils, ensuring iron, zinc, manganese, and copper reach plant root systems in plant-available forms. EDTA Chelates occupy the largest volume position due to broad-spectrum compatibility and established manufacturing infrastructure, though EDDHA Chelates command premium positioning for iron-deficiency correction in high-pH soils where EDTA complexes degrade. Organic Chelates represent the fastest-expanding category as certified organic operations and regenerative agriculture programs restrict synthetic ligand use.
The EPA governs chelated micronutrient registration and labeling requirements for products entering US agricultural channels, while REACH mandates full toxicological dossiers for ligand substances sold across EU member states. Brazil's national agricultural regulator enforces maximum residue limits that influence chelate formulation choices for export-oriented crop production. Stakeholders must monitor evolving ligand restriction proposals in multiple jurisdictions that could disqualify certain synthetic chelators from approved input lists.
Market Dynamics
Soil alkalinity intensification across intensive cultivation zones is forcing chelate specification upgrades, as EDTA complexes degrade in calcareous conditions where EDDHA and HBED ligands maintain iron bioavailability. This pH-driven performance gap is restructuring procurement priorities among specialty crop operations.
Growth Catalysts
- EU Fertilizing Products Regulation:Purity standard tightening for chelated micronutrients sold across member states is accelerating product registration investments by established suppliers.
- Brazil's Cerrado soybean belt:Large-scale iron and zinc correction programs on converted savanna soils generate concentrated demand for high-stability chelate formulations.
- Micro-irrigation compatibility:Drip and fertigation system expansion requires chelates with low phytotoxicity and complete solubility, favoring advanced ligand chemistries.
Market Restraints
- EDTA biodegradability limitations:Persistence in aquatic ecosystems triggers regulatory scrutiny under REACH dossier requirements, constraining formulation flexibility in EU markets.
- Phosphoric acid price volatility:Input cost swings for phosphorus-based intermediates compress margin stability for integrated chelate manufacturers.
- Synthetic amino acid supply concentration:EDDHA precursor production clusters in select chemical manufacturing regions, exposing buyers to single-source disruption risk.
Strategic Opportunities
- India's horticulture intensification:Protected cultivation expansion in Maharashtra and Karnataka creates underpenetrated demand for iron-chelate programs in high-pH alluvial soils.
- Biostimulant-chelate bundling:Regulatory convergence between fertilizer and biostimulant categories in Brazil enables novel product positioning for combined micronutrient-biological inputs.
- Organic certification pathways:USDA Organic and EU Organic acceptance of natural amino acid chelates opens premium positioning for lignosulfonate and protein-based alternatives.
Industry Challenges
- Analytical method standardization:Inconsistent chelate stability testing protocols across national laboratories delay product registration timelines and increase compliance costs.
- Formulation-legacy system integration:Compatibility validation with existing tank-mix adjuvants and pesticide programs requires extensive field testing, slowing new product adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Chelates Market |
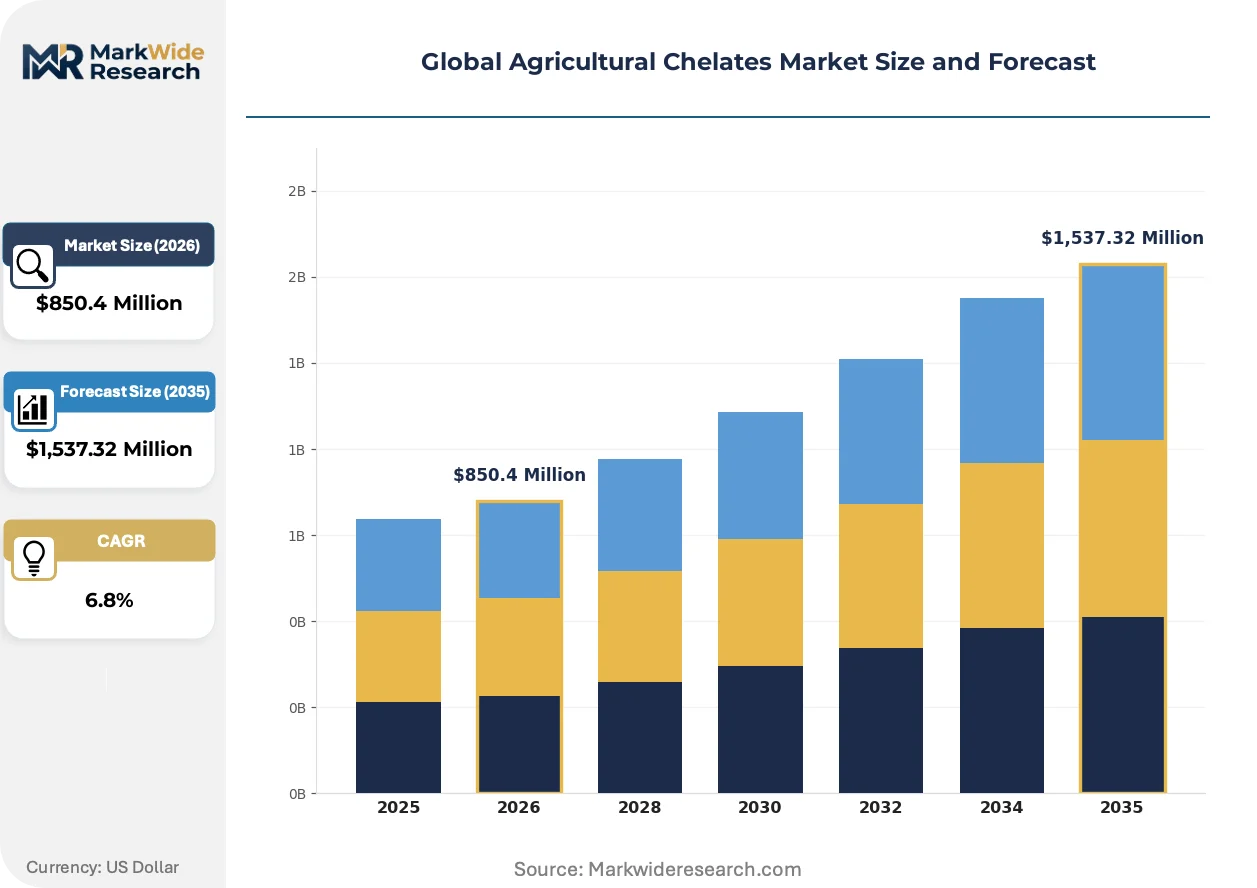
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,537.32 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EDTA Chelates, DTPA Chelates, EDDHA Chelates, Organic Chelates, Iron Chelates Mode of Application: Foliar Spray, Soil Treatment, Fertigation, Seed Treatment Crop Type: Cereals, Horticulture, Pulses, Oilseeds, Commercial Crops End Use: Farmers, Agricultural Cooperatives, Agrochemical Companies, Landscape Companies |
| Companies Covered | Yara International ASA, ICL, Nouryon, Dow, The Andersons, BASF SE, Haifa Group, Nufarm Ltd., Syngenta Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Chelates Market Shifts & Advancements
Digitization of soil-crop nutrient mapping is compressing the feedback loop between deficiency diagnosis and chelate prescription, enabling precision application at sub-field scales previously uneconomical for micronutrient interventions.
Sensor-enabled variable-rate application technology is virtualizing traditional broadcast chelate programs. Specialty vegetable operations in California's Central Valley deploy drone-mounted multispectral imaging to identify iron chlorosis patterns in real time, triggering targeted foliar EDDHA applications that reduce total input volumes by half versus prophylactic soil treatments. This virtualization is compressing the addressable market for commodity-grade EDTA products while expanding premium formulation demand.
REACH authorization requirements for EDTA and DTPA substances are tightening toxicological dossier standards across EU member states. Manufacturers must submit enhanced environmental fate data and biodegradation studies to maintain market access, elevating compliance costs for smaller formulators. The specialty crop segment in Spain and Italy responds by consolidating supplier relationships toward dossier-complete multinationals with dedicated regulatory affairs capabilities.
Direct-to-farm digital platforms are disintermediating traditional agricultural distribution channels for chelated micronutrients. Brazilian soybean growers in Mato Grosso now procure EDDHA iron through manufacturer-hosted e-commerce portals bundled with soil analysis services, bypassing cooperative and retail intermediaries. This channel compression is most visible in regions with consolidated farm structures and established precision agriculture infrastructure.
Global Agricultural Chelates Market Segmentation
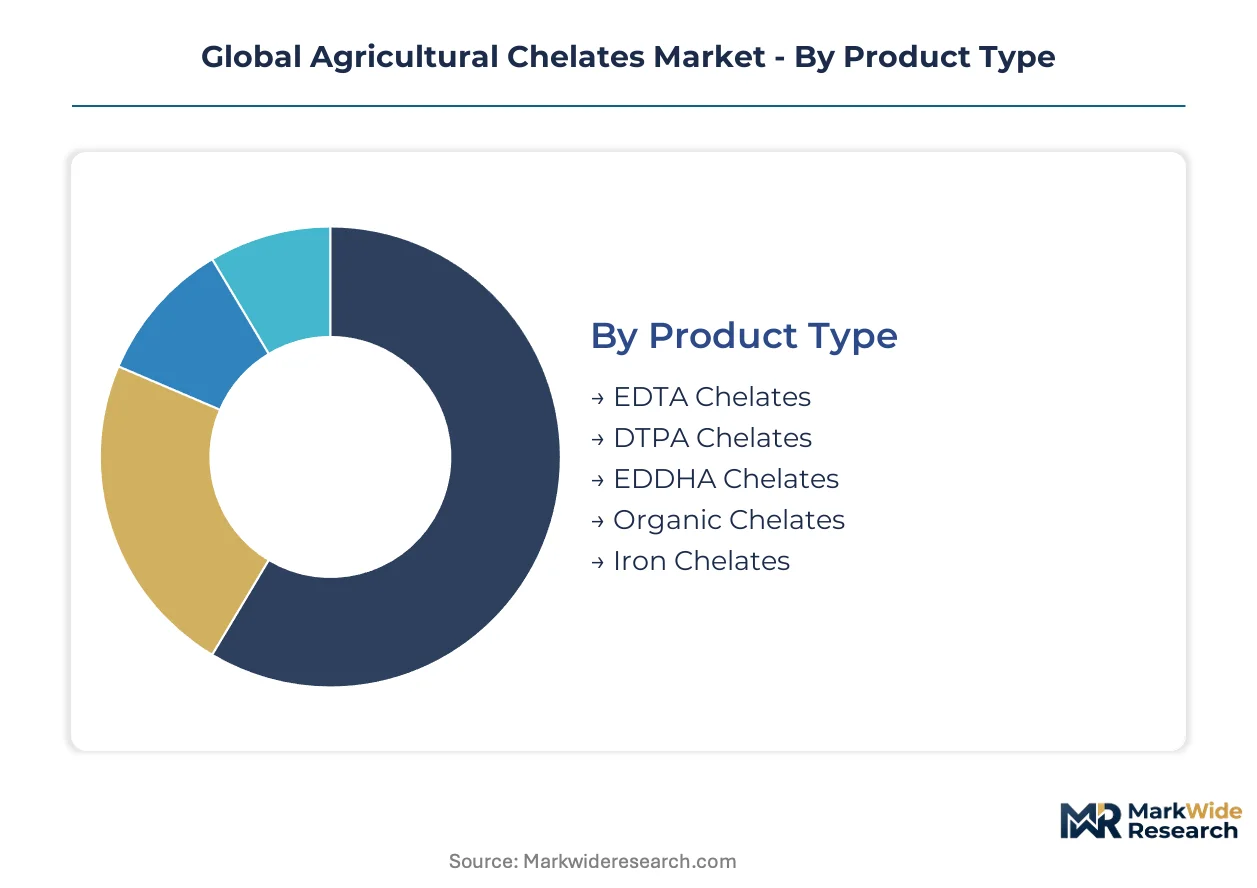
Chelate specification varies sharply across application contexts, soil chemistry, and operational scale. Segmentation reveals where formulation premiums command pricing power versus where commodity-grade products dominate procurement decisions.
Product Type:
Cost tier separation between synthetic ligand systems and emerging natural alternatives is restructuring supplier portfolios and margin structures.
- EDTA Chelates:Polyaminocarboxylic acid complexes formed with iron, zinc, manganese, and copper ions deliver broad-spectrum compatibility across pH ranges. Demand concentrates in Brazil's Mato Grosso soybean belt where large-scale operations prioritize cost efficiency over alkaline soil stability. REACH biodegradability scrutiny constrains formulation flexibility in EU markets.
- EDDHA Chelates:Ortho-ortho isomer configurations provide superior iron stability in calcareous soils above pH 7.5. California specialty vegetable growers and Florida citrus operations drive premium procurement for high-pH correction programs. Ortho-para isomer impurities differentiate quality tiers among competing suppliers.
- DTPA Chelates:Diethylenetriaminepentaacetic acid complexes serve intermediate pH zones where EDTA degrades but EDDHA economics prove prohibitive.
- Organic Chelates:Lignosulfonate and protein-based complexes gain traction in certified organic operations restricted from synthetic ligands.
- Iron Chelates:Dedicated iron-specific formulations address chlorosis correction in high-value horticultural systems.
EDTA Chelates command the established base. The steepest expansion runs through Organic Chelates.
Mode of Application:
Application technology maturity determines where precision delivery systems displace broadcast methods.
- Fertigation:Complete solubility requirements favor advanced ligand chemistries compatible with drip and micro-sprinkler infrastructure. Israel's Netafim-equipped desert agriculture and Spain's Almería greenhouse complexes drive specification intensity for low-phytotoxicity formulations.
- Soil Treatment:Traditional incorporation methods persist in broadacre cereal systems where equipment capital constraints limit precision adoption. Ukraine's black soil region and Australia's wheat belt maintain volume demand for granular and liquid soil-applied products.
- Foliar Spray:Rapid uptake formulations address acute deficiency symptoms in high-value crops.
- Seed Treatment:Emerging category bundling micronutrient priming with biological inoculants.
Soil Treatment retains volume leadership. Fertigation climbs fastest as irrigation infrastructure modernizes.
Crop Type:
Margin sensitivity across crop categories dictates chelate specification tier and application intensity.
- Horticulture:Protected cultivation of tomatoes, peppers, and leafy greens in the Netherlands, Mexico's Sinaloa valley, and China's Shandong province generates concentrated demand for high-purity iron and zinc programs. Visual quality standards and harvest timing pressures justify premium formulation expenditure.
- Cereals:Wheat, rice, and maize operations in India's Punjab and the US Great Plains prioritize cost-minimized micronutrient supplementation. Volume procurement through cooperative channels favors established EDTA formulations with proven field performance.
- Oilseeds:Soybean and canola systems in Argentina's Pampas require intensive iron correction on alkaline virgin soils.
- Pulses:Lentil and chickpea production in Canada's Saskatchewan faces emerging micronutrient deficiency patterns.
- Commercial Crops:Cotton, sugarcane, and tobacco operations balance input costs against quality premiums.
Cereals dominate procurement volume. Horticulture delivers the steepest margin expansion trajectory.
End Use:
Customer scale and technical capability create divergent purchasing behaviors and service requirements.
- Agricultural Cooperatives:Consolidated procurement for member farms in France's Axereal and Germany's BayWa generates volume contracts with specification standardization. Technical advisory services bundled with product supply lock in supplier relationships across growing seasons.
- Agrochemical Companies:Formulation houses in India's Gujarat and China's Jiangsu province source chelate intermediates for proprietary micronutrient blends. Backward integration pressure from multinationals constrains standalone supplier margins.
- Farmers:Direct procurement through digital platforms accelerates in Brazil and the US Midwest.
- Landscape Companies:Turf and ornamental maintenance in Gulf Cooperation Council states drives specialized iron programs for saline irrigation conditions.
Agricultural Cooperatives anchor the existing customer base. Agrochemical Companies expand most quickly as formulation complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium chelate formulations command threefold pricing multiples in California specialty vegetable markets versus commodity-grade procurement in Brazil's broadacre soybean belt. This asymmetry reflects divergent soil chemistry challenges and operational margin structures across cultivation systems.
United States
California's Central Valley specialty crop producers drive concentrated demand for EDDHA iron chelates addressing alkaline soil chlorosis in high-value tomato and lettuce operations. EPA registration requirements govern micronutrient labeling for products entering interstate agricultural commerce. Fresno County processing vegetable clusters and Monterey Bay leafy green districts sustain premium formulation procurement through precision fertigation infrastructure.
Brazil
Mato Grosso's Cerrado soybean belt generates volume demand for cost-optimized EDTA and DTPA iron and zinc correction programs on converted savanna soils. ANVISA enforces maximum residue limits that influence chelate formulation choices for export-oriented crop production. Rondonópolis and Sorriso logistics corridors concentrate input distribution for large-scale mechanized operations exceeding ten thousand hectares.
Germany
Industrial chelate manufacturing clusters in Ludwigshafen and Leverkusen anchor European supply continuity for EDTA and EDDHA ligand production. REACH authorization mandates enhanced toxicological dossiers and biodegradation studies for polyaminocarboxylic acid substances. Bavarian sugar beet cooperatives and Lower Saxony potato operations sustain technical advisory relationships with integrated suppliers.
India
Maharashtra's protected cultivation expansion in Nashik and Pune districts creates emerging demand for iron-chelate programs in high-pH alluvial soils. FSSAI and state agricultural departments regulate micronutrient quality standards for domestic fertilizer channels. Karnataka's Bengaluru-Mysuru corridor develops precision horticulture infrastructure requiring micro-irrigation compatible chelate specifications.
China
Shandong Province greenhouse vegetable complexes in Weifang and Qingdao drive specification intensity for high-purity zinc and manganese programs. MEE environmental standards and GB fertilizer quality regulations tighten manufacturing discharge requirements for ligand production facilities. Jiangsu formulation houses in Nantong and Changzhou source chelate intermediates for proprietary micronutrient blends.
Global Agricultural Chelates Market Competitive Landscape
Integrated chemical conglomerates and specialized agricultural input suppliers split the market along manufacturing depth and distribution reach dimensions. The vendor base concentrates around ligand production capability and regulatory dossier completeness. Three archetypes dominate: backward-integrated chemical majors with captive ligand synthesis, formulation specialists sourcing intermediate chelates for proprietary blends, and regional distributors bundling advisory services with product supply. Capacity expansion in high-stability EDDHA manufacturing and strategic partnerships for biostimulant-chelate bundling represent the dominant competitive vectors reshaping positioning.
Among integrated chemical majors with European manufacturing heritage, BASF SE and Nouryon occupy positions exemplifying the backward-integrated archetype with dedicated EDTA and EDDHA production facilities. Yara International ASA anchors the agricultural-specialist tier through direct farm advisory programs that bundle chelated micronutrients with precision application protocols. These three entities collectively represent the spectrum from petrochemical-derived ligand synthesis through farm-gate technical service integration.
| Leading Market Players |
|---|
| Yara International ASA |
| ICL |
| Nouryon |
| Dow |
| The Andersons |
| BASF SE |
| Haifa Group |
| Nufarm Ltd. |
| Syngenta Group |
| Others |
Supply & Pricing Matrix
Single-source dependency on Chinese EDDHA precursor manufacturing determines both the three-tier pricing spread across premium, standard, and economy chelate grades and the geographic clustering of formulation capacity near major agricultural demand centers.
Pricing Analysis
Configured-to-order pricing for high-ortho EDDHA iron chelates commands substantial premiums over standard-grade EDTA formulations in California specialty vegetable markets. Price differentiation hinges on isomer purity certification and micro-irrigation compatibility testing. Cost compression in commodity EDTA tiers is intensifying because Brazilian soybean cooperatives negotiate volume contracts with minimal specification variance. Broadacre cereal operations in Ukraine and Australia's wheat belt exhibit the highest price sensitivity, while Dutch greenhouse horticulture tolerates premium positioning for guaranteed batch consistency.
Supply Chain Analysis
Upstream feedstock concentration in German and Chinese chemical manufacturing clusters anchors global EDTA and EDDHA ligand supply. The chain draws from ethylenediamine, salicylic acid, and phosphorous acid intermediates sourced from Ludwigshafen, Nantong, and Houston production hubs. Single-source vulnerability in ortho-ortho EDDHA isomer production exposes formulators to disruption risk. Distribution runs through agricultural cooperative procurement networks in Europe, direct-to-farm digital platforms in Brazil, and specialty distributor channels in North American horticulture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against non-chelated micronutrient salts and emerging nanofertilizer technologies that threaten to displace conventional ligand systems in cost-sensitive segments.
For Market Incumbents: Pre-empt nanofertilizer substitution by accelerating biostimulant-chelate bundling programs in Brazil's regulatory convergence environment. Secure backward integration into natural amino acid chelate production to defend margin position as EU REACH restrictions tighten on synthetic ligands. Prioritize dossier completeness for EDDHA substances to maintain market access against smaller formulators facing compliance cost barriers.
For New Entrants and Emerging Players: Pursue white-space penetration in India's protected cultivation corridor, where Maharashtra and Karnataka horticulture intensification has outpaced established supplier coverage. Target organic certification pathways for lignosulfonate and protein-based alternatives as USDA Organic and EU Organic acceptance expands. Deploy soil analysis bundling through direct digital platforms to bypass entrenched cooperative distribution in consolidated farm regions.
For Investors and Strategic Acquirers: REACH authorization milestones reshape the acquisition landscape toward dossier-complete multinationals with dedicated regulatory affairs capabilities. Long-term viability favors targets with captive ligand synthesis and precision agriculture advisory integration. Watch for biostimulant-chelate regulatory convergence in Brazil as the inflection signal for combined input category expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Amino Acid Production | Captures margin expansion as EU REACH restricts synthetic EDTA and DTPA ligand use. |
| Biostimulant-Chelate Bundling Development | Exploits regulatory convergence in Brazil enabling novel combined micronutrient-biological positioning. |
| Precision Agriculture Advisory Expansion | Locks in supplier relationships through direct farm technical service bundling with chelate prescriptions. |
| EDDHA High-Ortho Isomer Capacity Addition | Addresses California and Florida specialty crop demand for alkaline soil chlorosis correction. |
| Direct-to-Farm Digital Platform Deployment | Disintermediates cooperative channels in Brazil's Mato Grosso soybean belt through manufacturer-hosted e-commerce. |
Research Methodology
A spread of perspectives from chelate manufacturing plant managers, agricultural cooperative procurement leads, specialty crop growers, distribution channel partners, and regulatory affairs directors converged on the working assumptions driving this analysis. Primary field engagement combined with secondary validation against customs and trade data, Fertilizers Europe industry reports, EPA registration filings, and REACH dossier submissions anchored the evidence base. Bottom-up segmentation modeling and top-down macroeconomic triangulation refined volume and value estimates across the projection horizon.
Demand-supply-balance framing structured the analytical approach throughout the modeling period. Segmentation dimensions included chelate ligand type, application mode, crop category, and end-use customer scale. CAGRs derived from trend extrapolation of input intensity per hectare, acreage expansion in target cultivation zones, and substitution rates from non-chelated alternatives. Industry-specific forecast inputs incorporated soil pH mapping data from agricultural extension services and micro-irrigation infrastructure deployment rates in priority regions.
Sensitivities concentrate around REACH authorization timelines for EDTA substances, phosphoric acid price volatility, and Brazilian real exchange rate movements affecting import-dependent input costs. Cross-checking against Fertilizers Europe production statistics and ANVISA residue limit enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
ASEAN Livestock Disinfectant Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
Global Agricultural Micronutrients Market