
 Auxin Substitutes Market | 2026-2036
Auxin Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Auxin Substitutes Market Analytics
Buyer concentration among agricultural companies is hardening as large-scale farming operations consolidate input procurement. BASF SE leverages its integrated agrochemical pipeline to supply formulated auxin substitutes across European distribution networks. Bayer CropScience anchors its position through field-testing partnerships with university extension services. Syngenta AG competes on biological growth regulator portfolios that target specialty crop segments.
Auxin substitutes are chemically synthesized or naturally derived compounds that mimic indole-3-acetic acid function to regulate cell elongation, root initiation, and fruit set in plants, typically applied at concentrations between 0.1 and 500 ppm depending on target species and desired physiological response. Synthetic auxins command the largest revenue share due to established efficacy in broad-acre row crops, while natural auxins and growth regulators represent the fastest-expanding category as organic farming certification programs multiply across supply chains. Herbicide-type auxin substitutes retain mature volume positions in conventional systems but face margin compression from regulatory review cycles.
The EU Green Deal and REACH frameworks restrict persistent synthetic auxin residues in food-grade agricultural outputs, pushing reformulation toward biodegradable analogs. The EPA in the United States maintains tolerance thresholds for dicamba and 2,4-D derivatives that shape product registration timelines and label restrictions. India's Central Insecticides Board evaluates import and manufacture of auxin-based formulations under the Insecticides Act. Stakeholders must monitor evolving residue standards across jurisdictions to align portfolio transitions with compliance windows.
Market Dynamics
The EU Green Deal's residue restrictions are forcing agricultural input manufacturers to abandon persistent synthetic auxin formulations and accelerate biodegradable analog development across European supply chains.
Growth Catalysts
- EU Green Deal mandates:The framework's pesticide reduction targets are compelling farmers to adopt bio-based growth regulators that degrade within single growing seasons rather than accumulating in soil profiles.
- Organic certification expansion:USDA Organic and EU Organic label requirements are multiplying certified hectarage, creating addressable demand for natural auxin alternatives that satisfy input material restrictions.
- Precision application hardware:Variable-rate sprayers and drone-based delivery systems are reducing per-hectare auxin substitute volumes while maintaining efficacy, improving unit economics for biological formulations.
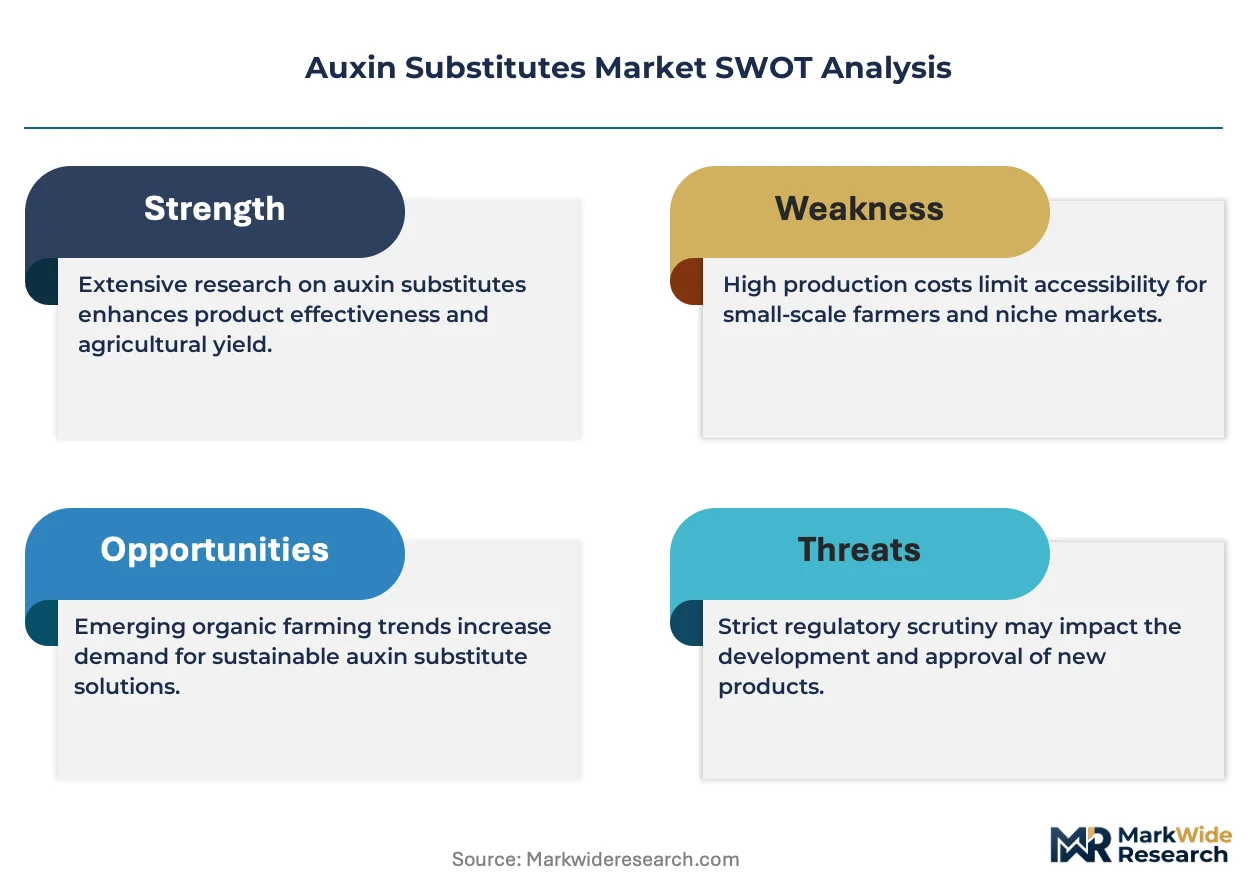
Market Restraints
- Petrochemical feedstock volatility:Synthetic auxin production depends on benzene and phenol derivatives whose pricing fluctuates with crude oil indices, compressing margin stability for conventional manufacturers.
- German R&D concentration:BASF SE and Bayer CropScience anchor over half of European formulation patents, creating licensing bottlenecks for mid-tier competitors seeking advanced bio-based chemistries.
- 2,4-D tolerance thresholds:EPA label restrictions on dicamba and phenoxy herbicide drift are extending product registration timelines by 18-36 months, delaying commercialization windows for reformulated substitutes.
Strategic Opportunities
- India specialty crop penetration:The country's Central Insecticides Board is streamlining biological pesticide approvals under amended Insecticides Act rules, opening horticulture segments previously dominated by synthetic hormones.
- Controlled-release encapsulation:Chitosan and lignin-based delivery systems are converging with auxin substitutes to extend field persistence of biodegradable compounds without triggering residue violations.
- Direct-to-farm digital channels:Agritech platforms are bypassing traditional distributor markups, allowing biological input startups to capture margin previously allocated to wholesale networks.
Industry Challenges
- Formulation chemist scarcity:The intersection of plant physiology and green chemistry expertise remains concentrated in German and Dutch university programs, limiting workforce scaling for new market entrants.
- Multi-jurisdiction residue harmonization:Codex Alimentarius, EU MRL databases, and national tolerance lists maintain divergent analytical methods, forcing manufacturers to maintain parallel testing protocols for export crops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auxin Substitutes Market |
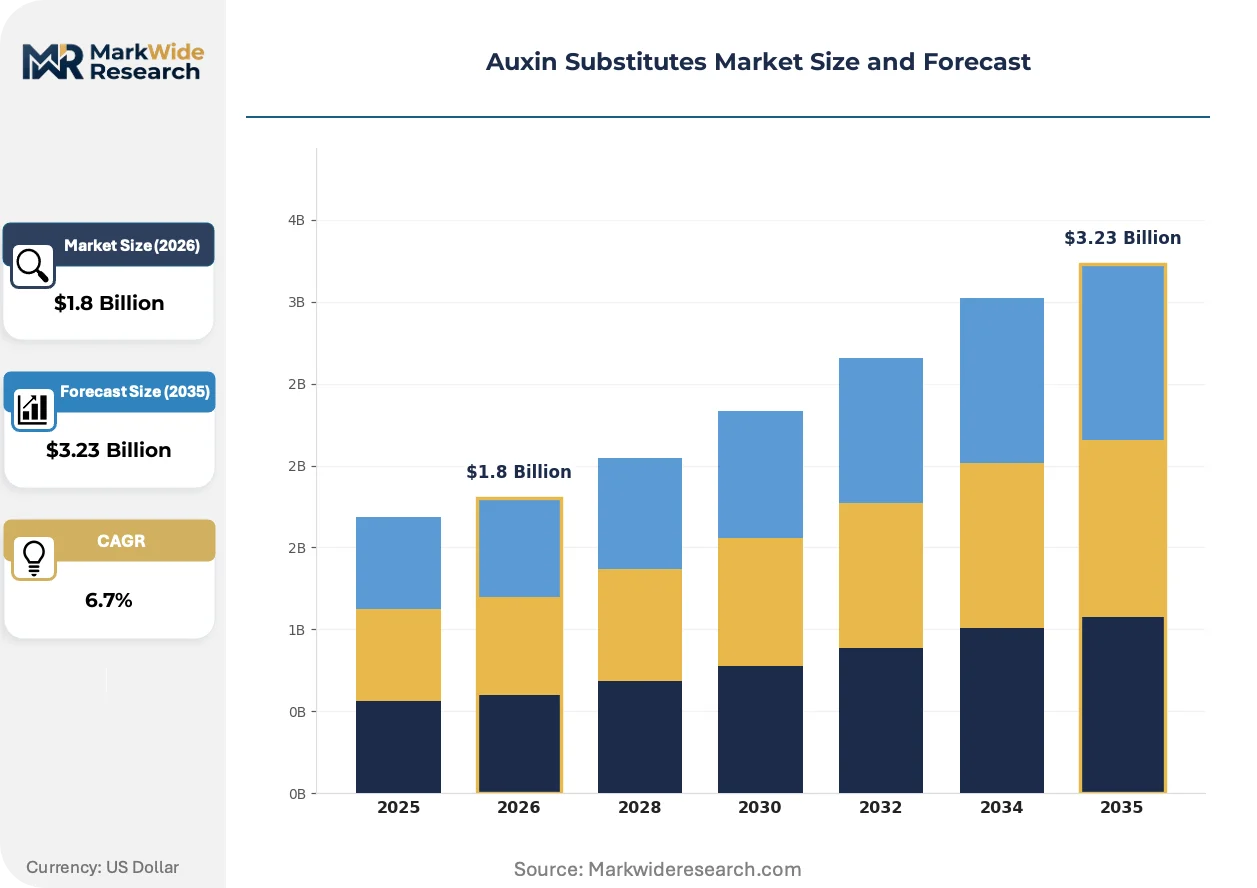
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Auxins, Synthetic Auxins, Growth Regulators, Herbicides Application: Agricultural Crops, Horticulture, Turf Management, Organic Farming Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distribution Partners End User: Farmers, Agricultural Companies, Research Institutions, Home Gardeners |
| Companies Covered | BASF SE, Bayer CropScience, Syngenta AG, Nufarm Ltd., FMC Corporation, Corteva Agriscience, Dow AgroSciences, Sumitomo Chemical Co., Ltd., Sichuan Guoguang Agrochemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auxin Substitutes Market Evolving Landscape
Biological auxin substitutes are displacing synthetic formulations through fermentation-derived production methods and novel application technologies that reduce environmental persistence without sacrificing agronomic performance.
Microbial fermentation of indole-3-acetic acid precursors is converging with CRISPR-edited yeast strains to achieve titers previously restricted to petrochemical synthesis. Specialty crop growers in Spain and Italy are piloting these fermentation-derived auxins in tomato and grape production. The technology is converging with precision fermentation infrastructure originally built for pharmaceutical intermediates, repurposing idle bioreactor capacity for agricultural outputs.
REACH authorization requirements are extending data obligations for synthetic auxin substances, forcing registrants to submit extended one-generation reproductive toxicity studies. The industrial consequence is a bifurcation between legacy phenoxy herbicides facing sunset clauses and bio-based alternatives receiving streamlined substance identity approvals. Fruit and vegetable exporters to EU markets are responding by specifying biodegradable auxin substitutes in procurement contracts to preempt MRL detention at border inspection posts.
Consolidated farming operations are unbundling after-sales agronomic advice from input purchases, previously bundled through distributor relationships. Large-scale row crop enterprises in Brazil and Australia are contracting independent crop consultants to prescribe auxin substitute regimens, then sourcing products through lowest-cost channels. This pattern is most visible in soybean and cotton systems where application timing precision outweighs brand loyalty in input selection.
Auxin Substitutes Market Segmentation
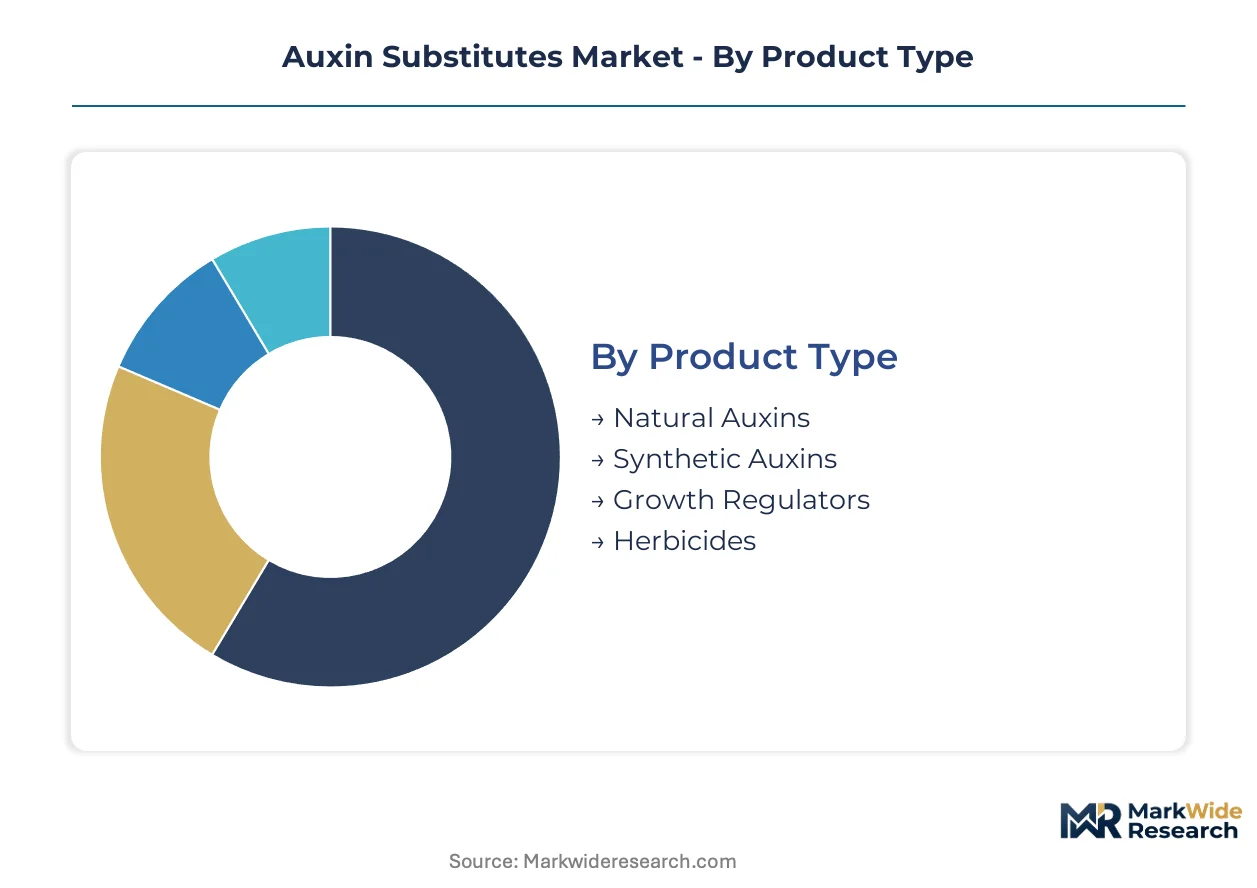
Auxin substitute procurement splits across four intersecting dimensions. Product chemistry determines REACH registration burden. Application context dictates residue tolerance thresholds. Channel selection reflects farm scale and agronomic service requirements.
Product Type:
EU Green Deal residue ceilings create divergent certification pathways across chemical classes, with synthetic phenoxy compounds facing sunset clauses while fermentation-derived alternatives receive streamlined substance identity approvals.
- Synthetic Auxins:Petrochemical-derived phenoxy compounds and benzoic acid analogs dominate broad-acre row crop applications. Demand concentrates in conventional corn and soybean systems where established efficacy outweighs regulatory risk. EPA dicamba drift restrictions and ECHA authorization extensions are compressing commercialization timelines for reformulated variants.
- Growth Regulators:Cytokinin-auxin blends and ethylene modulators regulate fruit set and abscission in high-value horticulture. Spanish tomato and Italian grape growers anchor procurement as precision application hardware improves unit economics for biological formulations.
- Natural Auxins:Indole-3-acetic acid extracted from plant biomass or microbial fermentation serves organic-certified operations. USDA Organic and EU Organic label requirements multiply addressable hectarage.
- Herbicides:2,4-D and dicamba formulations retain mature volume in conventional systems. Margin compression accelerates as multi-jurisdiction residue harmonization forces parallel testing protocols.
Leading the category by volume: Synthetic Auxins. Growing fastest: Growth Regulators.
Application:
End-use context determines concentration thresholds, with specialty crops tolerating higher per-hectare input costs than commodity systems.
- Horticulture:Protected cultivation of tomatoes, peppers, and stone fruits requires precise root initiation control. Controlled-release encapsulation with chitosan delivery systems extends field persistence of biodegradable compounds.
- Agricultural Crops:Broad-acre wheat, rice, and cotton operations prioritize cost-per-hectare metrics. Variable-rate sprayers reduce auxin substitute volumes while maintaining efficacy.
- Organic Farming:Certification programs restrict input materials to naturally derived compounds. Procurement contracts increasingly specify biodegradable auxin substitutes to preempt EU border inspection detention.
- Turf Management:Golf course and sports field maintenance applies auxin substitutes for root density and stress recovery. Seasonal application windows concentrate demand in spring and autumn cycles.
Highest margin concentration: Horticulture. Steepest expansion trajectory: Organic Farming.
Distribution Channel:
Channel selection correlates with farm scale and technical service requirements, with large enterprises unbundling agronomic advice from input purchases.
- Direct Sales:BASF SE and Bayer CropScience supply formulated auxin substitutes through captive agronomist networks. Field-testing partnerships with university extension services anchor customer retention.
- Distribution Partners:Regional agrochemical wholesalers maintain inventory positions for mid-tier manufacturers. Traditional markups face pressure from direct-to-farm digital channels.
- Online Retail:Agritech platforms bypass wholesale networks, allowing biological input startups to capture margin previously allocated to distributor tiers.
- Offline Retail:Cooperative and independent farm supply stores serve smallholder and home gardener segments. Geographic fragmentation limits national coverage.
Dominant by revenue: Direct Sales. Gaining share fastest: Online Retail.
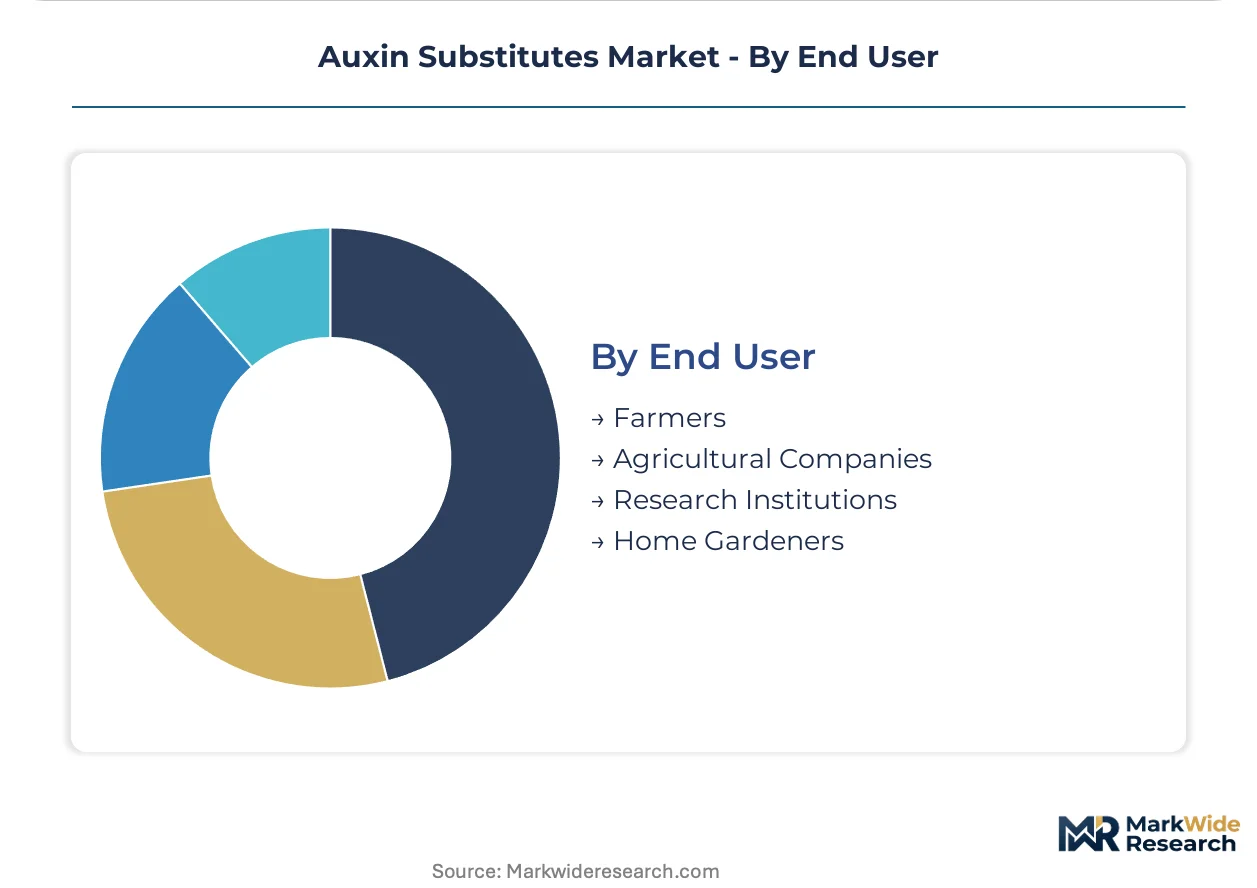
End User:
User type determines formulation complexity and service bundling, with consolidated operations driving procurement centralization.
- Agricultural Companies:Large-scale farming operations consolidate input procurement across multiple hectares. Independent crop consultants prescribe auxin substitute regimens, with products sourced through lowest-cost channels.
- Farmers:Mid-scale operators balance brand loyalty against price sensitivity. Application timing precision outweighs input origin in soybean and cotton systems.
- Research Institutions:University extension services and agricultural institutes conduct field trials for registration data. Partnerships with manufacturers accelerate biological formulation development.
- Home Gardeners:Consumer-packaged auxin substitutes target root cutting and ornamental propagation. Retail shelf placement and label clarity drive purchase decisions.
Primary volume anchor: Agricultural Companies. Expanding most quickly: Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural companies in Germany, the United States, and India concentrate procurement of auxin substitutes as regulatory frameworks diverge across jurisdictions. Large-scale farming operations in Brazil and China are consolidating input purchasing power. Field-testing partnerships with university extension services anchor commercial relationships in each market.
Germany
BASF SE and Bayer CropScience anchor R&D investment in bio-based auxin formulations across the Rhine-Ruhr and Upper Rhine industrial clusters. The EU Green Deal and ECHA REACH authorization requirements are forcing reformulation toward biodegradable analogs. Ludwigshafen-based manufacturing facilities supply formulated products across European distribution networks.
United States
Broad-acre corn and soybean operations in Iowa and Illinois prioritize cost-per-hectare metrics for synthetic auxin procurement. EPA tolerance thresholds for dicamba and 2,4-D derivatives shape product registration timelines and label restrictions. Precision agriculture adoption in the Corn Belt reduces per-hectare auxin substitute volumes while maintaining efficacy.
India
Horticulture segments in Maharashtra and Karnataka previously dominated by synthetic hormones are opening to biological alternatives. The Central Insecticides Board evaluates import and manufacture under amended Insecticides Act rules streamlining biological pesticide approvals. Mumbai-based agritech platforms are bypassing traditional distributor markups for specialty crop inputs.
Brazil
Consolidated soybean and cotton enterprises in Mato Grosso and Goiás are unbundling agronomic advice from input purchases. Independent crop consultants prescribe auxin substitute regimens with products sourced through lowest-cost channels. Application timing precision outweighs brand loyalty in procurement decisions across the Cerrado agricultural frontier.
China
Sichuan Guoguang Agrochemical Co., Ltd. exemplifies domestic production capacity serving protected cultivation in Shandong and Jiangsu provinces. The country's national pesticide regulator evaluates residue standards under evolving environmental protection frameworks. Yangtze River Delta greenhouse clusters pilot fermentation-derived auxins in tomato and pepper production systems.
Auxin Substitutes Market Competitive Landscape
German producers anchor one tier of the auxin substitute market; Chinese specialists hold manufacturing scale advantages in fermentation-derived compounds. The vendor base concentrates around integrated agrochemical conglomerates with captive distribution networks and biological input startups leveraging direct-to-farm digital channels. Three strategic archetypes dominate: integrated chemical conglomerates with full pipeline control, biological formulation specialists targeting organic certification programs, and generic manufacturers competing on price in commoditized synthetic segments. Competitive moves center on M&A to secure bio-based technology portfolios and strategic partnerships with university extension services for field trial data generation.
Within the integrated conglomerate tier, BASF SE and Bayer CropScience exemplify archetypes combining formulation expertise with distribution network control. Syngenta AG occupies a position emphasizing biological growth regulator portfolios. Nufarm Ltd. represents the generic manufacturing archetype competing in price-sensitive conventional systems. Each anchors distinct competitive positioning without overlapping strategic territory.
| Leading Market Players |
|---|
| BASF SE |
| Bayer CropScience |
| Syngenta AG |
| Nufarm Ltd. |
| FMC Corporation |
| Corteva Agriscience |
| Dow AgroSciences |
| Sumitomo Chemical Co., Ltd. |
| Sichuan Guoguang Agrochemical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Benzene and phenol derivative indices cascade through synthetic auxin substitute production into three distinct pricing tiers that separate petrochemical-derived formulations from fermentation-based alternatives and certified organic inputs. Agricultural companies in Germany and the United States negotiate contract-based long-term offtake agreements that buffer against crude oil volatility, while specialty crop growers in India and Spain absorb premium pricing for biodegradable compounds to satisfy EU Green Deal residue ceilings.
Pricing Analysis
Volume concentrates in synthetic phenoxy compounds serving broad-acre corn and soybean systems, while margins accrue to fermentation-derived growth regulators targeting certified organic horticulture. Price differentiation separates petrochemical formulations from chitosan-encapsulated biological alternatives, with certification grade and after-sales agronomic bundling as secondary drivers. Cost compression in synthetic tiers is intensifying because REACH authorization extensions force parallel toxicity testing protocols. Mid-scale farmers in Brazil exhibit highest price sensitivity, whereas German agricultural companies prioritize application timing precision over per-unit cost.
Supply Chain Analysis
Petrochemical feedstock supply rests on German and Chinese specialty chemical producers, with fermentation capacity expanding in Dutch and Indian bioreactor facilities. Raw material dependencies include benzene derivatives, indole-3-acetic acid precursors, and chitosan encapsulation agents. Single-source vulnerability concentrates in Ludwigshafen-based formulation plants controlled by integrated agrochemical conglomerates. Distribution runs through captive agronomist networks for large-scale operations, while agritech platforms bypass wholesale markups for biological input startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbial fermentation of indole-3-acetic acid precursors is displacing petrochemical synthesis as the dominant production paradigm, forcing legacy manufacturers to reconfigure R&D pipelines and manufacturing footprints.
For Market Incumbents: Lock in field-testing partnerships with university extension services to generate registration data ahead of REACH sunset clauses for phenoxy herbicides. Backward integration into fermentation infrastructure secures supply of biodegradable analogs as EU Green Deal residue restrictions tighten. Channel control through captive agronomist networks defends against direct-to-farm digital disintermediation.
For New Entrants and Emerging Players: Direct-to-farm agritech platforms offer the lowest-friction route to bypass established distributor markups and capture margin from biological formulation sales. Target India's Maharashtra and Karnataka horticulture segments, where Central Insecticides Board streamlining under amended Insecticides Act rules opens previously synthetic-dominated markets. Controlled-release encapsulation partnerships with chitosan suppliers anchor differentiated positioning.
For Investors and Strategic Acquirers: The window for entry favors biological formulation specialists with fermentation-derived pipelines and organic certification approvals. Long-term viability hinges on portfolio exposure to biodegradable growth regulators rather than legacy phenoxy compounds. Watch EPA tolerance threshold adjustments for dicamba and 2,4-D derivatives as the inflection signal for synthetic auxin sunset acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Captive bioreactor capacity secures biodegradable auxin supply as REACH restrictions tighten. |
| Controlled-Release Encapsulation Development | Chitosan and lignin delivery systems extend field persistence without triggering EU MRL violations. |
| Direct-to-Farm Digital Channel Launch | Agritech platforms bypass wholesale markups and capture margin from biological input sales. |
| University Extension Partnership Expansion | Field-testing relationships with agricultural institutes generate registration data and anchor customer retention. |
| Organic Certification Portfolio Repositioning | USDA Organic and EU Organic approvals multiply addressable hectarage in premium horticulture segments. |
Research Methodology
Independent corroboration across formulation chemists at German agrochemical manufacturers, procurement leads at Brazilian agricultural companies, and regulatory affairs specialists at Indian biological input firms underwrites the qualitative findings. Secondary validation draws from ECHA REACH authorization databases, EPA tolerance threshold filings, and Central Insecticides Board approval records. Bottom-up triangulation across product chemistry segments converges with top-down demand modeling from certified organic hectarage expansion.
Comparable historical reference periods anchor the projection horizon to pre-pandemic baseline demand patterns and post-EU Green Deal regulatory inflection points. The analytical framework models product chemistry, application context, distribution channel, and end-user scale as segmentation dimensions. CAGRs derive from shipment volume reconciliation with import-export customs data and biological pesticide registration trajectories. Fermentation titer improvements and precision agriculture adoption rates serve as industry-specific forecast inputs.
The model holds under stable regulatory enforcement timelines; deviation in EPA label restriction severity or ECHA authorization acceleration would shift commercialization windows. Forecasts reflect assumptions regarding organic certification program expansion and petrochemical feedstock price correlation. A small set of named triggers warrants ongoing watch: REACH sunset clause implementation pace, Central Insecticides Board approval streamlining, and dicamba drift litigation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
South America Herbicide Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
South America Feed Antibiotics Market
Agricultural Chemicals
Global Soil Wetting Agents Market