
 France Electric Bus Battery Pack Market | 2026-2036
France Electric Bus Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
France Electric Bus Battery Pack Market Insights
The EU Green Deal's transport decarbonization targets are hardening procurement standards across French public transit networks. Automotive Cells Company (ACC) leverages its Dunkirk gigafactory to anchor domestic cell supply for bus OEMs. Blue Solutions SA (Bolloré Group) sustains its lithium-metal polymer specialization for niche electric bus applications. Saft Groupe S A competes through its defense and industrial battery heritage translated into heavy-duty transit solutions.
France electric bus battery packs are integrated electrochemical storage systems, typically comprising lithium-ion cells arranged in modular configurations with battery management systems, thermal regulation hardware, and high-voltage interconnects, engineered to deliver sustained power output across variable duty cycles in commercial passenger transport. Lithium-ion chemistry dominates current procurement due to proven energy density and cycle life, while solid-state architectures represent the fastest-growing development track as manufacturers target enhanced safety margins and extended operational lifespans. Fast charging technology commands premium positioning in urban depot deployments where route minimization dictates turnaround efficiency.
France's national energy regulator, the Commission de Régulation de l'Énergie (CRE), oversees grid integration standards for high-capacity charging infrastructure, while ANSM monitors transport of hazardous battery materials and the EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations. The LOM law and France's national low-carbon strategy collectively mandate diesel bus elimination timelines that shape municipal procurement calendars. Stakeholders must monitor CRE tariff structures for depot charging and EU Battery Regulation compliance deadlines to align manufacturing and sourcing decisions.
Market Dynamics
The LOM law's diesel bus phase-out mandates are compressing procurement timelines across French urban transit networks. RATP's Île-de-France electrification schedule now dictates national battery pack demand patterns.
Growth Catalysts
- LOM Law Mandates:France's progressive diesel elimination framework binds municipal procurement calendars to fixed electrification deadlines. Transit agencies in Paris, Lyon, and Marseille accelerate fleet replacement cycles.
- EU Battery Regulation:Recycled content thresholds and carbon footprint declarations are redirecting sourcing decisions toward domestic cell production. Compliance requirements favor localized supply chain configurations.
- Depot Fast Charging:High-capacity infrastructure deployment at urban bus terminals is enabling extended-range battery configurations. Route minimization imperatives prioritize turnaround efficiency over battery capacity alone.
Market Restraints
- Lithium Supply Concentration:Raw material processing bottlenecks in non-European geographies expose French pack assemblers to input cost volatility. Cathode active material dependence creates margin compression risks.
- CRE Tariff Uncertainty:France's national energy regulator revises grid integration standards for high-capacity charging infrastructure. Depot electricity pricing unpredictability complicates total cost of ownership calculations for transit operators.
- Cell Manufacturing Scale Gap:Domestic gigafactory output lags projected bus sector demand through the mid-forecast period. Import reliance for cylindrical and prismatic cells persists despite ACC's Dunkirk investment.
Strategic Opportunities
- Solid-State Chemistry Transition:Lithium-metal polymer architectures from established French specialists target enhanced safety margins for tunnel-operated bus routes. Thermal runaway elimination opens premium transit segments.
- Second-Life Stationary Storage:Decommissioned bus battery packs cascade into grid stabilization applications under CRE integration frameworks. Circular economy compliance creates residual value capture mechanisms.
- Provence-Alpes-Côte d'Azur Electrification:Marseille's port-city transit authority lags Paris and Lyon in fleet conversion, representing concentrated future demand. Regional air quality directives tighten faster than national baselines.
Industry Challenges
- Battery Management System Integration:Legacy depot maintenance workflows require reskilling for high-voltage electrochemical diagnostics. Technician certification timelines delay fleet deployment schedules.
- Thermal Regulation Hardware Standardization:Proprietary cooling architectures from competing cell suppliers fragment pack design specifications. Interoperability gaps inflate engineering validation costs for bus OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Electric Bus Battery Pack Market |
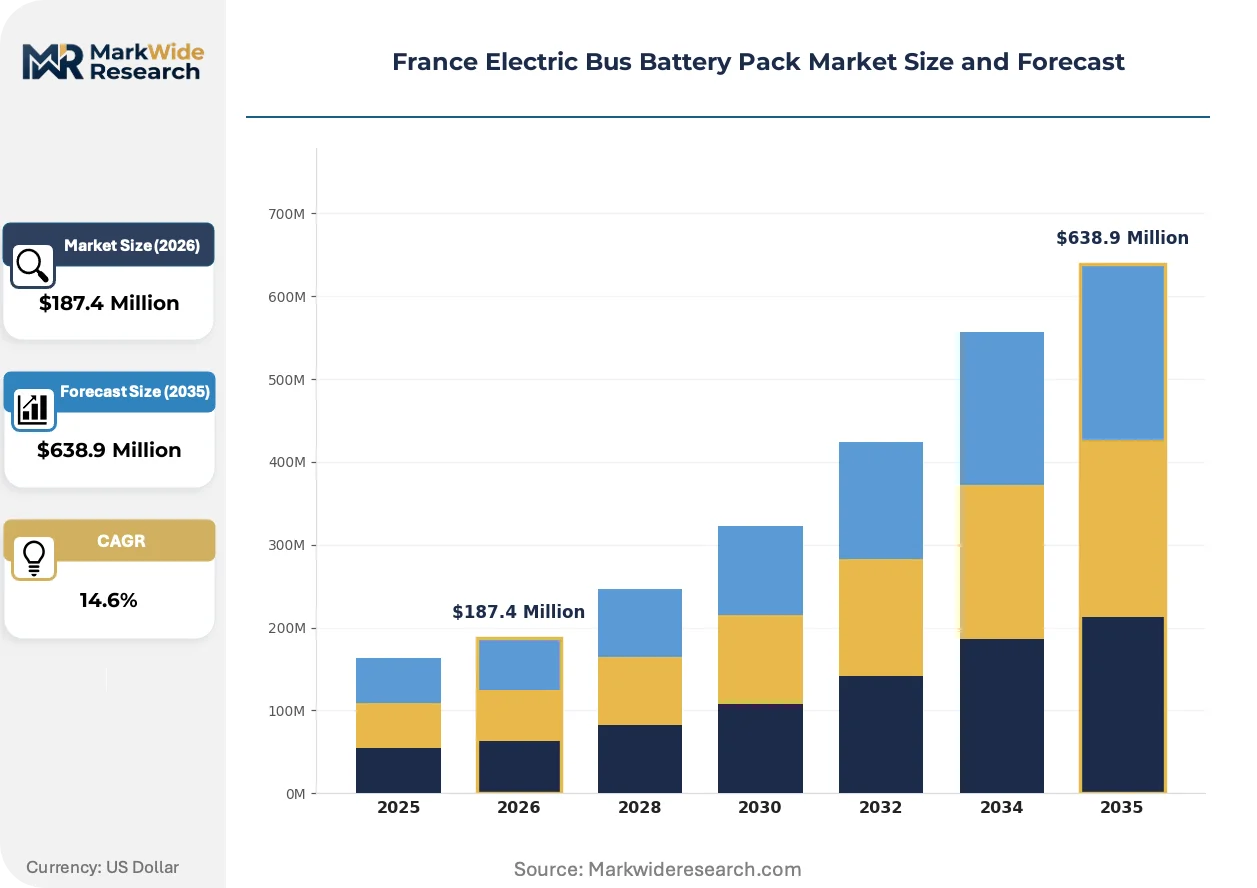
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State Bus Model: Articulated, Double Decker, Standard Length, Midi Bus Charging Technology: Overhead, Plug-In, Wireless, Fast Charging End User: Public Transport Authorities, Private Operators, School Districts, Tourism Services |
| Companies Covered | Automotive Cells Company (ACC), Blue Solutions SA (Bolloré Group), Contemporary Amperex Technology Co Ltd (CATL), LG Energy Solution Ltd, Saft Groupe S A, Akasol AG, Panasonic Holdings Corporation, Samsung SDI Co Ltd, BYD Company Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Electric Bus Battery Pack Market Trends and Innovations
Cell-to-pack architectures and solid-state prototyping are compressing traditional module-based manufacturing assumptions. French suppliers now compete on thermal management integration depth rather than standalone energy density metrics.
Prismatic lithium-iron-phosphate cells are modularizing around standardized 280Ah formats for heavy-duty transit applications. RATP's technical specifications now mandate swappable sub-pack units for depot-level maintenance. This standardization is modularizing aftermarket service economics and compressing specialized technician requirements across the Île-de-France network.
France's CRE has tightened grid connection standards for megawatt-scale depot charging infrastructure. Bus operators must now integrate battery energy storage systems to manage peak demand charges. The EU Green Deal's transport decarbonization targets harden these requirements fastest in urban cores with existing air quality non-attainment designations.
Total cost of ownership calculations now dominate municipal tender evaluations ahead of upfront capital expenditure. Lyon and Marseille transit authorities unbundle battery pack procurement from complete bus purchases. This financing separation concentrates technical specification authority with specialized energy storage engineers rather than traditional fleet managers.
France Electric Bus Battery Pack Market Segmentation
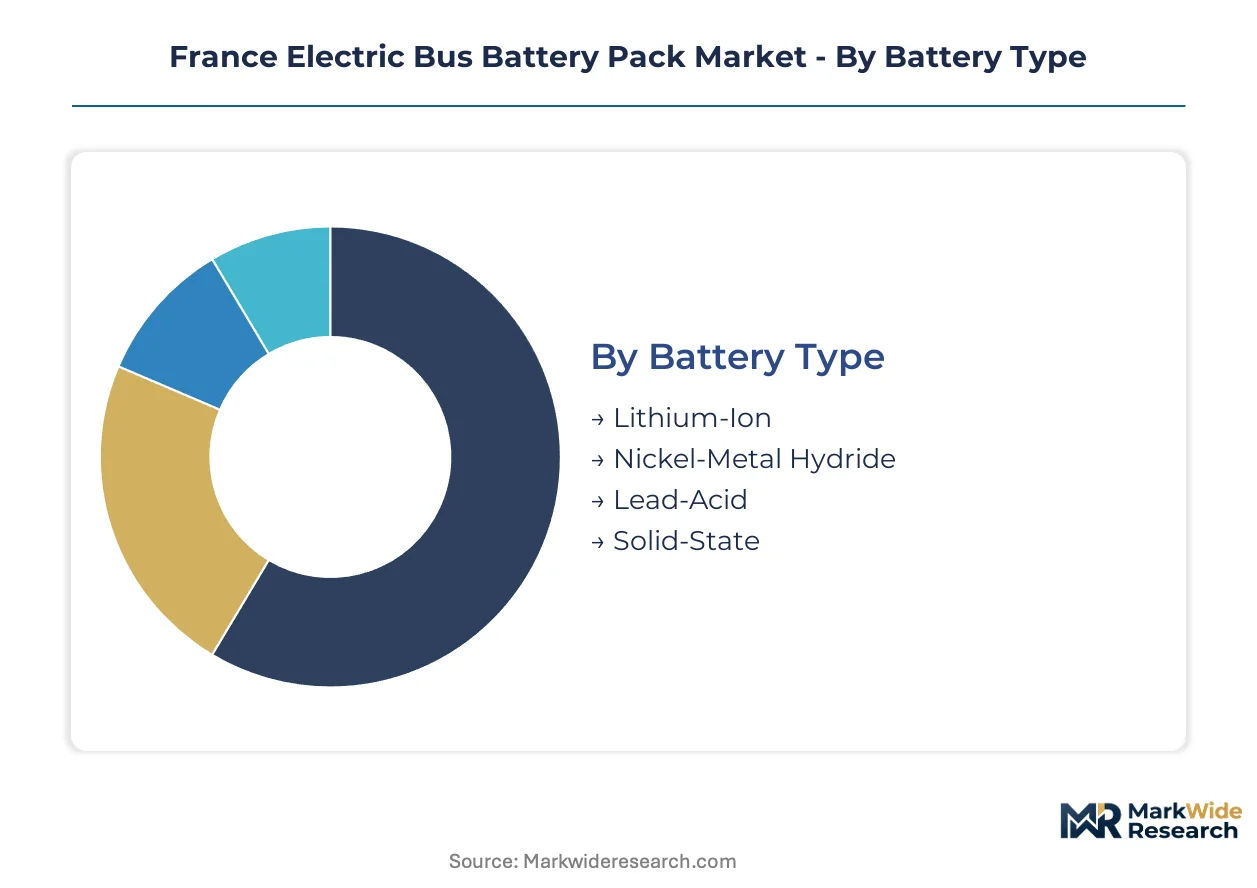
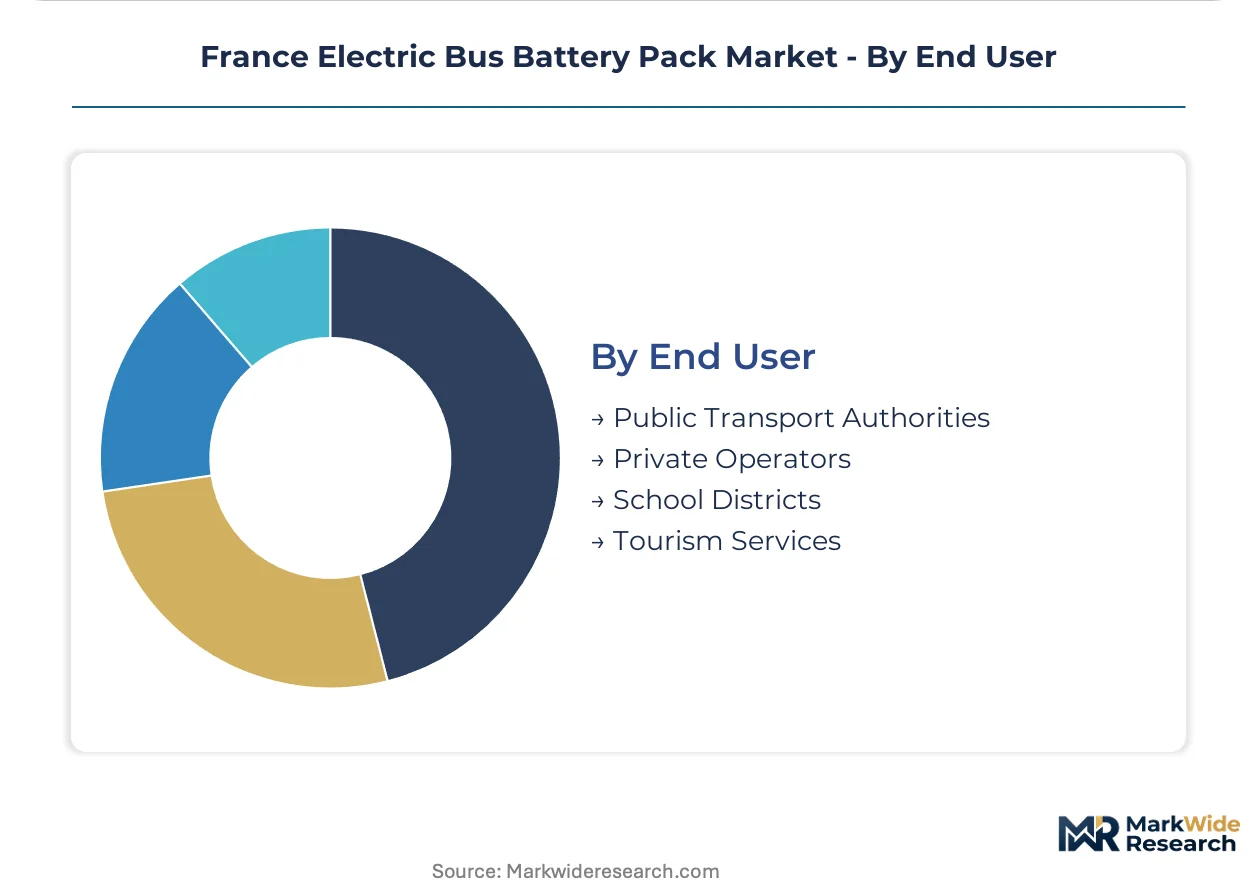
Segmentation in the France electric bus battery pack market reveals how regulatory compliance burdens and operational requirements reshape procurement patterns across transit networks. RATP's technical specifications now cascade through municipal tender documents, creating tiered certification requirements that favor certain battery architectures over others.
Battery Type:
Certification requirements under France's ANSM transport regulations and the EU Battery Regulation's carbon footprint declarations impose distinct compliance burdens across electrochemical architectures. Solid-state configurations face emerging safety validation protocols, while lithium-ion variants navigate established UN 38.3 testing frameworks.
- Lithium-Ion:Prismatic and cylindrical configurations utilizing nickel-manganese-cobalt or lithium-iron-phosphate cathodes deliver proven energy density above 250 Wh/kg for heavy-duty transit cycles. RATP's Île-de-France procurement pipeline concentrates demand here, driven by ACC's Dunkirk cell supply and CRE grid integration standards for depot charging infrastructure.
- Solid-State:Lithium-metal polymer architectures eliminate liquid electrolyte thermal runaway risks through dry ceramic or polymer ionic conductors. Tunnel-operated routes in Lyon and Marseille accelerate pilot deployments, constrained by ANSM certification timelines for novel transport battery formats.
- Nickel-Metal Hydride:Mature chemistry retains niche positioning in hybrid-electric retrofits where full electrification infrastructure remains incomplete.
- Lead-Acid:Auxiliary power applications and emergency backup systems in legacy depot fleets sustain minimal residual demand.
Leading the category by volume: Lithium-Ion. Expanding most quickly: Solid-State.
Bus Model:
Pack configuration dimensions and thermal management requirements scale non-linearly with vehicle architecture, fragmenting engineering validation costs across OEM supply chains.
- Standard Length:Single-deck 12-meter configurations dominate unit procurement volumes across French urban networks. Modular 280Ah prismatic cell arrangements accommodate RATP's swappable sub-pack maintenance specifications, with depot fast charging infrastructure optimized for this footprint.
- Articulated:18-meter bendy buses demand segmented battery enclosures distributed across both rigid sections, complicating high-voltage interconnect design. Marseille's port-city transit authority targets this segment for high-capacity corridor routes under regional air quality directives.
- Double Decker:Vertical space constraints in Paris and Lyon favor roof-mounted pack architectures with enhanced waterproofing to IP67+ standards.
- Midi Bus:Sub-9-meter configurations for peripheral and rural routes prioritize weight reduction over absolute range, driving demand for high-specific-energy cell formats.
Standard Length configurations anchor procurement volumes. Articulated models gain share fastest in corridor electrification programs.
Charging Technology:
CRE tariff structures and grid connection standards differentiate total cost of ownership calculations across infrastructure investment profiles.
- Fast Charging:Megawatt-capable depot infrastructure enables opportunity charging at route termini, permitting smaller pack capacities and reduced vehicle curb weight. CRE's revised peak demand charge frameworks now mandate integrated battery energy storage systems at high-capacity terminals, reshaping infrastructure economics.
- Plug-In:Standard CCS2 connectors dominate overnight depot charging configurations across RATP and Lyon networks, leveraging established technician training programs and interoperable maintenance protocols.
- Overhead:Pantograph and trolley-pole systems persist in Strasbourg and select legacy networks where infrastructure amortization spans decades.
- Wireless:Inductive charging pads at bus stops remain experimental, constrained by CRE electromagnetic compatibility certification requirements and copper loss efficiency penalties.
Plug-In infrastructure leads installed base. Fast Charging climbs fastest as route minimization imperatives harden.
End User:
Procurement authority fragmentation across public and private entities creates divergent specification pathways and financing structures.
- Public Transport Authorities:RATP, TCL Lyon, and RTM Marseille exercise consolidated technical specification authority through unbundled battery pack tenders. LOM law mandates compress procurement calendars, with total cost of ownership evaluations now superseding upfront capital expenditure metrics.
- Private Operators:Keolis, Transdev, and RATP Dev navigate concession contract renegotiations to recover electrification investments through extended operating terms. Fleet standardization pressures mount as OEM service networks consolidate.
- School Districts:Regional council transport departments procure midi-bus configurations under education ministry carbon reduction guidelines, with slower fleet turnover cycles than urban transit.
- Tourism Services:Open-top double-decker operators in Paris and Nice prioritize aesthetic integration and passenger cabin space preservation, accepting range limitations for sightseeing route profiles.
Public Transport Authorities command procurement volume. Private Operators scale fastest as concession restructuring accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors French electric bus battery pack demand through RATP's procurement dominance, while regional transit authorities in Lyon and Marseille accelerate fleet conversion timelines under tightening air quality mandates.
Île-de-France
RATP's electrification schedule concentrates national battery pack procurement, with depot fast charging infrastructure scaling across the Paris metropolitan network. The LOM law binds municipal procurement calendars to fixed diesel elimination deadlines. Automotive Cells Company's Dunkirk gigafactory supplies prismatic cells for RATP's swappable sub-pack specifications.
Auvergne-Rhône-Alpes
TCL Lyon's articulated bus corridor electrification drives demand for segmented battery enclosures distributed across 18-meter vehicle sections. Regional air quality directives tighten faster than national baselines. Tunnel-operated routes accelerate pilot deployments of lithium-metal polymer architectures from established French specialists.
Provence-Alpes-Côte d'Azur
Marseille's port-city transit authority lags Paris and Lyon in fleet conversion, representing concentrated future demand for high-capacity battery configurations. The CRE's revised peak demand charge frameworks mandate integrated battery energy storage systems at megawatt-scale terminals. RTM's procurement pipeline favors modular 280Ah prismatic cell arrangements for depot-level maintenance.
Hauts-de-France
ACC's Dunkirk gigafactory anchors domestic cell supply for bus OEMs serving northern French transit networks. The EU Battery Regulation's recycled content thresholds redirect sourcing decisions toward localized supply chain configurations. Lille's metropolitan transit authority unbundles battery pack procurement from complete bus purchases under total cost of ownership evaluations.
Nouvelle-Aquitaine
Bordeaux's tram-bus hybrid networks sustain niche demand for nickel-metal hydride chemistry in partial electrification deployments. Slower fleet turnover cycles in peripheral regional routes prioritize weight reduction over absolute range. Midi-bus configurations for rural services drive demand for high-specific-energy cell formats from specialized suppliers.
France Electric Bus Battery Pack Market Competitive Landscape
The competitive structure tilts toward domestic cell manufacturers with captive supply agreements to major transit authorities. French pack assemblers face input cost volatility from cathode active material dependence, compressing margins against vertically integrated Asian competitors. Three archetypes dominate: domestic gigafactory operators with localized supply chain advantages, European industrial battery specialists with defense heritage translation, and scale-driven Asian cell manufacturers with cost-optimized cylindrical and prismatic formats. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players secure long-term offtake agreements with RATP and regional transit operators.
Among domestic manufacturers, Automotive Cells Company and Blue Solutions SA exemplify contrasting strategic positions—ACC represents the scale-driven gigafactory archetype leveraging Dunkirk production for RATP supply, while Blue Solutions occupies the specialization tier through lithium-metal polymer expertise for tunnel safety applications. Saft Groupe S A anchors the industrial heritage segment, translating defense and heavy-duty battery experience into transit solutions. Contemporary Amperex Technology Co Ltd and LG Energy Solution Ltd sit within the cost-optimized import tier, supplying cylindrical and prismatic cells where domestic output falls short of projected bus sector demand.
| Leading Market Players |
|---|
| Automotive Cells Company (ACC) |
| Blue Solutions SA (Bolloré Group) |
| Contemporary Amperex Technology Co Ltd (CATL) |
| LG Energy Solution Ltd |
| Saft Groupe S A |
| Akasol AG |
| Panasonic Holdings Corporation |
| Samsung SDI Co Ltd |
| BYD Company Ltd |
| Others |
Pricing and Supply Chain Analysis
The EU Battery Regulation's recycled content thresholds and carbon footprint declarations gate qualified supply access for French pack assemblers while stratifying pricing tiers around compliance certification. Transit authorities in Île-de-France and Auvergne-Rhône-Alpes now unbundle battery procurement from vehicle purchases, concentrating specification authority with energy storage engineers who weight total cost of ownership above upfront capital expenditure.
Pricing Analysis
Value-based pricing anchored to guaranteed cycle life and depot uptime performance now dominates RATP and TCL Lyon tender evaluations. Three-tier pricing structure across premium solid-state configurations, standard lithium-ion prismatic formats, and economy cylindrical imports reflects certification grade and thermal management integration depth. Cost compression in the economy tier intensifies as Asian cell manufacturers scale cylindrical output for European bus OEMs. Private operators under concession renegotiations exhibit highest price sensitivity; public transport authorities with LOM-mandated procurement calendars prioritize performance guarantees over unit cost.
Supply Chain Analysis
Reverse logistics flows for end-of-life bus batteries cascade into second-life stationary storage applications under CRE integration frameworks, creating residual value capture mechanisms that reshape pack economics. Cathode active material processing concentrates in China, South Korea, and Japan, exposing French assemblers to input cost volatility from lithium carbonate and nickel sulfate spot markets. Single-source vulnerability persists for high-nickel cathode precursors despite ACC's Dunkirk gigafactory investment. Distribution runs through OEM-anchored service networks with depot-level maintenance contracts, fragmenting aftermarket access for independent pack specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France electric bus battery pack market sits in a technology-transition phase as solid-state lithium-metal polymer architectures displace liquid electrolyte systems for tunnel-operated routes. Cell-to-pack manufacturing and standardized 280Ah prismatic formats are compressing legacy module-based assembly assumptions.
For Market Incumbents: Cement captive supply relationships with RATP and regional transit authorities through long-term offtake agreements tied to CRE grid integration compliance. ACC should expand Dunkirk capacity for prismatic cell output before import reliance widens. Blue Solutions must accelerate ANSM certification timelines for solid-state tunnel applications ahead of Lyon and Marseille pilot scale-up. Threat substitution from Asian cylindrical imports demands backward integration into cathode active material processing.
For New Entrants and Emerging Players: Midi-bus configurations for peripheral regional routes represent an underserved buyer archetype with slower procurement cycles and less consolidated specification authority than Île-de-France. Provence-Alpes-Côte d'Azur electrification lags Paris and Lyon, offering concentrated future demand for high-capacity articulated bus packs. Second-life stationary storage partnerships with CRE-grid-connected depot operators provide a go-to-market angle that sidesteps direct OEM competition.
For Investors and Strategic Acquirers: RATP's unbundled battery tender announcements are the leading indicator that procurement authority is shifting from fleet managers to energy storage specialists, reshaping vendor selection criteria toward electrochemical engineering depth. Long-term viability favors pack assemblers with thermal management integration capabilities and circular economy compliance infrastructure. Acquisition targets should demonstrate CRE certification track records and established technician training programs. Monitor ANSM solid-state transport battery approval timelines as the signal for chemistry-transition inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Adoption | ACC and pack assemblers compress module costs while meeting RATP swappable sub-pack specifications. |
| Solid-State Certification Investment | Blue Solutions targets ANSM approval for tunnel-operated Lyon routes before lithium-ion displacement accelerates. |
| Backward Integration into Cathode Materials | French assemblers reduce China and South Korea supply concentration for nickel-manganese-cobalt precursors. |
| Second-Life Storage Partnerships | Decommissioned bus batteries cascade into CRE-grid stabilization assets, capturing circular economy value. |
| Depot Fast Charging Infrastructure Scale-Up | Transit operators integrate battery energy storage systems to manage CRE peak demand charge frameworks. |
Research Methodology
Regulatory filings from the Commission de Régulation de l'Énergie, ANSM transport safety submissions, and EU Battery Regulation compliance documentation formed the secondary backbone for supply chain and policy trajectory assessment. Primary interviews with RATP procurement directors, TCL Lyon fleet managers, Automotive Cells Company plant executives, and CRE grid integration officers validated demand assumptions and tariff impact scenarios. Bottom-up cell production forecasts from ACC's Dunkirk facility were triangulated against top-down municipal electrification schedules mandated under the LOM law.
Bottom-up modeling of pack deployment by bus model, charging technology, and regional transit authority was cross-referenced against top-down national diesel phase-out targets. Segmentation dimensions included battery chemistry architecture, vehicle configuration class, infrastructure investment profile, and end-user procurement authority structure. CAGRs were derived from fitted growth curves applied to RATP's disclosed electrification timeline and regional authority fleet conversion commitments. Industry-specific inputs incorporated CRE tariff revision schedules and EU Battery Regulation compliance deadline effects on sourcing decisions.
Revisions become necessary when lithium raw material supply disruptions, CRE peak demand charge framework modifications, or ANSM solid-state certification timeline extensions materialize across the analysis window. Forecasts reflect documented assumptions regarding ACC capacity ramp schedules and municipal procurement calendar adherence to LOM mandates. Practitioners should monitor cathode active material spot price movements and CRE grid connection standard updates for early signals of cost structure or infrastructure economics shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Denmark Solar E-Bike Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
E-Axle Market
Electric Vehicles
France Electric Vehicle Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
Electric Vehicle Power Control Unit Market