
 Electric Vehicle Heating System Market | 2026-2036
Electric Vehicle Heating System Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Heating System Market Insights
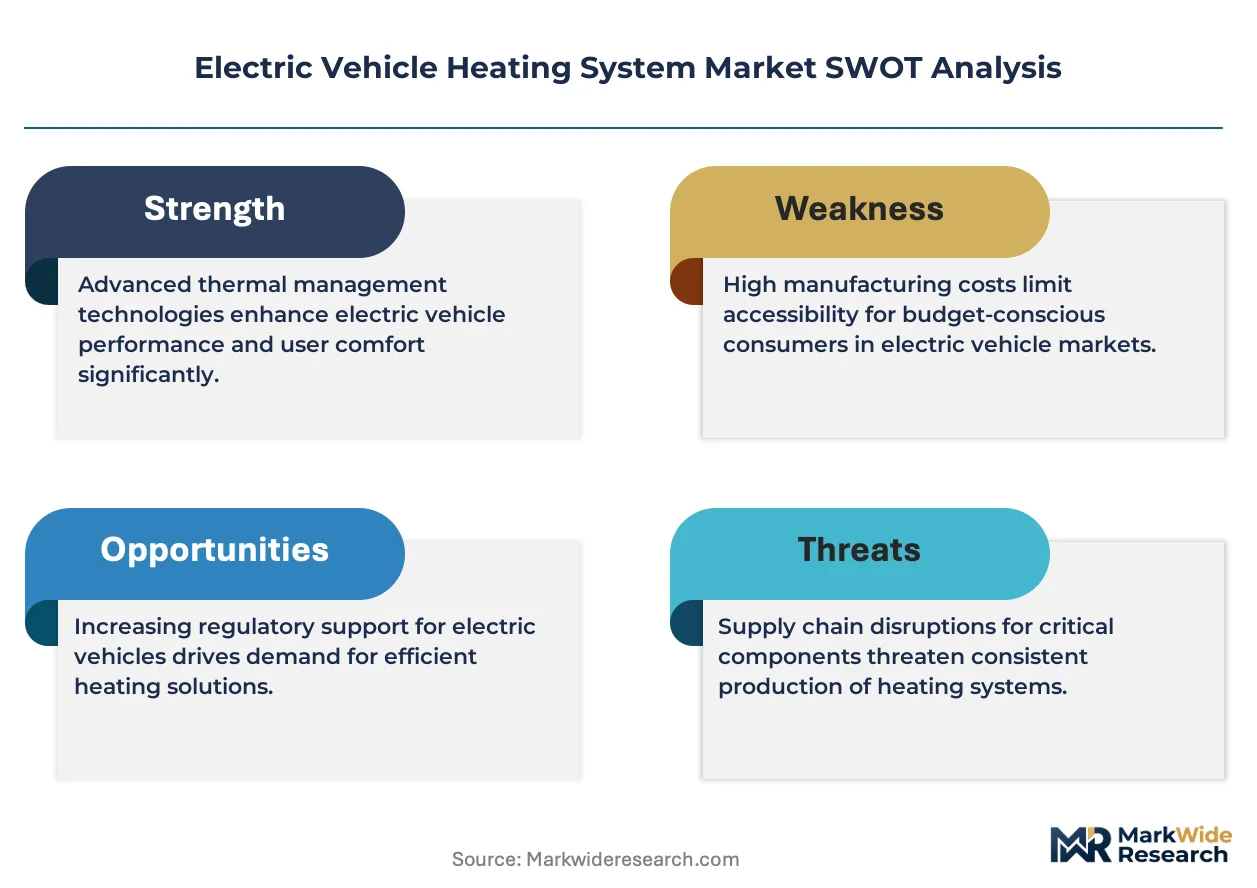
The EU F-Gas Regulation is recalibrating the cost-of-entry calculus for European suppliers of electric vehicle heating systems. Denso Corporation leverages its integrated powertrain thermal management portfolio to compete across multiple vehicle platforms. Valeo SA anchors its position through specialized heat pump systems engineered for extended-range electric vehicles. MAHLE GmbH differentiates via R&D intensity in liquid heating circuits that optimize battery preconditioning efficiency.
Electric vehicle heating systems comprise thermal management assemblies designed to regulate cabin comfort and battery operating temperatures, typically incorporating heat pumps with coefficient-of-performance ratings above two, positive-temperature-coefficient ceramic elements, or resistive wire grids with rapid-response characteristics. These systems serve the primary commercial purpose of minimizing range degradation caused by climate control loads in battery electric drivetrains. Heat pump technology leads installed value across premium passenger vehicle platforms, while PTC heater configurations retain cost advantages in compact two-wheeler and entry-level bus applications where system complexity must stay constrained. Liquid heating segments command concentrated margin pools given their integration with battery thermal management loops and the precision control requirements of high-voltage architectures.
The EPA tailpipe emission standards and NHTSA fuel economy mandates in the United States accelerate electrification timelines that expand addressable demand for efficient heating systems. EMA and REACH frameworks in Europe enforce material restrictions and chemical safety protocols that constrain refrigerant selections and solder compositions in heat pump manufacturing. Stakeholders must monitor regulatory divergence between refrigerant phase-down schedules and battery thermal runaway testing protocols to align product development roadmaps with divergent compliance timelines.
Market Dynamics
The EU F-Gas Regulation's refrigerant phase-down timeline is compressing product development cycles and forcing heat pump architecture redesigns across supplier portfolios. Battery preconditioning requirements in cold climates are pulling thermal management systems deeper into high-voltage architectures, reshaping component integration patterns and procurement specifications.
Growth Catalysts
- EPA tailpipe standards:NHTSA fuel economy mandates accelerate electrification timelines in the United States, expanding installed base for efficient cabin heating systems in battery electric passenger vehicles.
- Heat pump coefficient-of-performance gains:Coefficient-of-performance ratings above two in integrated thermal systems reduce range degradation penalties, improving consumer acceptance in Nordic and Canadian markets.
- China manufacturing concentration:Domestic production of PTC heating elements and control modules concentrates supply chain advantages for cost-optimized compact vehicle platforms.
Market Restraints
- Copper and rare earth price volatility:Magnet materials and conductive elements in heat pump compressors face input cost instability that compresses margin pools for system integrators.
- Refrigerant supply concentration:High-GWP refrigerant phase-down restrictions under REACH and F-Gas frameworks constrain formulation options and extend qualification timelines for new heat pump designs.
- PTC efficiency ceiling:Resistive ceramic heating elements carry coefficient-of-performance near unity, limiting their viability in extended-range electric vehicles where thermal efficiency directly impacts battery range.
Strategic Opportunities
- India two-wheeler electrification:Entry-level electric scooters and motorcycles present unserved demand for compact PTC heater modules where system complexity must stay constrained and cost thresholds remain aggressive.
- Battery thermal loop convergence:Liquid heating circuits that precondition battery packs while conditioning cabin air create integrated value propositions for premium passenger vehicle platforms.
- US Inflation Reduction Act incentives:Domestic content requirements and clean vehicle tax credits are reshaping sourcing strategies for North American thermal system assembly operations.
Industry Challenges
- Refrigerant chemistry expertise scarcity:Low-GWP refrigerant handling and system optimization require specialized thermal engineering capabilities that outpace current workforce development pipelines.
- High-voltage safety certification timelines:IEC and ISO standards for thermal runaway propagation testing extend product validation cycles, delaying platform launches for integrated heating architectures.
- Legacy HVAC supplier integration friction:Established climate control manufacturers face capability gaps in battery thermal management software and high-voltage control electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Heating System Market |
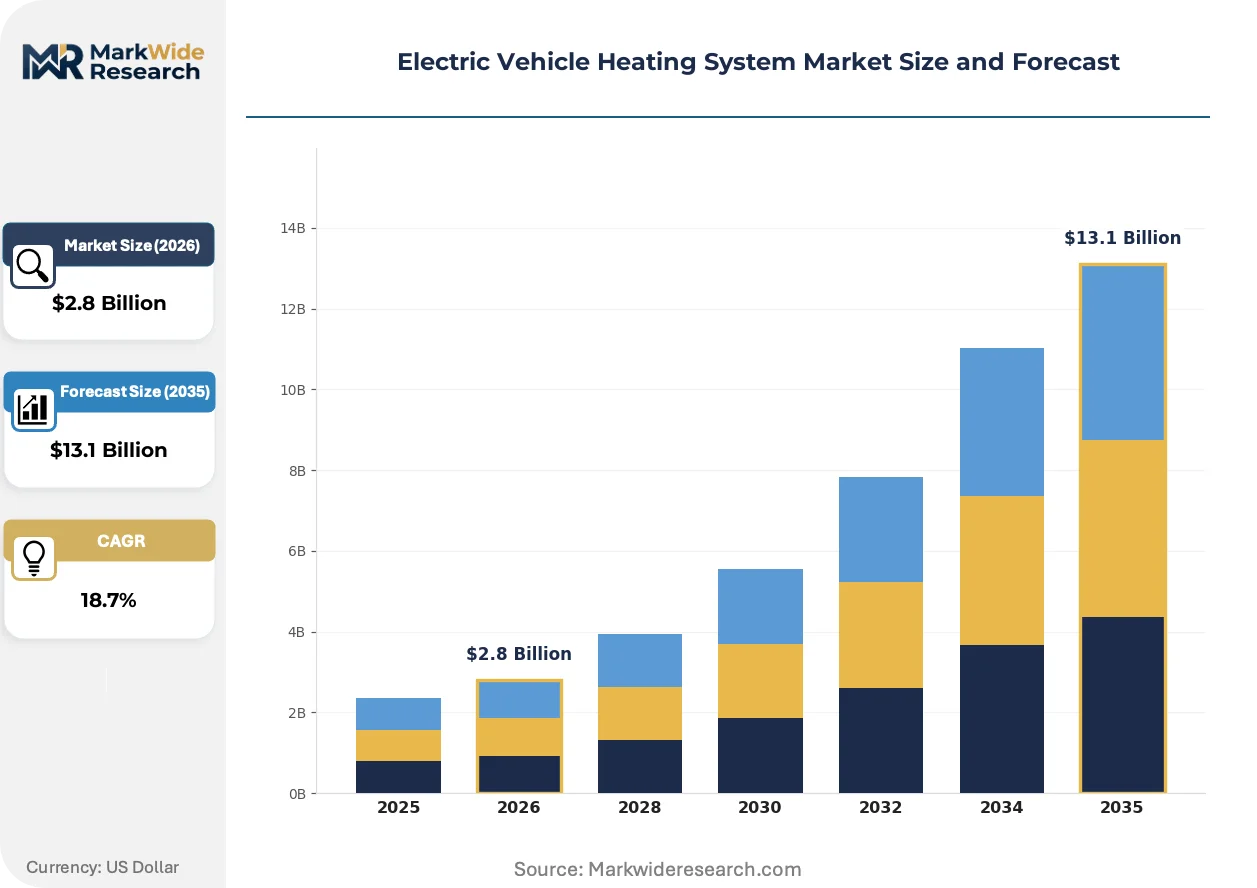
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.1 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Heat Pump, PTC Heater, Resistive Heater, Liquid Heating Component Type: Heating Element, Control Unit, Fan, Cooling System End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Installation Type: Integrated, Retrofit, Modular, Standalone |
| Companies Covered | Denso Corporation, Valeo SA, Hanon Systems, MAHLE GmbH, Robert Bosch GmbH, BorgWarner Inc., Continental AG, Gentherm Incorporated, Webasto SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Heating System Market Trends and Innovations
Heat pump system architectures are fragmenting into modular sub-assemblies that separate compressor, heat exchanger, and control electronics into independently serviceable units. This decomposition pattern is compressing supplier qualification barriers and enabling platform-specific customization without full system redesign.
Refrigerant circuit design is modularizing around swappable compressor and expansion valve configurations that accommodate multiple refrigerant chemistries within common chassis footprints. Tier 1 suppliers in Germany and Japan are adopting these flexible architectures to hedge against regulatory uncertainty in refrigerant phase-down schedules. The approach compresses retooling costs when F-Gas or REACH restrictions force formulation pivots.
EMA and ECHA frameworks are tightening material restrictions on solder compositions and flame-retardant additives in heat pump electronics housings. Manufacturers serving European OEMs are substituting traditional tin-lead connections with silver-sintered alternatives and reformulating potting compounds to eliminate restricted halogenated compounds. Premium passenger vehicle platforms absorb these cost premiums most readily, while compact vehicle segments delay compliance-driven redesigns.
Fleet operators and leasing companies are unbundling thermal system maintenance from vehicle procurement, creating standalone service contracts for heat pump refurbishment and refrigerant recovery. This pattern concentrates aftermarket demand in urban logistics hubs and taxi fleet depots where utilization rates accelerate component degradation. Germany and the Netherlands show the earliest adoption of this procurement model among commercial electric van operators.
Electric Vehicle Heating System Market Segmentation
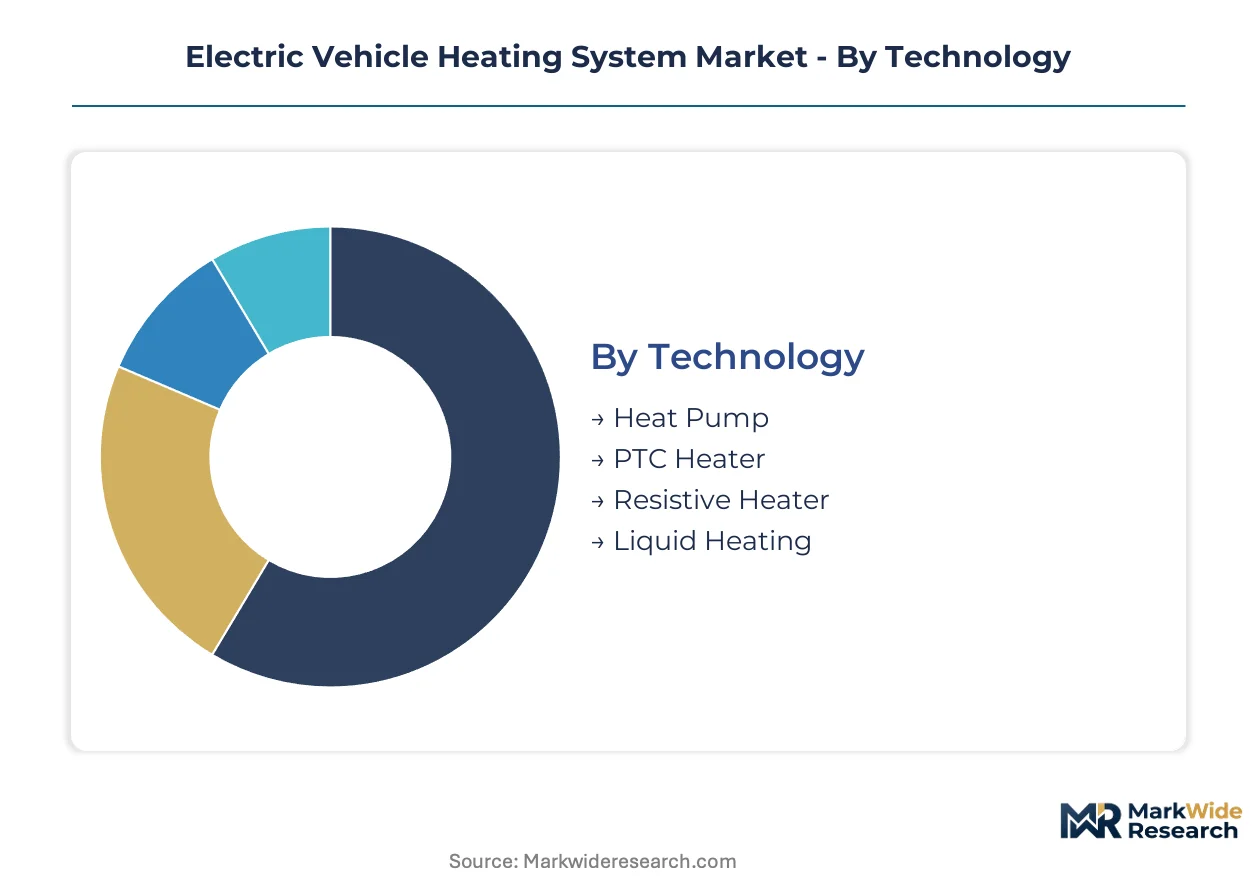
Technology choices in electric vehicle heating systems cascade through component procurement, installation complexity, and end-use viability. Segment boundaries shift as battery architectures converge with cabin thermal loops and refrigerant regulations force architectural pivots.
Technology:
Customization intensity varies sharply across this category, from fully integrated heat pump systems requiring OEM co-development to drop-in resistive modules serving aftermarket channels.
- Heat Pump:Refrigerant-based systems achieve coefficient-of-performance ratings above two by harvesting ambient thermal energy. Premium passenger vehicle platforms in Germany and South Korea concentrate demand as cold-climate range preservation becomes a purchase determinant. EU F-Gas Regulation phase-down schedules force refrigerant chemistry pivots that extend supplier qualification timelines.
- PTC Heater:Ceramic positive-temperature-coefficient elements deliver rapid response without refrigerant handling complexity. Two-wheeler and entry-level bus manufacturers in India and Southeast Asia specify these modules where cost thresholds block heat pump adoption. Resistive efficiency near unity limits viability in extended-range battery electric vehicles.
- Resistive Heater:Wire-grid elements provide baseline cabin warming for compact vehicle platforms and aftermarket retrofit applications. Simplified control electronics reduce system integration risk for emerging OEMs.
- Liquid Heating:Glycol-based circuits precondition battery packs while conditioning cabin air through integrated heat exchangers. High-voltage architectures in North American and European premium platforms specify these systems for thermal runaway mitigation compliance.
Most installed capacity flows through PTC Heater configurations. Expansion is steepest in Heat Pump systems.
Component Type:
Margin distribution across this category tracks the divergence between commodity heating elements and software-intensive control units requiring functional safety certification.
- Heating Element:PTC ceramics and resistive wire grids constitute the core thermal conversion layer. Manufacturing concentrates in Chinese industrial clusters serving cost-optimized compact vehicle programs. Raw material exposure to rare earth price volatility compresses margin stability for non-integrated suppliers.
- Control Unit:High-voltage power electronics and thermal management software govern energy allocation between cabin and battery loops. ISO 26262 functional safety requirements and IEC thermal runaway testing protocols extend validation cycles. German and Japanese Tier 1 suppliers anchor development capacity.
- Fan:Blower assemblies move conditioned air through cabin distribution networks. Noise-vibration-harshness specifications differentiate premium from standard tier sourcing.
- Cooling System:Refrigerant compressors and expansion valves complete heat pump architectures. Low-GWP refrigerant compatibility requirements under REACH and F-Gas frameworks drive redesign frequency.
Control Unit procurement absorbs the largest share of system value. Heating Element volume is climbing the fastest.
End User:
Application scale spans single-occupancy two-wheelers through multi-ton commercial freight platforms, with thermal load profiles dictating technology selection.
- Passenger Vehicles:Battery electric sedans and SUVs specify integrated heat pump or liquid heating systems to minimize range degradation. Nordic and Canadian markets impose the most stringent cold-start performance requirements. OEMs in Germany, South Korea, and the United States lead platform deployment.
- Commercial Vehicles:Electric vans and light trucks require robust thermal systems for cargo area conditioning and driver cabin comfort. Fleet operators in the Netherlands and Germany are unbundling maintenance contracts to concentrate refurbishment demand in urban logistics hubs.
- Two-Wheelers:Electric scooters and motorcycles specify compact PTC modules where space constraints and cost thresholds exclude heat pump complexity. India's electrification push generates concentrated demand for entry-level thermal components.
- Buses:Electric transit and coach platforms deploy high-capacity heat pumps or hybrid thermal systems for passenger compartment conditioning. Municipal procurement specifications in France and the United Kingdom emphasize refrigerant environmental compliance.
Passenger Vehicles channel the dominant share of installed value. Two-Wheelers are gaining share fastest.
Installation Type:
Supply chain configuration ranges from factory-integrated systems requiring OEM line-fit coordination to aftermarket modules serving vehicle modification specialists.
- Integrated:Thermal systems engineered for specific vehicle platforms during original design phases. Battery preconditioning loops and cabin distribution networks are co-optimized with high-voltage architectures. German and Japanese OEMs specify these configurations for premium battery electric platforms.
- Retrofit:Aftermarket heating modules installed in converted internal combustion vehicles or thermal system replacements. Installation complexity limits addressable volume to specialized conversion shops and fleet refurbishment operations.
- Modular:Sub-assembly components that separate compressor, heat exchanger, and control electronics into independently serviceable units. Tier 1 suppliers in Germany and Japan are adopting these architectures to compress qualification barriers and enable platform-specific customization.
- Standalone:Self-contained heating units for auxiliary applications or specialized commercial equipment. Limited penetration in mainstream passenger vehicle markets.
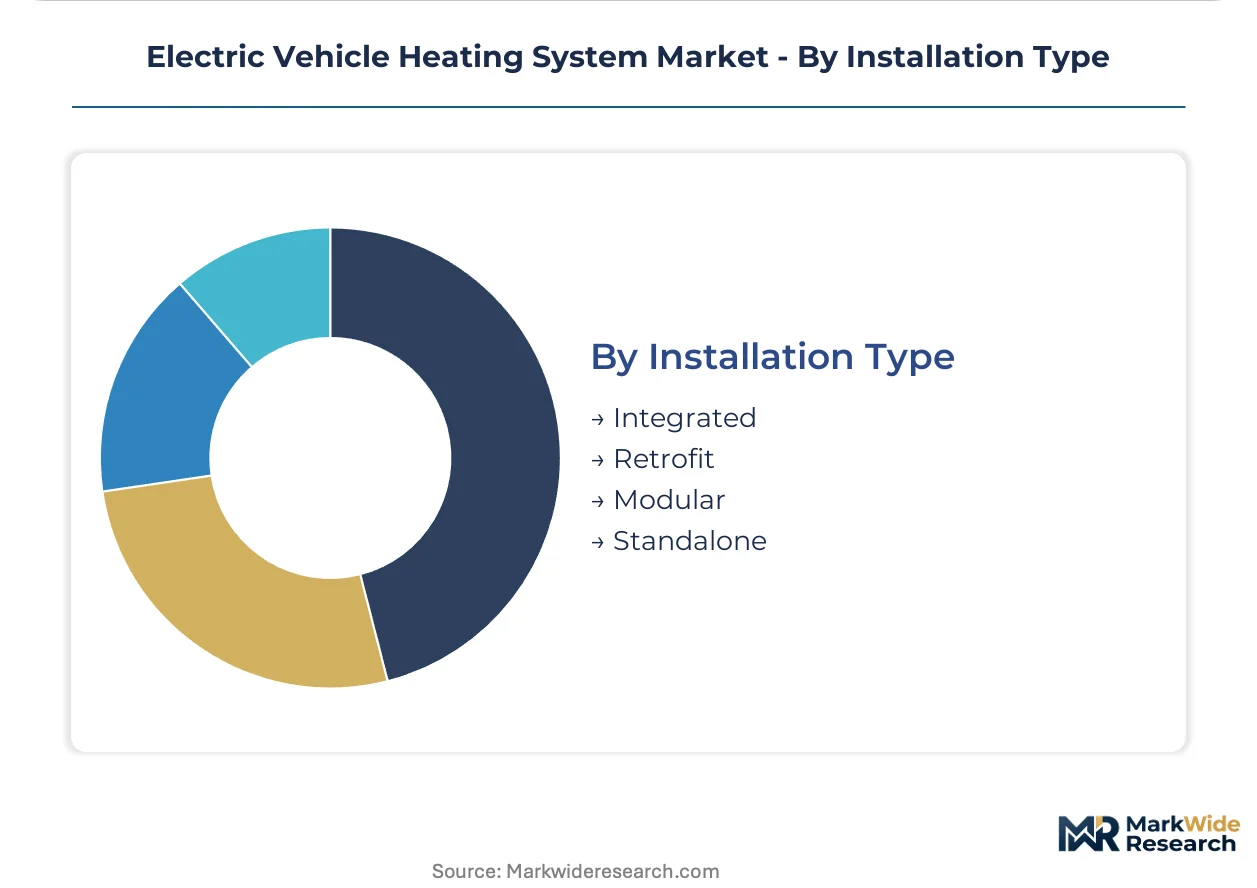
Integrated systems dominate production volume. Modular configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal engineering talent clusters in Germany's automotive belt and China's eastern manufacturing corridor anchor global production capacity for electric vehicle heating systems.
China
Domestic OEMs and battery manufacturers drive concentrated demand for PTC heating elements and control modules. The Ministry of Industry and Information Technology enforces GB standards for high-voltage thermal system safety. Zhejiang and Jiangsu provinces host dense supplier ecosystems serving cost-optimized compact vehicle platforms.
Germany
Premium passenger vehicle manufacturers specify integrated heat pump systems for cold-climate range preservation. The KBA enforces type approval protocols aligned with EU F-Gas Regulation phase-down schedules. Stuttgart and Munich metropolitan areas concentrate Tier 1 development centers for refrigerant-compatible compressor architectures.
United States
Domestic content requirements under the Inflation Reduction Act reshape sourcing strategies for North American thermal system assembly. EPA tailpipe standards and NHTSA fuel economy mandates accelerate electrification timelines. Michigan and Ohio industrial corridors anchor heat pump manufacturing investments serving Detroit Three OEM platforms.
South Korea
Battery electric vehicle exports to Nordic markets impose stringent cabin heating performance specifications. The Ministry of Trade, Industry and Energy coordinates national hydrogen and electrification roadmaps affecting thermal system R&D priorities. Gyeonggi-do province hosts concentrated supplier engineering centers co-located with domestic OEM headquarters.
India
Two-wheeler electrification generates unserved demand for compact PTC heater modules where cost thresholds exclude heat pump complexity. The Bureau of Indian Standards develops safety protocols for high-voltage thermal components in emerging vehicle categories. Tamil Nadu and Gujarat manufacturing corridors attract component suppliers targeting entry-level electric scooter platforms.
Electric Vehicle Heating System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers in the electric vehicle heating system market. The supplier base organizes around three strategic archetypes: integrated thermal management conglomerates with powertrain portfolios, specialized HVAC component manufacturers, and emerging pure-play battery thermal specialists. Consolidation pressure intensifies as refrigerant regulations force architecture redesigns and high-voltage safety certification requirements raise barriers to entry. Dominant competitive moves include strategic partnerships for refrigerant chemistry expertise and geographic expansion to capture India two-wheeler electrification demand.
Within the integrated conglomerate tier, Denso Corporation and Valeo SA exemplify archetypes combining climate control heritage with electrification-focused R&D investments. MAHLE GmbH occupies a position among specialized component manufacturers emphasizing liquid heating circuit development. These three anchors represent distinct strategic postures: full-system integration versus component specialization versus battery-cabin thermal loop convergence.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo SA |
| Hanon Systems |
| MAHLE GmbH |
| Robert Bosch GmbH |
| BorgWarner Inc. |
| Continental AG |
| Gentherm Incorporated |
| Webasto SE |
| Others |
Pricing and Supply Chain Analysis
Captive integration into PTC ceramic manufacturing anchors Chinese suppliers' cost position while compressing margin pools for European heat pump specialists facing refrigerant redesign cycles. This structural divergence between resistive and refrigerant-based architectures shapes how tiered pricing separates integrated conglomerates from component-dependent specialists across premium and economy vehicle platforms.
Pricing Analysis
Bundled maintenance contracts for fleet heat pump refurbishment coexist with transactional per-unit sales for OEM line-fit systems. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade for IEC thermal runaway compliance and volume scale for platform-specific procurement. Cost compression in PTC heater modules is intensifying because China's manufacturing concentration feeds aggressive cost thresholds for two-wheeler electrification. Entry-level electric scooter OEMs in India exhibit highest price sensitivity, while German premium passenger vehicle manufacturers absorb refrigerant chemistry transition premiums most readily.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and South Korean passenger vehicle manufacturers, while aftermarket distributors serve fleet refurbishment operations in the Netherlands and Germany. Manufacturing concentrates in China for PTC elements and control modules, Germany for refrigerant-compatible compressor architectures, and Japan for high-voltage power electronics. Rare earth magnet materials and copper conductive elements draw from concentrated mining jurisdictions, creating input cost instability. Single-source vulnerability in low-GWP refrigerant formulations under REACH and F-Gas restrictions threatens qualification timelines for heat pump redesigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's phasedown timeline compounds demand for compliant thermal architectures, accelerating supplier consolidation around refrigerant chemistry capabilities.
For Market Incumbents: Deepen backward integration into refrigerant handling and system optimization capabilities to offset emerging pure-play battery thermal specialists. Secure captive supply of PTC ceramics through Chinese manufacturing partnerships. Invest in ISO 26262 functional safety certification for control electronics to defend margin position against software-capable entrants. For New Entrants and Emerging Players: Begin with compact PTC heater modules for India's two-wheeler electrification wave, where cost thresholds exclude heat pump complexity and incumbent presence remains thin. Target Tamil Nadu and Gujarat manufacturing corridors for component assembly partnerships. Pursue white-label supply contracts with domestic scooter OEMs as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for specialized HVAC component manufacturers because refrigerant regulations force architecture redesigns that outpace organic R&D timelines for mid-cap suppliers. Focus acquisition screening on liquid heating circuit specialists with battery preconditioning IP and existing OEM validation. Watch for inflection when EU F-Gas phase-down schedules compress supplier qualification windows beyond 18-month development cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Partnership | Secures low-GWP formulation access ahead of REACH phase-down deadlines. |
| Battery Thermal Loop Integration | Combines cabin conditioning with preconditioning for high-voltage architectures. |
| India Manufacturing Footprint | Captures two-wheeler PTC demand through Tamil Nadu supplier clusters. |
| Modular Sub-Assembly Architecture | Separates compressor and control electronics for platform-specific customization. |
| Fleet Service Contract Unbundling | Concentrates aftermarket refurbishment demand in urban logistics hubs. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and thermal system R&D directors grounded qualitative findings. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and customs records for PTC element trade flows. Bottom-up and top-down triangulation reconciled component-level procurement patterns with platform-level installation estimates.
Segmented outputs across the projection horizon reflect technology-type splits between heat pump, PTC, resistive, and liquid heating configurations; component-type disaggregation into heating elements, control units, fans, and cooling systems; and end-user stratification across passenger vehicles, commercial vehicles, two-wheelers, and buses. CAGRs were derived from installed base modeling tied to battery electric vehicle production forecasts and content-per-vehicle assumptions for thermal system value. Refrigerant phase-down schedules and high-voltage safety certification timelines served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential acceleration of EU F-Gas restrictions, breakthrough solid-state battery thermal profiles, and trade policy shifts affecting rare earth magnet supply. Forecasts reflect documented assumptions about regulatory adherence and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Vietnam Electric Vehicle Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Electric Two Wheelers MRO Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Japan Electric Vehicle Market
Electric Vehicles
Compact E-Scooter Market