
 India Electric Vehicle Market | 2026-2036
India Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Vehicle Market Outlook
Battery-as-a-service unbundling is repositioning ownership economics for two-wheeler and three-wheeler buyers who previously faced high upfront costs. Tata Motors leverages its captive cell assembly partnerships to control battery supply for passenger electric vehicles. Mahindra & Mahindra anchors its farm-to-mobility heritage in rural commercial EV deployment. Ola Electric dominates the two-wheeler segment through vertically integrated cell manufacturing and direct-to-consumer channel control.
An electric vehicle integrates a traction motor, power electronics, and rechargeable energy storage to replace internal combustion propulsion, with lithium-ion battery packs typically delivering 150-400 watt-hours per kilogram depending on cathode chemistry and thermal management architecture. The India Electric Vehicle Market segments across vehicle type where two-wheelers lead unit volumes due to urban commute replacement cycles, battery type where lithium-ion chemistry captures the dominant margin pool despite lead-acid persistence in price-sensitive three-wheelers, and charging type where battery swap infrastructure is growing fastest for commercial fleet applications with high utilization requirements.
The Ministry of Heavy Industries administers FAME subsidy disbursement while the Bureau of Indian Standards certifies charging connector and battery safety protocols, and the Central Electricity Authority regulates grid interconnection standards for charging stations. These frameworks collectively determine which products qualify for incentives, what safety thresholds manufacturers must meet, and where infrastructure capital deploys. Stakeholders must track how BIS evolves cell-to-pack testing standards and whether state electricity regulators accelerate time-of-use tariffs for commercial charging.
Market Dynamics
Total cost of ownership compression through PLI scheme subsidies and FAME-II disbursement is restructuring purchase economics across passenger and commercial segments, pulling forward electrification timelines for fleet operators previously deterred by battery capital intensity.
Growth Catalysts
- FAME-II subsidy architecture:The Ministry of Heavy Industries incentive structure reduces upfront acquisition costs for electric two-wheelers and three-wheelers, expanding addressable demand into price-sensitive urban commuter segments.
- Commercial fleet electrification:Logistics operators and last-mile delivery aggregators are deploying electric three-wheelers at scale to exploit lower per-kilometer operating costs versus compressed natural gas alternatives.
- Lithium-ion cell localization:PLI scheme allocations for advanced chemistry cell manufacturing are building domestic cathode and electrolyte supply capacity, reducing import dependency for battery pack assembly.
Market Restraints
- Critical mineral import concentration:Cobalt and lithium refining capacity concentrates in Chinese and Congolese processing facilities, exposing Indian cell manufacturers to geopolitical supply disruptions and price volatility.
- Charging infrastructure gap:Public fast-charging station density remains below threshold levels in Uttar Pradesh, Bihar, and Rajasthan, constraining inter-city electric passenger vehicle viability.
- Grid stability limitations:Distribution transformer capacity in Tier-2 and Tier-3 urban clusters cannot absorb simultaneous fast-charging loads from commercial fleets without capital-intensive network upgrades.
Strategic Opportunities
- Battery-as-a-service commercialization:Decoupling battery asset ownership from vehicle purchase is opening subscription-based financing models for two-wheeler buyers in Tamil Nadu and Telangana.
- State-level EV policy arbitrage:Gujarat and Karnataka road tax exemptions and registration fee waivers are creating demand concentration corridors that infrastructure capital can target with predictive deployment.
- Second-life battery storage:Retired electric vehicle battery packs are integrating into stationary energy storage applications for telecom towers and commercial buildings, extending asset value capture.
Industry Challenges
- Cell-to-pack thermal management certification:BIS testing protocols for nail penetration and thermal runaway propagation remain under development, delaying product launch timelines for new market entrants.
- Power electronics talent scarcity:Domestic engineering programs produce insufficient specialists in motor control algorithms and wide-bandgap semiconductor integration, forcing reliance on expatriate technical leadership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Vehicle Market |
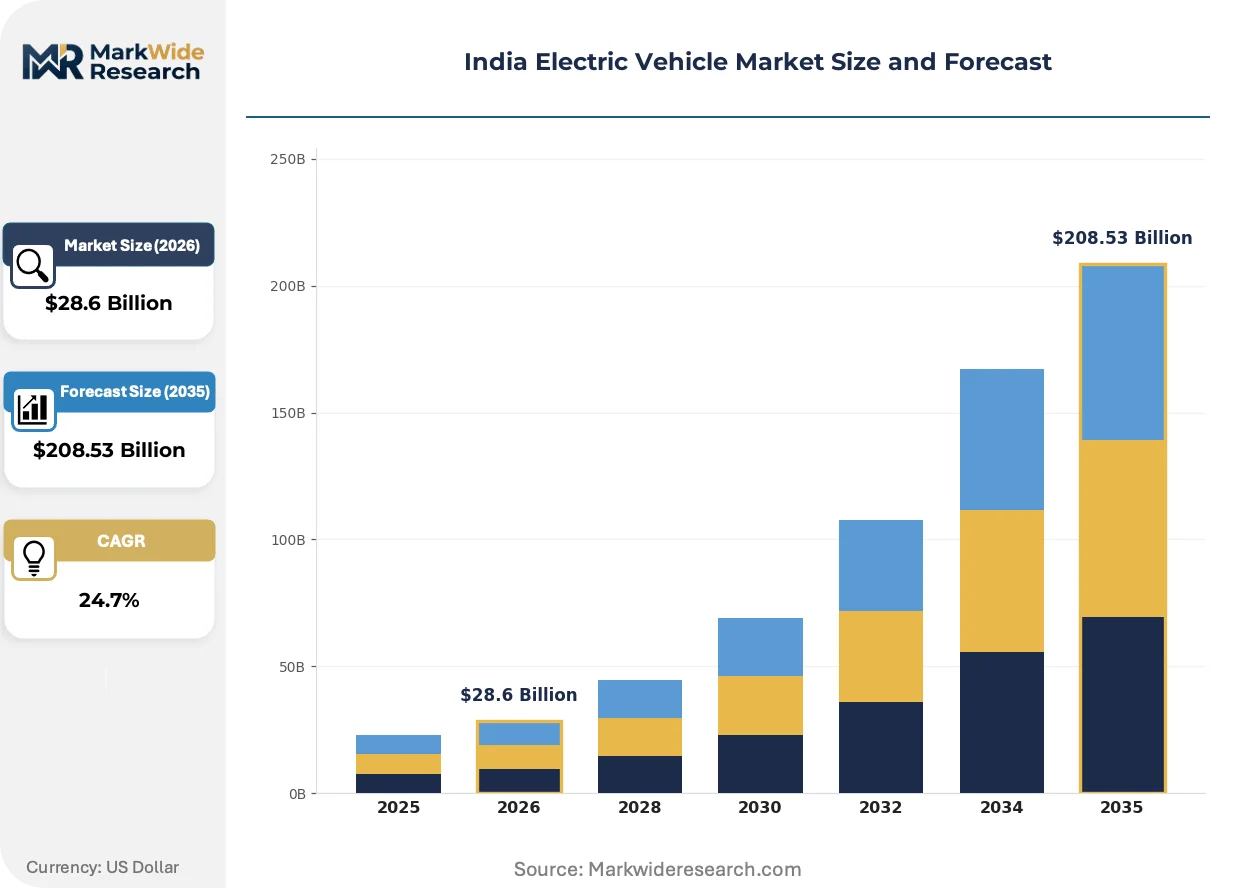
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $208.53 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Two-Wheelers, Three-Wheelers, Passenger Cars, Commercial Vehicles Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid State Charging Type: Fast Charging, Standard Charging, Wireless Charging, Battery Swap End User: Individual Consumers, Businesses, Government, Fleet Operators |
| Companies Covered | Tata Motors, Mahindra & Mahindra, Ola Electric, Ather Energy, Hero Electric, TVS Motor Company, Bajaj Auto, MG Motor India, BYD India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Vehicle Market Strategic Shifts
Electrification is penetrating beyond early adopter segments into mass-market replacement cycles, with technology convergence and policy calibration reshaping how vehicles are financed, serviced, and integrated with energy infrastructure.
Silicon carbide power electronics is integrating into traction inverters and onboard chargers, enabling higher switching frequencies that reduce thermal management mass and extend driving range per kilowatt-hour. Premium passenger electric vehicle platforms are adopting these wide-bandgap semiconductors first, with component suppliers scaling foundry capacity to serve mid-segment models. The technology is integrating cost structures downward as domestic packaging capabilities mature.
The PLI scheme for automotive and auto components is mandating minimum domestic value addition thresholds for incentive eligibility, forcing battery pack assemblers to localize cell management systems and thermal interface materials. This industrial policy is compressing import bill exposure while building supplier ecosystems around Chennai and Pune manufacturing clusters. Passenger vehicle original equipment manufacturers are responding by restructuring procurement contracts to qualify for subsidy tranches.
Fleet operators are consolidating vehicle procurement around total cost of ownership metrics rather than capital expenditure minimization, shifting evaluation frameworks toward residual value guarantees and energy cost predictability. This buying pattern is disintermediating traditional dealer networks in favor of direct manufacturer relationships with embedded service contracts. The transformation is most visible in Bengaluru and Hyderabad logistics corridors where electric three-wheeler deployment concentrates.
India Electric Vehicle Market Segmentation
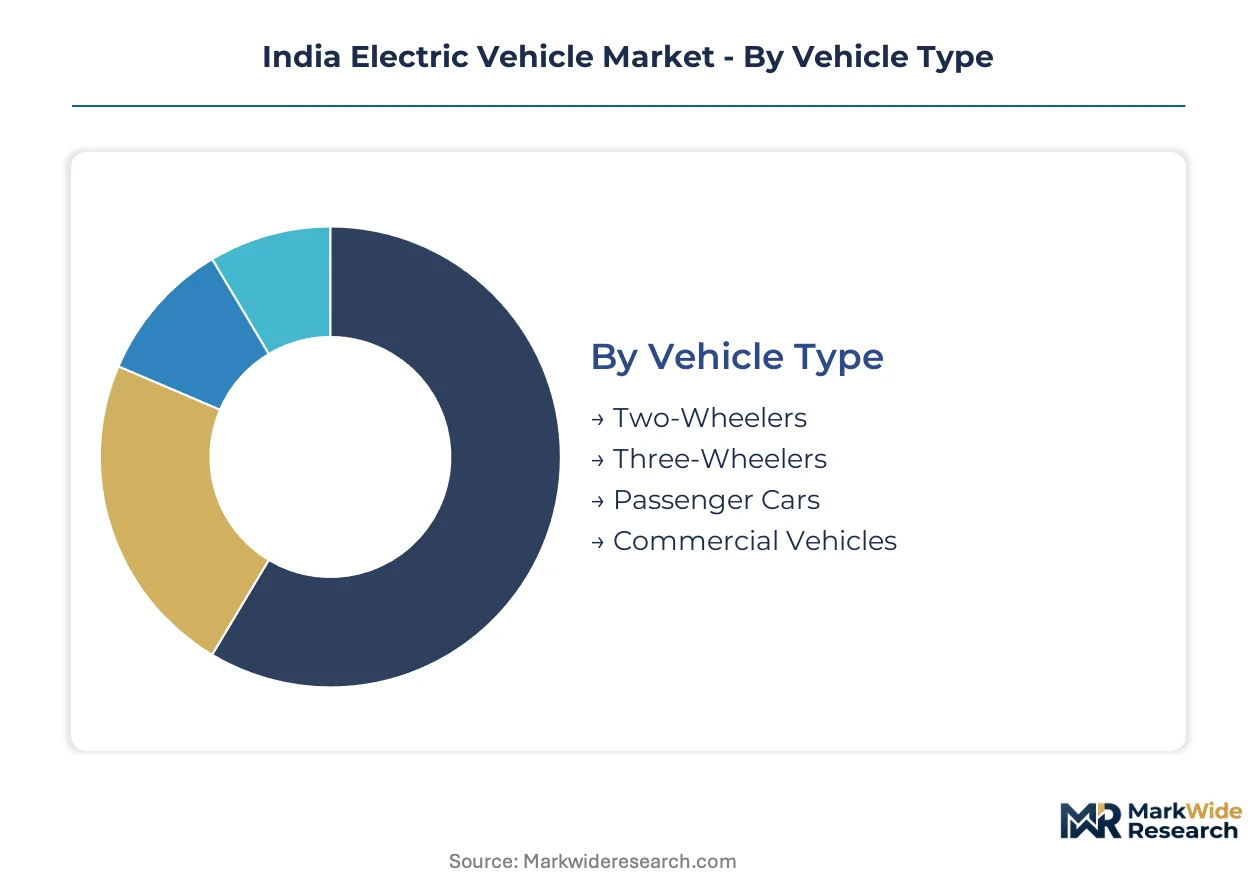
Segmentation reveals how electrification propagates unevenly across vehicle classes and use cases in India. Each dimension exposes distinct technology requirements, financing structures, and regulatory touchpoints that shape go-to-market strategy.
Vehicle Type:
Powertrain architecture and duty cycle requirements diverge sharply across vehicle classes, determining battery sizing, thermal management complexity, and infrastructure dependency.
- Two-Wheelers:Compact hub-mounted or mid-drive motors paired with 2-4 kWh lithium-ion packs dominate urban commute replacement. Maharashtra and Karnataka absorb the highest unit volumes where state-level registration incentives compress upfront costs below petrol equivalents.
- Three-Wheelers:L5 category cargo and passenger variants deploy fixed or swappable battery configurations optimized for 100-150 km daily duty cycles. Last-mile logistics operators in Bengaluru and Hyderabad corridors are electrifying fastest to exploit lower per-kilometer energy costs versus CNG.
- Passenger Cars:Skateboard platforms with 40-60 kWh packs and liquid-cooled thermal systems serve family mobility and premium fleet applications. Gujarat manufacturing clusters anchor domestic assembly capacity for compact SUV and sedan formats.
- Commercial Vehicles:Heavy-duty bus and truck segments require 200+ kWh pack architectures with active thermal management for inter-city routes. State transport undertakings in Delhi and Mumbai pilot depot-charged electric bus fleets under FAME-II procurement mandates.
Mature deployment sits with Two-Wheelers. Newer deployment is concentrated in Commercial Vehicles.
Battery Type:
Chemistry selection determines energy density, cycle life, and import dependency exposure for Indian cell assemblers qualifying under PLI scheme domestic value addition thresholds.
- Lithium-Ion:NMC and LFP cathode formulations deliver 150-180 Wh/kg cell-level energy density with 2,000-4,000 cycle lifespans. Tamil Nadu and Gujarat cathode active material plants are localizing precursor supply to reduce Chinese import concentration.
- Lead-Acid:Flooded and VRLA configurations persist in price-sensitive three-wheeler segments where total cost of ownership calculations favor lower capital expenditure over energy density. Uttar Pradesh and Bihar micro-entrepreneurs continue procuring lead-acid variants for short-radius cargo operations.
- Nickel-Metal Hydride:Mature chemistry with moderate energy density sees residual demand in hybrid vehicle applications and low-speed electric quadricycles. Limited new platform development targets this chemistry in Indian market configurations.
- Solid State:Ceramic or polymer electrolyte architectures promise 300+ Wh/kg density with inherent thermal stability advantages. Early pilot production from IIT-Madras incubated ventures targets two-wheeler and drone applications before automotive scale-up.
Volume concentration remains with Lithium-Ion. Technology migration is accelerating toward Solid State.
Charging Type:
Infrastructure topology selection reflects utilization intensity, dwell time economics, and grid interconnection capacity available at deployment locations.
- Fast Charging:50-150 kW DC systems with CCS2 or Bharat DC-001 connectors enable 30-60 minute recharge cycles for passenger vehicles. Maharashtra and Karnataka highway corridors are deploying fast-charging plazas at 100-kilometer intervals under state EV policy mandates.
- Standard Charging:3-7 kW AC wallbox or portable charger configurations serve overnight residential and workplace parking. Apartment complexes in Pune and Chennai are retrofitting parking infrastructure with load-managed AC distribution.
- Wireless Charging:Inductive pad systems with 85-93% transfer efficiency pilot at bus depots and premium residential installations. Limited commercial deployment due to capital intensity and alignment precision requirements.
- Battery Swap:Standardized pack exchange stations enable sub-3-minute energy replenishment for commercial two-wheeler and three-wheeler fleets. Sun Mobility and Bounce Infinity operate swap networks in Bengaluru and Delhi NCR targeting delivery aggregator vehicle pools.
Fast Charging dominates passenger vehicle infrastructure planning. Battery Swap is expanding most quickly in commercial fleet applications.
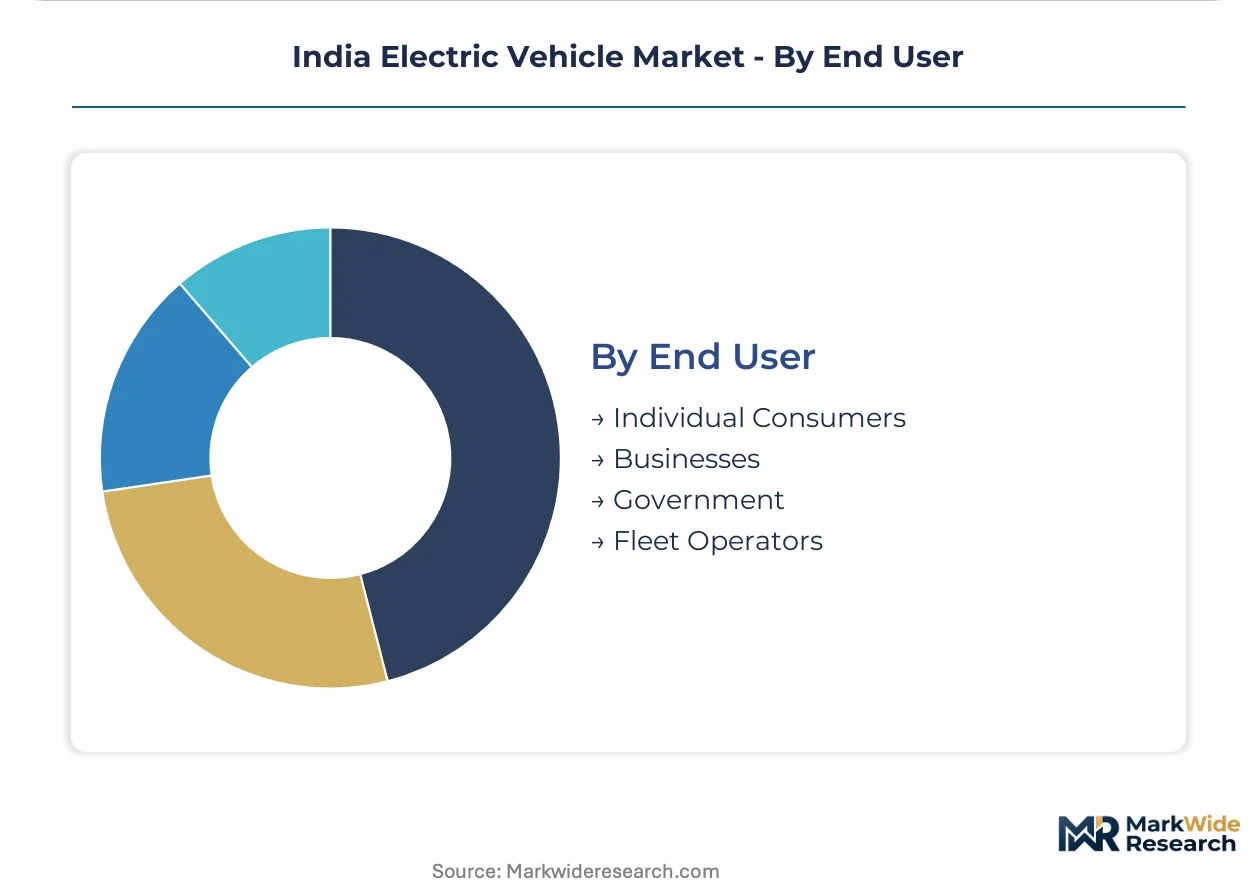
End User:
Procurement decision frameworks vary across buyer types, with total cost of ownership sensitivity, financing access, and residual risk allocation driving distinct contract structures.
- Individual Consumers:Retail buyers evaluate upfront subsidy-adjusted pricing, charging access at residence, and manufacturer warranty terms. Maharashtra and Gujarat urban households lead adoption where state road tax exemptions compound FAME-II benefits.
- Businesses:Corporate fleet and employee mobility programs procure through OEM direct sales with embedded service contracts. IT and consulting sector campuses in Hyderabad and Pune are electrifying shuttle and executive vehicle pools.
- Government:Central and state public sector undertakings follow GeM portal procurement guidelines with domestic content requirements. EESL aggregates demand for government officer vehicles and municipal service fleets.
- Fleet Operators:Logistics aggregators and last-mile delivery platforms negotiate volume procurement with battery-as-a-service unbundling. Zomato, Swiggy, and Amazon Flex partners in Delhi, Mumbai, and Bengaluru are deploying electric two-wheelers at thousand-unit scale with residual value guarantees from OEMs.
Individual Consumers anchor current unit volumes. Fleet Operators are gaining share fastest as electrification penetrates commercial mobility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in western and southern India while demand clusters in urban corridors with charging infrastructure and state-level incentives. This production-consumption geography shapes how OEMs configure distribution and service networks.
Maharashtra
Pune and Mumbai anchor passenger EV assembly and two-wheeler demand. The state electric vehicle policy extends road tax exemptions through 2025. Thane and Nagpur districts host fast-charging plaza deployment along Mumbai-Pune Expressway corridors.
Gujarat
Sanand and Vadodara manufacturing clusters supply lithium-ion packs to domestic OEMs. Registration fee waivers and capital subsidy schemes from the state energy department compress acquisition costs. Ahmedabad-Surat highway infrastructure attracts logistics fleet electrification pilots.
Karnataka
Bengaluru's technology workforce drives premium two-wheeler adoption and battery swap network deployment. The state EV policy mandates charging infrastructure in new commercial buildings. Hosur and Peenya industrial zones concentrate cell assembly and power electronics manufacturing.
Tamil Nadu
Chennai's automotive supplier ecosystem is localizing cathode active material production under PLI scheme incentives. State electricity regulatory provisions enable time-of-use tariffs for commercial charging stations. Sriperumbudur and Oragadam corridors host battery pack assembly joint ventures.
Delhi-NCR
The capital's air quality mandates accelerate bus fleet electrification and last-mile delivery vehicle replacement. FAME-II subsidy disbursement through the Ministry of Heavy Industries channels through designated dealerships. Gurugram and Noida logistics hubs concentrate electric three-wheeler deployment for e-commerce aggregators.
India Electric Vehicle Market Competitive Environment
The competitive structure tilts toward diversified automotive conglomerates with captive battery supply arrangements. Market concentration remains moderate with distinct tiering between volume manufacturers and emerging specialists. Two strategic archetypes dominate: legacy OEMs leveraging distribution depth and pure-play EV ventures controlling direct channels. Capacity expansion and backward integration into cell assembly represent the primary competitive vectors.
Within the diversified automotive tier, Tata Motors and Mahindra & Mahindra occupy positions shaped by decades of domestic market presence. Ola Electric exemplifies the vertically integrated specialist archetype. These three anchors illustrate how competitive positioning diverges between conglomerate resource deployment and venture-scale manufacturing control.
| Leading Market Players |
|---|
| Tata Motors |
| Mahindra & Mahindra |
| Ola Electric |
| Ather Energy |
| Hero Electric |
| TVS Motor Company |
| Bajaj Auto |
| MG Motor India |
| BYD India |
| Others |
Value Chain & Pricing Dynamics
Power electronics engineering talent clustering in Bengaluru and Pune feeds labor-cost differentials into pricing-tier spreads across passenger and commercial vehicle segments. PLI scheme domestic value addition thresholds compress import-heavy cost structures while FAME-II subsidies pull down consumer-facing price points in Maharashtra and Gujarat corridors.
Pricing Analysis
Cost-down pressure on mid-segment passenger vehicles accelerates because silicon carbide inverter adoption raises BOM complexity against lithium-ion pack localization gains. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled skateboard platforms from air-cooled compact formats and lead-acid three-wheeler configurations. Price differentiation hinges on thermal management sophistication and BIS certification tier for cell-to-pack safety protocols. Fleet operators in Bengaluru and Hyderabad corridors exhibit lowest price sensitivity due to TCO-based procurement frameworks, while individual two-wheeler buyers in Uttar Pradesh and Bihar remain most responsive to upfront subsidy-adjusted acquisition costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for lithium-ion cell supply, with cathode active material concentrating in China, South Korea, and Japan. Domestic pack assemblers draw from cobalt refining capacity in the Democratic Republic of Congo and lithium carbonate processing in Chile and Australia. Single-source vulnerability in electrolyte additive supply exposes Indian manufacturers to geopolitical disruption. Distribution runs through Tier 1 automotive supplier networks anchored in Chennai and Pune manufacturing clusters, with aftermarket service parts flowing through authorized dealership channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's electric vehicle market is consolidating around OEMs with captive battery supply and direct channel control, with PLI scheme qualification thresholds forcing weaker assemblers without domestic value addition capabilities toward exit or acquisition.
For Market Incumbents: Hedge against cobalt and lithium price volatility through long-term offtake agreements with Australian and Chilean mining ventures. Deepen backward integration into cell management system production in Tamil Nadu to secure PLI incentive tranches. Defend market position against pure-play EV entrants by locking fleet operator relationships through residual value guarantees and embedded service contracts in Delhi and Mumbai logistics corridors.
For New Entrants and Emerging Players: The price-point gap between premium passenger vehicles and economy two-wheelers opens white-space targeting for mid-segment electric three-wheeler configurations with swappable battery architecture. Target last-mile delivery aggregators in Hyderabad and Pune with battery-as-a-service subscription models that unbundle capital expenditure from operating budgets. Penetrate Gujarat and Karnataka state policy corridors where registration fee waivers compress customer acquisition costs below national benchmarks.
For Investors and Strategic Acquirers: The window for entry favors cell assembly specialists with BIS thermal runaway certification progress and established cathode precursor supply relationships. Five-to-ten-year viability hinges on PLI scheme renewal and FAME subsidy extension trajectories. Target acquisition archetypes include IIT-Madras incubated solid-state ventures and Tier 2 power electronics packaging shops in Bengaluru industrial zones. Watch for inflection signals in state electricity regulatory commission time-of-use tariff rulings for commercial charging infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Tata Motors' captive cell partnerships secure lithium-ion allocation ahead of PLI scheme qualification deadlines. |
| Charging Infrastructure Partnership | Sun Mobility's swap network expansion in Delhi NCR targets Zomato and Amazon Flex fleet density. |
| Platform Standardization | Mahindra's farm-to-mobility architecture reduces development overhead across rural commercial vehicle variants. |
| Software-Defined Vehicle Investment | Ola Electric's motor control algorithm development addresses domestic engineering talent scarcity in wide-bandgap semiconductors. |
| Geographic Manufacturing Footprint | Ather Energy's Hosur facility placement exploits Karnataka state EV policy charging infrastructure mandates. |
Study Parameters
Document review covered Ministry of Heavy Industries FAME-II disbursement records, Central Electricity Authority grid interconnection standards, and Bureau of Indian Standards cell-to-pack testing protocols, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, battery swap network operators, and state transport undertaking fleet managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs import records for lithium carbonate and cobalt, and PLI scheme applicant disclosures. Bottom-up unit volume estimates triangulated against top-down market value projections across vehicle class, propulsion architecture, and regional production cluster dimensions.
Unit shipment and value estimates across the analysis window reflect econometric modeling of subsidy elasticity, charging infrastructure density correlation, and fleet operator TCO sensitivity. Segmentation dimensions incorporated vehicle type, battery chemistry, charging topology, and end-user procurement framework. CAGRs derived from logistic diffusion curves fitted to state-level policy adoption timelines and manufacturing capacity buildout schedules. Industry-specific inputs included lithium-ion cell import dependency ratios, distribution transformer capacity utilization thresholds, and BIS certification pipeline velocities.
Inputs from Ministry of Heavy Industries subsidy disbursement databases and state electricity regulatory tariff filings were available through the study window; gaps in real-time commercial fleet utilization telemetry and second-life battery residual value trading data introduce uncertainty bands around commercial vehicle electrification velocity assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
Construction Electric Vehicle Market
Electric Vehicles
Silicone in Electric Vehicles Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
US Electric Bus Battery Pack Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
India Electric Car Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Electric Vehicle Insulation Market