
 Vehicle Solar Panel Market | 2026-2036
Vehicle Solar Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Solar Panel Market Insights
Perovskite-silicon tandem cell development is rewriting how vehicle-integrated photovoltaics achieve power density without weight penalties. Toyota Motor leverages its hybrid platform expertise to anchor solar roof deployment across passenger segments. Hyundai Motor Company competes through dedicated EV architectures that accommodate hood and roof photovoltaic arrays. BYD extends its battery-electric dominance into integrated panel systems for commercial fleet applications.
Vehicle solar panels are photovoltaic modules engineered with flexible or rigid substrates, typically rated between 50 and 300 watts, designed to harvest sunlight for auxiliary battery charging or direct drivetrain contribution. These systems employ monocrystalline or thin-film cells laminated onto curved automotive surfaces to extend electric range or power cabin electronics without depleting the main traction battery. Flexible panels lead commercial adoption due to conformal mounting on non-planar body panels, while integrated systems command premium positioning as OEMs embed photovoltaic layers during vehicle assembly. Thin-film technology sustains growth in applications where weight reduction outweighs absolute efficiency metrics.
The EPA tailpipe emission standards and NHTSA fuel economy regulations in the United States shape product development timelines by rewarding solar-assisted range extension as compliance credit. Japan's METI carbon neutrality roadmap and the EU Green Deal vehicle CO2 targets collectively push OEMs toward integrated energy harvesting systems. Fleet operators and component suppliers must monitor how dual carbon goals in China and evolving GB standards redefine module certification requirements for automotive photovoltaic deployment.
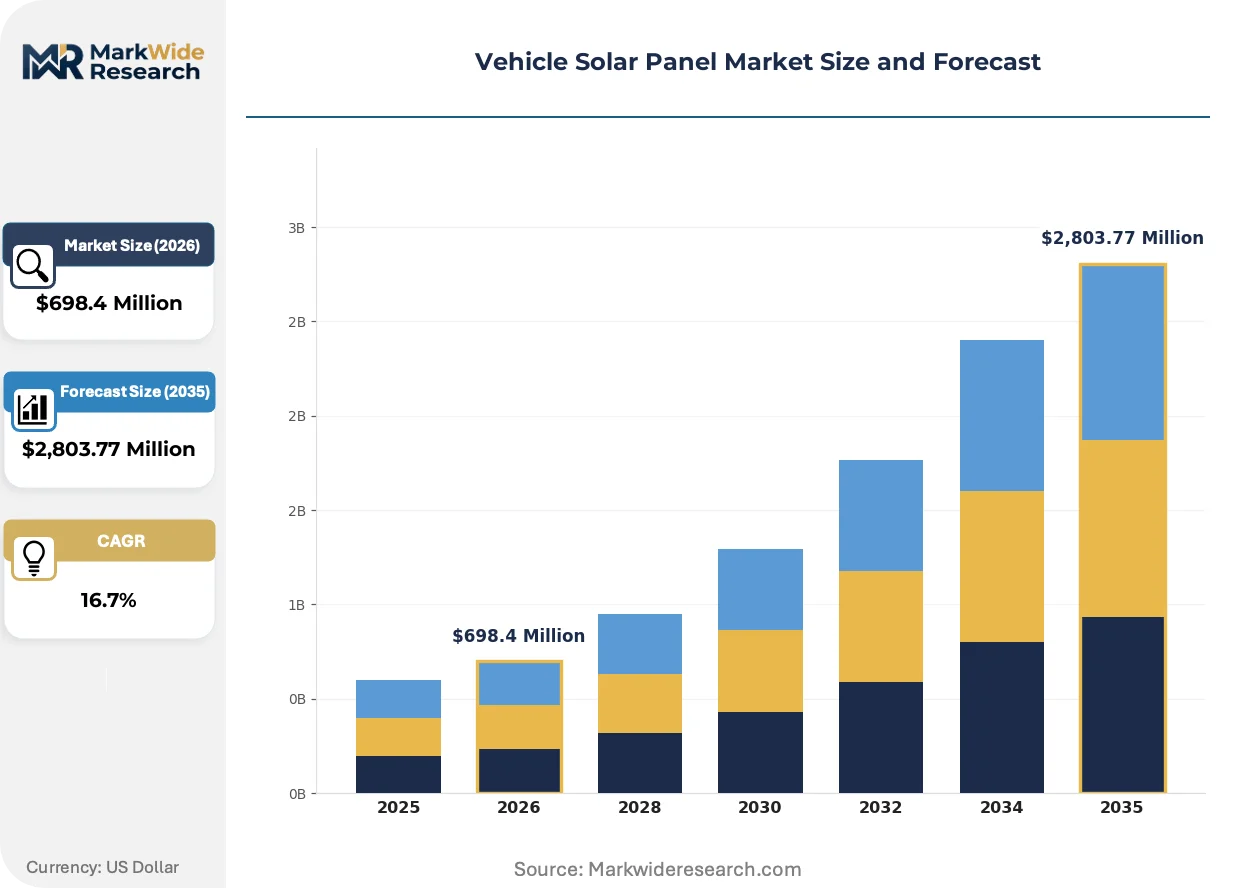
Market Dynamics
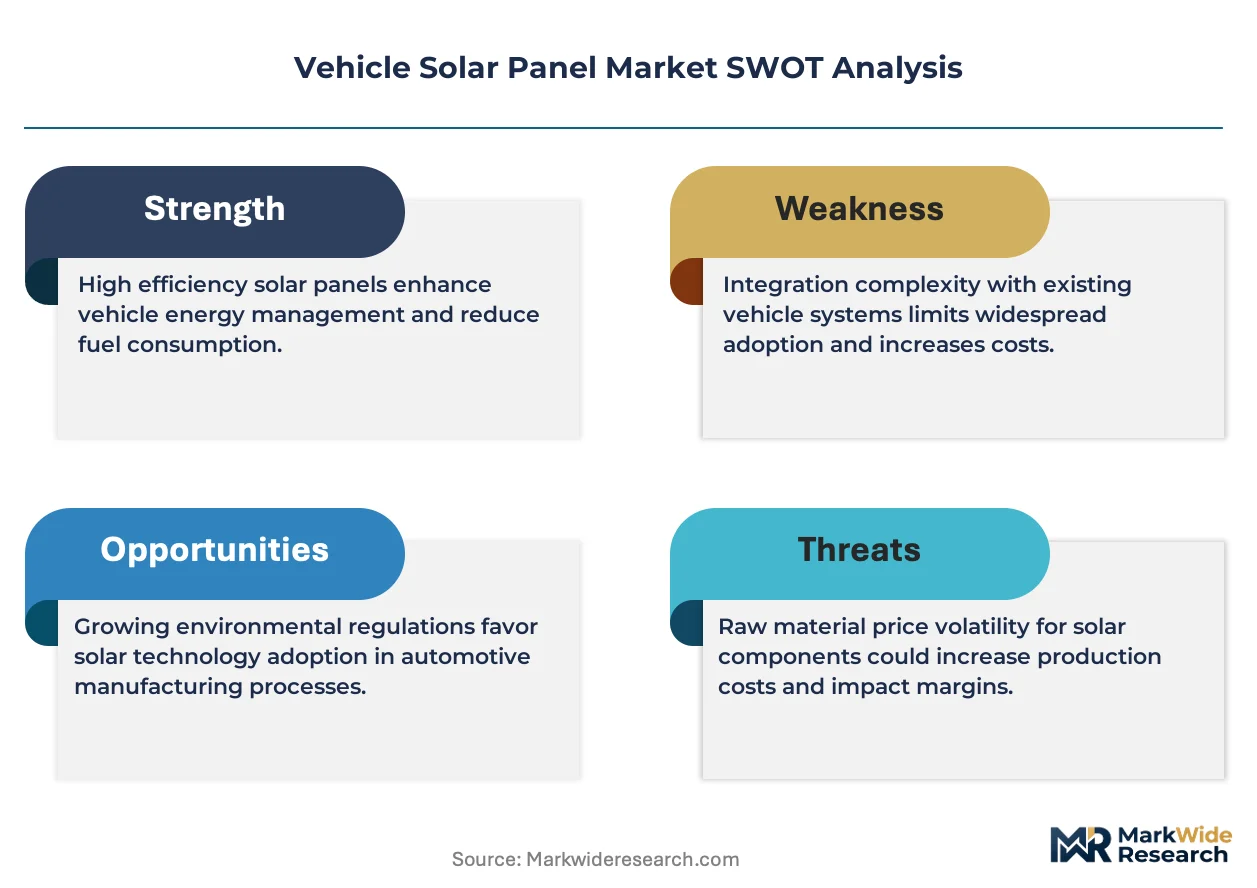
Perovskite-silicon tandem architectures are compressing module weight-to-power ratios below 1 kg per 150 watts, forcing OEMs to redesign body-in-white structures around embedded photovoltaics rather than retrofitting legacy platforms.
Growth Catalysts
- EU Green Deal CO2 mandates:Fleet-average emission targets below 95 g/km push manufacturers toward auxiliary solar charging to claim compliance credits without battery cost inflation.
- Commercial fleet electrification:Logistics operators in Germany and the United States deploy hood-integrated thin-film arrays to power refrigeration units and telematics without range sacrifice.
- Lightweight polymer substrates:Ethylene tetrafluoroethylene encapsulation reduces panel mass by 40% versus glass-glass laminates, enabling curved roof deployment without structural reinforcement.
Market Restraints
- High-purity silicon supply concentration:Polysilicon refining clusters in Xinjiang and Inner Mongolia expose module assemblers to forced-labor due-diligence compliance costs and supply interruption risk.
- Automotive qualification timelines:AEC-Q100 thermal cycling validation requires 18-24 months, compressing product refresh windows against faster-moving consumer electronics photovoltaic cycles.
- Silver metallization cost volatility:Paste consumption of 20 mg per cell ties module economics to precious metal commodity swings that erode margin predictability at scale.
Strategic Opportunities
- India PLI scheme for solar manufacturing:Production-linked incentives for module assembly create localized supply bases for domestic electric bus and two-wheeler integration programs.
- Vehicle-to-grid ancillary services:Bidirectional inverters paired with rooftop arrays allow parked EVs to sell frequency regulation services to regional transmission operators in deregulated power markets.
- Perovskite-on-silicon manufacturing convergence:Tandem cell deposition equipment overlaps with existing thin-film lines, enabling tier-two suppliers to leapfrog crystalline incumbents without greenfield capex.
Industry Challenges
- Automotive electrochemical compatibility testing:Salt spray and humidity cycling per IEC 61215 must be repeated for every vehicle platform curvature, multiplying certification costs across low-volume models.
- Photovoltaic-thermal management integration:Cell efficiency degradation above 65°C requires cooling loop redesigns that conflict with cabin HVAC packaging constraints in compact vehicle segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Solar Panel Market |
| Market Size in 2026 | $698.4 Million |
| Market Size in 2035 | $2,803.77 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Panels, Rigid Panels, Semi-Flexible Panels, Integrated Panels End User: OEMs, Aftermarket Providers, Vehicle Owners, Fleet Operators Technology: Monocrystalline, Polycrystalline, BIPV, Thin-Film Installation: Roof Mounting, Hood Mounting, Integrated Systems, DIY Kits |
| Companies Covered | Lightyear, Sono Motors, Aptera Motors, Toyota Motor, Ford Motor, General Motors, BYD, Nissan Motor, Hyundai Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Solar Panel Market Trends and Innovations
Photovoltaic integration is migrating from accessory-grade retrofit kits to structural body elements, with cell efficiency gains now measured against automotive durability rather than laboratory conditions alone.
Copper indium gallium selenide (CIGS) deposition onto stainless steel foils is rendering obsolete rigid glass-backplane modules for commercial vehicle applications. Fleet operators in refrigerated transport segments are specifying 150-micron flexible arrays for trailer roofs. The technology is compressing total cost of ownership calculations by eliminating structural reinforcement and aerodynamic penalty.
Japan's METI carbon neutrality roadmap now mandates solar-ready roofing for new commercial vehicle registrations above 3.5 tonnes from 2027. Domestic OEMs are pre-wiring body harnesses for 400V photovoltaic inputs. The requirement is accelerating JIS standard harmonization for automotive-grade junction boxes and bypass diode configurations.
Direct sales channels are displacing traditional aftermarket distribution for integrated photovoltaic systems. OEMs in Germany and the United States now bundle solar roof options at vehicle configuration rather than dealer fitment. The shift is visible most acutely in premium battery-electric SUV segments where buyers specify auxiliary charging during online reservation workflows.
Vehicle Solar Panel Market Segmentation
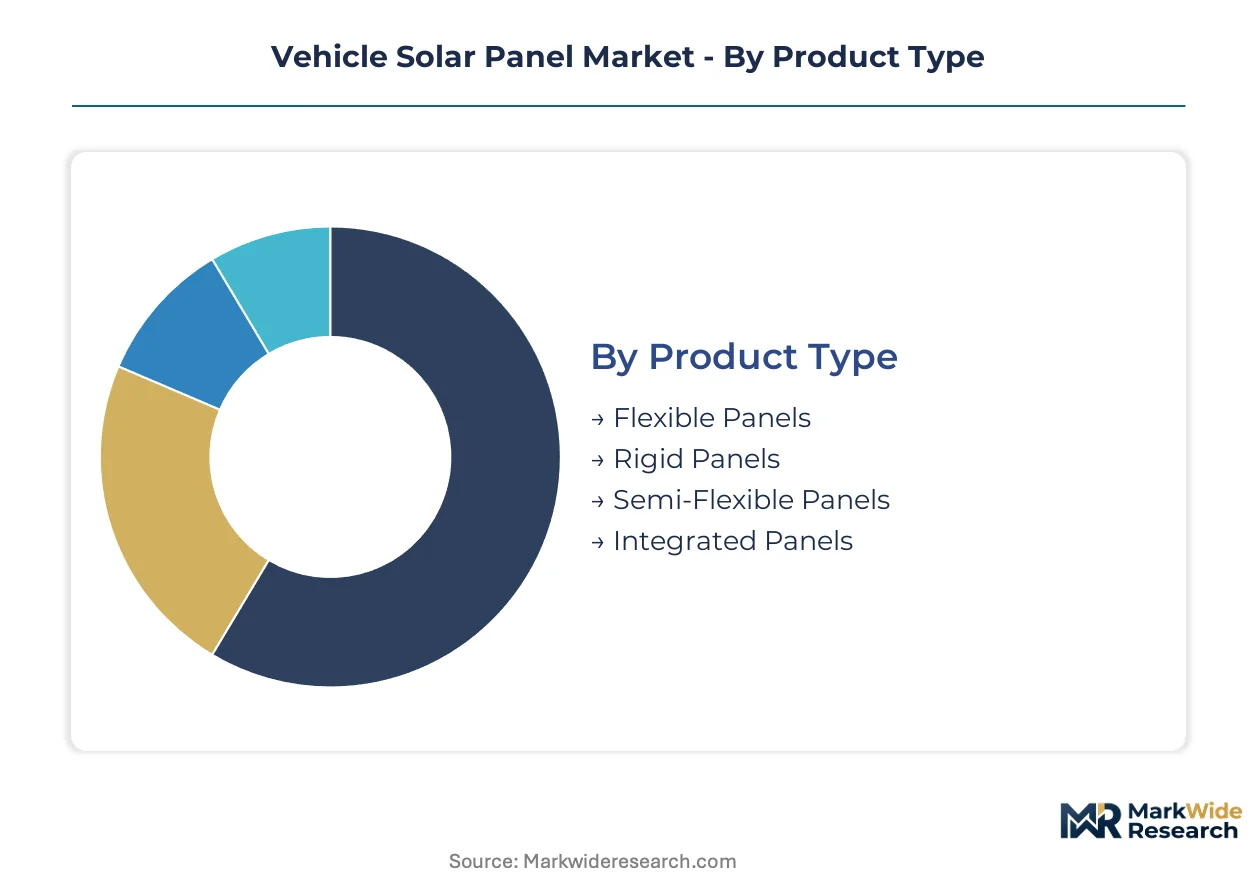
Vehicle solar panel segmentation reveals divergent service intensity profiles across product architectures. Flexible and integrated systems demand specialized installation protocols and warranty management, while rigid panels follow conventional aftermarket parts economics with lower touch requirements.
Product Type:
After-sales service intensity varies dramatically by substrate flexibility and integration depth, with embedded systems requiring OEM-trained technicians versus retrofit panels serviced through independent channels.
- Flexible Panels:Polymer-encapsulated cells bonded to curved automotive surfaces using pressure-sensitive adhesives. Demand concentrates in refrigerated transport fleets across Germany and the United States, where roof curvature compatibility eliminates structural modification costs. Fleet operators specify these for auxiliary refrigeration power without aerodynamic penalty.
- Integrated Panels:Photovoltaic layers deposited during body-in-white manufacturing, sealed within glass or polymer laminates as structural roof elements. Premium battery-electric SUV buyers in Japan and California configure these through direct OEM reservation platforms, treating solar range extension as a factory-integrated feature rather than aftermarket addition.
- Rigid Panels:Glass-fronted crystalline modules mounted via aluminum framing systems, dominating DIY installation segments where vehicle owners prioritize cost over conformal aesthetics.
- Semi-Flexible Panels:Hybrid substrates combining thin-film deposition with limited bend radius, serving commercial van upfitters requiring moderate curvature accommodation without full flexibility premiums.
Integrated panels hold the largest share; momentum sits with flexible arrays.
End User:
Customer type determines procurement channel structure and margin capture, with fleet operators consolidating volume through direct supplier agreements while individual owners fragment across retail and online channels.
- Fleet Operators:Logistics and refrigerated transport companies in Germany and the United States negotiate enterprise pricing for hood-integrated thin-film arrays powering telematics and cooling units. Procurement teams prioritize total cost of ownership calculations incorporating fuel savings and maintenance reduction.
- OEMs:Vehicle manufacturers embed photovoltaic layers during assembly, pre-wiring body harnesses for 400V inputs as seen in Japanese commercial vehicle platforms subject to METI solar-ready roofing mandates. Factory integration captures margin otherwise lost to aftermarket distribution.
- Aftermarket Providers:Specialty upfitters and dealer service departments install retrofit kits, facing compressed margins as direct OEM bundling displaces traditional distribution.
- Vehicle Owners:Individual consumers purchasing through online configuration workflows or retail channels, with premium SUV segments showing strongest attachment to solar roof options.
Fleet operators anchor volume procurement; individual owners are climbing the fastest as direct sales channels mature.
Technology:
Cell chemistry dictates efficiency-weight tradeoffs and thermal management requirements, with emerging tandem architectures threatening incumbent crystalline dominance in weight-sensitive applications.
- Thin-Film:Copper indium gallium selenide and cadmium telluride deposition onto stainless steel or polymer substrates, achieving sub-3 kg per square meter mass critical for commercial vehicle roof loading limits. CIGS arrays specified for European refrigerated trailers where every kilogram of panel mass displaces payload capacity.
- Monocrystalline:Silicon ingot-based cells delivering highest conversion efficiency in laboratory conditions, though glass encapsulation penalties limit deployment to rigid mounting applications where absolute output outweighs weight constraints.
- Polycrystalline:Lower-purity silicon offering cost advantages in price-sensitive aftermarket segments, losing ground to thin-film alternatives in automotive-qualified applications.
- BIPV:Building-integrated photovoltaic concepts adapted for vehicle structural elements, still awaiting automotive durability validation cycles.
Monocrystalline retains installed base dominance; thin-film is gaining share fastest as fleet electrification accelerates.
Installation:
Mounting methodology determines warranty liability and service lifecycle, with factory-integrated systems shifting responsibility to OEMs versus owner-assumed risk in DIY configurations.
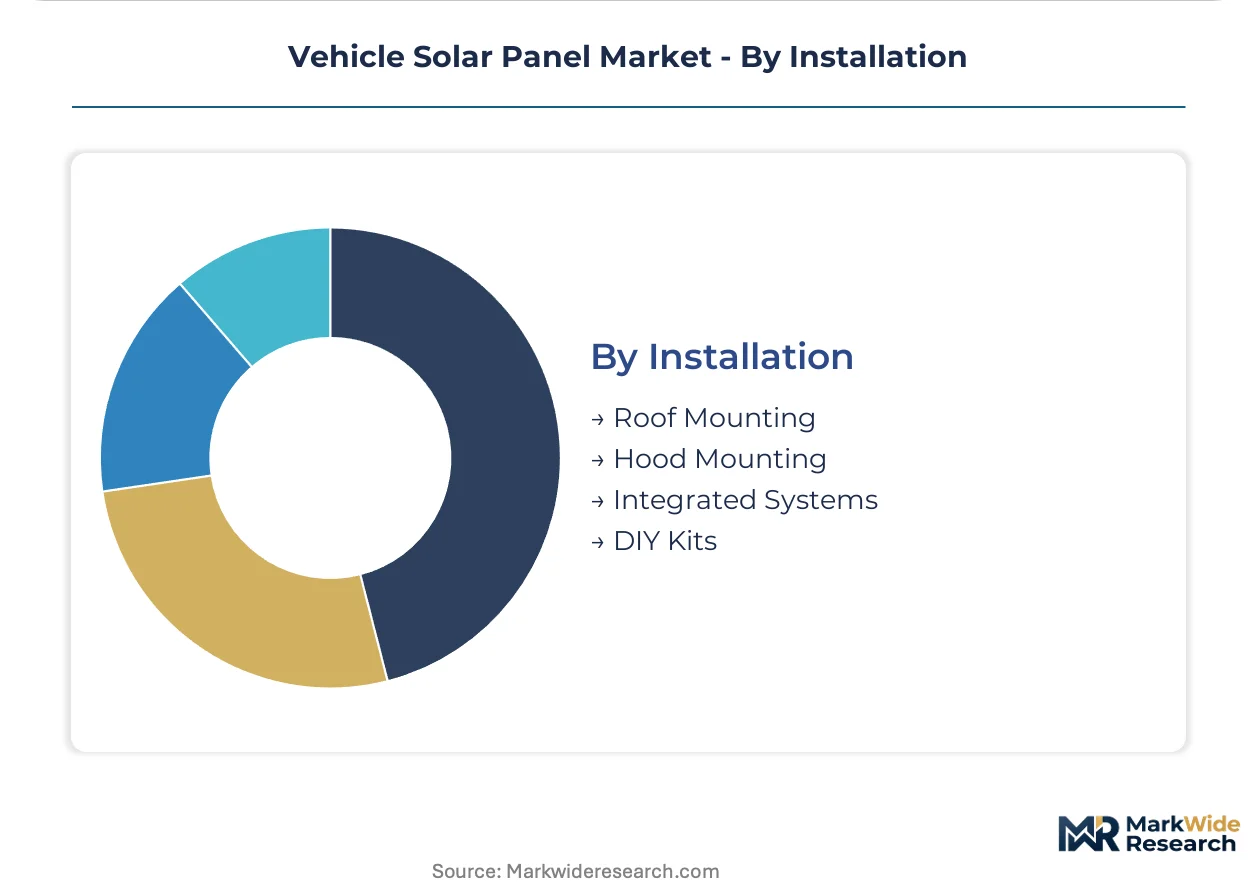
- Integrated Systems:Photovoltaic layers laminated during body panel stamping, with junction boxes and bypass diodes meeting JIS automotive standards. Japanese commercial vehicle manufacturers pre-certify these through AEC-Q100 thermal cycling protocols, eliminating per-vehicle validation costs.
- Roof Mounting:Rack-based or adhesive attachment to vehicle tops, the dominant configuration for aftermarket flexible panel deployment on vans and heavy trucks.
- Hood Mounting:Low-profile arrays on engine covers, specified by German logistics operators for auxiliary battery maintenance during extended parking.
- DIY Kits:Consumer-packaged systems with suction or magnetic mounting, occupying entry price tiers with limited durability warranties.
Roof mounting commands current volume; integrated systems show steepest expansion trajectory as OEMs internalize energy harvesting architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vehicle solar panel trade flows reflect concentrated manufacturing in East Asia against rising installation demand across German logistics corridors and Japanese commercial fleets. Import dependency for high-purity silicon and thin-film substrates shapes procurement strategies in Western markets. Regional regulatory divergence around automotive photovoltaic certification is fragmenting compliance pathways.
United States
Refrigerated transport operators in the Midwest and Southeast specify hood-integrated thin-film arrays to power auxiliary cooling without idling penalties. EPA tailpipe emission standards and NHTSA fuel economy regulations reward solar-assisted range extension as compliance credit mechanisms. Detroit-area OEM engineering centers are redesigning body-in-white structures around embedded photovoltaics rather than retrofitting legacy truck platforms.
Germany
Logistics operators across the Rhine-Ruhr and Bavarian freight corridors negotiate enterprise pricing for trailer-roof CIGS arrays that eliminate payload displacement from glass-glass laminates. EU Green Deal fleet-average CO2 mandates below 95 g/km push manufacturers toward auxiliary solar charging to claim compliance credits. Stuttgart-based OEMs are pre-wiring commercial vehicle harnesses for 400V photovoltaic inputs ahead of anticipated regulatory expansion.
Japan
Commercial fleet operators in the Kanto and Kansai industrial belts face METI mandates requiring solar-ready roofing for new vehicle registrations above 3.5 tonnes from 2027. Domestic OEMs are accelerating JIS standard harmonization for automotive-grade junction boxes and bypass diode configurations. Nagoya-area manufacturing clusters are adapting thin-film deposition lines for tandem cell architectures to serve domestic bus and heavy truck integration programs.
China
Polysilicon refining concentration in Xinjiang and Inner Mongolia exposes module assemblers to forced-labor due-diligence compliance costs and supply interruption risk. Dual carbon goals and evolving GB standards are redefining module certification requirements for automotive photovoltaic deployment. Shenzhen and Shanghai industrial zones are consolidating thin-film manufacturing capacity for export to European and North American fleet electrification programs.
India
Domestic electric bus and two-wheeler manufacturers are leveraging PLI scheme production-linked incentives to localize module assembly for vehicle integration. State transport utilities in Maharashtra and Karnataka are piloting rooftop photovoltaic arrays on intra-city bus fleets to reduce grid charging dependency. Tamil Nadu-based component suppliers are qualifying flexible polymer substrates for tropical humidity cycling under BIS automotive standards.
Vehicle Solar Panel Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated OEMs capturing factory-installation margin, tier-one module specialists supplying fleet retrofit programs, and regional assemblers serving price-sensitive aftermarket segments. Automotive qualification timelines favor incumbents with established AEC-Q100 validation infrastructure. Dominant competitive moves include backward integration into thin-film substrate manufacturing and technology licensing partnerships for perovskite-silicon tandem deposition.
Among integrated OEMs, Toyota Motor and Hyundai Motor Company exemplify divergent platform strategies for solar roof deployment across passenger and commercial segments. Within the battery-electric specialist tier, BYD occupies a position extending its cell manufacturing dominance into commercial fleet panel systems. These three entities represent distinct archetypes: legacy hybrid platform leverage, dedicated EV architecture design, and vertical cell-to-vehicle integration.
| Leading Market Players |
|---|
| Lightyear |
| Sono Motors |
| Aptera Motors |
| Toyota Motor |
| Ford Motor |
| General Motors |
| BYD |
| Nissan Motor |
| Hyundai Motor Company |
| Others |
Pricing and Supply Chain Analysis
Thin-film deposition line underutilization in Shanghai and Shenzhen industrial zones is compressing module quotes for European fleet retrofit programs while simultaneously eroding margin buffers for tier-two assemblers. This capacity slack forces suppliers into aggressive volume pricing to cover fixed equipment costs, reshaping procurement negotiations for logistics operators across German freight corridors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates AEC-Q100 certified integrated systems from aftermarket flexible arrays and entry-grade DIY kits. Cost compression in the standard tier is intensifying because silver metallization paste consumption of 20 mg per cell ties module economics to precious metal commodity swings. Fleet operators show highest price sensitivity due to total cost of ownership calculations, while premium SUV individual buyers exhibit lowest sensitivity when configuring factory-integrated options.
Supply Chain Analysis
High-purity polysilicon refining clusters in Xinjiang and Inner Mongolia feed crystalline cell manufacturing, while CIGS deposition equipment draws from Japanese and South Korean thin-film substrate specialists. Raw material dependencies rest on silver metallization pastes, ethylene tetrafluoroethylene encapsulation polymers, and stainless steel foils. Single-source vulnerability concentrates in forced-labor due-diligence compliance costs for polysilicon sourcing. Distribution runs through direct OEM bundling for integrated systems and enterprise supplier agreements for fleet retrofit volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from warranty extensions and thermal cycling recertification is expanding faster than hardware module sales, creating recurring margin pools for suppliers who capture fleet operator relationships. This service layer justifies upfront pricing concessions to lock in long-term maintenance contracts.
For Market Incumbents: Build certification moats through accelerated AEC-Q100 validation infrastructure that compresses 18-24 month automotive qualification timelines below competitor reach. Deepen backward integration into thin-film substrate manufacturing to neutralize silver paste cost volatility. Capture channel control by pre-wiring OEM body harnesses for 400V photovoltaic inputs before regulatory mandates expand.
For New Entrants and Emerging Players: Pursue refrigerated transport trailer segments in Germany and the United States where CIGS flexible arrays eliminate payload displacement penalties. Target India's PLI scheme production-linked incentives for domestic electric bus integration programs. Anchor go-to-market through direct supplier agreements with state transport utilities rather than fragmented aftermarket distribution.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across perovskite-silicon tandem deposition equipment as manufacturing convergence enables tier-two suppliers to leapfrog crystalline incumbents without greenfield capex. Long-term viability favors acquisition targets with established AEC-Q100 validation infrastructure and OEM pre-wiring relationships. Watch JIS standard harmonization progress for automotive-grade junction boxes as the inflection signal for Japanese commercial vehicle integration readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite-Silicon Tandem Manufacturing Convergence | Enables tier-two suppliers to leapfrog crystalline incumbents using existing thin-film deposition lines. |
| AEC-Q100 Validation Infrastructure Expansion | Compresses 18-24 month automotive qualification timelines against faster-moving consumer electronics cycles. |
| Backward Integration into Thin-Film Substrates | Neutralizes silver metallization cost volatility that erodes margin predictability at scale. |
| OEM Body Harness Pre-Wiring Programs | Captures factory-installation margin before METI solar-ready roofing mandates expand beyond Japan. |
| Vehicle-to-Grid Ancillary Services Partnership | Allows parked EVs to sell frequency regulation services to FERC-jurisdictional transmission operators. |
Research Methodology
The analysis maps flexible panel, integrated panel, rigid panel, and semi-flexible panel sub-sectors, each validated through OEM platform engineers, tier-one module procurement leads, fleet operator logistics directors, and aftermarket upfitter technical specialists. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC automotive supplier filings, and EPA compliance credit disclosures. Bottom-up unit economics triangulated against top-down OEM production planning figures across the analysis window.
Assumptions held fixed include current EPA tailpipe emission standards and NHTSA fuel economy regulations, while EU Green Deal CO2 mandate stringency and METI solar-ready roofing timeline enforcement were varied across scenarios. Segmentation dimensions modeled span product substrate flexibility, end-user procurement channel structure, cell chemistry efficiency-weight tradeoffs, and mounting methodology warranty liability. CAGRs derived from installed base growth rates and replacement cycle acceleration throughout the forecast period. Industry-specific inputs incorporated AEC-Q100 thermal cycling validation completion rates and polysilicon supply chain due-diligence compliance cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in silver commodity pricing, semiconductor equipment lead times, or logistics freight rates would shift the trajectory. Forecasts reflect these assumptions without guarantee of realization. Cross-checking against IEA electric vehicle deployment benchmarks and FERC vehicle-to-grid pilot program disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
E-Bike Accessories Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
US Electric Mobility Market