
 Fuel Cell Electric Vehicle (FCEV) Market | 2026-2036
Fuel Cell Electric Vehicle (FCEV) Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell Electric Vehicle (FCEV) Market Analysis
South Korean battery and fuel cell suppliers is restructuring output schedules to match OEM hydrogen platform rollouts. Toyota Motor Corporation leverages its Mirai architecture across multiple vehicle classes to sustain technology leadership. Hyundai Motor Company anchors its Xcient truck program with dedicated production lines in Ulsan. Ballard Power Systems competes on fuel cell stack cost curves for heavy-duty applications.
A fuel cell electric vehicle converts hydrogen into electricity through an electrochemical reaction in a fuel cell stack, typically operating at 60-80°C for proton exchange membrane systems, with water vapor as the sole emission. The technology serves zero-emission mobility requirements in weight-sensitive, long-range applications where battery energy density falls short. Passenger cars currently lead volume deployments, though trucks represent the fastest-expanding segment as logistics operators seek diesel replacements. Proton exchange membrane technology dominates commercial installations due to its power density and cold-start performance, while solid oxide systems occupy stationary range-extender niches.
The US EPA tailpipe standards and Japan's METI hydrogen supply chain subsidies shape product development timelines and infrastructure investment cycles. California's Air Resources Board mandates drive fleet procurement quotas for zero-emission trucks, directly influencing manufacturer capacity allocation. Stakeholders must monitor hydrogen production cost trajectories and station network density as the decisive variables for fleet conversion economics.
Market Dynamics
Fleet procurement mandates in California and Japan's METI hydrogen subsidies are compressing manufacturer platform development cycles while infrastructure buildout lags vehicle deployment. This temporal mismatch between supply-side scaling and demand-side conversion economics defines current competitive positioning.
Growth Catalysts
- Zero-emission truck mandates:California's Air Resources Board enforces fleet procurement quotas that force logistics operators into hydrogen pilot programs ahead of total cost parity.
- Japan METI roadmap:Subsidized hydrogen supply chain investments accelerate station network density in urban freight corridors and bus depots.
- PEM stack cost curves:Manufacturing scale improvements in membrane electrode assembly production reduce stack costs for heavy-duty powertrains.
Market Restraints
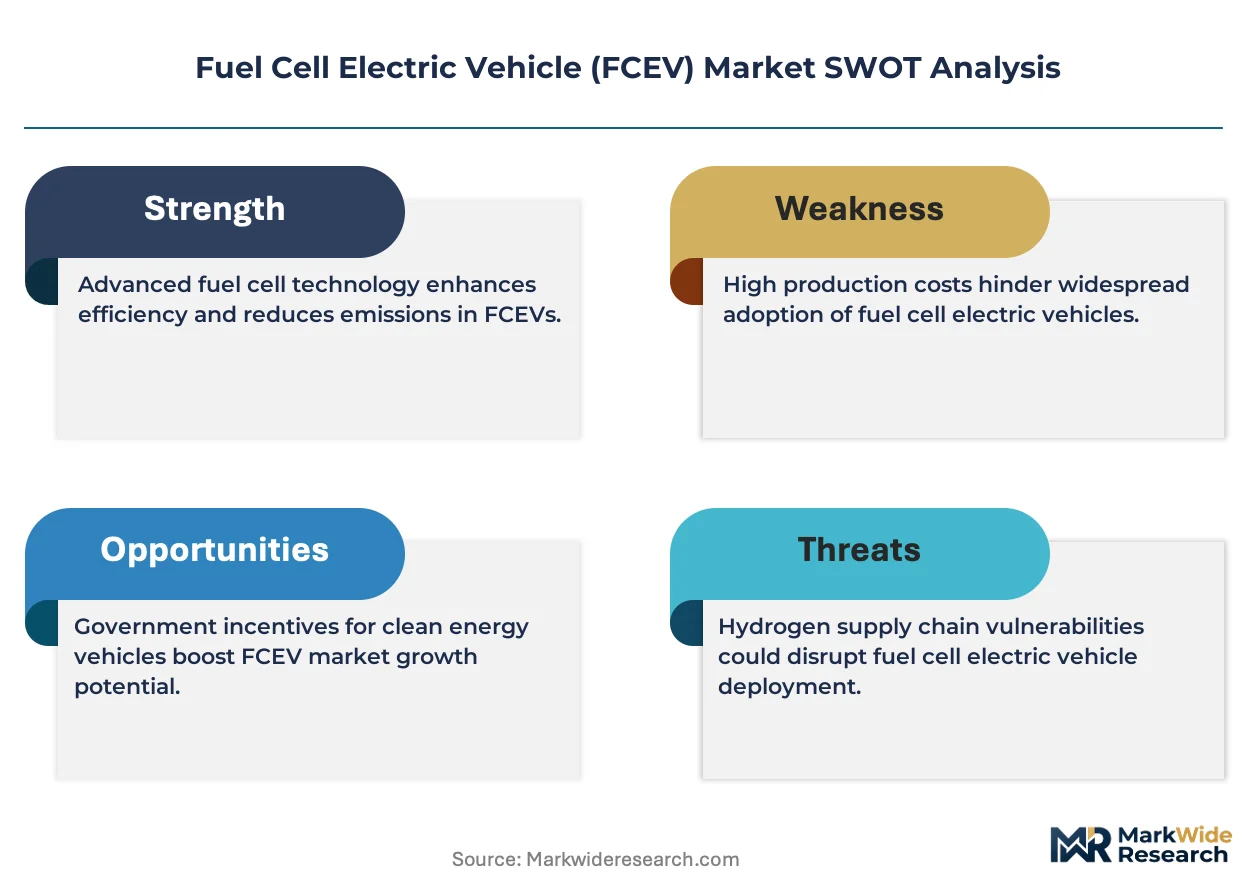
- Platinum group metal concentration:Catalyst supply chains concentrate in South Africa and Russia, exposing stack manufacturers to geopolitical input volatility.
- Station network gaps:Hydrogen refueling infrastructure remains sparse outside California's I-710 corridor and Japan's Tokyo-Osaka freight axis.
- Battery electric substitution:Lithium-ion energy density improvements in medium-duty routes threaten hydrogen's range-advantage positioning.
Strategic Opportunities
- Australian hydrogen export hubs:Green hydrogen production clusters in Queensland and Western Australia offer feedstock cost advantages for Asian market supply.
- Maritime port drayage:Short-haul container trucking at Los Angeles and Long Beach ports presents fleet-scale deployment potential with captive fueling.
- German H2Mobility program:Federal transport ministry funding for commercial vehicle corridors creates anchor demand for imported stack systems.
Industry Challenges
- Systems integration complexity:Fuel cell thermal management and hydrogen storage tank packaging require vehicle platform redesigns that extend OEM development timelines.
- Technician certification gaps:High-pressure hydrogen handling and fuel cell diagnostics demand specialized training programs that vocational institutions have not scaled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell Electric Vehicle (FCEV) Market |
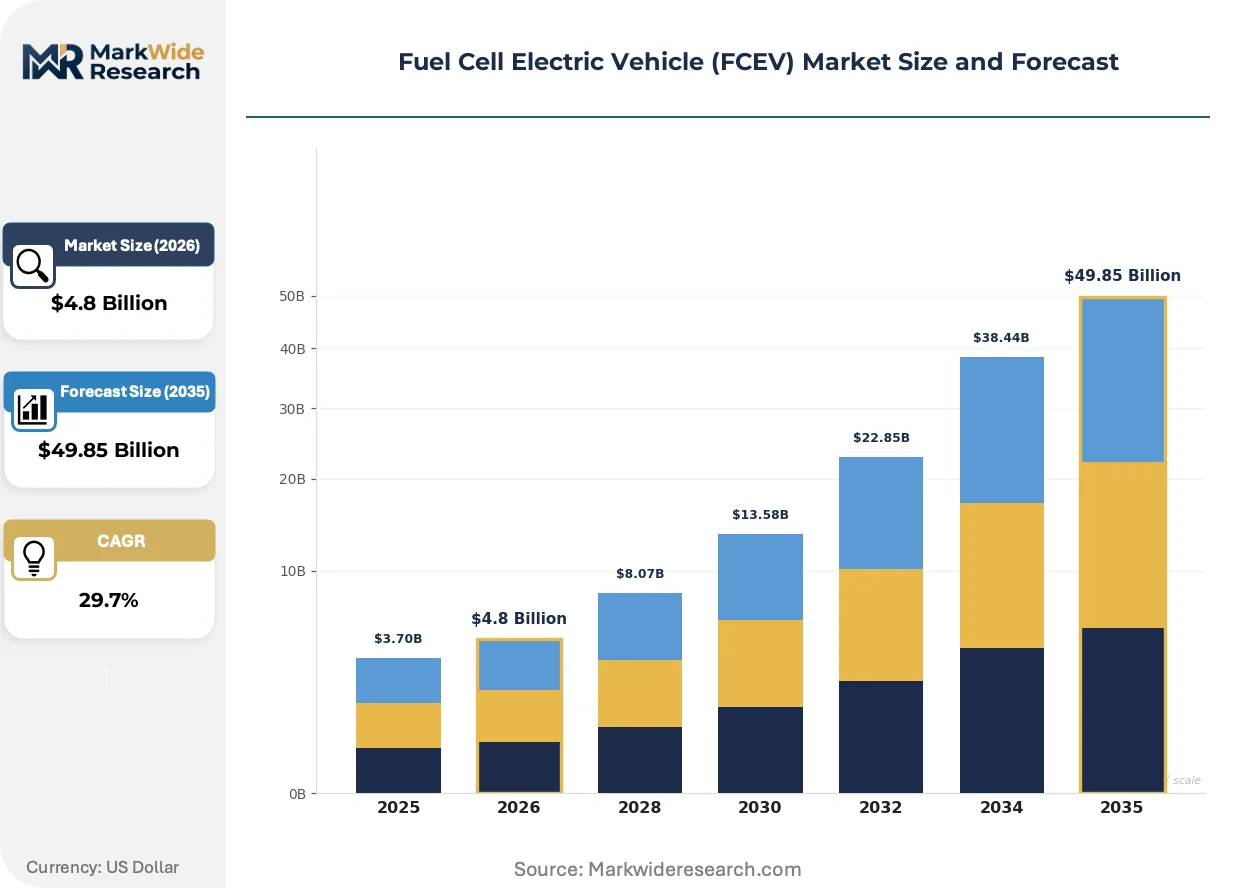
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $49.85 Billion |
| CAGR (2026 – 2036) | 29.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Buses, Trucks, Two-Wheelers Fuel Type: Hydrogen, Natural Gas, Methanol, Others End User: Government, Commercial, Residential, Logistics Technology: Proton Exchange Membrane, Solid Oxide, Alkaline, Others |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Company, Honda Motor Co., Ltd., Cummins Inc., Daimler AG, Ballard Power Systems, Nikola Corporation, General Motors Company, Mercedes-Benz Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell Electric Vehicle (FCEV) Market Emerging Trajectories
Modular fuel cell platform architectures are collapsing development costs across vehicle classes. Standardization of balance-of-plant components enables suppliers to serve multiple powertrain segments without dedicated tooling.
Integrated fuel cell-battery hybrid systems are unifying power management across transient load profiles. Transit bus operators in Japan and Korea are adopting these configurations for stop-start urban routes. The technology is compressing the performance gap between pure fuel cell and battery-dominant architectures in medium-duty applications.
EPA tailpipe standards for nitrogen oxides and particulate matter are tightening compliance windows for diesel truck manufacturers. Engine makers face accelerated R&D spending to meet 2027 model year requirements. Heavy-duty fleet procurement is rotating toward zero-emission alternatives in California, New York, and New Jersey corridors.
Long-term hydrogen supply contracting is replacing spot market purchasing for fleet operators. Logistics companies in California's San Pedro Bay ports are locking in ten-year offtake agreements with electrolyzer developers. This shift concentrates counterparty risk with green hydrogen producers in Texas and Arizona renewable energy zones.
Fuel Cell Electric Vehicle (FCEV) Market Segmentation
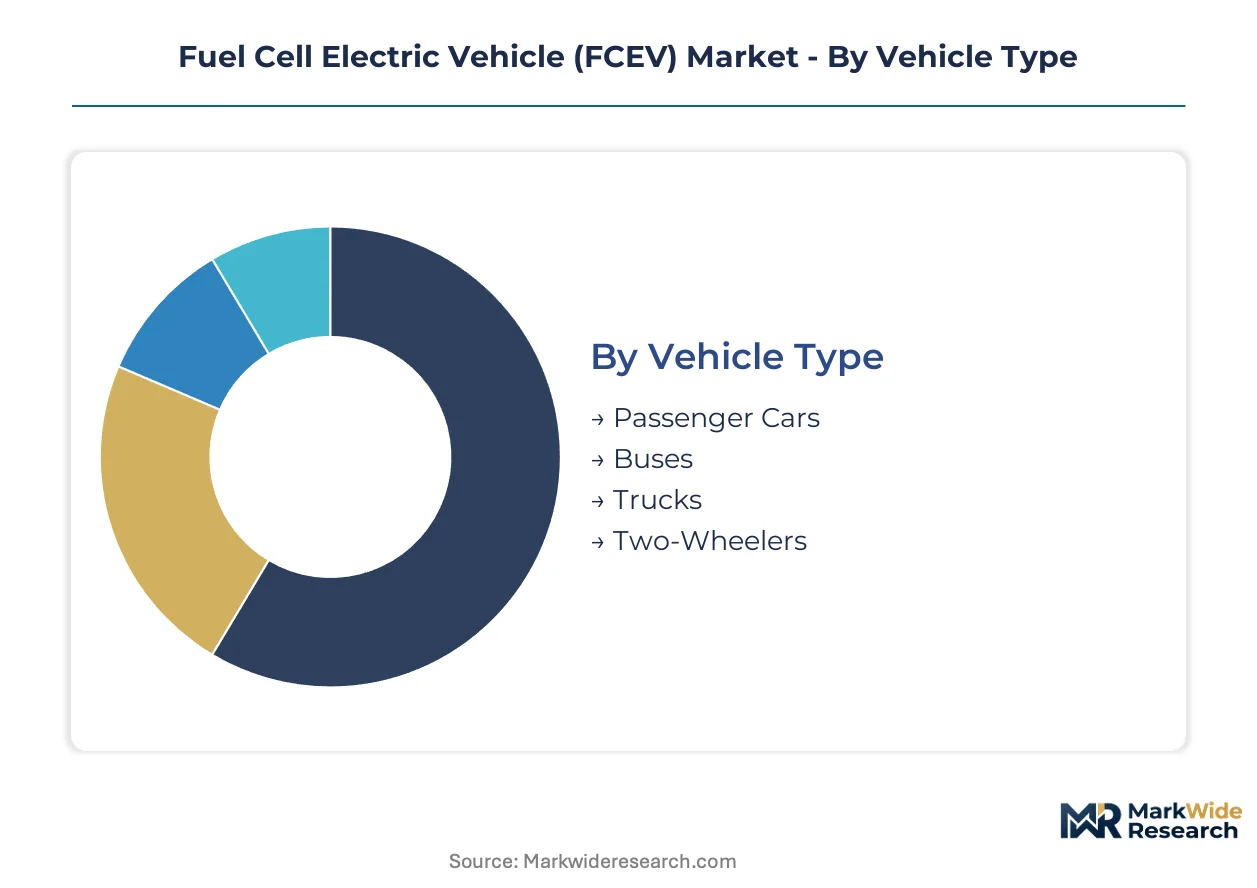
Segmentation in the Fuel Cell Electric Vehicle market reveals how hydrogen propulsion technology fragments across fundamentally different duty cycles and infrastructure requirements. Vehicle mass, route predictability, and refueling access determine which configurations achieve commercial viability first.
Vehicle Type:
Passenger cars dominate unit volumes while commercial vehicles command premium powertrain economics and dedicated production capacity.
- Passenger Cars:Light-duty platforms utilize 60-100kW fuel cell stacks paired with modest hydrogen storage at 700 bar. Toyota Mirai and Hyundai Nexo deployments concentrate in California and Japan where station networks support retail consumers. California's HOV lane access and state rebates sustain demand despite infrastructure gaps.
- Trucks:Heavy-duty long-haul configurations deploy 200-300kW stacks with cryogenic or compressed hydrogen storage for 500+ mile ranges. Hyundai Xcient and Nikola Tre programs anchor fleet procurement in California's I-710 freight corridor and Germany's Rhine-Alpine logistics axis. Steep expansion trajectory driven by diesel phase-out mandates in California, New York, and New Jersey.
- Buses:Transit operators in Japan, Korea, and Germany deploy 100-150kW systems for fixed-route urban service with depot fueling. Ballard Power and Toyota modules dominate procurement.
- Two-Wheelers:Niche applications in last-mile delivery and municipal service fleets in Japan and France test compact 1-5kW fuel cell range extenders.
Mature deployment sits with Passenger Cars. Newer deployment is concentrated in Trucks.
Fuel Type:
Fuel chemistry determines infrastructure compatibility, well-to-wheel emissions profile, and geographic deployment feasibility.
- Hydrogen:Gaseous and liquid forms constitute the primary commercial fuel with established ISO 19880 refueling protocols. Green hydrogen from electrolysis and blue hydrogen from steam methane reforming with carbon capture supply California, Japan, and German corridors. METI subsidies and IRA production credits compress feedstock costs.
- Methanol:Liquid fuel enables simplified storage and transport using existing petroleum infrastructure. Reforming onboard to hydrogen suits maritime and remote applications where compressed hydrogen logistics fail. Trials concentrate in China and Denmark for fleet vehicles.
- Natural Gas:Onboard reforming to hydrogen offers transitional pathway for regions with established CNG networks. Italy and Iran maintain limited pilot programs.
- Others:Ammonia and liquid organic hydrogen carrier research programs in Japan and Australia target long-duration storage and export applications.
Commercial traction clusters with Hydrogen. Methanol holds pilot-stage positioning for specialized logistics.
End User:
Procurement authority and total cost of ownership horizons segment demand between institutional mandate-driven and economics-driven adopters.
- Logistics:Fleet operators with centralized fueling and predictable routes achieve fastest payback. DHL, Amazon, and Walmart pilot programs in California and Germany lock in long-term hydrogen supply contracts. Procurement scales with station density along freight corridors.
- Government:Municipal transit agencies and defense procurement in Japan, Korea, and California absorb technology premiums to meet zero-emission mandates. Bus depot fueling simplifies infrastructure requirements.
- Commercial:Corporate fleet operators with ESG commitments deploy passenger cars and light trucks for executive transport and urban service. Leasing structures mitigate residual value risk.
- Residential:Minimal direct participation; consumer ownership limited to early adopters in California and Japan with home proximity to refueling stations.
Volume concentration rests with Logistics. Government procurement sustains technology maturation.
Technology:
Electrochemical system architecture trades operating temperature, efficiency, and response dynamics against application requirements.
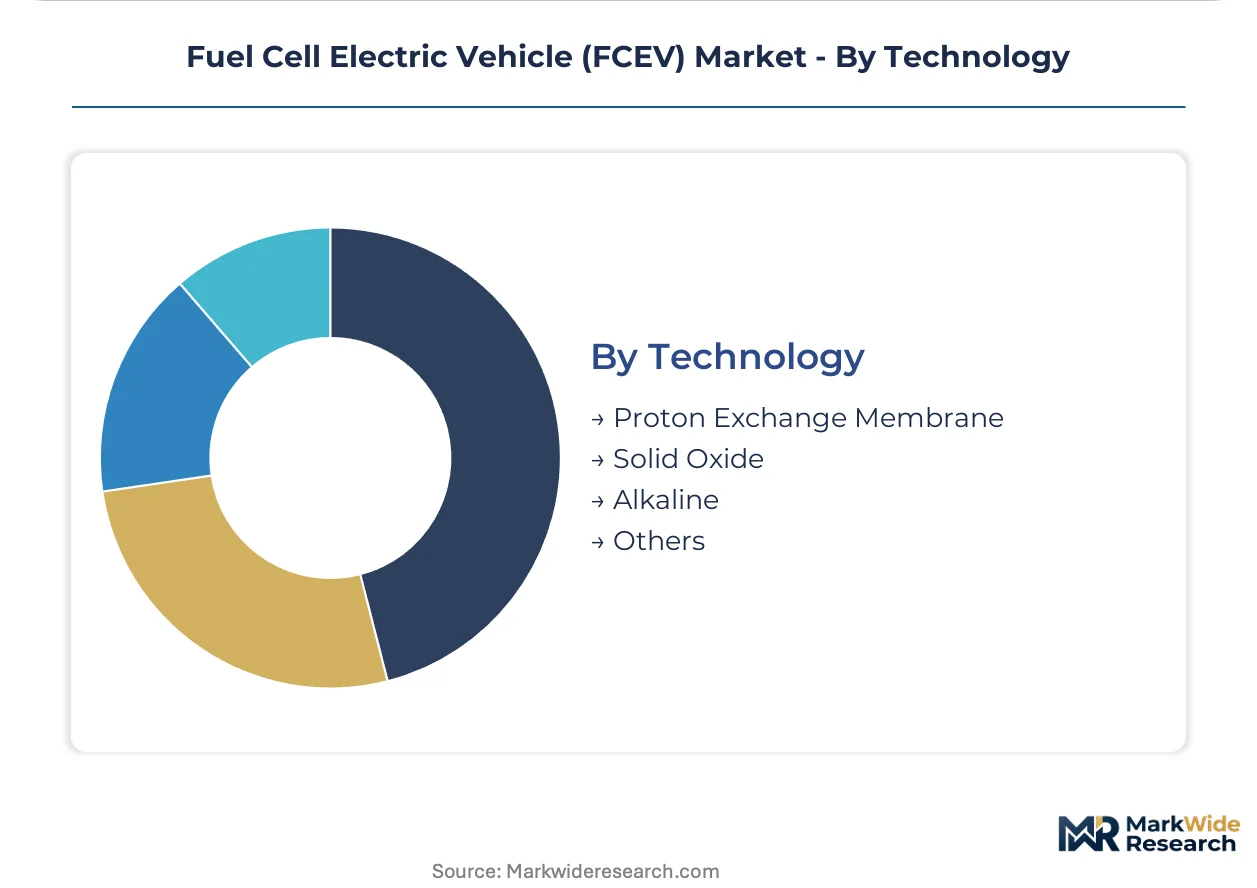
- Proton Exchange Membrane:Low-temperature (60-80°C) operation with rapid cold-start capability dominates automotive and bus installations. Platinum catalyst loadings and membrane electrode assembly manufacturing scale determine stack cost curves. Ballard, Toyota, and Hyundai production lines concentrate in Canada, Japan, and Korea.
- Solid Oxide:High-temperature (600-1000°C) operation achieves superior electrical efficiency and fuel flexibility including natural gas and biogas. Bloom Energy and Ceres Power target stationary range-extender and heavy-duty applications where thermal integration aids efficiency. Development programs in Germany and UK focus on long-haul trucking.
- Alkaline:Non-platinum catalysts reduce material costs for stationary and maritime applications with continuous operation profiles. AFC Energy and Enapter target port equipment and shipping.
- Others:Phosphoric acid and molten carbonate systems occupy legacy stationary markets with limited mobility relevance.
PEM systems anchor automotive volume. Solid oxide architectures gain share in heavy-duty thermal management applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum group metal deposits in South Africa and Russia anchor catalyst supply chains for fuel cell stack manufacturing. Japan's METI hydrogen roadmap and California's freight corridor mandates concentrate infrastructure investment. Station network density determines deployment feasibility across each geography.
United States
California's I-710 freight corridor and San Pedro Bay ports drive heavy-duty truck pilot programs. The EPA tailpipe standards and CARB zero-emission truck mandates force fleet procurement timelines. Los Angeles-Long Beach logistics operators lock in long-term hydrogen supply contracts with electrolyzer developers in Texas and Arizona renewable zones.
Japan
Urban bus networks in Tokyo and Osaka anchor transit fleet conversions. METI hydrogen supply chain subsidies compress station buildout costs along the Tokyo-Osaka freight axis. Toyota's Mirai architecture production in Aichi Prefecture sustains passenger car deployment.
Germany
The Rhine-Alpine logistics corridor generates commercial vehicle demand from DHL and Amazon fleet operators. Federal transport ministry funding through the H2Mobility program creates anchor demand for heavy-duty fuel cell systems. Stuttgart and Munich industrial clusters concentrate OEM development activity.
South Korea
Bus depot fueling in Seoul and Ulsan supports transit agency procurement. Hyundai's dedicated Xcient production lines in Ulsan anchor heavy-duty manufacturing scale. Domestic battery and fuel cell suppliers restructure output schedules to match OEM hydrogen platform rollouts.
China
Reforming-focused methanol trials in port cities test liquid fuel logistics. State-supported electrolyzer manufacturing in Sichuan and Inner Mongolia expands green hydrogen production capacity. Beijing-Tianjin-Hebei corridor pilots concentrate government fleet procurement.
Fuel Cell Electric Vehicle (FCEV) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent energy storage and stationary power applications. The market exhibits tiered concentration with integrated automotive OEMs controlling passenger vehicle deployment and specialized stack suppliers serving commercial segments. Three archetypes dominate: full-stack automotive integrators, dedicated fuel cell system suppliers, and diversified industrial conglomerates with powertrain divisions. Competitive moves center on manufacturing scale expansion in membrane electrode assembly production and strategic partnerships for hydrogen infrastructure co-investment.
Within the integrated automotive tier, Toyota Motor Corporation and Hyundai Motor Company exemplify platform architecture strategies that collapse development costs across vehicle classes. Ballard Power Systems occupies a position among dedicated fuel cell specialists focused on heavy-duty powertrain economics. These three anchors represent divergent approaches to technology commercialization—captive vertical integration versus component supply to third-party OEMs.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Honda Motor Co., Ltd. |
| Cummins Inc. |
| Daimler AG |
| Ballard Power Systems |
| Nikola Corporation |
| General Motors Company |
| Mercedes-Benz Group |
| Others |
Supply Flow & Price Mechanics
California's CARB zero-emission truck mandates and Japan's METI hydrogen subsidies gate qualified supply access for fleet operators, with certified fuel cell systems commanding premium-tier pricing while uncertified configurations face procurement exclusion.
Pricing Analysis
Warranty and service bundling separates premium fuel cell powertrain offerings from unbundled stack-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects membrane electrode assembly quality grades and platinum catalyst loadings. Cost compression in standard-tier stacks is intensifying because Chinese electrolyzer manufacturers are expanding membrane production capacity. Logistics fleet operators exhibit highest price sensitivity due to total cost of ownership scrutiny, while government transit agencies absorb technology premiums to meet mandate compliance.
Supply Chain Analysis
Platinum group metal catalyst supply rests on South African mining operations and Russian refining capacity, with membrane electrode assembly production concentrated in Japan, South Korea, and Canada. Hydrogen storage tank carbon fiber, high-purity hydrogen, and proton exchange membranes constitute critical input dependencies. Single-source vulnerability in South African platinum concentrate exposes stack manufacturers to geopolitical disruption. Distribution runs through Tier 1 automotive suppliers with captive fuel cell divisions serving OEM platform programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where membrane electrode assembly manufacturing scale and hydrogen infrastructure co-investment determine competitive survival.
For Market Incumbents: Acquire membrane electrode assembly production facilities in South Korea or Japan to secure catalyst coating capacity. Battery electric substitution in medium-duty routes threatens hydrogen's range positioning, necessitating backward integration into hydrogen storage tank manufacturing to preserve margin structure. For New Entrants and Emerging Players: Launch via maritime port drayage fleet partnerships at Los Angeles and Long Beach where captive fueling infrastructure eliminates station network dependency. Australian hydrogen export hubs offer feedstock cost advantages for Asian market supply contracts, with methanol reforming systems presenting the most penetrable technology entry point for remote logistics applications. For Investors and Strategic Acquirers: Ten-year hydrogen offtake agreement signings between California port operators and electrolyzer developers are the leading indicator that fleet-scale conversion economics are achieving bankability. Target alkaline fuel cell specialists with port equipment applications for acquisition, with electrolyzer capacity utilization rates as the critical inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrode Assembly Capacity Expansion | Ballard Power and Toyota production lines in Canada and Japan anchor stack cost curves for heavy-duty applications. |
| Hydrogen Infrastructure Co-Investment | Los Angeles-Long Beach port operators lock in long-term supply contracts with Texas and Arizona electrolyzer developers. |
| Platform Standardization Across Vehicle Classes | Toyota's Mirai architecture sustains technology leadership through modular fuel cell system deployment. |
| Green Hydrogen Supply Agreement | Queensland and Western Australia production clusters offer feedstock cost advantages for Asian market supply. |
| Technician Certification Program Development | Vocational institutions in California and Japan address high-pressure hydrogen handling training gaps for fleet maintenance. |
Methodological Framework
Independent corroboration across OEM platform engineers, hydrogen station network developers, and fleet procurement officers underwrites the qualitative findings in this study. Primary interviews with fuel cell stack manufacturers, logistics operators, and transit agency technical directors combined with secondary validation from EPA regulatory filings, METI hydrogen roadmap documents, and California Air Resources Board mandate records establish demand-side triangulation. Bottom-up vehicle deployment tracking and top-down infrastructure investment analysis cross-validate volume estimates.
Rate-of-change decomposition across vehicle class, powertrain architecture, and regional regulatory framework segments drives the analytical framework over the projection horizon. Modeled dimensions span passenger cars, trucks, buses, and two-wheelers against proton exchange membrane, solid oxide, and alkaline technology pathways. CAGRs derive from hydrogen station network density trajectories and fleet procurement mandate timelines, with membrane electrode assembly cost curves and platinum group metal price volatility as industry-specific forecast inputs.
Electrolyzer capacity buildout delays, platinum supply disruption, and battery electric range improvements are the dominant revision risks that could alter deployment trajectories. Forecasts reflect documented assumptions about infrastructure investment pacing and technology cost convergence. A small set of station network completion rates and green hydrogen production cost triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia Pacific Hybrid Electric Vehicle Battery Market
Electric Vehicles
Scooter Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
EV Platform Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
Electric Car Rental Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
Solar Car Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market